
 North America FMCG Logistics Market | 2026-2036
North America FMCG Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
North America FMCG Logistics Market Analytics
E-commerce platforms are unwinding the traditional retail-wholesaler dominance in FMCG fulfillment networks. C.H. Robinson leverages its digital freight-matching platform to capture spot-market volatility across temperature-controlled lanes. Lineage Logistics anchors North American cold storage capacity with automated high-bay warehousing systems. Americold competes through its integrated port-to-door temperature management services.
North America FMCG logistics encompasses the planning, execution, and control of fast-moving consumer goods movement across temperature-controlled, ambient, and frozen supply chains, typically operating within ±2°F variance protocols for perishables and leveraging cross-docking to minimize inventory holding. Its primary commercial purpose is to synchronize high-velocity replenishment cycles with retail shelf-life constraints. Warehousing commands the largest value pool due to automation capital intensity and land scarcity near consumption clusters. Last-mile delivery is expanding fastest as same-day expectations compress fulfillment windows. RFID and IoT tracking systems sit at the center of margin improvement programs by reducing shrinkage and enabling dynamic routing.
The EPA, FMCSA, and DOT collectively shape fleet composition, driver availability, and emissions compliance across interstate FMCG corridors. California's Advanced Clean Trucks regulation is forcing multi-state operators to pre-position zero-emission assets ahead of federal mandates. Stakeholders must decide whether to absorb electrification costs through rate surcharges or accelerate warehouse automation to offset fleet capital intensity.
Market Dynamics
EPA Phase 2 greenhouse gas standards for medium- and heavy-duty trucks are compressing fleet replacement cycles and forcing capital reallocation toward alternative powertrains across interstate FMCG corridors.
Growth Catalysts
- California's Advanced Clean Trucks regulation:Mandates zero-emission vehicle sales thresholds that cascade procurement decisions across multi-state operators serving the Texas-California freight corridor.
- Automated high-bay warehousing:Cold storage operators deploy robotics to offset labor scarcity and land cost inflation near Los Angeles basin and Dallas-Fort Worth consumption clusters.
- Same-day fulfillment compression:E-commerce platforms demand micro-fulfillment nodes within 50 miles of urban centers, expanding temperature-controlled last-mile infrastructure.
Market Restraints
- Electrification capital intensity:Battery-electric and hydrogen fuel cell trucks require 2-3x upfront capital versus diesel equivalents, straining fleet operator balance sheets.
- Driver availability constraints:FMCSA hours-of-service rules and demographic shifts tighten qualified operator supply across interstate temperature-controlled lanes.
- Land scarcity near consumption clusters:Industrial zoned parcels within 30 miles of major metropolitan areas command premium lease rates that compress warehouse operating margins.
Strategic Opportunities
- Port-to-door temperature integration:Cold chain operators can capture value by controlling handoffs from Los Angeles-Long Beach port complexes through final delivery.
- RFID-IoT convergence:Real-time perishable tracking enables dynamic routing and shrinkage reduction across multi-temperature supply chains.
- Mexico cross-border expansion:Nearshoring manufacturing to Mexican industrial corridors creates demand for synchronized US-Mexico cold chain infrastructure.
Industry Challenges
- Refrigeration technician scarcity:Specialized maintenance skills for automated high-bay systems and alternative powertrain cooling loops outpace training pipeline output.
- Multi-state compliance fragmentation:California's zero-emission mandates diverge from federal EPA timelines, forcing fleet operators to maintain dual-specification asset pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America FMCG Logistics Market |
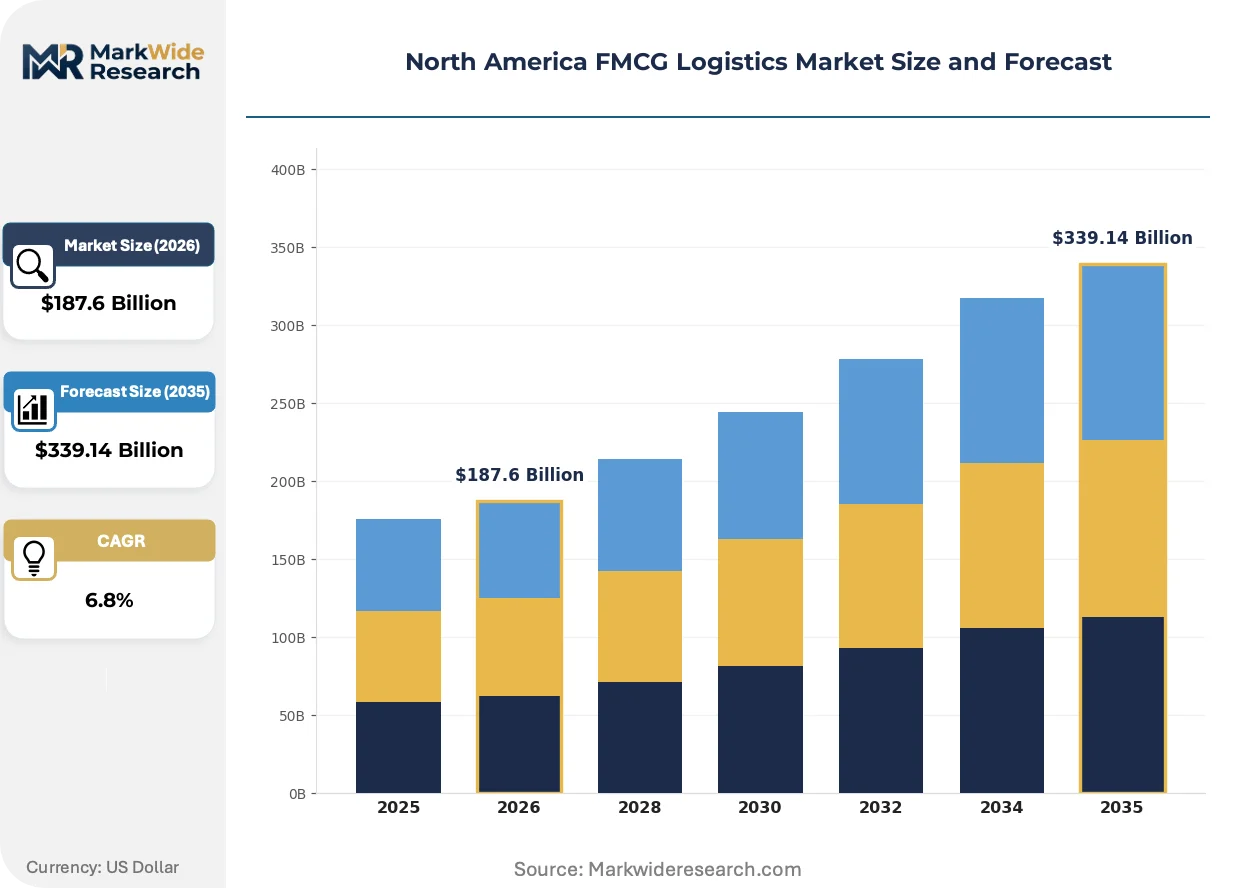
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $339.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Packaging End User: Retailers, Wholesalers, E-commerce Platforms, Manufacturers Technology: RFID, IoT, Automation, Tracking Systems Delivery Model: Direct Delivery, Drop Shipping, Last Mile, Cross Docking |
| Companies Covered | C.H. Robinson, Americold, DHL Group, XPO, Inc., Kuehne+Nagel, CEVA Logistics, FedEx, Lineage Logistics, DB Schenker, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America FMCG Logistics Market Evolving Landscape
Digital freight platforms and automated warehouse systems are compressing traditional intermediary layers while regulatory emissions mandates accelerate powertrain diversification across North American temperature-controlled networks.
Autonomous mobile robots in cold storage facilities is bifurcating warehouse labor models. Frozen and refrigerated 3PL operators deploy AMR fleets for pallet transport and high-bay retrieval, cutting pick-path times by half. Labor cost arbitrage is collapsing as automation capital substitutes for scarce forklift operators in land-constrained California and Texas distribution nodes.
EPA Phase 2 greenhouse gas standards tighten CO2 and fuel consumption benchmarks for model years 2027 and beyond. Fleet operators face compliance cliffs that force premature diesel retirement and alternative powertrain pilot programs. Multi-state carriers serving the Dallas-Los Angeles corridor pre-position battery-electric and hydrogen assets to meet California's Advanced Clean Trucks mandates ahead of federal deadlines.
Retailers now demand outcome-based temperature integrity guarantees rather than per-mile freight rates. CPG manufacturers negotiate contracts where 3PLs assume liability for product spoilage and shelf-life degradation. This risk transfer concentrates among cold storage operators with redundant refrigeration and real-time environmental monitoring across the US Sun Belt.
North America FMCG Logistics Market Segmentation
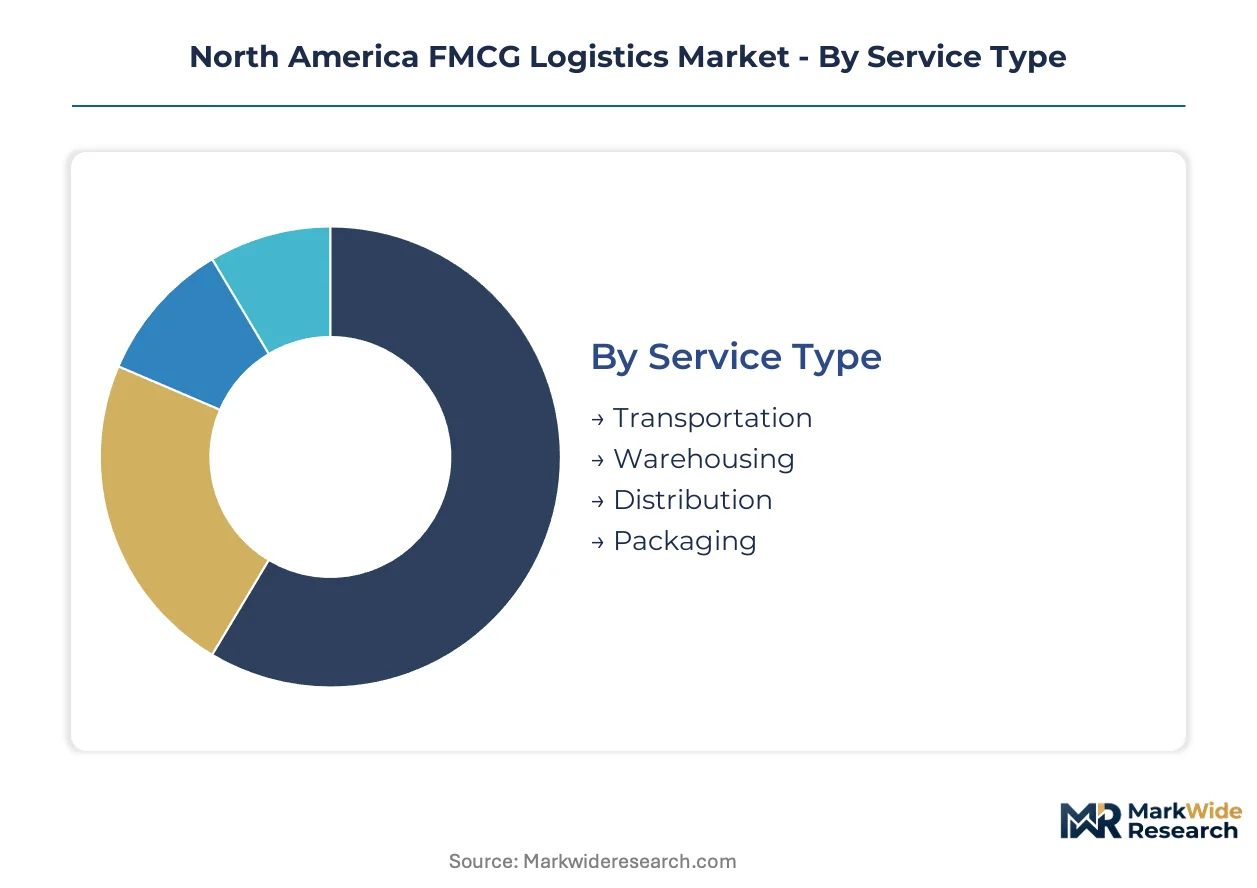
FMCG logistics segmentation reveals how service specialization, technology deployment, and delivery velocity separate margin pools across temperature-controlled and ambient supply chains. Regulatory pressure on emissions and labor scarcity near consumption clusters reshape which segments capture investment priority.
Service Type:
EPA Phase 2 standards and California's Advanced Clean Trucks regulation create divergent capital intensity across service modalities, forcing operators to align fleet composition with corridor-specific compliance timelines.
- Transportation:Interstate trucking of perishables and ambient goods operates under FMCSA hours-of-service constraints and tightening CO2 benchmarks. Demand concentrates along the Texas-California freight corridor where zero-emission pre-positioning accelerates ahead of federal mandates.
- Warehousing:Automated high-bay cold storage facilities command premium capital deployment near Dallas-Fort Worth and Los Angeles basin consumption clusters. Land scarcity within 30 miles of metropolitan centers compresses operating margins while robotics offset labor availability constraints.
- Distribution:Cross-docking and consolidation nodes synchronize high-velocity replenishment cycles with retail shelf-life requirements.
- Packaging:Temperature-controlled protective solutions maintain ±2°F variance protocols for perishables through final delivery handoffs.
Established volume favors transportation; emerging adoption favors warehousing.
End User:
Procurement authority is shifting from traditional intermediaries toward direct platform control, fragmenting contract structures and shortening fulfillment windows.
- E-commerce Platforms:Same-day and next-day expectations compress fulfillment windows to under 24 hours, demanding micro-fulfillment nodes within 50 miles of urban centers. California and Texas operators expand temperature-controlled last-mile infrastructure to serve platform-direct contracts.
- Retailers:Grocery and mass-market chains negotiate outcome-based temperature integrity guarantees rather than per-mile rates, transferring spoilage liability to 3PLs.
- Wholesalers:Traditional retail-wholesaler dominance in FMCG fulfillment networks faces volume displacement from platform-direct sourcing.
- Manufacturers:CPG producers seek integrated port-to-door temperature management from Los Angeles-Long Beach complexes through final delivery.
Legacy volume sits with retailers; steepest expansion trajectory belongs to e-commerce platforms.
Technology:
Capital allocation across technology layers determines shrinkage reduction and dynamic routing capabilities in multi-temperature supply chains.
- IoT:Real-time environmental monitoring enables predictive intervention before temperature excursions breach ±2°F protocols. Deployment concentrates among cold storage operators with redundant refrigeration across the US Sun Belt.
- RFID:Item-level tracking reduces inventory discrepancies and enables automated receiving at high-velocity distribution nodes.
- Automation:Autonomous mobile robots in frozen and refrigerated facilities cut pick-path times by half, substituting capital for scarce forklift operators.
- Tracking Systems:GPS and telematics integration supports FMCSA compliance documentation and route optimization.
Current investment gravitates toward IoT; automation gains share fastest in land-constrained California and Texas nodes.
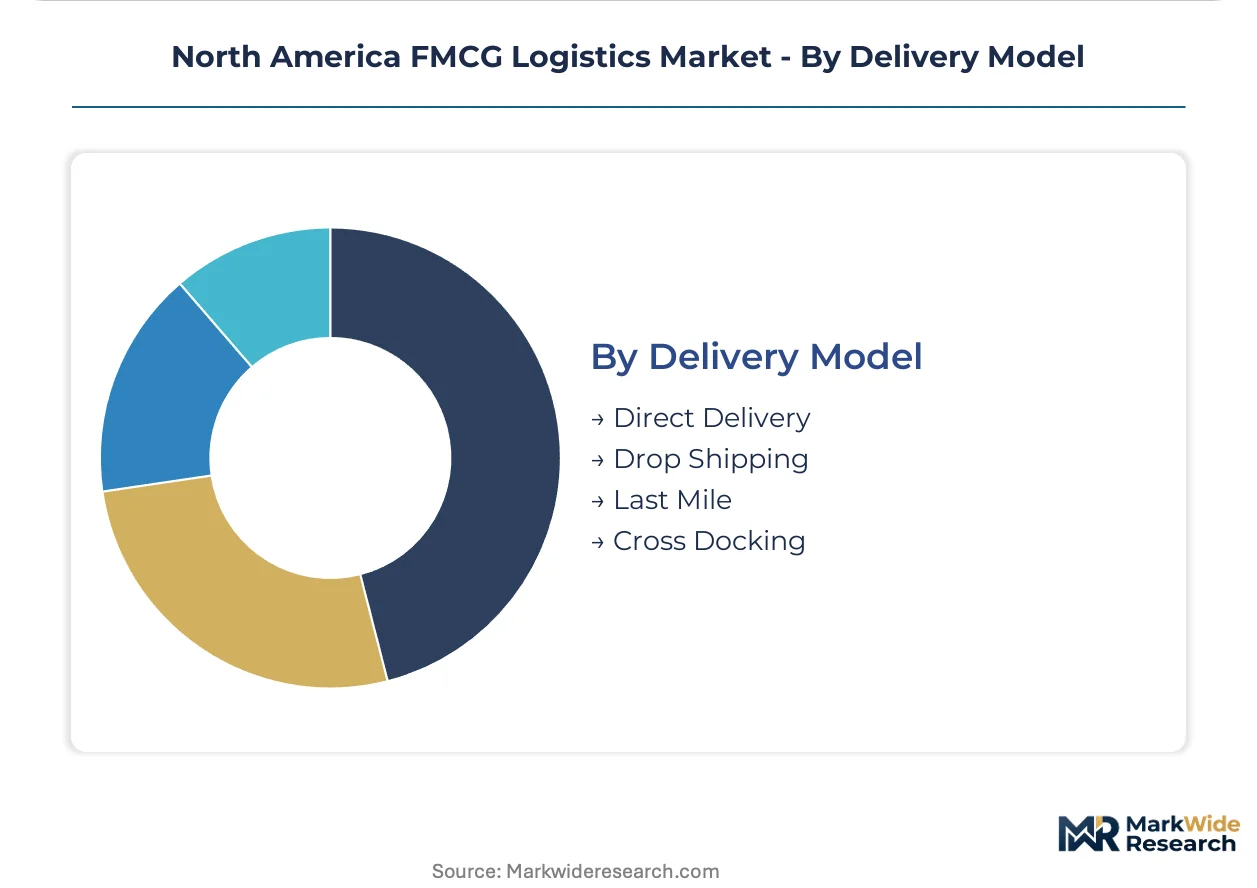
Delivery Model:
Inventory velocity requirements and real estate constraints determine which delivery architectures minimize holding costs.
- Last Mile:Temperature-controlled final delivery within urban centers requires refrigerated vehicle assets and driver pools compliant with local emissions ordinances. California's Advanced Clean Trucks regulation accelerates zero-emission vehicle deployment for urban routes.
- Cross Docking:Minimal inventory holding through rapid freight transfer dominates perishable grocery replenishment.
- Direct Delivery:Manufacturer-to-retailer shipment bypasses intermediary handling for high-volume SKU lanes.
- Drop Shipping:Platform-fulfilled orders ship directly from manufacturer or 3PL inventory without retailer warehousing.
Operational scale favors cross docking; regulatory pressure and platform demand expand last mile most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics infrastructure clusters along three distinct freight corridors where consumption density and cross-border manufacturing integration create differentiated operational requirements. The United States anchors capacity deployment through its regulatory mandates and e-commerce platform concentration. Mexico and Canada complete the triad with specialized cross-border and temperature-controlled trade lanes.
United States
The Texas-California freight corridor generates disproportionate volume as Dallas-Fort Worth and Los Angeles basin distribution nodes synchronize high-velocity replenishment cycles. EPA Phase 2 greenhouse gas standards force fleet operators toward alternative powertrains ahead of model year 2027 compliance cliffs. California's Advanced Clean Trucks regulation accelerates zero-emission asset pre-positioning in the Southwest.
Mexico
Nearshoring manufacturing to Mexican industrial corridors expands synchronized US-Mexico cold chain infrastructure for temperature-sensitive consumer goods. The country's central bank monitors peso volatility that affects cross-border freight contract pricing. Nuevo León and the Bajío Region concentrate automotive and electronics manufacturing requiring just-in-time logistics coordination.
Canada
Ontario and Quebec distribution networks integrate with US Midwest consumption clusters through the Windsor-Detroit and Buffalo-Toronto corridors. Health Canada regulations on food safety and pharmaceutical distribution align with FDA standards to facilitate seamless cross-border temperature-controlled transport. Vancouver anchors Pacific Rim import consolidation for western Canadian markets.
North America FMCG Logistics Market Competitive Landscape
Concentration sits with integrated cold storage operators and digital freight platforms that control temperature-controlled capacity across high-density corridors. The market structure shows tiered specialization between asset-heavy warehouse operators and asset-light brokerage platforms. Three archetypes dominate: automated high-bay cold storage specialists, digital freight-matching platforms, and integrated port-to-door temperature managers. Competitive moves center on warehouse automation capital deployment and strategic partnerships to secure last-mile refrigerated capacity.
Within the integrated cold storage tier, Lineage Logistics and Americold occupy positions as automated warehousing anchors. C.H. Robinson represents the digital freight-matching archetype with platform-based spot-market capture. These three companies exemplify the strategic divergence between asset-heavy infrastructure control and asset-light technology intermediation in North American temperature-controlled networks.
| Leading Market Players |
|---|
| C.H. Robinson |
| Americold |
| DHL Group |
| XPO, Inc. |
| Kuehne+Nagel |
| CEVA Logistics |
| FedEx |
| Lineage Logistics |
| DB Schenker |
| Others |
Value Network & Pricing Analysis
Automated high-bay cold storage capacity near Dallas-Fort Worth and Los Angeles basin nodes generates scale economies that compress per-pallet handling costs while elevating price floors for temperature-controlled services. Fleet electrification mandates from EPA Phase 2 standards and California's Advanced Clean Trucks regulation force capital reallocation that reshapes both supply concentration and rate-setting power across interstate corridors.
Pricing Analysis
Volume-discount tiering structures separate enterprise shippers with annual contracted lane commitments from spot-market participants absorbing volatility premiums. Price differentiation hinges on temperature integrity certification levels and dedicated fleet availability versus shared capacity pools. Pricing pressure stems from battery-electric truck capital intensity requiring 2-3x upfront investment versus diesel equivalents. E-commerce platforms demonstrate highest price sensitivity as they optimize fulfillment costs against same-day delivery promises, while pharmaceutical manufacturers accept premium rates for redundant cold chain protocols.
Supply Chain Analysis
Inventory velocity requirements compress lead times to under 24 hours for perishable replenishment cycles across Texas-California freight lanes. Supply concentration centers on automated warehousing nodes in California, Texas, and Illinois where land scarcity elevates facility costs. The network draws from diesel and emerging battery-electric fleet assets, specialized refrigeration technicians, and IoT-enabled tracking hardware. Single-source vulnerability sits with California port complexes handling Pacific Rim FMCG imports. Distribution runs through cross-docking consolidation nodes synchronizing manufacturer output with retail shelf-life constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American FMCG logistics functions as a defensive-moat market where regulatory entrenchment in emissions compliance and temperature-controlled certification creates switching costs that protect incumbent positions. Network effects concentrate among operators controlling automated high-bay capacity across the Dallas-Los Angeles corridor.
For Market Incumbents: Consolidate automated warehousing positions in land-constrained California and Texas consumption clusters to preempt emerging cold storage entrants. Acquire specialized refrigeration technician training pipelines to offset labor scarcity threatening uptime in high-bay facilities. EPA Phase 2 compliance cliffs present margin pressure requiring accelerated fleet electrification or rate surcharge absorption.
For New Entrants and Emerging Players: Lead with Mexico cross-border temperature-controlled infrastructure as nearshoring manufacturing expands synchronized US-Mexico cold chain demand. Target mid-tier retailers seeking alternatives to integrated port-to-door contracts dominated by established operators. Differentiate through RFID-IoT convergence offering real-time spoilage liability transfer that incumbent legacy systems cannot match.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated high-bay cold storage specialists with established California-Texas corridor density over asset-light freight brokers facing margin compression. Long-term viability rests on regulatory compliance infrastructure that new capital cannot replicate quickly. Watch California Advanced Clean Trucks enforcement intensity as inflection indicator for fleet replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Automation Deployment | Robotics substitution for scarce forklift operators compresses pick-path times by half in California and Texas nodes. |
| Zero-Emission Fleet Pre-Positioning | Battery-electric and hydrogen asset deployment ahead of EPA Phase 2 mandates secures California corridor access. |
| Port-to-Door Temperature Integration | Controlling Los Angeles-Long Beach handoffs through final delivery captures value from CPG manufacturer outsourcing. |
| RFID-IoT Convergence Investment | Real-time perishable tracking enables dynamic routing and shrinkage reduction across multi-temperature supply chains. |
| Mexico Cross-Border Infrastructure | Nuevo León and Bajío Region manufacturing expansion demands synchronized cold chain capacity for just-in-time coordination. |
Research Methodology
A standing panel of fleet operations directors, cold storage facility managers, CPG supply chain executives, and refrigerated carrier procurement leads provided ongoing calibration against market developments throughout the study period. Primary fieldwork combined structured interviews with secondary validation through FMCSA hours-of-service filings, EPA emissions compliance databases, California Air Resources Board regulatory notices, and SEC disclosures from publicly traded logistics operators. Bottom-up segment sizing triangulated against top-down corridor volume estimates from customs and cross-border trade data.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled service type, end-user category, technology deployment, and delivery velocity dimensions alongside corridor-specific regulatory compliance tiers. CAGRs derived from segment-level growth trajectories weighted by capital deployment patterns in automated warehousing and alternative powertrain fleets.
Forecasts assume regulatory continuity in EPA Phase 2 standards and California Advanced Clean Trucks mandates; material policy acceleration or federal preemption would require re-modeling. Specific risks include refrigeration technician training pipeline shortfalls, lithium-ion battery supply constraints for electric trucks, and peso volatility affecting Mexico cross-border contract pricing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Moving Services (Mover and Packers) Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
Egypt Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Digital Freight Forwarding Market
Logistics and Shipping
Warehousing and Distribution Logistics Market
Logistics and Shipping
France Cold Chain Logistics Market
Logistics and Shipping
Nigeria Air Freight Market
Logistics and Shipping
North America Same Day Delivery Market
Logistics and Shipping
Egypt Freight and Logistics Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
Military Logistics Market
Logistics and Shipping
Maritime Logistics and Services Market
Logistics and Shipping
Timber Logistics Market
Logistics and Shipping
North America Freight Brokerage Market
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
Netherlands Cold Chain Logistics Market