
 New Zealand Freight and Logistics Market | 2026-2036
New Zealand Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Freight and Logistics Market Foresight
The Emissions Reduction Plan is expanding compliance costs for diesel-heavy fleets entering the New Zealand freight and logistics sector. Mainfreight Ltd leverages its integrated Asia-Pacific network to sustain cross-border volume density. KiwiRail Holdings, Ltd. anchors intermodal capacity along the North Island Main Trunk corridor. Freightways Ltd differentiates through time-critical courier and healthcare logistics specialization.
New Zealand freight and logistics encompasses the physical movement, storage, and customs facilitation of goods across road, rail, sea, and air modes, typically measured by tonne-kilometres and container throughput. Refrigerated transport dominates agricultural export corridors, requiring continuous cold-chain integrity from farm gate to port. Transportation services command the largest revenue pool within service type segmentation, while warehousing margins tighten near Auckland and Tauranga port zones. E-commerce end users are reshaping last-mile infrastructure requirements, forcing automation investment into sortation hubs. IoT solutions and cloud computing within technology segmentation are displacing legacy telematics as fleet operators seek real-time cargo visibility.
WorkSafe New Zealand governs heavy vehicle operator fatigue and load safety standards, while the New Zealand Transport Agency administers road user charges and vehicle dimensions regulations. The Ministry of Transport coordinates mode-shift policies that redirect bulk freight from road to rail and coastal shipping. Stakeholders must monitor how carbon border adjustment mechanisms in Australia and East Asian export destinations reshape shipping route economics and vessel fuel choices.
Market Dynamics
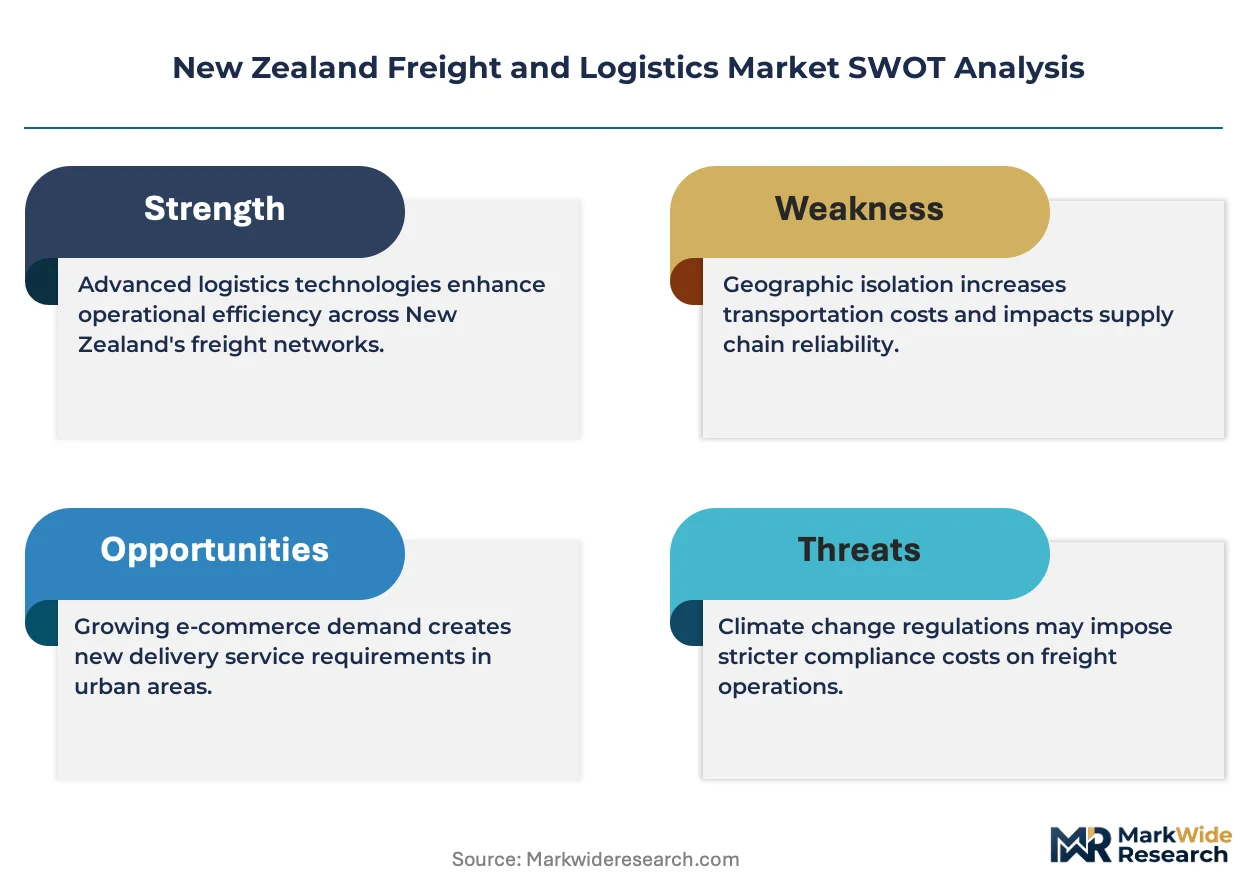
The Emissions Reduction Plan is compressing diesel fleet economics while e-commerce fulfillment pulls refrigerated capacity into Auckland and Christchurch corridors, reshaping asset deployment across the North Island logistics cluster.
Growth Catalysts
- Auckland-Christchurch refrigerated corridor expansion:E-commerce fulfillment demand is pulling cold-chain trucking capacity into these urban corridors, tightening spot market rates and accelerating fleet renewal cycles.
- WorkSafe New Zealand fatigue compliance:Stricter enforcement of heavy vehicle operator standards is professionalizing driver labor pools and pushing mid-sized carriers toward outsourced fleet management.
- IoT cargo visibility platforms:Cloud-based telematics are displacing legacy tracking systems, enabling real-time temperature monitoring across dairy and meat export chains.
Market Restraints
- Diesel fuel cost volatility:Road user charges administered by the New Zealand Transport Agency compound fuel price swings, squeezing margins for long-haul operators without fuel surcharge mechanisms.
- Auckland port zone warehousing concentration:Industrial land scarcity near Tauranga and Auckland ports is inflating storage costs and limiting network redundancy for agricultural exporters.
- Intermodal infrastructure gaps:KiwiRail's North Island Main Trunk corridor lacks sufficient rolling stock to absorb bulk freight shifts from road, constraining mode-switch policy goals.
Strategic Opportunities
- Waikato inland port development:The upper North Island logistics cluster spanning Hamilton offers underutilized rail-served industrial zones for distribution center expansion.
- Healthcare logistics specialization:Time-critical pharmaceutical and medical device distribution remains fragmented, creating white space for temperature-validated courier networks.
- Carbon border adjustment alignment:Australia's emerging carbon border mechanisms create first-mover advantage for New Zealand fleets investing in biofuel blends and electric terminal tractors.
Industry Challenges
- Commercial driver license pipeline:WorkSafe New Zealand certification timelines and aging workforce demographics are constraining qualified heavy vehicle operator supply.
- Legacy telematics integration:Fleet management software migration from on-premise servers to cloud architectures requires capital expenditure and operational downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Freight and Logistics Market |
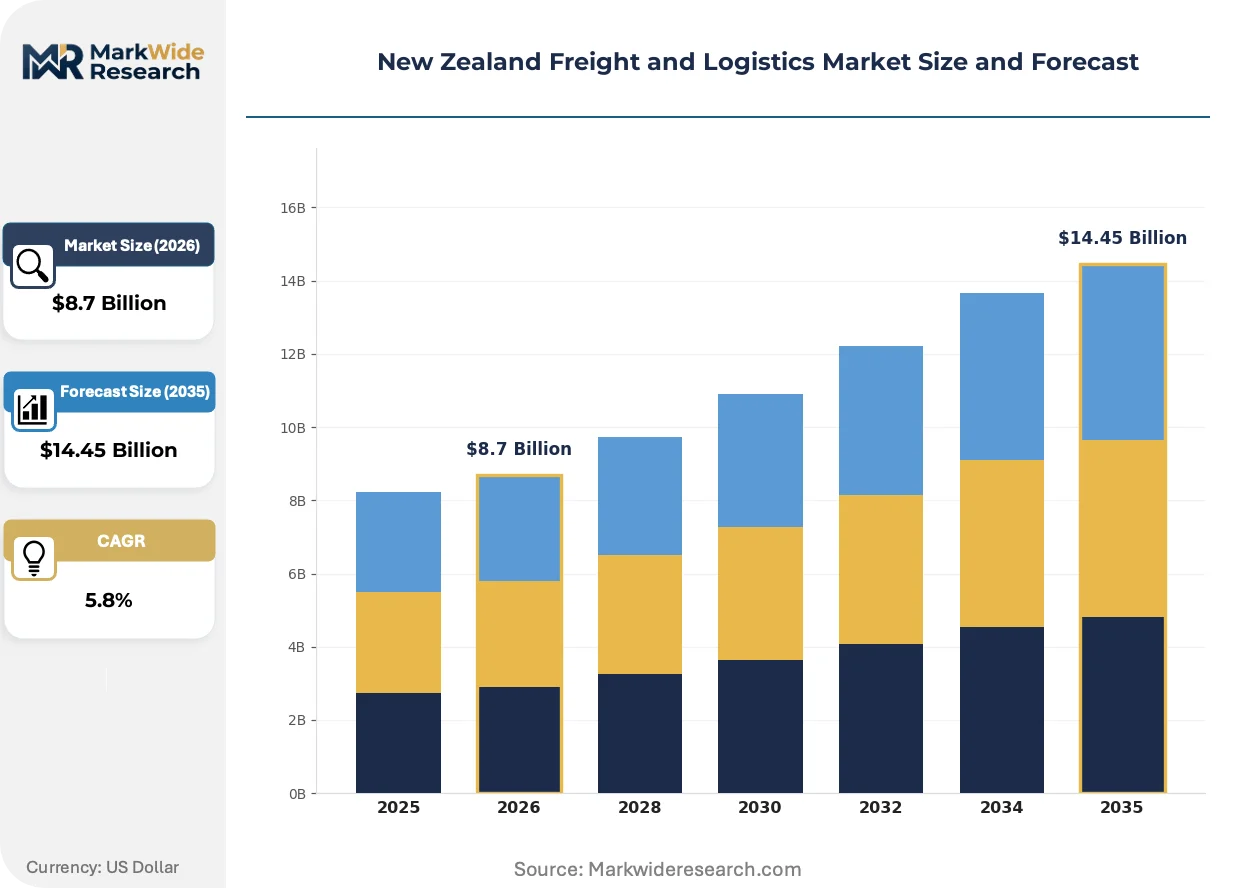
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Customs Brokerage End User: Retail, Manufacturing, E-commerce, Agriculture Technology: IoT Solutions, Cloud Computing, Automation, Blockchain Distribution Channel: Direct Sales, Online Platforms, Third-party Providers, Intermodal |
| Companies Covered | HW Richardson Group, Oceanbridge, Mainfreight Ltd, NZ Post, KiwiRail Holdings, Ltd., Freightways Ltd, Kotahi Logistics, Daily Freight, TIL Logistics Group Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Freight and Logistics Market Shifts & Advancements
Digital freight matching platforms and automated sortation hardware are compressing traditional brokerage margins while reshaping last-mile infrastructure requirements across New Zealand's urban corridors.
Telematics platforms integrating IoT sensors with cloud-based analytics are absorbing legacy GPS tracking market share by enabling real-time cargo condition monitoring. Dairy and meat exporters are adopting these systems fastest, driven by cold-chain integrity requirements for Asian export destinations. The technology is absorbing smaller fleet operators who previously relied on manual check-calls, consolidating vendor relationships around integrated platform providers.
The Ministry of Transport's mode-shift policies are tightening road user charge differentials to redirect bulk freight toward rail and coastal shipping. This regulatory pressure is accelerating investment in intermodal container handling equipment at Tauranga and Napier ports. Agricultural exporters with high-volume, low-time-sensitivity cargo are responding by renegotiating long-term contracts to include rail-first routing clauses.
Same-day delivery expectations from e-commerce end users are compressing last-mile distribution networks into micro-fulfillment configurations. Traditional hub-and-spoke courier models are yielding to automated sortation hubs in Auckland and Christchurch suburbs. Food and beverage verticals show the most visible demand rotation, with grocery chains deploying dark stores to bypass supermarket shelf constraints.
New Zealand Freight and Logistics Market Segmentation
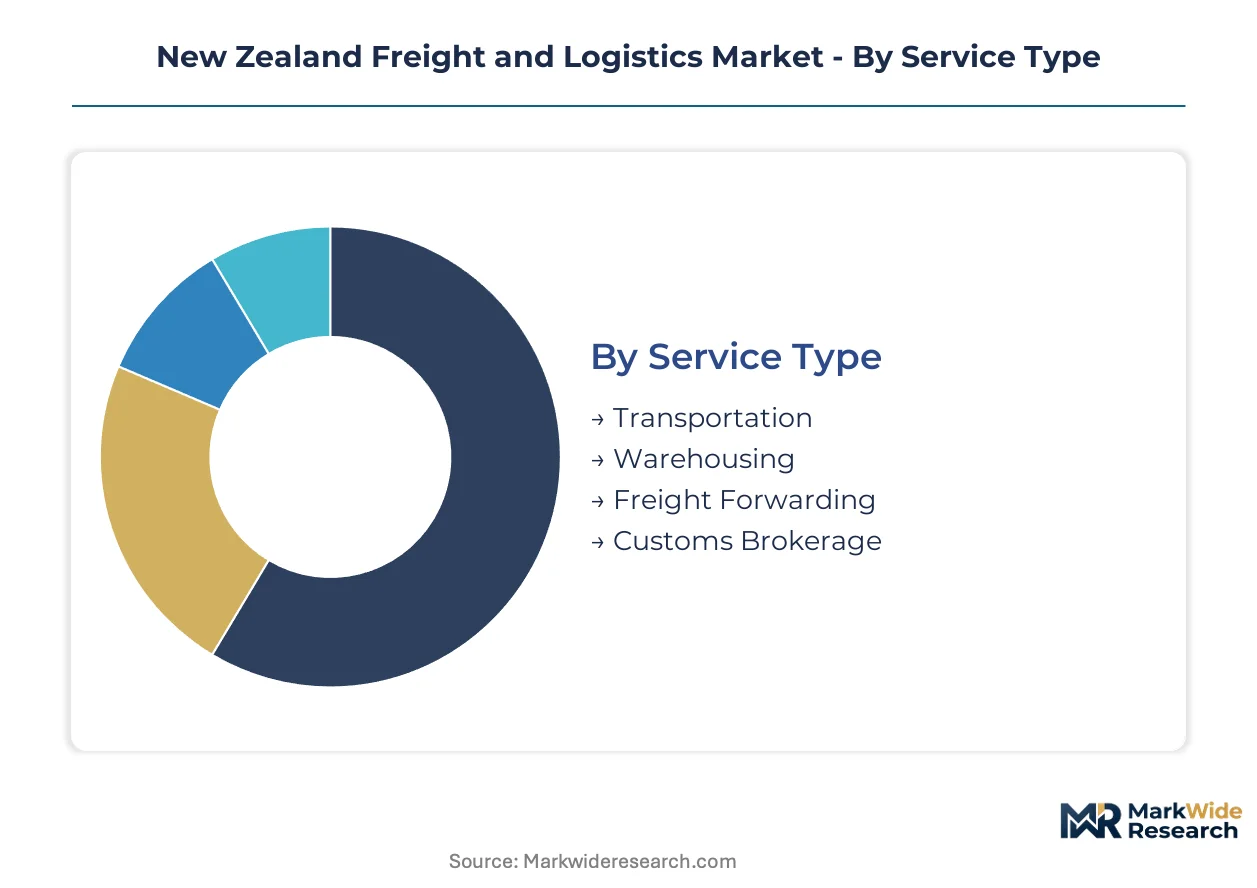
New Zealand freight and logistics segmentation reveals how service specialization, technology adoption, and end-use concentration reshape asset deployment across the Auckland-Tauranga-Hamilton corridor. Each axis exposes distinct margin structures and capital intensity patterns that determine competitive positioning.
Service Type:
Road-based service specifications dominate revenue capture, while integrated offerings command premium positioning through cross-border density.
- Transportation:Refrigerated trucking anchors agricultural export corridors with continuous cold-chain integrity from Waikato dairy farms to Tauranga port. Demand concentrates in Auckland-Christchurch urban corridors where e-commerce fulfillment tightens spot rates and accelerates fleet renewal cycles.
- Warehousing:Temperature-controlled storage facilities near Auckland and Tauranga port zones face industrial land scarcity inflating per-square-meter costs. Agricultural exporters with high-volume, low-time-sensitivity cargo are renegotiating contracts to include rail-served inland port clauses.
- Freight Forwarding:Cross-border customs facilitation and Asia-Pacific routing optimization absorb mid-sized carriers seeking integrated network access.
- Customs Brokerage:Compliance specialization around biosecurity protocols and carbon border documentation requirements serves meat and dairy export verticals.
Mature deployment sits with Transportation. Newer deployment is concentrated in Customs Brokerage.
End User:
Customer-type segmentation exposes divergent service-level requirements and infrastructure investment priorities across New Zealand's economic base.
- Retail:Traditional brick-and-mortar distribution networks face margin compression as inventory velocity requirements tighten. Regional supermarket chains are deploying dark store configurations in Auckland suburbs to bypass shelf constraints.
- Manufacturing:Just-in-time component delivery demands time-definite road transport with cross-dock consolidation at Hamilton industrial zones.
- E-commerce:Same-day delivery expectations compress last-mile networks into micro-fulfillment hubs with automated sortation hardware. Food and beverage verticals show visible demand rotation toward suburban fulfillment nodes.
- Agriculture:Dairy and meat exporters drive refrigerated capacity investment with cold-chain integrity mandates for Asian destination markets.
Established volume anchors Agriculture. Steepest expansion trajectory belongs to E-commerce.
Technology:
Technology segmentation tracks displacement of legacy systems by cloud-native platforms with real-time cargo visibility capabilities.
- IoT Solutions:Sensor-integrated telematics enable real-time temperature monitoring across export supply chains. Dairy and meat exporters adopt these systems fastest, consolidating vendor relationships around integrated platform providers who absorb smaller fleet operators.
- Cloud Computing:Fleet management software migration from on-premise servers to cloud architectures requires capital expenditure and operational downtime, pushing mid-sized carriers toward outsourced solutions.
- Automation:Automated sortation hubs in Auckland and Christchurch suburbs compress traditional brokerage margins while reshaping labor requirements.
- Blockchain:Distributed ledger applications for supply chain documentation remain nascent, with pilot programs concentrated in high-value pharmaceutical and seafood export tracking.
Proven adoption concentrates in IoT Solutions. Emerging investment flows to Blockchain.
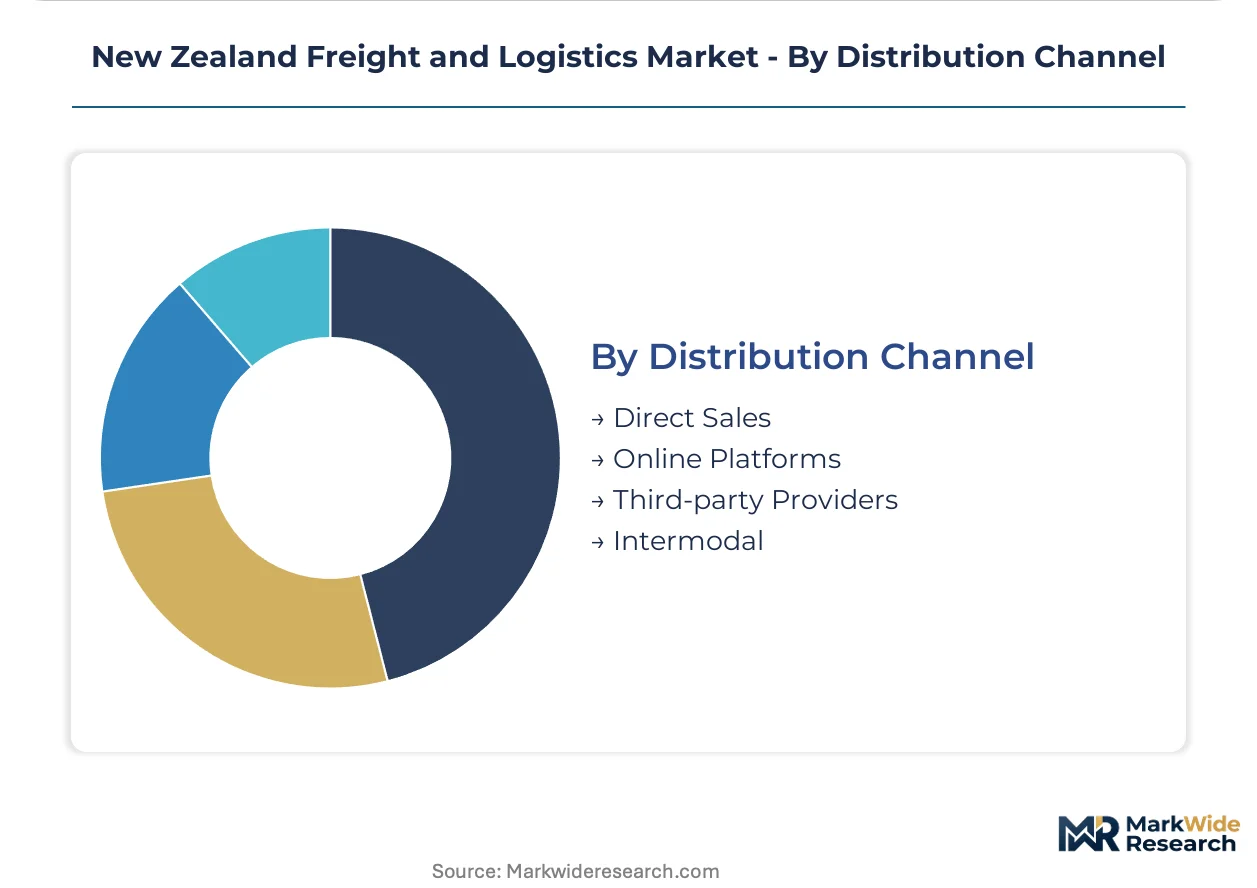
Distribution Channel:
Channel structure determines cost-to-serve economics and customer relationship depth across New Zealand's fragmented carrier landscape.
- Direct Sales:Large agricultural exporters and manufacturing conglomerates negotiate long-term contracts with dedicated fleet allocation and fuel surcharge mechanisms.
- Online Platforms:Digital freight matching platforms absorb spot market volume from small and mid-sized shippers seeking rate transparency.
- Third-party Providers:Outsourced fleet management and driver labor pools professionalize compliance with WorkSafe New Zealand fatigue standards.
- Intermodal:Rail-first routing clauses respond to Ministry of Transport mode-shift policies tightening road user charge differentials.
Volume concentration rests with Direct Sales. Channel expansion is accelerating through Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the upper North Island logistics cluster spanning Auckland, Tauranga, and Hamilton, where port throughput and refrigerated agricultural exports drive capacity allocation decisions across road and rail modes.
Auckland
E-commerce fulfillment demand pulls refrigerated trucking capacity into the Auckland corridor, tightening spot market rates and accelerating fleet renewal cycles. WorkSafe New Zealand enforces heavy vehicle operator fatigue standards that professionalize driver labor pools. The Auckland port zone faces industrial land scarcity inflating warehousing costs and limiting network redundancy.
Waikato
Dairy and meat exporters anchor refrigerated transport demand from farm gate to Tauranga port with continuous cold-chain integrity requirements. The Ministry of Transport coordinates mode-shift policies redirecting bulk freight from road to rail through this corridor. Hamilton offers underutilized rail-served industrial zones for distribution center expansion serving agricultural export chains.
Bay of Plenty
Tauranga port throughput drives container handling equipment investment and intermodal container facility development. The Emissions Reduction Plan tightens fleet carbon standards for diesel-heavy trucking serving this export gateway. Industrial land scarcity near the port zone inflates per-square-meter storage costs for agricultural exporters.
Canterbury
Christchurch anchors South Island refrigerated corridor expansion as e-commerce fulfillment pulls cold-chain capacity into urban delivery networks. The New Zealand Transport Agency administers road user charges compounding fuel price volatility for long-haul operators. Automated sortation hubs in Christchurch suburbs compress traditional brokerage margins while reshaping last-mile infrastructure.
New Zealand Freight and Logistics Market Competitive Landscape
Auckland-based integrated networks anchor one tier; regional specialists and rail operators hold differentiated positions in corridor-specific segments. The market structure reflects moderate consolidation around vertically integrated Asia-Pacific networks alongside fragmented mid-sized carriers facing compliance cost pressures. Three archetypes dominate: integrated multimodal operators with cross-border density, rail-anchored intermodal providers along the North Island Main Trunk, and time-critical courier specialists in healthcare and perishables. Competitive moves concentrate on fleet decarbonization alignment with the Emissions Reduction Plan and automation investment into suburban sortation hubs.
Among integrated network operators, Mainfreight Ltd and Freightways Ltd exemplify the cross-border density and time-critical specialization archetypes respectively. KiwiRail Holdings, Ltd. anchors the rail-intermodal tier along the North Island Main Trunk corridor. These three occupy positions that reflect the market's structural segmentation between international freight forwarding, domestic courier healthcare logistics, and bulk rail freight mode-shift policy alignment.
| Leading Market Players |
|---|
| HW Richardson Group |
| Oceanbridge |
| Mainfreight Ltd |
| NZ Post |
| KiwiRail Holdings, Ltd. |
| Freightways Ltd |
| Kotahi Logistics |
| Daily Freight |
| TIL Logistics Group Limited |
| Others |
Supply & Pricing Matrix
Road user charges administered by the New Zealand Transport Agency flow downstream as fuel surcharge mechanisms or absorbed margin compression depending on contract structure. Long-haul operators without indexed fuel clauses bear diesel volatility directly, while agricultural exporters with rail-first routing clauses shift cost exposure toward intermodal rate negotiations. This input cost architecture stratifies carrier economics across the Auckland-Tauranga-Hamilton corridor.
Pricing Analysis
Lead-time-driven pricing separates time-definite refrigerated transport from spot market dry freight, with dairy exporters paying premiums for guaranteed cold-chain slots during peak harvest windows. Three-tier pricing structure across premium, standard, and economy levels reflects service-level guarantees, cargo insurance bundling, and after-hours delivery availability. Cost compression in standard-tier road haulage intensifies as digital freight matching platforms erode traditional brokerage margins. E-commerce fulfillment networks show least price sensitivity for same-day suburban delivery, while bulk agricultural exporters negotiate hardest on per-tonne-kilometre rates.
Supply Chain Analysis
Warehouse-distribution layer concentration centers on Auckland port zones and Hamilton rail-served industrial parks, with limited redundancy forcing agricultural exporters into single-point-of-failure exposure. Rolling stock shortages on KiwiRail's North Island Main Trunk corridor and coastal shipping capacity constraints create modal inflexibility. Distribution runs through Tauranga as the primary export gateway, with Christchurch handling South Island transhipment. Single-source vulnerability sits with refrigerated container equipment pools concentrated near Auckland and Tauranga port zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
New Zealand freight and logistics functions as a consolidation play where WorkSafe New Zealand compliance costs and Emissions Reduction Plan fleet renewal requirements force sub-scale carriers toward exit or acquisition. Mid-sized operators without integrated Asia-Pacific networks or rail intermodal access face structural margin compression.
For Market Incumbents: Anchor defensive positioning through backward integration into temperature-controlled warehousing near Tauranga port zones, capturing agricultural exporter volume with rail-first contract clauses. Invest in IoT-enabled fleet telematics to professionalize driver labor pools ahead of WorkSafe New Zealand fatigue enforcement tightening. Vertical integration into healthcare courier specialization creates differentiation against digital freight matching platforms eroding standard freight margins.
For New Entrants and Emerging Players: Enter via healthcare logistics fragmentation, where time-critical pharmaceutical distribution lacks temperature-validated courier density outside Auckland. Target Waikato inland port development zones for rail-served distribution center construction, exploiting underutilized industrial land relative to Auckland port zone scarcity. White space sits with carbon border adjustment alignment services for meat and dairy exporters facing Australian emissions documentation requirements.
For Investors and Strategic Acquirers: KiwiRail rolling stock procurement announcements are the leading indicator that mode-shift policy is receiving capital backing sufficient to absorb bulk freight volume from road. Long-term viability favors rail-intermodal operators and integrated Asia-Pacific networks with cross-border density. Acquisition target archetype: regional refrigerated carriers with established agricultural exporter relationships but lacking compliance infrastructure to meet Emissions Reduction Plan standards independently.
| Strategic Initiative | Industry Significance |
|---|---|
| Intermodal Capacity Expansion | Rail-served inland port development at Hamilton absorbs Auckland warehousing scarcity pressure. |
| IoT Fleet Modernization | Cloud-based telematics platforms displace legacy GPS to meet WorkSafe New Zealand visibility mandates. |
| Healthcare Logistics Specialization | Temperature-validated courier networks capture pharmaceutical fragmentation outside Auckland corridor. |
| Carbon Border Alignment Services | Biofuel blend documentation and emissions reporting address Australian export destination requirements. |
| Automated Sortation Investment | Suburban micro-fulfillment hubs in Christchurch compress last-mile delivery costs for e-commerce verticals. |
Research Methodology
New Zealand Transport Agency road user charge databases, Stats NZ trade flow statistics, and KiwiRail freight volume disclosures formed the secondary backbone for demand modeling. Primary interviews with fleet operations managers at refrigerated carriers, agricultural exporter supply chain directors, and port authority commercial officers provided operational validation. Bottom-up triangulation against top-down GDP-correlated freight intensity estimates anchored volume projections. Secondary sources included Ministry of Transport mode-shift policy documentation, WorkSafe New Zealand compliance enforcement records, and Tauranga Port container throughput statistics.
Bottom-up modeling aggregated carrier fleet capacity, route density, and contract renewal cycles across transportation, warehousing, and forwarding segments. Top-down verification cross-checked against macroeconomic trade flow projections and agricultural export commodity forecasts. Segmentation dimensions included service type specialization, end-use vertical concentration, technology adoption tier, and distribution channel structure. CAGRs were derived from trend extrapolation of historical tonne-kilometre growth, port throughput trajectories, and e-commerce fulfillment expansion patterns across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Emissions Reduction Plan enforcement acceleration or prolonged rolling stock procurement delays. Forecasts reflect documented assumptions regarding fuel price volatility, driver license pipeline constraints, and carbon border adjustment mechanism implementation timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
ASEAN Warehousing and Distribution Logistics Market
Logistics and Shipping
Global Freight Broker Software Market
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
Saudi Arabia Last Mile Delivery Market
Logistics and Shipping
US Express Delivery Market
Logistics and Shipping
Internet of Things (IoT) in Logistics Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
Poland Freight and Logistics Market
Logistics and Shipping
Delivery Tracking Platform Market
Logistics and Shipping
Russia Courier Service Market
Logistics and Shipping
Canada Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Nigeria Air Freight Market
Logistics and Shipping
Asia Pacific Automotive Logistics Market
Logistics and Shipping
Australia Freight and Logistics Market
Logistics and Shipping
Global Logistics Market