
 Cross-Linked Polyethylene (XLPE) Market | 2026-2036
Cross-Linked Polyethylene (XLPE) Market Size, Share, and Industry Trends Forecast 2026-2036
Cross-Linked Polyethylene (XLPE) Market Outlook
Polyvinyl chloride is hardening into a cost-disadvantaged position against XLPE in medium-voltage power cable sheathing as utility procurement specifications tighten thermal-performance thresholds. Dow sustains integrated polyethylene-to-XLPE compound production across the US Gulf Coast, capturing feedstock proximity advantages. Prysmian Group dominates submarine and land cable markets through captive XLPE extrusion capacity in Italy and Finland. Nexans competes on European grid interconnector projects where XLPE-insulated high-voltage direct current cables displace oil-filled alternatives.
Cross-linked polyethylene forms when polyethylene chains bond through chemical or physical crosslinking, creating a thermoset polymer with continuous service temperatures up to 90°C and short-circuit tolerance exceeding 250°C; silane grafting and peroxide curing constitute the dominant industrial processes, yielding material for wire insulation, pipe systems, and foamed packaging. XLPE cable insulation captures the largest value pool within product-type segmentation as offshore wind arrays and urban grid upgrades multiply conductor ratings. Construction end-use applications for XLPE pipe in underfloor heating and potable water distribution represent the fastest-expanding demand segment in residential markets. Flooring applications lag in margin contribution due to commodity competition from vinyl and rubber alternatives.
REACH compliance through ECHA governs additive chemistries in European XLPE compounding, restricting certain flame retardants and peroxide initiators that remain permissible under US EPA frameworks. China's GB standards for XLPE power cables mandate partial discharge testing thresholds that exceed IEC baselines, creating technical barriers for imported compounds. India's BIS certification requirements for crosslinked polyethylene pipes in building construction have tightened migration limits for stabilizer packages. Stakeholders must monitor divergence between regional material-approval regimes when configuring multinational supply footprints and R&D allocation.
Market Dynamics
Silane crosslinking technology is compressing capital requirements for XLPE compound production while tightening emission standards across Asian manufacturing corridors, forcing incumbents to retool or exit medium-voltage cable supply.
Growth Catalysts
- Grid Modernization Mandates:State Grid Corporation tenders in China's coastal provinces specify XLPE-insulated medium-voltage cables for urban distribution upgrades, creating sustained compound demand from domestic suppliers.
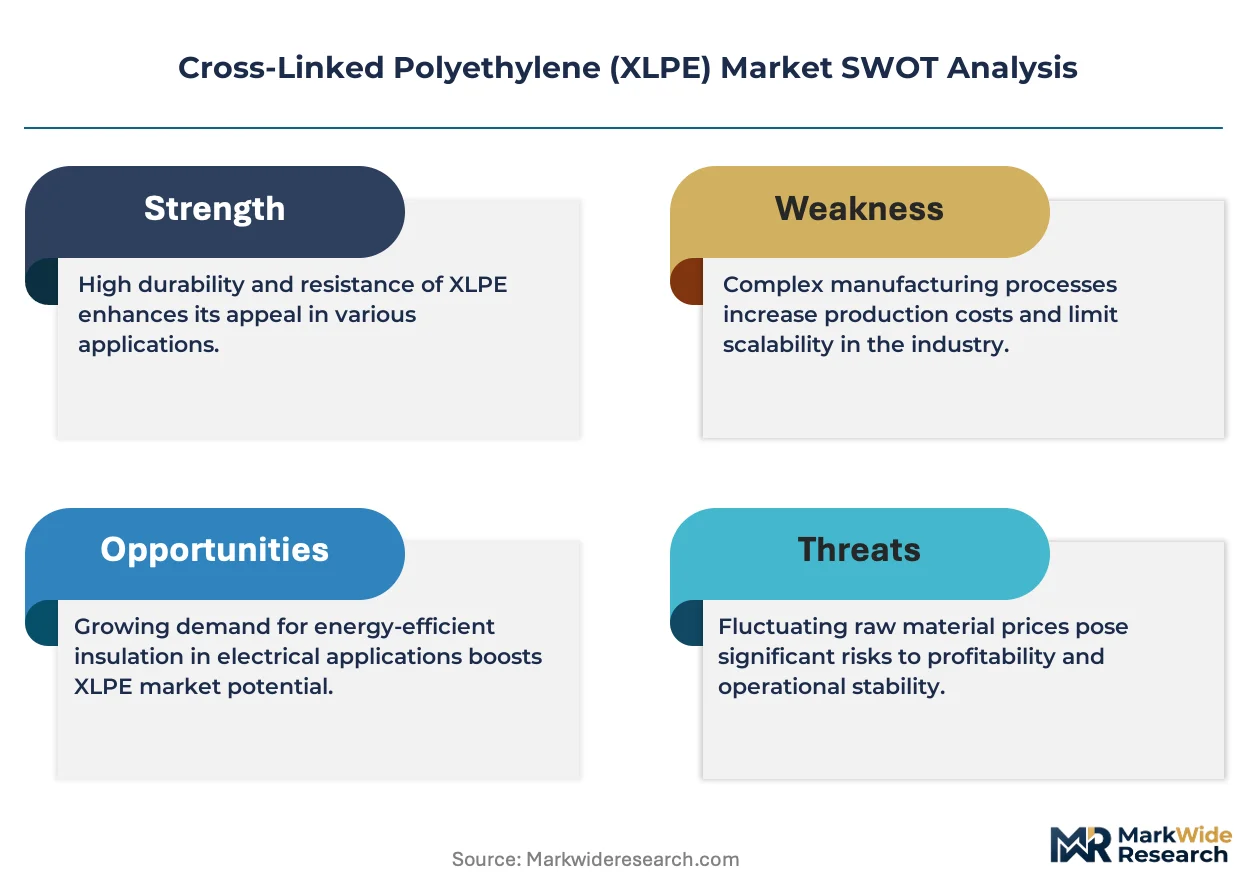
- REACH Phase-Down of Legacy Additives:ECHA restrictions on certain peroxide initiators and halogenated flame retardants are accelerating formulation shifts toward silane-grafting systems in European compounding operations.
- Offshore Wind Array Expansion:Submarine cable contractors in the North Sea and Baltic markets specify XLPE-insulated high-voltage direct current conductors for inter-array and export links, displacing oil-filled alternatives.
Market Restraints
- Ethylene Feedstock Volatility:Naphtha-cracking margins and shale-gas polyethylene output swings in the US Gulf Coast transmit directly to XLPE compound pricing, squeezing converter margins during upstream tightness.
- Chinese Supply Concentration:State-owned petrochemical complexes in Shandong and Jiangsu provinces control over half of Asia-Pacific silane-grafting masterbatch capacity, creating single-source vulnerability for Southeast Asian cable extruders.
- Technical Ceiling in High-Temperature Service:Continuous operating temperatures above 90°C remain inaccessible to standard XLPE formulations, limiting penetration into industrial process heating and certain automotive underhood applications where fluoropolymers dominate.
Strategic Opportunities
- India Building Construction Pipeline:BIS certification requirements for crosslinked polyethylene potable water pipes have tightened migration limits, creating premium-tier positioning for compounders with compliant stabilizer packages.
- EU Green Deal Carbon Border Adjustments:Embedded emissions accounting in imported XLPE compounds favors European producers with renewable-powered cracking and silane recycling, disadvantaging coal-intensive Asian supply.
- Recycling Technology Convergence:Advanced de-crosslinking via supercritical fluid processing and compatibilizer chemistry is enabling closed-loop recovery from cable manufacturing scrap, opening circular material claims for sustainability-specified tenders.
Industry Challenges
- Silane Grafting Process Control:Moisture-cure kinetics in humid tropical climates require precise humidity-controlled extrusion environments that many Southeast Asian cable plants lack, generating scrap rates above 8 percent.
- Dual Certification Timelines:Concurrent GB standard partial discharge testing and IEC baseline qualification for China-bound XLPE power cables extend compound approval cycles by 14-18 months, freezing R&D amortization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cross-Linked Polyethylene (XLPE) Market |
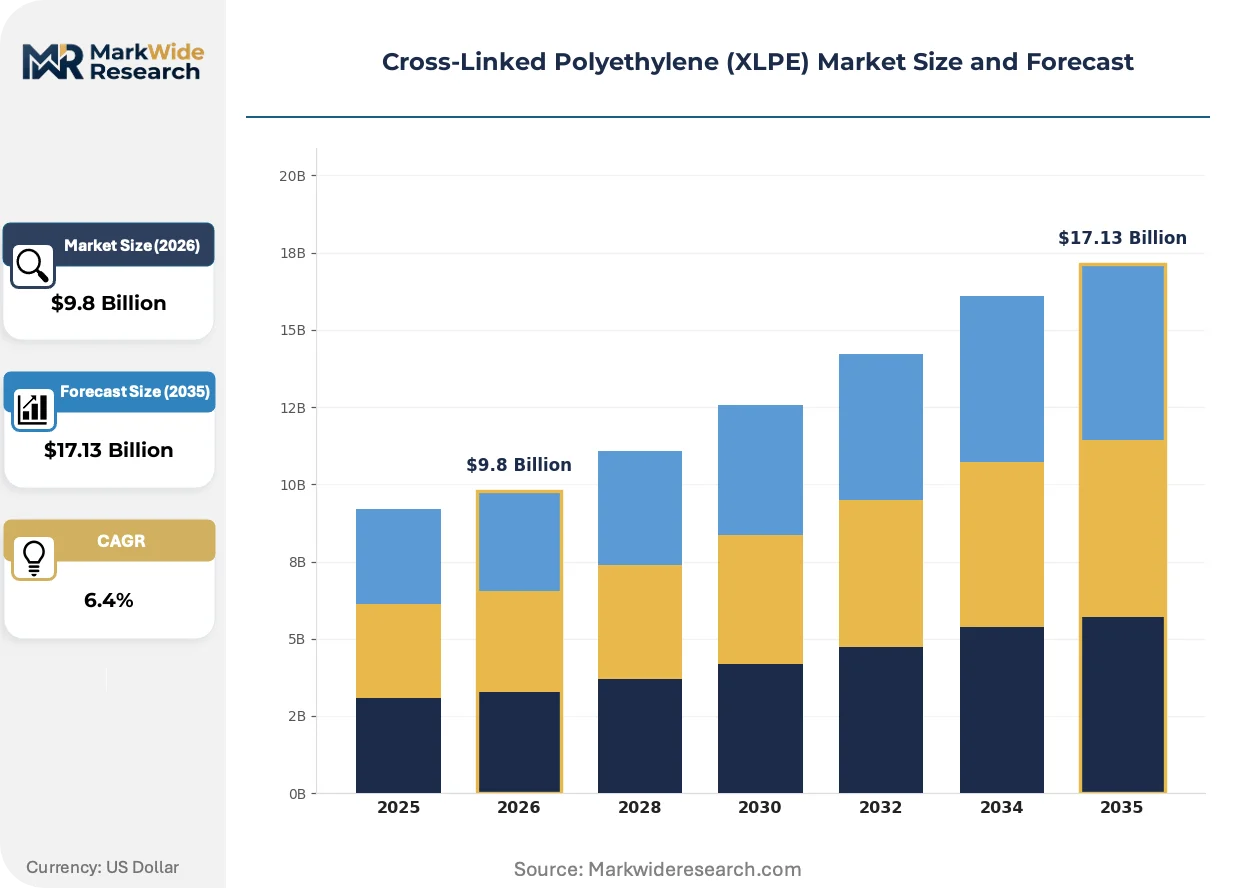
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: XLPE Foam, XLPE Pipe, XLPE Cable, XLPE Sheet End Use Industry: Construction, Automotive, Electrical, Healthcare Form: Sheets, Rolls, Tubes, Profiles Application: Insulation, Packaging, Flooring, Coating |
| Companies Covered | Exxon Mobil Chemical, Prysmian Group, Dow, Nexans, NKT A/S, Borealis AG, Solvay, Sumitomo Electric Industries, LyondellBasell Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cross-Linked Polyethylene (XLPE) Market Strategic Shifts
Formulation science and process control are converging to expand XLPE service envelopes while regulatory chemistry restrictions force additive package redesigns across major manufacturing jurisdictions.
Supercritical carbon dioxide foaming technology is rewriting density-performance tradeoffs in XLPE insulation systems. Offshore wind cable manufacturers in Denmark and Germany are adopting microcellular foamed XLPE layers to reduce conductor weight while maintaining dielectric strength. This density reduction is rewriting transport economics for long-length submarine cable laydown operations.
REACH authorization requirements through ECHA now govern specific organotin catalysts and certain aromatic peroxides used in XLPE crosslinking. Compounders serving European utilities must reformulate with alternative grafting initiators or face supply discontinuation. Medium-voltage cable producers in Italy and Finland are absorbing 12-15 percent formulation cost premiums to maintain CE-marked product lines.
Utility procurement departments now require certified carbon footprint declarations for XLPE-insulated cable awards. Transmission system operators in Germany and the Netherlands weight embodied emissions at 15-20 percent of tender scoring. Cable contractors are responding by sourcing compounds from crackers with verified renewable feedstock fractions and demanding silane supplier Scope 3 disclosures.
Cross-Linked Polyethylene (XLPE) Market Segmentation
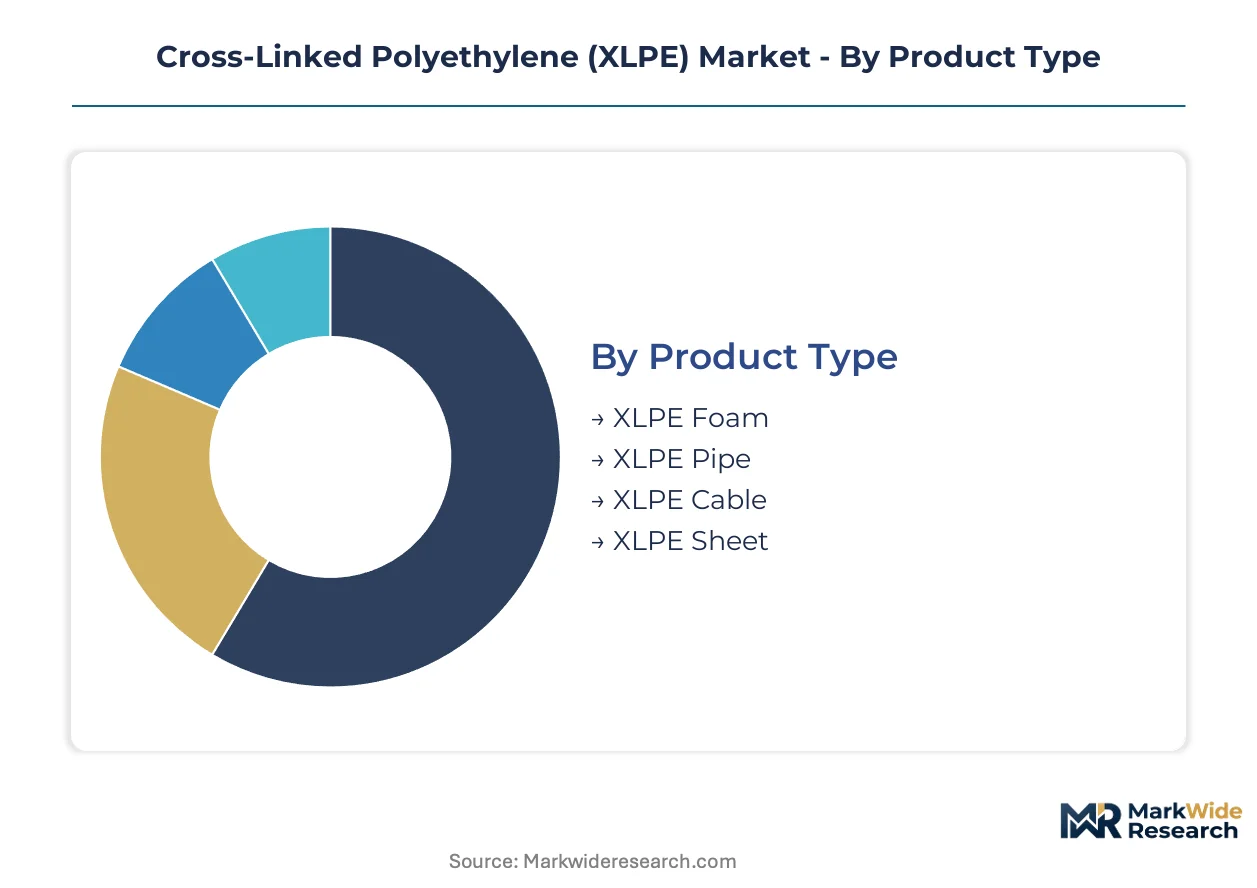
XLPE market segmentation reveals divergent margin structures across product forms and end-use applications. Cable insulation commands premium pricing tied to grid infrastructure cycles, while foam and sheet products compete in commoditized construction supply chains where formulation cost dominates procurement decisions.
Product Type:
Buyers in this category separate by thermal-performance requirements and capital-intensity of downstream processing.
- XLPE Cable:High-voltage insulation grades utilize peroxide-cured formulations for submarine and land-based transmission conductors. State Grid Corporation tenders in China's coastal provinces specify these compounds for urban distribution upgrades, creating sustained demand from domestic suppliers with captive silane-grafting capacity.
- XLPE Pipe:Potable water and underfloor heating systems employ silane-crosslinked formulations with migration-tested stabilizer packages. India's BIS certification tightening has created premium-tier positioning for compliant compounders serving residential construction pipelines in Mumbai and Delhi corridors.
- XLPE Foam:Microcellular structures serve automotive interior padding and HVAC insulation with density-performance tradeoffs managed through supercritical CO2 foaming technology.
- XLPE Sheet:Flat-extruded grades target construction vapor barriers and industrial gasketing where commodity polyethylene competition compresses margins.
Volume sits with XLPE Cable; growth tilts toward XLPE Pipe.
End Use Industry:
Application maturity and regulatory exposure differentiate procurement behavior across verticals.
- Electrical:Transmission system operators in Germany and the Netherlands now weight embodied carbon at 15-20 percent of tender scoring for XLPE-insulated conductor awards. Cable contractors respond by sourcing compounds from crackers with verified renewable feedstock fractions.
- Construction:Residential and commercial building codes in India mandate BIS-certified crosslinked polyethylene for potable water distribution, tightening migration limits that favor compounders with compliant stabilizer chemistry.
- Automotive:Underhood applications remain limited by the 90°C continuous service ceiling of standard XLPE formulations, ceding high-temperature zones to fluoropolymer alternatives.
- Healthcare:Medical packaging and device components require REACH-compliant additive packages with restricted peroxide initiators, extending formulation approval cycles through ECHA governance.
Electrical commands the revenue base; Construction climbs the fastest.
Form:
Processing method and dimensional precision requirements shape converter selection criteria.
- Tubes:Extruded pipe and cable insulation forms dominate tonnage throughput, with moisture-cure kinetics in humid tropical climates requiring humidity-controlled extrusion environments.
- Sheets:Flat-die extrusion serves construction membranes and industrial gasketing where thickness tolerance drives specification compliance.
- Rolls:Wound continuous sheet formats streamline logistics for flooring and roofing membrane installers.
- Profiles:Custom extruded shapes address automotive trim and HVAC ducting with geometry-specific die design requirements.
Tubes anchor current volume; Profiles gain share fastest.
Application:
Performance certification depth and replacement cycle length determine margin capture potential.
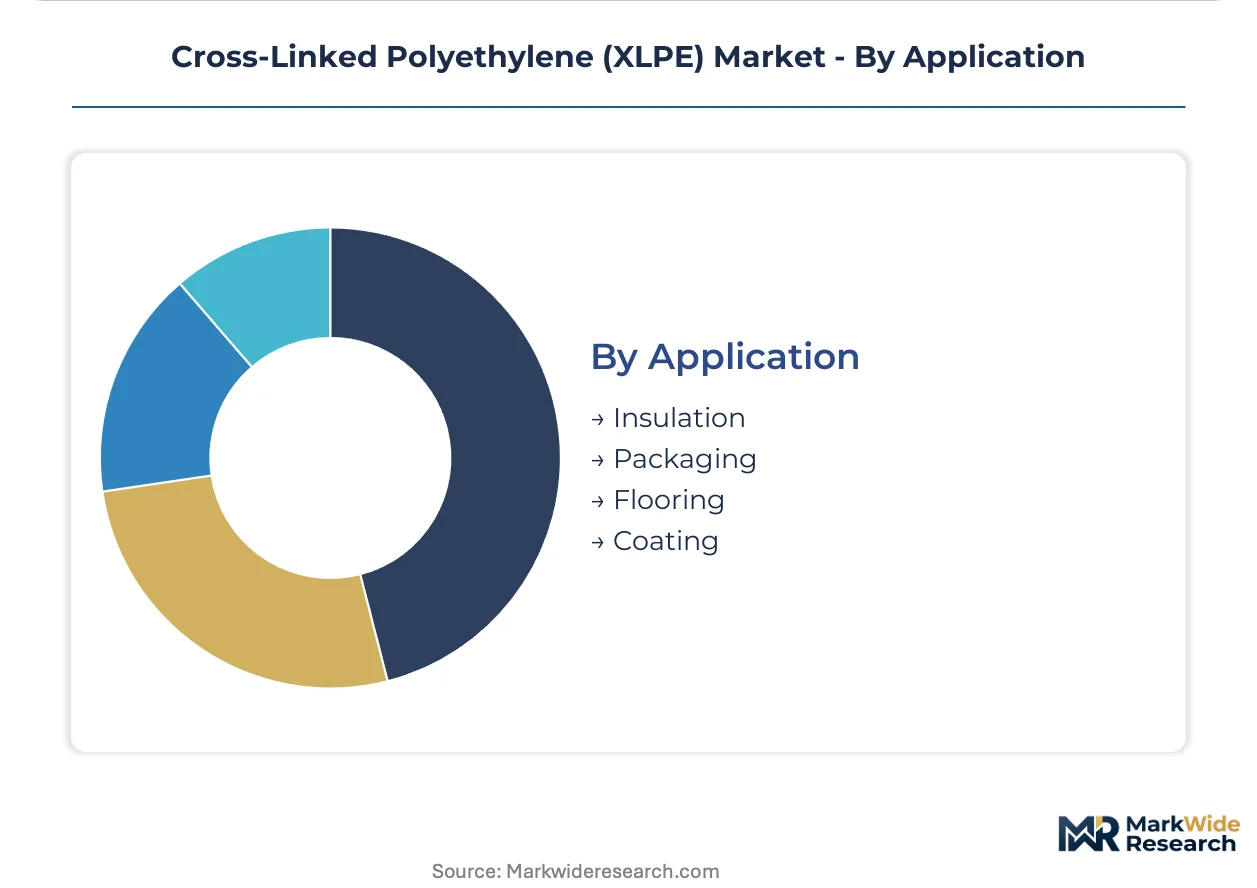
- Insulation:Dielectric-grade formulations for power cables and building thermal barriers carry the most extensive testing protocols, including China's GB standard partial discharge thresholds that exceed IEC baselines.
- Packaging:Foamed protective formats compete with expanded polystyrene and polyurethane alternatives on cushioning efficiency and recyclability claims.
- Flooring:Crosslinked polyethylene underlayment faces commodity competition from vinyl and rubber alternatives, compressing margin contribution.
- Coating:Protective layer applications for wire and pipe benefit from silane-grafting process advances that reduce volatile organic compound emissions versus peroxide curing.
Insulation generates the value pool; Coating expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement in China's coastal provinces concentrates XLPE demand for grid modernization, while European offshore wind expansion and Indian building code enforcement create secondary growth poles across distinct regulatory environments.
China
State Grid Corporation tenders in Shandong and Jiangsu provinces specify XLPE-insulated medium-voltage cables for urban distribution networks. GB standards for power cables mandate partial discharge testing thresholds exceeding IEC baselines, creating technical barriers for imported compounds. Domestic petrochemical complexes in these coastal manufacturing provinces control silane-grafting masterbatch capacity serving Southeast Asian cable extruders.
Germany
Transmission system operators weight embodied carbon at 15-20 percent of tender scoring for XLPE-insulated conductor awards. ECHA REACH restrictions on certain peroxide initiators accelerate formulation shifts toward silane-grafting systems in compounding operations. Cable contractors in the North Sea and Baltic markets specify XLPE-insulated high-voltage direct current conductors for offshore wind inter-array and export links.
United States
Dow maintains integrated polyethylene-to-XLPE compound production across the US Gulf Coast, capturing feedstock proximity advantages from shale-gas polyethylene output. EPA frameworks permit certain flame retardants and peroxide initiators restricted under European regulations, creating formulation divergence for multinational suppliers. Naphtha-cracking margin volatility transmits directly to XLPE compound pricing, squeezing converter margins during upstream tightness.
India
BIS certification requirements for crosslinked polyethylene pipes in building construction have tightened migration limits for stabilizer packages. Residential construction pipelines in Mumbai and Delhi corridors drive demand for potable water and underfloor heating systems. Compounders with compliant stabilizer chemistry occupy premium-tier positioning against commodity competitors.
Italy
Prysmian Group operates captive XLPE extrusion capacity serving submarine and land cable markets. Medium-voltage cable producers absorb 12-15 percent formulation cost premiums to maintain CE-marked product lines under REACH authorization requirements. Microcellular foamed XLPE layers from Danish and German technology adopters reduce conductor weight for long-length submarine cable laydown operations.
Cross-Linked Polyethylene (XLPE) Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical conglomerates controlling upstream compound supply and cable fabricators competing on extrusion scale and certification depth. The vendor base organizes around three archetypes: integrated resin-to-compound producers, captive cable manufacturers with in-house XLPE extrusion, and independent compounders serving regional converter markets. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as players secure feedstock access and utility qualification status.
Within the integrated chemical producer tier, Dow and LyondellBasell Industries exemplify Gulf Coast-based operators with backward control over polyethylene feedstock. Among European cable specialists, Prysmian Group and Nexans occupy positions defined by captive extrusion capacity and submarine project execution. Borealis AG represents the continental European compounder archetype with silane-grafting operations serving utility-specified tenders. Sumitomo Electric Industries anchors the Asia-Pacific manufacturer segment with integrated cable and materials production.
| Leading Market Players |
|---|
| Exxon Mobil Chemical |
| Prysmian Group |
| Dow |
| Nexans |
| NKT A/S |
| Borealis AG |
| Solvay |
| Sumitomo Electric Industries |
| LyondellBasell Industries |
| Others |
Value Chain & Pricing Dynamics
State-owned petrochemical complexes in China's coastal provinces anchor upstream XLPE compound supply, translating sovereign financing advantages into aggressive pricing discipline that compresses margins for privately held European compounders serving utility tenders. This ownership pattern tightens feedstock access for independent cable extruders while amplifying price volatility transmission from naphtha-cracking economics.
Pricing Analysis
Volume concentrates in standard-grade silane-grafting masterbatches for medium-voltage cable insulation, while margin pools in peroxide-cured high-voltage formulations certified for submarine export links. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked REACH-compliant compounds from commodity Asian supply and scrap-tolerant construction grades. Pricing pressure stems from Chinese state-owned producers absorbing ethylene feedstock volatility through integrated refining economics. Small-scale Southeast Asian cable extruders exhibit highest price sensitivity, lacking volume leverage to negotiate long-term offtake terms.
Supply Chain Analysis
Certification gating through GB standards, REACH authorization, and BIS migration limits fragments qualified supplier pools and extends compound approval timelines. Supply concentrates in China, South Korea, and Germany, with Chinese state-owned complexes controlling silane-grafting masterbatch capacity serving Southeast Asian cable plants. Raw material flows draw from naphtha crackers, peroxide initiators, and organotin catalysts subject to ECHA phase-down restrictions. Single-source vulnerability runs through Shandong and Jiangsu province production hubs. Distribution runs through direct mill-to-extruder contracts for high-volume cable insulation, with spot market layering for construction-grade pipe compounds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The XLPE market sits in a technology-transition phase as silane crosslinking displaces peroxide curing across Asian manufacturing corridors, compressing capital requirements while tightening emission standards.
For Market Incumbents: Hedge against Chinese supply concentration by diversifying silane-grafting masterbatch sourcing toward South Korean and European qualified suppliers. Secure captive ethylene feedstock access through backward integration or long-term cracking agreements to defend margin position during naphtha volatility. Accelerate REACH-compliant formulation R&D before ECHA authorization deadlines eliminate legacy peroxide initiators from European supply. For New Entrants and Emerging Players: Capture white-space in India's BIS-certified potable water pipe segment where migration-tested stabilizer packages command premium positioning against commodity competitors. Target Southeast Asian cable extruders struggling with humidity-controlled extrusion scrap rates by offering technical service partnerships for moisture-cure process optimization. Lead with carbon-footprint certification to access German and Dutch transmission operator tenders weighting embodied emissions at 15-20 percent of scoring. For Investors and Strategic Acquirers: State Grid Corporation tender awards for XLPE-insulated medium-voltage cables in Shandong and Jiangsu provinces are the leading indicator that Chinese domestic supply consolidation will accelerate, squeezing independent compounder margins. Long-term viability favors asset-light formulation specialists with silane-recycling capabilities and renewable-powered cracking partnerships over integrated petrochemical conglomerates tethered to coal-intensive economics. Watch for supercritical de-crosslinking technology commercialization as the inflection signal enabling circular material claims in sustainability-specified tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Silane Recycling Technology Deployment | Enables circular material claims for EU Green Deal carbon border compliance. |
| REACH-Compliant Formulation Reformulation | Maintains CE-marked product lines as ECHA phases down legacy peroxide initiators. |
| Humidity-Controlled Extrusion Partnership | Reduces scrap rates for Southeast Asian cable plants lacking climate-controlled environments. |
| Renewable Feedstock Cracking Agreement | Secures carbon-footprint certification for German and Dutch transmission operator tenders. |
| GB Standard Qualification Investment | Unlocks State Grid Corporation procurement in China's coastal manufacturing provinces. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with cable plant managers, utility procurement officers, compound technical directors, and ECHA regulatory affairs specialists. Dow and LyondellBasell SEC disclosures, Cefic chemical industry reports, and Chinese customs export statistics provided demand-side validation. Bottom-up volume modeling across cable insulation, pipe, foam, and sheet product types triangulated against top-down ethylene derivative consumption estimates from major cracking complexes.
Data-stream reconciliation merged silane-grafting capacity utilization rates from Asian petrochemical associations with European cable tender award databases and Indian BIS certification registries. Segmentation dimensions spanned product type, end-use industry, form factor, and application across the analysis window, with CAGRs derived from utility capital expenditure cycles and residential construction permit flows. Forecast inputs incorporated offshore wind array pipeline announcements from North Sea and Baltic developers, along with REACH authorization timelines for restricted crosslinking chemistries.
The model holds under stable naphtha-cracking margin conditions and sustained utility grid modernization procurement; deviation in ethylene feedstock volatility or ECHA accelerated phase-down schedules would shift compound pricing trajectories and regional supply shares. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Styrenics Market
Polymers & Resins
Middle East and Africa Poly Vinyl Chloride (PVC) Market
Polymers & Resins
Polyamide-Imide (PAI) Market
Polymers & Resins
Polysorbate Market
Polymers & Resins
Global Bio Polyamide Market
Polymers & Resins
Bakelite Market
Polymers & Resins
Global Styrenic Polymers Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
EVA Foam Market
Polymers & Resins
Gel Polymer Electrolytes Market
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
Chelating Resins Market
Polymers & Resins
Middle-East and Africa Thermoplastics Market
Polymers & Resins
Polymer Binders Market
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
Global Impregnating Resins Market