
 Asia-Pacific Paints and Coatings Market | 2026-2036
Asia-Pacific Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Paints and Coatings Market Analysis
Multi-sourced resin procurement is decoupling from the single-supplier model that long dominated Asia-Pacific formulation economics. Asian Paints leverages captive manufacturing of decorative emulsions to control input costs across its Indian distribution network. Nippon Paint Holdings anchors its regional position through deep R&D investment in low-VOC architectural systems for humid subtropical climates. Kansai Paint dominates marine and protective segments by sustaining technical service density at major shipyard clusters from South Korea to Vietnam.
Asia-Pacific paints and coatings encompass liquid, powder, and UV-curable film-forming systems composed of binders, pigments, solvents or carriers, and functional additives, applied to substrates for protection, decoration, or specialized performance. Architectural coatings command the largest revenue pool due to relentless urban residential and commercial construction across emerging Asian economies, while powder coatings represent the fastest-expanding formulation category as factory-applied industrial finishes displace solvent-based alternatives under tightening emissions protocols. Water-based systems lead volume in decorative applications where brush and roller methods prevail, though spray application dominates automotive and marine end uses where film thickness and edge coverage standards are most demanding.
China's MEE enforces progressive VOC limits under national environmental standards that reformulate solvent-based production lines toward waterborne and powder alternatives. India's BIS certification mandates for architectural coatings create compliance barriers that favor organized manufacturers with testing laboratory access over informal compounders. Japan's JIS standards and METI chemical management frameworks maintain premium quality tiers for industrial exports. Stakeholders must monitor regulatory divergence between harmonized ASEAN technical requirements and country-specific labeling rules that fragment product registration costs across the region.
Market Dynamics
China's MEE is enforcing progressively tighter VOC limits under GB standards, forcing solvent-based production lines toward waterborne and powder alternatives across the region's manufacturing base.
Growth Catalysts
- GB Standards on VOC Emissions:China's environmental ministry mandates are accelerating reformulation investments toward compliant waterborne systems in architectural and industrial coatings segments.
- Construction Procurement Expansion:Southeast Asian infrastructure and residential development is pulling decorative emulsions and protective coatings through distributor networks from Vietnam to Indonesia.
- UV-Curable Technology Adoption:Factory-applied industrial finishes are displacing conventional solvent-based alternatives as automotive and electronics manufacturers seek faster curing cycles.
Market Restraints
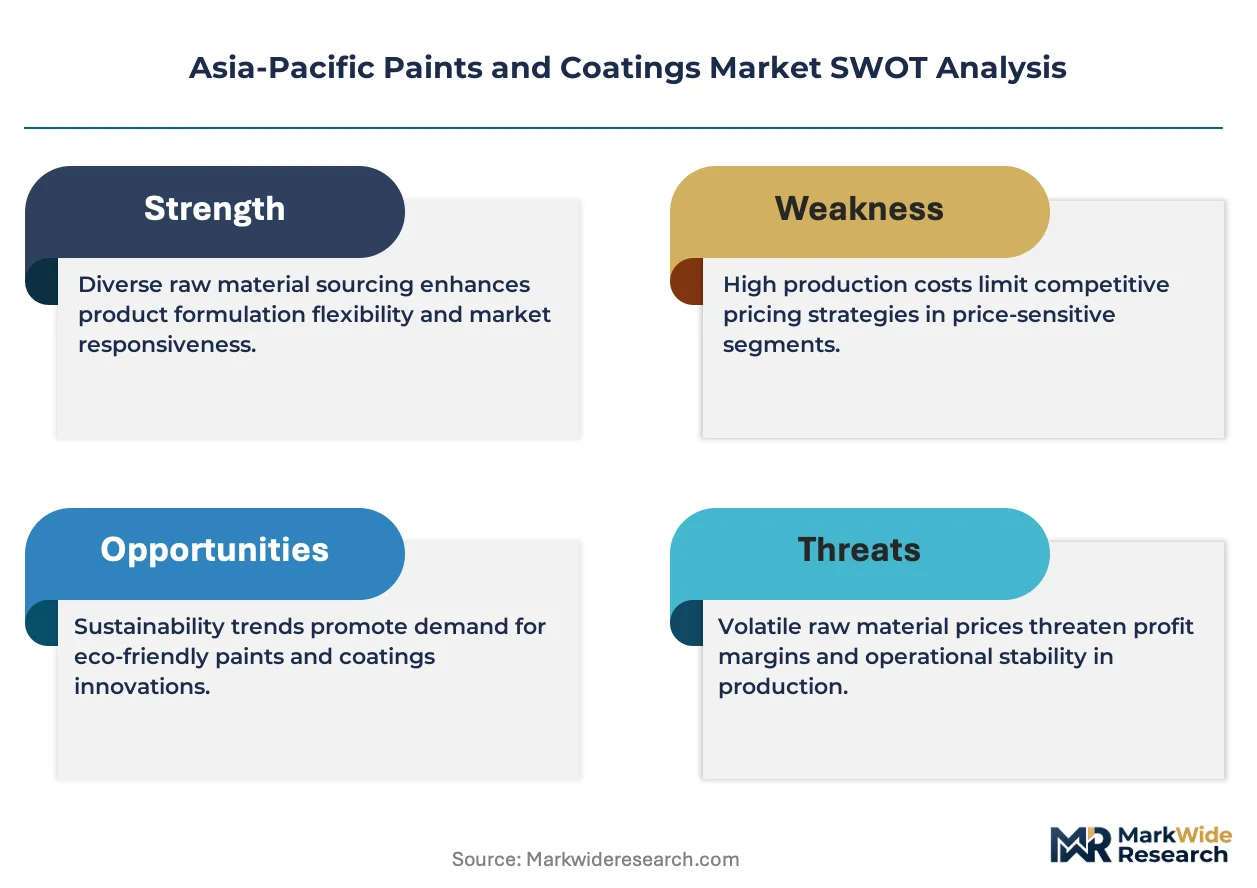
- Petrochemical Feedstock Volatility:Epoxy and acrylic resin prices fluctuate with naphtha and propylene derivatives, compressing formulation margins for regional compounders.
- Titanium Dioxide Supply Concentration:Chinese TiO2 producers control roughly two-thirds of Asia-Pacific chloride-route capacity, creating single-source vulnerability for white pigment procurement.
- Humid Subtropical Performance Limitations:Standard waterborne architectural systems suffer fungal degradation and adhesion failure in monsoon climates, requiring costly additive packages.
Strategic Opportunities
- India's Western Industrial Corridor:Manufacturing clusters from Gujarat to Maharashtra lack localized technical service density for protective coatings, creating white space for applied engineering capabilities.
- BIS Certification Barriers:India's mandatory testing laboratory access requirements favor organized manufacturers with capital to maintain compliance infrastructure over informal compounders.
- Marine Coatings Digitalization:Convergence of IoT-enabled corrosion monitoring with predictive maintenance contracts is reshaping how shipyards in South Korea and Vietnam specify protective systems.
Industry Challenges
- Formulation Chemist Scarcity:Shortage of specialists capable of balancing low-VOC compliance with humid-climate durability in waterborne architectural systems.
- Dual-Certification Timelines:Navigating divergent ASEAN technical harmonization efforts alongside country-specific labeling rules fragments product registration costs and extends time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Paints and Coatings Market |
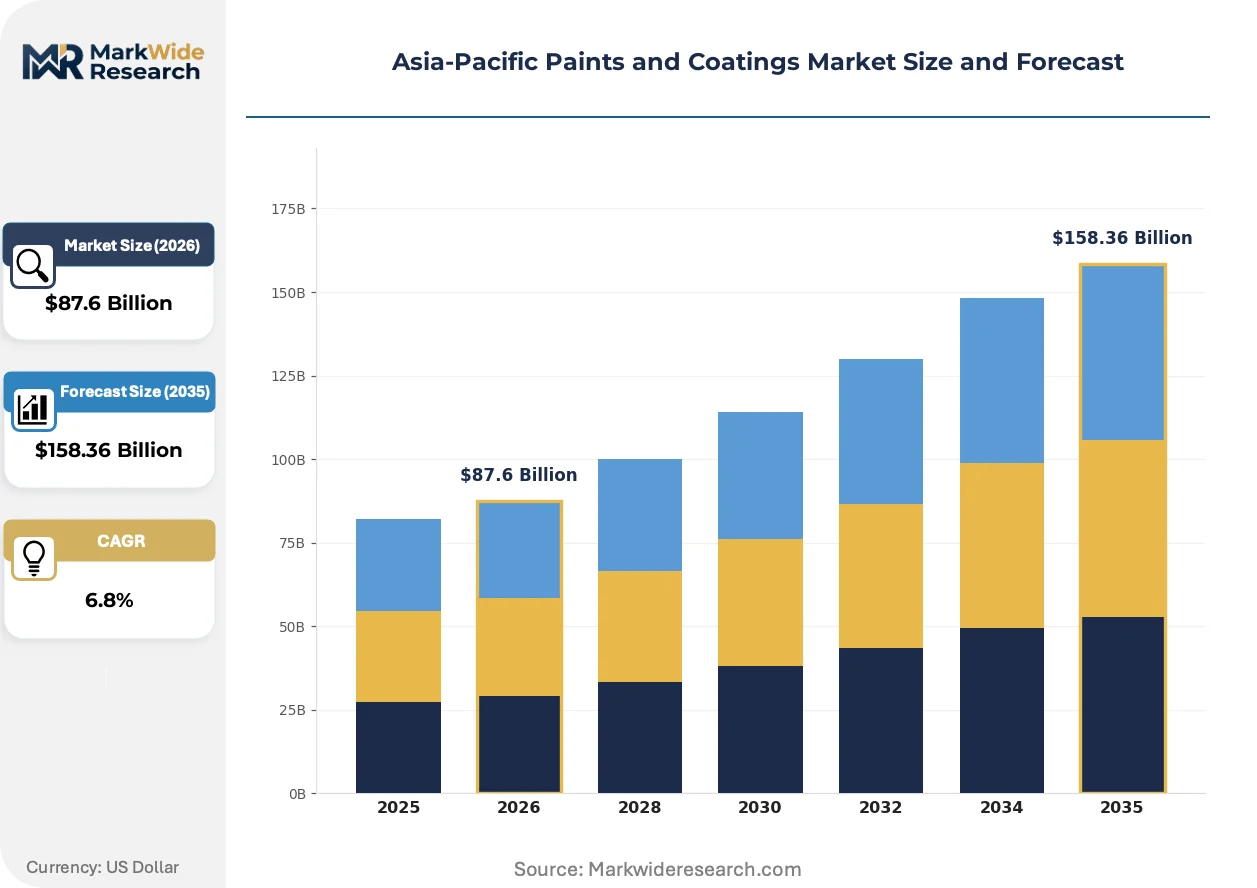
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural Coatings, Protective Coatings, Industrial Coatings, Automotive Coatings End Use Industry: Construction, Automotive, Marine, Aerospace Formulation: Water-Based, Solvent-Based, Powder Coatings, UV-Cured Application Method: Brush, Roller, Spray, Electrostatic |
| Companies Covered | Asian Paints, Nippon Paint Holdings Co., Ltd, Kansai Paint Co., Ltd, PPG Industries, Inc., Akzo Nobel N.V., Hempel A/S, Jotun, Berger Paints India, TOA Paint Public Company Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Paints and Coatings Market Emerging Trajectories
Formulation science is pivoting toward modular additive packages that enable rapid regional customization without full product redevelopment, compressing response times to regulatory and climatic variations.
Self-healing microcapsule technology is modularizing protective coating architectures by embedding repair agents within polymer matrices that activate upon mechanical damage. Marine and infrastructure asset operators in Vietnam and South Korea are piloting these systems for subsea pipelines and bridge decks. The technology is modularizing specification workflows, allowing engineers to decouple base corrosion protection from localized damage tolerance rather than over-specifying film thickness everywhere.
China's GB standards on VOC emissions are tightening incrementally across architectural, automotive, and industrial coating categories, with MEE enforcement expanding from megacities to provincial manufacturing zones. Waterborne alkyd and acrylic systems are capturing specification share in decorative applications previously dominated by solvent-borne alternatives. Indian and Southeast Asian formulators are accelerating technology licensing to preempt similar regulatory trajectories in their home markets.
Specification authority is migrating from general contractor procurement offices to specialized applicator networks with certified installation capabilities. Large-scale infrastructure developers in Indonesia and the Philippines now require applicator warranty backing for protective coating systems, not just manufacturer product guarantees. This shift concentrates demand among technical service-intensive suppliers with field engineering presence at major shipyard and petrochemical clusters.
Asia-Pacific Paints and Coatings Market Segmentation
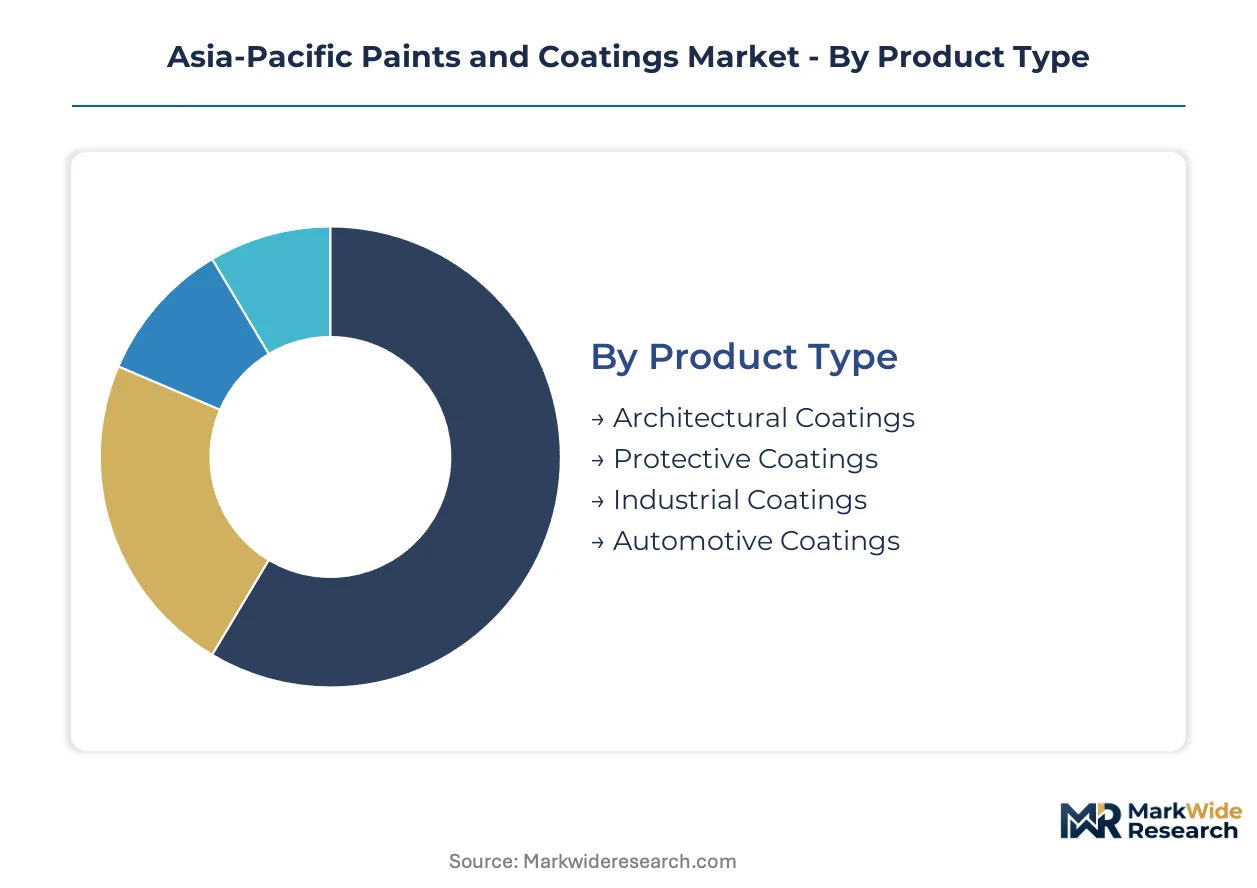
Segmentation in Asia-Pacific paints and coatings reveals how formulation chemistry, application infrastructure, and end-use performance requirements fragment procurement patterns across the region's diverse climatic and regulatory environments.
Product Type:
Customization intensity varies sharply across this category, from standardized decorative emulsions to engineered protective systems requiring site-specific specification.
- Architectural Coatings:Decorative emulsions and exterior finishes formulated with waterborne acrylic and alkyd binders for residential and commercial facades. Demand concentrates in Southeast Asian construction corridors from Vietnam to Indonesia, where humidity-resistant fungal protection drives additive package selection.
- Protective Coatings:High-build epoxy and polyurethane systems engineered for corrosion protection in chemical processing, offshore infrastructure, and power generation assets. Procurement clusters at Indian shipyards from Gujarat to Maharashtra, where MEE-style VOC enforcement is beginning to reshape specification criteria.
- Industrial Coatings:Factory-applied finishes for machinery, appliances, and general metal fabrication requiring rapid throughput and consistent film thickness.
- Automotive Coatings:Basecoat-clearcoat systems and electrodeposition primers for OEM and refinish applications, where spray application dominates and edge coverage standards are most demanding.
Leading the category by volume: Architectural Coatings. Expanding most quickly: Protective Coatings.
End Use Industry:
Cost tier stratification separates specification authority between owner-operated assets and contractor-driven procurement.
- Construction:The dominant revenue pool spanning residential, commercial, and infrastructure verticals. Brush and roller methods prevail in decorative applications across India's western industrial corridor, where BIS certification barriers favor organized manufacturers with laboratory access.
- Automotive:OEM assembly lines and collision repair networks specifying coatings by film thickness, durability, and color matching precision. South Korean and Chinese manufacturing clusters drive technology adoption for faster curing cycles.
- Marine:Ship newbuilding, maintenance, and offshore platform protection requiring specialized anti-corrosive and anti-fouling chemistries. Technical service density at Vietnamese and South Korean shipyards determines supplier selection.
- Aerospace:High-performance coatings for commercial aviation and military applications, where JIS and GB standards on VOC emissions create dual-compliance complexity for regional formulators.
Dominating procurement value: Construction. Steepest specification upgrade trajectory: Marine.
Formulation:
Volume concentration tilts toward waterborne systems, while margin capture favors specialized curing technologies.
- Water-Based:Acrylic, alkyd, and polyurethane dispersions replacing solvent-borne alternatives under tightening MEE enforcement in China and anticipated regulatory convergence across ASEAN markets.
- Solvent-Based:Conventional high-solids and conventional systems retaining share in industrial and automotive segments where drying speed and substrate compatibility outweigh VOC compliance pressures.
- Powder Coatings:Thermoset epoxy, polyester, and hybrid systems applied electrostatically for factory-finished metal goods. Expanding most quickly as manufacturing automation displaces liquid alternatives in appliance and automotive component finishing.
- UV-Cured:Rapid-curing acrylate formulations for electronics, wood, and specialty industrial applications where throughput speed justifies capital investment in curing equipment.
Commanding volume leadership: Water-Based. Gaining share fastest: Powder Coatings.
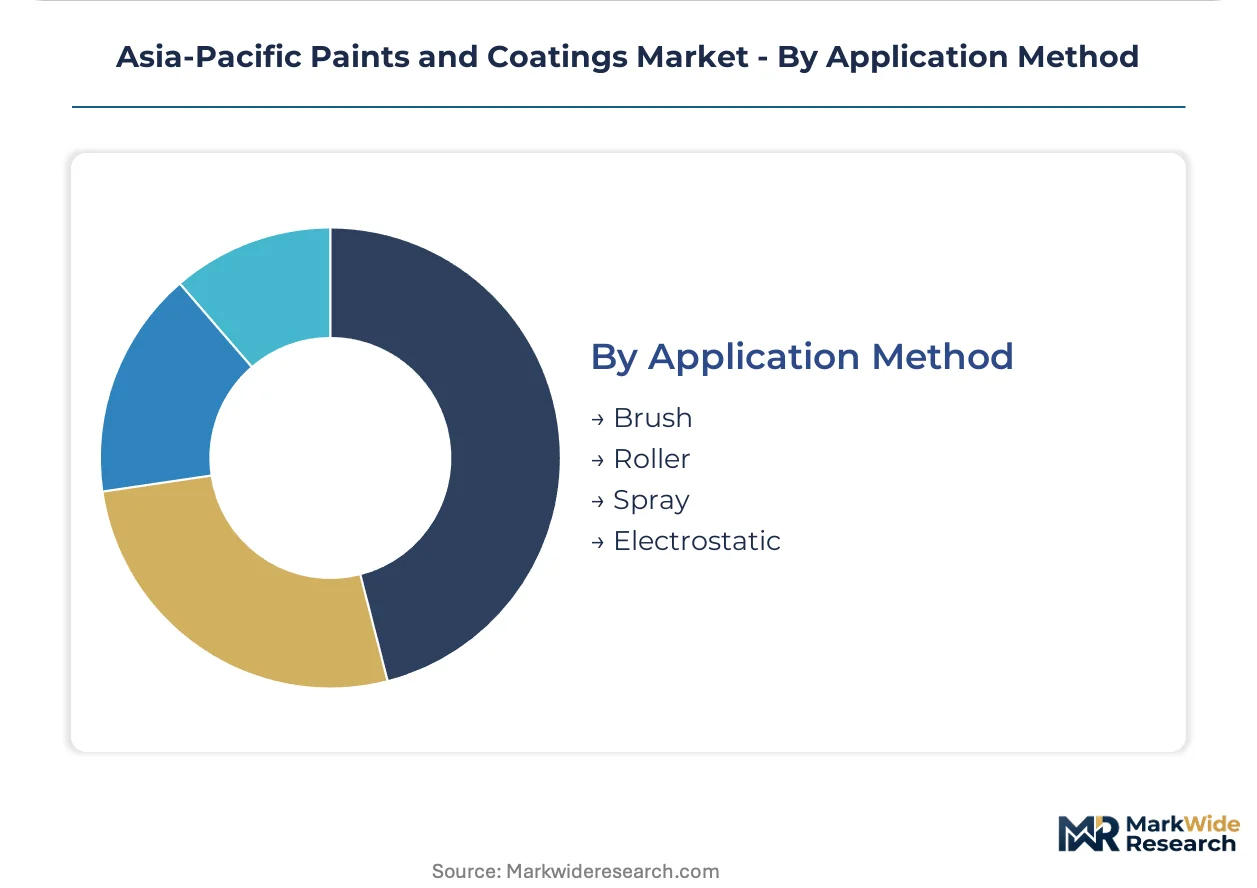
Application Method:
Customer type segmentation separates professional applicator networks from end-user direct procurement.
- Brush:Manual application for small-scale decorative touch-ups and maintenance, prevalent in informal construction segments across India and Southeast Asia.
- Roller:Efficient coverage for interior walls and ceilings in residential and commercial projects, dominating the architectural segment where labor cost minimization drives method selection.
- Spray:Airless and conventional spray systems for automotive, marine, and industrial finishes where film thickness uniformity and edge coverage are critical. Specification authority is migrating to certified applicator networks in Indonesia and the Philippines.
- Electrostatic:Charged particle deposition for powder coatings and specialized liquid systems, enabling high transfer efficiency and reduced overspray in automated manufacturing environments.
Highest volume throughput: Roller. Fastest technology substitution: Spray.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's eastern manufacturing belt, India's western industrial corridor, and Southeast Asian construction corridors, with regulatory divergence between MEE enforcement, BIS certification, and ASEAN harmonization efforts reshaping procurement geography.
China
MEE enforcement of GB standards on VOC emissions is accelerating reformulation investments toward waterborne architectural and industrial systems. Provincial manufacturing zones beyond megacities now face inspection protocols previously limited to Beijing-Tianjin-Hebei and Yangtze River Delta clusters. Shanghai and Jiangsu province host the densest concentration of powder coating production lines serving automotive component export manufacturing.
India
BIS certification mandates for architectural coatings create compliance barriers favoring organized manufacturers with laboratory infrastructure over informal compounders. Construction procurement across Maharashtra and Gujarat is pulling decorative emulsions through distributor networks. The western industrial corridor from Mumbai to Ahmedabad lacks localized technical service density for protective coatings, creating white space for applied engineering capabilities.
Japan
METI chemical management frameworks and JIS standards maintain premium quality tiers for industrial coatings exports to Southeast Asian shipyards. Domestic demand concentrates in automotive refinish and marine maintenance segments. Osaka and Nagoya manufacturing clusters sustain R&D investment in low-VOC systems for humid subtropical climate export markets.
South Korea
Shipyard clusters at Busan and Ulsan drive specification authority for marine protective coatings, with technical service density determining supplier selection. Automotive OEM assembly lines specify coatings by film thickness and curing speed requirements. MFDS-aligned chemical safety protocols influence formulation choices for industrial export applications.
Vietnam
Construction procurement from Ho Chi Minh City to Hanoi is expanding demand for humidity-resistant architectural finishes with fungal protection additive packages. Shipyard maintenance operations at Hai Phong and Ba Ria-Vung Tau create secondary demand for marine coatings. Regulatory anticipation of MEE-style VOC enforcement is accelerating technology licensing from Chinese and Japanese formulators.
Asia-Pacific Paints and Coatings Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers build captive resin production and regional blending facilities to escape feedstock volatility. The vendor base organizes around three tiers: integrated multinationals with captive raw material positions, mid-scale regional formulators with distribution density, and specialized applicator-backed technical service providers. Strategic archetypes include backward-integrated decorative emulsion producers, marine coatings specialists with shipyard field engineering presence, and powder coating fabricators serving automated manufacturing lines. M&A activity and technology licensing partnerships represent the dominant competitive vectors as firms acquire formulation capabilities and climate-specific additive packages.
Among India-based manufacturers, Asian Paints and Berger Paints India occupy positions within the integrated decorative emulsion tier, with captive manufacturing infrastructure supporting distribution network cost control. Japanese specialists Nippon Paint Holdings and Kansai Paint exemplify the R&D-intensive and marine-focused archetypes respectively, with the former representing sustained investment in humid-climate architectural systems and the latter anchoring technical service density at shipyard clusters. Hempel A/S and Jotun sit within the European-heritage marine and protective coatings segment, their positions shaped by specification authority migration toward certified applicator networks in Indonesian and Philippine infrastructure development.
| Leading Market Players |
|---|
| Asian Paints |
| Nippon Paint Holdings Co., Ltd |
| Kansai Paint Co., Ltd |
| PPG Industries, Inc. |
| Akzo Nobel N.V. |
| Hempel A/S |
| Jotun |
| Berger Paints India |
| TOA Paint Public Company Limited |
| Others |
Supply Flow & Price Mechanics
China's MEE enforcement of GB standards on VOC emissions gates both qualified supply and premium-tier pricing access, as compliant waterborne formulation capacity commands contract premiums while non-compliant solvent-based production faces provincial manufacturing zone shutdowns.
Pricing Analysis
Volume concentration in waterborne architectural emulsions runs at thinner margins than specialized protective coating systems, where three-tier pricing structure across premium, standard, and economy levels separates certified applicator-backed specifications from commodity distributor sales. Price differentiation hinges on BIS certification grade and technical service density, with margins tightening in decorative segments due to titanium dioxide feedstock volatility while marine and protective tiers retain pricing power through shipyard field engineering presence. Small-scale contractors in India's informal construction segments exhibit highest price sensitivity, whereas infrastructure developers in Indonesia and the Philippines prioritize warranty-backed applicator certification over unit cost.
Supply Chain Analysis
Freight cost differentials between naphtha-derived resin production in China and acrylic dispersion manufacturing in South Korea shape regional procurement patterns, with formulation economics favoring coastal blending facilities near terminal markets. Raw material supply draws from Chinese TiO2 chloride-route capacity, South Korean petrochemical derivatives, and Japanese specialty additive packages, creating single-source vulnerability in white pigment procurement. Distribution runs through authorized distributor networks in India and certified applicator channels in Southeast Asian infrastructure markets, with tariff exposure on epoxy resin imports compressing margins for non-integrated compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's MEE progressive VOC enforcement creates a cost-of-compliance barrier-to-entry moat that favors organized manufacturers with captive laboratory and reformulation infrastructure over informal compounders lacking GB standards certification access.
For Market Incumbents: Extend technical service density at Vietnamese and South Korean shipyard clusters to defend specification authority against emerging powder coating specialists, while accelerating backward integration into waterborne resin production to escape naphtha derivative volatility. For New Entrants and Emerging Players: Capture white space in India's western industrial corridor from Gujarat to Maharashtra, where protective coatings procurement lacks localized applied engineering capabilities; enter through BIS certification investment paired with distributor partnership rather than direct applicator competition. For Investors and Strategic Acquirers: Provincial MEE enforcement expansion beyond China's megacity clusters is the leading indicator that waterborne formulation capacity will command scarcity premiums; target mid-scale regional formulators with laboratory infrastructure and climate-specific additive licensing positions, watching for GB standards adoption signals across ASEAN markets as the inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Resin Manufacturing | Backward integration into waterborne acrylic production insulates Asian Paints from propylene derivative volatility across Indian distribution networks. |
| GB Standards Pre-Certification | Early MEE compliance investment by Nippon Paint Holdings secures specification lock-in before provincial enforcement reaches tier-two Chinese cities. |
| Shipyard Field Engineering Expansion | Kansai Paint's technical service density at Busan and Ulsan clusters creates switching costs for marine protective coating procurement. |
| BIS Laboratory Infrastructure | Certification barrier investment by Berger Paints India excludes informal compounders from Maharashtra government construction tenders. |
| UV-Curable Technology Licensing | Japanese formulator partnerships with Vietnamese electronics manufacturers accelerate factory-applied finish displacement of solvent-based alternatives. |
Methodological Framework
Independent corroboration across formulation chemists at regional manufacturing plants, procurement leads at Indian and Southeast Asian construction developers, and distribution channel partners in waterborne emulsion networks underwrites the qualitative findings. Secondary validation draws from MEE enforcement bulletins, BIS certification registries, customs trade data on TiO2 and epoxy resin flows, and SEC filings of listed coatings manufacturers. Bottom-up demand modeling across application methods and end-use industries triangulates against top-down market sizing from petrochemical feedstock consumption patterns.
Rate-of-change decomposition across the analysis window separates volume growth in waterborne architectural coatings from value capture in powder and UV-curable industrial segments. Segmentation dimensions include formulation chemistry, end-use industry, application infrastructure, and regional regulatory cluster. CAGRs derive from elasticity modeling against construction procurement indices and automotive production forecasts, with marine coatings demand anchored to shipyard orderbook projections and offshore platform maintenance cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MEE enforcement intensity beyond China's eastern manufacturing belt and ASEAN regulatory convergence timing. Forecasts reflect documented assumptions on feedstock price stability and certification barrier persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Automotive Coatings Market
Paints & Coatings
Middle-East Paints and Coatings Additives Market
Paints & Coatings
Water-Soluble Paints Market
Paints & Coatings
Low VOC Paints and Coatings Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
South America Architectural Coatings Market
Paints & Coatings
Global Anti-Formaldehyde Paint Market
Paints & Coatings
Middle East and Africa Floor Coatings Market
Paints & Coatings
Global Exterior Architectural Coatings Market
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
Nordic Countries Architectural Coatings Market
Paints & Coatings
Italy Industrial Wood Coatings Market
Paints & Coatings
Paint Rollers Market
Paints & Coatings
Hybrid Paint Cans Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
Nigeria Paint and Protective Coatings Market