
 Polyethersulfone (PES) Market | 2026-2036
Polyethersulfone (PES) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethersulfone (PES) Market Analytics
Specialized polymer engineering talent is unwinding capacity constraints across high-performance resin supply chains. Solvay SA leverages its integrated sulfone chemistry platform to sustain captive monomer supply for medical and aerospace grades. BASF SE anchors European PES compounding through controlled distribution of amorphous formulations to membrane fabricators. SABIC competes in automotive thermal management segments with rigid-grade specialization for electric vehicle battery housings.
Polyethersulfone is an amber-transparent amorphous thermoplastic with a glass transition temperature near 225 degrees Celsius, manufactured through nucleophilic aromatic substitution of bisphenol A with 4,4'-dichlorodiphenyl sulfone to yield repeat units containing aromatic ether and sulfone linkages that deliver hydrolytic stability and flame resistance for continuous-use applications above 180 degrees Celsius. Membrane products lead value capture due to asymmetric hollow-fiber configurations dominating hemodialysis and water purification, while film and sheet segments serve aircraft interior panels and electrical insulation where Federal Aviation Administration flammability standards apply. Powder grades occupy niche additive manufacturing and coating formulations where particle size distribution controls sintering behavior.
FDA enforces biocompatibility testing under ISO 10993 for PES devices contacting bodily fluids, while EPA regulates membrane manufacturing effluents under Clean Water Act pretreatment standards. REACH restricts residual solvent content in imported sulfone resins, compelling European compounders to certify supply chain purity. Stakeholders must monitor evolving EU MDR requirements for permanent implant contact materials and decide whether to qualify alternative bisphenol-free sulfone architectures before regulatory thresholds tighten.
Market Dynamics
Membrane-grade PES supply chains face acute pressure from REACH-mandated purity thresholds and FDA biocompatibility testing expansion, forcing compounders to recertify legacy formulations or abandon medical-hemodialysis segments entirely.
Growth Catalysts
- EU MDR implant-contact mandates:Permanent implant-grade sulfone demand is tightening certification requirements, advantaging German polymer clusters with validated cleanroom compounding infrastructure.
- Electric vehicle thermal management:Battery housing specifications above 180°C continuous-use temperature are displacing polyamide in under-hood applications across automotive OEM supply chains.
- Asymmetric hollow-fiber membrane technology:Municipal water treatment operators are retrofitting conventional filtration trains with PES-based ultrafiltration modules for dissolved organic removal.
Market Restraints
- Bisphenol A feedstock volatility:Nucleophilic aromatic substitution chemistry depends on bisphenol A pricing tied to phenol-acetone spreads, creating margin compression for non-integrated compounders.
- European monomer supply concentration:Captive dichlorodiphenyl sulfone production sits with integrated sulfone chemistry platforms, limiting second-source qualification options for medical-grade buyers.
- Polyphenylsulfone substitution in autoclave cycles:Steam-sterilization resistance above 200 cycles favors PPSU in reusable surgical instrument handles, capping PES penetration in high-cycle medical devices.
Strategic Opportunities
- India pharmaceutical filtration infrastructure:CDSCO-aligned active pharmaceutical ingredient manufacturing expansion is creating membrane demand for sterile filtration and virus removal applications.
- Additive manufacturing powder grades:Selective laser sintering of PES powders with controlled particle size distribution is opening aerospace bracket and ducting prototypes previously machined from aluminum.
- F-Gas Regulation thermal insulation:European HVAC manufacturers are evaluating PES foam cores as hydrofluorocarbon-free alternatives to polyurethane in commercial refrigeration panels.
Industry Challenges
- ISO 10993-18 chemical characterization:Extractables and leachables testing timelines for new medical-grade formulations now extend 18-24 months, delaying product launches.
- Clean Water Act pretreatment compliance:Membrane manufacturing effluent streams containing N-methyl-2-pyrrolidone solvent require on-site recovery systems with seven-figure capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethersulfone (PES) Market |
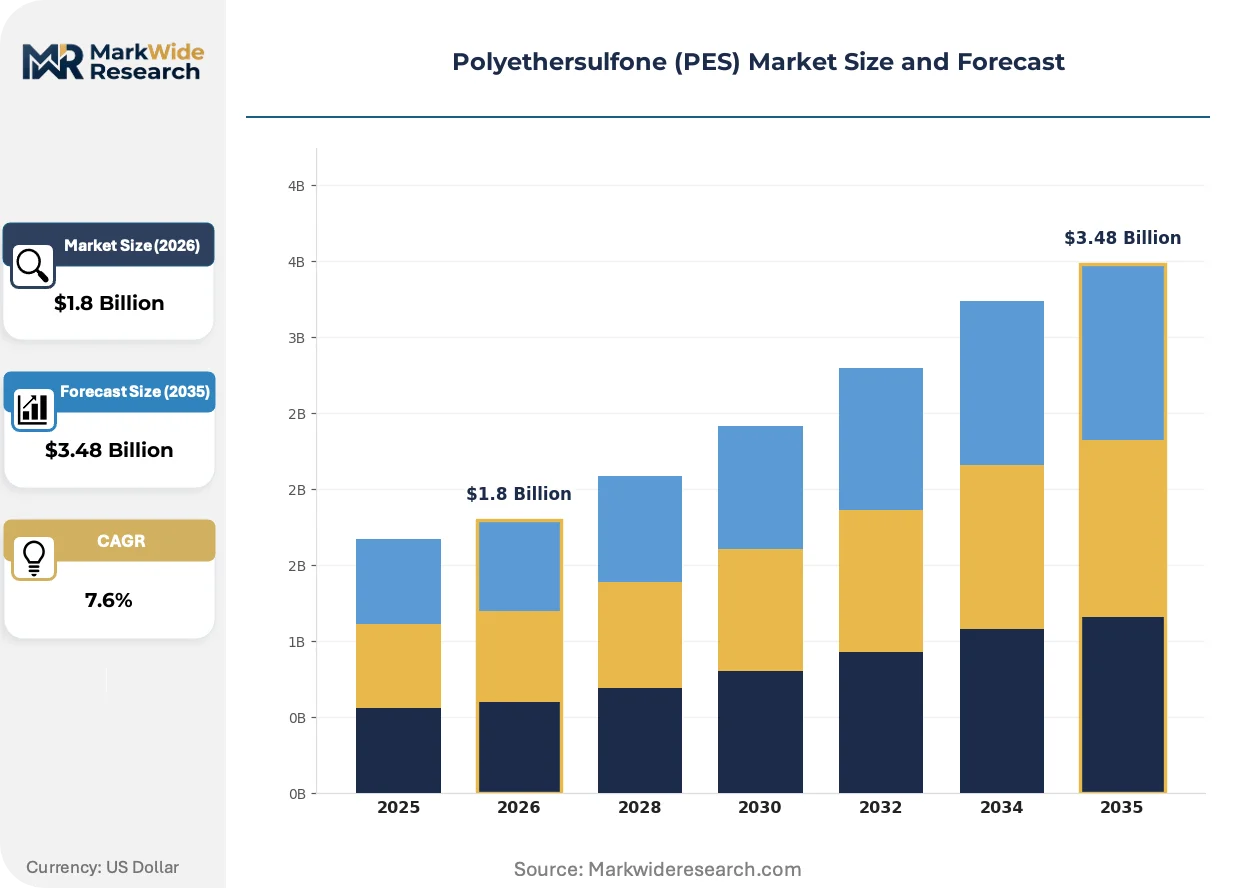
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane, Film, Sheet, Powder Application: Aerospace, Automotive, Electronics, Water Treatment Form: Granular, Amorphous, Rigid, Flexible End User: Manufacturing, Healthcare, Energy, Research |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Solvay SA, RTP Company, SABIC, BASF SE, Sartorius AG, Evonik Industries AG, Sumitomo Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethersulfone (PES) Market Evolving Landscape
Material science and regulatory chemistry are diverging PES specification pathways, creating parallel tracks for commodity water-treatment grades versus certified medical-aerospace formulations with non-overlapping supply bases.
Bisphenol-free sulfone architectures are bifurcating the medical-grade segment. Isoindoline-based and fluorene-derived alternatives deliver comparable glass transition temperatures while satisfying emerging EU restrictions on bisphenol A in permanent implant contact. Swissmedic and TGA are piloting accelerated review pathways for these next-generation sulfones. The structural consequence is a split supply base where legacy PES serves water treatment and hemodialysis, while bisphenol-free variants capture new implantable device approvals.
REACH Annex XVII restrictions on residual solvent content are tightening import documentation for sulfone resins. ECHA enforcement actions against non-EU compounders lacking certified supply chain purity have redirected membrane-grade volume toward German and Belgian production facilities. Medical device OEMs are responding by qualifying single-source European suppliers rather than dual-sourcing with Asian compounders.
Certificate-of-analysis-driven procurement is displacing spot purchasing in pharmaceutical filtration. End-users now require lot-specific biocompatibility data and extractables profiles before accepting membrane shipments, compressing supplier qualification cycles and favoring compounders with integrated analytical laboratories. This pattern is most pronounced in US hemodialysis concentrate manufacturing and European vaccine filtration operations.
Polyethersulfone (PES) Market Segmentation
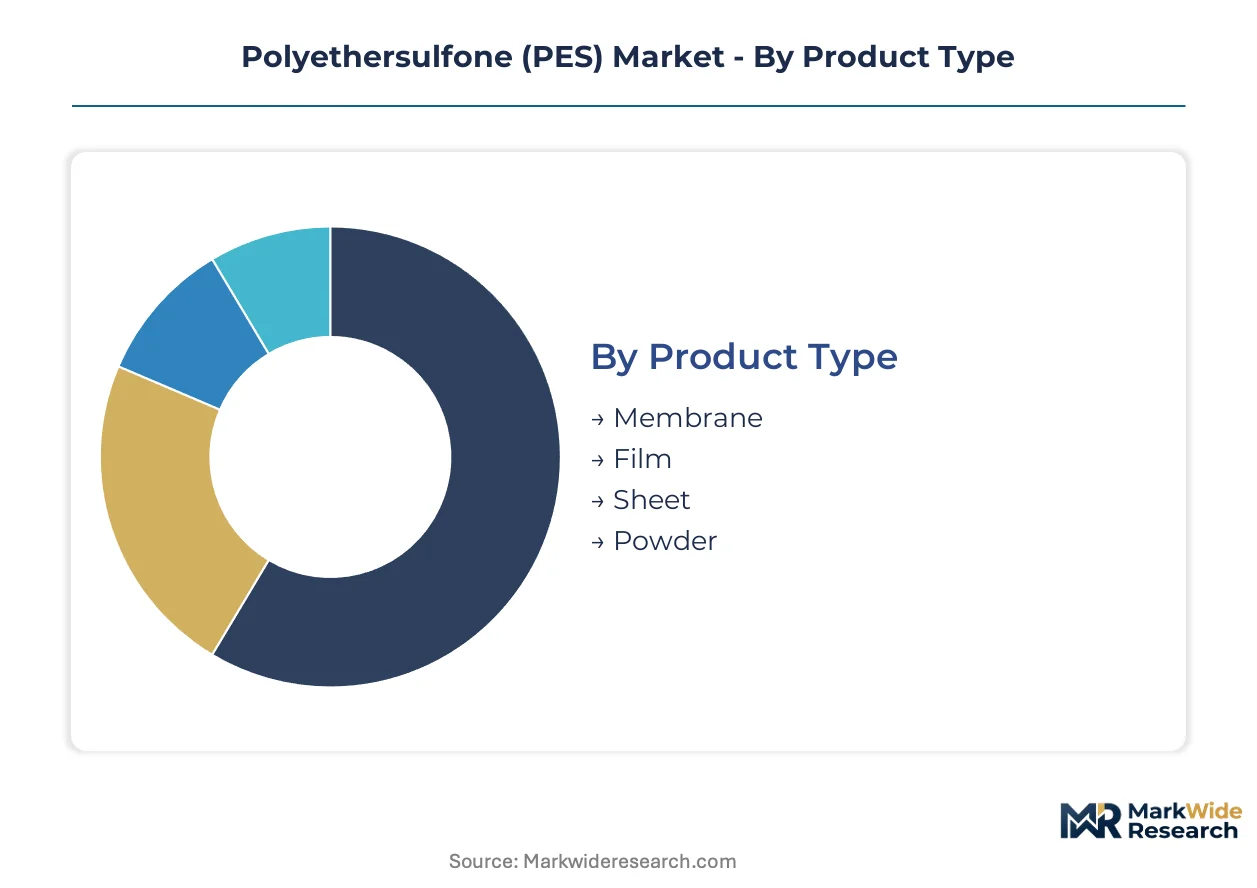
PES market segmentation reveals divergent substitution pressures across product architectures. Membrane and powder grades face distinct competitive threats from polyphenylsulfone and polyimide alternatives, while film and sheet configurations defend position through regulatory certification moats.
Product Type:
Substitution pressure concentrates in steam-sterilizable formats where polyphenylsulfone outperforms PES on hydrolytic stability above 200 autoclave cycles.
- Membrane:Asymmetric hollow-fiber configurations dominate hemodialysis and municipal ultrafiltration, with demand concentrating in German compounding clusters serving FDA-certified medical device OEMs. REACH-mandated purity thresholds and ISO 10993-18 extractables testing are forcing compounders to abandon non-certified legacy formulations.
- Film:Aircraft interior panels and electrical insulation applications leverage Federal Aviation Administration flammability compliance to resist substitution from lower-cost thermoplastics. Demand clusters in aerospace supply chains serving Boeing and Airbus tier-1 fabricators.
- Sheet:Thermoformed aircraft interior components and battery housing substrates occupy mid-tier pricing, with volume concentrated in automotive thermal management retrofits.
- Powder:Selective laser sintering feedstock with controlled particle size distribution serves aerospace bracket prototyping, with CDSCO-aligned Indian pharmaceutical filtration infrastructure emerging as a demand node.
Membrane retains volume leadership; powder holds the steepest expansion curve.
Application:
Cost tier stratification separates aerospace-certified formulations from commodity water-treatment grades, with medical-aerospace specifications commanding 3-4x raw material premiums.
- Aerospace:Federal Aviation Administration flammability standards and smoke toxicity requirements lock in PES for interior panels and ducting, with qualification cycles spanning 24-36 months.
- Automotive:Battery housing specifications above 180°C continuous-use temperature are displacing polyamide in electric vehicle under-hood applications across OEM supply chains anchored in Germany and Michigan.
- Electronics:High-temperature electrical insulation and connector housings serve 5G infrastructure and industrial automation, with demand fragmented across Asian contract manufacturers.
- Water Treatment:Municipal ultrafiltration retrofits and industrial dissolved organic removal drive volume, though margin compression from Asian membrane fabricators limits compounder profitability.
Water treatment commands absolute volume; automotive battery applications climb the fastest.
Form:
Customer type bifurcation separates medical device OEMs demanding amorphous optical clarity from automotive processors prioritizing rigid-grade dimensional stability.
- Granular:Extrusion and injection molding feedstock for industrial components, with volume concentrated in European automotive thermal management supply chains.
- Amorphous:Optical clarity and melt-processability serve medical device housings and analytical instrumentation, with Swissmedic and TGA piloting accelerated review pathways for bisphenol-free variants.
- Rigid:High-modulus formulations for electric vehicle battery housings and structural brackets, with SABIC specialization competing against Solvay integrated sulfone chemistry.
- Flexible:Lower glass-transition formulations for film and sheet thermoforming, occupying price-sensitive packaging and disposable medical device segments vulnerable to polyphenylsulfone substitution.
Amorphous retains medical-grade premium positioning; rigid formats gain share fastest in automotive electrification.
End User:
Supply concentration in German polymer compounding clusters shapes procurement patterns for healthcare and manufacturing segments demanding REACH-certified purity documentation.
- Manufacturing:Industrial filtration, chemical processing equipment, and semiconductor fabrication components drive steady demand, with certificate-of-analysis requirements displacing spot purchasing.
- Healthcare:Hemodialysis membranes, surgical instrument handles, and implantable device housings face EU MDR permanent implant-contact mandates tightening certification requirements.
- Energy:Battery thermal management and fuel cell humidifier membranes serve hydrogen economy infrastructure, with F-Gas Regulation thermal insulation applications evaluating PES foam cores.
- Research:Laboratory filtration, chromatography media, and analytical instrumentation housings occupy low-volume, high-specification niches with elongated qualification timelines.
Manufacturing commands volume leadership; energy applications track the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA biocompatibility testing and REACH purity mandates anchor regulatory intensity across the dominant geographies. Solvay SA's integrated sulfone chemistry platform in Belgium and German compounding clusters concentrate medical-grade supply. Municipal water treatment retrofits and electric vehicle battery housing specifications drive demand dispersion.
Germany
Specialized polymer compounding clusters in North Rhine-Westphalia and Baden-Württemberg serve pharmaceutical filtration and automotive under-the-hood applications. EU MDR permanent implant-contact mandates tighten certification requirements, advantaging facilities with validated cleanroom infrastructure. Stuttgart and Leverkusen anchor hemodialysis membrane supply chains for FDA-certified medical device OEMs.
United States
Electric vehicle thermal management specifications above 180°C continuous-use temperature displace polyamide in Michigan and California automotive supply chains. EPA Clean Water Act pretreatment standards regulate membrane manufacturing effluents containing N-methyl-2-pyrrolidone solvent. Boston and San Diego concentrate aerospace interior panel fabricators serving Boeing and Airbus tier-1 suppliers.
Belgium
Solvay SA's captive dichlorodiphenyl sulfone production sustains medical and aerospace grade resin supply from Brussels-capital operations. REACH Annex XVII residual solvent restrictions redirect membrane-grade volume toward Belgian and German facilities. Antwerp polymer engineering talent unwinds capacity constraints across high-performance resin supply chains.
India
CDSCO-aligned active pharmaceutical ingredient manufacturing expansion creates membrane demand for sterile filtration and virus removal in Maharashtra and Gujarat. Certificate-of-analysis-driven procurement displaces spot purchasing among pharmaceutical filtration end-users. Hyderabad and Ahmedabad clusters serve vaccine filtration operations requiring lot-specific biocompatibility data.
Japan
Sumitomo Chemical Company anchors regional sulfone chemistry production for electronics and water treatment segments. METI industrial standards govern high-temperature electrical insulation applications in 5G infrastructure. Osaka and Nagoya concentrate contract manufacturers serving industrial automation connector housing demand.
Polyethersulfone (PES) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the PES value chain. Integrated sulfone chemistry platforms command medical-aerospace premiums through captive monomer supply, while compounders compete on formulation breadth for industrial segments. Three archetypes dominate: European integrated chemical conglomerates, specialized polymer compounders, and Asian membrane fabricators. Strategic moves concentrate on backward integration into monomer production and qualification of bisphenol-free sulfone architectures for EU MDR compliance.
Among integrated chemical conglomerates, Solvay SA and BASF SE exemplify the technology leadership archetype through European-based sulfone chemistry platforms. SABIC occupies a position on the cost-competitive vector for automotive thermal management applications. These three anchors represent divergent specialization patterns: medical-aerospace certification, membrane formulation breadth, and rigid-grade automotive electrification materials.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Solvay SA |
| RTP Company |
| SABIC |
| BASF SE |
| Sartorius AG |
| Evonik Industries AG |
| Sumitomo Chemical Company |
| Others |
Value Network & Pricing Analysis
Eighteen-month ISO 10993-18 extractables testing timelines concentrate pricing power with German and Belgian compounders possessing validated cleanroom infrastructure, while membrane-grade buyers face single-source premiums for REACH-certified purity documentation. Medical-aerospace specifications command raw material premiums against commodity water-treatment grades where Asian fabricators compress compounder margins.
Pricing Analysis
Belgian-German price spreads of three-to-four times separate medical-aerospace formulations from commodity water-treatment grades. Three-tier pricing structure across medical-certified, industrial-standard, and economy water-treatment levels anchors the dominant model. Price differentiation hinges on REACH purity certification and FDA biocompatibility tier, with bisphenol-free sulfone architectures capturing additional premiums. Cost compression in municipal ultrafiltration grades intensifies because Asian membrane fabricators expand asymmetric hollow-fiber capacity. Pharmaceutical filtration OEMs exhibit least price sensitivity due to certificate-of-analysis requirements, while municipal water operators drive hardest bargaining.
Supply Chain Analysis
Germany and Belgium anchor medical-grade PES compounding, while China and Japan concentrate electronics and water-treatment membrane fabrication. Dichlorodiphenyl sulfone monomer supply rests on captive production within integrated sulfone chemistry platforms, with bisphenol A feedstock drawing from phenol-acetone spreads. Single-source vulnerability concentrates in European monomer supply, limiting second-source qualification for medical-grade buyers. Distribution runs through qualified polymer compounders serving FDA-certified device OEMs and direct sales to automotive tier-1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certificate-of-analysis-driven procurement and lot-specific biocompatibility data represent expanding service-attach layers growing faster than base resin volumes, as pharmaceutical filtration end-users displace spot purchasing with integrated analytical laboratory relationships.
For Market Incumbents: Compound backward integration into dichlorodiphenyl sulfone monomer production to defend against bisphenol A feedstock volatility and secure captive supply for medical-aerospace grades. Expand cleanroom compounding capacity in North Rhine-Westphalia to capture EU MDR permanent implant-contact certification demand before regulatory thresholds tighten against legacy bisphenol-based architectures. For New Entrants and Emerging Players: Lead with bisphenol-free sulfone qualification for CDSCO-aligned Indian pharmaceutical filtration infrastructure, where vaccine filtration operations require lot-specific extractables profiles and European supply concentration creates procurement gaps. Target selective laser sintering powder grades for aerospace bracket prototyping as the most penetrable segment, leveraging particle size distribution control as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because REACH Annex XVII enforcement and FDA biocompatibility testing expansion are structurally raising barriers to medical-grade supply qualification. Acquisition targets should display integrated sulfone chemistry platforms or validated cleanroom infrastructure with existing ISO 10993 certification. The signal to watch is ECHA enforcement actions redirecting membrane-grade volume toward European facilities, indicating regulatory-driven supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Captive dichlorodiphenyl sulfone supply secures medical-aerospace grade margins against feedstock volatility. |
| Bisphenol-Free Sulfone Architecture Qualification | Swissmedic and TGA accelerated review pathways capture EU MDR-compliant implant-grade demand ahead of regulatory bans. |
| Cleanroom Compounding Capacity Expansion | Validated North Rhine-Westphalia infrastructure serves FDA-certified hemodialysis membrane OEMs with REACH purity documentation. |
| Certificate-of-Analysis Service Layer Development | Integrated analytical laboratories compress supplier qualification cycles for pharmaceutical filtration end-users. |
| Selective Laser Sintering Powder Grade Launch | Controlled particle size distribution opens aerospace bracket prototyping previously machined from aluminum. |
Research Methodology
The analysis maps membrane-grade, film and sheet, powder-grade, and medical-aerospace formulation sub-sectors, each validated through technical R&D directors at polymer compounders, procurement leads at membrane fabricators, regulatory affairs specialists at medical device OEMs, and aftermarket service heads at automotive tier-1 suppliers. Primary interview findings triangulated against customs and trade data, SEC 10-K filings, ECHA REACH registration databases, and Cefic industry reports. Bottom-up volume estimates from individual production facilities reconciled with top-down demand modeling across end-use applications.
Consistency checks validated volume and value outputs against external benchmarks from chemical industry associations and regulatory filing disclosures across the projection horizon. Segmentation dimensions modeled include product architecture, application sector, formulation grade, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for REACH enforcement intensity and electric vehicle battery housing specification adoption. Industry-specific forecast inputs incorporated phenol-acetone spread volatility and EU MDR implementation timelines.
Forecasts assume regulatory continuity in REACH Annex XVII, FDA biocompatibility testing expansion, and EU MDR permanent implant-contact mandates; material policy shifts in bisphenol A restrictions or solvent content thresholds would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Orthophthalic Resins Market
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
Global Polybutene Market
Polymers & Resins
Ethylene Acrylic Acid (EAA) Copolymers Market
Polymers & Resins
Ethylene-Vinyl Alcohol Copolymer (EVOH) Market
Polymers & Resins
Thermoplastic Polyamide Elastomer (TPE) Market
Polymers & Resins
Cathodic Acrylic Market
Polymers & Resins
Global Styrene Acrylic Emulsion Polymer Market
Polymers & Resins
Polyether Block Amide Market
Polymers & Resins
Fluorine Polymer Films Market
Polymers & Resins
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market
Polymers & Resins
Nylon-6 Market
Polymers & Resins
Polymer Plastic Plain Bearings Market
Polymers & Resins
Thermoplastic Polyester Engineering Resin (TPER) Market
Polymers & Resins
Global Thermoset Resin Market
Polymers & Resins
Low Density Polyethylene Market