
 Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market | 2026-2036
Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market Foresight
Buyer concentration in the Middle East and Africa Hydroxyl-Terminated Polybutadiene market is shifting as state-owned defense contractors consolidate procurement authority while specialty coatings formulators fragment across North African industrial zones. Idemitsu Kosan Co., Ltd. anchors its regional position through captive supply relationships with Japanese automotive OEMs operating in South Africa. Evonik Industries AG differentiates via high-purity liquid HTPB grades tailored to aerospace specifications. Huntsman Corporation competes through backward integration into polybutadiene feedstock streams serving the Gulf's adhesives sector.
Hydroxyl-Terminated Polybutadiene is a liquid telechelic polymer with terminal hydroxyl functionality, typically manufactured through free-radical polymerization of 1,3-butadiene followed by selective hydroxylation, and serves primarily as a binder and fuel component in solid rocket propellants plus a toughening agent in polyurethane formulations. Liquid HTPB dominates volume flows due to its processability in cast-cure propellant systems, while modified HTPB variants capture expanding margin pools as defense contractors demand customized hydroxyl values and viscosity profiles. The aerospace application segment leads value generation, though coatings demand accelerates fastest across Morocco and Egypt as infrastructure spending rises.
South Africa's National Regulator for Compulsory Specifications enforces polymer purity benchmarks affecting import eligibility, while Saudi Arabia's Saudi Standards, Metrology and Quality Organization aligns chemical certification with defense procurement protocols. REACH-equivalent frameworks under development across Gulf Cooperation Council member states will tighten hydroxyl content disclosure requirements for cross-border trade. Stakeholders must monitor divergence between South Africa's evolving industrial chemical standards and Gulf defense-driven specification regimes when allocating technical service resources.
Market Dynamics
Defense procurement consolidation across Gulf Cooperation Council states is concentrating HTPB demand authority into fewer state-owned contractors, while South Africa's National Cleaner Production Centre protocols force formulation redesigns that fragment specialty coatings procurement.
Growth Catalysts
- Saudi Standards, Metrology and Quality Organization alignment:Defense certification protocols now integrate chemical specification benchmarks, streamlining propellant-grade HTPB procurement for aerospace contractors in the Kingdom's manufacturing corridor.
- Cast-cure propellant system adoption:Liquid HTPB processability advantages are pulling solid rocket motor production toward standardized binder platforms across UAE and Saudi defense facilities.
- Infrastructure coatings demand:Morocco and Egypt construction spending is accelerating polyurethane toughening agent consumption for protective industrial applications.
Market Restraints
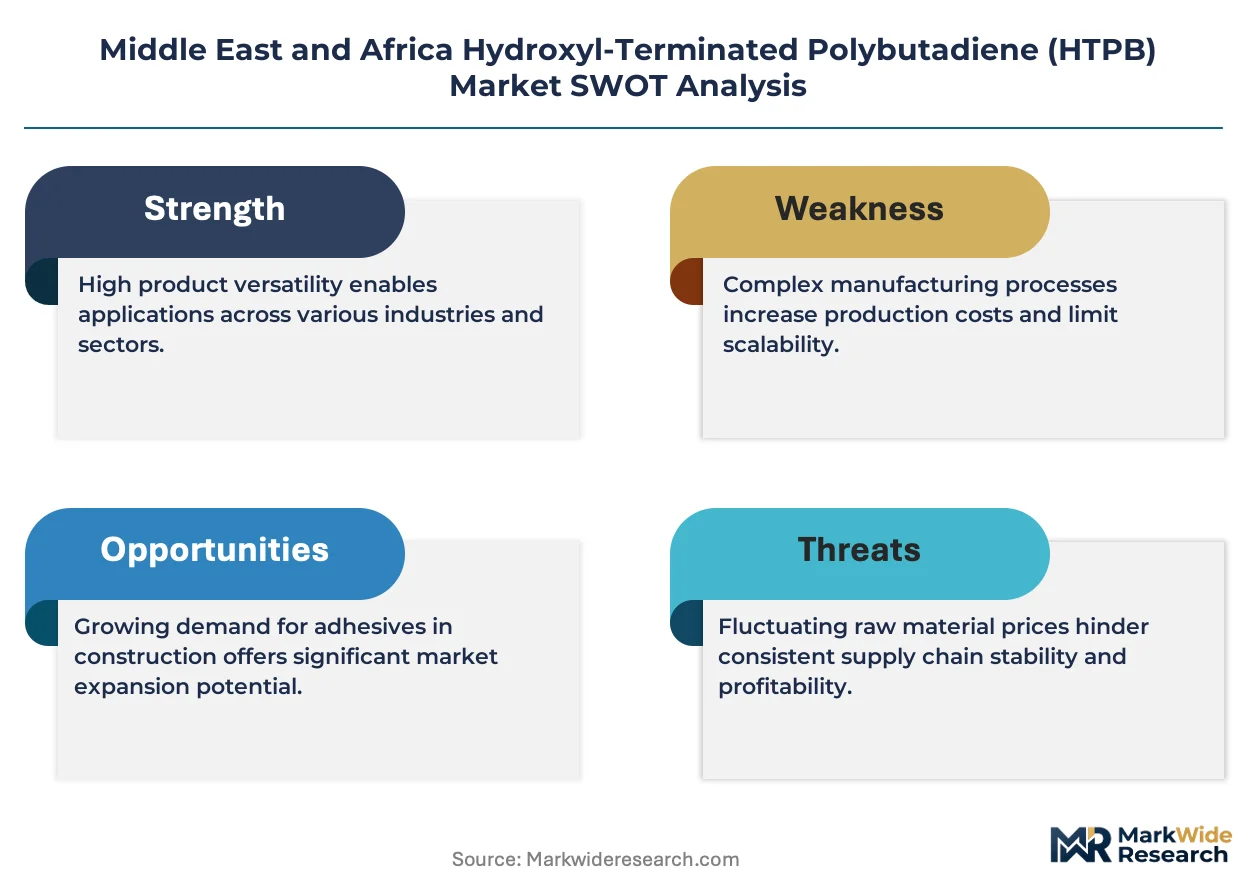
- Butadiene feedstock volatility:Polybutadiene raw material price swings compress margin predictability for regional formulators dependent on imported monomer streams.
- South African purity enforcement:The National Regulator for Compulsory Specifications maintains strict polymer import eligibility thresholds that exclude lower-grade Asian supply.
- Epoxy toughening substitution:Aerospace contractors in select Gulf programs are evaluating hybrid binder systems that reduce HTPB volume per motor.
Strategic Opportunities
- Egyptian industrial zone expansion:Suez Canal Economic Zone chemical processing incentives are attracting HTPB downstream formulation investments for North African coatings distribution.
- REACH-equivalent GCC frameworks:Emerging hydroxyl content disclosure mandates will privilege pre-registered suppliers with technical documentation capabilities.
- Polyurethane-HTPB hybrid R&D:Convergence of elastomer toughening science with propellant binder chemistry is opening modified-grade specification white space.
Industry Challenges
- Propellant chemist scarcity:Gulf defense contractors face recruitment gaps for solid rocket motor formulation specialists familiar with cast-cure HTPB processing.
- Dual certification timelines:Suppliers must simultaneously satisfy South African industrial chemical standards and Saudi defense procurement protocols, extending qualification cycles.
- Legacy adhesive system integration:North African industrial coatings formulators encounter compatibility friction when substituting HTPB tougheners into established epoxy-polyurethane production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market |
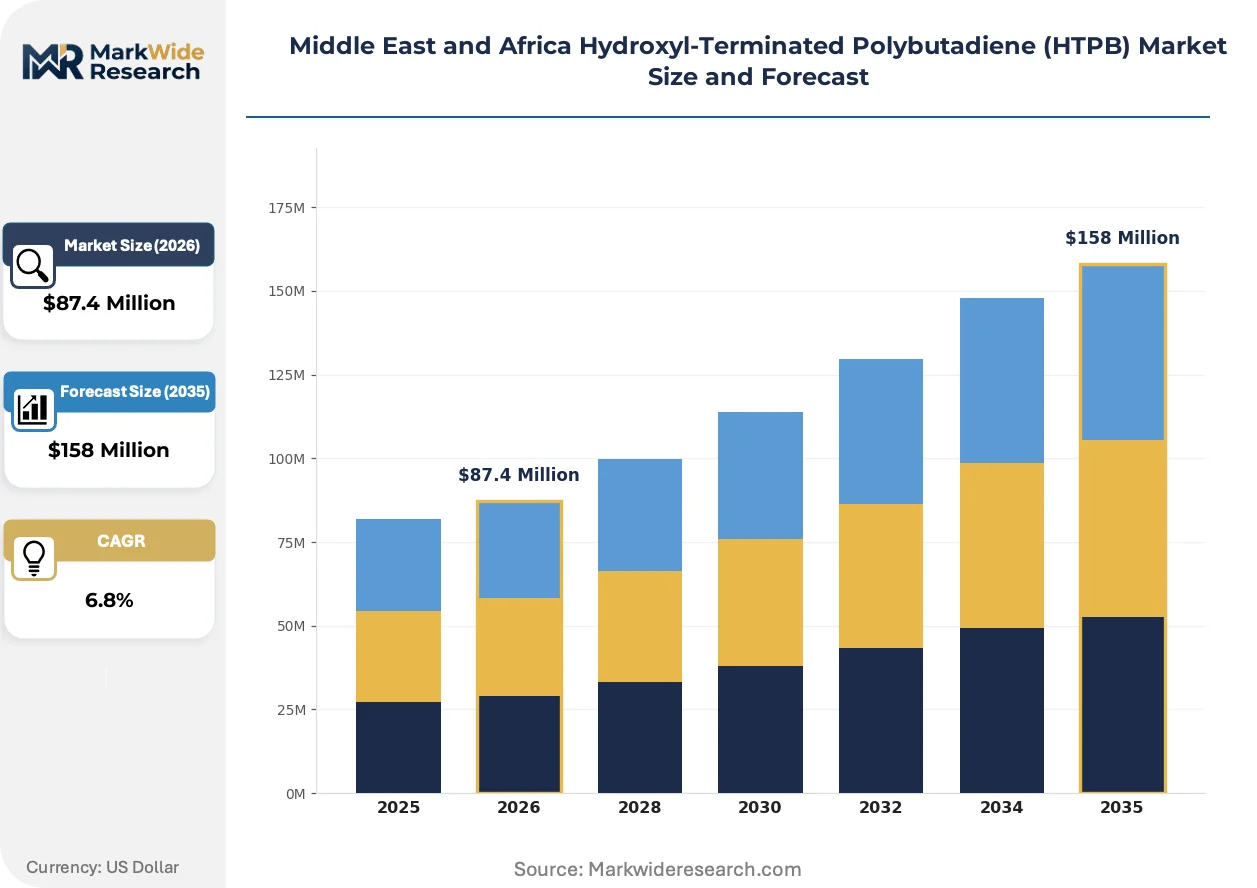
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid HTPB, Solid HTPB, Gel HTPB, Modified HTPB Application: Aerospace, Automotive, Coatings, Adhesives End User: Primary Manufacturers, Aerospace Companies, Automotive OEMs, Research Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Third-Party Suppliers |
| Companies Covered | Island Pyrochemical Industries, Huntsman Corporation, Evonik Industries AG, Tanyun Chemicals, Idemitsu Kosan Co., Ltd., Cray Valley, BASF SE, Orion Chem Pvt. Ltd., CRS Chemicals, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market Shifts & Advancements
Formulation chemistry is pivoting toward customized hydroxyl value specifications as defense contractors demand viscosity-tailored binders, while regulatory disclosure frameworks reshape cross-border trade documentation requirements across the Middle East and Africa.
Modified HTPB variants with tunable hydroxyl functionality are absorbing specification authority from standard liquid grades in aerospace propellant applications. Saudi and UAE defense contractors are specifying these customized grades for next-generation solid rocket motor programs. This technology shift is absorbing margin pools previously captured by commodity HTPB suppliers, compressing price competition around performance differentiation.
South Africa's National Cleaner Production Centre protocols are mandating volatile organic compound reduction in industrial polyurethane formulations. These standards force HTPB suppliers to document environmental fate characteristics and reformulate for lower-emission curing systems. Coatings manufacturers in Gauteng industrial zones are responding by qualifying low-VOC HTPB-toughened systems ahead of anticipated enforcement expansion.
Buyer concentration among Gulf state-owned defense contractors is compressing supplier negotiation leverage and elongating payment cycles. Specialty coatings formulators in North Africa are responding by developing direct distribution relationships with infrastructure project owners, bypassing traditional chemical distributor markups. This channel restructuring is most visible in Morocco's Atlantic port industrial corridor, where project-specific HTPB procurement is displacing stock-and-sell distribution.
Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market Segmentation
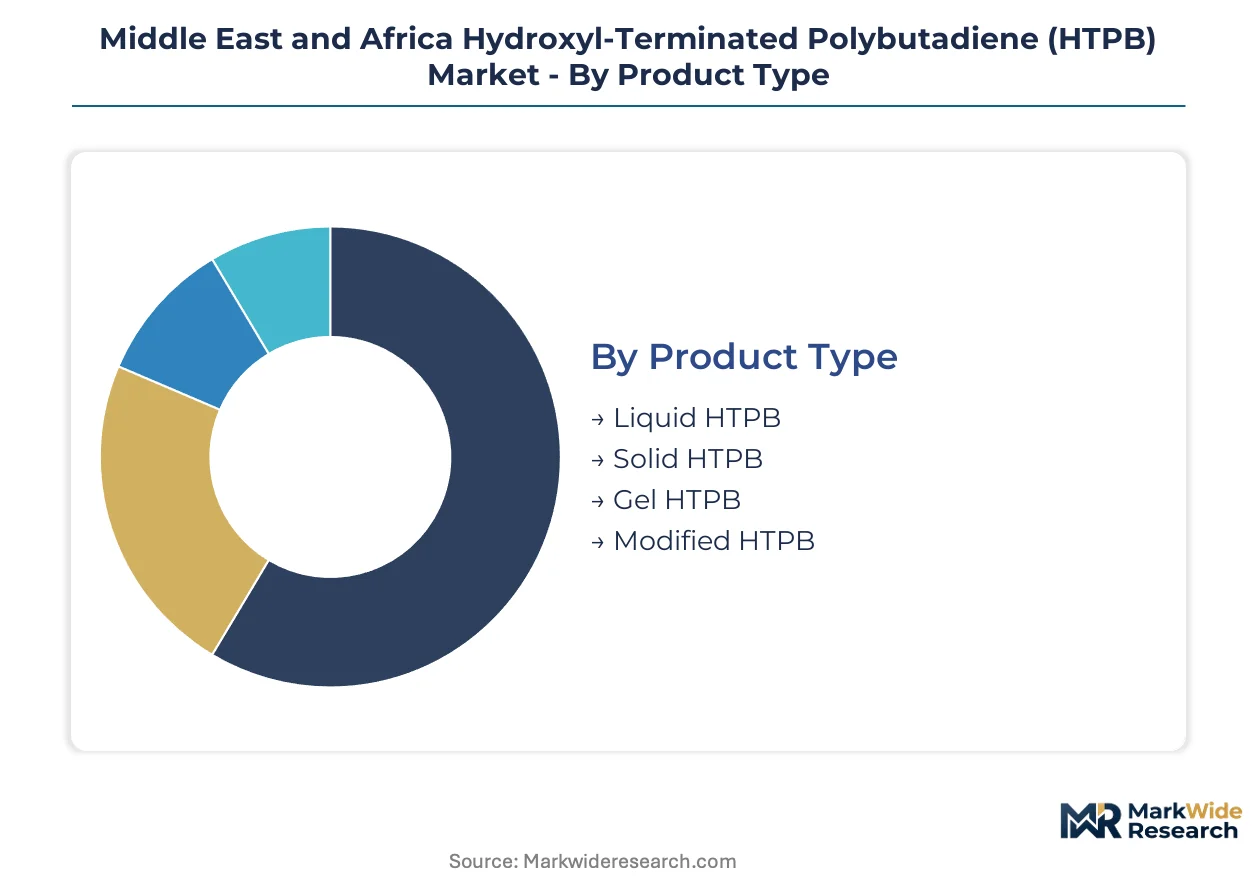
Segmentation in the Middle East and Africa Hydroxyl-Terminated Polybutadiene market reveals divergent procurement logics between defense-driven aerospace demand and industrial coatings applications. Understanding these splits enables suppliers to align technical service resources with distinct specification regimes across Gulf state-owned contractors and North African formulators.
Product Type:
Defense contractors prioritize viscosity control and hydroxyl value precision when selecting binder grades for solid rocket motor programs.
- Liquid HTPB:Standard liquid telechelic polymer with terminal hydroxyl functionality, manufactured through free-radical polymerization of 1,3-butadiene followed by selective hydroxylation. Saudi and UAE defense facilities specify this grade for cast-cure propellant systems due to its processability advantages in high-volume motor production.
- Modified HTPB:Customized variants with tunable hydroxyl values and viscosity profiles tailored to specific aerospace specifications. These grades capture expanding margin pools as Gulf contractors demand performance differentiation for next-generation solid rocket motor programs.
- Solid HTPB:Higher-viscosity grades requiring elevated processing temperatures, serving niche adhesive applications in South African automotive supply chains.
- Gel HTPB:Intermediate rheology formulations finding limited uptake in specialized coatings applications across Morocco's industrial zones.
Liquid HTPB leads on scale; Modified HTPB leads on momentum.
Application:
End-use concentration determines margin structure, with aerospace commanding specification premiums and coatings driving volume expansion.
- Aerospace:Solid rocket propellant binder and fuel component applications dominate value generation. Saudi Arabia's manufacturing corridor concentrates procurement authority for defense-grade material, with Saudi Standards, Metrology and Quality Organization certification protocols streamlining qualification cycles.
- Coatings:Polyurethane toughening agent demand accelerates across Morocco and Egypt as infrastructure spending rises. South Africa's National Cleaner Production Centre protocols force volatile organic compound reduction, pushing Gauteng formulators toward low-VOC HTPB-toughened systems.
- Automotive:Elastomer modification for vibration damping and impact resistance, primarily serving Japanese OEM supply chains operating in South Africa.
- Adhesives:Structural bonding applications in Gulf construction and industrial assembly, competing with epoxy-based alternatives.
Aerospace leads on scale; Coatings leads on momentum.
End User:
Procurement authority concentration varies sharply between consolidated state defense contractors and fragmented industrial formulators.
- Primary Manufacturers:Chemical processors and compounders serving downstream formulation markets. These intermediaries face margin compression from feedstock volatility in imported butadiene streams.
- Aerospace Companies:State-owned defense contractors across GCC states consolidating HTPB demand authority. Saudi and UAE entities specify customized hydroxyl values, elongating supplier qualification cycles.
- Automotive OEMs:Japanese manufacturers operating South African assembly plants, sourcing through captive supply relationships with established polymer suppliers.
- Research Institutions:Limited procurement volume centered on polyurethane-HTPB hybrid R&D programs in Egyptian and South African technical universities.
Aerospace Companies lead on scale; Primary Manufacturers lead on momentum.
Distribution Channel:
Channel structure reflects the tension between defense procurement formalism and industrial coatings formulators' cost sensitivity.
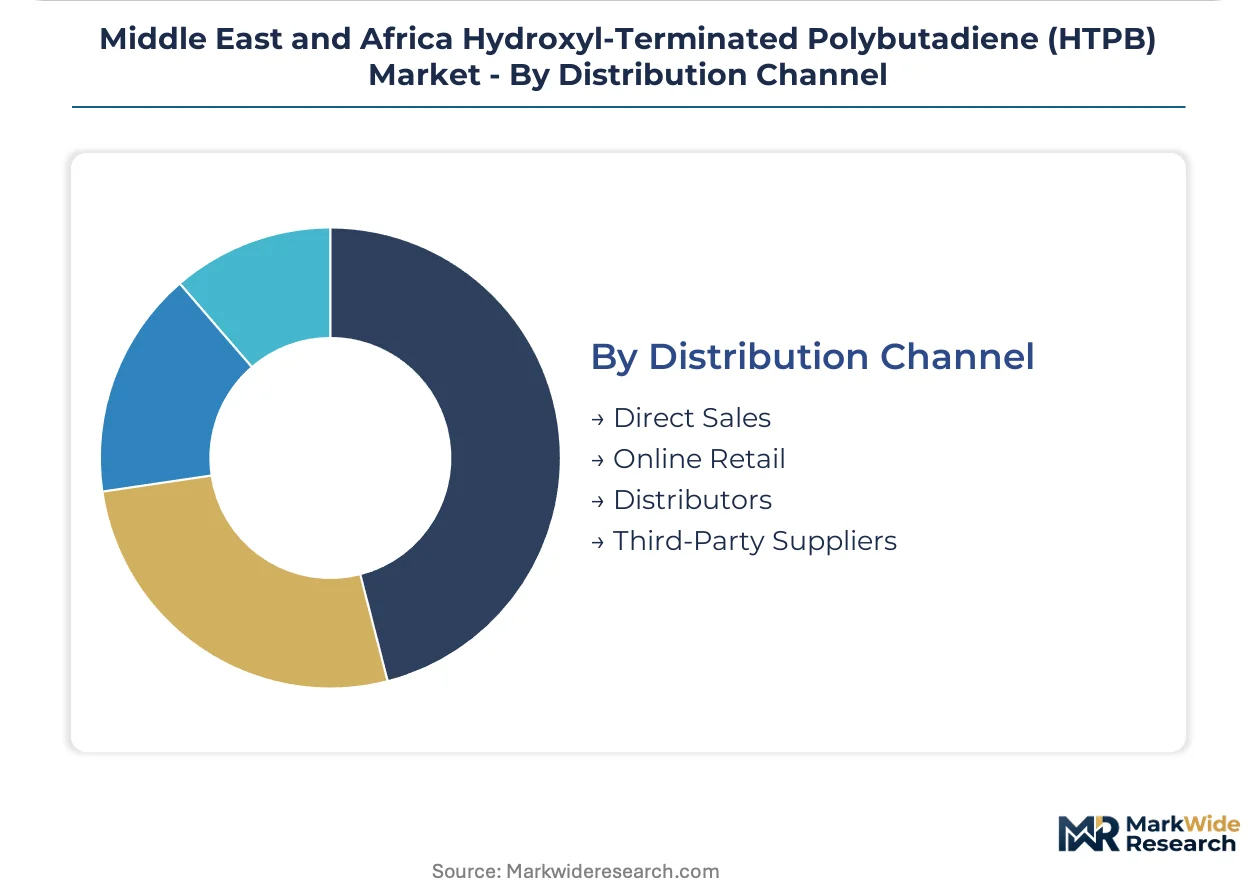
- Direct Sales:Dominant channel for aerospace-grade material, with suppliers maintaining technical service relationships with Saudi and UAE state-owned contractors. Long payment cycles compress working capital efficiency.
- Distributors:Traditional stock-and-sell networks serving North African coatings formulators. Project-specific procurement in Morocco's Atlantic port industrial corridor is displacing this model.
- Third-Party Suppliers:Intermediaries handling import logistics for South African formulators navigating National Regulator for Compulsory Specifications purity benchmarks.
- Online Retail:Negligible penetration due to technical specification complexity and certification documentation requirements.
Direct Sales leads on scale; Distributors leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia concentrates aerospace-grade procurement authority while South Africa enforces industrial purity standards that reshape import eligibility. Divergent regulatory frameworks across the Middle East and Africa fragment HTPB specification regimes and elongate supplier qualification cycles.
Saudi Arabia
State-owned defense contractors consolidate solid rocket motor procurement through the Kingdom's manufacturing corridor. Saudi Standards, Metrology and Quality Organization certification protocols now integrate chemical specification benchmarks, streamlining propellant-grade material qualification. Riyadh and the Eastern Province anchor cast-cure propellant production facilities serving GCC aerospace programs.
United Arab Emirates
Defense facilities in Abu Dhabi and Dubai specify liquid HTPB grades for standardized binder platforms in next-generation solid rocket motors. The UAE's national quality infrastructure aligns with Gulf defense procurement harmonization initiatives. Tawazun Council-backed industrial zones concentrate formulation expertise for regional aerospace supply chains.
South Africa
Gauteng industrial zones drive polyurethane toughening agent demand as automotive OEMs and coatings formulators adapt to National Cleaner Production Centre protocols. The National Regulator for Compulsory Specifications enforces polymer purity benchmarks that exclude lower-grade Asian supply. Japanese automotive supply chains operating in Eastern Cape and KwaZulu-Natal source through captive polymer relationships.
Egypt
Infrastructure construction across Cairo and Alexandria accelerates protective coatings consumption for industrial applications. Suez Canal Economic Zone chemical processing incentives attract downstream formulation investments targeting North African distribution. Project-specific procurement in the Canal corridor displaces traditional stock-and-sell distribution models.
Morocco
Atlantic port industrial zones concentrate infrastructure coatings demand as construction spending rises in Casablanca and Tangier-Med. Low-VOC polyurethane toughening systems gain qualification ahead of anticipated environmental enforcement expansion. Direct distribution relationships with project owners bypass traditional chemical distributor markups.
Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market Competitive Landscape
Japanese and European producers anchor the premium-grade tier; Chinese and Indian specialists hold volume positions in industrial formulations. Defense procurement consolidation across GCC states compresses supplier negotiation leverage and elongates payment cycles. Three archetypes dominate: petrochemical conglomerates with captive feedstock integration, aerospace-focused purity specialists, and regional distributors navigating dual certification requirements. Competitive moves center on backward integration into polybutadiene feedstock streams and technical documentation capabilities for emerging REACH-equivalent frameworks.
Within the petrochemical conglomerate tier, Idemitsu Kosan Co., Ltd. and BASF SE exemplify producers leveraging integrated feedstock positions. Evonik Industries AG occupies a position among purity specialists serving aerospace specification regimes. These anchors represent divergent strategic postures: feedstock security versus performance differentiation in high-specification segments.
| Leading Market Players |
|---|
| Island Pyrochemical Industries |
| Huntsman Corporation |
| Evonik Industries AG |
| Tanyun Chemicals |
| Idemitsu Kosan Co., Ltd. |
| Cray Valley |
| BASF SE |
| Orion Chem Pvt. Ltd. |
| CRS Chemicals |
| Others |
Supply & Pricing Matrix
Backward integration into polybutadiene feedstock streams anchors pricing power for Gulf-based suppliers serving Saudi and UAE defense contractors, while fragmented North African coatings procurement drives spot-market volatility for non-integrated formulators. Idemitsu Kosan's captive supply relationships with Japanese automotive OEMs in South Africa demonstrate how upstream control insulates margin stability against butadiene monomer price swings.
Pricing Analysis
Capacity additions in Saudi Arabia's Eastern Province manufacturing corridor are reshaping price floors for propellant-grade HTPB as state-owned contractors consolidate procurement authority. Contract-based long-term offtake dominates aerospace applications, with price differentiation resting on hydroxyl value precision and Saudi Standards, Metrology and Quality Organization certification tier. Cost compression in standard liquid grades is intensifying because Asian suppliers compete on volume for North African coatings demand. Specialty coatings formulators in Morocco exhibit highest price sensitivity, while GCC defense contractors prioritize performance over unit cost.
Supply Chain Analysis
Direct-to-aerospace-contractor channels handle consolidated Gulf defense demand, while distributor networks fragment across North African industrial zones. Geographic supply concentrates in Saudi Arabia, South Africa, and Egypt, with feedstock dependencies on imported 1,3-butadiene monomer, hydroxylation catalysts, and specialized packaging for moisture-sensitive liquid grades. Single-source vulnerability runs through the narrow base of qualified propellant chemists capable of cast-cure formulation support. Distribution runs through project-specific procurement in Morocco's Atlantic port corridor, displacing traditional stock-and-sell models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa HTPB market functions as a stable compounder anchored by defense procurement continuity across Gulf Cooperation Council states, where solid rocket motor programs generate predictable multi-year demand visibility regardless of industrial coatings cyclicality.
For Market Incumbents: Deepen technical documentation capabilities for emerging REACH-equivalent Gulf frameworks before disclosure mandates harden competitive barriers. Invest in captive hydroxylation capacity within Saudi Arabia's manufacturing corridor to compress logistics costs and accelerate qualification cycles with state-owned contractors. Epoxy toughening substitution in select aerospace programs demands performance differentiation through customized viscosity profiles rather than commodity volume competition. For New Entrants and Emerging Players: Enter via Egyptian Suez Canal Economic Zone chemical processing incentives, where downstream formulation investments for North African coatings distribution face lower incumbent saturation than Gulf defense supply chains. Target low-VOC polyurethane toughening systems in South Africa's Gauteng industrial zones ahead of National Cleaner Production Centre enforcement expansion. Qualify direct distribution relationships with Moroccan infrastructure project owners to bypass established chemical distributor markups. For Investors and Strategic Acquirers: Roll-up economics work for regional distributors with dual-certification capabilities because South African purity standards and Saudi defense protocols elongate qualification cycles beyond standalone capital reach. Five-to-ten year viability rests on consolidation of technical service assets serving fragmented North African coatings demand. Monitor propellant chemist scarcity as an inflection signal—recruitment gaps in Gulf defense facilities indicate sustained pricing power for qualified formulation support providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polybutadiene Feedstock | Captive butadiene supply insulates margin stability against import price volatility for Saudi defense contractors. |
| REACH-Equivalent Technical Documentation Pre-Registration | Early hydroxyl content disclosure capabilities privilege suppliers ahead of Gulf Cooperation Council framework harmonization. |
| Suez Canal Economic Zone Formulation Investment | Downstream processing assets capture North African coatings distribution margin pools from Egyptian industrial expansion. |
| Low-VOC Polyurethane System Qualification | South Africa's National Cleaner Production Centre protocols force reformulation toward emission-compliant toughening agents. |
| Direct Project-Owner Distribution Relationships | Morocco's Atlantic port corridor infrastructure spending enables bypass of traditional chemical distributor markups. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with solid rocket motor procurement officers at GCC state-owned contractors, polyurethane formulators in Gauteng industrial zones, and technical directors at Saudi and UAE defense facilities with secondary validation through customs trade data, Saudi Standards, Metrology and Quality Organization certification registries, and South African National Regulator for Compulsory Specifications import records. Bottom-up demand modeling from end-use applications and top-down supply verification from producer capacity disclosures were cross-referenced for triangulation.
Historical reference periods anchored the projection horizon through verified shipment volumes and contract award patterns across aerospace and coatings segments. Segmentation dimensions modeled include product grade tier, end-use application, procurement channel structure, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to normalized baseline data, with industry-specific inputs incorporating butadiene feedstock cost trajectories and defense budget allocation trends across Gulf Cooperation Council member states.
The model holds under sustained defense procurement continuity and gradual regulatory harmonization; deviation in butadiene supply disruption or accelerated epoxy substitution in aerospace binders would shift volume and value trajectories. Periodic stress-testing of base assumptions is recommended given feedstock volatility exposure and dual-certification timeline uncertainty.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Global Nylon Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market
Polymers & Resins
Global Acrylic Solid Surface Market
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Hybrid Polymer Market
Polymers & Resins
Polysulfide Market
Polymers & Resins
Bio-Based Polymer Market
Polymers & Resins
Bio-Based Epoxy Resin Market
Polymers & Resins
Polysorbate Market
Polymers & Resins
Amorphous Polyethylene Terephthalate (APET) Market
Polymers & Resins
Lactic Acid and Polylactic Acid Market
Polymers & Resins
Basic Methacrylate Copolymer Market
Polymers & Resins
Polyethylene Terephthalate (PET) Resin Market