
 Global Polypropylene Homopolymer (PPH) Market | 2026-2036
Global Polypropylene Homopolymer (PPH) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polypropylene Homopolymer (PPH) Market Foresight
Capital-intensity divergence between integrated refiners and standalone polymer producers is rotating competitive advantage toward feedstock-backed players. LyondellBasell Industries leverages its Gulf Coast propylene integration to sustain margin capture across injection molding grade output. Sinopec anchors volume leadership through captive refinery streams serving East Asian packaging converters. Braskem differentiates via bio-based polypropylene development, positioning its Brazilian operations for European sustainability-linked procurement.
Global Polypropylene Homopolymer is a semi-crystalline thermoplastic polymer composed solely of propylene monomer units, exhibiting a melting point near 160°C and high tensile stiffness suitable for precision molding and fiber extrusion. Its primary industrial purpose centers on rigid packaging, automotive structural components, and woven textile applications where chemical resistance and processability outweigh impact flexibility requirements. Injection molding grade commands the largest volume share across the analysis window, reflecting automotive and consumer goods tooling requirements, while film grade captures expanding food packaging demand driven by clarity and moisture barrier specifications. Fiber grade maintains mature growth trajectories in geotextiles and carpet backing, with margin pools concentrating in compounding grade formulations tailored to appliance and electronics housings.
FDA food contact regulations, EU REACH substance restrictions, and China's GB standards for automotive interior emissions collectively elevate testing and certification burdens for cross-border suppliers. These frameworks shape demand by disqualifying uncertified material from pharmaceutical packaging and European automotive supply chains, channeling procurement toward documented compliance holders. Stakeholders must monitor evolving extended producer responsibility mandates and polymer recycling content thresholds as these mechanisms increasingly determine market access qualifications across major consumption zones.
Market Dynamics
Automotive lightweighting mandates in Germany and China are redirecting injection molding grade polypropylene homopolymer into structural bumper and interior panel applications, compressing traditional metal substitution timelines while elevating material certification requirements.
Growth Catalysts
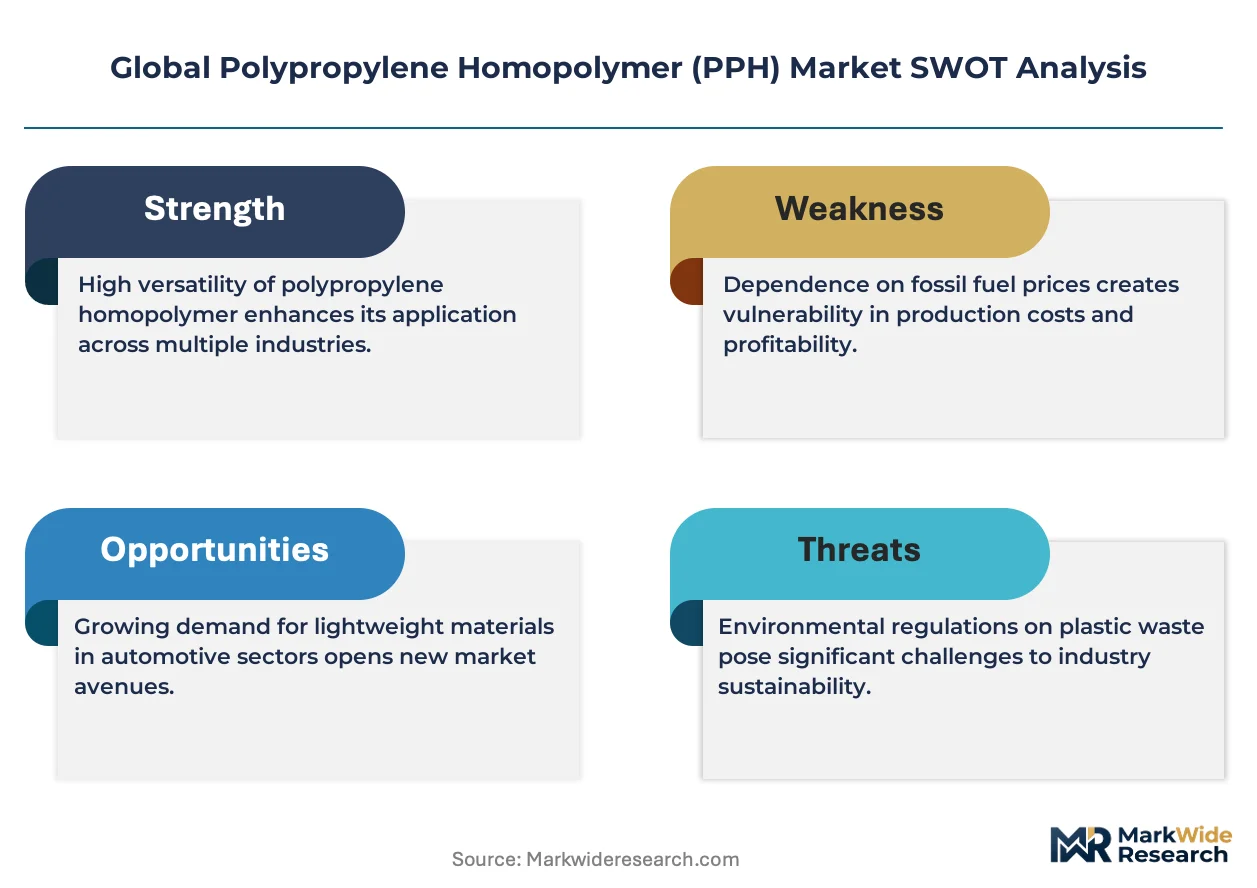
- REACH substance restrictions:European ECHA compliance protocols are channeling pharmaceutical packaging procurement toward certified PPH suppliers with documented purity traceability, locking out uncertified competitors.
- Automotive interior emissions standards:China's GB standards for cabin air quality are accelerating homopolymer adoption in dashboard and door panel applications where low-VOC performance is mandatory.
- Textile corridor concentration:India's western industrial belt around Gujarat and Maharashtra is pulling fiber-grade material into geotextile and carpet backing production anchored by Reliance Industries' captive supply.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker economics and PDH unit operating rates create margin compression for standalone polymer producers lacking refinery integration.
- Impact copolymer substitution:Polypropylene random copolymer and impact copolymer grades are displacing homopolymer in cold-chain packaging and refrigerated container applications where low-temperature ductility matters.
- Single-supplier concentration risk:Gulf Coast propylene derivative capacity dominance creates geographic vulnerability for buyers dependent on US Gulf material flows.
Strategic Opportunities
- Bio-based feedstock pathways:Braskem's sugarcane-derived propylene development opens European sustainability-linked procurement pools for converters seeking Scope 3 emission reductions.
- Extended producer responsibility mandates:EU packaging waste directives and emerging state-level US laws are creating certified recycled-content grade premiums for mechanical recycling-compatible homopolymer formulations.
- Appliance compounding grade expansion:India's northern electronics manufacturing clusters around Noida and Pune present underpenetrated demand for flame-retardant compounded PPH in washing machine and refrigerator housings.
Industry Challenges
- Multijurisdictional certification timelines:Simultaneous FDA food contact, EU REACH, and China GB automotive compliance requires 18-24 month documentation cycles that delay new supplier market entry.
- Legacy injection molding asset retrofit:Converting automotive Tier-1 tooling from ABS and PC-ABS to PPH-grade specifications demands capital-intensive mold flow redesign and cooling channel reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polypropylene Homopolymer (PPH) Market |
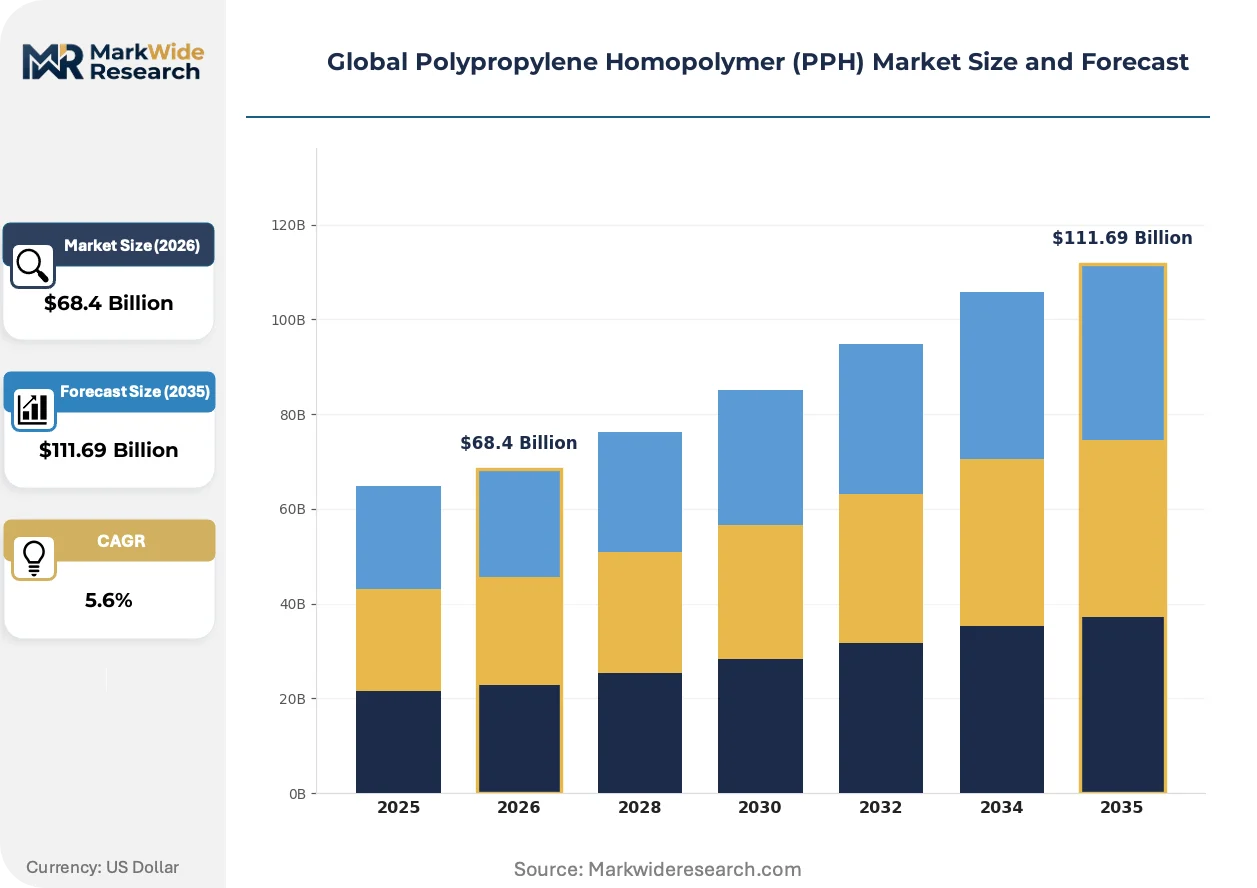
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $111.69 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molding Grade, Film Grade, Fiber Grade, Compounding Grade Application: Packaging, Textiles, Automotive Components, Consumer Goods End User Industry: Manufacturing, Construction, Electronics, Appliances Form: Granules, Pellets, Powder, Flakes |
| Companies Covered | INEOS, Borealis AG, LyondellBasell Industries, Reliance Industries Limited, Braskem, ExxonMobil, TotalEnergies, China Petrochemical Corporation (Sinopec), SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polypropylene Homopolymer (PPH) Market Shifts & Advancements
Process intensification and regulatory chemistry are reshaping competitive differentiation in polypropylene homopolymer, with technology trajectories diverging between mechanical recycling integration and bio-attributed feedstock verification systems.
Advanced nucleating agent technology is bifurcating injection molding grade performance tiers. Millad NX8000 clarifiers and HPN-20E hyper-nucleating systems enable 15-20% cycle time reduction in thin-wall packaging tooling. Tier-1 automotive suppliers in Stuttgart and Shanghai are specifying clarified grades for Class A interior surfaces. This capability split is compressing margin pools for commodity-grade producers while concentrating premium capture with additive-masterbatch integrated compounders.
EU F-Gas Regulation phase-down schedules are accelerating HFO-1234yf adoption in mobile air conditioning systems, indirectly elevating PPH demand for under-hood HVAC housings requiring 150°C continuous service temperature resistance. Tier-2 suppliers in Wolfsburg and Tianjin are qualifying new homopolymer grades for blower motor enclosures. The regulatory cascade is most acute in German and Chinese automotive supply chains where OEM sustainability scorecards weight refrigerant transition compliance.
Direct mill procurement contracts are displacing distributor intermediaries in high-volume packaging converter segments. Reliance Industries and Sinopec are establishing annual volume frameworks with Indian flexible packaging leaders in Vadodara and Mumbai, bypassing traditional polymer trading houses. This channel compression is most visible in India's western corridor where captive refinery supply guarantees and rail-served silo infrastructure enable just-in-time resin delivery without inventory carrying costs.
Global Polypropylene Homopolymer (PPH) Market Segmentation
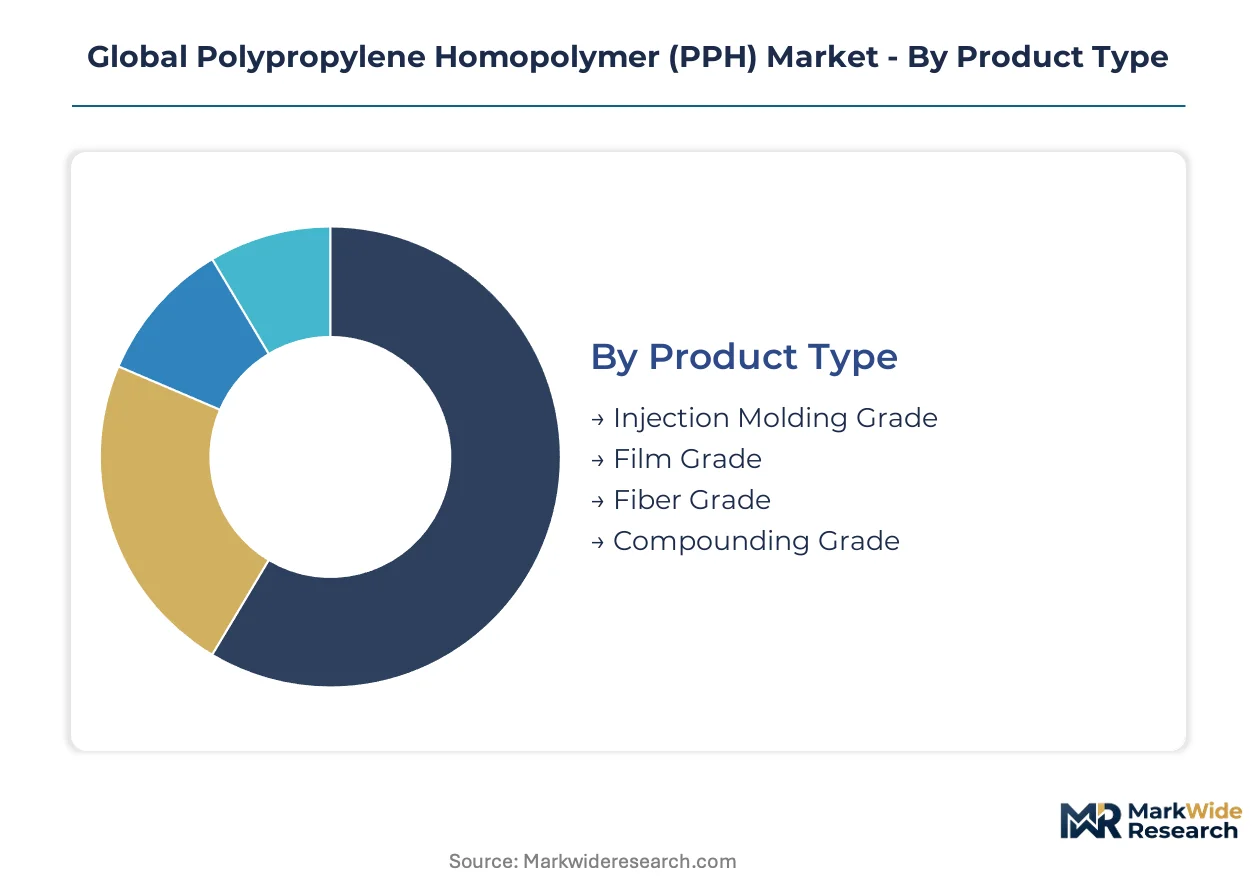
Polypropylene homopolymer segments diverge sharply in their exposure to copolymer substitution and regulatory compliance burdens. Understanding these fault lines enables suppliers to prioritize certification investments and defend margin pools against adjacent-grade competition.
Product Type:
Injection molding grade faces the most acute displacement pressure from impact copolymers in cold-chain applications, while fiber grade maintains structural insulation from substitution through crystallinity requirements.
- Injection Molding Grade:High-flow formulations with melt flow indices of 20-100 g/10min enable thin-wall precision in automotive bumper substrates. Demand concentrates in Stuttgart and Shanghai automotive clusters where OEM lightweighting mandates compress metal substitution timelines. China's GB standards for cabin emissions disqualify non-certified material from dashboard contracts.
- Film Grade:Biaxially oriented variants deliver moisture barriers below 0.5 g/m²/day for snack packaging. Indian flexible packaging converters in Vadodara and Mumbai are pulling clarified grades through direct mill contracts that bypass distributor markups.
- Fiber Grade:High-tenacity yarns for geotextile reinforcement require isotactic indices above 95%.
- Compounding Grade:Base resin for flame-retardant appliance housings with customized additive packages.
Injection molding grade retains volume leadership; film grade holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity packaging from specification-driven automotive and medical segments where certification premiums concentrate.
- Packaging:Rigid containers and thin-wall cups dominate volume, with food contact FDA compliance mandatory for dairy and ready-meal segments. Indian converters around Ahmedabad are expanding BOPP film lines for export markets.
- Automotive Components:Under-hood HVAC housings require 150°C continuous service temperature resistance for HFO-1234yf refrigerant compatibility. German Tier-1 suppliers in Wolfsburg specify clarified nucleated grades for Class A interior surfaces.
- Textiles:Woven sacks and carpet backing in India's Gujarat corridor leverage Reliance Industries' captive supply.
- Consumer Goods:Houseware and furniture applications compete with recycled PET and bio-based alternatives.
Packaging retains volume leadership; automotive components hold the steepest expansion curve.
End User Industry:
Customer type fragmentation concentrates procurement power in automotive OEMs and electronics contract manufacturers while dispersing leverage across construction distributors.
- Manufacturing:Injection molders and extruders serving diverse industrial accounts represent the baseline demand pool.
- Construction:Geotextile and membrane applications in infrastructure projects favor fiber grade with UV stabilization packages.
- Electronics:Noida and Pune manufacturing clusters present underpenetrated demand for flame-retardant compounded grades in washing machine and refrigerator housings.
- Appliances:White goods producers specify custom color-matched compounds with scratch resistance additives.
Manufacturing retains volume leadership; electronics holds the steepest expansion curve.
Form:
Supply chain configuration determines form selection, with rail-served silo infrastructure favoring bulk granules and export logistics privileging dense pellet packaging.
- Granules:Standard extrusion feedstock delivered via pneumatic conveying systems to high-volume converters.
- Pellets:Uniform cylindrical form optimized for ocean freight containerization and automated handling.
- Powder:Rotational molding and coating applications require fine particle size distribution.
- Flakes:Post-industrial regrind streams feeding mechanical recycling lines for emerging EPR-mandated content.
Granules retain volume leadership; pellets hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Indian packaging converters exhibit acute price sensitivity, driving direct mill procurement. German automotive buyers absorb certification premiums for REACH-compliant material. China's state-backed capacity expansion compresses regional margins.
China
State-directed refinery-polymer integration sustains cost leadership in injection molding grade output. MIIT's GB standards for automotive interior emissions disqualify uncertified imports from dashboard contracts. Shanghai and Tianjin automotive clusters specify clarified nucleated grades for Class A surface applications.
Germany
Stuttgart and Wolfsburg OEMs mandate REACH-traceable material for pharmaceutical packaging and under-hood HVAC housings. ECHA substance restrictions channel procurement toward documented purity suppliers. Bavarian Tier-1 suppliers qualify homopolymer grades for HFO-1234yf refrigerant compatibility.
India
Gujarat and Maharashtra textile corridors pull fiber-grade material through Reliance Industries' captive refinery supply. BIS certification requirements for food contact applications elevate testing burdens for imports. Vadodara and Mumbai flexible packaging converters expand BOPP film lines via direct annual volume frameworks.
United States
Gulf Coast propylene derivative concentration creates geographic vulnerability for buyers lacking alternative sourcing. FDA food contact regulations and emerging state-level extended producer responsibility laws reshape certification requirements. Houston-area integrated refiners leverage feedstock backing for margin capture.
Brazil
Sugarcane-derived propylene development opens European sustainability-linked procurement pools. ANVISA pharmaceutical packaging standards align with FDA equivalency protocols. São Paulo state operations anchor bio-based grade differentiation for Scope 3 emission-conscious converters.
Global Polypropylene Homopolymer (PPH) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes. The market exhibits tiered concentration with integrated refiners commanding feedstock-backed margins while standalone compounders compete on formulation specialization. Three archetypes dominate: Gulf Coast propylene integrators, European REACH-certified purity suppliers, and bio-based feedstock pioneers. Capacity expansion and certification portfolio diversification constitute the primary competitive vectors.
Among integrated petrochemical giants, LyondellBasell Industries and Sinopec exemplify the feedstock-backed archetype through Gulf Coast and East Asian refinery integration respectively. Braskem occupies a distinctive position within the bio-based tier, anchoring sustainability-linked procurement channels for European converters seeking emission reductions.
| Leading Market Players |
|---|
| INEOS |
| Borealis AG |
| LyondellBasell Industries |
| Reliance Industries Limited |
| Braskem |
| ExxonMobil |
| TotalEnergies |
| China Petrochemical Corporation (Sinopec) |
| SABIC |
| Others |
Supply & Pricing Matrix
Gulf Coast propylene derivative concentration at 160 million tonnes annual capacity anchors global cost floors for injection molding grade material. This scale concentration compresses margins for standalone polymer producers lacking refinery integration while elevating pricing power among feedstock-backed players serving automotive and pharmaceutical certification tiers.
Pricing Analysis
After-sales compounding service contracts and technical support subscriptions drive lifetime value capture beyond resin spot sales. Three-tier pricing structure across REACH-certified premium, FDA food-contact standard, and commodity economy levels separates procurement pools by documentation burden. Cost compression in commodity injection molding grade intensifies because China's state-backed refinery expansions flood regional spot markets. Indian flexible packaging converters exhibit acute price sensitivity, while German automotive Tier-1 suppliers absorb certification premiums for ECHA-traceable material.
Supply Chain Analysis
Inventory cycles extending 45-60 days from Gulf Coast propylene hubs to European compounders expose buyers to naphtha-cracker margin volatility. Production gravity centers on the United States, China, and Saudi Arabia, with Braskem's Brazilian bio-based operations feeding European sustainability-linked procurement. Feedstock supply rests on naphtha steam crackers, PDH unit propylene yields, and refinery FCC offgas streams. Single-source concentration risk concentrates in Houston-area propylene derivative capacity. Distribution runs through direct mill procurement contracts displacing traditional polymer trading houses in high-volume converter segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks cyclical recovery patterns tied to automotive production schedules and refinery operating rate adjustments. Naphtha-cracker margin compression cycles historically precede pricing inflections by 6-9 months.
For Market Incumbents: Fortify REACH certification portfolios against ECHA substance restriction expansions that threaten to disqualify legacy purity grades from pharmaceutical packaging contracts. Deepen backward integration into propylene feedstock through PDH unit investments or long-term offtake agreements with Gulf Coast refiners to defend margin capture against standalone polymer competitors. For New Entrants and Emerging Players: FDA food contact certification fast-tracks unlock dairy and ready-meal packaging procurement pools where incumbent documentation backlogs create 18-24 month entry delays. India's northern electronics manufacturing clusters around Noida present underpenetrated demand for flame-retardant compounded grades in appliance housings. Pursue direct annual volume frameworks with flexible packaging converters bypassing distributor markups. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated refiners with captive propylene supply and long-term automotive supply agreements. Five-to-ten year viability favors feedstock-backed players with certification breadth across FDA, REACH, and China GB standards. Monitor PDH unit operating rate spreads as the signal for margin inflection and capacity rationalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstock | Gulf Coast PDH unit investments lock in margin capture against naphtha-cracker volatility cycles. |
| REACH Certification Portfolio Expansion | ECHA-traceable purity documentation opens pharmaceutical packaging procurement pools with 15-20% premium capture. |
| Direct Mill Procurement Contracts | Reliance Industries and Sinopec annual volume frameworks bypass distributor markups for Indian flexible packaging converters. |
| Bio-Based Feedstock Transition | Braskem's sugarcane-derived propylene development accesses European sustainability-linked procurement with Scope 3 emission reductions. |
| Flame-Retardant Compounding Grade Capacity | Noida and Pune electronics clusters present underpenetrated demand for appliance housing specifications. |
Research Methodology
A spread of perspectives from polymer plant managers, automotive Tier-1 procurement leads, flexible packaging converter executives, and distribution channel partners converged on the working assumptions for demand elasticity and substitution thresholds. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated petrochemical majors, and ECHA substance restriction notifications. Bottom-up grade-level volume builds and top-down refinery capacity utilization assessments were triangulated against regional production database estimates.
Segmentation dimensions modeled include product grade tier, end-use industry application, regional production hub concentration, and certification compliance level across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections tied to automotive lightweighting program timelines and packaging converter capacity expansion announcements. Forecast inputs incorporated naphtha-to-polypropylene spread assumptions and PDH unit operating rate trajectories without specifying year-over-year progression.
The analysis sits within stated boundaries; outcomes outside sustained refinery integration economics or accelerated ECHA substance restriction timelines would require recalibration. Forecasts reflect documented assumptions about feedstock cost trajectories and regulatory certification burden evolution. Revision becomes warranted when propylene feedstock volatility indices cross threshold spreads that trigger standalone producer capacity rationalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Filled Fluoropolymer Market
Polymers & Resins
Bio Based Resin Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
Global Bio Polyamide Market
Polymers & Resins
Bakelite Market
Polymers & Resins
Global UV Curable Resins and Formulated Products Market
Polymers & Resins
Liquid Saturated Polyester Resin Market
Polymers & Resins
Bio-Based PU Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Europe Superabsorbent Polymers Market
Polymers & Resins
Bio-Polybutadiene Market
Polymers & Resins
United States Polyols Market
Polymers & Resins
1-Hexene Based Polyethylene Market
Polymers & Resins
Global Cyanate Ester Resins Market
Polymers & Resins
Cast Polymers Market