
 Synthetic and Bio Thermosets Market | 2026-2036
Synthetic and Bio Thermosets Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic and Bio Thermosets Market Intelligence
The market's end-use composition is pivoting away from traditional consumer goods applications toward high-performance materials for the automotive and aerospace sectors. Huntsman Corporation leverages its specialized epoxy resin portfolio to serve demanding aerospace clients. BASF sustains a broad market presence through its extensive polyurethane product lines. Dow Chemicals competes on scale and process efficiency in foundational phenolic resins, targeting large-volume industrial applications.
Synthetic and bio thermosets are polymers that irreversibly cure into a rigid, three-dimensional network through a process of cross-linking. This chemical reaction provides high thermal stability and mechanical strength, making them essential for durable components. Epoxy resins lead in high-performance applications like aerospace due to their superior strength-to-weight ratio. Polyurethane formulations are expanding rapidly, driven by their versatility in automotive and electrical and electronics end uses.
The European Union's REACH regulation governs the chemical composition and safety of synthetic thermosets, impacting market access. In the United States, EPA standards on volatile organic compounds influence formulation choices, particularly for phenolic and urea-formaldehyde resins. Navigating the divergent material requirements between traditional synthetic and emerging bio-based supply chains will be a critical strategic decision for manufacturers.
Market Dynamics
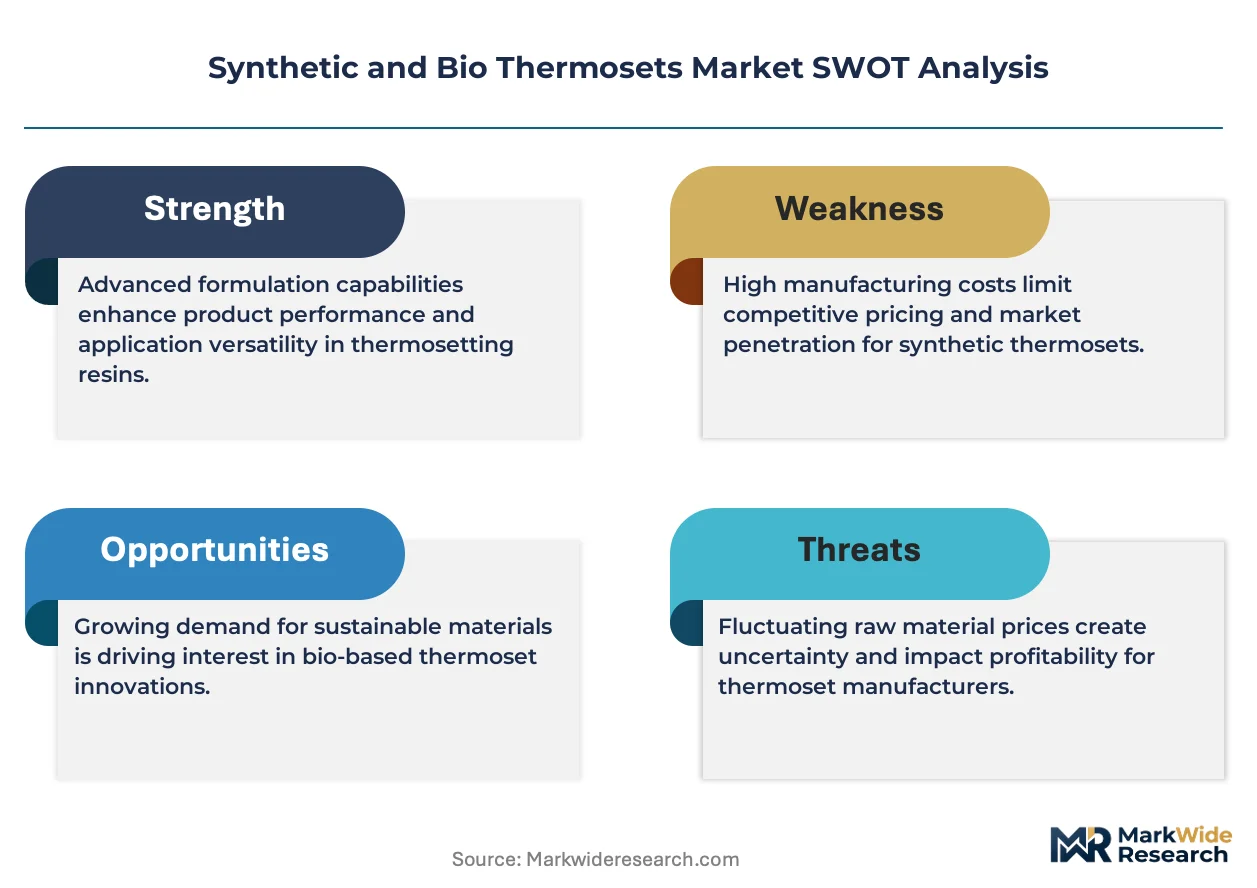
A fundamental bifurcation is shaping the thermoset market. One path deepens specialization in high-performance synthetic resins for aerospace and automotive sectors, while the other accelerates development of bio-based alternatives to meet sustainability mandates like the EU Green Deal and national carbon goals in China.
Growth Catalysts
- Aerospace Lightweighting:The aviation sector's pursuit of fuel efficiency drives adoption of high-strength epoxy composites for structural components.
- Sustainability Mandates:Policies like the EU Green Deal incentivize development of bio-thermosets from renewable feedstocks such as lignin.
- Electric Vehicle Components:Polyurethane formulations are critical for battery encapsulation and thermal management systems in electric vehicles.
Market Restraints
- Feedstock Volatility:Production costs for synthetic thermosets are directly exposed to price fluctuations of petrochemical derivatives, impacting margin stability.
- Regulatory Burden:Adherence to chemical safety rules like the EU's REACH regulation imposes significant testing and documentation costs on producers.
- Bio-Resin Performance Gaps:Many bio-based thermosets exhibit longer cure times and lower thermal stability, limiting their use in high-performance applications.
Strategic Opportunities
- Additive Manufacturing:Developing photocurable thermoset resins for 3D printing opens new markets for rapid prototyping and complex part fabrication.
- Recyclable Chemistries:Research into vitrimers and other dynamic covalent network polymers offers a path to recyclable thermosets, addressing end-of-life waste.
- Infrastructure in India:India's expanding construction and transportation sectors create significant demand for durable phenolic and epoxy resins in new projects.
Industry Challenges
- Supply Chain Reconfiguration:Shifting from established petrochemical supply chains to agricultural or forestry-based feedstocks for bio-thermosets presents significant logistical and sourcing challenges.
- Capital Investment for Bio-Production:Scaling up biorefinery capacity to produce bio-based precursors at an industrial scale requires substantial capital expenditure and long investment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic and Bio Thermosets Market |
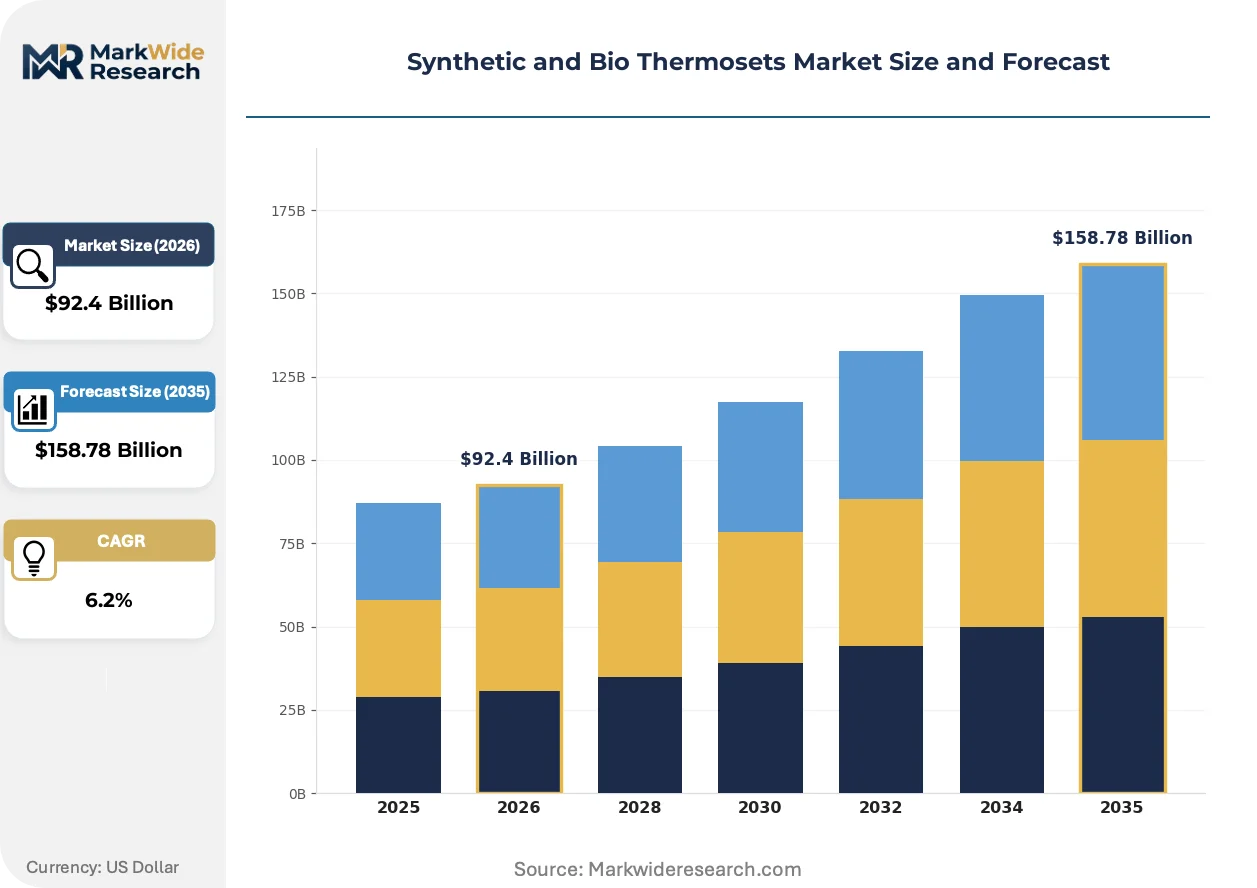
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $158.78 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Resins, Phenolic Resins, Urea-Formaldehyde, Polyurethane Application: Aerospace, Automotive, Consumer Goods, Electrical & Electronics End User: Manufacturers, OEMs, Contractors, Distributors Distribution Channel: Direct Sales, Online Sales, Retail, Wholesalers |
| Companies Covered | BASF, Huntsman Corporation, Dow Chemicals, Hexion Inc., Lanxess, Ashland, AOC Resins, DSM, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic and Bio Thermosets Market Strategic Shifts & Innovations
The convergence of advanced material science with digital manufacturing processes is transforming thermoset applications. Sustainability requirements are accelerating this shift, pushing innovation beyond incremental formulation changes toward fundamentally new material and production paradigms.
Self-healing thermosets utilize dynamic chemical bonds or encapsulated healing agents to autonomously repair cracks. Aerospace and high-end automotive sectors are primary adopters, seeking to extend the service life of critical parts. This capability is absorbing R&D focus from passive damage resistance, enabling designs with built-in longevity and reduced maintenance.
Regulations from the US Environmental Protection Agency (EPA) targeting volatile organic compounds (VOCs) are driving formulation changes. These rules impact solvent-based phenolic and formaldehyde resins used in coatings and composites. Manufacturers are accelerating the shift to water-based and 100% solids epoxy or polyurethane systems to ensure compliance in regulated US states.
A demand-side shift is underway from purchasing commodity resins to procuring complete material systems, including catalysts and processing support. This model challenges bulk chemical distributors, favoring suppliers offering integrated solutions. The wind energy sector exemplifies this, where blade manufacturers demand certified resin-infusion systems to ensure component reliability and performance.
Synthetic and Bio Thermosets Market Segmentation
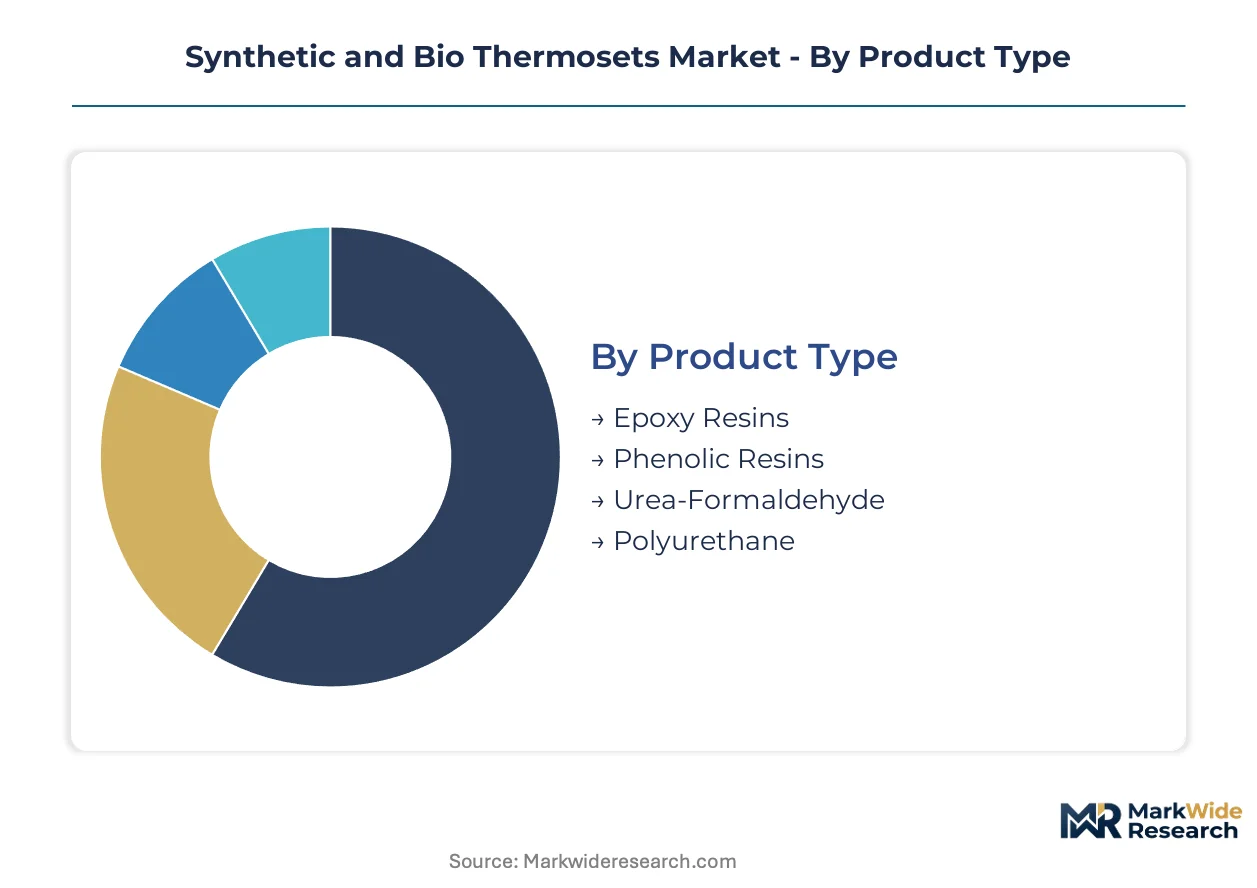
The segmentation of the synthetic and bio thermosets market provides a granular view of material applications and value chain dynamics. Understanding these distinct segments is essential for manufacturers to align product development with specific end-use requirements and distribution strategies.
Product Type:
The market for thermosets demonstrates varying levels of integration, from standalone resin systems to complex embedded components.
- Epoxy Resins:These thermosets are characterized by their exceptional strength-to-weight ratio and adhesive properties, forming rigid, cross-linked networks upon curing. Demand concentrates in the aerospace sector for structural components, driven by the aviation industry's pursuit of fuel efficiency.
- Polyurethane:Polyurethane formulations offer remarkable versatility, ranging from rigid foams to flexible elastomers, and exhibit excellent abrasion resistance. Their application in electric vehicle battery encapsulation and thermal management systems is expanding rapidly in the automotive sector.
- Phenolic Resins:These resins are known for their high thermal stability and cost-effectiveness, commonly used in large-volume industrial applications.
- Urea-Formaldehyde:Urea-formaldehyde resins provide good adhesion and rigidity, primarily utilized in wood composites and certain adhesive applications.
Epoxy Resins leads volumes today; Polyurethane is gaining share fastest.
Application:
Application segments delineate where thermoset materials deliver their highest value, from high-stress structural components to everyday consumer items.
- Aerospace:This application segment demands materials with superior strength, lightweight properties, and thermal resistance for aircraft structural components and interior parts. The aviation sector's pursuit of fuel efficiency drives the adoption of advanced epoxy composites.
- Automotive:Thermosets in the automotive sector are critical for lightweighting, noise reduction, and thermal management in both traditional and electric vehicles. Polyurethane formulations are essential for battery components and interior parts, enhancing vehicle performance.
- Electrical & Electronics:These materials provide insulation, encapsulation, and structural support for various electronic devices and components.
- Consumer Goods:Thermosets find use in durable consumer products requiring specific mechanical properties or aesthetic finishes.
Aerospace applications demand the most stringent performance, while Automotive applications represent a substantial and expanding volume base.
End User:
End-user categories reflect the diverse points of consumption within the value chain, from direct manufacturing to project-based procurement.
- Manufacturers:These end users integrate thermoset materials directly into their production processes for a wide array of industrial and consumer products. Huntsman Corporation and BASF serve these clients with specialized resin portfolios and broad product lines.
- OEMs:Original Equipment Manufacturers specify and procure thermosets for critical components within their final products, particularly in the automotive and aerospace industries. Their material requirements often dictate performance and compliance standards.
- Contractors:Contractors utilize thermoset products, especially in construction and infrastructure projects, for durable coatings and structural elements.
- Distributors:Distributors serve as intermediaries, supplying a range of thermoset materials to smaller businesses and specialized fabricators.
OEMs drive significant material specifications, and Manufacturers integrate thermosets into final product assemblies.
Distribution Channel:
Distribution channels illustrate the primary routes to market, ranging from direct supplier-to-client relationships to broad retail availability.
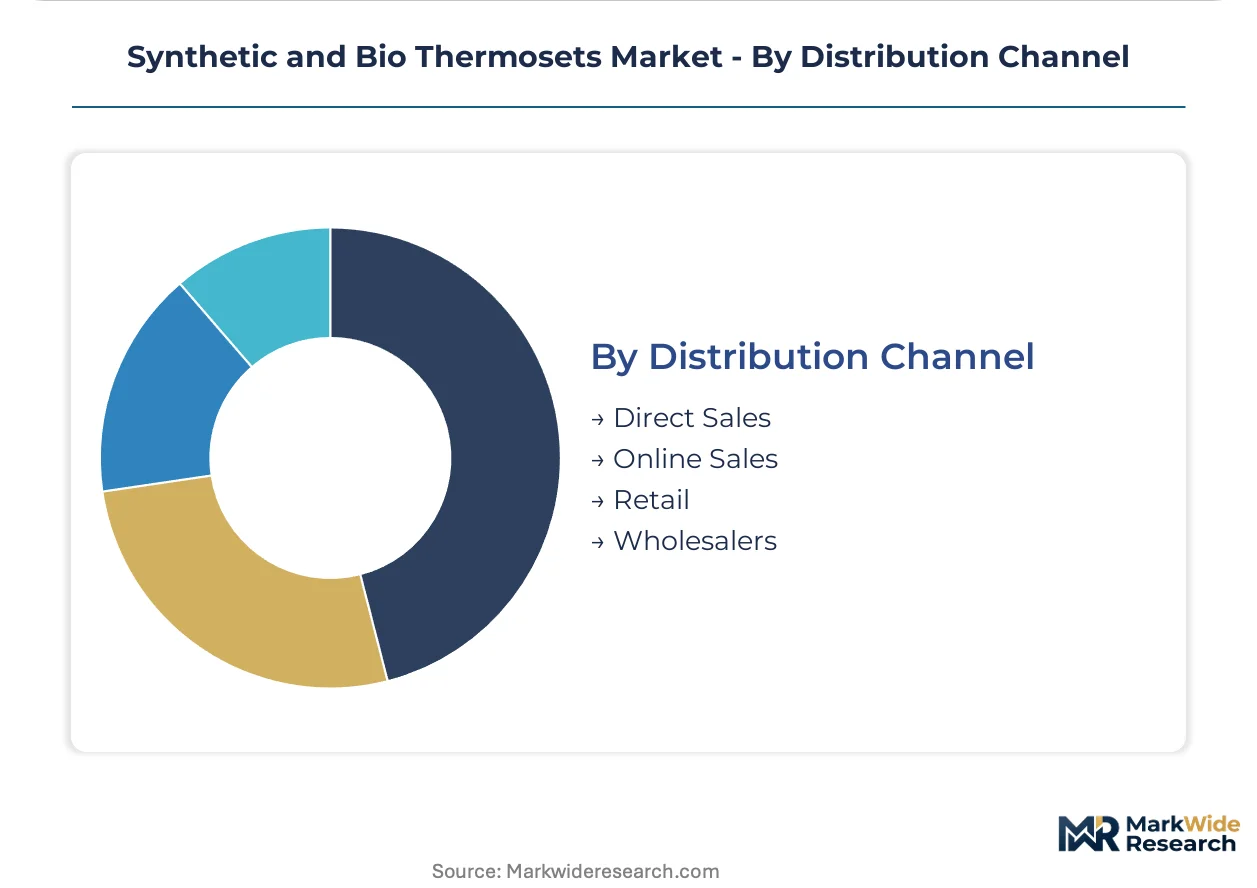
- Direct Sales:This channel involves direct transactions between thermoset producers and large industrial customers, often for specialized or high-volume orders. This approach facilitates technical support and customized material solutions for demanding clients.
- Wholesalers:Wholesalers purchase thermoset materials in bulk from manufacturers and then distribute them to a diverse range of smaller businesses and regional customers. They provide logistical support and broader market reach for producers.
- Online Sales:E-commerce platforms facilitate the purchase of certain thermoset products, offering convenience and accessibility for smaller buyers.
- Retail:Retail channels cater to individual consumers or small-scale users for general-purpose thermoset products.
Direct Sales channels manage large, specialized orders, whereas Wholesalers serve a broader array of smaller clients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage influences the global thermoset market, as producers navigate varying environmental standards and cost structures across regions. This dynamic often shifts manufacturing bases to areas with more favorable compliance costs or robust local demand. Such strategic relocation impacts supply chain configurations and investment patterns worldwide.
China
China's national carbon goals drive significant investment in bio-based thermoset development for sustainable manufacturing. The country's dual carbon goals incentivize domestic production of advanced materials for electric vehicle components and infrastructure. Industrial clusters in the Yangtze River Delta actively scale up biorefinery capacity for bio-based precursors.
United States
United States demand for high-performance thermosets stems from its aerospace and defense sectors, alongside electric vehicle manufacturing. EPA standards on volatile organic compounds influence formulation choices, particularly for phenolic and urea-formaldehyde resins. Aerospace hubs in Seattle and Wichita integrate epoxy composites for structural aircraft components.
Germany
Germany's automotive and advanced manufacturing industries create strong demand for versatile polyurethane formulations and high-performance epoxies. Adherence to the EU Green Deal and REACH regulation shapes material development towards sustainable and compliant chemistries. The Stuttgart region's automotive cluster focuses on polyurethane formulations for electric vehicle battery encapsulation.
India
India's expanding construction and transportation sectors generate substantial demand for durable phenolic and epoxy resins in new infrastructure projects. The country's PLI scheme for automotive and electronics manufacturing encourages local production of high-performance materials. Industrial zones near Mumbai are witnessing increased adoption of thermosets for building and automotive components.
France
France's aerospace industry, particularly around Toulouse, drives demand for high-strength epoxy composites for structural components. The EU Green Deal significantly influences research into bio-thermosets derived from renewable feedstocks like lignin. Research centers in Lyon collaborate on developing advanced recyclable chemistries for aerospace applications.
Synthetic and Bio Thermosets Market Key Industry Players
Strategic partnerships and portfolio diversification dominate the current landscape, as companies seek to navigate the bifurcated thermoset market. The market structure features a mix of large, diversified chemical conglomerates and specialized resin manufacturers. Key strategic archetypes include broad-spectrum providers and high-performance specialists. Companies are actively pursuing technology licensing and capacity expansion, particularly in bio-based materials.
Broad-spectrum providers like BASF sustain a wide market presence through extensive polyurethane product lines, catering to diverse end-use applications across automotive and electrical sectors. Huntsman Corporation exemplifies the high-performance specialist archetype, leveraging its specialized epoxy resin portfolio to serve demanding aerospace clients with tailored solutions requiring superior strength-to-weight ratios. Dow Chemicals occupies a position focused on scale and process efficiency in foundational phenolic resins, targeting large-volume industrial applications that require consistent material properties and cost-effectiveness. These companies demonstrate distinct strategic approaches within the competitive thermoset market, influencing material specifications and supply dynamics.
| Leading Market Players |
|---|
| BASF |
| Huntsman Corporation |
| Dow Chemicals |
| Hexion Inc. |
| Lanxess |
| Ashland |
| AOC Resins |
| DSM |
| DuPont |
| Others |
Cost & Logistics Intelligence
Vertical integration into upstream petrochemical feedstocks anchors producers' supply position and enhances their pricing power over commodity thermosets. This integration insulates large chemical companies from raw material price volatility.
Pricing Analysis
Direct-to-OEM discounts characterize pricing for high-performance epoxy resins supplied to aerospace clients. The dominant pricing model involves contract-based long-term offtake agreements for specialized formulations. Price differentiation stems from certification level, particularly for aerospace-grade materials, and customization for specific applications. Pricing softness is evident in commodity phenolic resins due to intense competition and feedstock volatility, making automotive OEMs highly price-sensitive for volume components.
Supply Chain Analysis
Petrochemical derivatives supply for synthetic thermosets primarily draws from industrial clusters in China, the United States, and Germany. Bio-based thermoset feedstocks, like lignin, are sourced from agricultural and forestry sectors, creating new supply chains. Single-source vulnerability in specialized precursors for high-performance resins represents a significant supply chain risk. Distribution runs through direct sales channels for large industrial customers and wholesalers for smaller fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermoset market functions as a geographic-arbitrage play, leveraging lower manufacturing costs in China against stringent EU Green Deal sustainability mandates in Europe. This dynamic influences investment and production relocation decisions.
For Market Incumbents:To counter bio-resin performance gaps and sustainability mandates, incumbents should accelerate R&D into recyclable chemistries like vitrimers. Capacity addition in bio-based material production, particularly in regions like the Yangtze River Delta, can mitigate feedstock volatility and regulatory pressure. Investing in sophisticated process efficiency for foundational resins also maintains cost leadership against emerging alternatives.
For New Entrants and Emerging Players:Photocurable thermoset resins for 3D printing offer a technology-first wedge into rapid prototyping and complex part fabrication markets. Targeting specialized aerospace and medical device applications with customized formulations can bypass commodity competition. A go-to-market angle focused on integrated material systems, including processing support, appeals to OEMs seeking certified solutions.
For Investors and Strategic Acquirers:Roll-up economics work for specialized bio-thermoset producers because the market fragments across diverse feedstock sources and emerging application niches. Long-term viability hinges on companies with proprietary bio-based precursor technologies or strong intellectual property in recyclable chemistries. A signal to watch is the increasing number of strategic partnerships between large chemical companies and bio-material startups.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Bio-Thermosets | Scaling biorefinery output addresses sustainability mandates and diversifies feedstock reliance away from petrochemicals. |
| Joint Venture for Recyclable Chemistries | Collaborative R&D accelerates development of vitrimers, extending product lifecycles for aerospace components. |
| Long-term Supply Agreement with OEMs | Securing volume commitments from automotive or aerospace OEMs stabilizes demand for high-performance resins. |
| Technology Licensing for 3D Printing Resins | Expanding market reach for photocurable thermosets into additive manufacturing applications creates new revenue streams. |
| Green Manufacturing Transition | Adopting water-based epoxy systems ensures compliance with EPA VOC standards in regulated US states. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary validation. Primary data derived from discussions with R&D directors, procurement leads at OEMs, plant managers, and distribution channel partners. Secondary sources included customs data, SEC 10-K filings, and industry association reports. Bottom-up market sizing and top-down validation ensured robust triangulation.
Historical market performance across comparable periods anchored the forecast window, establishing baseline growth trajectories. The analytical framework modeled key segmentation dimensions including product type, application, end-user, and bio-content percentage. Compound Annual Growth Rates were derived from multi-factor regression analysis. Electric vehicle production forecasts and aerospace build rates served as critical industry-specific inputs over the projection horizon.
The model holds under current regulatory frameworks and feedstock availability; deviation in global trade policies or significant bio-resin breakthroughs would shift market dynamics. Forecasts reflect assumptions regarding technological advancements. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
Polyetherketone Market
Polymers & Resins
Epoxy Resin Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Virgin Resin Market
Polymers & Resins
Global Thermoset Resin Market
Polymers & Resins
GCC Polyethylene Terephthalate (PET) Market
Polymers & Resins
Global Encapsulation Resins Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
Global Medium Molecular Weight Polyisobutylene Market
Polymers & Resins
Global Chromatography Resin Market
Polymers & Resins
Orthophthalic Resins Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Global Low Density Polyethylene (LDPE) Foams Market
Polymers & Resins
Resorbable Polymers Market
Polymers & Resins
Antiviral Polymers for Packaging Market