
 Asia-Pacific Floating Offshore Wind Power Market | 2026-2036
Asia-Pacific Floating Offshore Wind Power Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Floating Offshore Wind Power Market Outlook
Utility offtakers is bifurcating from independent power producers as the dominant procurement force across Asia-Pacific floating wind developments. Equinor leverages its Hywind platform experience to anchor early-mover positioning in Korean waters. MingYang Smart Energy competes through integrated turbine-foundation system design tailored for typhoon-prone basins. Marubeni Offshore Wind Development sustains project development capabilities across multiple Japanese prefectures.
Asia-Pacific floating offshore wind power encompasses electricity generation systems mounted on buoyant substructures anchored to seabeds exceeding 60 meters depth, where fixed foundations prove technically unfeasible. Semi-submersible platforms dominate current engineering preferences due to superior stability during Asian monsoon conditions and simplified port-based assembly logistics. Spar-buoy designs occupy niche roles in ultra-deep waters off Japan's Pacific coastline where vertical hull economics improve with depth. Tension leg platforms remain pre-commercial but attract R&D investment for their minimal heave response in cyclonic sea states.
METI's offshore wind general maritime area usage rules, South Korea's Ocean Energy Development Promotion Act, and Taiwan's Electricity Act amendments collectively establish site leasing frameworks and grid interconnection standards. These regulatory architectures determine project bankability timelines and localize supply chain requirements through domestic content provisions. Stakeholders must monitor evolving submarine cable corridor designations and port infrastructure upgrade commitments across Japan, South Korea, and Taiwan to align fabrication capacity with construction windows.
Market Dynamics
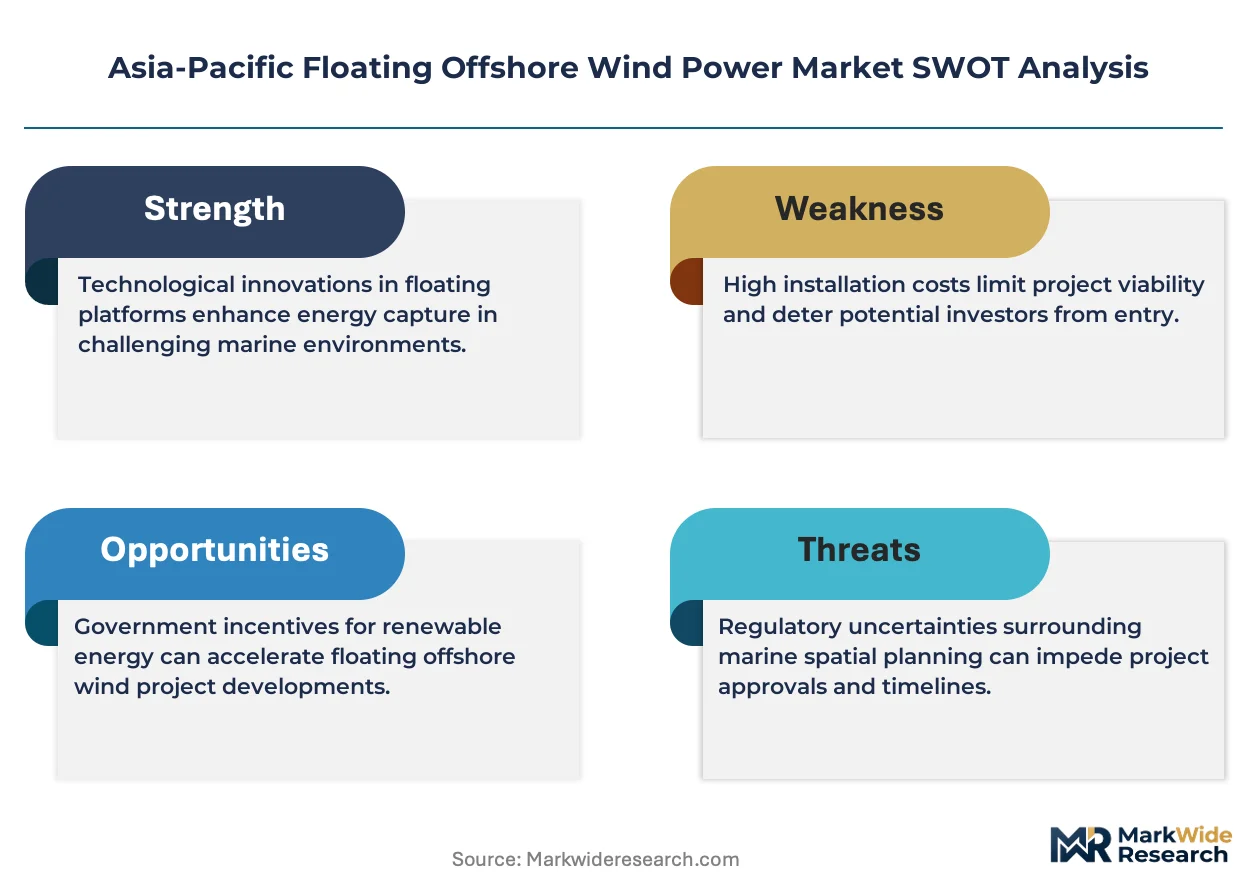
Seabed depth constraints across the Asia-Pacific basin are forcing a wholesale technology pivot from fixed-bottom to floating substructure architectures, with port infrastructure bottlenecks now determining project commissioning schedules more than turbine supply.
Growth Catalysts
- METI's feed-in tariff revisions:Japan's Ministry of Economy, Trade and Industry has recalibrated offshore wind tariffs to improve project IRRs, triggering accelerated environmental impact assessments in the Goto Islands.
- Semi-submersible platform maturation:Port-based assembly logistics for these buoyant foundations now enable year-round construction windows independent of seasonal weather windows that constrain fixed-bottom installation.
- Utility offtaker procurement consolidation:Regional power utilities in South Korea and Taiwan are bypassing merchant power developers to directly contract floating wind capacity through competitive auctions.
Market Restraints
- Dynamic cable cost volatility:High-voltage subsea cable systems connecting floating platforms to seabed junction boxes represent 15-20% of project capex, with copper and cross-linked polyethylene pricing subject to commodity swings.
- Fabrication yard concentration:Heavy-lift assembly capacity for multi-thousand-ton floating hulls clusters in South Korea's Ulsan and Geoje shipbuilding zones, creating single-source risk for Japanese and Taiwanese developers.
- Grid interconnection queue delays:Taiwan's Electricity Act amendments have not resolved transmission system operator backlogs for offshore substation approvals, stretching project timelines.
Strategic Opportunities
- Vietnam's unexplored deepwater zones:The absence of established offshore wind frameworks creates first-mover positioning for developers willing to shape regulatory precedent in waters exceeding 60 meters depth.
- Spar-buoy technology convergence with typhoon-resistant mooring:Synthetic rope mooring systems from deepwater oil and gas applications are transferring to floating wind, enabling hull designs optimized for Japan's Pacific coastline cyclone exposure.
- Integrated turbine-foundation system sales:OEMs capturing both turbine supply and platform engineering contracts can compress interface risk and capture margin pools currently lost to third-party structural engineers.
Industry Challenges
- Floating foundation certification timeline compression:DNV and Bureau Veritas lack sufficient surveyor capacity to process novel platform designs on developer-mandated schedules, forcing construction starts prior to full type certification.
- Marine coordination skill scarcity:Project management expertise in simultaneous turbine load-out, wet-tow operations, and offshore hook-up concentrates among North Sea veterans, with insufficient Asia-Pacific localization.
- Domestic content requirement navigation:South Korea's renewable energy certificate scheme mandates local fabrication percentages that exceed current indigenous supply chain capability, forcing joint ventures with European engineering houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Floating Offshore Wind Power Market |
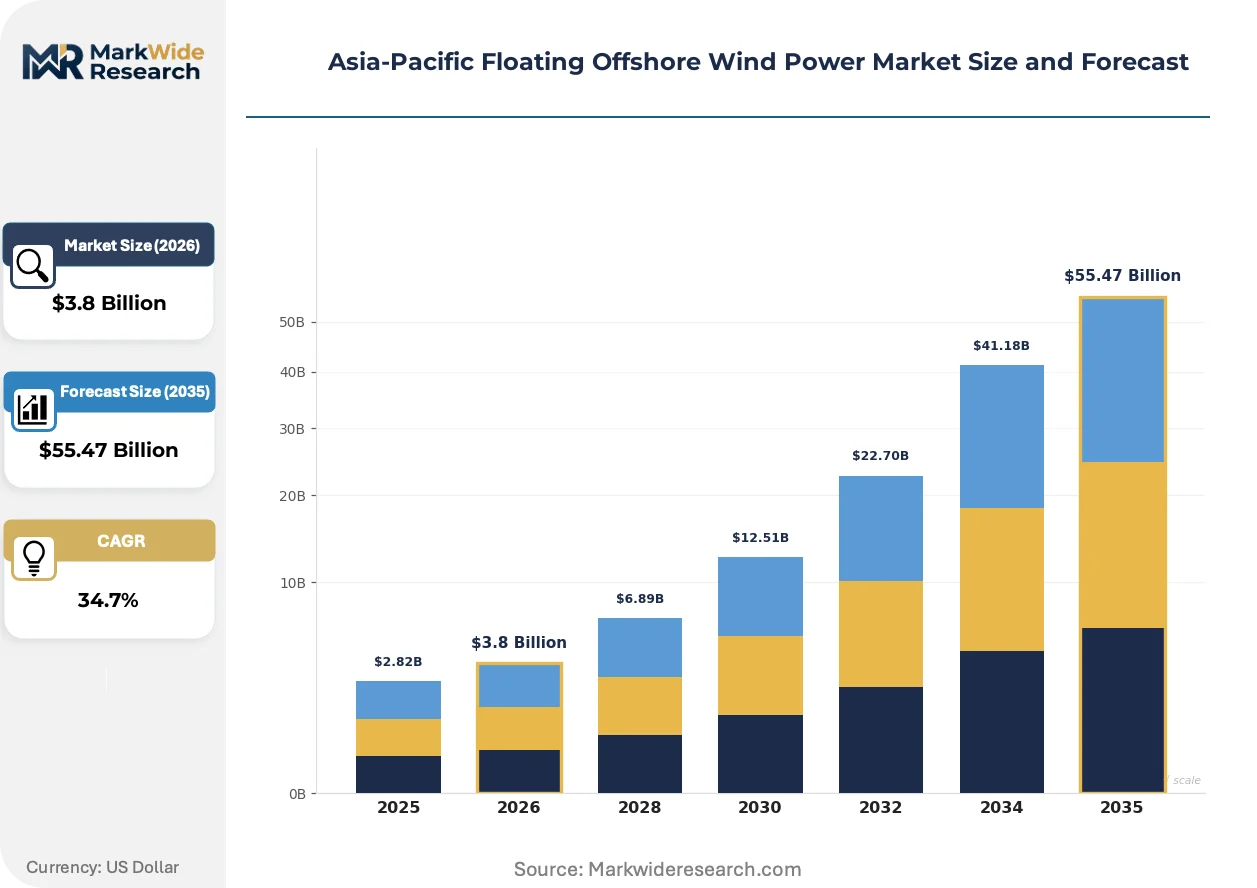
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $55.47 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Semi-Submersible, Spar-Buoy, Tension Leg Platform, Other Installation Type: Fixed, Mobile, Temporary, Permanent End User: Utilities, Independent Power Producers, Government, Commercial Project Size: Small Scale, Medium Scale, Large Scale, Extra Large Scale |
| Companies Covered | Equinor, Tohoku Electric Power, Vestas Wind Systems, Marubeni Offshore Wind Development, CNOOC, Siemens Gamesa Renewable Energy, MingYang Smart Energy, Ørsted, BW Ideol, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Floating Offshore Wind Power Market Strategic Shifts
Modularization of floating platform components is compressing fabrication timelines and enabling distributed manufacturing across multiple port facilities rather than single-yard dependency.
Concrete-steel hybrid floater technology is miniaturizing platform displacement requirements while maintaining stability margins for 15MW+ turbine payloads. Japanese engineering consortia are adopting these reduced-mass designs for Pacific coastline projects where wet-tow distance constraints limit hull draft. The structural consequence is a 30% reduction in required towing vessel capacity, opening contractor bidding to mid-size marine operators previously excluded from floating wind logistics.
South Korea's Ocean Energy Development Promotion Act is mandating centralized offshore wind zoning through competitive bidding rather than site-by-site permitting, compressing development timelines but concentrating risk in fewer large-scale project clusters. The industrial consequence is a shakeout of small-scale independent developers unable to meet bid-bond requirements. Utility-scale IPPs with balance-sheet capacity are consolidating early-stage project pipelines previously held by fragmented local consortia.
Offtake contracting patterns are fragmenting from traditional 20-year power purchase agreements toward merchant-exposed structures with shorter tenors and floor-price mechanisms. Japanese regional utilities are resisting long-term fixed-price commitments given grid balancing cost uncertainty, forcing developers to absorb wholesale price volatility through contracted floor arrangements. This behavioral shift is most visible in Tokyo Electric Power's procurement approach for Fukushima offshore zones, where 10-year contracts with price reopeners now dominate negotiation frameworks.
Asia-Pacific Floating Offshore Wind Power Market Segmentation
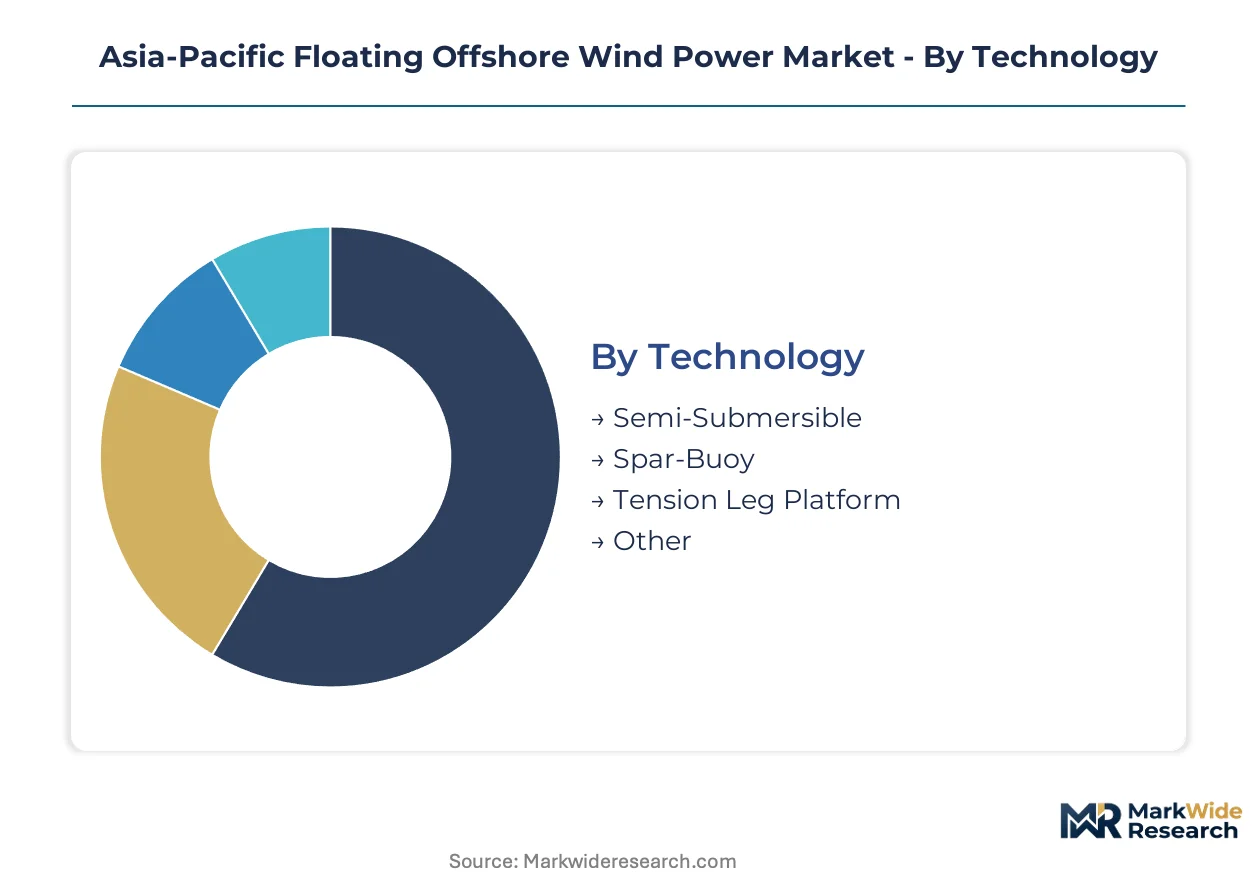
Technology selection determines regulatory pathway complexity across Asia-Pacific floating wind developments. Installation methodology shapes port infrastructure requirements and domestic content compliance. End-user procurement structures influence project finance availability and offtake contract tenors.
Technology:
METI's certification timelines and South Korea's Ocean Energy Development Promotion Act create divergent approval burdens across platform architectures.
- Semi-Submersible:Tri-column or square hull configurations with distributed buoyancy enable wet-tow operations from existing Korean shipyards. Procurement concentrates in South Korea's Ulsan zone where fabrication yards already supply oil and gas semi-submersibles, though DNV surveyor bottlenecks stretch certification timelines.
- Spar-Buoy:Single cylindrical hull with deep draft ballast section dominates Japanese Pacific coastline projects. METI's environmental impact assessment requirements for deepwater mooring systems favor this design's reduced footprint, with synthetic rope suppliers from offshore oil transferring expertise.
- Tension Leg Platform:Vertical mooring tethers minimize heave response for cyclonic conditions. South Korea's renewable energy certificate scheme domestic content thresholds complicate procurement of European tendon connector technology.
- Other:Barge-based and multi-turbine platform concepts remain pre-commercial, attracting R&D investment from Japanese engineering consortia seeking Pacific coastline differentiation.
Established volume favors Semi-Submersible; emerging adoption favors Spar-Buoy.
Installation Type:
Cost tier stratification separates capital-intensive permanent infrastructure from flexible deployment models suited to regulatory uncertainty.
- Fixed:Permanent mooring systems with pre-laid anchors and chain segments dominate utility-scale developments. Taiwan's Electricity Act amendments have not resolved transmission queue delays, forcing developers toward fixed installations with longer asset lives to amortize interconnection risk.
- Mobile:Disconnectable mooring enables seasonal relocation or maintenance tow-back to port. Japanese fishing cooperative negotiations in the Goto Islands favor mobile configurations that demonstrate reversible seabed occupation.
- Temporary:Short-duration deployment for demonstration or grid testing phases. METI's feed-in tariff revision windows create demand for temporary installations that secure tariff qualification before permanent commitment.
- Permanent:Integrated foundation-turbine systems designed for 25-year operational life without major component retrieval. South Korean utility offtakers require permanent installations to meet renewable portfolio standard compliance deadlines.
Capital deployment favors Permanent; risk mitigation favors Mobile.
End User:
Customer type determines procurement contract structures and grid interconnection priority.
- Utilities:Regional power companies in Japan, South Korea, and Taiwan directly contract floating wind capacity through competitive auctions. Tokyo Electric Power's 10-year floor-price contracts for Fukushima zones exemplify utility resistance to long-term fixed commitments.
- Independent Power Producers:Merchant developers face consolidation pressure as South Korea's centralized zoning concentrates projects in fewer large-scale clusters. Balance-sheet capacity requirements now exclude fragmented local consortia.
- Government:Public-sector demonstration projects support technology validation and supply chain localization. METI's Goto Islands environmental assessments anchor early-stage demand.
- Commercial:Corporate power purchase agreements from technology and manufacturing sectors seek renewable energy certificates. Taiwan's industrial electricity consumers represent emerging procurement volume.
Contract security favors Utilities; margin capture favors Independent Power Producers.
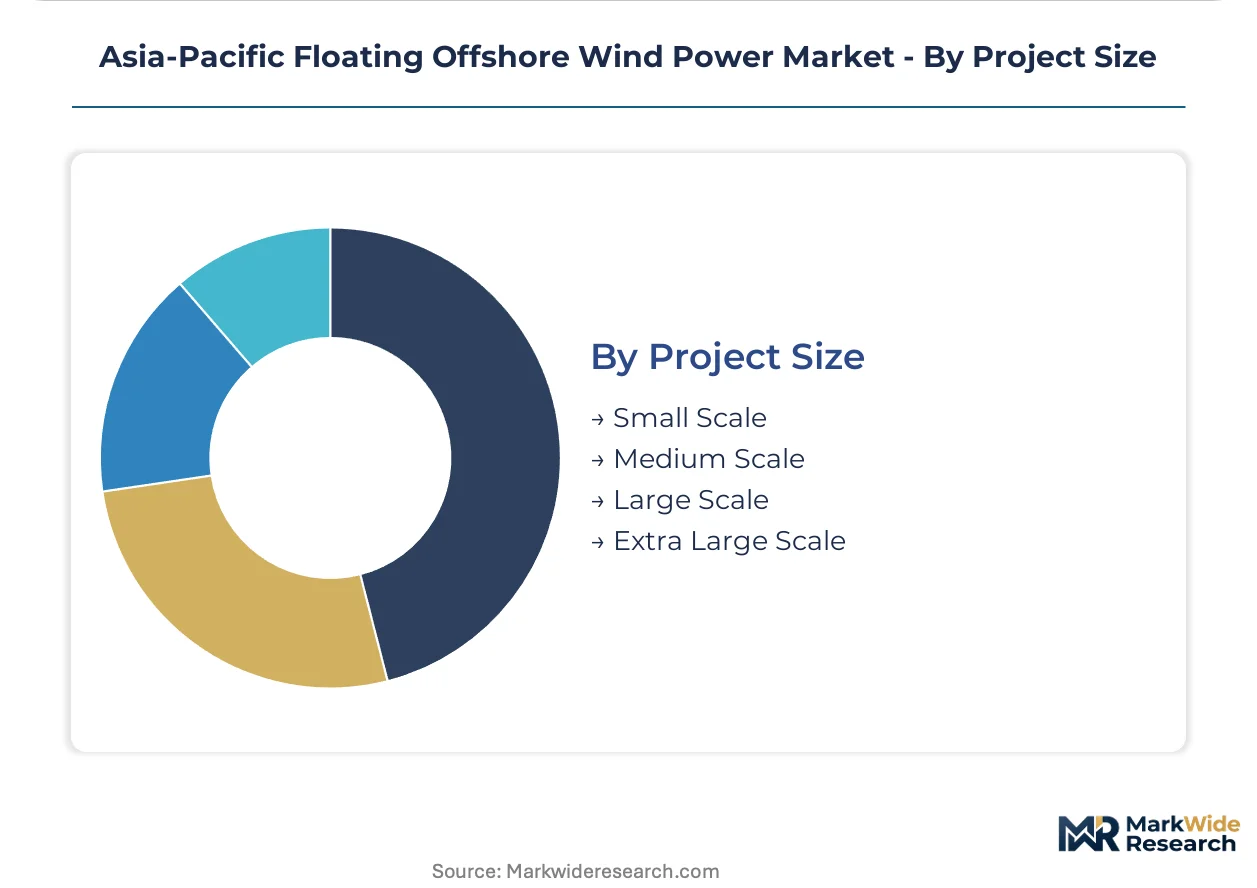
Project Size:
Scale thresholds determine financing structure and supply chain contracting strategy.
- Large Scale:500MW+ developments anchor South Korea's Ulsan offshore zone competitive bidding rounds. Centralized zoning under the Ocean Energy Development Promotion Act concentrates risk in these clusters.
- Extra Large Scale:Multi-gigawatt regional hubs require dedicated transmission infrastructure and international consortia. Japanese Pacific coastline depth gradients may enable these configurations with sufficient grid investment.
- Medium Scale:100-500MW projects suit Taiwan's current grid interconnection capacity and domestic fabrication constraints. Electricity Act amendment implementation lags limit larger commitments.
- Small Scale:Sub-100MW demonstration and pilot projects dominate early Japanese developments. METI's feed-in tariff revisions improve IRRs sufficiently to attract developer capital at this scale.
Bankability concentration favors Large Scale; pipeline depth favors Small Scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heavy-lift assembly capacity clusters in South Korea's Ulsan and Geoje shipbuilding zones, creating single-source risk for Japanese and Taiwanese developers. Port infrastructure bottlenecks now determine project commissioning schedules more than turbine supply. Grid interconnection queue delays stretch timelines across the region.
Japan
Seabed depths exceeding 60 meters preclude fixed-bottom installations across the Pacific coastline. METI's feed-in tariff revisions have recalibrated offshore wind tariffs to improve project IRRs. Environmental impact assessments concentrate in the Goto Islands where early-stage demand anchors utility-scale developments.
South Korea
The Ocean Energy Development Promotion Act mandates centralized offshore wind zoning through competitive bidding rather than site-by-site permitting. The renewable energy certificate scheme mandates local fabrication percentages that exceed current indigenous supply chain capability. Ulsan offshore zones host 500MW+ competitive bidding rounds that concentrate risk in large-scale project clusters.
Taiwan
Electricity Act amendments have established site leasing frameworks without resolving transmission system operator backlogs for offshore substation approvals. Grid interconnection queue delays stretch project timelines despite regulatory progress. Medium-scale 100-500MW projects suit current grid interconnection capacity and domestic fabrication constraints.
Vietnam
The absence of established offshore wind frameworks creates first-mover positioning for developers willing to shape regulatory precedent. Waters exceeding 60 meters depth remain unexplored for commercial floating wind deployment. Deepwater zones along the southern coastline attract preliminary site assessments from regional utilities seeking diversification.
Asia-Pacific Floating Offshore Wind Power Market Competitive Environment
Concentration sits with integrated energy conglomerates and specialized offshore engineering houses that control platform design intellectual property. The competitive structure splits between European technology licensors with North Sea deployment experience and Asia-Pacific utilities building in-house development capabilities. Two strategic archetypes dominate: foundation engineering specialists and integrated turbine-foundation system providers. Competitive moves center on joint ventures to satisfy domestic content requirements and technology licensing agreements to compress certification timelines.
Among European technology anchors, Equinor and Ørsted occupy positions exemplifying floating platform deployment experience transferred from North Sea oil and gas applications. Within the Asia-Pacific utility tier, Marubeni Offshore Wind Development represents integrated project development capabilities across multiple Japanese prefectures. MingYang Smart Energy sits within the OEM archetype pursuing integrated turbine-foundation system design tailored for typhoon-prone basins.
| Leading Market Players |
|---|
| Equinor |
| Tohoku Electric Power |
| Vestas Wind Systems |
| Marubeni Offshore Wind Development |
| CNOOC |
| Siemens Gamesa Renewable Energy |
| MingYang Smart Energy |
| Ørsted |
| BW Ideol |
| Others |
Value Chain & Pricing Dynamics
Concrete-steel hybrid floater technology replacing conventional steel-only hulls is redrawing fabrication geography toward Japanese engineering consortia while compressing platform displacement economics and resetting cost benchmarks across Pacific coastline developments.
Pricing Analysis
METI's feed-in tariff revisions dictate the pricing tier structure for floating wind developments across Japanese waters. Three-tier pricing structure across integrated turbine-foundation packages, standalone platform engineering, and port-based assembly services separates premium DNV-certified designs from standard Bureau Veritas tiers and pre-certified economy alternatives. Cost compression in economy-tier hull fabrication is intensifying because South Korean shipyards are absorbing margin pressure to secure utility-scale IPP contracts. Merchant developers exhibit highest price sensitivity due to merchant-exposed offtake structures, while regional utilities with renewable portfolio standard mandates accept premium pricing for certified permanent installations.
Supply Chain Analysis
Port congestion at Ulsan and Geoje shipbuilding zones is extending wet-tow vessel scheduling windows and inflating marine logistics costs for Japanese and Taiwanese developers. Heavy-lift assembly capacity concentrates in South Korea, Japan, and Taiwan, with fabrication yards drawing from Chinese steel plate, European synthetic rope mooring systems, and Korean heavy-lift vessel fleets. Single-source vulnerability sits with concentrated semi-submersible hull production in Ulsan, where oil and gas fabrication backlogs compete for yard slots. Distribution runs through utility-led competitive auctions in South Korea, direct procurement by Japanese regional utilities, and IPP merchant structures in Taiwan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific floating offshore wind is recovering from certification bottlenecks and port infrastructure constraints as METI tariff revisions and South Korean competitive bidding cycles restore project bankability.
For Market Incumbents: Compound platform design intellectual property advantages through joint ventures with Korean shipbuilders to satisfy domestic content requirements under the renewable energy certificate scheme. Deepen captive supply of synthetic rope mooring systems to offset European tendon connector procurement risks. Secure long-term fabrication slots at Geoje yards before utility-scale IPPs consolidate remaining capacity. For New Entrants and Emerging Players: Lead with Vietnam's unexplored deepwater zones where regulatory precedent remains unformed and first-mover positioning in waters exceeding 60 meters depth offers negotiation leverage. Target mobile mooring configurations for Japanese fishing cooperative negotiations in the Goto Islands. Pursue technology licensing agreements with DNV to compress certification timelines relative to de novo type approval pathways. For Investors and Strategic Acquirers: Capital is best deployed toward integrated turbine-foundation system providers with typhoon-resistant design portfolios and established utility relationships across Japan and South Korea. Long-term viability hinges on capturing margin pools currently fragmented between turbine OEMs and third-party structural engineers. Watch for METI environmental impact assessment acceleration as the inflection signal for construction-ready pipeline conversion.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Turbine-Foundation System Development | MingYang Smart Energy captures margin pools lost to third-party structural engineers through combined design liability. |
| Synthetic Rope Mooring Technology Transfer | Deepwater oil and gas suppliers enable spar-buoy hull optimization for Japan's Pacific coastline cyclone exposure. |
| Joint Venture Fabrication Agreements | European engineering houses satisfy South Korea's domestic content thresholds exceeding indigenous supply capability. |
| Mobile Mooring Configuration Deployment | Disconnectable systems secure Japanese fishing cooperative approvals through reversible seabed occupation demonstrations. |
| Concrete-Steel Hybrid Floater Miniaturization | Reduced-mass designs open contractor bidding to mid-size marine operators previously excluded from floating wind logistics. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across Japan, South Korea, and Taiwan. Secondary validation drew from METI regulatory filings, South Korea's Ocean Energy Development Promotion Act implementation documents, Taiwan Electricity Act amendment records, and project development databases. Bottom-up capacity aggregation and top-down policy target reconciliation were triangulated to establish baseline market sizing.
Across the analysis window, the analytical framework modeled segmentation dimensions including platform technology type, installation methodology, end-user procurement structure, and project scale tier. CAGRs were derived from project pipeline aggregation and commissioning schedule probability weighting. Forecast inputs incorporated seabed depth constraints, port infrastructure upgrade commitments, and grid interconnection queue progression.
Forecasts assume regulatory continuity in METI's feed-in tariff regime, South Korea's renewable energy certificate scheme, and Taiwan's Electricity Act framework; material policy shifts would require re-modeling of project IRR thresholds and domestic content compliance pathways. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Kuwait Oil and Gas Downstream Market
Offshore Oil and Gas
Southeast Asia Offshore Seismic Survey Market
Offshore Oil and Gas
Offshore Rental Equipment Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Upstream Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Upstream Market
Offshore Oil and Gas
Deepwater and Ultra-Deepwater Drilling Market
Offshore Oil and Gas
Gabon Oil and Gas Downstream Market
Offshore Oil and Gas
United Kingdom Oil and Gas Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
Middle East and Africa Offshore Energy Market
Offshore Oil and Gas
Oman Oil and Gas Market
Offshore Oil and Gas
Global Floating LNG Power Vessel Market
Offshore Oil and Gas
Offshore Equipment Market
Offshore Oil and Gas
Offshore Oil and Gas Communications Market