
 Offshore Equipment Market | 2026-2036
Offshore Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Equipment Market Analytics
Modular platform configurations is expanding as buyers favor integrated packages combining ROVs, umbilicals, and control systems over standalone procurement. Liebherr leverages its crane technology leadership to anchor deepwater lifting contracts across Atlantic basins. Huisman Equipment specializes in custom-built offshore cranes and pipelay systems, differentiating on engineering depth for ultra-deepwater projects. National Oilwell Varco sustains its position through aftermarket service networks that control replacement-part revenue streams.
Offshore equipment encompasses submersible vessels, remotely operated vehicles, umbilical cables, mooring systems, and associated control technologies engineered to operate at depths exceeding 3,000 meters under extreme pressure, salinity, and temperature conditions. Hydraulic drive systems retain dominant installed-base share due to proven torque density in subsea construction, though electrical actuation is displacing legacy architectures in inspection-class ROVs where precision and reduced maintenance intervals matter. Deepwater drilling commands the largest absolute spend among applications, while inspection and maintenance represents the fastest-expanding segment as aging North Sea and Gulf of Mexico infrastructure requires structural integrity monitoring.
The US Bureau of Safety and Environmental Enforcement mandates blowout preventer testing protocols that shape capital equipment specifications for Gulf of Mexico operators, while Norway's Petroleum Safety Authority enforces facility integrity standards that accelerate demand for automated inspection technologies. Brazil's national petroleum regulator imposes local-content requirements that condition market access for foreign equipment suppliers bidding on pre-salt development contracts. Stakeholders must weigh electrification roadmaps against the residual service life of hydraulic fleets as regulatory thresholds tighten across multiple jurisdictions simultaneously.
Market Dynamics
Electrification mandates from the EU's F-Gas Regulation are forcing simultaneous fleet turnover across multiple offshore basins, compressing the transition timeline for hydraulic equipment replacement and reshaping capital allocation priorities for drilling contractors and vessel operators.
Growth Catalysts
- Pre-salt field development:Brazil's national petroleum regulator imposes local-content requirements that sustain equipment procurement volumes for subsea production systems and floating platforms.
- EU F-Gas Regulation:Tightening emissions standards for offshore machinery accelerate manufacturer investment in electrified drive systems and low-GWP refrigerant architectures.
- Aging infrastructure inspection:North Sea and Gulf of Mexico asset integrity mandates from the US Bureau of Safety and Environmental Enforcement and Norway's Petroleum Safety Authority expand demand for automated ROV deployment.
Market Restraints
- Steel alloy input volatility:High-strength chromium-molybdenum steel prices fluctuate with nickel market swings, compressing fabrication margins for subsea riser and mooring component suppliers.
- Deepwater crane supply concentration:European and Asian heavy-lift specialists control critical capacity for ultra-deepwater hook loads above 2,000 tonnes, limiting buyer negotiation leverage.
- Hydraulic residual life mismatch:Decades of proven subsea torque density create technical drag against electrical actuation adoption in construction-class equipment.
Strategic Opportunities
- Decommissioning service expansion:North Sea platform removal mandates create white space for integrated cutting and lifting package providers serving UK and Norwegian contractors.
- Digital twin convergence:Real-time sensor fusion with physics-based modeling enables predictive maintenance contracts for subsea umbilical and control system operators.
- West Africa marginal field development:Ghana and Senegal offshore licensing rounds attract modular production system vendors seeking lower-capex entry points.
Industry Challenges
- Subsea electrical engineer scarcity:Power electronics and high-voltage connector design expertise concentrates within a handful of specialized suppliers, constraining in-house electrification program staffing.
- Blowout preventer certification timelines:US Bureau of Safety and Environmental Enforcement testing protocols extend equipment qualification cycles, delaying rig deployment schedules.
- Legacy hydraulic-electric integration complexity:Hybrid architectures for construction vessels require simultaneous mastery of both drive systems, fragmenting maintenance competency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Equipment Market |
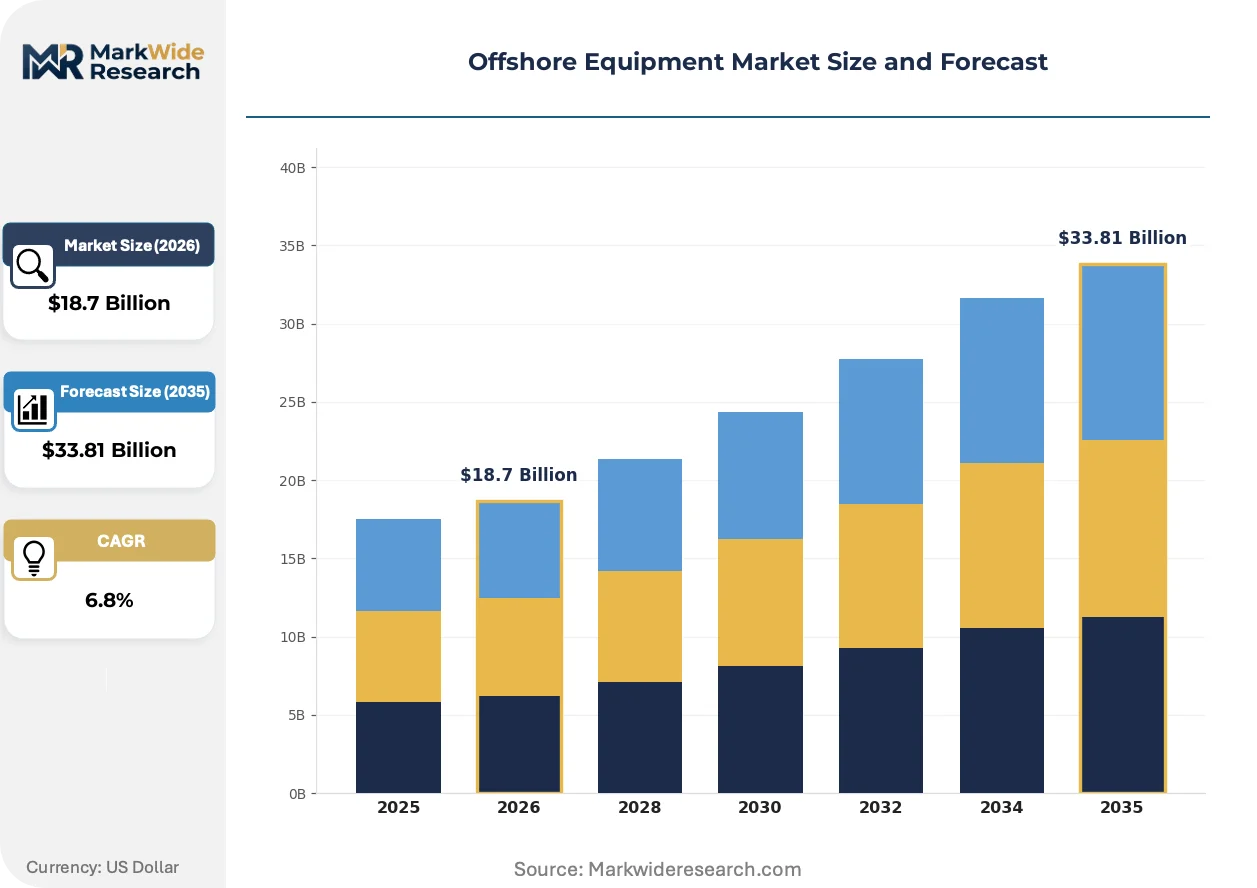
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersibles, ROVs, Umbilicals, Mooring Systems Technology: Hydraulic, Electrical, Mechanical, Control Systems Application: Deepwater Drilling, Inspection, Maintenance, Construction End User: Oil & Gas Companies, Marine Contractors, Government Agencies, Others |
| Companies Covered | Cargotec, Palfinger, Liebherr, Zoomlion, TEREX Corporation, National Oilwell Varco, Konecranes, Manitowoc, Huisman Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Equipment Market Evolving Landscape
Subsea power distribution architectures and condition-based monitoring systems are compressing operational models for offshore asset management. Equipment vendors and operators face simultaneous pressure to electrify fleets while extending legacy hydraulic service revenue.
Subsea variable speed drives are decentralizing power conversion from surface vessels to seabed installations. Brazilian pre-salt operators deploy these units at 2,500-meter depths to reduce umbilical copper mass and surface deck footprint. The technology is decentralizing vessel specification requirements, enabling smaller dynamically positioned construction ships to service deeper fields.
The EU's F-Gas Regulation bans refrigerants with global warming potential above 750 in new offshore machinery from 2027. Equipment manufacturers accelerate R-513A and CO2 cascade system qualification for HVAC and hyperbaric chambers. Norwegian North Sea platforms face the most acute retrofit pressure given their 1980s-vintage installed base and stringent Petroleum Safety Authority enforcement timelines.
Integrated service contracts now bundle ROV availability, spare parts logistics, and structural inspection scheduling under single-vendor accountability. Brazilian operators lead this consolidation, demanding outcome-guaranteed packages from equipment suppliers rather than discrete capital purchases. The shift compresses procurement cycle complexity but transfers operational risk to vendors with limited control over weather downtime.
Offshore Equipment Market Segmentation
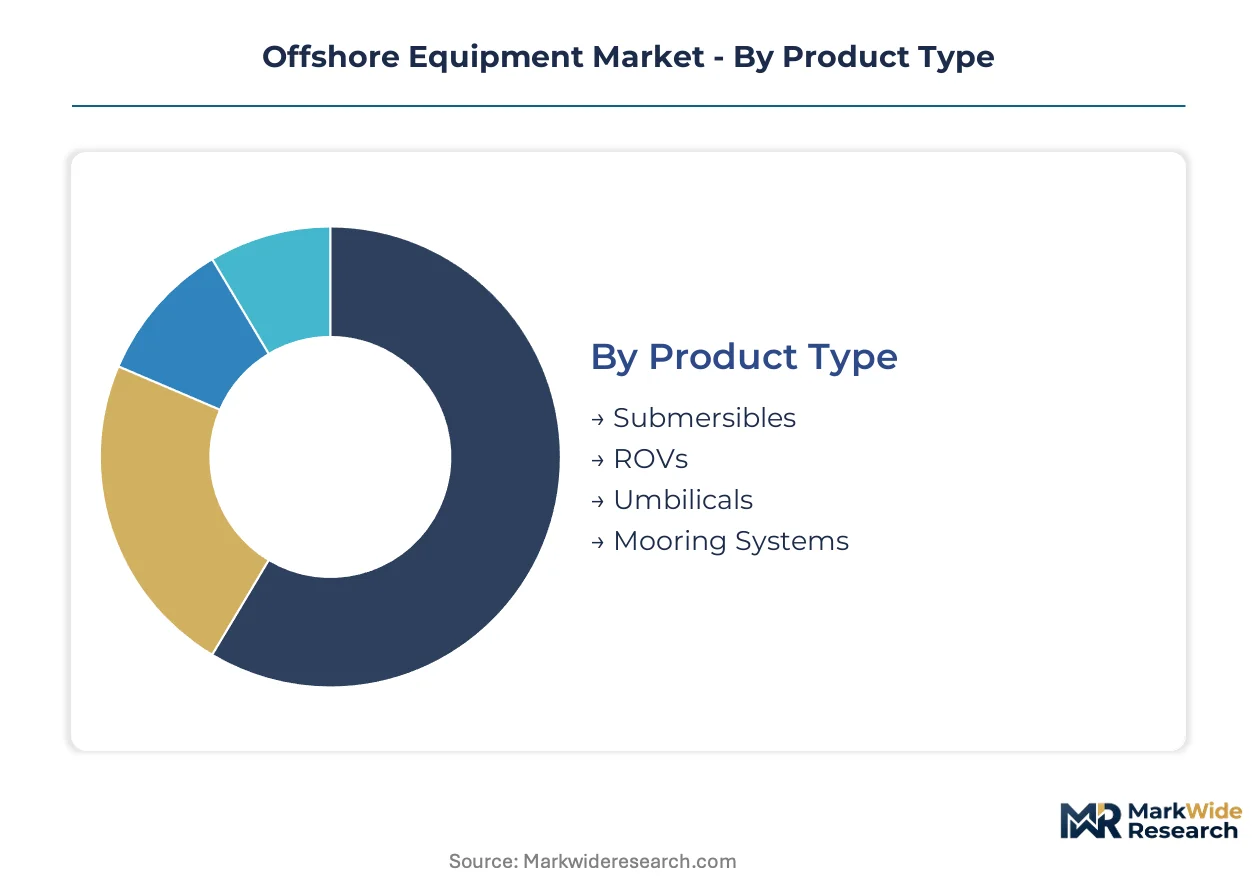
Offshore equipment procurement patterns diverge sharply between capital-intensive subsea production systems and consumable inspection technologies. Understanding these segment boundaries clarifies where electrification investments concentrate versus where hydraulic legacy architectures retain pricing power.
Product Type:
Volume concentrates in standardized umbilical and mooring hardware, while premium engineering margins attach to integrated submersible platforms and ROV systems.
- Submersibles:Manned and unmanned underwater vessels engineered for 3,000-meter pressure ratings with titanium alloy hulls and syntactic foam buoyancy modules. Brazil's pre-salt operators drive procurement for intervention-class submersibles capable of wellhead manipulation at 2,500-meter depths where surface vessel access is weather-constrained.
- ROVs:Tethered robotic systems spanning observation-class mini-ROVs to work-class units with 200+ horsepower hydraulic manipulators. North Sea asset integrity mandates from Norway's Petroleum Safety Authority accelerate demand for automated inspection-class electrical ROVs that reduce vessel day rates through smaller launch-and-recovery systems.
- Umbilicals:Composite tubes bundling hydraulic lines, electrical conductors, and fiber optic cables for subsea control signal transmission.
- Mooring Systems:Anchor chains, polyester ropes, and suction pile foundations securing floating production platforms against cyclonic loading.
Today's leader: ROVs. Tomorrow's challenger: Submersibles.
Technology:
Application severity determines technology selection, with construction-class equipment favoring hydraulic torque density and inspection tasks migrating toward electrical precision.
- Hydraulic:Pressurized fluid drive systems delivering 400+ bar working pressure for subsea torque tools and heavy-lift crane winches. Decades of Gulf of Mexico deepwater construction history validate hydraulic architectures for blowout preventer handling and riser installation where electrical alternatives lack proven load capacity.
- Electrical:Permanent magnet motors and silicon carbide inverters enabling precise position control with 40% maintenance interval extension versus hydraulic equivalents. EU F-Gas Regulation refrigerant bans accelerate electrical HVAC and hyperbaric chamber retrofits on Norwegian North Sea platforms with 1980s-vintage installed base.
- Mechanical:Direct-drive winches, rack-and-pinion jacking systems, and passive heave compensation without power conversion losses.
- Control Systems:Subsea electronics pods processing sensor feedback for dynamic positioning and blowout preventer emergency disconnect sequences.
Hydraulic retains construction-class dominance. Electrical gains fastest in inspection and maintenance substitution cycles.
Application:
Capital deployment intensity separates greenfield drilling from brownfield integrity management, with divergent procurement rhythms and vendor qualification requirements.
- Deepwater Drilling:BOP stacks, riser systems, and subsea wellhead connectors for frontier exploration below 1,500 meters. Brazil's national petroleum regulator local-content requirements condition foreign supplier access to pre-salt development contracts, privileging equipment packages with domestic fabrication components.
- Inspection:Structural integrity assessment of aging jacket platforms and subsea pipelines using ROV-mounted ultrasonic thickness gauges and cathodic potential sensors. US Bureau of Safety and Environmental Enforcement facility assessment mandates expand automated deployment demand for Gulf of Mexico infrastructure exceeding 30-year design life.
- Maintenance:Subsea valve replacement, anode retrofit, and umbilical repair interventions requiring saturation diving support or atmospheric diving suits.
- Construction:Pipelay, cable lay, and platform installation campaigns executed by dynamically positioned vessels with heavy-lift crane capacity.
Deepwater drilling commands absolute capital spend. Inspection climbs fastest on regulatory compliance timelines.
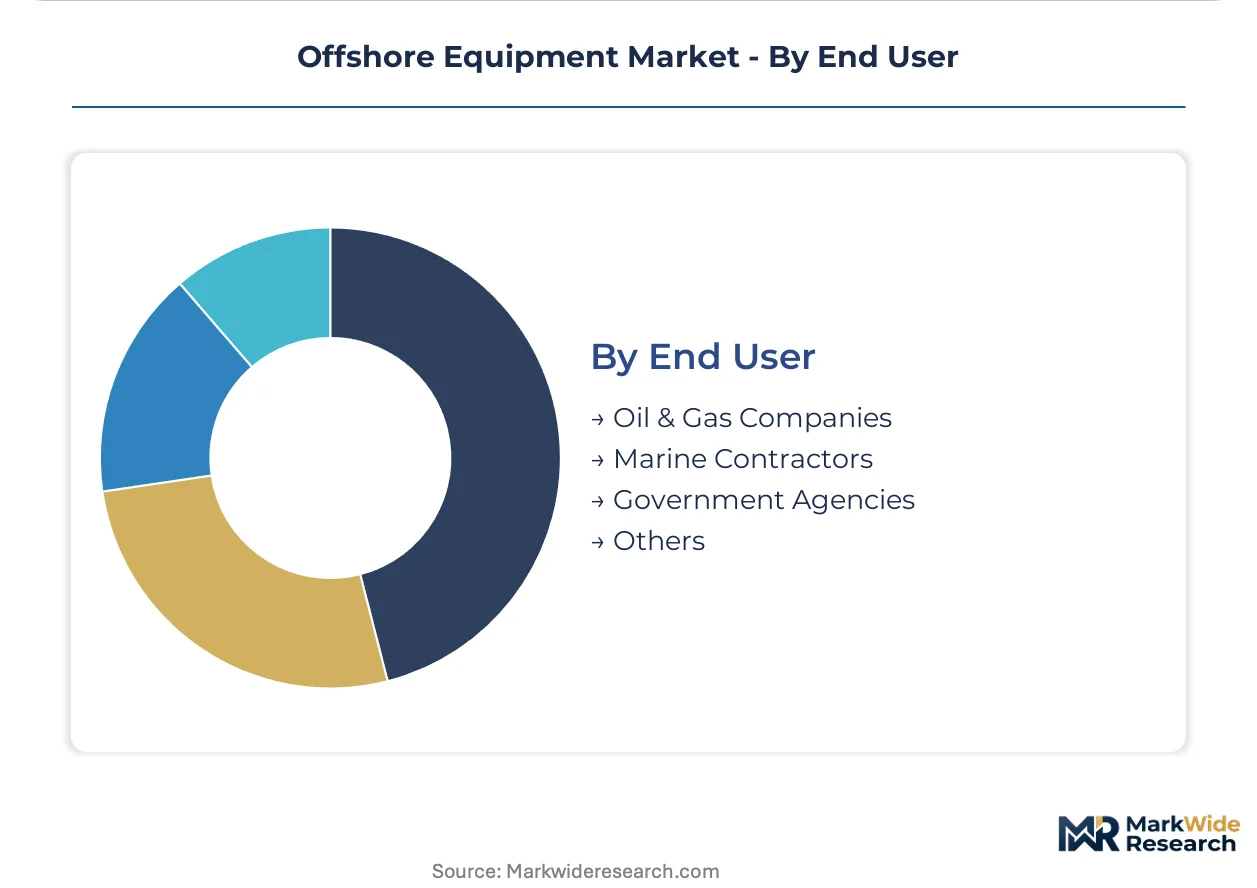
End User:
Risk allocation patterns distinguish integrated oil company procurement from contractor rental models, with divergent preferences for capital purchase versus operational expenditure structures.
- Oil & Gas Companies:Supermajors and national oil companies specifying equipment for operated fields with 20+ year production horizons. Petrobras pre-salt development programs sustain long-term subsea production system procurement volumes with local-content weighted supplier selection criteria.
- Marine Contractors:Drilling and construction vessel operators acquiring ROV spreads, cranes, and pipelay systems for project-based deployment. Integrated service contract trends in Brazil transfer operational risk to contractors through outcome-guaranteed availability packages rather than discrete equipment sales.
- Government Agencies:Regulatory bodies and research institutions funding seabed mapping and environmental monitoring equipment.
- Others:Offshore wind developers adapting oil and gas subsea cable and foundation installation technologies for renewable energy transmission infrastructure.
Oil & Gas Companies anchor equipment specification authority. Marine Contractors expand fastest through integrated service model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore equipment manufacturing traces its commercial roots to North Sea oil development in the 1970s, when Norwegian and UK fabrication yards pioneered subsea production systems for harsh-environment extraction. This engineering heritage now distributes across Atlantic, Pacific, and pre-salt basins where water depth and regulatory complexity determine procurement patterns.
Norway
Stavanger and Bergen host Europe's densest cluster of subsea engineering contractors serving North Sea decommissioning and electrification retrofits. The Petroleum Safety Authority enforces facility integrity standards that accelerate automated inspection technology deployment. Aker Solutions and Equinor's supplier networks concentrate technical expertise for subsea power distribution and variable speed drive integration at depths exceeding 2,000 meters.
Brazil
Pre-salt field development in the Santos and Campos basins sustains the world's most active floating production platform procurement cycle. The national petroleum regulator imposes local-content requirements that condition foreign equipment access, privileging suppliers with domestic fabrication partnerships. Rio de Janeiro's Porto do Açu and Niterói industrial zones anchor subsea production system assembly for Petrobras-operated fields.
United States
Gulf of Mexico deepwater drilling contractors maintain the largest installed base of hydraulic blowout preventer systems subject to Bureau of Safety and Environmental Enforcement testing protocols. Houston's Energy Corridor clusters engineering headquarters for drilling contractors and subsea service companies. Regulatory mandates for structural integrity assessment of aging infrastructure expand automated ROV deployment demand for platforms exceeding 30-year design life.
China
Yantai and Qingdao shipyards scale production of offshore construction vessels and heavy-lift cranes for domestic and export markets. MIIT industrial policy prioritizes subsea equipment localization to reduce import dependence for deepwater oil and gas development. The Bohai Bay and South China Sea shallow-water fields provide proving grounds for indigenous subsea production system qualification.
United Kingdom
Aberdeen's subsea engineering cluster pivots from North Sea greenfield development toward decommissioning and offshore wind foundation installation. The North Sea Transition Authority's platform removal mandates create procurement volume for integrated cutting and lifting packages. Scottish fabrication yards at Nigg and Arnish repurpose oil and gas capabilities for floating offshore wind turbine foundation construction.
Offshore Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across engineering depth and aftermarket service integration. The market structures around three tiers: heavy-lift crane specialists commanding ultra-deepwater hook loads above 2,000 tonnes; integrated subsea production system vendors bundling ROV spreads with umbilical and control packages; and regional fabrication contractors competing on local-content compliance and delivery speed. Consolidation pressure concentrates in the middle tier as Brazilian and Norwegian operators demand single-vendor accountability for outcome-guaranteed availability contracts. Strategic moves emphasize backward integration into high-strength steel alloy supply and technology licensing partnerships for electrical actuation architectures.
Within the integrated subsea tier, National Oilwell Varco anchors aftermarket service networks that control replacement-part revenue streams, while Liebherr occupies a position exemplifying crane technology leadership for Atlantic basin deepwater lifting contracts. Huisman Equipment represents the custom-engineering archetype, specializing in project-specific offshore cranes and pipelay systems where ultra-deepwater specifications demand non-standard configurations.
| Leading Market Players |
|---|
| Cargotec |
| Palfinger |
| Liebherr |
| Zoomlion |
| TEREX Corporation |
| National Oilwell Varco |
| Konecranes |
| Manitowoc |
| Huisman Equipment |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation refrigerant bans are forcing Norwegian and UK operators to accelerate electrification retrofits, compelling suppliers to reconfigure production lines for electrical actuation systems and compressing margins on legacy hydraulic equipment.
Pricing Analysis
Project-based contracting with outcome-guaranteed availability clauses dominates Brazilian pre-salt procurement, transferring operational risk to vendors. Price differentiation rests on certification tier for subsea pressure ratings and local-content compliance scores. Cost compression in inspection-class ROVs is intensifying as electrical alternatives achieve parity with hydraulic maintenance intervals. Marine contractors exhibit highest price sensitivity due to project-based utilization uncertainty, while national oil companies prioritize technical specification adherence over unit economics.
Supply Chain Analysis
Specialized welding and subsea electrical engineering talent pools in Norway, Scotland, and Singapore constrain capacity expansion for ultra-deepwater fabrication. High-strength chromium-molybdenum steel draws from nickel market dynamics, while titanium alloy hull sourcing centers on Japanese and Russian feedstock. Single-source vulnerability concentrates in European heavy-lift crane specialists controlling 2,000-tonne hook capacity. Distribution runs through integrated service contracts bundling equipment, spares logistics, and maintenance scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as Brazilian pre-salt operators shift procurement toward integrated packages demanding single-vendor accountability for subsea production system performance.
For Market Incumbents: Anticipate electrical actuation substitution accelerating beyond inspection-class ROVs into construction equipment, threatening hydraulic service revenue streams. Prioritize backward integration into high-voltage connector and silicon carbide inverter supply chains. Secure Petrobras-qualified fabrication partnerships in Rio de Janeiro industrial zones to defend local-content weighted contract access. For New Entrants and Emerging Players: West African marginal field developers in Ghana and Senegal present underserved buyer archetypes seeking modular production systems with lower capital intensity entry points. Target integrated cutting and lifting packages for North Sea decommissioning mandates where incumbent capacity is committed to Brazilian pre-salt cycles. Pursue technology licensing partnerships with Norwegian subsea power distribution specialists to shortcut qualification timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with electrical actuation component suppliers possessing proprietary high-voltage seabed connector designs. Five-to-ten year viability favors vendors with established aftermarket service networks controlling replacement-part revenue rather than pure equipment manufacturers. Monitor EU F-Gas Regulation enforcement intensity across Norwegian North Sea platforms as inflection indicator for electrification retrofit cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Captures margin from silicon carbide inverter and high-voltage connector supply chains serving electrified subsea systems. |
| Local-Content Fabrication Partnership | Secures Petrobras contract eligibility under Brazil's national petroleum regulator domestic assembly requirements. |
| Integrated Service Contract Expansion | Transfers operational risk from Brazilian operators through outcome-guaranteed availability packages bundling ROV spreads and maintenance. |
| Decommissioning Capability Buildout | Positions for North Sea platform removal mandates creating procurement volume for cutting and lifting specialists. |
| Digital Twin Platform Development | Enables predictive maintenance contracts for subsea umbilical operators using real-time sensor fusion with physics-based modeling. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with subsea engineering directors, drilling contractor procurement leads, Petrobras contract managers, and Norwegian Petroleum Safety Authority technical inspectors with secondary validation. Regulatory filings from the US Bureau of Safety and Environmental Enforcement, EU F-Gas Regulation implementation guidance, and Brazilian national petroleum regulator local-content scorecards anchored policy trajectory assessment. Bottom-up equipment procurement databases and top-down energy capex forecasts provided triangulation anchors.
Segment-weighting approaches applied differential growth assumptions across hydraulic and electrical technology trajectories, construction versus inspection application intensity, and integrated oil company versus marine contractor procurement patterns. CAGRs derived from equipment fleet turnover timelines, regulatory compliance deadlines, and pre-salt field development sanctioning schedules. Subsea variable speed drive deployment curves and ROV electrical substitution rates served as industry-specific forecast inputs.
Inputs from Bureau of Safety and Environmental Enforcement testing protocol disclosures and Petrobras procurement bulletins were available through the study window; gaps in contractor fleet utilization transparency introduce uncertainty bands around maintenance and inspection segment projections. Forecasts reflect documented assumptions regarding electrification technology cost curves and regulatory enforcement intensity. Material deviation in EU F-Gas Regulation phase-out timelines or Brazilian pre-salt licensing round outcomes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
North Sea Offshore Decommissioning Market
Offshore Oil and Gas
Gulf of Mexico Oil and Gas Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
Oil and Gas Fishing Market
Offshore Oil and Gas
Central Asia Oil and Gas Upstream Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market
Offshore Oil and Gas
Oil Rig Market
Offshore Oil and Gas
Floating Production Systems (FPS) Market
Offshore Oil and Gas
Southeast Asia Offshore Seismic Survey Market
Offshore Oil and Gas
Norway Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
South Sudan Oil and Gas Downstream Market
Offshore Oil and Gas
Subsea Production and Processing System Market
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
Middle East Offshore MRO Market
Offshore Oil and Gas
Floating Production System Sales Market
Offshore Oil and Gas
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market