
 Connected Solutions for Oil and Gas Market | 2026-2036
Connected Solutions for Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Solutions for Oil and Gas Market Outlook
Software-defined predictive maintenance is broadening what operators purchase as a recurring service rather than capital equipment. Emerson Electric leverages its Plantweb digital ecosystem to anchor long-term service contracts across offshore platforms. Honeywell sustains R&D intensity in edge analytics hardware that processes vibration and thermal data locally before cloud transmission. Siemens differentiates through integrated cybersecurity protocols embedded within its industrial IoT gateways.
Connected solutions for oil and gas integrate sensors, communication networks, and analytics platforms to monitor subsurface equipment, pipeline integrity, and refinery throughput in real time, typically operating across temperature ranges from minus 40 to 85 degrees Celsius with explosion-proof certifications. The primary purpose is converting operational data into actionable intelligence that reduces unplanned shutdowns and optimizes hydrocarbon recovery rates. IoT sensor networks and edge computing infrastructure represent the most mature technology layers with established procurement frameworks, while AI-driven subsurface interpretation commands premium pricing due to specialized geoscience expertise scarcity. Cloud computing adoption accelerates fastest among midstream operators managing distributed pipeline networks, though data analytics services capture disproportionate margin pools through recurring subscription structures.
The EPA enforces methane monitoring mandates under revised Clean Air Act standards, while the Pipeline and Hazardous Materials Safety Administration imposes leak detection and repair protocols that directly specify sensor coverage density and response time thresholds. These frameworks elevate demand for certified monitoring hardware and audit-ready data logging platforms. Stakeholders must weigh interoperability commitments against vendor lock-in risks as regulatory data formats solidify across jurisdictions.
Market Dynamics
Upstream operators are converting capital equipment purchases into recurring predictive maintenance subscriptions, compressing vendor sales cycles while extending contract tenures across offshore and shale assets.
Growth Catalysts
- EPA methane monitoring mandates:Revised Clean Air Act standards compel continuous emissions surveillance, mandating certified sensor networks and audit-ready data logging platforms across US production basins.
- Pad drilling density economics:Permian Basin operators justify dedicated fiber and edge computing infrastructure where multi-well pads cluster, reducing per-well connectivity costs below satellite-dependent alternatives.
- Predictive maintenance contract expansion:Offshore platform operators now procure vibration and thermal analytics as bundled services rather than discrete hardware, locking in decade-long vendor relationships.
Market Restraints
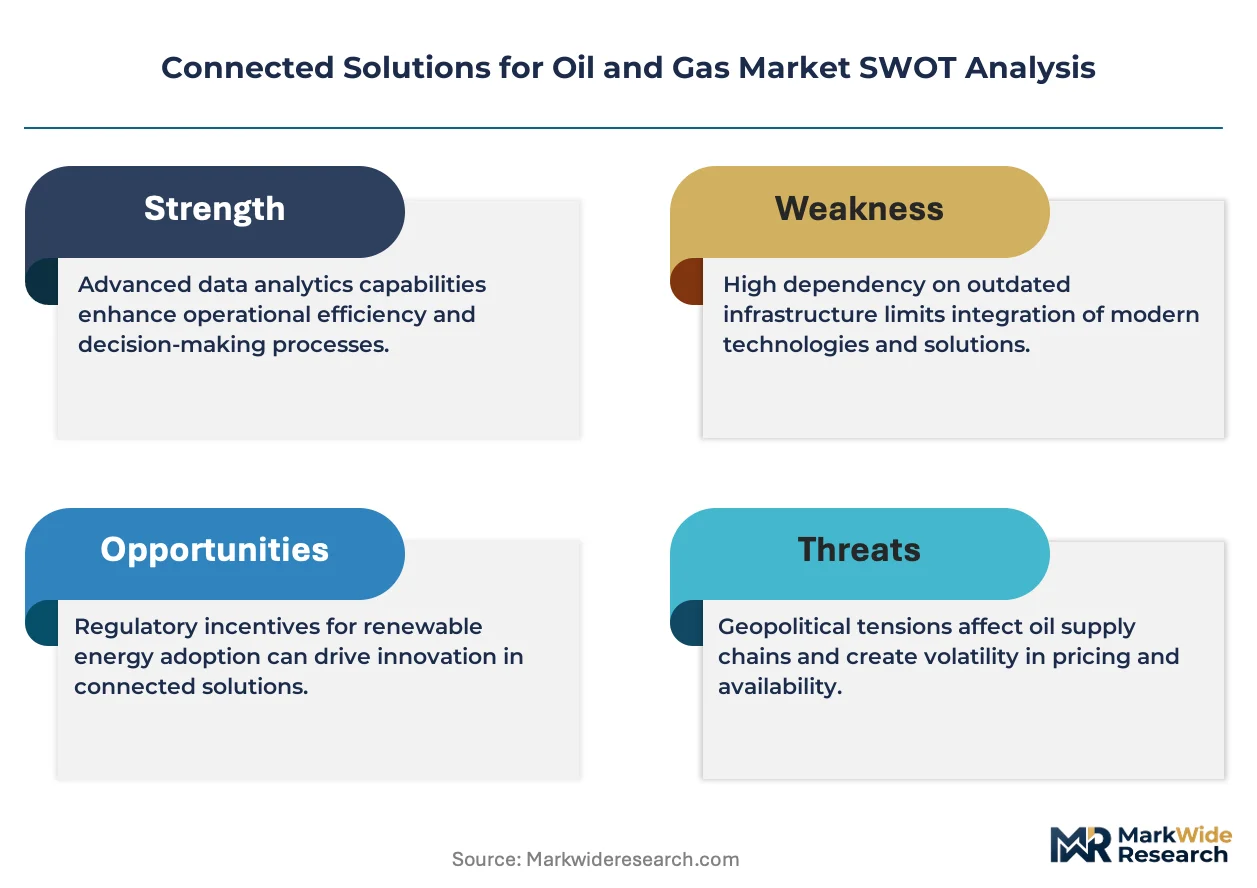
- Explosion-proof certification costs:ATEX and IECEx compliance for sensors operating across minus 40 to 85 degrees Celsius temperature ranges adds 30-40% hardware premiums versus standard industrial IoT equivalents.
- Specialized geoscience talent scarcity:AI-driven subsurface interpretation requires hybrid petroleum engineering and machine learning expertise that commands compensation premiums exceeding general software development roles.
- Vendor interoperability gaps:Proprietary data formats from Emerson Plantweb, Honeywell Forge, and Siemens Industrial Edge create integration friction that delays multi-vendor deployment timelines.
Strategic Opportunities
- Midstream cloud acceleration:Pipeline operators managing distributed networks across Texas, North Dakota, and Alberta represent underpenetrated demand for centralized SCADA-to-cloud migration services.
- EU methane regulation alignment:The EU Green Deal's impending methane performance standards for imported natural gas create compliance service opportunities for European terminal and storage operators.
- Edge-to-cloud convergence:Integration of NVIDIA GPU-accelerated edge devices with hyperscaler analytics platforms enables real-time subsurface modeling that was previously batch-processed overnight.
Industry Challenges
- Cybersecurity certification bottlenecks:IEC 62443-3-3 SL2/SL3 compliance for industrial IoT gateways requires 12-18 month validation cycles that delay field deployment of security-hardened hardware.
- Legacy DCS integration complexity:Brownfield refineries running 1990s-era distributed control systems face protocol translation challenges when overlaying modern wireless sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Solutions for Oil and Gas Market |
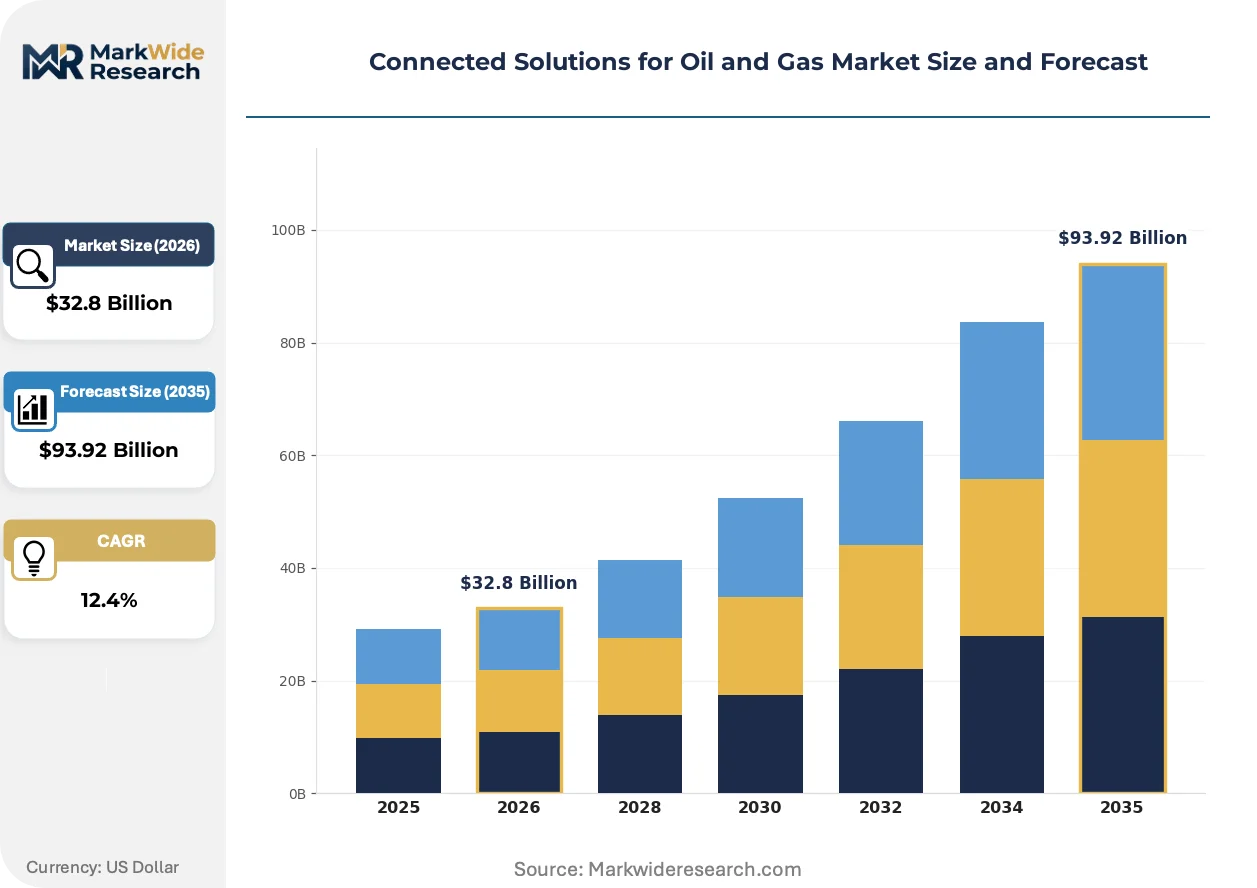
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $93.92 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Exploration, Drilling, Production, Refining Technology: IoT, AI, Cloud Computing, Big Data Service Type: Consulting, Maintenance, Monitoring, Data Analytics End User: Upstream, Midstream, Downstream, Service Companies |
| Companies Covered | Emerson Electric, Yokogawa Electric Corporation, Schneider Electric, Amazon Web Services, Microsoft, Honeywell, ABB, Google Cloud, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Solutions for Oil and Gas Market Strategic Shifts
Software-defined architectures are collapsing the boundary between operational technology and information technology, forcing vendors to restructure engineering teams and support models around continuous deployment rather than discrete commissioning.
Digital twin technology for subsurface reservoir simulation is electrifying how operators manage waterflooding and carbon sequestration projects. Permian and Bakken producers are deploying these models at pilot scale with weekly update frequencies. The technology is electrifying traditional reservoir engineering workflows by compressing scenario analysis from months to hours.
The EPA's finalized methane emissions performance standards under Subpart OOOOb impose strict leak detection and repair timelines that cascade through equipment procurement specifications. Operators must now demonstrate continuous monitoring coverage with 90-day repair mandates for detected super-emitters. Midstream gatherers in the Permian and Appalachian basins are responding by pre-positioning spare sensor inventory to guarantee compliance response windows.
Service contract unbundling is fragmenting how operators procure connected solutions. National oil companies in the Middle East now separate hardware ownership from analytics subscriptions and field service agreements, enabling multi-vendor sourcing that was previously locked into single-source frameworks. This pattern is most visible in Saudi Aramco's master gas system expansion, where edge hardware, cloud platforms, and interpretation services are tendered independently.
Connected Solutions for Oil and Gas Market Segmentation
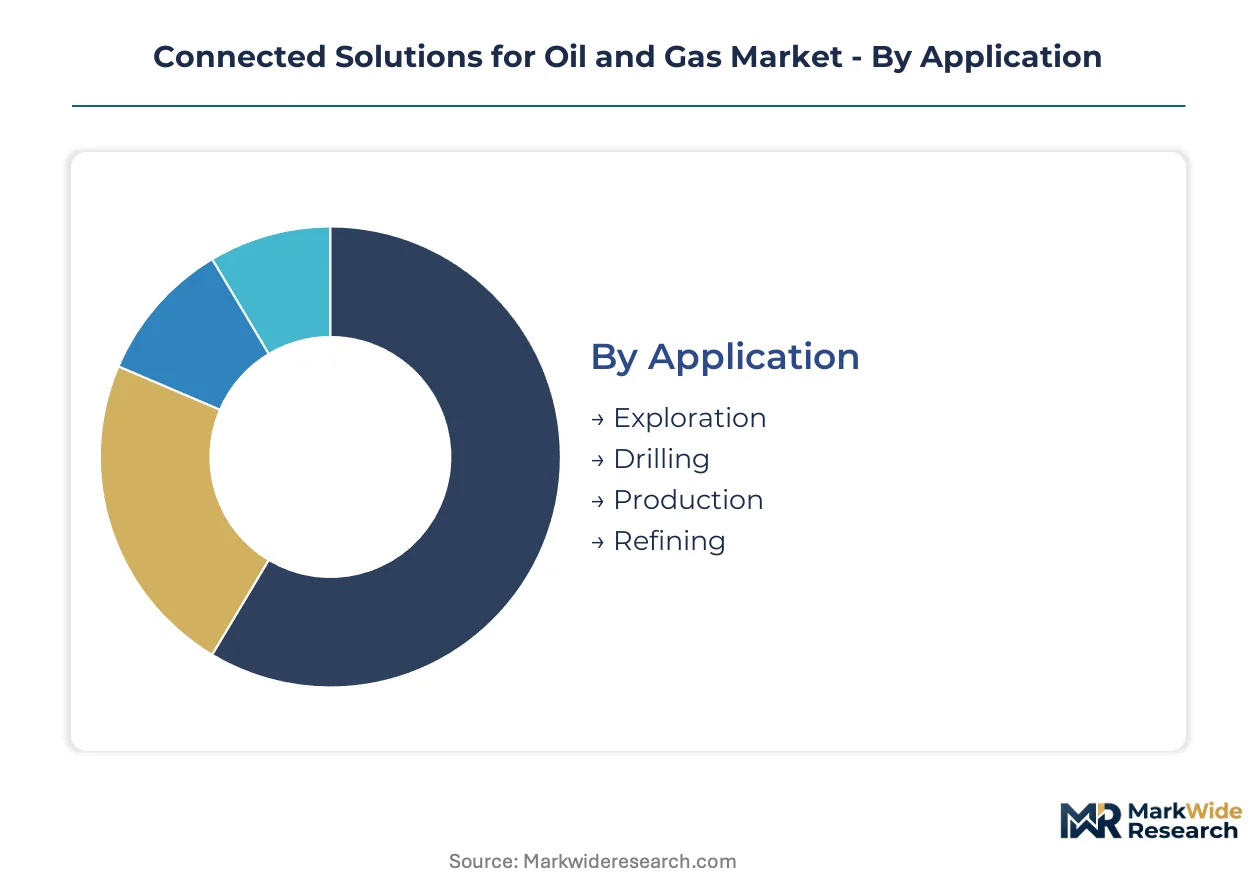
Connected solutions for oil and gas fragment across operational layers, from subsurface exploration through refining optimization. Buyers select technology-service bundles based on regulatory exposure, asset vintage, and internal data science capabilities rather than uniform procurement templates.
Application:
Operators prioritize applications based on unplanned downtime costs and emissions compliance exposure rather than technology novelty.
- Production:Real-time wellhead monitoring and artificial lift optimization dominate contract values. Permian Basin operators deploy edge-computing clusters at multi-well pads to compress response times below EPA methane repair windows.
- Refining:Catalytic reformer and distillation column analytics command premium service fees due to continuous process criticality. Gulf Coast refiners integrate predictive corrosion monitoring with existing DCS infrastructure to avoid catastrophic turnaround delays.
- Exploration:Seismic data processing and reservoir characterization rely on cloud-scale compute for velocity model updates.
- Drilling:Directional steering automation and bit vibration analytics reduce mechanical specific energy consumption.
Volume sits with Production; growth tilts toward Refining as US Gulf Coast capacity expansions accelerate.
Technology:
Technology selection tracks data gravity—whether processing occurs at the wellhead, regional edge, or hyperscale cloud.
- IoT:Explosion-proof sensor networks operating across minus 40 to 85 degrees Celsius form the physical layer. ATEX and IECEx certification requirements add hardware premiums that downstream buyers absorb more readily than marginal shale producers.
- AI:Subsurface interpretation and predictive maintenance algorithms command specialist premiums due to petroleum engineering-machine learning hybrid talent scarcity. Supermajors staff dedicated centers of excellence; independents purchase algorithm-as-a-service subscriptions.
- Cloud Computing:Midstream pipeline operators migrate SCADA historians to centralized platforms for cross-asset optimization.
- Big Data:Seismic and production data lake architectures enable multi-decade reservoir history matching.
IoT captures installed base dominance; AI expands most quickly as vendors productize geoscience workflows.
Service Type:
Procurement patterns diverge between capital-constrained independents seeking operational expenditure flexibility and national oil companies separating ownership from analytics.
- Data Analytics:Recurring subscription models for production optimization and emissions reporting displace perpetual software licenses. Saudi Aramco's master gas system expansion tenders analytics separately from hardware and field services.
- Monitoring:Continuous methane detection and pipeline integrity surveillance carry regulatory mandates. Permian gatherers pre-position spare sensor inventory to guarantee 90-day EPA repair compliance.
- Consulting:Digital transformation roadmapping and cybersecurity architecture reviews precede large-scale deployments.
- Maintenance:Predictive service contracts bundle vibration analysis, thermal imaging, and spare parts logistics.
Monitoring holds contract volume leadership; Data Analytics climbs the fastest as software-defined architectures mature.
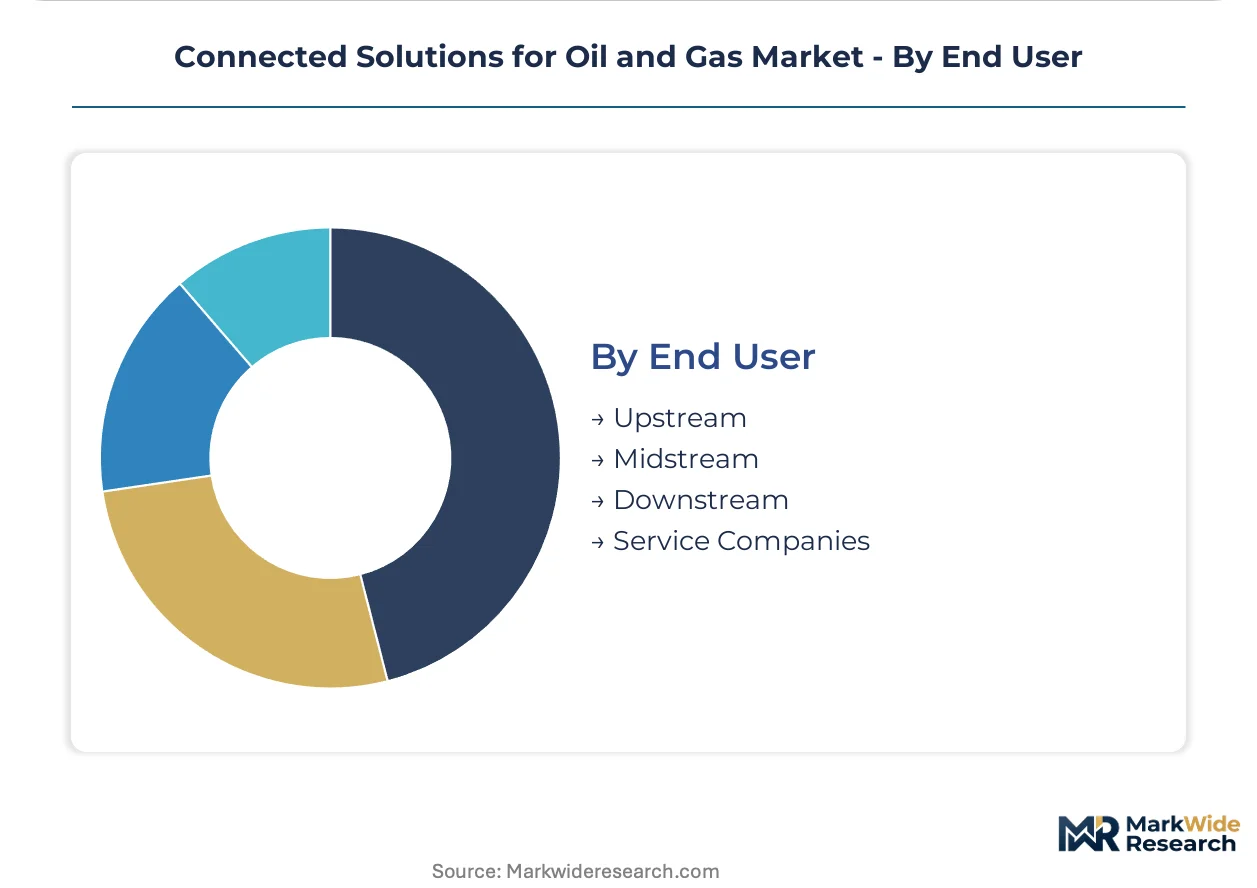
End User:
End-user sophistication ranges from supermajor internal digital units to service company white-label offerings for capital-constrained operators.
- Upstream:Shale producers and offshore platform operators drive predictive maintenance contract conversion from capital equipment purchases. Deepwater developments justify decade-long vendor relationships for subsea fiber and edge infrastructure.
- Midstream:Pipeline and storage terminal operators lag in cloud adoption but represent underpenetrated demand for centralized SCADA migration across Texas, North Dakota, and Alberta networks.
- Downstream:Refiners prioritize cybersecurity-hardened gateways and legacy DCS integration over greenfield sensor deployment.
- Service Companies:Schlumberger and Halliburton digital divisions package connected solutions for independents lacking internal data science capabilities.
Upstream commands revenue concentration; Midstream offers the steepest expansion trajectory as distributed network management demands cloud-scale analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes more connected oil and gas solutions than it produces, importing specialized edge hardware and AI talent from Germany and Japan. Saudi Arabia and China concentrate upstream deployment volumes, while Norway and the UAE compete for subsea fiber infrastructure contracts.
United States
EPA methane monitoring mandates under Subpart OOOOb drive sensor network procurement across the Permian Basin and Appalachian shale plays. The Pipeline and Hazardous Materials Safety Administration enforces leak detection protocols specifying response time thresholds. Houston anchors vendor headquarters concentration, while Midland-Odessa clusters edge computing deployment for multi-well pad density economics.
Saudi Arabia
Aramco's master gas system expansion tenders separate hardware, cloud platforms, and analytics services, fragmenting procurement patterns across national upstream assets. The country's national petroleum regulator aligns methane performance standards with impending EU import requirements. Dhahran concentrates digital transformation roadmapping and cybersecurity architecture reviews for brownfield infrastructure.
Norway
Equinor deploys subsea fiber and edge infrastructure across deepwater developments in the North Sea and Barents Sea, justifying decade-long vendor relationships. The Norwegian Petroleum Directorate mandates continuous emissions surveillance for offshore platform electrification projects. Stavanger clusters predictive maintenance subscription conversion from capital equipment purchases for subsea production systems.
China
Sinopec and PetroChina accelerate SCADA-to-cloud migration for pipeline networks spanning Sichuan-Chongqing shale gas fields and Xinjiang crude corridors. The Ministry of Ecology and Environment enforces methane emission intensity targets for national oil companies under dual carbon goals. Shanghai concentrates hyperscaler analytics platform development for real-time reservoir modeling.
United Arab Emirates
ADNOC deploys integrated cybersecurity protocols within industrial IoT gateways across onshore Bab and offshore Upper Zakum assets. The national petroleum regulator mandates audit-ready data logging platforms for LNG export terminal certification. Abu Dhabi clusters digital twin technology pilots for waterflooding and carbon sequestration project management.
Connected Solutions for Oil and Gas Market Competitive Environment
Top-tier vendors anchor long-term service contracts across offshore platforms and national oil company frameworks, while mid-tier specialists compete on edge hardware certification speed and legacy DCS integration expertise. The vendor base stratifies across industrial automation conglomerates, hyperscale cloud providers, and petroleum engineering service companies. Three archetypes dominate: automation-anchored ecosystems, cloud-native analytics platforms, and oilfield service digital divisions. Competitive moves concentrate on strategic partnerships between sensor manufacturers and hyperscalers, plus portfolio diversification into cybersecurity-hardened gateway certification.
Among industrial automation conglomerates, Emerson Electric, Yokogawa Electric Corporation, and Siemens occupy positions exemplifying ecosystem-centric competitive strategy. Emerson represents the automation-anchored archetype through its Plantweb digital ecosystem, Yokogawa exemplifies precision instrumentation integration for process-critical refining applications, and Siemens sits within the integrated cybersecurity protocol tier for industrial IoT gateway deployment. These three entities anchor tier-one positioning without claiming specific market share figures or revenue thresholds.
| Leading Market Players |
|---|
| Emerson Electric |
| Yokogawa Electric Corporation |
| Schneider Electric |
| Amazon Web Services |
| Microsoft |
| Honeywell |
| ABB |
| Google Cloud |
| Siemens |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between ATEX/IECEx explosion-proof hardware and standard industrial IoT sensors manifests in parallel supply chain configurations, with premium-tier vendors captive to German and Japanese component sourcing while commodity sensor assemblers draw from distributed Asian manufacturing networks.
Pricing Analysis
Margin tightening in explosion-proof sensor tiers reflects ATEX and IECEx compliance premiums that add hardware costs versus standard industrial equivalents. Three-tier pricing structure across certified-premium, industrial-standard, and unlicensed-economy levels segments buyers by regulatory exposure, with Permian shale producers most price-sensitive and Gulf Coast refiners least sensitive due to catastrophic turnaround risk. Cost-down pressure on edge computing hardware accelerates as NVIDIA GPU-accelerated devices commoditize.
Supply Chain Analysis
Dual-sourcing requirements from Aramco and ADNOC procurement frameworks mandate qualified secondary suppliers for subsea fiber and edge infrastructure components. Manufacturing concentrates in Germany, Japan, and the United States for precision instrumentation, while China dominates enclosure fabrication and PCB assembly. Supply chains draw from rare earth magnet dependencies for vibration sensors and specialized glass for fiber optic cables. Single-source vulnerability sits with subsea cable armoring capacity. Distribution runs through Houston, Dhahran, and Stavanger as regional hub clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA methane monitoring mandates under Subpart OOOOb erect compliance barriers that favor incumbent vendors with certified hardware portfolios and audit-ready data logging platforms.
For Market Incumbents: Deploy cybersecurity certification acceleration as the primary lever. Compress IEC 62443-3-3 SL2/SL3 validation cycles below 12-month thresholds to outpace emerging cloud-native entrants. Deepen backward integration into explosion-proof enclosure manufacturing to offset German supplier premiums. Lock in decade-long service contracts across offshore platform operators before hyperscalers penetrate subsea fiber markets. For New Entrants and Emerging Players: Begin with midstream pipeline operators in North Dakota and Alberta as the most penetrable white-space target. These assets lag in SCADA-to-cloud migration and lack internal data science capabilities. Package edge-to-cloud convergence as bundled subscription services rather than capital equipment. Target service company white-label partnerships for capital-constrained shale independents. For Investors and Strategic Acquirers: Re-rating potential sits with industrial IoT gateway specialists possessing embedded cybersecurity protocols given EU methane regulation alignment for imported natural gas. Long-term viability favors vendors with hybrid petroleum engineering-machine learning talent pipelines. Watch EPA enforcement intensity as the signal to monitor for demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Acceleration | IEC 62443-3-3 SL2/SL3 compliance compresses field deployment timelines for security-hardened gateways. |
| Edge-to-Cloud Convergence Partnership | NVIDIA GPU integration with hyperscaler platforms enables real-time subsurface modeling previously batch-processed overnight. |
| Midstream Cloud Migration Services | Pipeline operators across Texas and Alberta represent underpenetrated demand for centralized SCADA platforms. |
| EU Methane Compliance Services | European terminal operators face impending performance standards for imported natural gas certification. |
| Predictive Maintenance Subscription Conversion | Offshore platform operators now procure vibration analytics as bundled services rather than discrete hardware. |
Study Parameters
SEC 10-K filings, EPA regulatory dockets, and hyperscaler capex disclosures formed the secondary backbone for market sizing and competitive positioning. Primary interviews with upstream operations directors, midstream SCADA engineers, and industrial IoT procurement managers validated demand assumptions across the Permian Basin, North Sea, and Saudi national assets. Bottom-up and top-down triangulation reconciled sensor deployment volumes against predictive maintenance contract values.
Bottom-up modeling tracked IoT sensor shipments, edge computing node installations, and analytics subscription revenues by application layer. Segmentation dimensions included operational layer (upstream, midstream, downstream), technology tier (IoT, AI, cloud, edge), and service type (monitoring, analytics, consulting, maintenance). CAGRs were derived from regression analysis against EPA compliance deadlines and pad drilling density economics. Forecast inputs incorporated methane repair window timelines and subsea fiber deployment cycles.
Underlying measurement precision varies by segment; IoT sensor networks carry tighter precision than AI-driven subsurface interpretation due to established procurement frameworks. Forecasts reflect assumptions about regulatory enforcement continuity and vendor interoperability resolution. Deviation in EPA methane rule implementation timelines or EU import standard ratification would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
West Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Subsea Production and Processing System Market
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
Floating Storage and Regasification Unit Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market
Offshore Oil and Gas
Asia-Pacific Floating Production Systems Market
Offshore Oil and Gas
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market
Offshore Oil and Gas
Asia Pacific Oil and Gas CAPEX Market
Offshore Oil and Gas
Kuwait Oil and Gas Downstream Market
Offshore Oil and Gas
Oil Rig Market
Offshore Oil and Gas
Floating Production Systems (FPS) Market
Offshore Oil and Gas
South America Offshore Energy Market
Offshore Oil and Gas
East Africa Oil and Gas Midstream Market
Offshore Oil and Gas
Offshore Drilling Market
Offshore Oil and Gas
FPSO Market
Offshore Oil and Gas
Marine Seismic Equipment and Acquisition Market