
 Offshore Oil and Gas Communications Market | 2026-2036
Offshore Oil and Gas Communications Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Oil and Gas Communications Market Analytics
Brazil's pre-salt basin development is fragmenting procurement patterns across the offshore communications value chain. Ericsson leverages its 5G private network portfolio to anchor European platform modernization contracts. Inmarsat sustains dominance in L-band satellite coverage for drilling vessels operating beyond cellular range. Huawei Technologies competes aggressively on microwave and LTE infrastructure bids across Asian and African offshore concessions.
Offshore oil and gas communications encompasses the integrated systems enabling voice, data, and video transmission between remote drilling platforms, subsea installations, and onshore control centers, typically operating across VSAT links with sub-500ms latency thresholds and fiber optic cables rated for hydrostatic pressures exceeding 10,000 psi. These networks support real-time production monitoring, emergency response coordination, and remote equipment diagnostics in environments where terrestrial connectivity is unavailable. Satellite communication services capture the largest revenue share due to their indispensability for ultra-deepwater and Arctic operations where subsea cable deployment remains economically prohibitive. IP Networking technology is gaining share fastest as operators replace legacy TDM architectures with packet-based infrastructure that converges SCADA, telephony, and video surveillance onto unified platforms. Among end users, production companies represent the most concentrated margin pool because their multi-decade field lifecycles generate recurring service contracts and infrastructure refresh cycles.
The US Coast Guard and FCC mandate GMDSS-compatible satellite terminals on all offshore vessels, while Brazil's ANP imposes local content requirements that steer procurement toward domestically integrated communication packages. The EU's F-Gas Regulation indirectly shapes demand by accelerating platform electrification projects that require upgraded fiber and microwave backbones to connect offshore wind-hybrid installations. Stakeholders must weigh the trade-off between proprietary vendor ecosystems and interoperable open standards as field operators demand seamless handoffs between satellite, subsea fiber, and emerging low-earth orbit constellations.
Market Dynamics
The IEC 61850 standardization push is compressing vendor selection cycles as operators demand interoperable digital substations that unify SCADA, protection, and telephony onto single IP backbones across Gulf of Mexico and Brazilian deepwater assets.
Growth Catalysts
- Brazil's ANP local content mandates:Domestic integration requirements for pre-salt field development are steering procurement toward locally assembled communication packages, expanding the addressable base for regional system integrators.
- Subsea fiber optic pressure ratings:Cables engineered for hydrostatic pressures exceeding 10,000 psi now enable real-time monitoring at previously inaccessible ultra-deepwater depths, opening new drilling frontiers.
- US Coast Guard GMDSS compatibility requirements:Mandatory satellite terminal specifications for all offshore vessels create baseline demand for L-band and VSAT infrastructure refresh cycles.
Market Restraints
- Copper and optical fiber input volatility:Subsea cable manufacturing faces raw material cost swings that compress margin predictability for infrastructure providers bidding multi-year frame agreements.
- Arctic and ultra-deepwater satellite dependency:Regions where subsea fiber deployment remains economically prohibitive lock operators into higher recurring service costs with limited vendor alternatives.
- Legacy TDM architecture replacement drag:Platform operators with decades-old voice switching infrastructure face extended migration timelines that delay packet-based convergence investments.
Strategic Opportunities
- Low-earth orbit constellation integration:Emerging LEO networks offer sub-100ms latency alternatives to geostationary VSAT, creating white space for hybrid satellite architectures in Arctic exploration zones.
- EU F-Gas Regulation electrification tailwinds:Platform electrification mandates are accelerating fiber and microwave backbone upgrades to connect offshore wind-hybrid installations.
- Industrial IoT sensor convergence:Unified platforms combining vibration monitoring, corrosion detection, and video analytics represent underpenetrated spend categories for production companies.
Industry Challenges
- Subsea fiber splicing technician scarcity:Specialized skills for high-pressure cable termination and repair face supply constraints that extend installation timelines and inflate day rates.
- Multi-vendor interoperability certification:Seamless handoffs between satellite, fiber, and microwave networks require extended testing protocols that delay field deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Oil and Gas Communications Market |
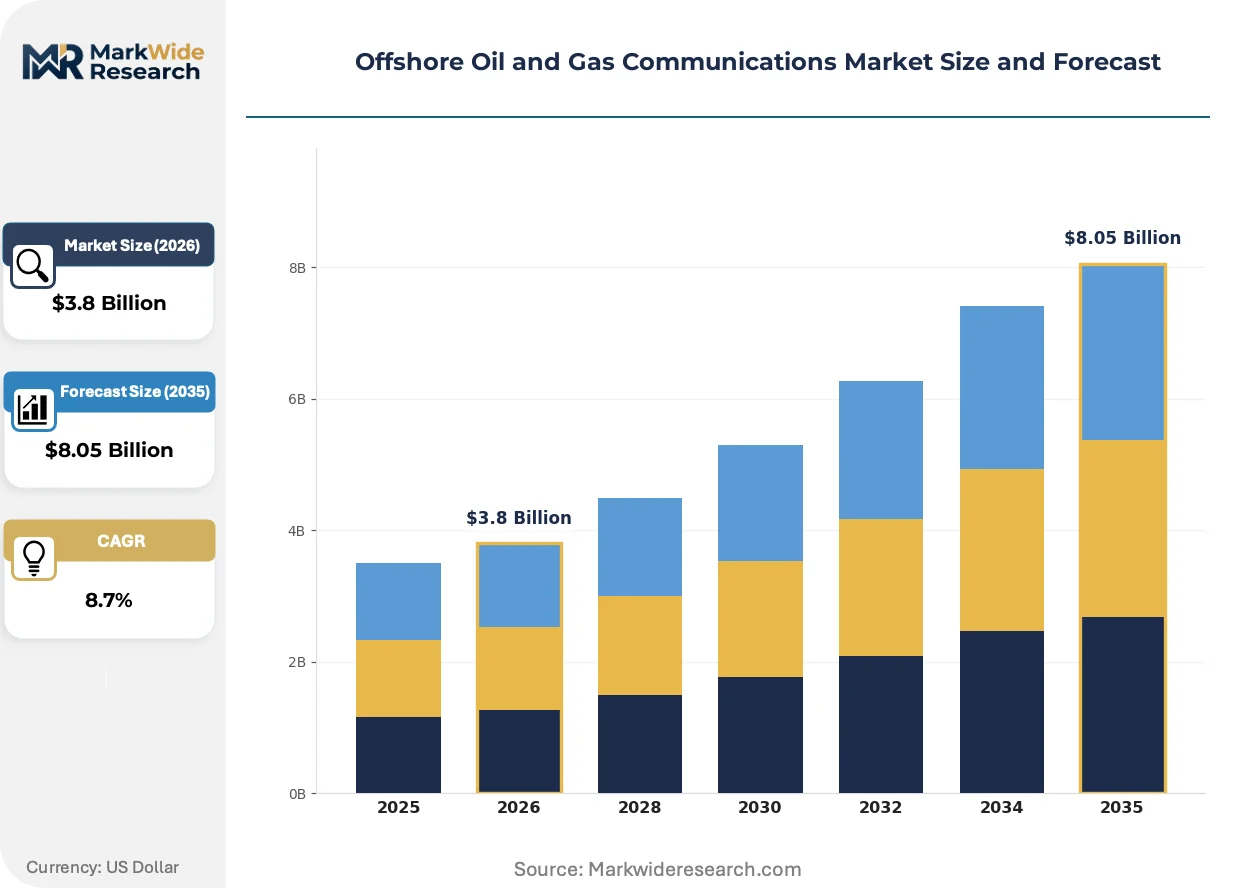
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Satellite Communication, Subsea Communication, Radio Communication, Fiber Optic Communication Technology: VSAT, LTE, Microwave, IP Networking End User: Exploration Companies, Production Companies, Service Providers, Regulatory Bodies Deployment: Onshore, Offshore, Remote, Semi-submersible |
| Companies Covered | Ericsson, Siemens Energy, Inmarsat, Huawei Technologies, Baker Hughes, Hughes Network Systems, ABB, Speedcast, Nokia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Oil and Gas Communications Market Evolving Landscape
Communications architecture is migrating from purpose-built silos toward converged IP platforms, driven by operator demands for unified visibility across drilling, production, and safety systems.
Subsea fiber optic transmission systems are migrating from single-purpose telemetry links toward multi-service backbones carrying SCADA, high-definition video, and voice traffic simultaneously. Production companies in Brazil's pre-salt fields are accelerating this transition to reduce deck space and power consumption. The technology is migrating from niche ultra-deepwater applications toward standard specification in mid-water developments, compressing the addressable market for standalone satellite-only platforms.
The EU's F-Gas Regulation is accelerating platform electrification timelines, mandating reduced fluorinated gas emissions that drive replacement of gas turbine power generation. This regulatory pressure forces communication infrastructure upgrades to support higher-bandwidth connections between offshore substations and onshore grids. North Sea operators are responding with hybrid fiber-microwave deployments that integrate legacy oil and gas assets with adjacent offshore wind installations.
Service contracting is compressing from equipment-centric procurement toward integrated managed service agreements spanning installation, maintenance, and bandwidth provisioning. Drilling contractors are unbundling hardware ownership from operational responsibility, transferring capital risk to communication service providers. This behavioral shift is most visible in the Gulf of Mexico, where independent operators favor operational expenditure models over subsea cable ownership.
Offshore Oil and Gas Communications Market Segmentation
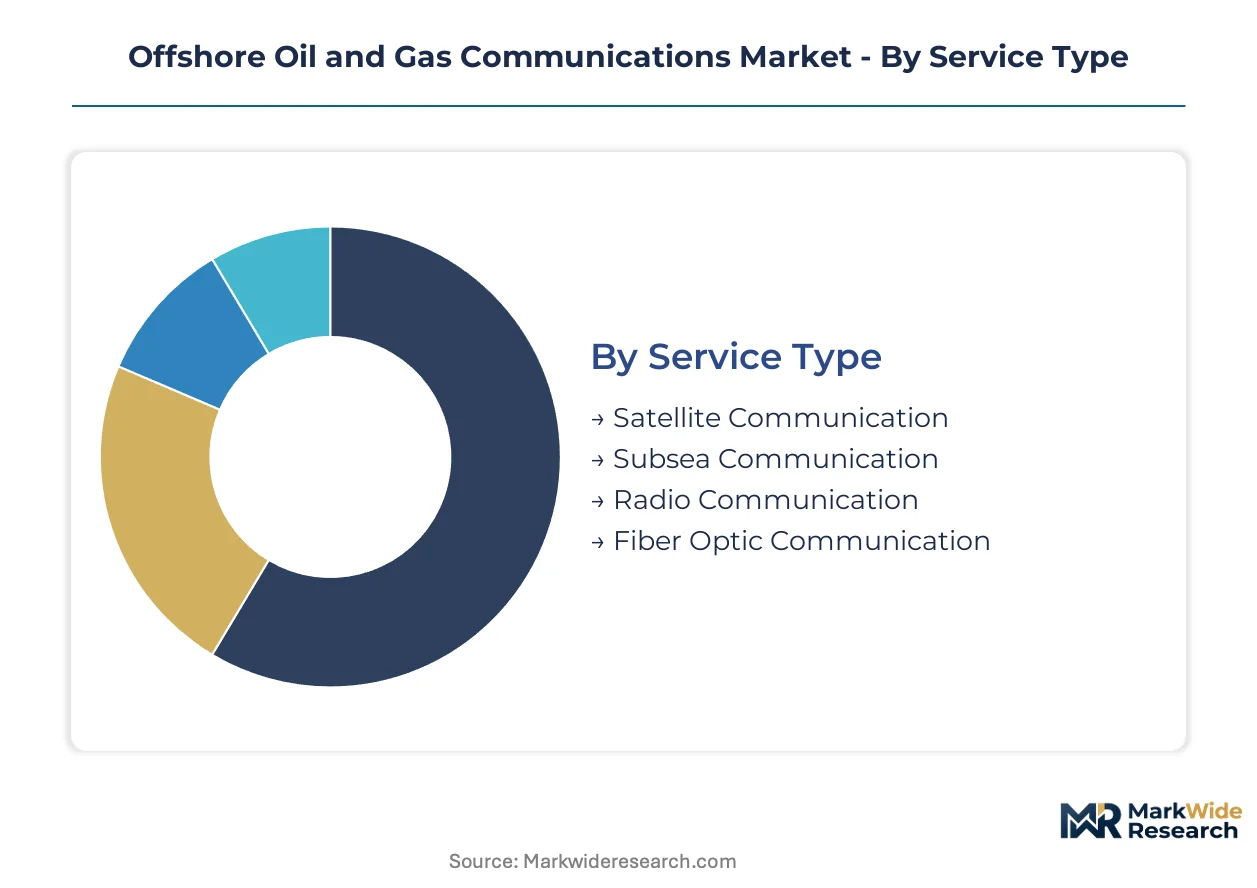
Offshore communications infrastructure exhibits divergent lifecycle economics across service categories, with satellite terminals requiring continuous bandwidth provisioning while subsea fiber demands intensive splice-repair capabilities. Understanding segment-specific maintenance intensity and capital deployment patterns enables vendors to calibrate pricing models and partnership structures.
Service Type:
After-sales service intensity varies dramatically across service modalities, with satellite communication requiring perpetual orbital bandwidth leasing and ground station maintenance, while subsea fiber networks demand specialized vessel-based repair crews and pressure-rated splice certification.
- Satellite Communication:Geostationary and L-band constellations deliver voice, data, and video links to drilling vessels and platforms beyond terrestrial coverage. Demand concentrates with ultra-deepwater operators in the Gulf of Mexico and Brazilian pre-salt basins where hydrostatic pressure prohibits fiber deployment. Recurring service contracts generate the most concentrated margin pools due to multi-decade field lifecycles and mandatory GMDSS compliance.
- Subsea Communication:Pressure-rated fiber optic cables rated for 10,000+ psi enable real-time SCADA and high-definition video transmission from wellheads to surface platforms. Brazilian Petrobras-led developments anchor procurement volume, with ANP local content mandates steering integration toward domestic assembly facilities. Capital intensity and specialized installation vessels create the highest barrier to competitive entry.
- Radio Communication:Terrestrial microwave and UHF systems provide platform-to-platform and platform-to-vessel connectivity in coastal and mid-water developments. North Sea operators favor hybrid fiber-microwave architectures for wind-hybrid electrification projects.
- Fiber Optic Communication:Surface and shallow-water fiber deployments connect offshore platforms to onshore control centers with sub-millisecond latency. Gulf of Mexico independent operators increasingly favor managed service models over cable ownership.
By volume, satellite communication leads. By growth pace, subsea communication is ahead.
Technology:
Technology selection maps directly to latency tolerance and mobility requirements, with fixed platforms favoring deterministic IP backbones while drilling fleets prioritize rapidly deployable VSAT terminals.
- VSAT:Very Small Aperture Terminal systems provide Ku-band and Ka-band connectivity for mobile drilling units and emergency backup on fixed platforms. Arctic and ultra-deepwater operators depend on VSAT where fiber economics fail.
- LTE:Private 4G/5G cellular networks deliver high-bandwidth, low-latency coverage across platform decks and adjacent vessel clusters. European North Sea modernization contracts favor LTE for crew welfare and industrial IoT sensor convergence.
- Microwave:Point-to-point radio links bridge gaps between platform clusters and fiber landing points. Hybrid fiber-microwave deployments accelerate where EU F-Gas Regulation electrification mandates require upgraded backbones.
- IP Networking:Packet-based infrastructure converges SCADA, telephony, and video surveillance onto unified platforms, displacing legacy TDM architectures. IEC 61850 standardization compresses vendor selection cycles as operators demand interoperable digital substations.
By installed base, VSAT dominates. By substitution velocity, IP Networking is climbing the fastest.
End User:
End user procurement behavior splits between capital-intensive asset owners seeking long-term infrastructure control and operational expenditure-focused contractors favoring managed service flexibility.
- Exploration Companies:Seismic survey and drilling contractors prioritize rapidly deployable, mobile communication packages with short-term leasing structures. Gulf of Mexico independents increasingly unbundle hardware ownership from operational responsibility.
- Production Companies:Field operators with multi-decade asset lifecycles generate recurring infrastructure refresh cycles and integrated service contracts. Brazilian pre-salt development anchors the most concentrated procurement volume.
- Service Providers:Drilling contractors and maintenance firms demand seamless handoffs between satellite, fiber, and microwave networks for vessel fleet coordination.
- Regulatory Bodies:US Coast Guard and ANP compliance mandates create baseline demand for GMDSS-compatible terminals and local content verification.
By contract value, production companies lead. By procurement flexibility, exploration companies are expanding most quickly.
Deployment:
Deployment mode determines environmental protection ratings, power availability, and crew accessibility, with remote and semi-submersible configurations imposing the most severe engineering constraints.
- Onshore:Control centers and coastal logistics bases aggregate fiber backbones and satellite ground stations. Brazilian integration facilities concentrate under ANP local content requirements.
- Offshore:Fixed production platforms host converged IP networks combining subsea fiber uplinks with platform-local LTE and microwave distribution. Gulf of Mexico and North Sea infrastructure modernization drives replacement demand.
- Remote:Ultra-deepwater and Arctic installations depend exclusively on satellite connectivity due to fiber deployment economics. LEO constellation integration offers emerging alternatives to geostationary latency.
- Semi-submersible:Mobile drilling units require rapidly deployable VSAT and radio packages with self-stabilizing antenna platforms. Service contracting compression favors operational expenditure models.
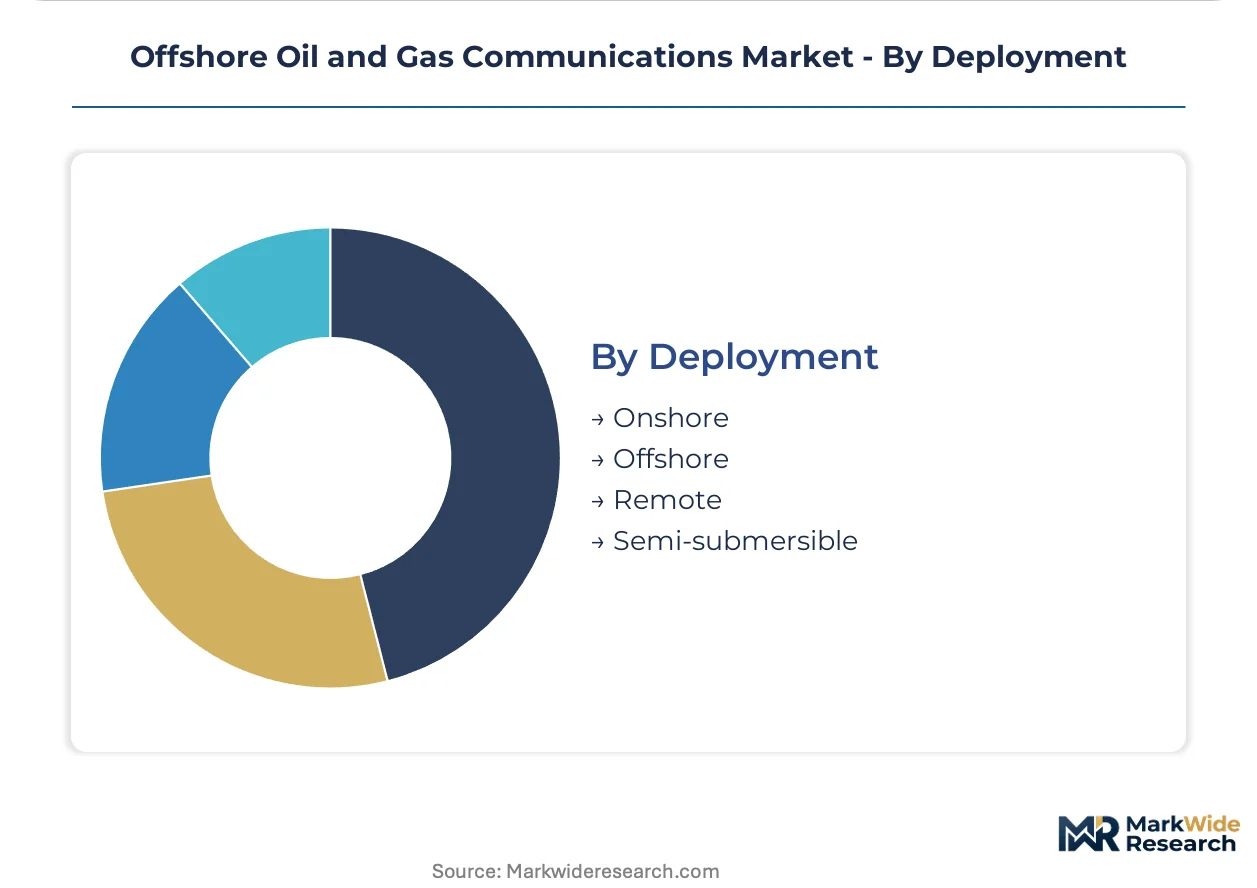
By infrastructure stock, offshore fixed platforms lead. By connectivity challenge intensity, remote deployments are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subsea fiber manufacturing clusters in Norway and satellite ground station networks in the United States concentrate supply-side capacity for ultra-deepwater communication infrastructure. Brazilian integration facilities and Gulf of Mexico service hubs anchor downstream assembly and deployment operations.
United States
Gulf of Mexico independent operators favor managed service models over cable ownership, compressing procurement cycles for VSAT and subsea fiber installations. The US Coast Guard mandates GMDSS-compatible satellite terminals on all offshore vessels, creating baseline demand for L-band infrastructure. Houston anchors the largest concentration of drilling contractor headquarters, where operational expenditure models now dominate communication contracting.
Brazil
Petrobras-led pre-salt field development drives substantial investment in resilient subsea communication backbones rated for 10,000+ psi hydrostatic pressure. ANP local content requirements steer procurement toward domestically integrated communication packages, expanding the addressable base for regional system integrators. Macaé and Rio de Janeiro host the primary integration facilities where domestic assembly mandates concentrate vendor activity.
Norway
North Sea platform electrification timelines accelerate under EU F-Gas Regulation mandates, forcing communication infrastructure upgrades for offshore wind-hybrid installations. The country's national petroleum regulator imposes stringent safety communication standards for subsea fiber and microwave deployments. Stavanger and Bergen anchor specialized subsea cable manufacturing and splicing technician training centers.
United Kingdom
North Sea decommissioning and electrification projects drive hybrid fiber-microwave backbone replacements across aging platform infrastructure. The Health and Safety Executive mandates redundant communication pathways for emergency response coordination on all offshore installations. Aberdeen concentrates service provider headquarters and subsea engineering consultancies managing multi-vendor interoperability certification.
China
State-directed offshore wind expansion in the East China Sea and South China Sea generates demand for integrated microwave and fiber backbones connecting hybrid oil-gas-wind installations. MIIT spectrum allocation policies shape private LTE network deployment across coastal drilling concessions. Tianjin and Shenzhen host manufacturing clusters for pressure-rated fiber optic cable and marine communication terminals.
Offshore Oil and Gas Communications Market Competitive Landscape
Integrated infrastructure conglomerates and specialized satellite service providers split the market between capital-intensive subsea fiber deployments and recurring bandwidth provisioning contracts. The vendor landscape exhibits tiered concentration, with a handful of European and Asian conglomerates controlling pressure-rated cable manufacturing while regional integrators capture downstream assembly margins. Two strategic archetypes dominate: full-stack infrastructure vendors bundling fiber, microwave, and satellite assets; and pure-play satellite operators leasing orbital capacity under long-term service agreements. Competitive intensity centers on M&A activity targeting subsea splicing capabilities and strategic partnerships bridging LEO constellation integration.
Within the full-stack infrastructure tier, Ericsson and Siemens Energy exemplify European conglomerates leveraging 5G private network portfolios and digital substation expertise to anchor platform modernization contracts. Inmarsat occupies a distinct position as a pure-play satellite operator sustaining L-band coverage dominance for drilling vessels operating beyond cellular range. Huawei Technologies represents the aggressive-price Asian archetype competing on microwave and LTE infrastructure bids across Asian and African offshore concessions.
| Leading Market Players |
|---|
| Ericsson |
| Siemens Energy |
| Inmarsat |
| Huawei Technologies |
| Baker Hughes |
| Hughes Network Systems |
| ABB |
| Speedcast |
| Nokia |
| Others |
Value Network & Pricing Analysis
Stavanger's subsea cable manufacturing cluster anchors global capacity for pressure-rated fiber optics, concentrating pricing power among Norwegian producers who supply Brazilian pre-salt developments and Gulf of Mexico deepwater projects. This geographic concentration creates asymmetric leverage where vessel availability and splice technician scarcity translate directly into premium service pricing for urgent repair contracts.
Pricing Analysis
ANP local content mandates dictate the pricing tier structure across Brazilian offshore communications procurement. Three-tier pricing structure across premium, standard, and economy levels segments buyers by integration depth and certification grade. Price differentiation hinges on IEC 61850 compliance status and after-sales service bundling. Cost compression in standard-tier microwave infrastructure is intensifying because Huawei Technologies and regional Asian vendors compete aggressively on equipment bids. Exploration companies exhibit the highest price sensitivity due to short-term contracting horizons, while production companies with multi-decade field lifecycles absorb premium pricing for integrated managed service agreements.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for microwave and LTE infrastructure components. Manufacturing concentrates in China, Norway, and the United States for pressure-rated fiber, subsea repeaters, and satellite ground station equipment. Raw material dependencies rest on high-purity silica for fiber cores, copper alloys for marine-grade connectors, and gallium nitride for RF amplifiers. Single-source vulnerability persists for 10,000+ psi pressure-rated cable termination equipment. Distribution runs through system integrators in Macaé, Houston, and Aberdeen who bundle hardware with installation and maintenance services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The offshore communications market sits at a platform-economics inflection where IEC 61850 standardization is collapsing proprietary vendor silos into interoperable IP backbones. Ecosystem openness now determines competitive survival more than hardware performance specifications.
For Market Incumbents: Entrench position through backward integration into subsea splicing technician training and certification programs, addressing the supply constraint that extends installation timelines. Lock in long-term frame agreements with Petrobras and Gulf of Mexico independents before LEO constellation integration commoditizes geostationary VSAT latency advantages. Prioritize digital substation expertise as the defensive moat against pure-play satellite operators expanding into converged platform contracts.
For New Entrants and Emerging Players: Arctic exploration zones with prohibitive fiber deployment economics represent the most penetrable entry point for hybrid LEO-VSAT service architectures. Mid-water developments in West Africa and Southeast Asia offer secondary white-space where incumbent presence remains thin and procurement flexibility favors operational expenditure models. Lead with managed service contracting that unbundles hardware ownership from bandwidth provisioning, mirroring the Gulf of Mexico behavioral shift.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors full-stack infrastructure vendors with integrated fiber-microwave-satellite capabilities over pure-play satellite operators facing LEO disruption. Long-term viability rests on multi-decade production company relationships and recurring service contract visibility. Acquisition targets should demonstrate ANP-compliant Brazilian integration capacity or North Sea electrification project credentials. Monitor LEO constellation coverage expansion as the critical inflection signal for geostationary VSAT pricing power erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| LEO Constellation Integration | Sub-100ms latency alternatives disrupt geostationary VSAT dominance in Arctic ultra-deepwater zones. |
| Subsea Splicing Capability Acquisition | Technician scarcity creates captive supply advantages for vessel-based repair and installation services. |
| Digital Substation Certification Investment | IEC 61850 compliance anchors European and Brazilian platform modernization contract awards. |
| Managed Service Contract Expansion | Operational expenditure models transfer capital risk from drilling contractors to communication providers. |
| ANP Local Content Partnership | Domestic assembly mandates in Brazil steer procurement toward regionally integrated vendor ecosystems. |
Research Methodology
Initial hypotheses were tested against primary input from offshore platform engineers, drilling contractor procurement directors, subsea cable installation supervisors, and satellite service operations managers and refined through secondary validation. Primary fieldwork drew from structured discussions with Gulf of Mexico independent operators, Petrobras technical planning divisions, and North Sea electrification project leads. Secondary sources encompassed ANP regulatory filings, US Coast Guard GMDSS certification databases, EU F-Gas Regulation implementation reports, and subsea cable manufacturing trade data. Bottom-up segment sizing triangulated against top-down macro demand indicators across the analysis window.
Demand-supply-balance framing anchored the forecast framework, modeling capacity deployment against field development timelines across service type, technology, end user, and deployment mode dimensions. Segmentation captured satellite communication, subsea fiber, radio, and surface fiber modalities alongside VSAT, LTE, microwave, and IP networking technologies. CAGRs were derived from production company capital expenditure trajectories, drilling fleet utilization patterns, and regulatory compliance refresh cycles without year-specific anchoring.
Macroeconomic conditions sit as an overlay; deviation in offshore oil price bands, deepwater drilling rig day rates, or Brazilian real exchange volatility would shift the trajectory of pre-salt communication infrastructure investment. Forecasts reflect documented assumptions regarding LEO constellation deployment timelines, IEC 61850 adoption velocity, and ANP local content enforcement consistency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Floating Liquefied Natural Gas (FLNG) Market
Offshore Oil and Gas
Oil and Gas Downstream Market
Offshore Oil and Gas
Thailand Oil and Gas Downstream Market
Offshore Oil and Gas
East Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Asia Pacific Oil and Gas CAPEX Market
Offshore Oil and Gas
Europe Offshore Energy Market
Offshore Oil and Gas
East Africa Oil and Gas Downstream Market
Offshore Oil and Gas
FPSO Market
Offshore Oil and Gas
Offshore Drilling Riser Market
Offshore Oil and Gas
Kuwait Oil and Gas Downstream Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market
Offshore Oil and Gas
South America Offshore Energy Market
Offshore Oil and Gas
Indonesia Oil and Gas Upstream Market
Offshore Oil and Gas
Offshore Oilfield Services Market
Offshore Oil and Gas
Floating Production Systems (FPS) Market