
 United Kingdom Oil and Gas Market | 2026-2036
United Kingdom Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Oil and Gas Market Analytics
Maintenance and integrity management contracts are hardening into the core revenue layer for UK offshore operators. BP leverages its integrated service model across the Clair Ridge and ETAP hubs to sustain long-term field economics. Harbour Energy anchors its position through dominant control of the Forties pipeline system and associated infrastructure fees. Serica Energy specializes in acquiring mature North Sea assets and extending their productive life through targeted redevelopment.
The United Kingdom Oil and Gas sector encompasses the exploration, extraction, processing, and distribution of hydrocarbon resources across the UK Continental Shelf, with crude oil API gravities typically ranging from 34 to 40 degrees and natural gas containing up to 10 percent carbon dioxide in certain southern North Sea fields. The upstream segment dominates value generation through offshore platform and subsea tieback developments, though the midstream transportation category commands disproportionate margin stability through regulated tariff structures on pipeline and terminal assets. Downstream refining occupies a mature position with constrained capacity expansion, while oilfield services represents the fastest-adjusting segment as drillers and subsea contractors restructure fleets for decommissioning-heavy workloads.
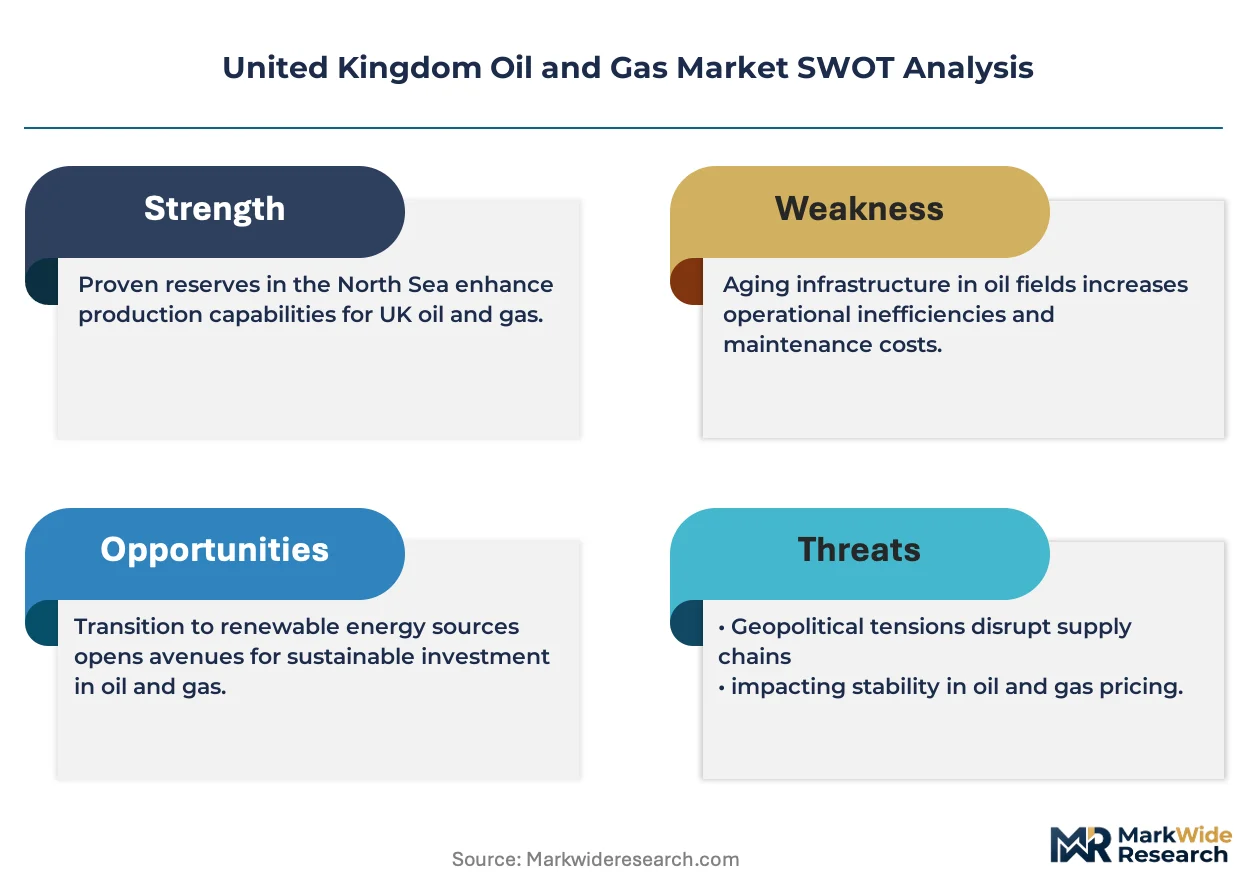
The North Sea Transition Authority enforces field development consent and decommissioning security arrangements that directly shape operator investment horizons and asset divestment timing. The Health and Safety Executive mandates offshore installation safety case requirements that influence platform modification scopes and maintenance expenditure levels. The Environment Agency regulates produced water discharge standards and atmospheric emissions limits that constrain operational flexibility across ageing facilities. Stakeholders must weigh the accelerating cost of regulatory compliance against the diminishing reserve base when sequencing final investment decisions on late-life assets.
Market Dynamics
The North Sea Transition Authority's decommissioning security arrangements are compressing investment horizons and accelerating asset handovers as operators recalculate late-life field economics against statutory cleanup liabilities.
Growth Catalysts
- Carbon Capture Integration:The UK government's cluster sequencing process for industrial decarbonization is creating new demand for repurposed pipeline infrastructure and depleted reservoir storage across the Humber and Scottish clusters.
- Offshore Wind Co-location:Shared logistics corridors and vessel fleets between oil and gas decommissioning and offshore wind installation are reducing marginal costs for both sectors in the Aberdeen energy corridor.
- Energy Profits Levy Modifications:The revised fiscal treatment of decommissioning expenditure is improving project returns for late-life asset operators and accelerating field redevelopment decisions.
Market Restraints
- Steel and Alloy Input Volatility:Specialized subsea grades and corrosion-resistant alloys face price instability tied to nickel and molybdenum supply concentration in Indonesian and Chilean processing facilities.
- Regulatory Friction:The Environment Agency's tightening produced water discharge standards are forcing premature well abandonment on marginal fields where retrofit treatment economics fail.
- Substitution Acceleration:Norwegian pipeline gas and LNG imports through Dragon and South Hook terminals are displacing indigenous UK Continental Shelf production in power generation feedstock decisions.
Strategic Opportunities
- Scottish Carbon Storage:The Acorn and Viking CCS projects offer first-mover positioning for operators with suitable saline aquifer and depleted gas field acreage in the central North Sea.
- Hydrogen Blending Infrastructure:Existing high-pressure transmission systems operated by National Gas present conversion pathways for hydrogen service that oil and gas engineering capabilities can capture.
- Decommissioning Export Services:UK contractors with North Sea execution experience are transferring project management methodologies to offshore Malaysia and West Africa where platform removal demand is emerging.
Industry Challenges
- Subsea Engineering Talent Crunch:The demographic cliff in subsea installation and inspection expertise is colliding with simultaneous demand from offshore wind interconnection projects.
- Legacy Platform Integration:Digital twin deployment on 1970s-era fixed installations requires sensor retrofit compatibility workarounds that consume disproportionate commissioning resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Oil and Gas Market |
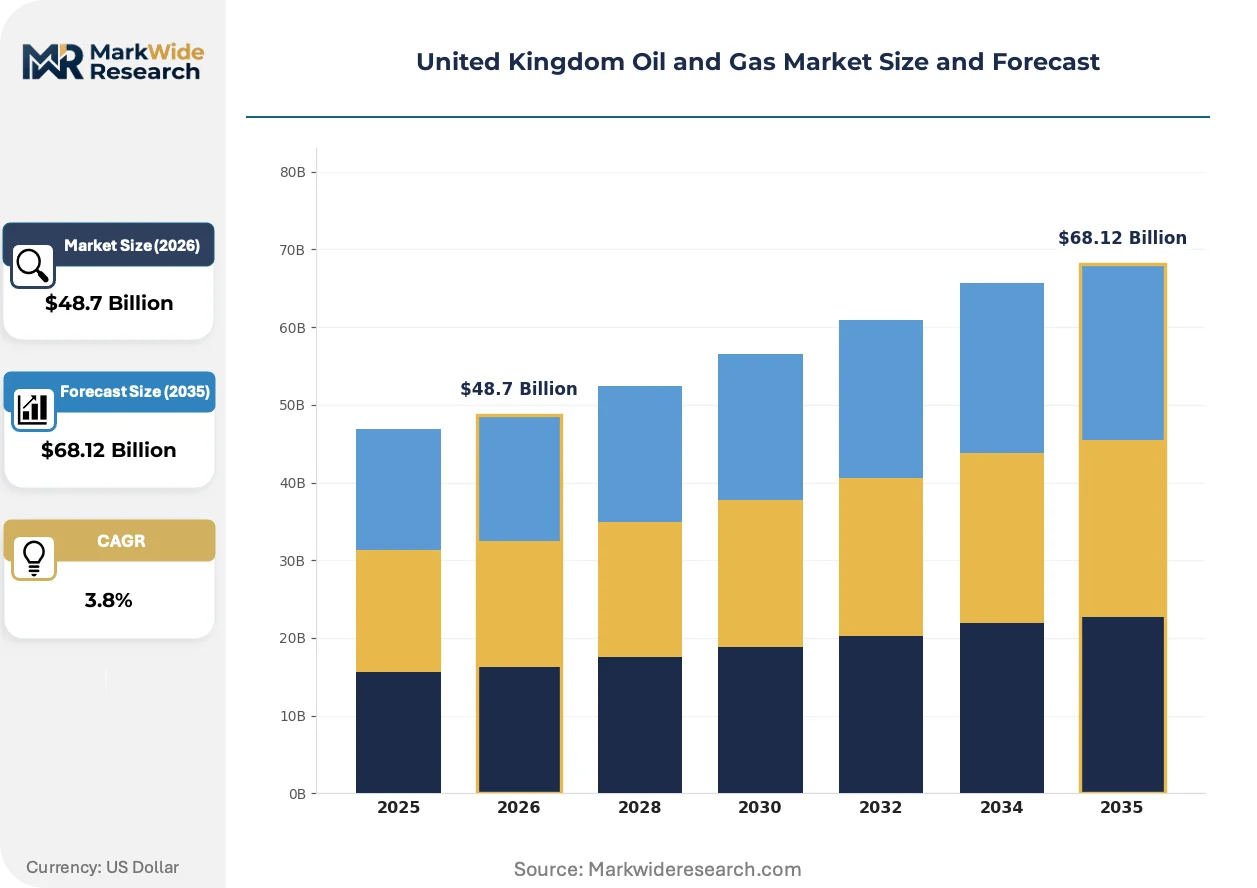
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $68.12 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Upstream, Midstream, Downstream, Oilfield Services Application: Exploration, Production, Transportation, Refining End User: Utilities, Industrial, Commercial, Residential Technology: Seismic, Drilling, Subsea, Refinery |
| Companies Covered | BP, Shell, Harbour Energy, TotalEnergies, Equinor, EnQuest, Serica Energy, Ithaca Energy, INEOS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Oil and Gas Market Evolving Landscape
Electrification of offshore platforms and autonomous subsea inspection systems are compressing operational expenditure structures while regulatory carbon accounting forces transparency through the supply chain.
Subsea power distribution and variable speed drive technology is expanding into brownfield tieback developments where platform electrification eliminates offshore gas turbine fuel consumption. Harbour Energy and other operators with clustered assets are adopting shared power from shore infrastructure to reduce Scope 1 emissions intensity. This architecture is expanding into marginal field developments previously uneconomic under combustion-based power assumptions.
The North Sea Transition Authority's revised flaring and venting consents are mandating continuous emissions monitoring and punitive fiscal exposure for non-compliance events. Operators must now install methane detection arrays and submit verified atmospheric discharge data quarterly. This enforcement regime is accelerating investment in vapor recovery units and closed-flare systems on ageing facilities with legacy atmospheric venting designs.
Buyer consolidation among North Sea midstream offtakers is compressing contracting timelines and unbundling traditional production-handling agreements. Major terminals at Sullom Voe and Flotta are now procuring crude segregation and tankage services through discrete spot-market mechanisms rather than integrated field development packages. This fragmentation is most pronounced in the northern North Sea where Brent benchmark-linked grades face disintermediation pressure from trading houses with direct producer relationships.
United Kingdom Oil and Gas Market Segmentation
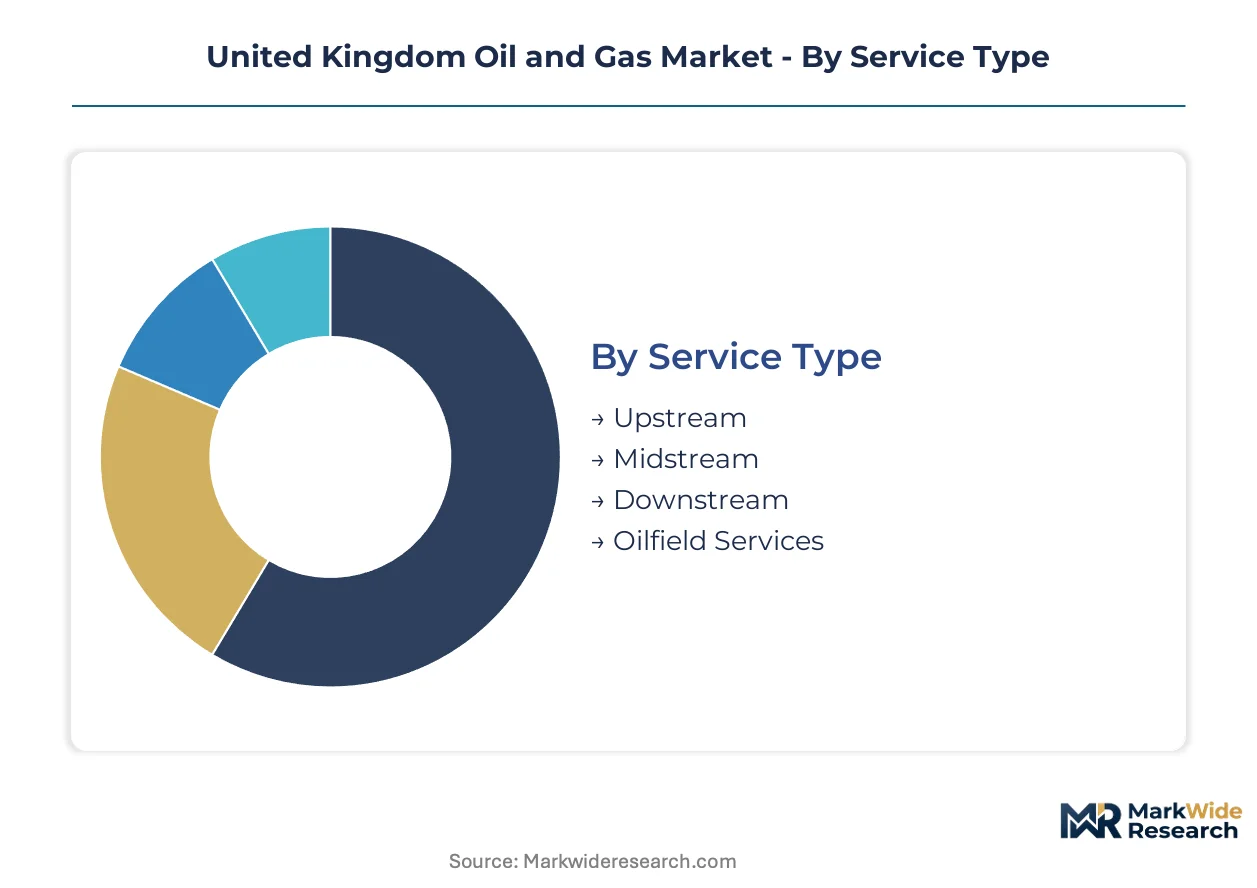
Segmentation in the United Kingdom Oil and Gas Market reveals how capital allocation priorities diverge across the asset lifecycle. Understanding these divisions helps operators align service procurement with regulatory timelines and decommissioning obligations.
Service Type:
Upstream operators prioritize reserve replacement economics while midstream players chase tariff stability through regulated infrastructure.
- Upstream:Exploration and production activities across the UK Continental Shelf generate value through offshore platform developments and subsea tieback installations. Demand concentrates in the northern North Sea and west of Shetland where Clair Ridge and ETAP hubs sustain field economics against statutory decommissioning timelines.
- Midstream:Pipeline transportation and terminal operations command margin stability through regulated tariff structures on assets like the Forties pipeline system. Investment gravitates toward infrastructure repurposing for carbon capture and hydrogen blending as the energy transition accelerates.
- Downstream:Refining and processing operations occupy mature positions with constrained capacity expansion. Facilities at Grangemouth and Fawley face feedstock competition from Norwegian pipeline gas and LNG imports.
- Oilfield Services:Drilling, subsea contracting, and decommissioning execution represent the fastest-adjusting segment as contractors restructure fleets for platform removal workloads.
Upstream leads volumes today; Oilfield Services is gaining share fastest.
Application:
Application segments track hydrocarbon movement from reservoir to market, with each stage carrying distinct regulatory and capital intensity profiles.
- Exploration:Seismic surveying and appraisal drilling target remaining prospects in mature basins. Activity clusters west of Shetland and in the central North Sea where the North Sea Transition Authority issues field development consents.
- Production:Extraction operations span fixed platforms, floating facilities, and subsea tiebacks. Brownfield redevelopment dominates as operators extend productive life of ageing assets through targeted investment.
- Transportation:Pipeline networks and marine terminals handle crude segregation and tankage services. Spot-market procurement mechanisms are displacing integrated field development packages at northern terminals.
- Refining:Downstream processing converts raw hydrocarbons into transport fuels and petrochemical feedstocks. Capacity constraints limit expansion as imports capture power generation feedstock decisions.
Production commands current revenue share; Transportation infrastructure is expanding most quickly through repurposing investments.
End User:
End user categories reflect divergent procurement patterns across power generation, manufacturing, and distributed consumption.
- Utilities:Power generators and grid operators procure natural gas for electricity production and peaking capacity. Substitution pressure from Norwegian pipeline gas and LNG imports through Dragon and South Hook terminals is displacing indigenous UK Continental Shelf supply.
- Industrial:Manufacturing and petrochemical facilities consume hydrocarbons as process feedstocks and thermal energy sources. Cluster sequencing for industrial decarbonization is creating new demand for repurposed pipeline infrastructure.
- Commercial:Business and institutional consumers purchase refined products for heating and transport applications. Efficiency improvements and electrification are compressing growth trajectories.
- Residential:Household heating and cooking demand concentrates in regions with legacy gas distribution networks. Heat pump deployment and building efficiency standards are eroding traditional consumption patterns.
Utilities anchor current offtake volumes; Industrial end users are climbing the fastest through carbon capture integration.
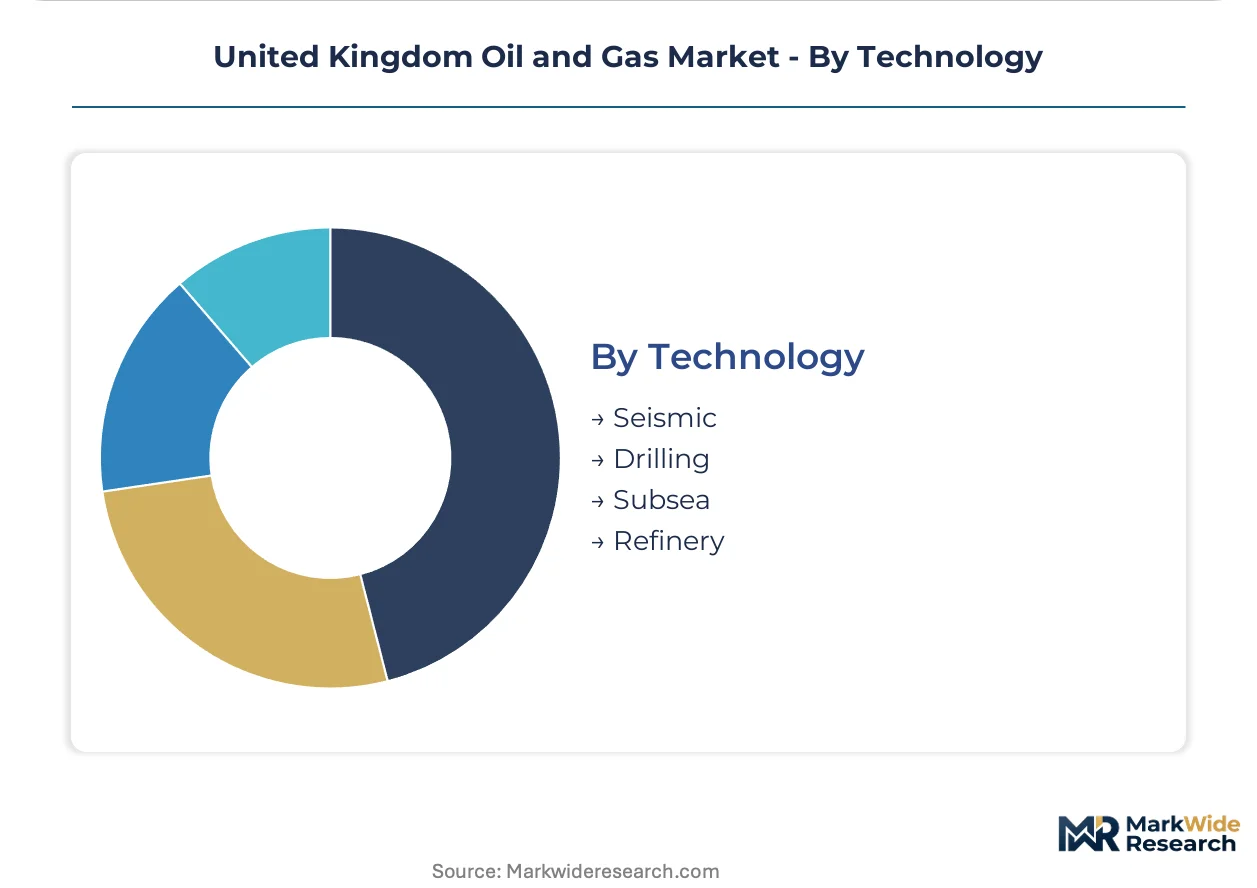
Technology:
Technology segments differentiate by engineering complexity and capital intensity, with digital and electrification trends reshaping investment priorities.
- Seismic:Advanced imaging and subsurface characterization technologies target remaining exploration prospects. Processing capabilities are improving recovery factors from mature fields.
- Drilling:Extended-reach and horizontal drilling technologies access bypassed reserves from existing infrastructure. Rig availability constraints are elevating day rates for high-specification units.
- Subsea:Subsea power distribution and variable speed drive technology is expanding into brownfield tieback developments. Electrification eliminates offshore gas turbine fuel consumption and reduces Scope 1 emissions intensity for clustered assets.
- Refinery:Catalytic cracking, hydroprocessing, and emissions control systems process crude into refined products. Carbon accounting transparency is forcing investment in vapor recovery and closed-flare systems.
Drilling technology leads deployment today; Subsea electrification is gaining share fastest through emissions reduction mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redirecting capital toward jurisdictions where decommissioning security arrangements and emissions compliance costs diverge most sharply from UK Continental Shelf baselines. Operators now sequence asset divestments based on statutory cleanup liability timelines rather than pure reserve economics.
Scotland
North Sea production clusters around Aberdeen and the central North Sea generate the majority of UK Continental Shelf output. The North Sea Transition Authority enforces field development consents and decommissioning security arrangements that compress investment horizons for mature assets. The Scottish Carbon Capture and Storage cluster at St Fergus anchors industrial decarbonization demand for repurposed pipeline infrastructure.
England
Southern North Sea gas fields with elevated carbon dioxide content face premature abandonment under tightening Environment Agency discharge standards. The Humber industrial cluster sequencing process creates new demand for carbon capture integration and hydrogen blending infrastructure. Teesside and Humberside terminals handle crude segregation and tankage services through increasingly fragmented spot-market mechanisms.
Norway
Pipeline gas exports from the Norwegian Continental Shelf displace indigenous UK production in power generation feedstock decisions. Equinor operates integrated field developments with lower carbon intensity benchmarks than ageing UK facilities. The Johan Sverdrup electrified platform architecture demonstrates production economics that UK brownfield redevelopment struggles to match.
Netherlands
Rotterdam refining and petrochemical complexes compete for North Sea crude feedstock against UK downstream facilities at Grangemouth and Fawley. The Port of Rotterdam's carbon capture and storage import terminal infrastructure offers alternative offtake routes for UK producers. Dutch gas trading hubs at Title Transfer Facility increasingly price marginal UK Continental Shelf production out of continental power generation markets.
United Kingdom Oil and Gas Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated majors controlling infrastructure-heavy midstream assets while independent operators concentrate on late-life field redevelopment. The upstream segment exhibits tiered consolidation around pipeline system ownership and hub-and-spoke production architectures. Three archetypes dominate: integrated majors with captive infrastructure networks, independent producers specializing in mature asset acquisition, and service contractors restructuring for decommissioning execution. Competitive moves center on portfolio divestment sequencing and shared power-from-shore infrastructure partnerships.
Among UK-based operators, BP, Harbour Energy, and Serica Energy exemplify distinct strategic positioning within this tripartite structure. BP anchors the integrated major archetype through its Clair Ridge and ETAP hub operations. Harbour Energy occupies the infrastructure consolidator position through its Forties pipeline system control. Serica Energy represents the mature asset specialist model through targeted redevelopment of late-life North Sea properties.
| Leading Market Players |
|---|
| BP |
| Shell |
| Harbour Energy |
| TotalEnergies |
| Equinor |
| EnQuest |
| Serica Energy |
| Ithaca Energy |
| INEOS |
| Others |
Value Network & Pricing Analysis
The North Sea Transition Authority's methane emissions monitoring mandate gates qualified supply access and premium-tier pricing for decommissioning contractors. Operators lacking certified low-emission vessel fleets face exclusion from high-margin platform removal contracts while compliant service providers capture tariff premiums tied to verified carbon accounting.
Pricing Analysis
Capacity additions in Norway's electrified platform architecture are reshaping price floors for UK brownfield redevelopment services. Project-based contracting dominates decommissioning execution, with price differentiation driven by vessel emission certification tiers and integrated waste handling capabilities. Cost compression in standard-tier drilling services is intensifying because rig oversupply from North Sea wind farm construction overlaps with oil and gas demand troughs. Independent operators show highest price sensitivity due to thin reserve-backed borrowing bases, while integrated majors absorb premiums for guaranteed slot access.
Supply Chain Analysis
Specialized subsea alloy supply rests on Indonesian nickel processing and Chilean molybdenum concentrate operations. UK contractors draw from German high-pressure valve manufacturers, Norwegian subsea engineering houses, and US Gulf Coast blowout preventer fabricators. Single-source vulnerability concentrates in corrosion-resistant alloy forging capacity where three European mills control global output. Distribution runs through Aberdeen service clusters for platform maintenance, with heavy-lift vessel chartering coordinated through Rotterdam and Hamburg broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK oil and gas market represents a late-cycle quality story where carbon-capture-ready infrastructure commands scarcity premiums. Industrial cluster sequencing toward net-zero specifications is redirecting capital toward pipeline repurposing and saline aquifer storage assets.
For Market Incumbents: To counter Norwegian pipeline gas displacement in power generation feedstock decisions, Harbour Energy and BP should deepen backward integration into carbon capture infrastructure at St Fergus and Humber clusters. Certification investment in ISO 14064-compliant methane monitoring systems will defend tariff premiums as the Environment Agency tightens atmospheric discharge enforcement. For New Entrants and Emerging Players: Digital platform-based vessel chartering offers the lowest-friction entry path into spot-market decommissioning logistics. White-space targets cluster around autonomous subsea inspection services for ageing 1970s platforms and vapor recovery unit retrofit installation. The most penetrable segment is marginal field operators lacking in-house engineering capability, best accessed through fixed-fee platform modification contracts bundled with regulatory compliance reporting. For Investors and Strategic Acquirers: Roll-up economics work for decommissioning specialists because the North Sea Transition Authority's compressed cleanup timelines are forcing asset handovers from capital-constrained independents. Long-term viability hinges on exposure to repurposable pipeline infrastructure rather than pure production decline curves. The signal to watch is Forties pipeline system tariff renegotiation outcomes, which will indicate whether midstream incumbents can sustain infrastructure fee structures against carbon-capture conversion capital demands.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Acorn and Viking CCS projects anchor first-mover positioning for depleted gas field operators. |
| Power-from-Shore Infrastructure | Shared electrification partnerships between Harbour Energy and clustered assets reduce Scope 1 emissions intensity. |
| Decommissioning Export Services | UK contractors transfer North Sea platform removal methodologies to emerging offshore Malaysia demand. |
| Hydrogen Blending Conversion | National Gas transmission systems present engineering capture opportunities for oil and gas service providers. |
| Autonomous Subsea Inspection | Digital twin deployment on ageing facilities compresses operational expenditure through reduced vessel chartering. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both structured market sizing and unstructured strategic intent. Primary engagement spanned North Sea Transition Authority regulatory leads, Harbour Energy and Serica Energy asset managers, Aberdeen-based drilling contractors, and Environment Agency compliance officers. Secondary validation drew from OGA production statistics, NSTA decommissioning estimates, BEIS energy transition disclosures, and pipeline operator tariff filings. Bottom-up field-level cost modeling and top-down sector revenue aggregation were cross-checked for consistency.
Historical reference periods anchored the projection horizon through trailing production decline curves and announced decommissioning expenditure schedules. Segmentation modeling spanned service type, application stage, end-user category, and technology tier across the analysis window. CAGRs were derived from expenditure phasing tied to statutory cleanup timelines and carbon capture cluster sequencing announcements. Forecast inputs incorporated vessel day-rate trajectories and alloy price volatility indices from commodity exchanges.
The model assumes a particular technology adoption path; alternative pathways for offshore platform electrification would alter the outlook for gas turbine maintenance demand and associated service contracting. Forecasts reflect assumptions about regulatory enforcement continuity and North Sea Transition Authority consent timing. Material deviation in Energy Profits Levy treatment or Environment Agency discharge standard acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Gabon Oil and Gas Downstream Market
Offshore Oil and Gas
Argentina Oil and Gas Downstream Market
Offshore Oil and Gas
United Kingdom LNG Bunkering Market
Offshore Oil and Gas
Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Drilling Market
Offshore Oil and Gas
Gulf of Mexico Oil & Gas Decommissioning Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market
Offshore Oil and Gas
Floating Production Storage and Offloading Market
Offshore Oil and Gas
South America Offshore Seismic Survey Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
Central Asia Oil and Gas Upstream Market
Offshore Oil and Gas
Floating Liquefied Natural Gas (FLNG) Market
Offshore Oil and Gas
Turkmenistan Oil and Gas Upstream Market
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
North America Floating Offshore Wind Power Market