
 Southeast Asia Offshore Seismic Survey Market | 2026-2036
Southeast Asia Offshore Seismic Survey Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Offshore Seismic Survey Market Analytics
Transition to high-density broadband seismic acquisition is reconfiguring how subsurface data is captured and processed across Southeast Asian waters. Schlumberger Ltd leverages proprietary nodal systems to anchor its position in complex geologies off Myanmar and Vietnam. Fugro NV sustains competitive differentiation through integrated site-characterization capabilities that span seabed mapping through reservoir monitoring. PGS ASA specializes in multisensor streamer technology, dominating deep-tow operations in the South China Sea margins.
Offshore seismic survey denotes the systematic acquisition of acoustic reflection data from sub-seafloor geological formations, typically employing tuned air-gun arrays emitting 10-250 Hz pressure waves captured by hydrophone streamers or ocean-bottom nodes, to generate structural maps for hydrocarbon prospect evaluation. 3D seismic services command the largest share of contracted value, as dense spatial sampling reduces exploration risk in structurally complex basins. QI services represent the fastest-expanding category, driven by national oil companies demanding quantitative rock-property estimates to optimize development drilling locations. Subsurface imaging retains concentrated margin pools where proprietary full-waveform inversion algorithms create vendor stickiness.
Indonesia's SKK Migas, Malaysia's Petronas technical standards, and Vietnam's PetroVietnam licensing frameworks collectively shape equipment-certification requirements and local-content obligations for seismic contractors. These regulators enforce environmental-impact assessments for marine mammal mitigation, directly influencing survey timing and air-gun specifications in sensitive bioregions. Stakeholders must monitor evolving carbon-accounting rules for offshore operations, as scope-emissions disclosure requirements begin penetrating procurement criteria for exploration services.
Market Dynamics
High-density broadband seismic acquisition is compressing survey timelines while expanding subsurface resolution, forcing contractors to reconfigure vessel fleets and processing workflows around nodal streamer architectures.
Growth Catalysts
- SKK Migas cost-recovery relaxation:Indonesia's upstream regulator has loosened fiscal terms for frontier drilling, directly stimulating seismic contracting in the Natuna and North Sumatra basins.
- Deepwater exploration budgets:National oil companies across Indonesia, Vietnam, and Malaysia are redirecting capital toward untapped deepwater blocks, sustaining demand for 3D and 4D acquisition services.
- Quantitative interpretation services:PetroVietnam and Petronas technical teams now require rock-property estimates to optimize development drilling, expanding the addressable market for QI processing.
Market Restraints
- Marine mammal mitigation protocols:Indonesia's environmental-impact assessment requirements enforce seasonal survey windows and air-gun specification limits, compressing viable operating calendars.
- Specialized vessel scarcity:The regional fleet of deep-tow capable seismic ships concentrates among a handful of contractors, creating bottleneck risk for multi-vessel campaigns.
- Carbon-accounting disclosure pressure:Scope-emissions tracking requirements are penetrating procurement criteria, adding compliance overhead without corresponding fee recovery mechanisms.
Strategic Opportunities
- Myanmar frontier acreage:Underexplored offshore blocks present white-space potential for contractors with proprietary nodal systems suited to complex geologies.
- Ocean-bottom node convergence:Integration of autonomous underwater vehicle deployment with nodal retrieval is reducing seabed equipment costs and enabling repeatability for 4D monitoring.
- Site-characterization bundling:Contractors can capture adjacent value pools by extending offerings from seabed mapping through reservoir monitoring, mirroring integrated service models proven in the North Sea.
Industry Challenges
- Full-waveform inversion talent scarcity:Proprietary subsurface imaging algorithms require specialized geophysicists, and regional training pipelines are insufficient to meet contractor hiring needs.
- Multi-client data library amortization:Pre-funding seismic programs demands extended sales cycles to national oil companies with fragmented budget approval hierarchies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Offshore Seismic Survey Market |
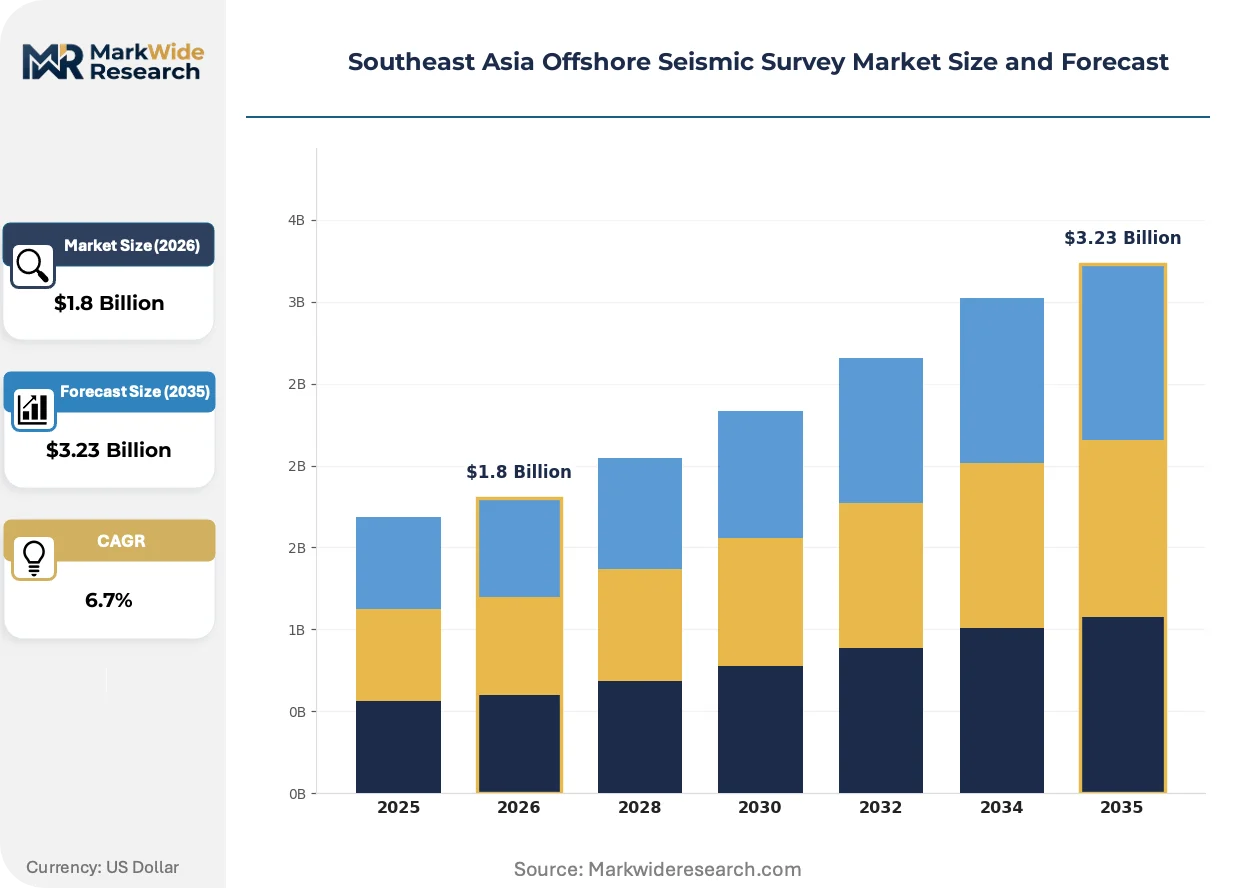
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: 2D Seismic, 3D Seismic, QI Services, Subsurface Imaging Technology: Air Gun, Ocean Bottom Seismometers, Streamers, Sensors End User: Oil & Gas Companies, Government Agencies, Mining Firms, Research Institutions Application: Exploration, Reservoir Characterization, Environmental Monitoring, Site Assessment |
| Companies Covered | Halliburton Company, Schlumberger Ltd, Fugro NV, PGS ASA, China Oilfield Services Limited, BGP Inc, CGG SA, TGS ASA, Shearwater GeoServices AS, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Offshore Seismic Survey Market Evolving Landscape
Acquisition technology is compressing the trade-off between survey speed and subsurface fidelity, while regulatory pressure on marine operations is forcing simultaneous investment in emissions tracking and biological monitoring systems.
Nodal ocean-bottom seismic technology is digitizing how contractors capture azimuth-rich data in obstructed or complex geologies. Indonesia's Pertamina and Vietnam's PetroVietnam exploration divisions are adopting these systems for basalt-covered prospects where conventional streamers fail. The technology is digitizing project economics by enabling single-vessel operations that previously required dual-source configurations.
Indonesia's environmental ministry has mandated real-time marine mammal observation protocols for all seismic operations in biologically sensitive zones. This regulation is extending survey timelines by 15-30 percent where cetacean activity is detected. Contractors operating in the Natuna basin are responding with passive acoustic monitoring systems that reduce reliance on visual observer coverage.
Service unbundling is fragmenting how national oil companies contract seismic work. PetroVietnam and Petronas technical teams increasingly separate acquisition from processing, awarding imaging contracts to specialized vendors with proprietary inversion algorithms. Vietnam's central licensing areas exhibit the most pronounced shift, with QI processing contracts now regularly awarded 6-12 months after field data delivery.
Southeast Asia Offshore Seismic Survey Market Segmentation
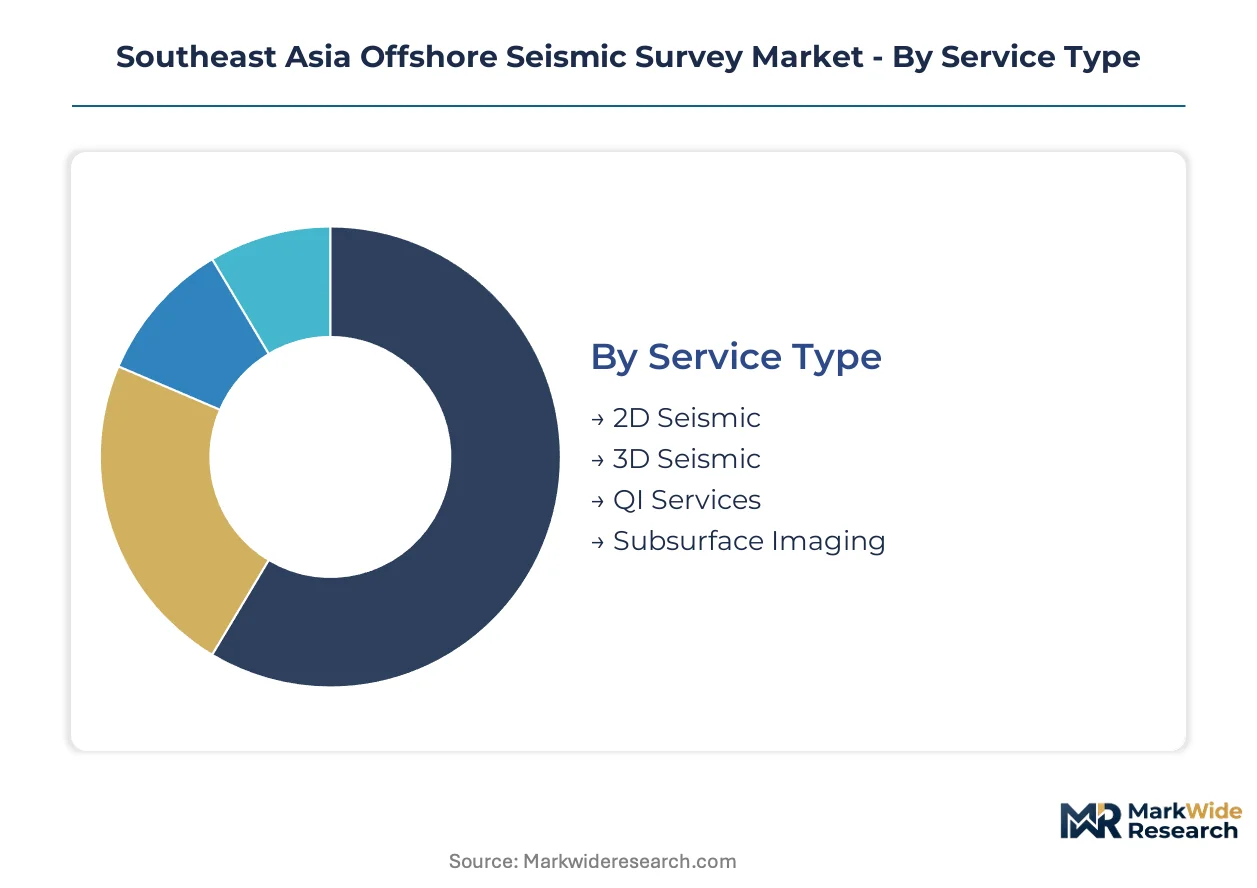
Service differentiation in Southeast Asian waters follows the technical complexity of subsurface targets. Contractors align capabilities to basin-specific challenges, from shallow-water streamer work through deep-node deployments in obstructed geologies.
Service Type:
Contractors deploy distinct acquisition and processing methodologies matched to exploration risk profiles and development-stage decisions.
- 3D Seismic:Dense spatial sampling through multi-streamer or nodal configurations generates volumetric subsurface models. Indonesia's North Sumatra and Natuna basins concentrate contracting here, as national oil companies demand reduced dry-hole risk in structurally complex blocks.
- QI Services:Quantitative interpretation delivers rock-property estimates from seismic amplitudes, directly informing PetroVietnam and Petronas drilling-location optimization. This segment is climbing the fastest as state operators separate acquisition from specialized processing contracts.
- 2D Seismic:Regional reconnaissance surveys across frontier acreage employ sparse line spacing for initial basin evaluation.
- Subsurface Imaging:Proprietary full-waveform inversion algorithms create vendor stickiness in margin-concentrated processing workflows.
Established volume favors 3D Seismic; emerging adoption favors QI Services.
Technology:
Equipment selection hinges on water depth, seabed obstruction, and repeatability requirements for reservoir monitoring.
- Streamers:Towed hydrophone arrays remain the workhorse for open-water 3D acquisition, with PGS ASA multisensor configurations dominating deep-tow operations in South China Sea margins where source-ghost removal demands broadband fidelity.
- Ocean Bottom Seismometers:Autonomous nodal systems capture azimuth-rich data in basalt-covered or platform-obstructed prospects where conventional streamers fail. Pertamina and PetroVietnam exploration divisions are adopting these for Indonesia's volcanic provinces.
- Air Gun:Tuned pressure-wave sources operate at 10-250 Hz, with specifications constrained by Indonesia's marine mammal mitigation protocols.
- Sensors:Accelerometer and hydrophone combinations enable multi-component recording for shear-wave analysis in gas-cloud environments.
Deployment scale favors Streamers; technology transition favors Ocean Bottom Seismometers.
End User:
Budget authority and technical specifications diver sharply between commercial operators and state-directed programs.
- Oil & Gas Companies:International and national oil companies commission the majority of contracted value, with SKK Migas cost-recovery relaxation directly stimulating Indonesian frontier exploration spending.
- Government Agencies:Malaysia's Petronas technical standards and Vietnam's licensing frameworks shape equipment-certification requirements and local-content obligations for all contractors operating in their waters.
- Mining Firms:Seabed mineral prospecting generates intermittent demand for site-characterization surveys ahead of extraction licensing.
- Research Institutions:Academic programs contribute modest contracting for crustal-scale imaging and geohazard assessment.
Contract concentration favors Oil & Gas Companies; regulatory influence favors Government Agencies.
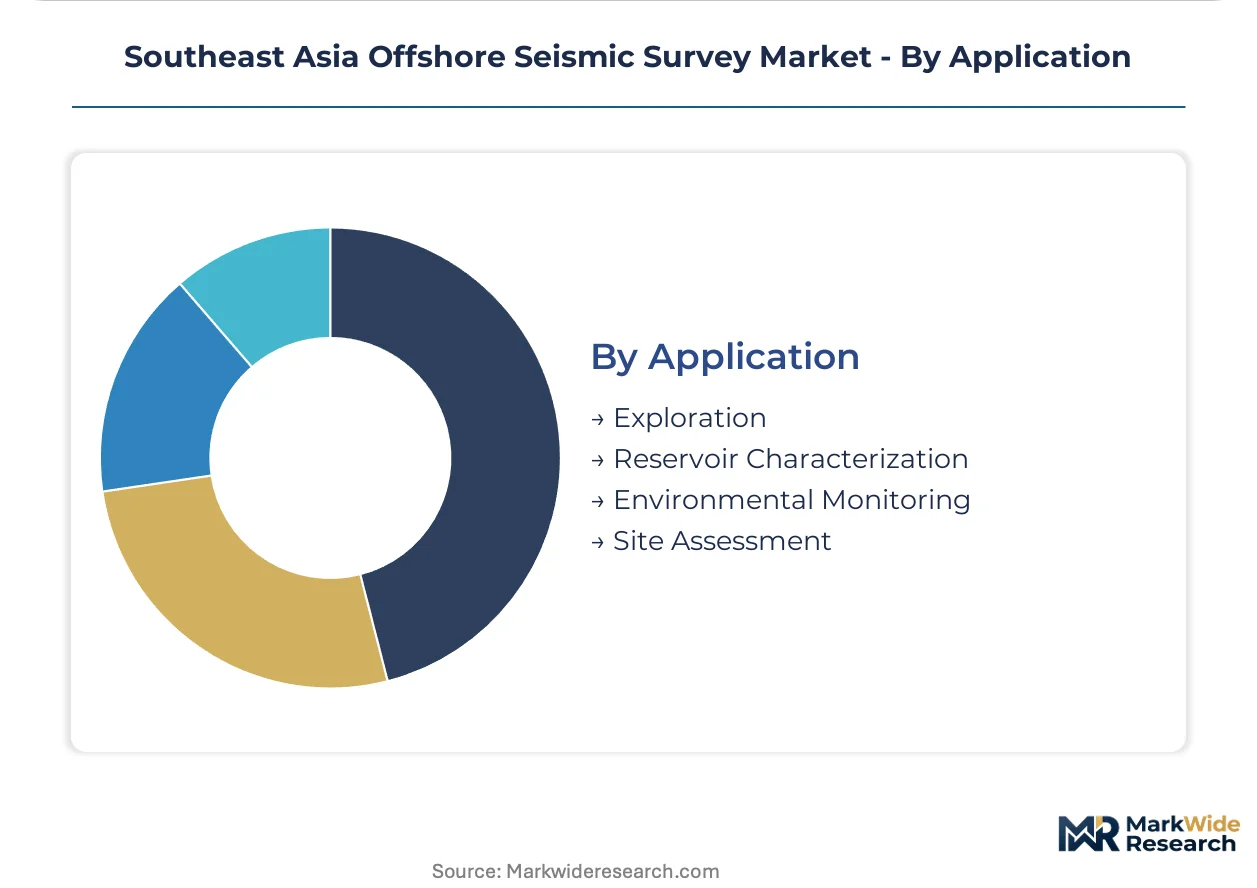
Application:
Project scope spans the full hydrocarbon value chain from frontier screening through production optimization.
- Exploration:Greenfield seismic programs in Indonesia's relaxed fiscal blocks and Myanmar frontier acreage drive vessel utilization, with 3D acquisition reducing geological uncertainty ahead of drilling commitments.
- Reservoir Characterization:4D time-lapse monitoring of producing fields requires repeatable ocean-bottom installations, with repeat surveys tracking fluid movement to inform infill drilling.
- Environmental Monitoring:Indonesia's real-time marine mammal observation mandates extend survey timelines by 15-30 percent where cetacean activity is detected, forcing investment in passive acoustic monitoring systems.
- Site Assessment:Integrated seabed mapping through reservoir monitoring captures adjacent value pools for contractors with bundled service capabilities.
Revenue scale favors Exploration; contract longevity favors Reservoir Characterization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in marine seismic equipment and data processing services flow predominantly from European and North American technology centers into Southeast Asian exploration waters, with Indonesia, Vietnam, and Malaysia absorbing the majority of contracted vessel days.
Indonesia
SKK Migas cost-recovery relaxation for frontier drilling has unlocked exploration budgets across the Natuna and North Sumatra basins. The upstream regulator now permits faster depreciation of seismic pre-investment against future production-sharing contract revenues. Jakarta-based Pertamina exploration divisions concentrate contracting in volcanic provinces where ocean-bottom nodes displace conventional streamers.
Vietnam
PetroVietnam technical teams separate acquisition from processing contracts, extending sales cycles but expanding the addressable market for quantitative interpretation specialists. The national oil company's licensing frameworks enforce local-content obligations on foreign seismic contractors operating in central offshore blocks. Ho Chi Minh City serves as the procurement hub where state-directed exploration programs coordinate vessel chartering.
Malaysia
Petronas deepwater exploration budgets sustain demand for 3D and 4D acquisition services in untapped blocks off Sabah and Sarawak. The national oil company's technical standards shape equipment-certification requirements for all contractors in Malaysian waters. Kuala Lumpur anchors regional headquarters for seismic service providers targeting shared Malay Basin prospects.
Myanmar
Underexplored offshore blocks present white-space contracting potential for contractors with proprietary nodal systems suited to complex geologies. The country's petroleum regulator has issued limited exploration licenses following political transition, constraining near-term vessel utilization. Yangon functions as the administrative center where frontier acreage awards await technical evaluation.
Thailand
Mature Gulf of Thailand fields sustain 4D time-lapse monitoring contracts for reservoir characterization and infill drilling optimization. The Department of Mineral Fuels enforces environmental-impact assessments that compress viable operating calendars during cetacean migration periods. Bangkok-based procurement offices coordinate repeat survey programs across producing assets.
Southeast Asia Offshore Seismic Survey Market Competitive Landscape
On the supply side, the industry is consolidating around integrated service providers capable of bundling seabed mapping through reservoir monitoring. The regional vessel fleet concentrates among a handful of contractors with deep-tow capable seismic ships, creating bottleneck risk for multi-vessel campaigns. Two strategic archetypes dominate: technology-anchored specialists with proprietary acquisition systems, and integrated site-characterization providers with bundled service portfolios. Competitive moves center on fleet reconfiguration around nodal streamer architectures and strategic partnerships for autonomous underwater vehicle deployment.
Among technology-anchored specialists, Schlumberger Ltd and PGS ASA occupy positions defined by proprietary hardware differentiation. Schlumberger represents the nodal-system archetype with deployments suited to complex geologies off Myanmar and Vietnam. PGS ASA exemplifies the multisensor-streamer tier, with configurations dominating deep-tow operations in South China Sea margins. Fugro NV anchors the integrated-site-characterization archetype, extending capabilities from seabed mapping through reservoir monitoring.
| Leading Market Players |
|---|
| Halliburton Company |
| Schlumberger Ltd |
| Fugro NV |
| PGS ASA |
| China Oilfield Services Limited |
| BGP Inc |
| CGG SA |
| TGS ASA |
| Shearwater GeoServices AS |
| Others |
Value Network & Pricing Analysis
Marine mammal mitigation protocol compliance costs determine both pricing tier spreads and supply chain shape across Southeast Asian seismic contracting. Indonesia's seasonal survey windows and air-gun specification limits compress viable operating calendars, forcing contractors to amortize fixed vessel costs across fewer billable days and pushing price differentiation toward equipment-generation tiers.
Pricing Analysis
Current-generation broadband nodal systems command substantial premiums over legacy streamer configurations and early-generation ocean-bottom nodes. Pricing stratifies across premium, standard, and economy tiers based on acquisition density specifications and proprietary processing algorithm access. Cost compression in the standard tier is intensifying because PetroVietnam and Petronas technical teams increasingly separate acquisition from processing contracts. National oil companies exhibit the highest price sensitivity, while international operators with frontier drilling commitments absorb premium pricing for reduced dry-hole risk.
Supply Chain Analysis
Extended payment terms from national oil companies with fragmented budget approval hierarchies strain contractor working capital requirements across multi-client data library programs. Equipment manufacturing concentrates in Norway, the United States, and Singapore, with seismic vessel hull construction drawing from South Korean and Chinese shipyards. The regional fleet rests on specialized air-gun arrays and streamer cable assemblies sourced from single-source vendors in Europe. Tariff exposure on Chinese-manufactured components creates vulnerability for contractors reconfiguring fleets around nodal architectures. Distribution runs through Jakarta, Ho Chi Minh City, and Kuala Lumpur procurement hubs where state-directed exploration programs coordinate vessel chartering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical lows as deepwater exploration budgets redirect capital toward untapped blocks across Indonesia, Vietnam, and Malaysia. The cyclical driver is SKK Migas cost-recovery relaxation unlocking frontier drilling pre-investment.
For Market Incumbents: Build proprietary full-waveform inversion algorithm moats through targeted geophysicist hiring in regional training pipelines. Defensive consolidation moves center on fleet reconfiguration around nodal streamer architectures and strategic partnerships for autonomous underwater vehicle deployment. The emerging threat is service unbundling fragmenting how national oil companies contract seismic work. Vertical integration into integrated site-characterization capabilities from seabed mapping through reservoir monitoring provides defensive leverage. For New Entrants and Emerging Players: Myanmar frontier acreage underpenetration offers white-space contracting potential for contractors with proprietary nodal systems suited to complex geologies. The most penetrable segment is quantitative interpretation services, where PetroVietnam and Petronas technical teams now require rock-property estimates separated from acquisition contracts. A specialized go-to-market angle targets 4D time-lapse monitoring of producing fields in Thailand's mature Gulf of Thailand assets. For Investors and Strategic Acquirers: Technology-anchored specialists with proprietary acquisition hardware represent the primary acquisition target archetype. Long-term viability over the coming decade hinges on contractor ability to bundle seabed mapping through reservoir monitoring capabilities. The signal to watch is carbon-accounting disclosure requirements penetrating procurement criteria for exploration services, which would accelerate consolidation around integrated providers with emissions tracking infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Reconfiguration Around Nodal Architectures | Enables single-vessel operations in Indonesia's volcanic provinces where conventional streamers fail. |
| Autonomous Underwater Vehicle Partnership | Reduces seabed equipment costs and enables repeatability for 4D monitoring in Vietnam's central blocks. |
| Integrated Site-Characterization Bundling | Captures adjacent value pools from seabed mapping through reservoir monitoring mirroring North Sea models. |
| Proprietary Full-Waveform Inversion Investment | Creates vendor stickiness in margin-concentrated processing workflows for complex geologies. |
| Passive Acoustic Monitoring System Deployment | Responds to Indonesia's real-time marine mammal observation mandates extending survey timelines. |
Research Methodology
A spread of perspectives from seismic vessel operators, national oil company exploration managers, upstream regulator technical staff, and marine equipment procurement leads converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation from SKK Migas cost-recovery circulars, PetroVietnam licensing framework documents, Petronas technical standards publications, and regional trade data on marine seismic equipment imports. Bottom-up vessel utilization estimates and top-down exploration budget allocations were triangulated to cross-check market sizing.
Demand-supply balance dynamics across the analysis window anchored the forecast framework, with segmentation dimensions spanning service type, technology generation, water depth tier, and end-user budget authority. CAGRs were derived from modeled vessel day rates, equipment deployment costs, and processing contract values across the projection horizon. Industry-specific forecast inputs included SKK Migas frontier drilling incentive trajectories and PetroVietnam quantitative interpretation adoption curves.
Practitioners should monitor regulatory shifts in marine mammal mitigation protocols, carbon-accounting disclosure mandates, and national oil company budget reallocation patterns for early signals of trajectory revision. Forecasts reflect documented assumptions on vessel fleet availability and exploration licensing timelines. Macroeconomic volatility in oil prices, regulatory tightening on scope emissions, or technological disruption in autonomous seismic acquisition would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
North America Floating Offshore Wind Power Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market
Offshore Oil and Gas
Oil Rig Market
Offshore Oil and Gas
LNG Satellite Station Market
Offshore Oil and Gas
Deep Water Drilling Market
Offshore Oil and Gas
Canada Oil and Gas Downstream Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Midstream Market
Offshore Oil and Gas
Middle East Offshore MRO Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Upstream Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
Floating Liquefied Natural Gas (FLNG) Market
Offshore Oil and Gas
Argentina Oil and Gas Downstream Market
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
Asia-Pacific Floating Production Systems Market
Offshore Oil and Gas
Asia Pacific Oil and Gas CAPEX Market