
 Iran Oil and Gas Downstream Market | 2026-2036
Iran Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Oil and Gas Downstream Market Foresight
Multi-sourced equipment procurement for refinery modernization is rebalancing toward domestic fabrication partnerships as international sanctions constrain cross-border supply chains. National Iranian Oil Refining and Distribution Company anchors Iran's fuel distribution network through its monopoly on product allocation across provincial depots. Persian Gulf Star Oil Company leverages condensate splitting technology to produce Euro-5 gasoline, differentiating its output from older hydroskimming facilities. Pars Oil Company competes in the lubricant segment through brand recognition among Iranian commercial fleet operators.
Iran oil and gas downstream encompasses refining, petrochemical synthesis, fuel blending, and product distribution operations that transform crude oil and natural gas condensate into marketable fuels, chemical feedstocks, and specialty products, with modern refineries achieving conversion rates exceeding 90% through hydrocracking and coking processes. The sector supplies transportation energy, industrial heat, and polymer precursors to manufacturing industries across the domestic economy. Petrochemicals command the largest value share within product type segmentation, reflecting Iran's strategic prioritization of methanol, ethylene, and aromatics capacity expansion at Asaluyeh and Mahshahr. Fuels retain volume dominance but face margin compression from aging refinery infrastructure and product quality upgrade requirements. Within end user segmentation, chemical plants represent the fastest-growing demand pool as downstream derivative projects multiply the value captured from each barrel of feedstock processed.
Iran's petroleum sector operates under oversight from the Ministry of Petroleum and the National Iranian Oil Company, with refinery investment approvals flowing through state planning mechanisms that prioritize import substitution in gasoline and diesel. The country's national petroleum regulator enforces product specification standards that gradually align with regional environmental benchmarks despite equipment access constraints. Stakeholders must monitor sanctions architecture evolution, domestic gas field development rates, and regional petrochemical competition from Saudi and Qatari expansions to calibrate capacity commitment timelines.
Market Dynamics
International sanctions are fragmenting equipment procurement channels for Iranian refineries, forcing a structural pivot toward domestic fabrication partnerships and non-Western technology sourcing that reshapes both cost structures and project timelines.
Growth Catalysts
- Condensate Splitting Expansion:Persian Gulf Star Oil Company's Euro-5 gasoline output demonstrates that Iranian refiners can achieve product quality upgrades despite equipment access constraints. The technology spreads to Bandar Abbas and Asaluyeh complexes.
- Petrochemical Derivative Demand:Automotive polymer consumption absorbs rising methanol and ethylene volumes. The country's national petroleum regulator licenses capacity additions that feed this manufacturing pull.
- Import Substitution Mandates:Ministry of Petroleum planning mechanisms prioritize gasoline and diesel self-sufficiency. State investment approvals flow toward refinery upgrades that displace fuel imports.
Market Restraints
- Specialized Equipment Access:Hydrocracking catalysts and advanced process control systems face procurement bottlenecks. Iranian fabricators lack certification for high-pressure reactor vessels.
- Feedstock Quality Variability:South Pars gas field condensate composition shifts complicate splitter unit optimization. Refinery yield planning encounters operational friction.
- Product Specification Gaps:Euro-5 gasoline sulfur limits exceed output from hydroskimming facilities at older complexes. Environmental benchmark alignment requires capital-intensive revamps.
Strategic Opportunities
- Asaluyeh Petrochemical Cluster:Mahshahr adjacent capacity expansion captures value from ethylene and aromatics derivative projects. Methanol-to-olefins technology integration multiplies feedstock leverage.
- Lubricant Premiumization:Pars Oil Company brand equity among commercial fleet operators creates pricing power. Synthetic base stock blending upgrades target industrial machinery segments.
- Provincial Depot Network:National Iranian Oil Refining and Distribution Company monopoly on product allocation enables logistics optimization. Digital inventory management reduces working capital intensity.
Industry Challenges
- Process Control Engineering Talent:Distributed control system programming and advanced process simulation expertise concentrates at state-owned engineering subsidiaries. Private sector project execution competes for limited specialists.
- Refinery Turnaround Coordination:Simultaneous maintenance of multiple units strains domestic contractor capacity. Project scheduling conflicts extend downtime duration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Oil and Gas Downstream Market |
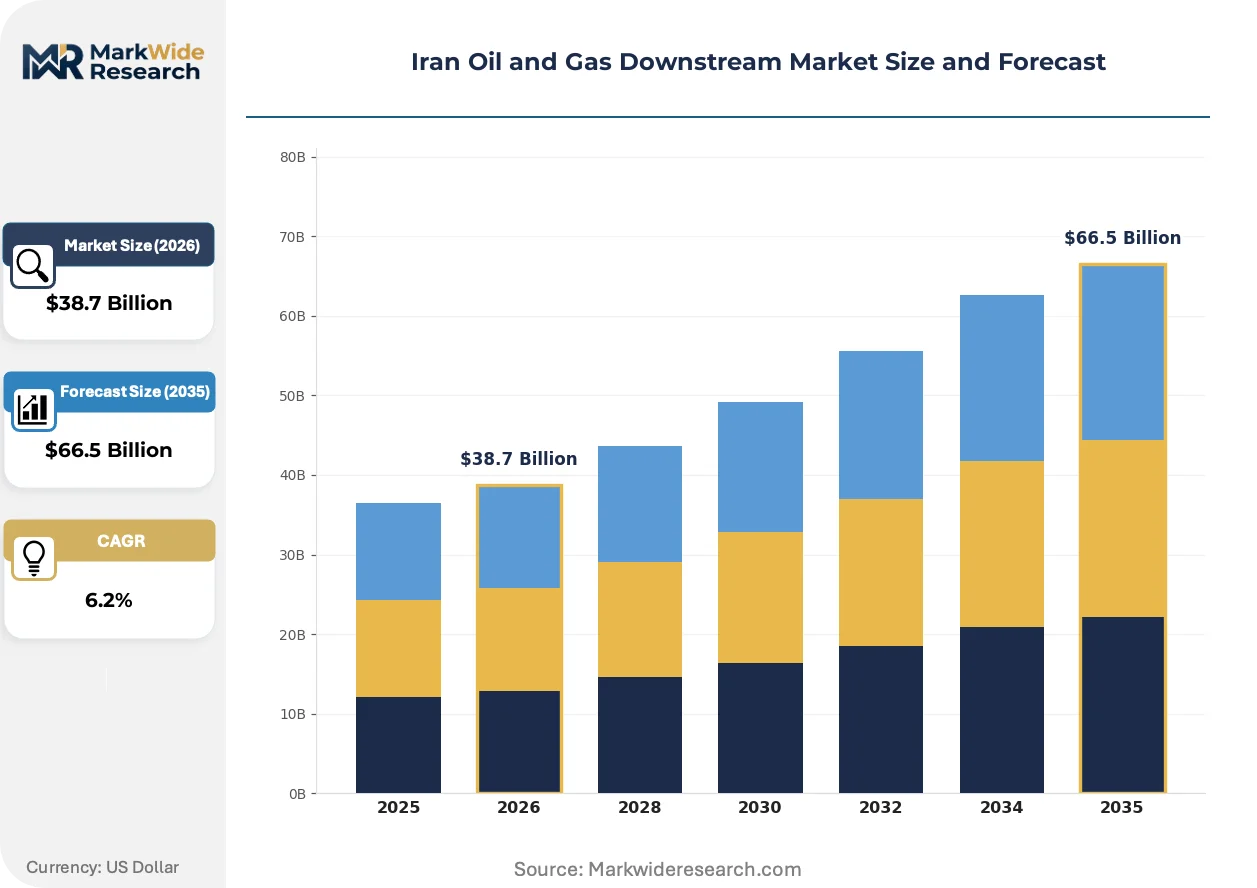
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $66.5 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Petrochemicals, Fuels, Lubricants, Asphalts Application: Industrial, Transportation, Residential, Commercial End User: Refineries, Chemical Plants, Power Plants, Distributors Service Type: Storage, Distribution, Marketing, Retail |
| Companies Covered | Pars Oil Company, Esfahan Oil Refining Company, National Iranian Oil Refining and Distribution Company, Persian Gulf Star Oil Company, Lavan Oil Refining Company, National Iranian Gas Company, Iranol Oil Company, Apadana Methanol, National Petrochemical Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Oil and Gas Downstream Market Shifts & Advancements
Refinery modernization in Iran is rewiring around sanctions-resilient technology pathways, with process intensification and domestic fabrication partnerships displacing conventional equipment procurement models that relied on Western engineering licenses.
Residue upgrading through delayed coking and hydrocracking is rewriting conversion economics at Iranian refineries. Complex operators in Bandar Abbas adopt these technologies to push conversion rates past hydroskimming limitations. The shift enables heavier crude processing and expands the barrel value captured before product export or domestic allocation.
REACH-equivalent product specification alignment is tightening fuel quality enforcement despite equipment access constraints. The country's national petroleum regulator phases in sulfur and aromatics limits that mirror regional environmental benchmarks. Refinery investment approvals now incorporate emissions control retrofits as mandatory licensing conditions.
Commercial fleet procurement is consolidating around lubricant suppliers with verified base stock traceability. Pars Oil Company and regional competitors face buyer concentration among large transport operators who unbundle service contracts from product supply. This specification-driven selection is most visible in Tehran-Isfahan corridor logistics corridors where fleet scale justifies direct supplier relationships.
Iran Oil and Gas Downstream Market Segmentation
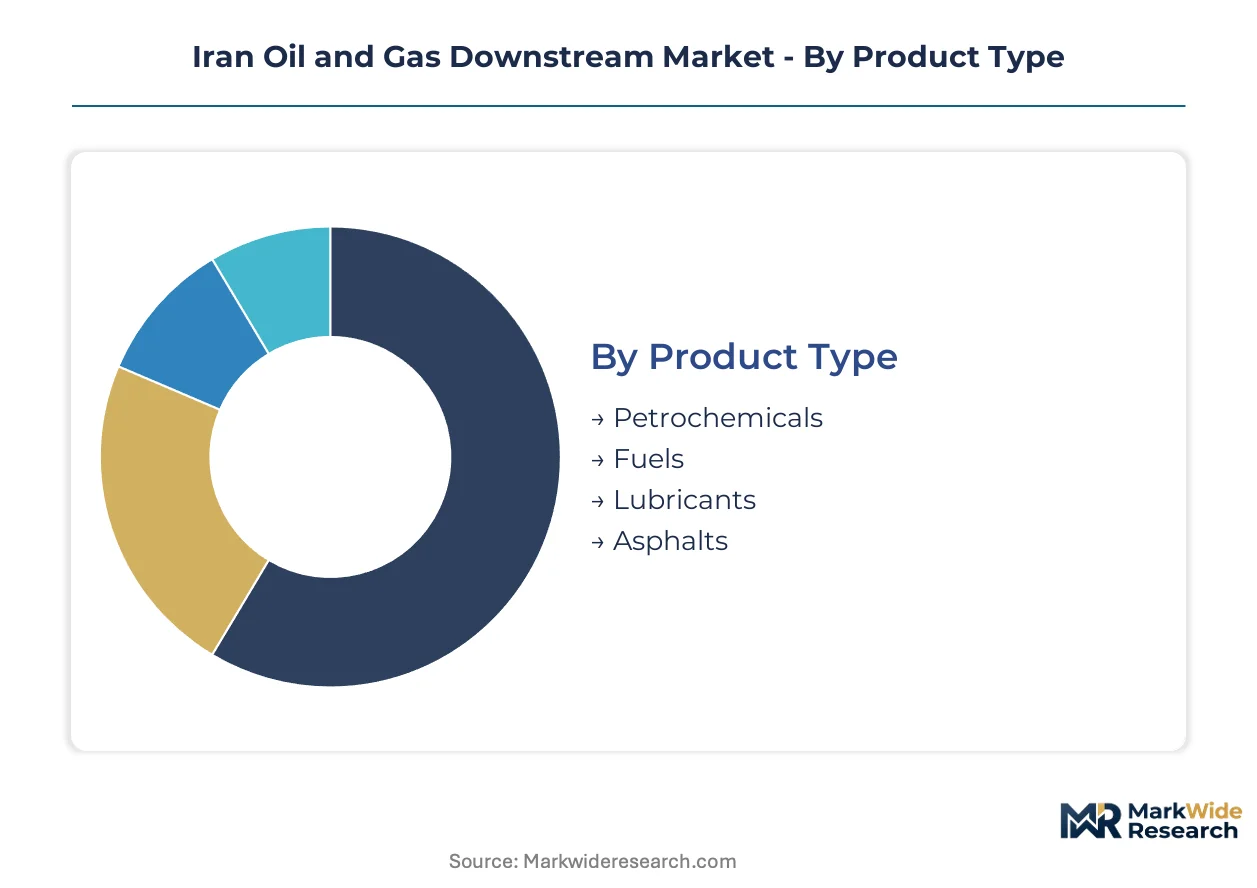
Segmentation in Iran's downstream petroleum sector reveals how sanctions constraints reshape product mix priorities and channel economics. Distinct margin profiles across petrochemical derivatives versus finished fuels drive capital allocation toward higher-value conversion pathways.
Product Type:
Standalone commodity outputs compete with integrated refinery-petrochemical complexes for feedstock access and export logistics capacity.
- Petrochemicals:Methanol, ethylene, and aromatics production dominates value capture at Asaluyeh and Mahshahr complexes. Chemical plants absorb rising polymer feedstock volumes from automotive sector expansion along the Tehran-Isfahan corridor.
- Fuels:Gasoline, diesel, and fuel oil output retains volume leadership but faces margin compression from hydroskimming facility limitations. Persian Gulf Star Oil Company's condensate splitting technology demonstrates upgrade feasibility despite equipment access constraints.
- Lubricants:Pars Oil Company brand recognition supports premium positioning among commercial fleet operators.
- Asphalts:Road construction and infrastructure maintenance absorb refinery residual streams.
Volume placements concentrate in Fuels; the faster expansion belongs to Petrochemicals.
Application:
Cost tier differentiation separates bulk commodity supply from specification-grade product deliveries.
- Industrial:Manufacturing heat, process energy, and chemical feedstocks absorb the largest share of downstream output. Petrochemical derivative demand from polymer processing plants climbs fastest as domestic automotive production scales.
- Transportation:Euro-5 gasoline and diesel specifications drive refinery investment despite catalyst procurement bottlenecks. Fleet operators in the Tehran-Isfahan logistics corridor consolidate procurement around verified base stock traceability.
- Residential:LPG and heating fuel distribution runs through National Iranian Oil Refining and Distribution Company provincial depot network.
- Commercial:Retail fuel stations and lubricant service points compete on location density and brand equity.
Industrial applications absorb the largest volume share; Transportation specifications are climbing the fastest.
End User:
Customer type fragmentation splits between captive state-owned offtake and independent commercial buyers.
- Refineries:Intermediate product exchange between complexes enables feedstock optimization across Bandar Abbas and Asaluyeh facilities.
- Chemical Plants:Methanol-to-olefins and derivative projects multiply value captured per barrel processed. The country's national petroleum regulator licenses capacity additions targeting this demand pool.
- Power Plants:Fuel oil and natural gas liquids supply electricity generation capacity.
- Distributors:National Iranian Oil Refining and Distribution Company monopoly on product allocation shapes logistics economics for independent retailers.
Refineries handle the largest internal volumes; Chemical Plants are gaining share fastest.
Service Type:
Supply concentration patterns differentiate infrastructure-heavy segments from trading and branding activities.
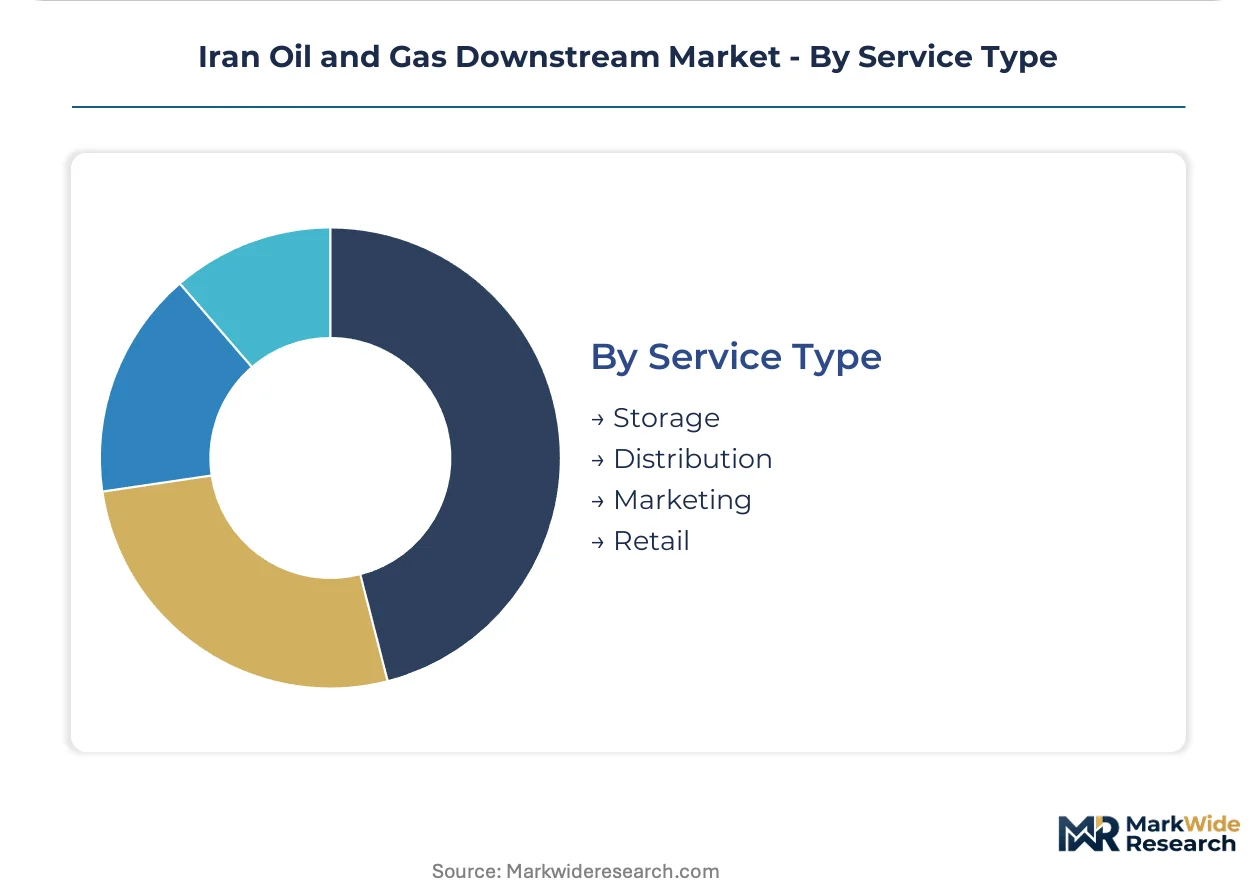
- Storage:Crude and product tankage at Persian Gulf coastal terminals enables export logistics and strategic reserve management.
- Distribution:Provincial depot network optimization reduces working capital intensity through digital inventory management. Pipeline and tanker movements connect refining centers to inland demand clusters.
- Marketing:Branded fuel and lubricant positioning targets fleet operator procurement consolidation.
- Retail:Service station networks compete on location coverage and payment system integration.
Storage infrastructure anchors the physical supply chain; Distribution network optimization shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Pars gas field condensate feeds Iran's downstream complex network, with coastal refining capacity clustering along the Persian Gulf shoreline where tanker export logistics intersect with domestic product distribution infrastructure.
Tehran Province
Commercial fleet operators in the Tehran-Isfahan logistics corridor consolidate lubricant procurement around verified base stock traceability. The Ministry of Petroleum coordinates state investment approvals for refinery upgrades through centralized planning mechanisms. Industrial demand concentrates in Karaj and Qom satellite manufacturing zones where polymer processing plants absorb rising methanol volumes.
Hormozgan Province
Bandar Abbas hosts integrated refining-petrochemical complexes that process imported crude alongside domestic condensate feedstocks. The country's national petroleum regulator licenses capacity expansion timelines through environmental benchmark alignment requirements. Persian Gulf Star Oil Company operates condensate splitting technology at the Bandar Abbas refinery complex, producing Euro-5 gasoline for domestic distribution.
Bushehr Province
Asaluyeh anchors Iran's petrochemical value chain through methanol, ethylene, and aromatics capacity at the Pars Special Economic Energy Zone. National Petrochemical Company directs capacity additions targeting methanol-to-olefins technology integration. The coastal cluster captures export logistics advantages through dedicated jetties and storage tankage at the Persian Gulf terminal.
Khuzestan Province
Mahshahr petrochemical complexes compete for feedstock access with Asaluyeh facilities along the same coastal corridor. The national petroleum regulator enforces product specification standards that phase in sulfur limits mirroring regional environmental benchmarks. Abadan refinery modernization projects face equipment procurement bottlenecks from hydrocracking catalyst sourcing constraints.
Fars Province
Shiraz industrial zones absorb refined product allocations from coastal refineries through the National Iranian Oil Refining and Distribution Company provincial depot network. State planning mechanisms prioritize import substitution in gasoline and diesel through refinery investment approvals. The region's automotive manufacturing base drives polymer feedstock demand from petrochemical derivative projects.
Iran Oil and Gas Downstream Market Competitive Landscape
Global engineering contractors compete with domestic fabricators across technology licensing and equipment procurement channels, though sanctions architecture has fragmented international participation. State-owned entities dominate capacity ownership through monopoly positions in refining and distribution infrastructure. Two strategic archetypes define competitive positioning: integrated refinery-petrochemical operators capturing value across conversion stages, and specialized lubricant marketers building brand equity among fleet operators. Capacity expansion and domestic fabrication partnerships represent the dominant competitive moves as international supply chains constrict.
Among state-owned refining operators, National Iranian Oil Refining and Distribution Company anchors fuel distribution logistics through its monopoly on provincial depot allocation. Persian Gulf Star Oil Company occupies a position within the condensate splitting technology tier, exemplifying product quality upgrade feasibility despite equipment access constraints. Pars Oil Company sits within the lubricant marketing archetype, representing brand-based competition among commercial fleet operators.
| Leading Market Players |
|---|
| Pars Oil Company |
| Esfahan Oil Refining Company |
| National Iranian Oil Refining and Distribution Company |
| Persian Gulf Star Oil Company |
| Lavan Oil Refining Company |
| National Iranian Gas Company |
| Iranol Oil Company |
| Apadana Methanol |
| National Petrochemical Company |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers dominate Iran's downstream petroleum sector, concentrating supply-side control within state-owned refining complexes and channeling pricing discipline through centralized allocation mechanisms rather than competitive market clearing.
Pricing Analysis
Service bundling separates lubricant procurement from fuel supply contracts, with Pars Oil Company unbranded bulk sales competing against specification-grade synthetic blends that include fleet maintenance packages. Three-tier pricing structure across premium Euro-5 gasoline, standard hydroskimming output, and residual fuel oil reflects refinery technology vintage and sulfur content compliance. Pricing pressure stems from hydrocracking catalyst procurement bottlenecks that constrain high-margin product output. Commercial fleet operators exhibit highest price sensitivity, while chemical plants prioritize feedstock quality consistency over unit cost.
Supply Chain Analysis
Hydrocracking catalyst supply rests on Chinese and Russian specialty chemical producers after Western engineering licenses withdrew under sanctions architecture. Condensate feedstock draws from South Pars gas field operations, with splitter unit optimization complicated by compositional variability. Single-source vulnerability concentrates in advanced process control systems where domestic fabricators lack high-pressure reactor vessel certification. Distribution runs through National Iranian Oil Refining and Distribution Company provincial depot monopoly, connecting Bandar Abbas and Asaluyeh complexes to inland demand clusters via pipeline and tanker movements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iran's downstream petroleum sector is consolidating around state-backed capacity ownership, with international equipment access constraints forcing weaker private fabricators into domestic partnership structures or exit.
For Market Incumbents: Anchor market position through backward integration into condensate splitter technology replication at Bandar Abbas and Asaluyeh complexes, countering emerging non-Western engineering contractors from China and Russia. Deepen captive supply of hydrocracking catalysts via technology licensing with sanctioned-resilient partners to defend margin position against product specification upgrades mandated by the country's national petroleum regulator. For New Entrants and Emerging Players: Digital inventory management platforms offer the most penetrable entry vector, targeting National Iranian Oil Refining and Distribution Company depot network optimization gaps in Fars and Tehran provinces. Fleet telematics integration with lubricant procurement systems captures commercial transport operator consolidation along the Tehran-Isfahan corridor, bypassing capital-intensive refining assets entirely. For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic fabrication specialists with Iranian Pressure Vessel Certification in Hormozgan and Bushehr provinces, positioned for sanctions-resilient equipment procurement partnerships. Long-term viability hinges on regulator alignment with REACH-equivalent sulfur limits; the signal to watch is licensing velocity for methanol-to-olefins capacity additions at Asaluyeh.| Strategic Initiative | Industry Significance |
|---|---|
| Condensate Splitter Technology Licensing | Persian Gulf Star Oil Company's Euro-5 output demonstrates upgrade feasibility despite equipment constraints. |
| Backward Integration into Catalyst Production | Domestic fabrication partnerships with Chinese and Russian suppliers reduce hydrocracking unit downtime risk. |
| Digital Depot Network Optimization | National Iranian Oil Refining and Distribution Company monopoly enables working capital reduction through inventory visibility. |
| Methanol-to-Olefins Capacity Expansion | Asaluyeh cluster integration multiplies value captured per barrel of South Pars condensate processed. |
| Synthetic Lubricant Premiumization | Pars Oil Company brand equity supports pricing power among commercial fleet operators requiring base stock traceability. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with refinery operations managers, petrochemical procurement leads at polymer processing plants, National Iranian Oil Refining and Distribution Company logistics coordinators, and engineering subsidiary technical directors. Secondary validation drew from Ministry of Petroleum planning disclosures, National Petrochemical Company capacity announcements, South Pars gas field production reports, and provincial industrial development filings. Bottom-up project-level capacity assessments triangulated against top-down sectoral value estimates.
Segment-level granularity modeled product type across petrochemicals, fuels, lubricants, and asphalts; application across industrial, transportation, residential, and commercial end-uses; and service type across storage, distribution, marketing, and retail channels. CAGRs derived from capacity expansion timelines licensed by the country's national petroleum regulator, feedstock availability projections from South Pars development phases, and automotive sector polymer absorption rates across the analysis window. Forecast inputs incorporated sanctions architecture evolution scenarios and regional petrochemical competition from Saudi and Qatari expansions.
The model holds under sustained sanctions-resilient technology sourcing; deviation in international diplomatic breakthroughs or domestic gas field depletion rates would shift capacity commitment timelines. Forecasts reflect assumptions regarding regulator enforcement of product specification standards and domestic fabrication partnership maturation. A small set of named triggers warrants ongoing watch: licensing velocity for refinery upgrades, condensate splitter unit operational uptime, and methanol-to-olefins project financing closure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Azerbaijan Oil and Gas Upstream Market
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market
Offshore Oil and Gas
Global Subsea Systems Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
Enhanced Oil Recovery Market
Offshore Oil and Gas
United Kingdom LNG Bunkering Market
Offshore Oil and Gas
Offshore Drilling Riser Market
Offshore Oil and Gas
Kazakhstan Oil and Gas Upstream Market
Offshore Oil and Gas
North America FLNG Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market
Offshore Oil and Gas
FPSO Market
Offshore Oil and Gas
Gulf of Mexico Subsea Systems Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Kuwait Oil and Gas Downstream Market