
 Industrial Computed Radiography Market | 2026-2036
Industrial Computed Radiography Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Computed Radiography Market Foresight
Phosphor-based imaging plates are hardening their cost advantage over traditional silver-halide film in heavy-industry inspection workflows. Fujifilm Corporation leverages decades of photosensitive material expertise to sustain leadership in plate chemistry and scanner integration. Baker Hughes anchors its position through upstream control over oilfield inspection protocols, while Waygate Technologies competes aggressively in power generation sector deployments across North America and Europe.
Industrial computed radiography captures radiation passing through metallic structures using photostimulable phosphor plates, then digitizes latent images through laser scanning at resolutions reaching 25 micrometers per pixel for weld defect characterization. CR Systems dominate installed base value due to bundled hardware-software contracts, while Imaging Plates represent the fastest-growing recurring revenue stream as replacement cycles shorten under high-duty-cycle manufacturing environments. Detection applications command premium pricing relative to routine maintenance screening, reflecting the liability costs of undiscovered structural flaws in aerospace and energy infrastructure.
FDA device regulations and ASME Boiler and Pressure Vessel Code standards govern North American product qualification pathways, while REACH compliance requirements shape phosphor chemistry formulations for European suppliers. The EU AI Act introduces emerging scrutiny of automated defect-classification algorithms embedded in modern scanner software. Stakeholders must evaluate whether to prioritize detector sensitivity investments or software-driven workflow automation as capital allocation decisions intensify.
Market Dynamics
The transition from silver-halide film to photostimulable phosphor plates is compressing inspection cycle times while elevating resolution standards across heavy manufacturing. This substrate shift is redrawing supplier hierarchies and forcing capital reallocation toward laser scanner integration and software-defined defect classification.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is accelerating plate-based system deployment in European aerospace and power generation facilities, eliminating wet-chemistry film processing entirely.
- Automotive lightweighting:Aluminum-intensive vehicle architectures in Germany's industrial belt are multiplying weld inspection points, driving recurring demand for high-duty-cycle imaging plate replacement.
- Phosphor chemistry advances:Europium-doped barium fluorohalide formulations are extending plate reusability beyond ten thousand exposure cycles, reducing per-inspection consumable costs.
Market Restraints
- Rare earth supply concentration:Europium and lanthanum extraction concentrates in Chinese processing facilities, exposing plate manufacturers to input cost volatility and geopolitical supply risk.
- Digital radiography substitution:Flat-panel detector systems are capturing share in high-throughput pipeline inspection, particularly in North American oilfield services where real-time imaging justifies premium hardware investment.
- REACH compliance burden:ECHA substance restrictions on barium compounds are lengthening formulation approval timelines for new phosphor chemistries, delaying product launches by eighteen to twenty-four months.
Strategic Opportunities
- India industrial corridor expansion:The country's PLI scheme for specialty steel and defense manufacturing is creating first-mover advantage for plate-system vendors establishing localized scanner service networks.
- AI-augmented classification:Machine learning defect recognition algorithms are enabling automated pass-fail triage, allowing inspection bureaus to redeploy radiographic interpreters toward complex anomaly arbitration.
- Wind turbine blade manufacturing:Carbon fiber composite inspection for offshore installations represents an emerging application segment with resolution requirements that favor CR over ultrasonic alternatives.
Industry Challenges
- Radiographic interpreter certification:ASME and ISO 9712 qualification pathways require eighteen-month training commitments, constraining workforce expansion as inspection volume multiplies.
- Legacy film archive digitization:Decades of silver-halide reference standards must be rescanned to phosphor-compatible formats, imposing capital and labor costs on quality assurance departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Computed Radiography Market |
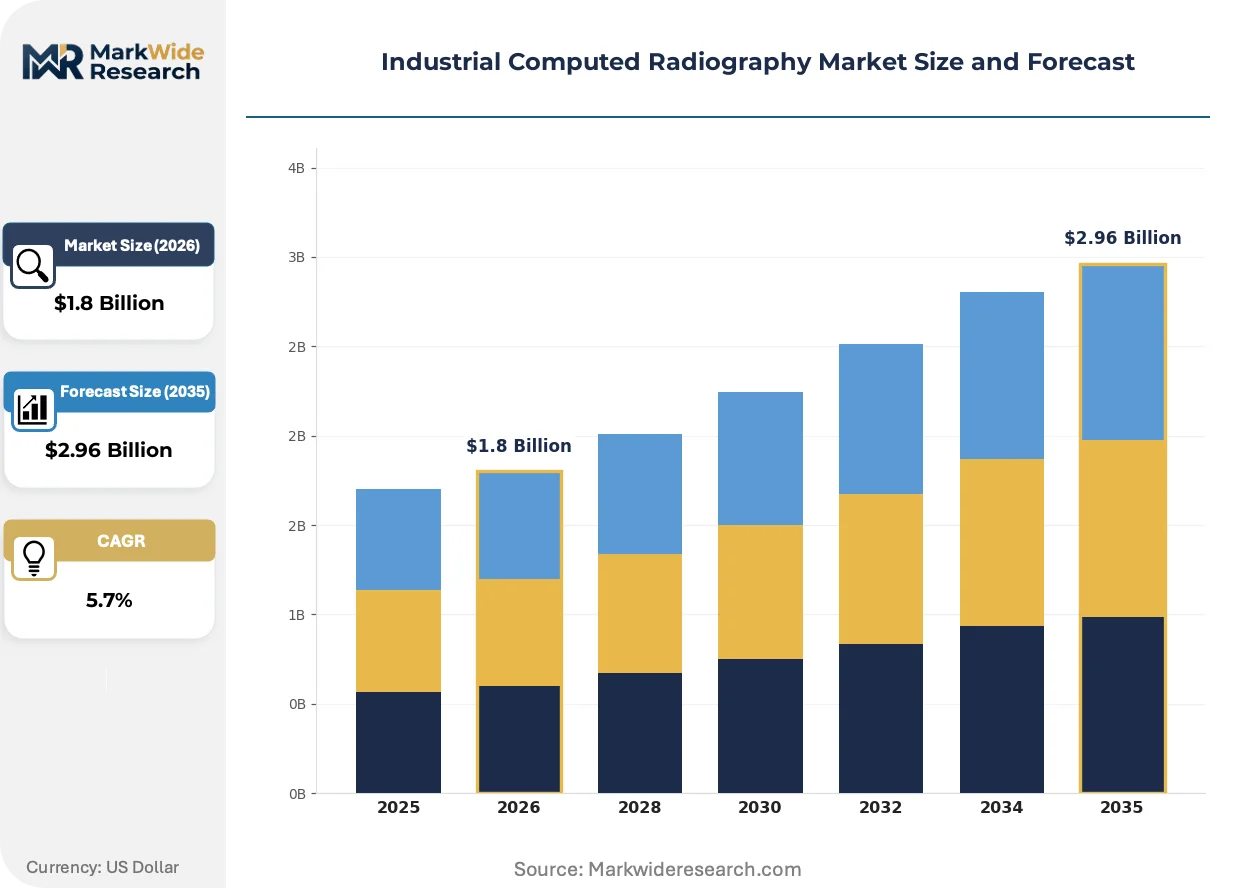
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CR Systems, Imaging Plates, Scanners, Software End User: Aerospace, Manufacturing, Oil & Gas, Power Generation Technology: Digital Radiography, Optical Imaging, X-Ray, Gamma Ray Application: Detection, Inspection, Quality Control, Maintenance |
| Companies Covered | DÜRR NDT GmbH & Co. KG, Fujifilm Corporation, Carestream Health, Baker Hughes, Rigaku Corporation, Waygate Technologies, L3Harris Technologies, Acuren, Blue Star, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Computed Radiography Market Shifts & Advancements
Scanner hardware architecture is fragmenting into configurable subsystems, allowing end-users to match detector sensitivity, laser wavelength, and throughput speed to specific inspection protocols. This componentization is enabling faster technology refresh cycles and reducing total replacement capex.
Photostimulable phosphor plate manufacturing is modularizing across three functional layers: base substrate, phosphor deposition, and protective overcoating. European plate suppliers are adopting this disaggregated production model to isolate REACH compliance risk within the chemistry layer while sourcing mechanically standardized substrates from Asian converters. The approach compresses new product introduction timelines and localizes regulatory liability.
REACH and the EU AI Act are jointly reshaping European product qualification pathways. The F-Gas Regulation's processing chemical prohibitions have already eliminated solvent-based film development, while the AI Act's risk classification framework is imposing documentation burdens on automated defect-recognition software embedded in scanner control systems. German TÜV certification bodies are expanding audit scope to cover algorithm training data provenance.
Inspection procurement is consolidating through multi-year fleet management contracts that bundle hardware, plate supply, and software maintenance into per-image pricing. North American power generation utilities are leading this shift, displacing transactional equipment purchases with operational expenditure models that transfer obsolescence risk to vendors. Baker Hughes and Waygate Technologies are restructuring sales organizations to capture these recurring revenue streams.
Industrial Computed Radiography Market Segmentation
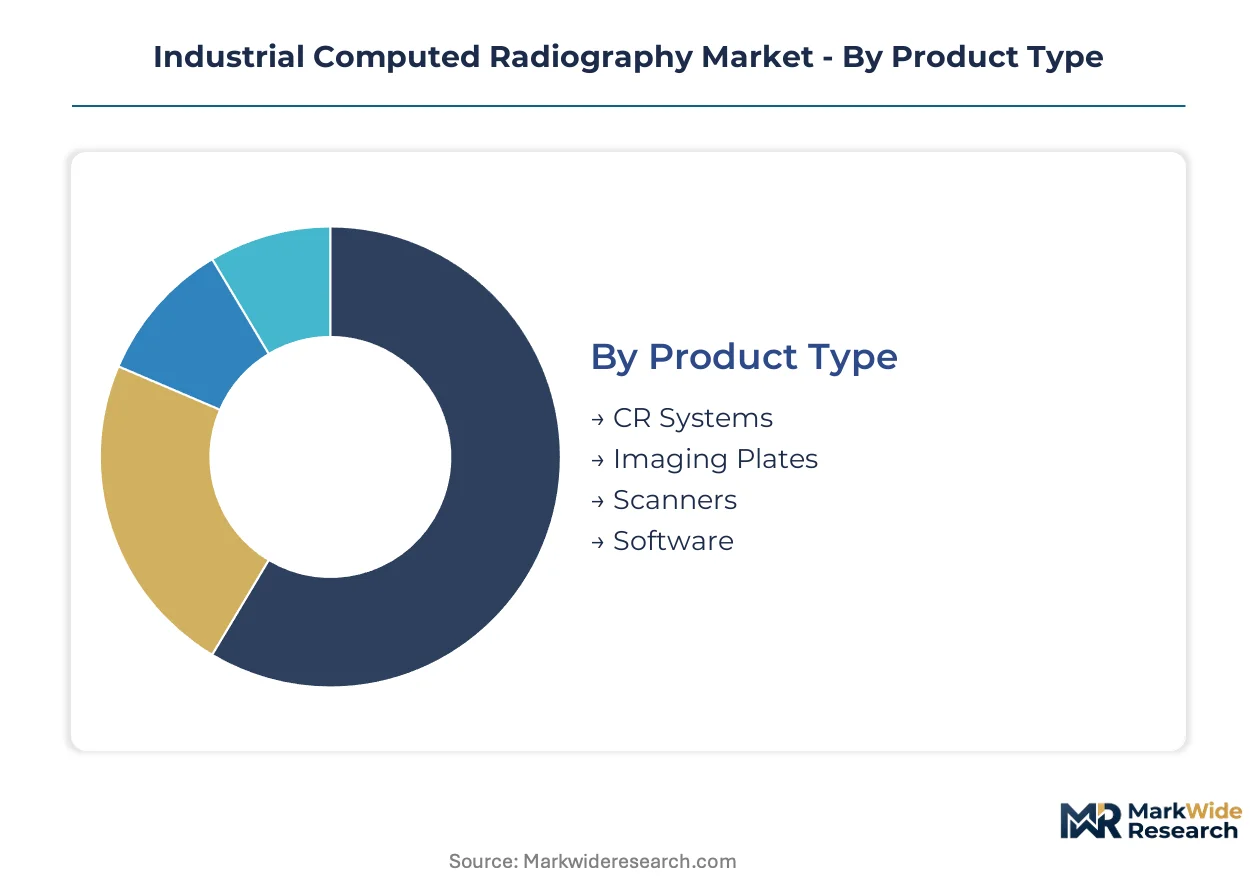
Industrial computed radiography suppliers configure product portfolios around inspection duty cycles and regulatory exposure levels. Segmentation reveals where bundled hardware-software contracts dominate versus consumable-driven recurring revenue streams.
Product Type:
Volume shipments concentrate in consumable imaging plates, while premium capture sits with integrated CR systems bundling scanners and proprietary software.
- CR Systems:Laser scanner units with embedded phosphor plate readers command bundled pricing through multi-year fleet management contracts. North American power generation utilities favor these integrated deployments for weld inspection protocols under ASME Boiler and Pressure Vessel Code requirements.
- Imaging Plates:Photostimulable phosphor sheets represent the recurring revenue anchor as replacement cycles compress under high-duty-cycle manufacturing environments. Europium-doped barium fluorohalide formulations from German chemical suppliers dominate European aerospace adoption.
- Scanners:Modular laser reading units enable technology refresh without full system replacement.
- Software:Defect classification algorithms face emerging documentation burdens under EU AI Act risk classification frameworks.
Mature deployment sits with CR Systems. Newer deployment is concentrated in Imaging Plates as plate reusability extends beyond ten thousand exposure cycles.
End User:
Application margins split between liability-sensitive detection tasks and routine maintenance screening with lower certification overhead.
- Aerospace:Turbine blade inspection demands 25-micrometer resolution for subsurface defect characterization in single-crystal superalloys. German TÜV certification bodies audit automated defect-recognition software training data provenance for European manufacturers.
- Manufacturing:Aluminum-intensive automotive architectures multiply weld inspection points across Germany's industrial belt.
- Oil & Gas:Upstream pipeline inspection protocols favor real-time imaging where flat-panel digital radiography captures share.
- Power Generation:Pressure vessel integrity programs drive recurring plate consumption under sustained radiation exposure conditions.
Established demand anchors in Power Generation. Expanding most quickly in Aerospace as F-Gas Regulation eliminates wet-chemistry film processing entirely.
Technology:
Performance tiering separates real-time digital capture from phosphor-based latent imaging with intermediate processing steps.
- Digital Radiography:Flat-panel detectors deliver immediate image acquisition without laser scanning delays. North American oilfield services deploy these systems for high-throughput pipeline inspection where time-to-decision justifies premium hardware investment.
- X-Ray:Conventional tube-based radiation sources dominate metallic structure penetration requirements.
- Gamma Ray:Isotope-based sources enable field inspection without electrical power infrastructure.
- Optical Imaging:Visible-light surface inspection complements subsurface radiographic methods.
Legacy installed base rests with X-Ray. Steepest expansion trajectory belongs to Digital Radiography as detector sensitivity improves and unit costs decline.
Application:
Customer procurement patterns diverge between capital-project detection with liability exposure and operational maintenance with predictable scheduling.
- Detection:Structural flaw identification in critical infrastructure commands premium pricing reflecting undiscovered defect liability costs. Offshore wind turbine blade manufacturing for carbon fiber composite inspection represents an emerging demand segment.
- Inspection:Protocol-driven examination schedules dominate regulatory compliance workflows.
- Quality Control:In-process verification integrates with manufacturing execution systems.
- Maintenance:Condition-based monitoring programs reduce unplanned downtime in continuous-process industries.
Regulatory-mandated volume concentrates in Inspection. Gaining share fastest in Detection as AI-augmented classification enables automated pass-fail triage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's automotive and power generation belt, where weld inspection protocols drive plate replacement cycles. The United States anchors aerospace turbine blade inspection volume. China's expanding specialty steel capacity and India's PLI-scheme industrial corridors are emerging as high-growth deployment zones.
Germany
Automotive lightweighting and aluminum-intensive vehicle architectures multiply weld inspection points across Baden-Württemberg and Bavaria. The EU F-Gas Regulation eliminates wet-chemistry film processing entirely, accelerating plate-based system transitions. Stuttgart's industrial cluster hosts dense concentrations of TÜV-certified inspection bureaus serving power generation and aerospace supply chains.
United States
Aerospace manufacturers in Washington State and Texas expand computed radiography adoption for single-crystal superalloy turbine blade characterization. FDA device regulations and ASME Boiler and Pressure Vessel Code standards govern product qualification pathways. Houston's oilfield services corridor maintains substantial installed base value through bundled hardware-software contracts.
China
Specialty steel capacity expansion under national dual carbon goals drives defect detection demand in pressure vessel manufacturing. The country's national industrial standards regulator enforces GB compliance frameworks for non-destructive testing equipment. Yangtze River Delta fabrication clusters absorb high volumes of imaging plates for shipbuilding and energy infrastructure weld verification.
India
The PLI scheme for specialty steel and defense manufacturing creates first-mover advantage for vendors establishing localized scanner service networks. BIS certification requirements shape equipment import and domestic assembly protocols. Maharashtra's industrial corridor around Pune and Mumbai anchors initial deployment concentration for automotive and heavy engineering inspection workflows.
Japan
Precise manufacturing execution systems in automotive and electronics supply chains sustain premium-tier scanner demand. METI industrial technology roadmaps prioritize automated defect-classification algorithm development. Kansai region fabrication clusters, particularly around Osaka and Kyoto, maintain rigorous quality control protocols that favor high-resolution phosphor-based imaging.
Industrial Computed Radiography Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system vendors capturing bundled contract value and component suppliers anchoring recurring consumable revenue. The vendor landscape organizes around three archetypes: photosensitive material specialists with decades of chemistry expertise, industrial inspection conglomerates with upstream protocol control, and diversified technology holding companies with cross-sector imaging portfolios. Dominant competitive moves include vertical integration into phosphor deposition processes and geographic expansion through localized scanner service networks.
Within the diversified technology tier, Fujifilm Corporation and Rigaku Corporation exemplify material science anchoring strategies, while Baker Hughes and Waygate Technologies occupy positions shaped by sector-specific inspection protocol ownership. DÜRR NDT GmbH & Co. KG represents the European specialist archetype with concentrated NDT equipment focus.
| Leading Market Players |
|---|
| DÜRR NDT GmbH & Co. KG |
| Fujifilm Corporation |
| Carestream Health |
| Baker Hughes |
| Rigaku Corporation |
| Waygate Technologies |
| L3Harris Technologies |
| Acuren |
| Blue Star |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap phosphor plate specialists in Germany and Japan anchor pricing discipline through captive europium supply arrangements and multi-year service contracts with automotive OEMs. Their concentrated ownership structures enable patient capital allocation toward REACH-compliant chemistry layers while resisting commoditization pressure from Asian contract manufacturers.
Pricing Analysis
Volume shipments of consumable imaging plates compress per-unit margins while integrated CR systems bundled with proprietary software capture premium pricing through fleet management contracts. Three-tier pricing structure across aerospace-certified, industrial-standard, and economy-grade scanner configurations reflects ASME and TÜV certification overhead. Pricing pressure stems from flat-panel digital radiography substitution in North American oilfield services where real-time imaging commands hardware premiums. Power generation utilities exhibit lowest price sensitivity due to liability exposure from undetected pressure vessel flaws, while commodity inspection bureaus in emerging markets drive hardest bargain on plate replacement cycles.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for scanner assembly and phosphor plate finishing operations. Raw material supply concentrates in Chinese rare earth processing facilities for europium and lanthanum, German chemical suppliers for barium fluorohalide formulations, and Japanese substrate converters for base plate manufacturing. Single-source vulnerability in Chinese rare earth extraction exposes plate manufacturers to geopolitical disruption and input cost volatility. Distribution runs through authorized service networks for high-value CR systems and direct bulk procurement channels for recurring imaging plate consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial computed radiography sits in a technology-transition phase as photostimulable phosphor plates displace silver-halide film entirely under EU F-Gas Regulation prohibitions on wet-chemistry processing.
For Market Incumbents: Deepen backward integration into phosphor deposition processes to isolate REACH compliance risk and secure europium supply chains against Chinese export restrictions. Expand localized scanner service networks in India's Maharashtra industrial corridor to capture PLI-scheme defense and specialty steel manufacturing demand. Flat-panel digital radiography substitution in high-throughput pipeline inspection represents the most acute technology threat requiring defensive software bundling responses. For New Entrants and Emerging Players: Launch via per-image pricing fleet management contracts targeting North American power generation utilities seeking operational expenditure models. Carbon fiber composite inspection for offshore wind turbine blade manufacturing offers the most penetrable white-space application with resolution requirements favoring CR over ultrasonic alternatives. Pursue TÜV certification partnerships for automated defect-classification algorithms to overcome eighteen-month radiographic interpreter qualification barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor European phosphor chemistry specialists with REACH-compliant formulation libraries and established automotive supply chain relationships. Long-term viability over the next decade hinges on software-defined workflow automation capabilities rather than hardware manufacturing scale. Monitor EU AI Act implementation timelines for automated defect-recognition algorithm documentation burdens as the critical inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphor Deposition | Captive europium supply from German chemical partners reduces Chinese rare earth exposure. |
| AI-Augmented Defect Classification Development | Machine learning pass-fail triage addresses ASME certification workforce constraints. |
| Localized Scanner Service Network Expansion | Maharashtra and Pune facilities capture India's PLI-scheme defense manufacturing demand. |
| Fleet Management Contract Restructuring | Per-image pricing transfers obsolescence risk from power generation utilities to vendors. |
| REACH-Compliant Chemistry Layer Modularization | Disaggregated production isolates regulatory liability within European supplier tiers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this industrial computed radiography market assessment. Primary interviews with NDT equipment procurement managers at aerospace OEMs, radiographic interpreter certification bodies, phosphor plate manufacturing plant engineers, and power generation utility inspection directors combined with secondary validation from ASME Boiler and Pressure Vessel Code documentation, ECHA REACH substance restriction databases, FDA device registration records, and EU F-Gas Regulation implementation reports. Bottom-up scanner shipment tallies and top-down imaging plate consumption estimates were triangulated against customs trade flows.
Data-stream reconciliation across product type, end-use industry, technology tier, and geographic deployment pattern produced volume and value outputs across the projection horizon. Segmentation modeling incorporated inspection duty cycle intensity, regulatory exposure level, and resolution requirement granularity as cross-cutting dimensions. CAGRs were derived from fitted growth curves applied to disclosed equipment replacement cycles and consumable consumption rates. Industry-specific forecast inputs included europium spot price volatility indices and TÜV certification backlog durations for automated defect-recognition software.
Rare earth supply disruption, EU AI Act documentation burden escalation, and flat-panel digital radiography cost parity achievement are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding phosphor plate reusability extension and F-Gas Regulation enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
United Kingdom Diagnostic Imaging Equipment Market
Medical Imaging
Mobile Vascular Imaging Market
Medical Imaging
Africa Nuclear Imaging Market
Medical Imaging
PACS and RIS Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
North America Digital Radiology Market
Medical Imaging
United States Computed Tomography Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
Digital Pathology Market
Medical Imaging
Industrial Radiography Equipment Market
Medical Imaging
AI-Based Medical Imaging Algorithm Validation Test Platforms Market
Medical Imaging
Germany Computed Tomography Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
Asia-Pacific CT Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
US and Europe Digital Pathology Market