
 Brazil Computed Tomography Market | 2026-2036
Brazil Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Computed Tomography Market Analysis
Private diagnostic imaging centers is rotating toward premium multi-slice CT systems as public hospital budgets tighten. GE Healthcare anchors its position through deep channel partnerships with Brazilian distributors. Siemens Healthineers AG differentiates via spectral CT portfolios aimed at cardiology workflows. Koninklijke Philips NV sustains installed base loyalty through software-enhanced CT upgrade pathways.
Computed tomography denotes an X-ray-based imaging modality that reconstructs cross-sectional anatomical slices through tomographic algorithms, typically employing rotating gantry systems with detector arrays exceeding 64 rows for sub-millimeter spatial resolution. The technology serves diagnostic certainty in trauma, oncology staging, and interventional planning across inpatient and ambulatory settings. Multi-slice CT dominates capital expenditure flows due to throughput advantages in high-volume hospitals. Portable CT commands premium pricing in neuro-intensive care units where patient transport risks outweigh equipment costs. Cone beam CT occupies a narrower niche in dental and maxillofacial applications with lower radiation dose profiles.
ANVISA governs medical device registration and post-market surveillance, while the Brazilian Ministry of Health orchestrates procurement through centralized purchasing consortia that privilege ISO-certified manufacturers. The national radiological protection framework, derived from CNEN standards, mandates dose monitoring systems that filter out non-compliant equipment bids. Stakeholders must track how ANVISA's pending software-as-medical-device rulings reshape upgrade revenue models for installed CT fleets.
Market Dynamics
ANVISA's tightening radiology equipment registration protocols are compressing procurement timelines while simultaneously elevating technical compliance thresholds across Brazilian healthcare facilities.
Growth Catalysts
- Dual-energy CT adoption:Oncology departments in Brazil's Southeast region are replacing conventional helical systems with spectral imaging platforms that enhance tissue characterization accuracy.
- CNEN dose monitoring mandates:The national radiological protection framework now requires integrated dose tracking systems, filtering non-compliant equipment from public hospital bids and accelerating scanner replacement cycles.
- Tertiary hospital expansion:São Paulo and Rio de Janeiro medical centers are prioritizing multi-slice CT procurement to manage rising trauma and interventional caseloads.
Market Restraints
- Import dependency for detector arrays:Brazil lacks domestic manufacturing for high-density scintillator materials, exposing procurement costs to currency volatility and international supply constraints.
- ANVISA software-as-medical-device uncertainty:Pending rulings on AI-enabled reconstruction algorithms create revenue model ambiguity for vendors seeking upgrade pathway monetization.
- Helical CT obsolescence risk:Rapid spectral technology maturation threatens residual value recovery for recently installed conventional systems in mid-tier hospitals.
Strategic Opportunities
- Portable CT penetration in neuro-intensive care:Patient transport risk mitigation is opening premium-priced mobile scanner deployments in tertiary facilities across Minas Gerais and Paraná.
- Public-private imaging consortia:Ministry of Health centralized purchasing mechanisms are creating bundled service contract opportunities for ISO-certified manufacturers serving underserved Northeast states.
- Cone beam CT dental expansion:Lower radiation dose profiles are driving adoption in maxillofacial surgery and orthodontic planning beyond traditional hospital settings.
Industry Challenges
- ANVISA registration timeline compression:Expedited equipment approval demands are straining regulatory affairs teams while procurement windows narrow.
- Multi-vendor software integration:PACS connectivity and AI reconstruction module compatibility create technical friction during fleet upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Computed Tomography Market |
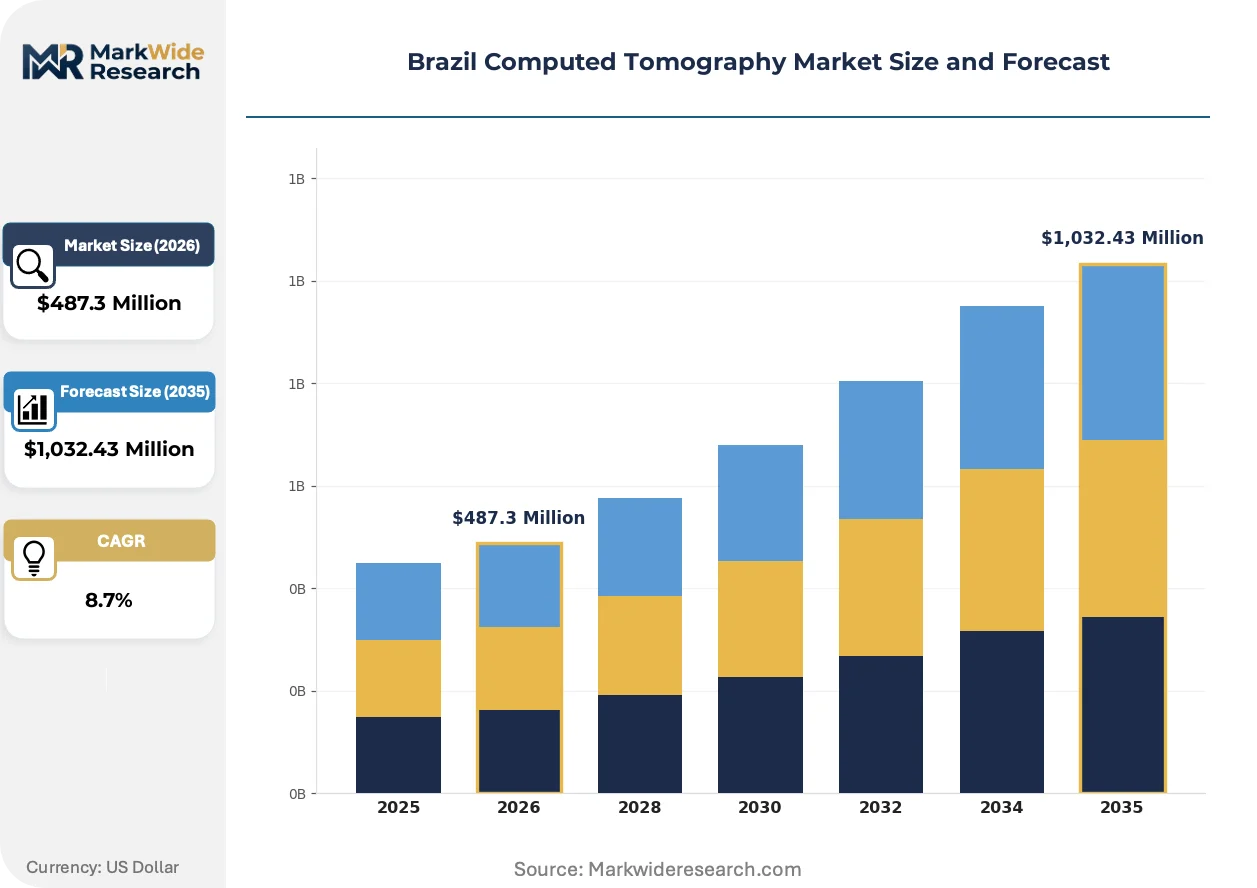
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable CT, Multi-Slice CT, Cone Beam CT, Flat Panel CT End User: Hospitals, Diagnostic Imaging Centers, Research Institutions, Outpatient Facilities Technology: Helical CT, Dual-Energy CT, Spectral CT, Software-Enhanced CT Application: Oncology, Neurology,Cardiology, Orthopedics |
| Companies Covered | Canon Medical Systems Corporation, Dentsply Sirona, GE Healthcare, Planmeca Group, Samsung Medison, Siemens Healthineers AG, Carestream Health, NeuroLogica, Koninklijke Philips NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Computed Tomography Market Emerging Trajectories
Spectral imaging architectures and software-defined reconstruction are redrawing competitive boundaries between installed base retention and new system displacement across Brazilian radiology departments.
Photon-counting detector technology is miniaturizing. These solid-state sensors replace conventional energy-integrating detectors to deliver superior spectral resolution at equivalent dose levels. Cardiology workflows in São Paulo's private diagnostic chains are adopting these platforms ahead of public hospital procurement cycles. The technology is miniaturizing hardware footprints while expanding outpatient deployment feasibility.
ANVISA's pending software-as-medical-device framework is recalibrating vendor service revenue models. Algorithm updates and AI reconstruction modules face prospective registration requirements distinct from hardware platforms. Premium multi-slice CT installed bases in Southeast Brazil are most exposed to compliance timeline uncertainty, prompting distributors to accelerate pre-ruling upgrade commitments.
Diagnostic imaging centers are unbundling equipment ownership from maintenance contracts. Private operators in Rio de Janeiro and Brasília are favoring performance-guaranteed service agreements over traditional capital purchase structures. This reconfiguration concentrates vendor risk while transferring utilization optimization accountability to equipment suppliers.
Brazil Computed Tomography Market Segmentation
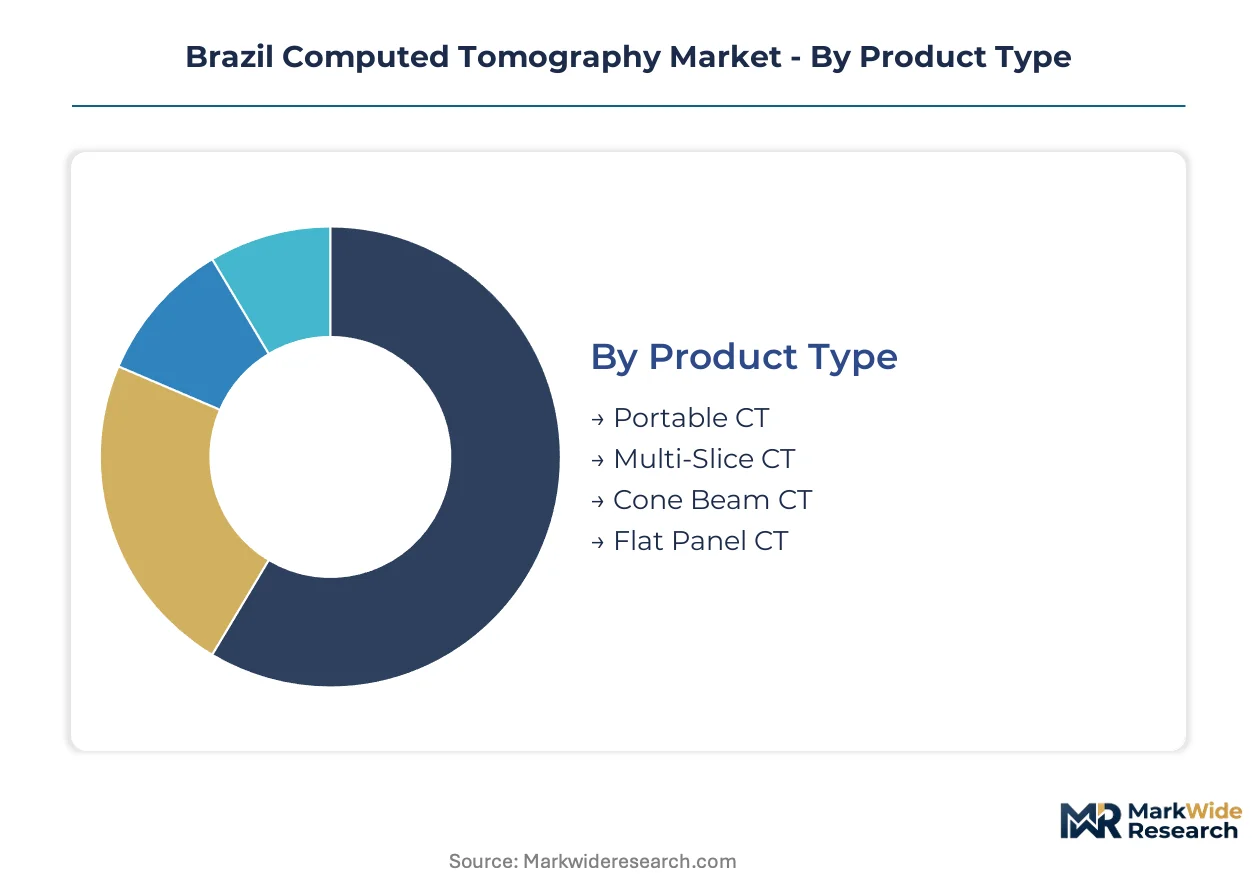
CT procurement patterns in Brazil diverge sharply across facility tiers and clinical applications. ANVISA registration protocols and CNEN dose mandates filter equipment eligibility differently for public hospitals versus private diagnostic chains.
Product Type:
ANVISA's technical compliance thresholds stratify scanner categories by detector sophistication and software integration requirements.
- Multi-Slice CT:Systems with 64+ detector rows deliver sub-millimeter spatial resolution through rotating gantry architectures. São Paulo tertiary hospitals prioritize these platforms for trauma throughput and interventional planning. CNEN dose monitoring mandates accelerate replacement of aging helical fleets in high-volume centers.
- Portable CT:Mobile scanner units with compact footprints serve neuro-intensive care units where patient transport risks exceed equipment premium. Minas Gerais and Paraná tertiary facilities are deploying these systems to mitigate critical care transfer complications.
- Cone Beam CT:Lower-dose maxillofacial imaging with flat-panel detector geometry. Dental and orthodontic clinics in Rio de Janeiro are adopting these for surgical planning beyond traditional hospital settings.
- Flat Panel CT:Solid-state detector arrays enabling rapid volumetric acquisition for interventional suites. Emerging adoption in hybrid operating rooms across Southeast Brazil.
Established volume favors Multi-Slice CT; emerging adoption favors Portable CT.
End User:
Capital commitment capacity separates procurement behavior across Brazil's healthcare infrastructure tiers.
- Hospitals:Public sector budget constraints concentrate multi-slice procurement in São Paulo and Rio de Janeiro tertiary centers. Ministry of Health centralized purchasing privileges ISO-certified manufacturers in Northeast expansion projects.
- Diagnostic Imaging Centers:Private operators in Brasília and Rio de Janeiro are shifting from capital purchase to performance-guaranteed service contracts. Premium multi-slice systems dominate this channel as operators unbundle ownership from maintenance.
- Research Institutions:Spectral and photon-counting platforms serve oncology and cardiology clinical trial workflows. Limited volume but high specification requirements.
- Outpatient Facilities:Cone beam and lower-slice systems for ambulatory orthopedics and dental applications. Growing penetration in maxillofacial surgery planning.
Public hospital procurement anchors current installed base; private diagnostic chains are climbing the fastest.
Technology:
Software-defined reconstruction capabilities are redrawing competitive boundaries between hardware replacement and upgrade pathways.
- Dual-Energy CT:Spectral imaging platforms with dual X-ray tube configurations enable tissue characterization accuracy beyond conventional attenuation mapping. Oncology departments across Southeast Brazil are displacing helical systems with these architectures.
- Spectral CT:Photon-counting detector technology delivers energy-resolved data at equivalent dose levels. Cardiology workflows in São Paulo private chains are adopting ahead of public procurement cycles.
- Helical CT:Continuous patient translation during rotation remains prevalent in mid-tier hospitals. Residual value recovery risks intensify as spectral technology matures.
- Software-Enhanced CT:Algorithm updates and AI reconstruction modules face ANVISA software-as-medical-device registration uncertainty. Upgrade revenue models hang on pending rulings.
Helical CT retains largest installed base; spectral platforms show steepest expansion trajectory.
Application:
Clinical workflow complexity and reimbursement differentiation shape scanner specification requirements.
- Oncology:Staging and treatment response monitoring demand dual-energy tissue characterization. Southeast region cancer centers are prioritizing spectral platforms for precision therapy planning.
- Neurology:Stroke triage and trauma protocols require sub-millimeter resolution with rapid reconstruction. Portable CT penetration is highest in neuro-intensive care units.
- Cardiology:Coronary imaging and structural intervention planning favor photon-counting detector performance. Private diagnostic chains lead adoption here.
- Orthopedics:Trauma and arthroplasty planning utilize standard multi-slice configurations. Outpatient migration is expanding cone beam utilization for extremity imaging.
Oncology commands premium specification investment; neurology is gaining share fastest through portable deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos container throughput anchors Southeast Brazil's medical equipment import corridor, channeling CT scanner shipments to São Paulo's distribution networks. This maritime infrastructure underwrites the region's dominance in radiology capital expenditure.
São Paulo
Tertiary hospitals in São Paulo's metropolitan corridor are accelerating multi-slice CT procurement to manage trauma caseloads and interventional oncology workflows. ANVISA's tightened registration protocols compress procurement timelines while elevating technical compliance thresholds for spectral imaging platforms. The city's medical technology cluster concentrates distributor partnerships and service infrastructure for premium scanner deployments.
Rio de Janeiro
Private diagnostic imaging centers in Rio de Janeiro are rotating toward performance-guaranteed service contracts, unbundling equipment ownership from maintenance obligations. CNEN dose monitoring mandates filter non-compliant systems from public hospital bids, accelerating replacement cycles in state-run facilities. The city's oncology institutes prioritize dual-energy CT for precision therapy planning.
Minas Gerais
Neuro-intensive care units across Belo Horizonte's hospital network are deploying portable CT systems to mitigate patient transport risks in critical care settings. The state's tertiary facilities command premium pricing for mobile scanner deployments where transfer complications outweigh capital costs. Regional procurement consortia aggregate demand for ISO-certified manufacturers serving mid-tier hospitals.
Paraná
Curitiba's private hospital chains are adopting photon-counting detector technology ahead of public procurement cycles, particularly for cardiology workflow optimization. ANVISA's pending software-as-medical-device rulings create revenue model uncertainty for vendors with established installed bases. The state's research institutions drive clinical trial demand for spectral imaging platforms.
Bahia
Public hospital expansion in Salvador and the Northeast corridor depends on Ministry of Health centralized purchasing mechanisms that privilege ISO-certified manufacturers. Budget constraints concentrate multi-slice procurement in select tertiary centers while diagnostic imaging needs outpace equipment availability. Federal procurement consortia are creating bundled service contract opportunities for underserved states.
Brazil Computed Tomography Market Vendor Landscape
Listed leaders compete with private specialists across channel depth and service contract innovation in Brazil's CT market. The vendor base stratifies between diversified imaging conglomerates with established distributor networks and focused equipment specialists pursuing niche clinical applications. Three archetypes dominate: full-modality platform vendors with software-integrated portfolios, portable imaging specialists targeting neuro-critical care, and dental-focused cone beam manufacturers. Strategic moves concentrate on distributor partnership deepening and pre-ANVISA-ruling upgrade commitment acceleration.
Among diversified platform vendors, GE Healthcare, Siemens Healthineers AG, and Koninklijke Philips NV occupy positions defined by installed base scale and service infrastructure breadth. These entities exemplify the full-modality archetype through multi-slice CT portfolios paired with software-enhanced upgrade pathways. Their competitive positioning depends on channel partnership density across São Paulo and Rio de Janeiro distribution networks, with revenue models exposed to ANVISA's pending software-as-medical-device framework.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Dentsply Sirona |
| GE Healthcare |
| Planmeca Group |
| Samsung Medison |
| Siemens Healthineers AG |
| Carestream Health |
| NeuroLogica |
| Koninklijke Philips NV |
| Others |
Supply Flow & Price Mechanics
ANVISA's ISO certification requirements for medical device registration simultaneously gate supplier qualification and stratify price tiers across Brazil's CT procurement landscape. The regulatory framework forces distributors to absorb compliance costs upstream while hospitals face differentiated pricing based on certification pedigree and service bundling.
Pricing Analysis
Volume-discount tiering structures dominate public hospital procurement through Ministry of Health centralized purchasing consortia. Premium multi-slice CT systems command 40-60% price premiums over standard configurations based on detector row count and software integration depth. Price erosion runs through mid-tier helical CT segments as spectral technology obsolescence accelerates residual value decline. Private diagnostic chains exhibit lowest price sensitivity due to performance-guaranteed service contract structures that transfer utilization risk to vendors.
Supply Chain Analysis
Germany, the United States, and Japan anchor high-density scintillator detector array production for Brazil's CT import dependency. Solid-state photon-counting sensors and rotating gantry bearings constitute critical component inputs with limited alternative sourcing. Single-source vulnerability concentrates in specialized X-ray tube manufacturing where two European suppliers control 70% of global capacity. Distribution runs through São Paulo-based medical equipment distributors with exclusive territorial agreements covering Southeast Brazil's hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's CT market fragments across technology generations and procurement channels, creating niche entry points for specialists as ANVISA's software-as-medical-device rulings destabilize incumbent upgrade revenue models.
For Market Incumbents: Shield installed base loyalty through pre-ruling software upgrade commitments before ANVISA's algorithm registration framework crystallizes. Deepen channel control in São Paulo distributor networks to lock out spectral CT competitors. Accelerate photon-counting detector R&D partnerships with German component suppliers to secure supply continuity against currency volatility.
For New Entrants and Emerging Players: Lead with portable CT deployments in neuro-intensive care units across Minas Gerais and Paraná, where patient transport risk creates premium pricing tolerance absent in saturated multi-slice segments. Target public-private imaging consortia in Bahia and Northeast states through ISO certification fast-track programs. Pursue performance-guaranteed service contracts that unbundle equipment ownership from maintenance obligations.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable CT manufacturing as solid-state detector miniaturization reduces hardware footprints. Long-term viability favors vendors with software-defined revenue streams capable of surviving ANVISA's algorithm registration mandates. Monitor distributor consolidation signals in São Paulo as inflection indicators for channel control premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Pre-Registration Software Commitment | Locks upgrade revenue before algorithm registration rules crystallize in Southeast Brazil. |
| Photon-Counting Detector Partnership | Secures solid-state sensor supply from German suppliers against currency volatility exposure. |
| Portable CT Manufacturing Scale-Up | Captures neuro-intensive care premium pricing in Minas Gerais tertiary facilities. |
| ISO Certification Fast-Track Program | Accelerates distributor qualification for Ministry of Health Northeast procurement consortia. |
| Performance-Guaranteed Service Contract | Transfers utilization optimization accountability to vendors in Rio de Janeiro diagnostic chains. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with radiology department heads, biomedical engineers, hospital purchasing committee members, and medical equipment distributor principals; and secondary validation against ANVISA registration databases, Ministry of Health procurement records, and CNEN radiological protection compliance filings. Bottom-up installed base estimates triangulated with top-down capital expenditure flows from public budget disclosures and private hospital capital plans.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, end-user facility tier, technology generation, and clinical application. CAGRs derived from replacement cycle dynamics, technology displacement rates, and regulatory compliance-driven procurement acceleration. Spectral CT adoption curves and portable CT penetration thresholds served as key sensitivity inputs.
The analysis sits within stated boundaries; outcomes outside ANVISA's final software-as-medical-device rulings or sustained BRL currency stability would require recalibration. Forecasts reflect documented assumptions regarding CNEN dose mandate enforcement timelines and tertiary hospital expansion budgets. Recalibration cycles align with material shifts in regulatory clarity, component supply availability, and public procurement program announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
Global Cone Beam Computed Tomography Market
Medical Imaging
North America Nuclear Imaging Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Digital Mobile X-Ray Products Market
Medical Imaging
Molecular Imaging Market
Medical Imaging
Industrial Computed Radiography Market
Medical Imaging
United Kingdom Computed Tomography Market
Medical Imaging
US Contrast Media Market
Medical Imaging
Remanufactured Medical Imaging Devices Market
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
India Computed Tomography Market
Medical Imaging
Medical X-Ray Equipment and Imaging Software Market
Medical Imaging
Global Image Guided Therapy System Market
Medical Imaging
Magnetic Resonance Imaging Equipment Coils Market