
 Magnetic Resonance Imaging Market | 2026-2036
Magnetic Resonance Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Resonance Imaging Market Outlook
The split between premium 3T systems and commodity 1.5T platforms is shifting procurement patterns across hospital networks. GE Healthcare leverages its helium-free magnet technology to reduce operational constraints in emerging markets. Siemens Healthineers anchors its position through dual-gradient architecture that shortens scan protocols. United Imaging competes aggressively on total cost of ownership, undercutting Western incumbents by roughly thirty percent in comparable configurations.
Magnetic resonance imaging deploys superconducting electromagnets, typically niobium-titanium coils cooled by liquid helium to 4 Kelvin, generating field strengths from 0.2 to 7 Tesla for tomographic reconstruction of soft tissue proton density. Closed MRI systems dominate installed base value due to superior signal-to-noise ratios, while open MRI configurations serve the bariatric and claustrophobic patient segments where accessibility constraints limit conventional bore utilization. Neurology applications command the largest procedure volume, though oncology imaging represents the fastest-expanding demand pool as multiparametric protocols enable tumor characterization without ionizing radiation exposure.
The FDA oversees device premarket approval and gadolinium-based contrast agent safety labeling, while the EU MDR imposes stricter clinical evidence requirements on MRI system manufacturers seeking CE marking. Japan's PMDA maintains distinct pharmacovigilance reporting for macrocyclic versus linear contrast agents, creating formulation divergence across regional supply chains. Stakeholders must monitor helium supply consolidation and alternative cooling technologies, as magnet sustainability will determine long-term service economics and replacement cycles.
Market Dynamics
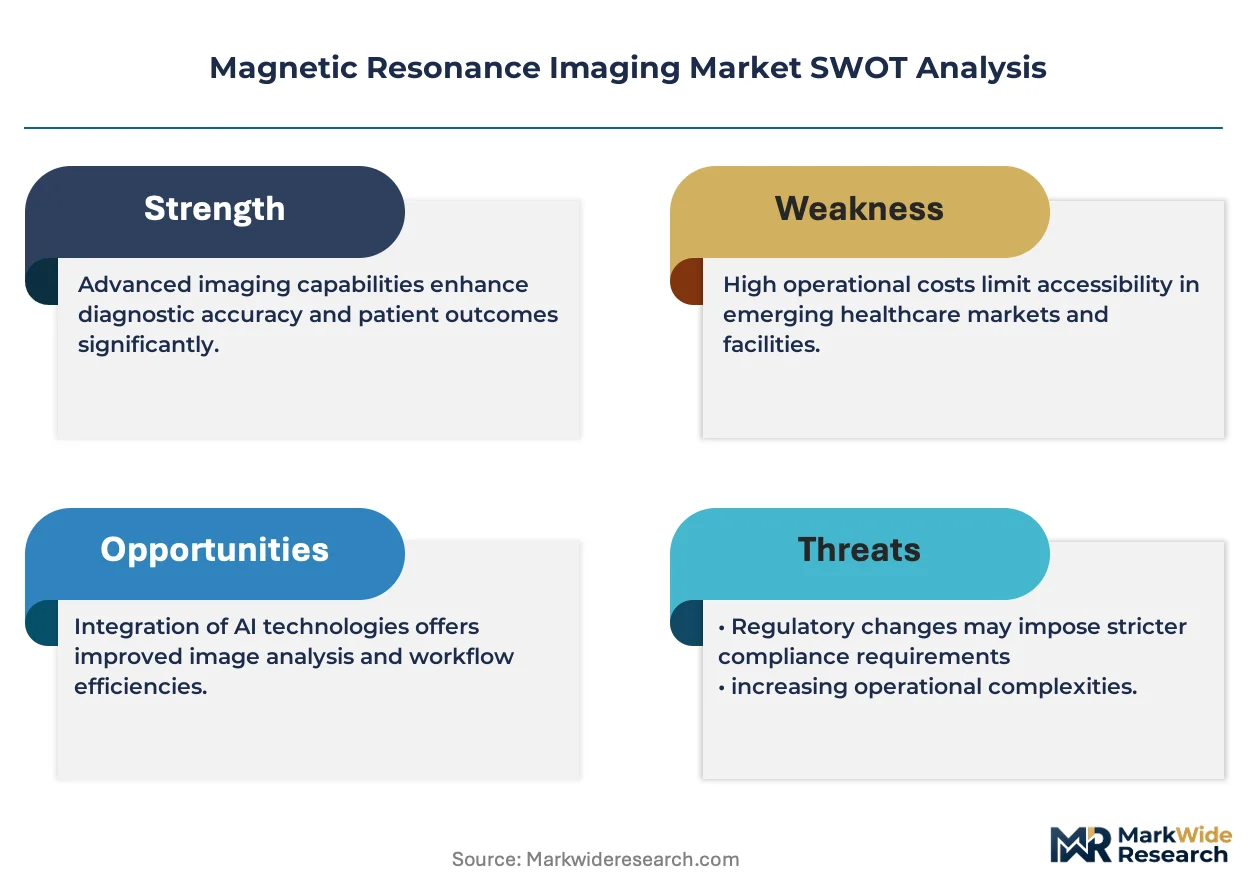
Helium supply consolidation and FDA gadolinium retention guidance are compressing operational margins while forcing magnet cooling technology transitions across hospital procurement cycles.
Growth Catalysts
- 3T System Replacement Cycles:Aging 1.5T installed bases in the United States, Germany, and China are driving fleet modernization as hospitals prioritize signal-to-noise ratio improvements for neurovascular diagnostics.
- EU MDR Clinical Evidence Requirements:Stricter CE marking pathways are filtering subscale manufacturers and concentrating procurement authority within integrated health networks capable of absorbing compliance costs.
- Multiparametric Oncology Protocols:Tumor characterization without ionizing radiation exposure is expanding MRI procedure volumes in tertiary hospital oncology departments.
Market Restraints
- Liquid Helium Supply Concentration:Qatar and the United States control over eighty percent of global helium production, exposing magnet service economics to export quota volatility.
- Gadolinium-Based Contrast Agent Safety Labeling:FDA retention warnings are extending procurement review timelines and elevating macrocyclic formulation costs.
- Superconducting Magnet Technical Limitations:Niobium-titanium coil cooling requirements constrain field strength scalability below 7 Tesla for commercial diagnostic platforms.
Strategic Opportunities
- Helium-Free Magnet Architectures:Conduction-cooled superconducting systems eliminate cryogen dependency and open procurement in helium-constrained emerging markets.
- Open MRI Configurations:Bariatric and claustrophobic patient segments remain underpenetrated by closed-bore systems, creating accessible volume for specialized equipment.
- Japan PMDA Macrocyclic Formulation Divergence:Regional pharmacovigilance reporting distinctions enable tailored contrast agent portfolios matching local regulatory preferences.
Industry Challenges
- Superconducting Coil Engineering Talent Scarcity:Niobium-titanium fabrication and cryogenic system design expertise concentrates within a limited supplier base, constraining OEM vertical integration options.
- Dual-Gradient Architecture Integration Complexity:Shortened scan protocol implementations require radiology workflow reconfiguration and technologist retraining across installed base upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Resonance Imaging Market |
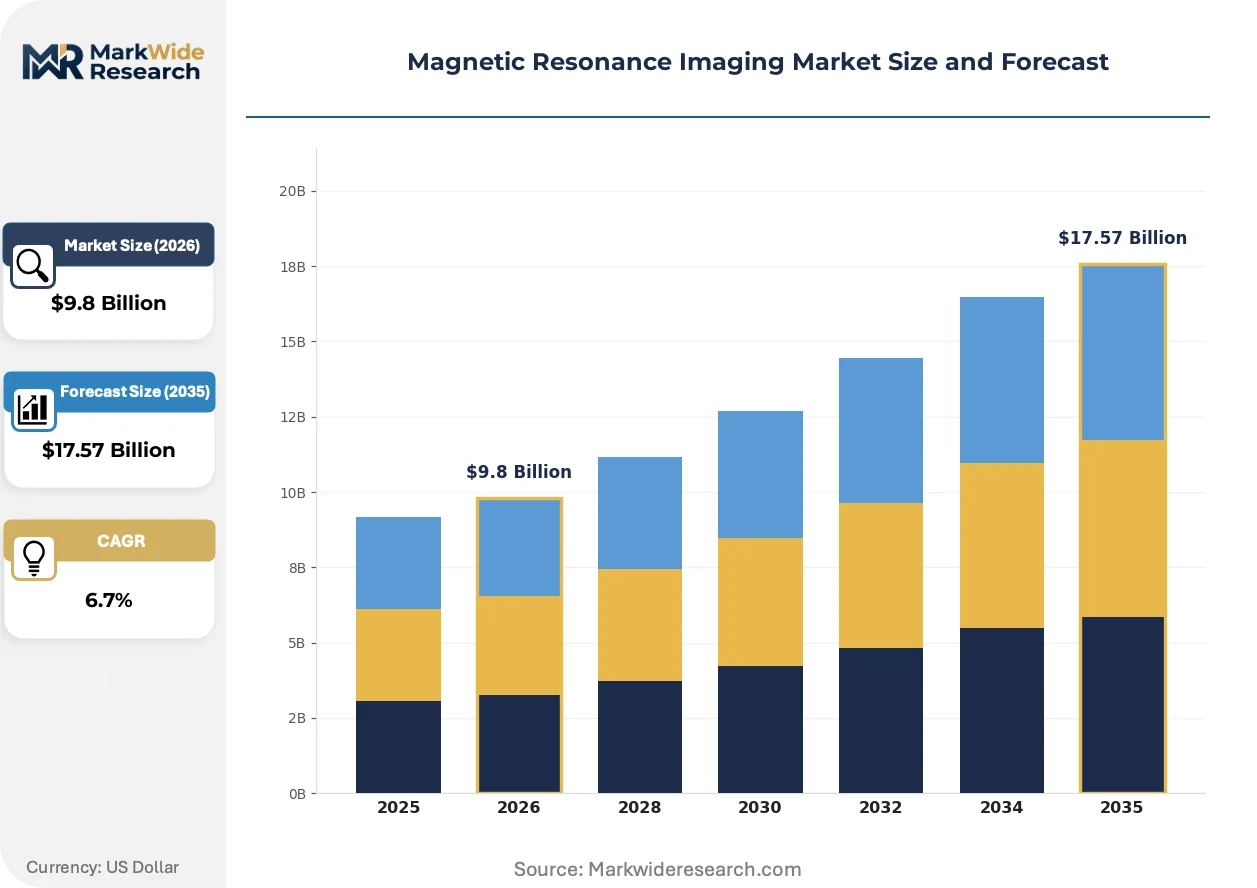
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Functional MRI End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Facilities Contrast Agent: Gadolinium-based, Iron-based, Macrocyclic Agents, Others Application: Neurology, Orthopedics, Cardiology, Oncology |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., Canon Medical Systems Corporation, FUJIFILM Holdings Corporation, ESAOTE SPA, Bruker Corporation, United Imaging Healthcare, FONAR Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Resonance Imaging Market Strategic Shifts
Artificial intelligence reconstruction algorithms and alternative cooling modalities are compressing scan durations while decoupling MRI deployment from helium supply chains.
Compressed sensing acquisition protocols are integrating deep learning reconstruction to maintain diagnostic quality at fractional scan times. Tertiary hospital radiology departments in the United States and Germany are adopting these workflows to increase daily throughput per magnet. Siemens Healthineers and GE Healthcare are positioning AI-accelerated sequences as standard configurations, forcing competitors to match software capabilities or concede high-volume accounts.
The FDA's enhanced gadolinium retention guidance is mandating macrocyclic agent preference in contrast-enhanced procedures. This labeling revision is elevating procurement costs for hospital pharmacies while compressing demand for linear chelate formulations. Oncology imaging centers are responding by consolidating purchasing through group purchasing organizations to offset per-dose price premiums.
Service unbundling from equipment contracts is altering capital allocation patterns among mid-sized hospital networks. Buyers in China and India are separating maintenance agreements from initial system purchases, pressuring OEM margins on recurring revenue streams. United Imaging is exploiting this preference with modular service tiers, compelling Western incumbents to restructure pricing architectures.
Magnetic Resonance Imaging Market Segmentation
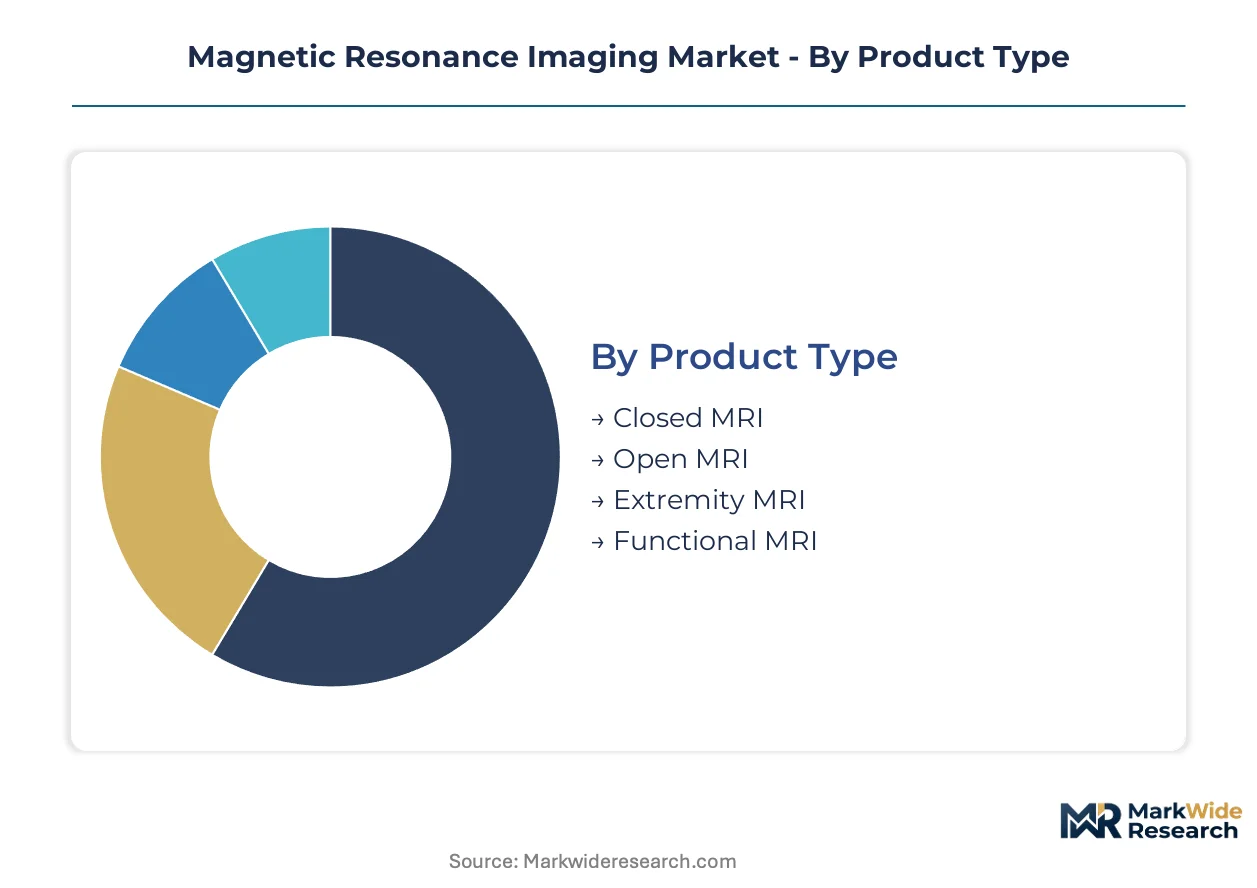
Magnetic resonance imaging segmentation reveals how technical specifications, clinical workflows, and procurement economics intersect across hospital networks. Understanding these divisions exposes where capital allocation concentrates and where technology transitions create procurement leverage.
Product Type:
Magnet architecture and bore configuration determine signal fidelity, patient throughput, and operational economics across installed bases.
- Closed MRI:Superconducting niobium-titanium coils cooled to 4 Kelvin generate field strengths of 1.5T to 3T within enclosed bore geometries. United States and German tertiary hospitals prioritize these systems for neurovascular diagnostics where signal-to-noise ratio directly impacts diagnostic confidence.
- Open MRI:Permanent magnet or resistive coil configurations eliminate the enclosed bore, sacrificing field strength for accessibility. Demand concentrates in bariatric and claustrophobic patient segments where conventional bore utilization fails.
- Extremity MRI:Dedicated limb-focused systems with compact footprints and lower capital requirements serve orthopedic practices and sports medicine clinics.
- Functional MRI:Blood-oxygen-level-dependent (BOLD) imaging capabilities enable real-time neural activity mapping for pre-surgical planning and research protocols.
Mature deployment sits with Closed MRI. Newer deployment is concentrated in Open MRI.
End User:
Procurement authority and utilization intensity vary sharply across facility types, shaping pricing architectures and service contract structures.
- Hospitals:Integrated health networks command the largest installed base value, with radiology departments managing high-throughput workflows across multiple magnet platforms. China's tertiary hospital expansion and Germany's fleet modernization are driving 3T replacement cycles.
- Diagnostic Centers:Specialized imaging facilities optimize throughput per square meter through extended operating hours and streamlined patient logistics. These buyers separate equipment purchases from service agreements more frequently than hospital networks.
- Research Institutions:Academic medical centers and university hospitals deploy 7T and above systems for protocol development, prioritizing field strength over patient volume.
- Outpatient Facilities:Ambulatory surgical centers and physician-owned clinics favor compact systems with simplified technologist requirements.
Volume concentration favors Hospitals. Margin expansion is steepest in Diagnostic Centers.
Contrast Agent:
Chelate chemistry and molecular structure determine safety profiles, regulatory classification, and pharmacy procurement costs.
- Gadolinium-based:Paramagnetic chelates enhance T1-weighted imaging across neurological, abdominal, and musculoskeletal protocols. FDA retention warnings are elevating macrocyclic preference and extending procurement review timelines.
- Iron-based:Superparamagnetic iron oxide nanoparticles target reticuloendothelial system imaging, particularly liver lesion characterization.
- Macrocyclic Agents:Rigid chelate structures exhibit lower dissociation rates and reduced tissue retention compared to linear formulations. Japan's PMDA maintains distinct pharmacovigilance reporting requirements, creating regional formulation divergence.
- Others:Manganese-based and novel nanoparticle formulations serve niche indications and research applications.
Regulatory pressure is compressing linear gadolinium deployment. Macrocyclic uptake is climbing the fastest.
Application:
Clinical indication drives protocol complexity, reimbursement rates, and magnet specification requirements across procurement decisions.
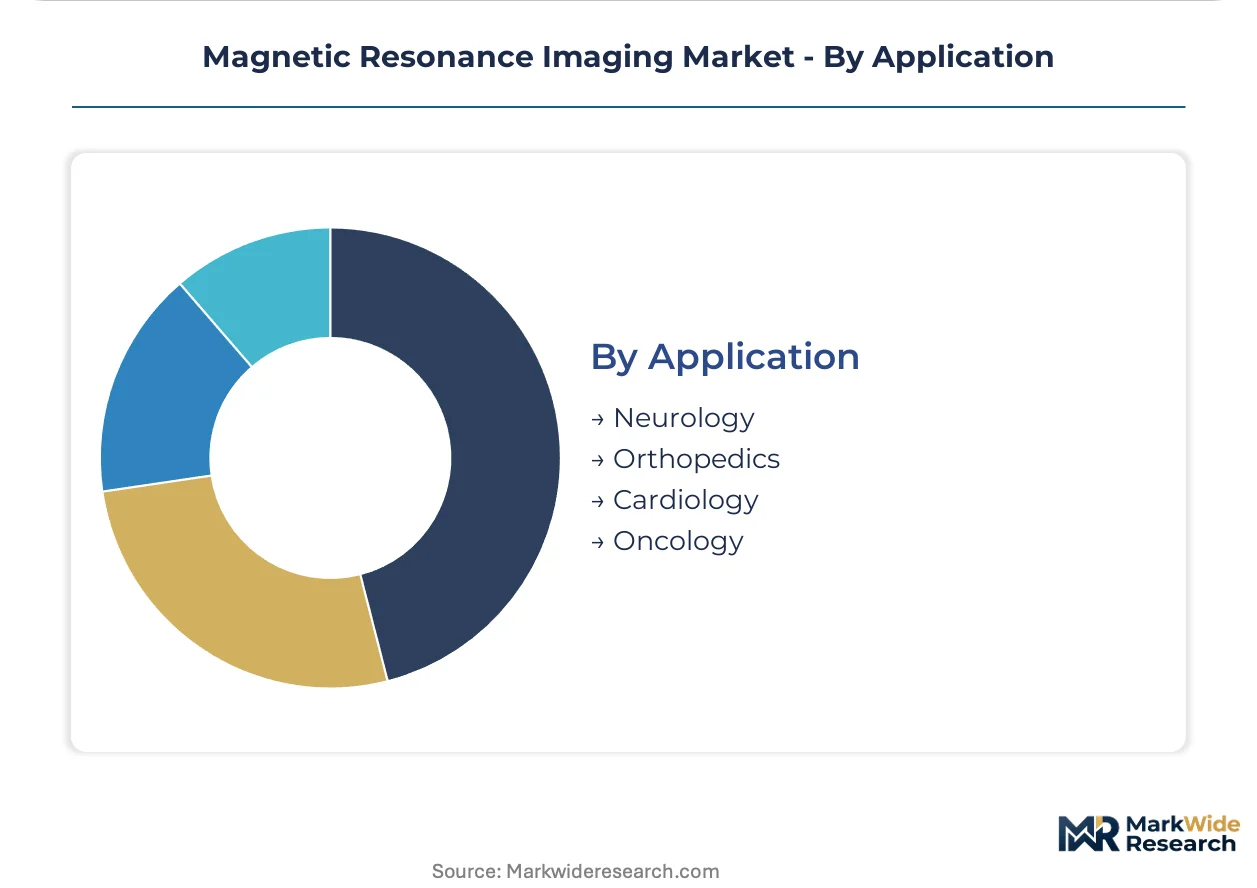
- Neurology:Brain and spinal cord imaging commands the largest procedure volume, with multiparametric protocols requiring advanced gradient performance and diffusion tensor capabilities.
- Oncology:Tumor characterization without ionizing radiation exposure is expanding MRI procedure volumes in tertiary hospital oncology departments. Multiparametric sequences enable staging and treatment response assessment.
- Orthopedics:Musculoskeletal imaging leverages high-resolution sequences for ligament, cartilage, and bone marrow evaluation. Extremity-dedicated systems serve this segment efficiently.
- Cardiology:Cardiac MRI requires ECG-gated sequences and specialized coils for functional assessment and viability imaging.
Established volume sits with Neurology. Steepest expansion trajectory belongs to Oncology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge medical technology corridor anchors North American MRI innovation, hosting concentrated R&D operations alongside major tertiary hospital networks that drive 3T system procurement cycles.
United States
Tertiary hospital networks in Massachusetts and California are replacing aging 1.5T systems with 3T platforms to improve neurovascular diagnostic confidence. FDA enhanced gadolinium retention guidance is extending pharmacy procurement review timelines and elevating macrocyclic agent preference. The Cleveland Clinic and Mayo Clinic anchor high-volume MRI service lines that validate AI-accelerated reconstruction protocols for commercial deployment.
Germany
Integrated health networks in Bavaria and North Rhine-Westphalia prioritize dual-gradient architecture systems to compress scan protocols and increase daily magnet throughput. EU MDR clinical evidence requirements are filtering subscale manufacturers from CE marking pathways. Siemens Healthineers anchors superconducting magnet engineering expertise in Erlangen, while university hospitals in Heidelberg and Munich validate 7T research platforms.
China
Tertiary hospital expansion in Shanghai and Beijing is driving fleet modernization as oncology departments scale MRI capacity for multiparametric tumor characterization. NMPA device registration pathways are converging toward international standards, accelerating local approval timelines for Western OEMs. United Imaging leverages domestic manufacturing in Shanghai to undercut Western incumbents on total cost of ownership across provincial hospital networks.
Japan
Academic medical centers in Tokyo and Osaka deploy 7T systems for pre-surgical neural mapping and research protocol development. PMDA maintains distinct pharmacovigilance reporting requirements for macrocyclic versus linear gadolinium agents, creating formulation divergence from Western supply chains. Canon Medical Systems anchors domestic MRI manufacturing in Tochigi Prefecture, serving both domestic demand and export markets across Southeast Asia.
India
Diagnostic center chains in Maharashtra and Karnataka are separating equipment purchases from service agreements to optimize capital allocation on compact 1.5T platforms. CDSCO medical device regulations are tightening import documentation requirements for superconducting systems. Apollo Hospitals and Max Healthcare operate high-throughput imaging networks in Delhi-NCR and Mumbai that validate helium-free magnet architectures for tropical deployment conditions.
Magnetic Resonance Imaging Market Competitive Environment
Premium-margin players sit above commodity-margin players across magnet cooling technology and gradient performance specifications. The vendor base stratifies into three tiers: integrated conglomerates with full modality portfolios, specialized MRI OEMs with focused engineering depth, and emerging Asian manufacturers competing on total cost of ownership. Two dominant competitive moves are reshaping positioning: helium-free magnet architecture development to decouple from cryogen supply chains, and AI-accelerated reconstruction software integration to compress scan durations and increase daily throughput.
Within the integrated conglomerate tier, GE Healthcare, Siemens Healthineers, and United Imaging Healthcare exemplify divergent strategic approaches to magnet technology and geographic penetration. GE Healthcare represents helium-free superconducting innovation targeted at emerging market constraints. Siemens Healthineers anchors dual-gradient architecture expertise concentrated in European engineering centers. United Imaging Healthcare occupies a position as the scale-driven challenger, leveraging domestic Chinese manufacturing to compress pricing on comparable 3T configurations.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| FUJIFILM Holdings Corporation |
| ESAOTE SPA |
| Bruker Corporation |
| United Imaging Healthcare |
| FONAR Corporation |
| Others |
Value Chain & Pricing Dynamics
Helium conservation mandates and cryogen-phaseout timelines gate qualified magnet supply and premium-tier pricing access for 3T and 7T platforms, compressing procurement options for hospitals unable to absorb conduction-cooled system premiums.
Pricing Analysis
Throughput-based pricing anchors procurement negotiations, with hospitals paying premiums for dual-gradient architectures that compress neurovascular scan protocols by thirty to forty percent. Three-tier pricing structure across premium, standard, and economy levels separates 3T closed-bore systems from 1.5T workhorse platforms and refurbished legacy magnets. Cost compression in the 1.5T tier is intensifying because United Imaging's domestic manufacturing undercuts Western incumbents on total cost of ownership. Diagnostic center chains exhibit highest price sensitivity, while academic medical centers prioritize field strength over acquisition cost.
Supply Chain Analysis
China's NMPA local-content requirements and India's CDSCO domestic assembly mandates are reshaping sourcing patterns for superconducting coil fabrication and cryogenic system integration. Niobium-titanium coil production draws from Japan, Germany, and the United States, while liquid helium supply concentrates in Qatar and the American Hugoton-Panhandle gas fields. Single-source vulnerability in helium extraction exposes magnet service economics to export quota volatility. Distribution runs through integrated health networks in developed markets and provincial hospital procurement consortia in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Conduction-cooled superconducting technology is displacing liquid helium-dependent architectures, forcing capital reallocation across OEM engineering roadmaps and hospital procurement cycles.
For Market Incumbents: Hedge helium supply exposure by accelerating in-house production of conduction-cooled magnet platforms and securing long-term niobium-titanium coil supply agreements with Japanese metallurgical suppliers. Siemens Healthineers and GE Healthcare must defend installed base service contracts against United Imaging's modular service tier incursion in Chinese provincial networks.
For New Entrants and Emerging Players: Group purchasing organizations represent the fastest channel to hospital pharmacy procurement committees seeking macrocyclic contrast agent consolidation. White-space concentration sits with open MRI configurations for bariatric and claustrophobic patient segments in Indian diagnostic center chains and Southeast Asian ambulatory facilities. Lead with total cost of ownership messaging against Western incumbents' premium positioning.
For Investors and Strategic Acquirers: FDA macrocyclic labeling revision completion is the leading indicator that contrast agent formulation portfolios will consolidate around rigid chelate structures, elevating specialized pharmaceutical manufacturers. Five-to-ten year viability favors OEMs with captive helium-free magnet technology and AI-accelerated reconstruction software stacks. Watch for NMPA approval acceleration for Western OEMs as signal of Chinese market access normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Helium-Free Magnet Platform Development | Eliminates cryogen dependency and opens procurement in Qatar supply-constrained emerging markets. |
| AI-Accelerated Reconstruction Software Integration | Compresses scan durations at Cleveland Clinic and Mayo Clinic, validating commercial deployment pathways. |
| Macrocyclic Contrast Agent Portfolio Consolidation | Aligns with FDA retention guidance and Japan PMDA pharmacovigilance reporting requirements. |
| Dual-Gradient Architecture Deployment | Shortens neurovascular protocols at German integrated health networks, increasing daily magnet throughput. |
| Service Contract Unbundling | Matches United Imaging's modular tiers to retain Chinese and Indian mid-sized hospital network accounts. |
Study Parameters
Multi-period observation of FDA gadolinium retention guidance implementation, EU MDR CE marking pathway completion rates, and NMPA registration timeline convergence anchored the trend analysis, supplemented by interviews with radiology department heads, hospital procurement committee chairs, biomedical engineering directors, and GPO contracts managers. Secondary validation drew from FDA 510(k) and PMA filings, EUDAMED device registration data, CMS Medicare imaging procedure volume records, and OEM SEC 10-K segment disclosures. Bottom-up installed base modeling and top-down healthcare capital expenditure triangulation cross-checked volume and value estimates.
Input-output matrix framing mapped magnet field strength specifications, gradient performance tiers, and cooling technology categories against hospital network replacement cycles and diagnostic center expansion patterns across the projection horizon. Segmentation dimensions modeled included product architecture, end-user facility type, contrast agent chemistry, and clinical application indication. CAGRs were derived from logistic diffusion curves fitted to 3T system adoption rates and helium-free platform penetration assumptions, with sensitivity testing around Qatar helium export quota volatility and macrocyclic agent price elasticity.
Caveats apply where FDA contrast agent labeling revisions, EU MDR clinical evidence requirement enforcement intensity, or China NMPA local-content rule expansion could materially shift the outlook for Western OEM market access and procurement timeline assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
US Interventional Radiology Market
Medical Imaging
Canada Nuclear Medicine Market
Medical Imaging
Global Refurbished Medical Imaging Equipment Market
Medical Imaging
Image Guided Radiotherapy Market
Medical Imaging
Carotid Ultrasound Imaging Market
Medical Imaging
Asia-Pacific Digital Radiology Market
Medical Imaging
Middle East and Africa Mammography Market
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
Canada Digital Radiology Market
Medical Imaging
France Computed Tomography Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Cone Beam CT Scanner Market
Medical Imaging
US Magnetic Resonance Imaging Coils Market
Medical Imaging
Brazil Nuclear Imaging Market
Medical Imaging
Medical X-Ray Films Market
Medical Imaging
South America Fluoroscopy Market