
 Reflective Air Bags Market | 2026-2036
Reflective Air Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Reflective Air Bags Market Analytics
Modular air bag system bundling is broadening buyer choice as automakers specify integrated cockpit protection modules rather than discrete components. Autoliv Inc. leverages its global manufacturing footprint to supply multi-chamber curtain systems across premium vehicle platforms. Joyson Safety Systems anchors its position through captive relationships with Chinese OEMs and localized production capacity. Continental AG differentiates via sensor-to-deployment integration spanning electronic control units and inflator hardware.
Reflective air bags incorporate woven textile substrates with metallized or glass-bead reflective coatings engineered to enhance occupant visibility during low-light collision events and post-crash rescue operations. Manufacturing employs precision coating lamination onto nylon or polyester base fabrics followed by cut-and-sew assembly with gas generator integration, yielding modules that deploy within milliseconds while maintaining reflective integrity. Curtain air bags represent the fastest-growing product configuration as side-impact protection mandates expand across vehicle classes. Electronic deployment technology leads the technology split due to its compatibility with multi-point crash sensing architectures. OEM end users command the dominant demand channel through long-term supply agreements tied to vehicle platform life cycles.
NHTSA Federal Motor Vehicle Safety Standards govern deployment force limits and occupant positioning compatibility in the United States, while ECE R94 and R95 regulations establish side-impact protection requirements across European type-approval frameworks. Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces mandatory front air bag fitment under its safety certification regime. Stakeholders must monitor divergent regional test protocols for out-of-position occupant scenarios as these standards reshape module design specifications and validation timelines.
Market Dynamics
NHTSA occupant protection mandates and Euro NCAP rating protocols are tightening deployment performance thresholds, forcing module redesigns and validation cycle compression across supplier networks.
Growth Catalysts
- Side-impact mandate expansion:ECE R94 and R95 regulations now cover light commercial vehicles and electric platforms, widening addressable module volumes beyond traditional passenger car segments.
- Low-light visibility requirements:Emergency responder protocols in Germany and Japan now specify post-crash occupant location marking, creating pull-through demand for metallized textile integration.
- Multi-chamber curtain architectures:Electronic deployment technology enables zonal inflation control, allowing single modules to protect front and rear occupants with differentiated pressure profiles.
Market Restraints
- Inflator propellant cost volatility:Sodium azide and guanidine nitrate prices fluctuate with specialty chemical feedstock markets, compressing margin predictability for cut-and-sew assemblers.
- German engineering concentration:Tier-one integrators co-locate validation centers in Stuttgart and Wolfsburg corridors, creating geographic supply risk for programs requiring rapid design iteration.
- Out-of-position test complexity:Divergent NHTSA and Euro NCAP protocols for small-stature occupant scenarios force parallel validation tracks, extending development timelines.
Strategic Opportunities
- Chinese EV platform penetration:Domestic OEMs are localizing curtain module sourcing, creating entry points for suppliers with captive nylon weaving and coating lamination capabilities.
- Sensor-to-deployment integration:Convergence of electronic control units with textile module hardware enables single-source contracting for crash management subsystems.
- Post-crash rescue standardization:ISO technical committees are drafting reflective material performance specifications, potentially harmonizing procurement specifications across national type-approval frameworks.
Industry Challenges
- Millisecond deployment precision:Gas generator integration with woven substrates requires sub-micron coating thickness control, constraining qualified supplier pools.
- Platform lifecycle lock-in:Long-term supply agreements tied to vehicle programs limit supplier mobility and compress pricing leverage during mid-cycle contract renegotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reflective Air Bags Market |
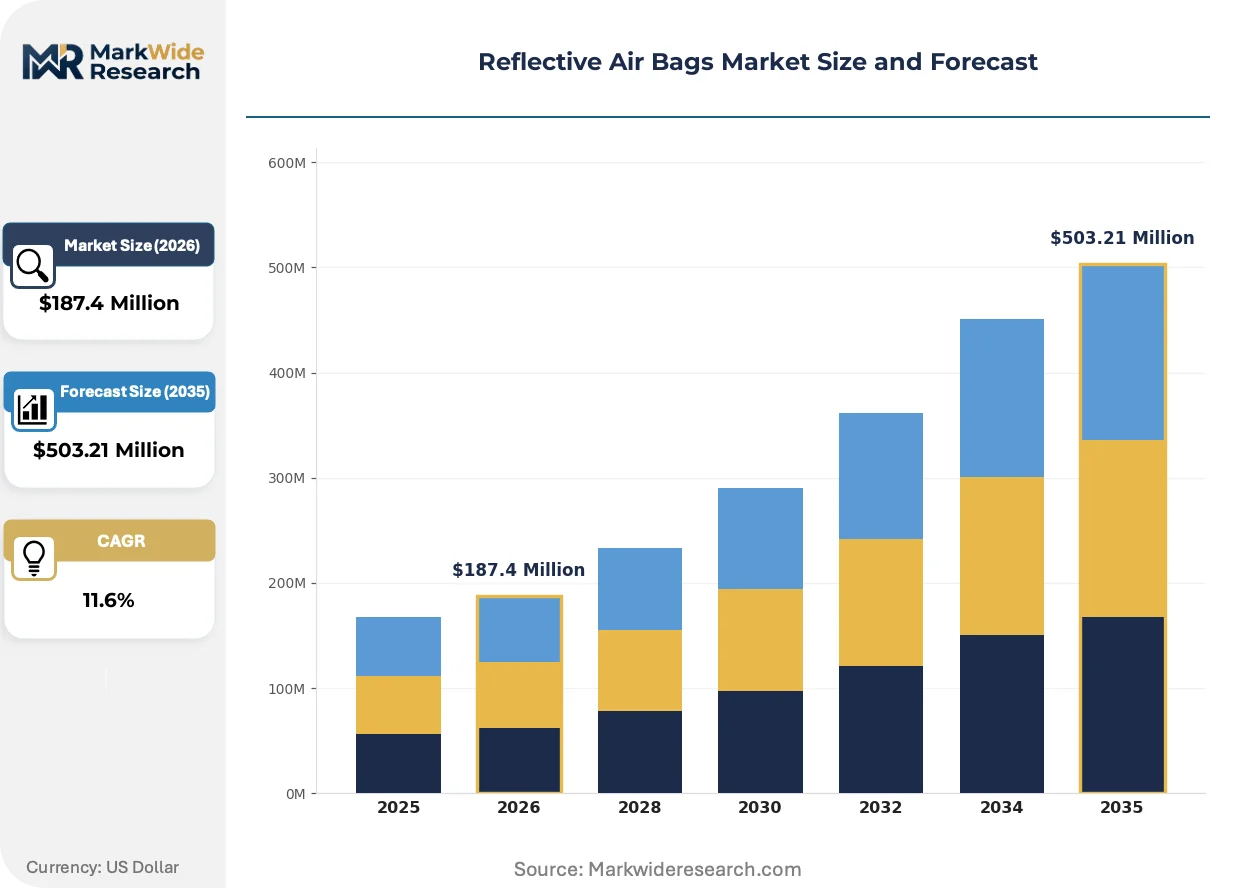
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Air Bags, Side Air Bags, Curtain Air Bags, Knee Air Bags Technology: Mechanical, Electronic, Hybrid, Inflatable End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Others |
| Companies Covered | Autoliv Inc., Takata Corporation, Zhejiang Jincheng Group, Nihon Plast Co., Ltd., Continental AG, Denso Corporation, Robert Bosch GmbH, Joyson Safety Systems, Hyundai Mobis Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reflective Air Bags Market Evolving Landscape
Reflective air bag manufacturing is pivoting from discrete component supply toward integrated cockpit protection subsystems, with coating lamination precision and electronic deployment architectures as the primary technical battlegrounds.
Glass-bead reflective coatings engineered for high-visibility textile substrates are expanding into premium electric vehicle platforms where extended rescue timelines increase occupant location criticality. German and Japanese OEMs specify these materials for curtain modules in luxury segments, compressing the adoption cycle that previously required decade-long regulatory incubation. The technology is expanding into adjacent visibility applications including seat belt webbing and interior trim surfaces.
Euro NCAP's 2026 roadmap incorporates far-side impact protection scoring, mandating center-mounted air bag deployment that exceeds current side-curtain geometries. This regulatory pressure forces module suppliers to revalidate gas generator output curves and textile tear seam designs. European type-approval frameworks are responding fastest, with KBA and French homologation bodies issuing draft test protocols ahead of formal ECE regulation updates.
Fleet procurement of integrated safety modules is consolidating supplier relationships around single-source electronic control unit providers. Tier-one integrators now bundle sensor hardware, deployment logic, and textile modules under unified program management, displacing discrete component sourcing. This pattern is most visible in United States commercial vehicle programs where total cost of ownership calculations favor subsystem consolidation over best-of-component strategies.
Reflective Air Bags Market Segmentation
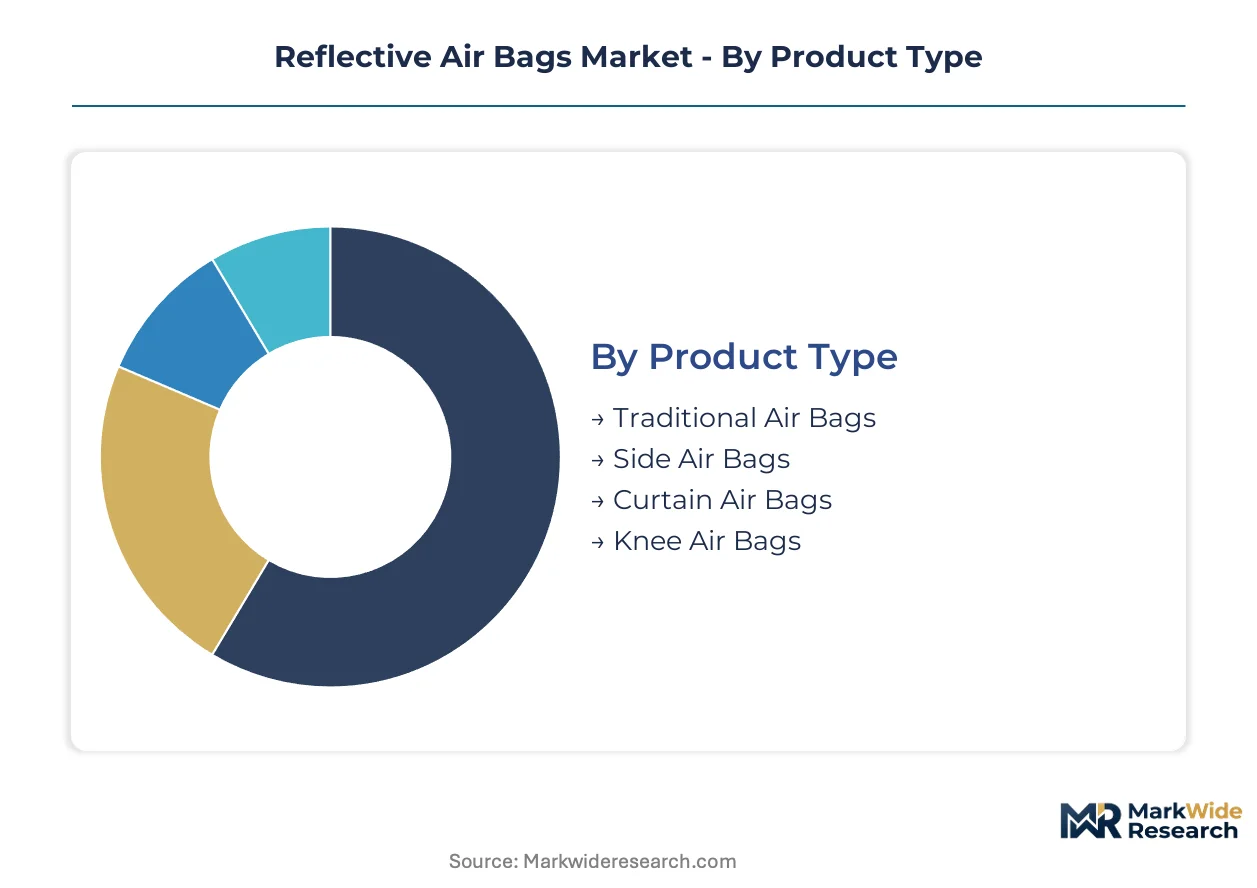
Reflective air bag procurement patterns diverge sharply across vehicle programs, with regulatory mandates and platform architecture dictating module specifications rather than buyer preference alone. Segment boundaries reflect supply chain capability requirements as much as end-use application differences.
Product Type:
Buyers in this category differentiate by crash scenario coverage and installation geometry rather than unit economics, with platform safety ratings driving specification choices.
- Curtain Air Bags:These modules deploy from roof rails to shield occupant heads during side-impact and rollover events, utilizing elongated gas generators with zonal inflation chambers. Procurement concentrates in Germany and Japan where Euro NCAP and the country's Ministry of Land, Infrastructure, Transport and Tourism enforce side-impact protection mandates that exceed baseline requirements. The fastest-expanding segment gains share as electric vehicle architectures extend roofline dimensions and increase protected cabin volume.
- Side Air Bags:Seat-mounted or door-integrated modules protect thorax and pelvic regions through compact pyrotechnic inflators paired with tear-seam textile housings. United States passenger vehicle programs generate concentrated demand following NHTSA Federal Motor Vehicle Safety Standards that mandate side-impact performance for light vehicles. Adoption accelerates as mid-size crossover platforms proliferate and automakers consolidate module sourcing across regional variants.
- Traditional Air Bags:Steering wheel and dashboard-mounted frontal modules retain specification dominance in emerging market vehicle programs with cost-constrained safety budgets.
- Knee Air Bags:Lower-dashboard modules mitigate femur loading and pelvic submarining in severe frontal crashes, specified primarily in premium vehicle segments.
Volume sits with traditional frontal modules in cost-sensitive programs; growth tilts toward curtain architectures as side-impact mandates broaden.
Technology:
Technology selection tracks with platform electronic architecture maturity, with newer vehicle programs favoring deployment systems that integrate with multi-sensor crash detection networks.
- Electronic:Microprocessor-controlled deployment systems process accelerometer and pressure sensor inputs to calculate inflation timing and pressure curves with millisecond precision. These systems anchor specification in Japan and Germany where vehicle manufacturers specify subsystem integration with electronic control unit providers. The technology commands premium positioning through compatibility with advanced driver-assistance system architectures and predictive crash sensing capabilities.
- Mechanical:Spring-mass and ball-in-tube sensors trigger deployment through purely physical inertia mechanisms without electrical signal processing. Fleet operators in commercial vehicle segments specify these systems for field serviceability and electromagnetic immunity in heavy-duty operating environments. Demand persists where total cost of ownership calculations prioritize component longevity over sensing sophistication.
- Hybrid:Combined mechanical-electronic sensing architectures bridge legacy platform constraints and modern integration requirements.
- Inflatable:Specialized modules for non-occupant protection applications including pedestrian impact mitigation and external air bag systems.
Electronic systems capture revenue concentration in premium platforms; mechanical architectures defend position in commercial and heavy-duty segments.
End User:
End user category reflects contract structure complexity, with long-term supply agreements versus spot procurement creating divergent supplier relationship patterns.
- OEMs:Vehicle manufacturers specify reflective air bag modules through platform lifecycle contracts spanning five to seven years, with engineering co-development requirements locking supplier relationships early in vehicle development. German and United States OEMs concentrate procurement authority at engineering centers in Stuttgart, Wolfsburg, and Detroit corridors.
- Aftermarket Providers:Independent distributors and repair networks source replacement modules through authorized channels with strict traceability requirements for pyrotechnic components.
- Vehicle Assemblers:Contract manufacturing operations for emerging market OEMs procure modules on shorter lead times with localized validation.
- Fleet Operators:Commercial vehicle fleet managers negotiate subsystem bundles including electronic control units and deployment hardware under total cost of ownership frameworks.
OEM channel dominates contract value; aftermarket volume expands with vehicle parc aging and regulatory inspection tightening.
Application:
Application segmentation aligns with regulatory jurisdiction boundaries, with passenger and commercial vehicle categories subject to divergent type-approval frameworks and test protocols.
- Passenger Vehicles:Light duty cars and crossover utility vehicles specify multi-chamber curtain systems with reflective textile integration for post-crash rescue visibility. Japanese and German OEMs lead specification of glass-bead reflective coatings in luxury electric platforms where extended rescue timelines increase occupant location criticality.
- Commercial Vehicles:Light and medium duty trucks require side air bag modules under expanded ECE R94 and R95 coverage, with fleet procurement favoring mechanical deployment technology for field durability.
- Two-Wheelers:Motorcycle air bag systems remain nascent with limited regulatory mandate and technical challenges in deployment geometry.
- Others:Specialized applications including off-highway equipment and agricultural machinery with customized mounting and environmental sealing.
Passenger vehicle specifications anchor module revenue; commercial vehicle applications climb fastest as mandate expansion widens addressable volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany, Japan, and the United States where tier-one integrators co-locate engineering centers with vehicle manufacturers. Consumption spreads across these same markets as NHTSA and Euro NCAP mandates tighten deployment thresholds.
Germany
Curtain air bag procurement concentrates in Stuttgart and Wolfsburg corridors where OEM engineering centers validate multi-chamber modules. KBA homologation protocols enforce ECE R94 and R95 side-impact requirements ahead of formal EU regulation updates. Glass-bead reflective coatings gain specification in luxury electric platforms manufactured across Bavaria and Baden-Württemberg.
United States
NHTSA Federal Motor Vehicle Safety Standards mandate side-impact performance for light vehicles, driving module specification across passenger and commercial segments. Detroit-area engineering centers lock supplier relationships through platform lifecycle contracts spanning five to seven years. Fleet procurement in the Midwest favors mechanical deployment technology for field durability in heavy-duty operating environments.
Japan
The Ministry of Land, Infrastructure, Transport and Tourism enforces mandatory front air bag fitment under national safety certification. Electronic deployment technology anchors specification in Tokyo and Nagoya metropolitan manufacturing zones. Curtain modules with metallized textile integration penetrate domestic OEM programs as side-impact mandates expand to light commercial vehicles.
China
Domestic OEMs localize curtain module sourcing, creating entry points for suppliers with captive nylon weaving and coating lamination capabilities. Yangtze River Delta and Pearl River Delta clusters concentrate cut-and-sew assembly capacity for both export and domestic consumption. MIIT vehicle safety standards tighten in parallel with Euro NCAP alignment efforts.
South Korea
Seoul Capital Area manufacturers specify electronic control unit integration with textile module hardware under single-source contracting frameworks. Busan-Ulsan automotive corridors supply multi-chamber curtain systems for export-oriented vehicle programs. Domestic OEMs accelerate reflective material adoption as post-crash rescue protocols formalize occupant location marking requirements.
Reflective Air Bags Market Competitive Landscape
The competitive structure tilts toward tier-one integrators with captive relationships to major OEM engineering centers. Three to four global suppliers command the majority of platform lifecycle contracts through co-development requirements that lock specifications early in vehicle development. Two strategic archetypes dominate: full-system integrators bundling sensor hardware with textile modules, and component specialists supplying precision-coated substrates to assembly partners. Competitive moves center on geographic co-location with OEM validation centers and backward integration into nylon weaving and coating lamination capabilities.
Among the established integrators, Autoliv Inc. and Joyson Safety Systems exemplify the full-system archetype with positions spanning electronic deployment technology and textile module supply. Continental AG occupies a comparable tier through sensor-to-deployment integration spanning control units and inflator hardware. Zhejiang Jincheng Group represents the specialist fabricator category with capabilities in precision coating lamination for reflective textile substrates. Hyundai Mobis Co., Ltd. anchors Korean-market sourcing relationships. Robert Bosch GmbH and Denso Corporation sit within the electronic control and sensing tier that supplies deployment logic to module assemblers.
| Leading Market Players |
|---|
| Autoliv Inc. |
| Takata Corporation |
| Zhejiang Jincheng Group |
| Nihon Plast Co., Ltd. |
| Continental AG |
| Denso Corporation |
| Robert Bosch GmbH |
| Joyson Safety Systems |
| Hyundai Mobis Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap fabricators in Germany and Japan anchor supply discipline through captive nylon weaving operations, translating raw material cost volatility into selective pricing power over aftermarket distributors while contract manufacturers absorb margin compression.
Pricing Analysis
Margin tightening in standard-grade modules reflects sodium azide and guanidine nitrate feedstock volatility, compressing assembler economics. Three-tier pricing structure across premium, standard, and economy levels separates multi-chamber electronic systems from mechanical deployment units. Pricing pressure stems from OEM lifecycle contract lock-in that limits renegotiation leverage. Fleet operators exhibit highest price sensitivity; luxury electric platforms show lowest.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Wolfsburg, and Detroit corridors operate hub-and-spoke patterns feeding just-in-time assembly lines. Manufacturing concentrates in Germany, Japan, and the United States. Production draws from specialty chemical feedstocks, precision-coated textile substrates, and microprocessor-controlled gas generators. Single-source vulnerability sits with qualified coating lamination suppliers. Distribution runs through tier-one integrator warehouses co-located with OEM engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic deployment architectures are displacing mechanical sensing systems across premium vehicle platforms, compressing adoption timelines for subsystem integrators.
For Market Incumbents: Deploy sensor-to-deployment integration capabilities to defend against discrete component displacement. Deepen captive relationships with Chinese OEMs through localized coating lamination capacity. Lock platform lifecycle contracts early in vehicle development cycles before Euro NCAP 2026 far-side impact mandates reshape specifications. For New Entrants and Emerging Players: Enter via domestic EV platform sourcing in China's Yangtze River Delta, where tier-one integrators lack captive nylon weaving. Target curtain module supply for light commercial vehicles under expanded ECE R94 and R95 coverage. Pursue single-source electronic control unit bundling as the go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision coating specialists with automotive textile certifications in South Korea and China. Five-to-ten year viability hinges on backward integration into gas generator hardware. Watch ISO reflective material specification finalization as inflection signal for procurement harmonization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nylon Weaving | Captive substrate supply secures coating lamination quality control against qualified supplier scarcity. |
| Multi-Chamber Curtain System Launch | Zonal inflation architectures address Euro NCAP far-side impact scoring ahead of formal mandate. |
| Electronic Control Unit Partnership | Single-source contracting with Bosch or Denso displaces discrete component procurement patterns. |
| Chinese EV Platform Penetration | Localized production in Yangtze River Delta clusters captures domestic OEM sourcing shifts. |
| ISO Reflective Material Certification | Harmonized procurement specifications across KBA, NHTSA, and MLIT type-approval frameworks reduce parallel validation. |
Research Methodology
Independent corroboration across tier-one supplier procurement directors, OEM platform engineers, and aftermarket distribution managers underwrites the qualitative findings. Primary fieldwork with coating lamination specialists and gas generator technical leads combined with secondary validation from NHTSA Federal Motor Vehicle Safety Standards filings, ECE R94 and R95 type-approval databases, and vehicle production registration data. Bottom-up module volume estimates triangulated against top-down safety content per vehicle analysis.
Rate-of-change decomposition across the analysis window segments volume by product type, technology architecture, end-user contract structure, and regional regulatory cluster. CAGRs derived from platform lifecycle contract timing, mandate phase-in schedules, and electric vehicle architecture adoption curves. Forecast inputs include OEM engineering center co-location patterns and reflective material specification harmonization progress.
Forecast precision tightens around the base case; tail outcomes carry wider variance under inflator propellant cost spikes or divergent out-of-position test protocol delays. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market
Automotive Interior & Exterior
Automotive in-Cabin Air Quality Improvement Solutions Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
Automotive Headlamp Reflector Market
Automotive Interior & Exterior
LED-Based Exterior Navigation and Position Lighting Systems Market
Automotive Interior & Exterior
Auto Ventilated Seats Market
Automotive Interior & Exterior
Automotive Interior Bovine Leather Market
Automotive Interior & Exterior
Fog Free Mirrors Market
Automotive Interior & Exterior
Automotive OE Bumper Cover Market
Automotive Interior & Exterior
Bonnet Lock Plate and Latch Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market
Automotive Interior & Exterior
Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Steering Wheel Covers Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Auto Glass Encapsulation Market
Automotive Interior & Exterior
Europe Automotive Upholstery Market