
 Global Automotive Rear Window Blinds Market | 2026-2036
Global Automotive Rear Window Blinds Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Rear Window Blinds Market Intelligence
The market for automotive rear window blinds is pivoting on the divergence between OEM-integrated motorized systems and aftermarket manual solutions. BOS GmbH & Co. KG specializes in complex mechatronic systems for premium automotive brands, while Inalfa Roof Systems Group BV integrates these into larger interior comfort modules. MACAUTO INDUSTRIAL CO., LTD leverages its manufacturing scale to supply a broad range of product types across channels.
Automotive rear window blinds are manually or electronically operated screens designed to cover a vehicle's rear windshield. Constructed from materials like polyester or PVC laminated mesh fabric, they primarily function to reduce solar heat gain, block UV radiation, and enhance passenger privacy. Motorized blinds represent the fastest-growing product category, driven by their integration into new SUVs and passenger cars through OEM channels. The aftermarket segment, served by online marketplaces, remains a stable, high-volume channel for manual blinds and retractable sunshades.
Vehicle interior safety standards, such as those mandated by the US NHTSA and China's GB standards, govern material flammability and component design. In Europe, CE marking requirements ensure that motorized blind systems comply with electronic safety and electromagnetic compatibility directives. Suppliers must navigate these varied regional compliance pathways while deciding where to invest in either advanced mechatronic capabilities or high-volume fabric production.
Market Dynamics
The market's central dynamic is the bifurcation between high-cost, OEM-integrated mechatronic systems for premium vehicles and high-volume, price-sensitive manual blinds sold through aftermarket channels. This split dictates design, material choice, and distribution strategies.
Growth Catalysts
- Premium Vehicle Demand:Strong consumer appetite for premium SUVs and limousines, particularly in the United States and Germany, directly increases the fitment rate of integrated rear window blinds as standard or optional equipment.
- Material Science Advances:Innovations in PVC laminated and acrylic coated fabrics offer improved UV protection, heat reduction, and durability, aligning with consumer demand for enhanced cabin comfort and material longevity.
- Automotive Manufacturing Hubs:The concentration of vehicle production in Germany, Japan, and the United States creates dense ecosystems of demand, where OEMs and Tier 1 suppliers co-locate, accelerating adoption cycles.
Market Restraints
- High System Complexity:Motorized blinds require costly micro-motors, sensors, and control units, increasing the bill of materials and making them unsuitable for economy vehicle segments where cost is the primary concern.
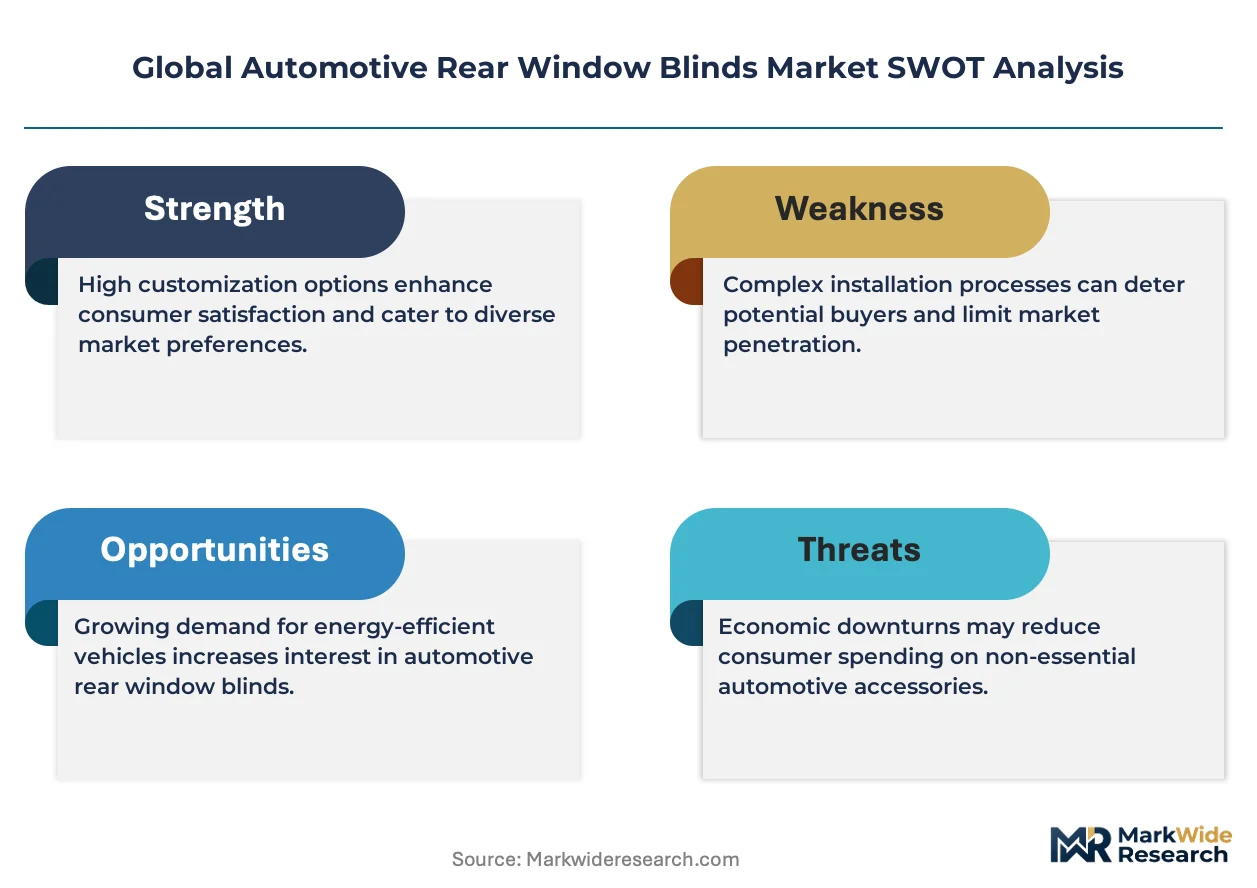
- Aftermarket Substitution:The widespread availability of low-cost, universal-fit retractable sunshades and static cling films presents a significant substitution threat, particularly in the budget-conscious aftermarket segment.
- Fragmented Regulatory Compliance:Suppliers must navigate disparate safety and material standards, such as NHTSA rules in the US and GB standards in China, increasing testing costs and design complexity for global platforms.
Strategic Opportunities
- Smart Cabin Integration:There is an opportunity to link motorized blinds with vehicle climate control and infotainment systems, enabling automated adjustments based on sun load sensors, time of day, or passenger preferences.
- Emerging Market Penetration:Aftermarket suppliers can target growing middle-class consumer bases in automotive markets like India and Brazil with affordable, easy-to-install manual and retractable blind solutions.
- Lightweighting Materials:Development of blinds using carbon fiber composites or advanced polymer textiles offers an opportunity to reduce weight, appealing to electric vehicle manufacturers focused on maximizing battery range.
Industry Challenges
- ECU Integration:Ensuring seamless communication between the blind's motor control unit and the vehicle's central CAN bus network without introducing electronic interference is a persistent engineering challenge for suppliers.
- Supply Chain Adaptation:Shifting from purely mechanical production to mechatronics requires establishing new supply chains for electronic components, which involves different qualification processes than for fabrics and plastics.
- Certification Bottlenecks:Obtaining CE marking for electromagnetic compatibility in Europe can be a lengthy process for motorized systems, potentially delaying vehicle program launches and creating scheduling conflicts for OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Rear Window Blinds Market |
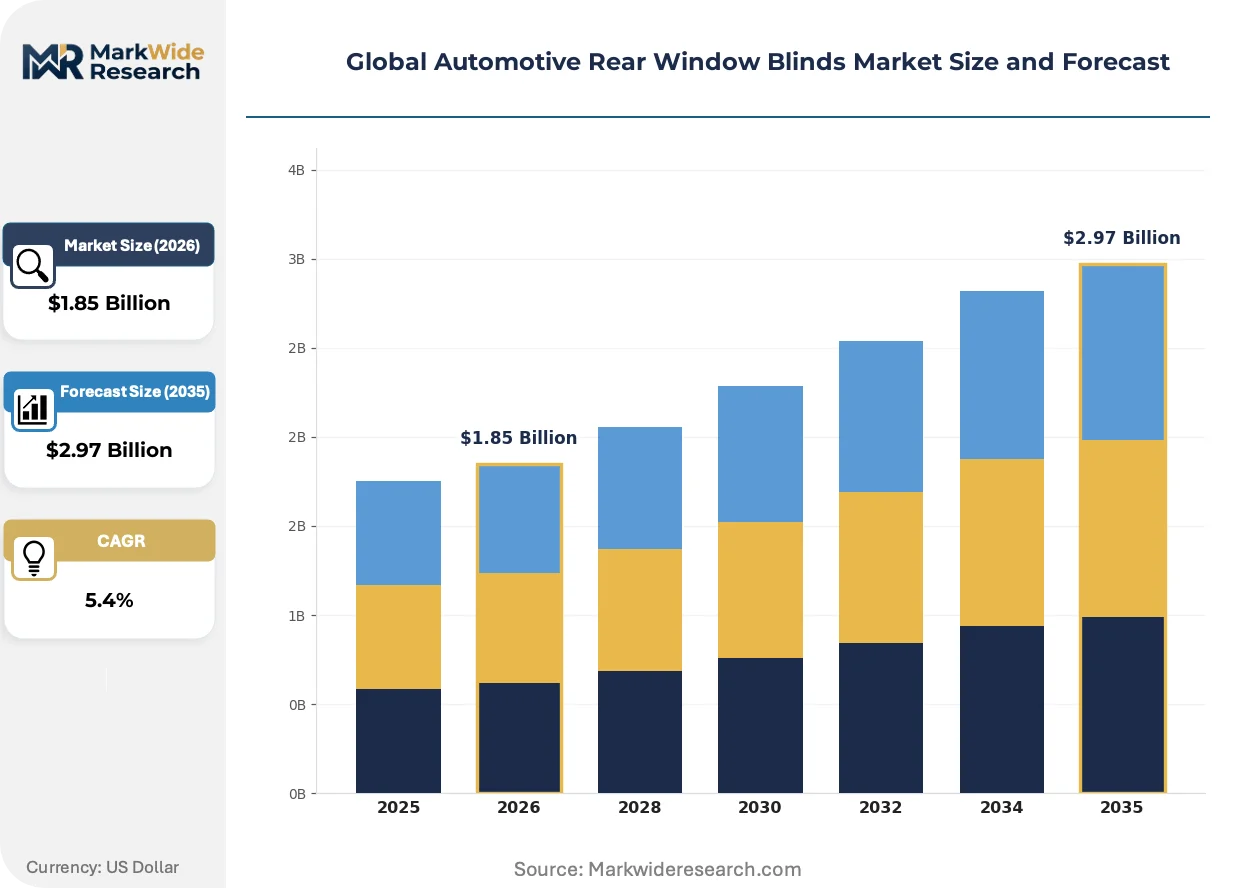
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Blinds, Motorized Blinds, Retractable Sunshades, Fixed Louvers Technology: Mesh Fabric, Polyester, Nylon, Acrylic Coated, PVC Laminated Vehicle Type: Passenger Cars, Light Commercial Vehicles, Heavy Duty Trucks, SUVs, Limousines Distribution Channel: OEMs, Aftermarket Retailers, Online Marketplaces, Authorized Dealers |
| Companies Covered | MACAUTO INDUSTRIAL CO., LTD, World Inc, Vaccess India Pvt Ltd, KK Motors Inc., Widney Manufacturing Ltd, Mavrick Blinds, CAR SHADES, BOS GmbH & Co. KG, Inalfa Roof Systems Group BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Rear Window Blinds Market Strategic Shifts & Innovations
Innovation in the automotive rear window blind market follows two parallel paths. One focuses on material science to improve the performance of manual products, while the other centers on mechatronic sophistication for electronically integrated systems.
Advanced fabrics incorporating PVC lamination or acrylic coatings provide superior UV blocking and thermal insulation. Luxury and electric vehicle OEMs are the primary adopters of these higher-performance materials to enhance cabin comfort and energy efficiency. This material technology is expanding into the premium aftermarket, challenging the dominance of basic polyester mesh in non-OEM channels.
Vehicle interior safety standards, including the US NHTSA's Federal Motor Vehicle Safety Standard 302 on material flammability, govern product design. This regulation compels suppliers to use certified fire-retardant polymers and textiles in their blind assemblies. The passenger car and SUV segments are most affected, forcing a standardization of material chemistry across global vehicle platforms.
A shift toward vehicle personalization at the point of purchase is altering distribution patterns. Buyers increasingly select accessories like rear window blinds from OEM online configurators or as dealer-installed options, disrupting the traditional, purely aftermarket retail model. This trend is most prominent in the European premium vehicle market, where bespoke configuration is a key element of the brand experience.
Global Automotive Rear Window Blinds Market Segmentation
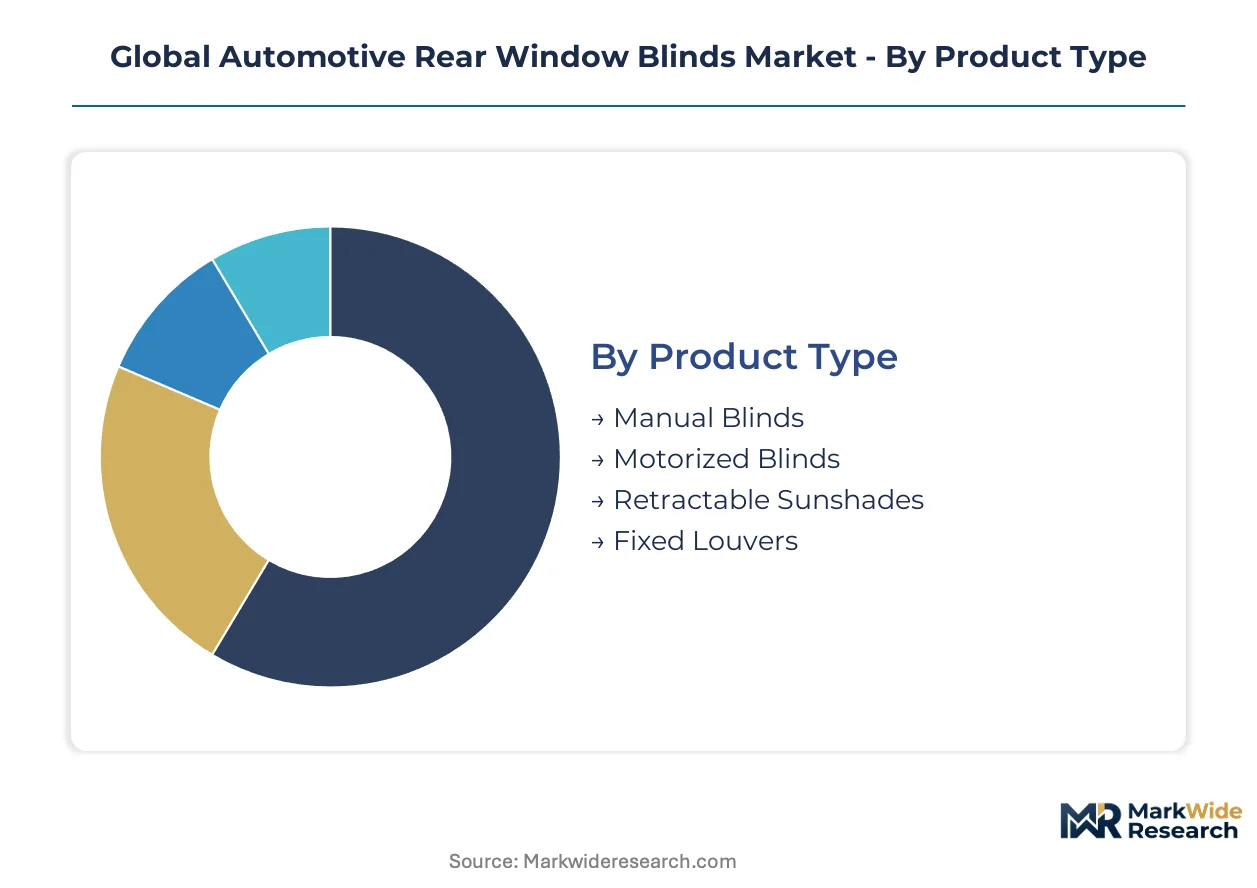
The automotive rear window blinds market segments reflect the diverse requirements of vehicle manufacturers and end-users, influencing product design, material selection, and distribution strategies. Understanding these distinctions is critical for suppliers to align their production capabilities with specific market demands, from high-volume aftermarket to premium OEM integrations.
Product Type:
The capital intensity of product development varies significantly across different rear window blind types, influencing investment in manufacturing processes and electronic integration.
- Motorized Blinds:These systems incorporate micro-motors, sensors, and control units for automated operation, requiring substantial investment in mechatronic engineering. Demand concentrates in premium SUVs and luxury passenger cars, driven by enhanced cabin comfort features.
- Manual Blinds:Operated by hand with basic mechanical components, these blinds represent a lower capital expenditure in design and manufacturing. Demand remains stable within the aftermarket segment, appealing to budget-conscious consumers seeking essential sun protection.
- Retractable Sunshades:Simple spring-loaded mechanisms allow for manual extension and retraction, offering a flexible and cost-effective solution. These are widely available through online marketplaces for universal fit applications.
- Fixed Louvers:These rigid, non-adjustable panels are primarily for aesthetic or specific utility vehicle applications. Fixed louvers offer a durable, permanent sun-blocking solution.
Most installed capacity flows through Manual Blinds. Expansion is steepest in Motorized Blinds.
Technology:
Material selection for rear window blinds is stratified by cost tier, with advanced coatings commanding higher prices due to superior performance characteristics.
- PVC Laminated:These multi-layer fabrics offer enhanced durability, superior UV blocking, and effective thermal insulation properties. Luxury vehicle manufacturers and premium aftermarket suppliers prioritize these materials for longevity and performance.
- Acrylic Coated:Featuring a fabric base with an acrylic layer, these materials provide improved thermal insulation and robust UV resistance. Electric vehicle OEMs adopt these for energy efficiency and cabin climate control.
- Polyester:A widely used synthetic fiber, polyester offers a balance of durability and cost-effectiveness for standard applications. It is common in both OEM and aftermarket manual blind solutions.
- Mesh Fabric:Lightweight and breathable, mesh fabric provides basic sun protection while maintaining visibility. It is a staple for universal-fit retractable sunshades.
- Nylon:Known for its strength and abrasion resistance, nylon is used in specific components requiring high mechanical resilience. Nylon finds application in the structural elements of some manual blinds.
Material innovation centers on improving UV protection and thermal insulation.
Vehicle Type:
Application volume and value define the market for rear window blinds, with premium segments driving higher-value integrations and standard vehicles supporting volume sales.
- SUVs:This high-volume segment frequently includes integrated rear window blinds as standard or optional equipment. Demand in the United States and Germany reflects strong consumer preference for feature-rich family vehicles.
- Limousines:A niche luxury segment where rear window blinds are a standard feature, essential for passenger privacy and comfort. Demand in chauffeur-driven markets emphasizes bespoke passenger experience.
- Passenger Cars:A broad category encompassing sedans and hatchbacks, where blinds are offered as options or aftermarket accessories. This segment drives significant volume for manual and retractable solutions.
- Light Commercial Vehicles:Utility-focused vehicles often utilize basic sunshade solutions for driver comfort or cargo protection. These vehicles prioritize functionality and durability in their blind installations.
- Heavy Duty Trucks:Blinds for heavy duty trucks focus on driver comfort during long-haul operations, often emphasizing robust construction. Custom-fit solutions are common for cabin privacy.
Consumer demand for comfort and privacy drives adoption across vehicle types.
Distribution Channel:
Customer type and procurement patterns dictate the specialized supply chains and sales strategies within the automotive rear window blinds market.
- OEMs:Original Equipment Manufacturers procure blinds directly from Tier 1 suppliers for factory installation into new vehicles. Demand in Germany and Japan focuses on seamless integration into vehicle architecture.
- Aftermarket Retailers:These channels sell blinds directly to end-consumers for post-purchase installation, often through brick-and-mortar stores. Aftermarket retailers cater to a broad base of vehicle owners seeking cost-effective solutions.
- Online Marketplaces:E-commerce platforms facilitate direct-to-consumer sales, primarily for universal-fit manual blinds and retractable sunshades. This channel offers convenience and competitive pricing to a global audience.
- Authorized Dealers:Vehicle dealerships offer OEM-approved accessories, including rear window blinds, as dealer-installed options. Authorized dealers provide installation services and maintain brand-specific product lines.
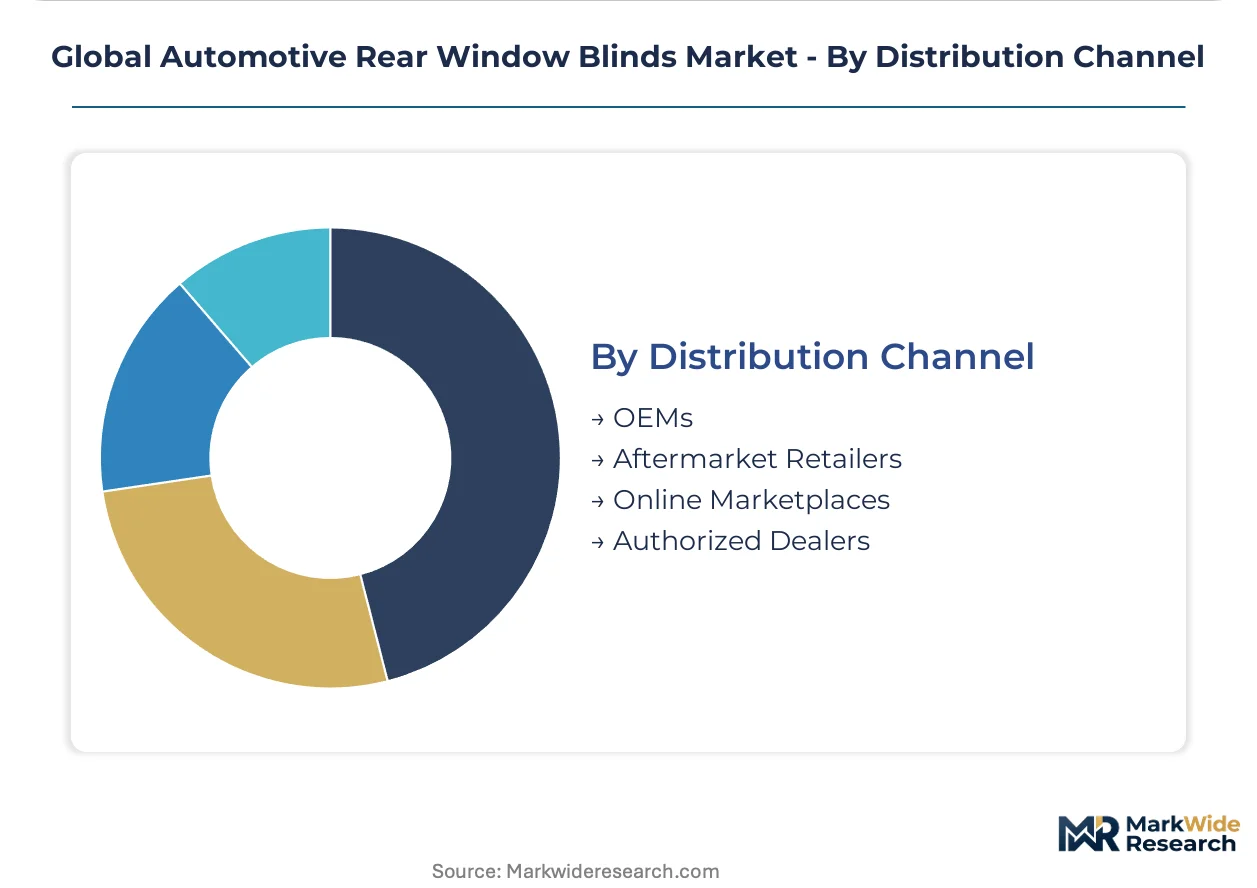
Channels bifurcate between high-volume, cost-sensitive aftermarket and integrated, premium OEM solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Germany exhibit strong demand for premium vehicle integrations, contrasting with China's expanding automotive production that drives both OEM and aftermarket solutions. Japan's focus on advanced manufacturing techniques influences component quality, while India's growing middle-class consumer base represents a significant opportunity for affordable manual blind solutions.
United States
Demand for premium SUVs and limousines drives the fitment of integrated rear window blinds. The US NHTSA's Federal Motor Vehicle Safety Standard 302 mandates material flammability standards for interior components. Automotive manufacturing in Michigan, particularly around Detroit, focuses on advanced mechatronic systems for luxury vehicles.
Germany
Consumer appetite for premium SUVs and luxury passenger cars fuels high adoption rates of motorized blinds. KBA regulations ensure electronic safety and electromagnetic compatibility for integrated systems. Bavaria's automotive cluster, home to major OEMs, prioritizes advanced material science and mechatronic integration.
Japan
OEMs in Japan increasingly integrate advanced rear window blinds into new passenger cars, focusing on cabin comfort. METI guidelines influence material innovation for improved UV protection and thermal insulation. The Nagoya region, a key automotive hub, sees significant investment in high-performance materials and automated production.
China
Expanding vehicle production and rising consumer income support both OEM and aftermarket blind installations. China's GB standards enforce strict material and component design regulations for vehicle interiors. Manufacturing centers in the Yangtze River Delta are scaling production for both motorized and manual solutions.
India
Growing middle-class consumer bases and increasing vehicle ownership drive demand for affordable manual and retractable blind solutions. BIS standards ensure product quality and safety for aftermarket accessories. Production facilities in Chennai and Pune are expanding to meet the regional need for cost-effective sun protection.
Global Automotive Rear Window Blinds Market Key Industry Players
Top-tier vendors anchor the premium OEM segment, while high-volume manufacturers and aftermarket specialists compete in the manual blind market. The industry comprises specialized mechatronic system providers, large-scale fabricators, and diverse aftermarket distributors, reflecting a tiered market structure. Strategic partnerships with automotive OEMs and continuous material science advancements are common competitive moves. Portfolio diversification into smart cabin solutions also drives competitive positioning among advanced suppliers.
On the premium-tier vector, BOS GmbH & Co. KG exemplifies expertise in complex mechatronic systems for luxury automotive brands. Inalfa Roof Systems Group BV further integrates these sophisticated components into larger interior comfort modules for vehicle manufacturers. MACAUTO INDUSTRIAL CO., LTD, representing a large-scale fabricator, leverages its manufacturing capabilities to supply a broad range of product types across various channels. These companies collectively illustrate the market's bifurcation between advanced OEM integration and high-volume production.
| Leading Market Players |
|---|
| MACAUTO INDUSTRIAL CO., LTD |
| World Inc |
| Vaccess India Pvt Ltd |
| KK Motors Inc. |
| Widney Manufacturing Ltd |
| Mavrick Blinds |
| CAR SHADES |
| BOS GmbH & Co. KG |
| Inalfa Roof Systems Group BV |
| Others |
Cost & Logistics Intelligence
Vertical integration into mechatronic component production anchors the supply position for premium automotive blind systems, enabling OEMs to control quality and secure pricing power. Outsourcing high-volume fabric production, conversely, introduces cost efficiencies but exposes suppliers to commodity price fluctuations.
Pricing Analysis
Capacity additions in China are reshaping price floors for manual and retractable sunshades, intensifying competition. The market operates on a per-unit transactional pricing model, with significant price differentiation driven by material quality grade and brand premium for OEM-integrated systems. Pricing softness runs through the aftermarket segment due to the widespread availability of low-cost alternatives. Premium vehicle OEMs exhibit low price sensitivity for advanced mechatronic blinds, while budget-conscious aftermarket consumers are highly price-sensitive.
Supply Chain Analysis
Global logistics costs for importing electronic components and specialized fabrics impact the final price of automotive rear window blinds. Supply concentration for advanced mechatronic systems centers in Germany and Japan, while high-volume fabric production originates primarily from China and India. Raw material dependencies include PVC laminated fabrics, acrylic coatings, and micro-motors. Single-source vulnerability for specialized control units represents a structural risk. Distribution runs through OEM direct channels for integrated systems and diversified aftermarket retailers, including online marketplaces, for manual solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play, leveraging lower manufacturing costs in Asia for high-volume manual blinds against premium pricing for advanced mechatronics in Europe and North America.
For Market Incumbents: Deepen integration with premium automotive OEMs by co-developing next-generation smart cabin features. Invest in advanced material science R&D to counter the substitution threat from low-cost aftermarket alternatives. Expand mechatronic engineering capabilities to secure long-term contracts for motorized blinds. Consolidate fabric suppliers to mitigate commodity price volatility and secure material quality.
For New Entrants and Emerging Players: China's GB standards for material flammability open a window for compliant, cost-effective fabric and manual blind manufacturers. Target the underpenetrated light commercial vehicle segment with durable, easy-to-install manual solutions. Focus on online marketplaces for direct-to-consumer sales, emphasizing universal fit and quick installation. Develop modular, affordable electronic sunshades for mid-range passenger cars in emerging markets like India.
For Investors and Strategic Acquirers: Roll-up economics work for specialized mechatronics providers because capability scarcity in complex system integration creates defensible niches. The long-term viability favors entities capable of delivering integrated comfort modules for electric and autonomous vehicles. Target acquisition profiles include mid-sized Tier 1 suppliers with proprietary micro-motor technology or advanced fabric coating expertise. A signal to watch is OEM investment in platform standardization for electronic interior components.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Mechatronic R&D | Secures future OEM contracts for smart, integrated cabin comfort systems in luxury vehicles. |
| Expand Fabric Coating Capacity | Enhances UV protection and thermal insulation, meeting demand from electric vehicle manufacturers. |
| Form OEM Joint Ventures | Ensures early design-in for new vehicle platforms, reducing market entry barriers for advanced systems. |
| Digitalize Aftermarket Sales | Broadens reach for manual blinds and retractable sunshades, capturing budget-conscious consumers globally. |
| Standardize Electronic Components | Reduces system complexity and cost for motorized blinds, enabling wider adoption across vehicle segments. |
Research Approach
Direct dialogue with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations provided granular insights into market dynamics. This primary research was validated against secondary sources including vehicle production databases, IHS Markit registration data, customs records, and company financial reports. The analysis employed both bottom-up and top-down triangulation to ensure data accuracy and comprehensive market understanding.
A bottom-up analytical framework was utilized to model market volume and value across the projection horizon. Segmentation dimensions modeled included product type, technology, vehicle type, distribution channel, and regional production clusters. Compound annual growth rates were derived through a regression analysis of historical data and forward-looking market drivers. Key forecast inputs included new vehicle production forecasts and material science innovation roadmaps.
Revisions become necessary when macroeconomic shifts, new regulatory mandates, or significant technological breakthroughs materialize. Forecasts reflect assumptions documented through extensive research and expert consultation. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market
Automotive Interior & Exterior
Global Automotive Anti Vibration Mounting Market
Automotive Interior & Exterior
Automotive Floor Carpet Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Automotive Display Market
Automotive Interior & Exterior
Global Automotive Luggage Trim Market
Automotive Interior & Exterior
Commercial Vehicle Seats Market
Automotive Interior & Exterior
Reflective Air Bags Market
Automotive Interior & Exterior
Truck Parking Air Conditioner Market
Automotive Interior & Exterior
Asia-Pacific Automotive Seat Market
Automotive Interior & Exterior
Automotive Airbag Fabric Market
Automotive Interior & Exterior
Automotive Seats Market
Automotive Interior & Exterior
Automotive Windshield Market
Automotive Interior & Exterior
Europe Automotive Interior Materials Market