
 Fog Free Mirrors Market | 2026-2036
Fog Free Mirrors Market Size, Share, and Industry Trends Forecast 2026-2036
Fog Free Mirrors Market Foresight
Thin-film indium tin oxide is pivoting toward copper nanowire alternatives in heated mirror substrates, cutting material costs by half while preserving optical clarity. Electric Mirror leverages captive supply of LED-backlit assemblies to dominate North American hospitality channels. Kohler Co. anchors its position through in-house production of hydrophilic coating chemistries. Zadro competes on price at the residential tier through simplified resistive heating designs.
Fog free mirrors integrate active heating elements or passive hydrophilic coatings to prevent condensation-induced light scattering, maintaining reflectance above 90% at surface temperatures of 30–45°C in heated configurations. Their primary commercial purpose spans automotive safety systems, residential wellness installations, and aviation cockpit visibility. Heated mirrors occupy the largest revenue pool given embedded electronics and wiring complexity, while hydrophobic mirrors represent the fastest-expanding category due to zero-energy operation and compatibility with existing glass lines. Electrochromic mirrors command premium positioning in automotive mirror systems where dimming and defogging functions merge.
The US Consumer Product Safety Commission governs electrical safety in heated mirror installations, while the EU Ecodesign Directive mandates standby power limits for active defogging systems. REACH compliance constrains coating formulations containing perfluorinated compounds, pushing suppliers toward silicone-based hydrophilic alternatives. Stakeholders must monitor evolving energy-efficiency thresholds in building codes and automotive type-approval processes, as these will determine which technology platforms retain market access across major economies.
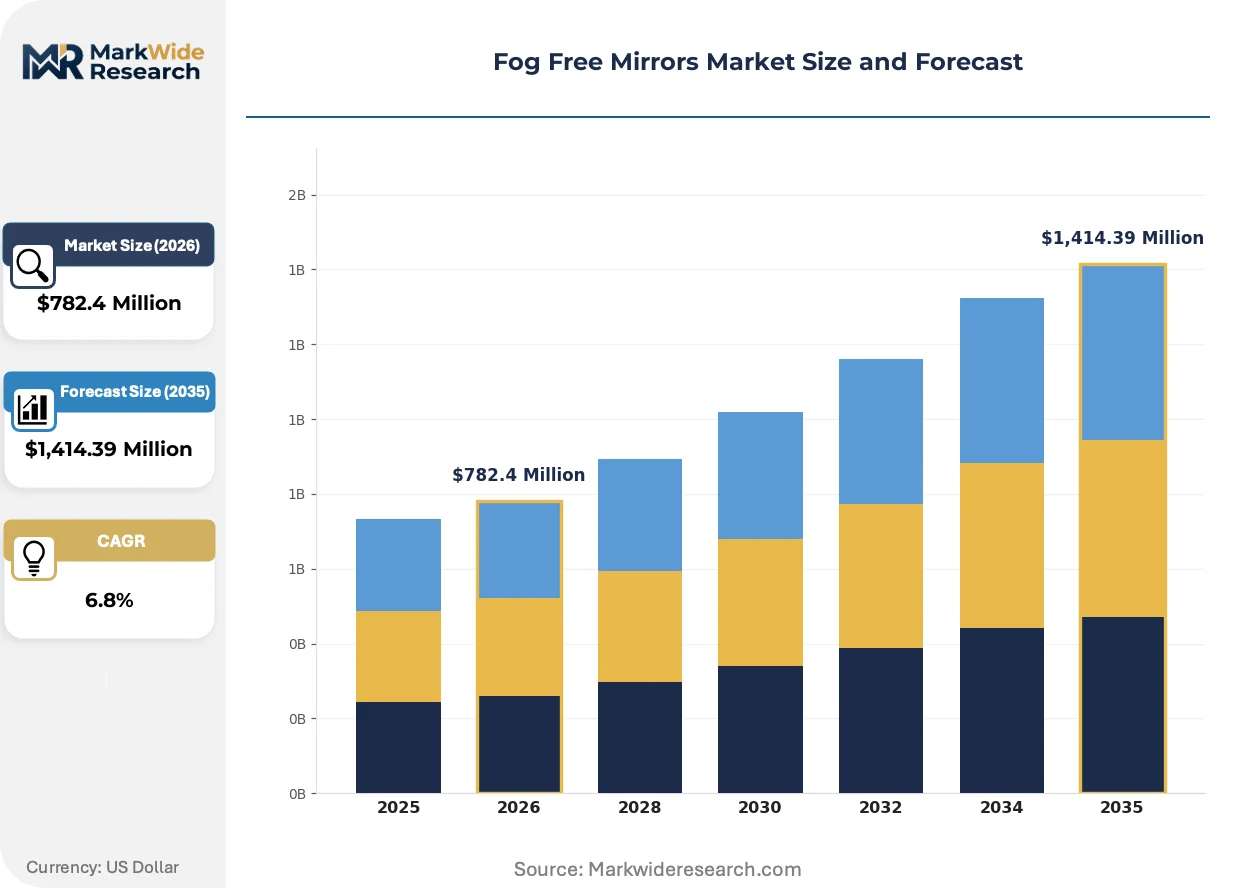
Market Dynamics
The EU Ecodesign Directive's standby power limits for active defogging systems are forcing heated mirror manufacturers toward resistive heating redesigns, compressing margins while opening pathways for zero-energy hydrophilic alternatives.
Growth Catalysts
- Hospitality renovation cycles:North American hotel chains are standardizing fog free mirrors across property refreshes, embedding the technology in procurement specifications for new construction and retrofit programs.
- REACH compliance migration:The European Chemicals Agency's restrictions on perfluorinated compounds are accelerating silicone-based hydrophilic coating adoption, validating lower-toxicity formulation platforms.
- Automotive electrochromic convergence:Dimming and defogging function integration in rearview mirror assemblies is expanding addressable glass area per vehicle platform.
Market Restraints
- Indium supply concentration:Thin-film indium tin oxide substrates depend on concentrated rare earth processing capacity, exposing cost structures to geopolitical supply disruptions.
- Installation labor intensity:Heated mirror retrofitting requires certified electrical work, limiting residential penetration where contractor availability constrains project timelines.
- Passive coating durability gaps:Hydrophilic surface treatments degrade faster than active heating elements in high-humidity environments, creating replacement cycle uncertainty.
Strategic Opportunities
- Aviation cockpit visibility:Commercial aircraft manufacturers are evaluating heated mirror integration for pilot side-window defogging, representing an untested application vertical.
- German bathroom renovation density:Renovation rates exceeding broader European averages create concentrated demand for premium hydrophilic mirror installations.
- LED-backlit assembly convergence:Mirror-integrated lighting systems are enabling bundled specification wins in hospitality and residential new-build channels.
Industry Challenges
- Electrical certification timelines:US Consumer Product Safety Commission approval processes for new heated mirror designs extend product launch windows by multiple quarters.
- Coating-application equipment capex:Hydrophilic layer deposition requires vacuum or spray-line investments that fragment manufacturing scale economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fog Free Mirrors Market |
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,414.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heated Mirrors, Hydrophobic Mirrors, Electrochromic Mirrors, Anti-Fog Coated Mirrors, Plastic Mirrors Technology: Resistive Heating, Capacitive Heating, Hydrophilic Coating, Optical Coating, Thermal Conductive Films Application: Automotive Mirror Systems, Residential Bathroom Mirrors, Commercial Lavatory Mirrors, Marine Vessel Mirrors, Aviation Cockpit Mirrors End User: OEM Manufacturers, Aftermarket Suppliers, Commercial Property Owners, Residential Consumers, Aerospace Companies |
| Companies Covered | Electric Mirror, Zadro, The Shave Well Company, ToiletTree Products, Kohler Co., Conair Corporation, Foshan Sino Hardware Products Co. Ltd., WeProFab, New Home Bath & Mirror Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fog Free Mirrors Market Shifts & Advancements
Material substitution and regulatory energy thresholds are compressing technology lifecycles, rewarding suppliers who can bridge active heating performance with passive coating simplicity.
Copper nanowire transparent conductors are integrating into heated mirror substrates as direct replacements for indium tin oxide, cutting material input costs while preserving optical clarity above 90% reflectance. Automotive and hospitality specification teams are validating these substrates in pilot programs. The shift is integrating new supply chain partnerships between glass fabricators and nanomaterial specialists, restructuring traditional coating chemistry relationships.
The EU Ecodesign Directive's standby power regulations are mandating sub-watt consumption thresholds for active defogging systems during idle states. Manufacturers are redesigning control electronics and heating element geometries to comply. Heated mirror product lines destined for European building codes face the steepest redesign requirements, with some suppliers accelerating hydrophilic coating development to bypass electrical compliance entirely.
Specification authority is migrating from general contractors to interior design firms in premium residential and hospitality segments, compressing traditional distribution through building material wholesalers. Design firms are developing preferred vendor lists that privilege aesthetic customization and lead-time reliability over unit cost. This pattern is most pronounced in German-speaking markets and coastal US metropolitan areas where renovation project values support design-fee structures.
Fog Free Mirrors Market Segmentation
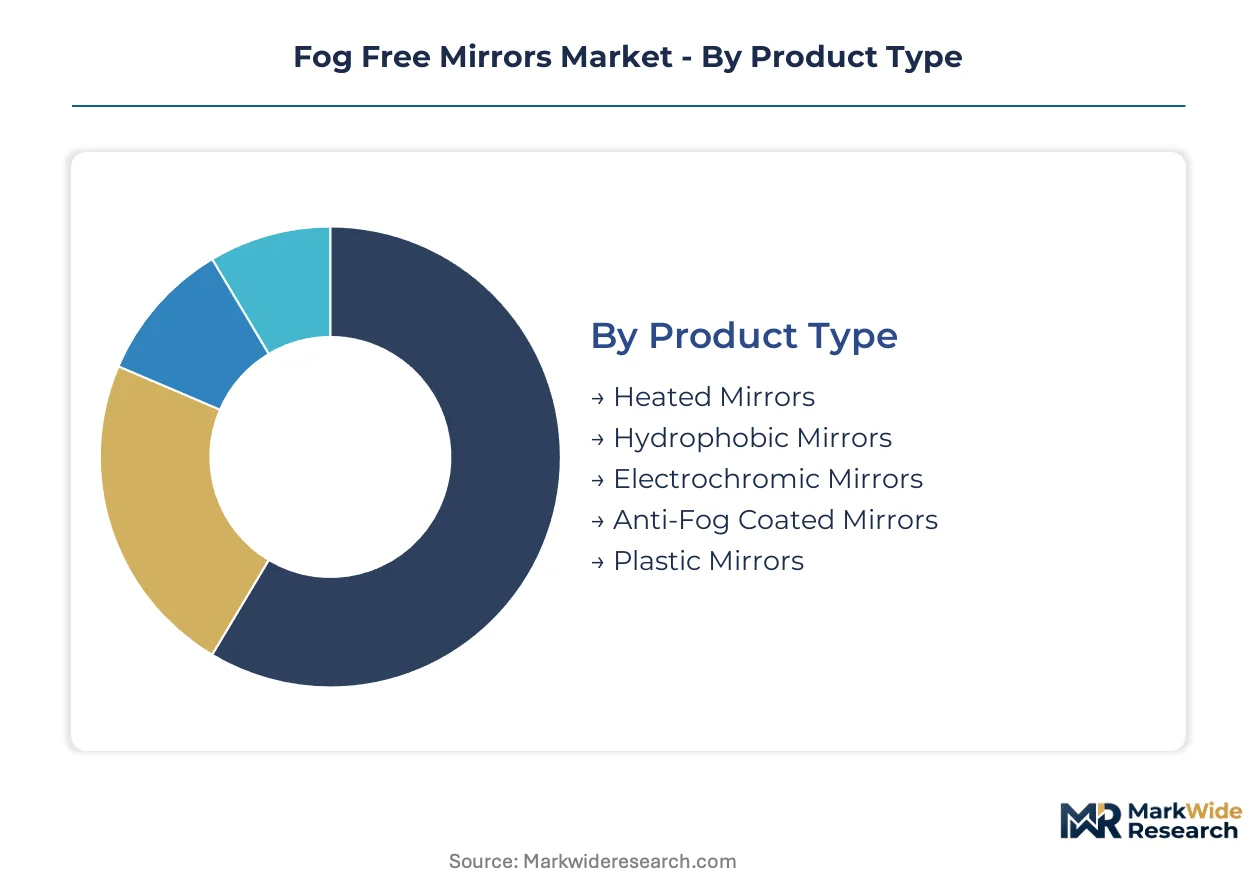
Technology platforms in fog free mirrors carry divergent regulatory burdens that reshape procurement economics. Certification requirements for electrical safety, energy efficiency, and chemical compliance fragment addressable markets by segment.
Product Type:
Heated mirrors require NHTSA automotive approval or CPSC electrical certification depending on end-use, while hydrophilic alternatives navigate REACH coating restrictions without electrical compliance overhead.
- Heated Mirrors:Embedded resistive or capacitive elements maintain surface temperatures between 30–45°C through integrated wiring and control electronics. Hospitality chains in the United States specify these for commercial lavatory retrofits where active performance overrides energy considerations. CPSC electrical safety mandates extend product launch timelines by multiple quarters.
- Hydrophobic Mirrors:Passive coatings exploit surface tension modification to repel water droplets without energy input. German bathroom renovation markets favor these for zero-operating-cost compliance with EU Ecodesign Directive standby power limits. REACH restrictions on perfluorinated compounds accelerate silicone-based formulation adoption.
- Electrochromic Mirrors:Dimming and defogging functions merge in automotive rearview assemblies commanding premium positioning.
- Anti-Fog Coated Mirrors:Hydrophilic treatments absorb moisture into uniform transparent films rather than scattering light through droplets.
- Plastic Mirrors:Polymer substrates reduce weight and breakage risk in marine and aviation applications where glass fragility constrains specification.
Leading the category by volume: Heated Mirrors. Growing fastest: Hydrophobic Mirrors.
Technology:
Cost tiers separate established resistive heating from emerging nanomaterial conductors, with coating technologies occupying the lowest capital intensity band.
- Resistive Heating:Metallic wire or thin-film elements embedded behind glass substrates deliver predictable thermal output across voltage ranges. North American hospitality procurement specifications standardize on resistive platforms for installation familiarity and contractor availability. Indium tin oxide supply concentration exposes cost structures to rare earth processing bottlenecks.
- Capacitive Heating:Electric field-driven warming enables more uniform heat distribution with faster response times than resistive alternatives. Automotive OEM qualification programs in Germany validate capacitive systems for electrochromic mirror integration where rapid defogging merges with dimming functionality. Control electronics complexity elevates unit costs above resistive baselines.
- Hydrophilic Coating:Silicone or metal oxide surface treatments attract water into transparent sheets rather than beads.
- Optical Coating:Multi-layer interference films manipulate reflectance and transmission properties alongside fog prevention.
- Thermal Conductive Films:Graphene or carbon nanotube dispersions promise heating uniformity without indium dependency.
Volume concentrates in Resistive Heating. Capacitive Heating claims the steepest expansion trajectory as automotive electrochromic convergence accelerates.
Application:
Customer types fragment across specification authority patterns, with design firms displacing general contractors in premium residential and hospitality channels.
- Automotive Mirror Systems:Rearview and side-view assemblies integrate defogging with dimming, blind-spot monitoring, and camera housing functions. OEM manufacturers in Germany and the United States drive specification volumes through platform-level integration decisions. NHTSA visibility standards mandate minimum defogging performance in type-approval processes.
- Residential Bathroom Mirrors:New construction and renovation demand splits between active heating for cold climates and passive coatings for energy-conscious markets. Coastal United States metropolitan areas exhibit design-firm-driven procurement privileging aesthetic customization over unit cost. Installation labor intensity constrains retrofit penetration where certified electrical work limits contractor availability.
- Commercial Lavatory Mirrors:Hospitality chains standardize fog free specifications across property refresh cycles.
- Marine Vessel Mirrors:Salt corrosion and humidity extremes demand specialized coating durability or sealed heating assemblies.
- Aviation Cockpit Mirrors:Pilot side-window defogging applications remain untested at commercial scale.
Automotive Mirror Systems generates the largest revenue pool. Aviation Cockpit Mirrors represents the most speculative expansion pathway.
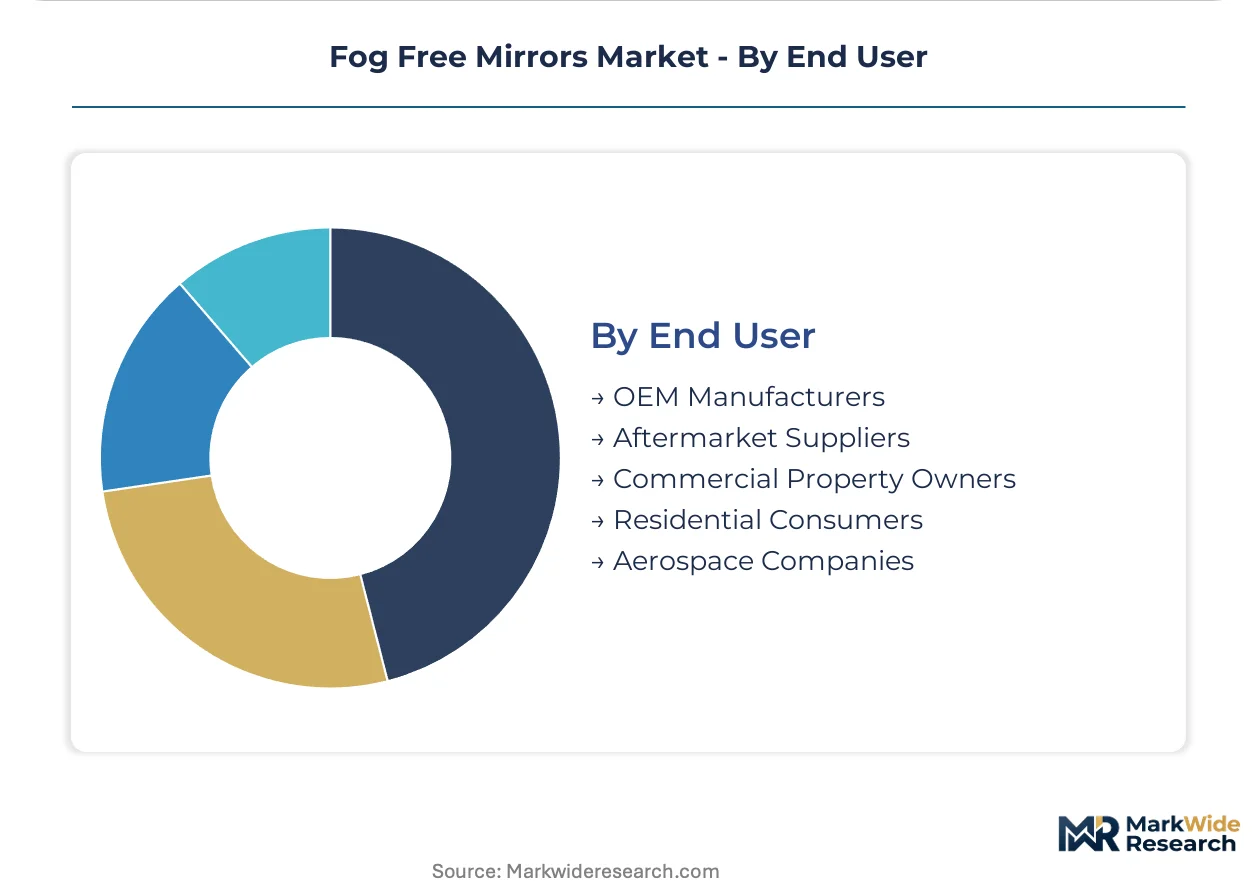
End User:
Supply chain configuration separates captive OEM production from distributed aftermarket channels, with aerospace qualification timelines extending furthest.
- OEM Manufacturers:Automotive and aviation platform integrators specify fog free mirror subsystems through multi-year design cycles. German automotive OEMs anchor European demand through electrochromic rearview mirror programs. In-house coating chemistry production at major suppliers compresses external procurement volumes.
- Aftermarket Suppliers:Retrofit-focused distributors serve residential and commercial replacement demand through wholesale building material channels. United States residential markets exhibit price sensitivity favoring simplified resistive designs over feature-rich alternatives. Electrical certification requirements fragment supplier bases by jurisdiction.
- Commercial Property Owners:Hospitality and office building operators specify through design firms rather than direct procurement.
- Residential Consumers:End-user purchasing concentrates in big-box retail and e-commerce channels.
- Aerospace Companies:Commercial aircraft manufacturers evaluate heated mirror integration for cockpit visibility applications.
OEM Manufacturers dominate procurement value. Aftermarket Suppliers distribute the widest unit volumes across fragmented residential demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hotel chains in the United States and bathroom renovators in Germany concentrate the majority of procurement volume for fog free mirror installations, with regulatory energy thresholds in the European Union redirecting specification patterns toward passive coating technologies.
United States
Hospitality property refresh cycles and residential new-build specifications drive demand across coastal metropolitan areas. The US Consumer Product Safety Commission governs electrical safety certification for heated mirror designs, extending product launch timelines. Electric Mirror leverages captive LED-backlit assembly supply from its Washington state operations to dominate North American hospitality channels.
Germany
Bathroom renovation rates exceeding broader European averages create concentrated demand for premium hydrophilic mirror installations. The EU Ecodesign Directive mandates standby power limits for active defogging systems, compressing margins for heated mirror suppliers. Automotive OEMs in Stuttgart and Munich anchor electrochromic rearview mirror programs through multi-year platform integration decisions.
China
Glass fabricators in the Yangtze River Delta region are integrating copper nanowire transparent conductors into heated mirror substrates as direct replacements for indium tin oxide. The country's dual carbon goals pressure manufacturers toward lower-energy resistive heating technologies. Foshan-based hardware specialists supply simplified resistive heating designs to price-sensitive residential export markets.
Japan
Automotive mirror system integration programs in the Chubu region validate capacitive heating platforms for electrochromic convergence. METI energy-efficiency guidelines shape building code thresholds for residential bathroom installations. Nagoya-area OEM manufacturers specify fog free mirror subsystems through captive coating chemistry partnerships.
United Kingdom
Interior design firms in London and the Southeast are displacing general contractors as specification authorities for premium residential renovations. REACH compliance constraints on perfluorinated compounds push suppliers toward silicone-based hydrophilic coating alternatives. Manchester and Birmingham distribution channels serve aftermarket retrofit demand where electrical certification requirements fragment supplier bases.
Fog Free Mirrors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospitality procurement favoring established brand recognition while residential channels tolerate unbranded imports. The vendor base organizes around three strategic archetypes: integrated lighting-and-mirror specialists, captive coating chemistry producers, and price-focused simplified heating designers. Capacity expansion and strategic partnerships dominate competitive moves as suppliers navigate material substitution and regulatory compliance redesigns.
Among North American branded specialists, Electric Mirror and Kohler Co. exemplify divergent integration strategies, with the former anchoring hospitality channel dominance through captive LED-backlit assembly supply and the latter securing coating chemistry control through in-house production. Zadro occupies a position within the price-competitive residential tier, representing the simplified resistive heating archetype that competes on unit cost rather than feature complexity. Foshan Sino Hardware Products Co. Ltd. sits among Chinese contract fabricators supplying export markets with standardized heating element configurations.
| Leading Market Players |
|---|
| Electric Mirror |
| Zadro |
| The Shave Well Company |
| ToiletTree Products |
| Kohler Co. |
| Conair Corporation |
| Foshan Sino Hardware Products Co. Ltd. |
| WeProFab |
| New Home Bath & Mirror Inc. |
| Others |
Supply & Pricing Matrix
Indium spot prices cascading through thin-film substrate costs compress margins for heated mirror manufacturers while opening arbitrage for copper nanowire alternatives and zero-energy hydrophilic coatings across pricing tiers.
Pricing Analysis
Volume concentrates in simplified resistive heating designs where Foshan-based fabricators compete on unit cost, while margins expand in capacitive heating and electrochromic platforms serving German automotive OEMs. Price differentiation hinges on CPSC electrical certification overhead and EU Ecodesign Directive standby power compliance grade. Cost compression in resistive tiers is intensifying because indium supply concentration exposes input volatility. Residential aftermarket channels exhibit the sharpest price sensitivity, whereas hospitality procurement privileges lead-time reliability and aesthetic customization over unit economics.
Supply Chain Analysis
Domestic-content mandates in Chinese dual carbon policy frameworks are reshaping sourcing patterns for glass fabricators in the Yangtze River Delta. Manufacturing gravity centers on China, Germany, and the United States, with coating chemistry production anchored in captive facilities at Kohler and Electric Mirror. Raw material flows draw from rare earth processing nodes for indium, copper nanowire specialists for transparent conductors, and silicone precursor suppliers for hydrophilic formulations. Single-source vulnerability in indium concentrate exposes cost structures to geopolitical disruption. Distribution runs through building material wholesalers for residential retrofit, design firm direct specification for premium hospitality, and OEM platform integration for automotive.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fog free mirrors market sits in a technology-transition phase as copper nanowire transparent conductors displace indium tin oxide substrates, compressing legacy cost structures while validating new supply chain partnerships.
For Market Incumbents: Cement hospitality channel dominance through captive LED-backlit assembly supply and in-house hydrophilic coating chemistry production. Defend against copper nanowire entrants by accelerating CPSC pre-certification for redesigned resistive platforms. Prioritize backward integration into silicone-based coating formulations to bypass REACH perfluorinated compound restrictions.
For New Entrants and Emerging Players: Interior design firms in coastal US metropolitan areas and German-speaking markets represent the most penetrable specification authority channel. Target aviation cockpit visibility applications as an untested vertical with extended qualification timelines favoring patient capital. Pursue bundled mirror-integrated lighting system wins to bypass established electrical certification barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap coating chemistry specialists in Germany facing EU Ecodesign margin compression. Long-term viability rests on technology platforms bridging active heating performance with passive simplicity. Watch copper nanowire substrate validation in automotive pilot programs as the inflection signal for material substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Copper Nanowire Substrate Integration | Validates lower-cost transparent conductors in automotive and hospitality pilot programs. |
| Silicone-Based Coating Chemistry Scale-Up | Secures REACH-compliant formulation capacity ahead of perfluorinated compound phase-outs. |
| CPSC Pre-Certification Investment | Compresses product launch timelines for heated mirror redesigns targeting US hospitality. |
| LED-Backlit Assembly Convergence | Enables bundled specification wins in design-firm-driven premium residential channels. |
| Aviation Qualification Partnership | Positions heated mirror technology for commercial aircraft cockpit visibility applications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospitality procurement directors, automotive Tier 1 supplier engineers, glass fabricator operations managers, and coating chemistry R&D leads. Bottom-up demand modeling triangulated against top-down macroeconomic indicators validated volume and value outputs. Secondary sources included CPSC electrical safety filings, EU Ecodesign Directive compliance databases, REACH substance restriction updates, and NHTSA automotive type-approval records.
Data-stream reconciliation across production volume estimates, import-export flows, and end-use installation rates informed the analytical framework across the analysis window. Segmentation dimensions spanned technology platform, application vertical, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to baseline penetration rates and replacement cycle assumptions. Industry-specific forecast inputs incorporated bathroom renovation intensity indices and automotive platform-level mirror content specifications.
Caveats apply where indium supply disruptions, EU standby power threshold revisions, or aviation qualification timeline extensions could materially shift the outlook. Forecasts reflect documented assumptions regarding material substitution velocity and regulatory enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Heated Steering Wheel Market
Automotive Interior & Exterior
Automotive Soft Trim Interior Materials Market
Automotive Interior & Exterior
Commercial Vehicle Seats Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market
Automotive Interior & Exterior
Zero Gravity Seat Market
Automotive Interior & Exterior
Europe Automotive Seat Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
Global Automotive Power Sliding Door Market
Automotive Interior & Exterior
Automotive Door Handle Sensors Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Automotive Heat Shield Market
Automotive Interior & Exterior
Automotive Body-In-White Market
Automotive Interior & Exterior
Automotive Flooring Market
Automotive Interior & Exterior
Automotive Fuel Tank Covers Market
Automotive Interior & Exterior
Automotive Convertible Top Market