
 Airport Information Display System Market | 2026-2036
Airport Information Display System Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Information Display System Market Outlook
Buyer concentration among top-tier international airports is realigning procurement patterns toward integrated display ecosystems. SITA leverages its baggage handling heritage to bundle display solutions with operational software. Honeywell International Inc. anchors its position through building automation synergies that extend into terminal visual systems. Thales Group competes on air traffic management integration, allowing its display products to feed directly from flight data processors.
An airport information display system comprises networked visual output devices—typically LED matrices, LCD panels, and projection systems—engineered for high ambient-light readability, IP-rated enclosure durability, and real-time data synchronization with airport operational databases. These systems serve the commercial purpose of reducing passenger anxiety, minimizing missed connections, and enabling dynamic gate reassignments through centralized content management. LED Displays command the largest installed base due to superior luminance efficiency and lifecycle economics in 24/7 operational environments. Cloud-Based Solutions represent the fastest-expanding technology segment as airports migrate from on-premise servers to SaaS architectures that reduce IT overhead. Fixed installations still dominate by value, though modular configurations are gaining traction in retrofit scenarios where phased capital deployment matters.
The FAA mandates specific visibility and reliability standards for safety-critical airport systems, while the EU Green Deal's energy performance requirements are accelerating LED retrofits across European hubs. EASA's continuing airworthiness frameworks indirectly shape display system redundancy specifications for integrated terminal operations. Stakeholders must weigh cloud dependency risks against operational resilience requirements as cyber regulations tighten across aviation infrastructure.
Market Dynamics
The FAA's updated visibility mandates for safety-critical terminal systems are compressing procurement cycles while simultaneously elevating LED retrofit urgency across aging hub infrastructure. This regulatory pressure intersects with airline operational demands for real-time gate flexibility, creating a structural pull toward integrated display ecosystems.
Growth Catalysts
- EU Green Deal energy performance mandates:European hub operators face binding efficiency thresholds that accelerate LED matrix replacements of legacy fluorescent backlit systems. Germany's Frankfurt Airport and France's Charles de Gaulle have initiated terminal-wide conversions.
- Baggage handling integration requirements:Airlines demand synchronized passenger-facing displays with automated baggage sortation systems to reduce misconnection anxiety and rebooking costs.
- Cloud migration economics:Mid-tier airports in India and Southeast Asia bypass on-premise server investments entirely, adopting SaaS content management architectures from greenfield deployment.
Market Restraints
- Semiconductor supply concentration:LED driver IC fabrication concentrates in Taiwan and South Korea, exposing display manufacturers to foundry allocation volatility and extended lead times.
- FAA certification timeline friction:Safety-critical display deployments require extensive electromagnetic interference testing and operational approval cycles that extend project delivery by 8-14 months.
- Projection system substitution:Large-format laser projection retains cost advantages in temporary gate configurations and remote apron operations, limiting LED penetration in niche applications.
Strategic Opportunities
- India airport privatization wave:The Airports Authority of India's brownfield modernization program at Chennai, Kolkata, and Ahmedabad creates concentrated demand for modular display architectures with phased capital deployment.
- Predictive maintenance convergence:Integration of IoT sensor networks with display hardware enables condition-based servicing contracts that shift revenue from equipment sales to recurring service streams.
- Biometric boarding alignment:Facial recognition gate systems require synchronized passenger information displays, creating specification bundling opportunities for integrated terminal ecosystem vendors.
Industry Challenges
- Cyber-physical security certification complexity:TSA and EASA diverging cybersecurity frameworks for aviation infrastructure create compliance fragmentation for multinational airport operators managing display networks across jurisdictions.
- Legacy serial protocol integration:Decades-old RS-485 and proprietary FIDS data feeds persist in established hubs, forcing middleware development costs for cloud-native display management platforms.
- Specialized field technician scarcity:IP-rated enclosure servicing and high-brightness calibration require certified personnel pools that lag deployment scale in rapid-growth markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Information Display System Market |
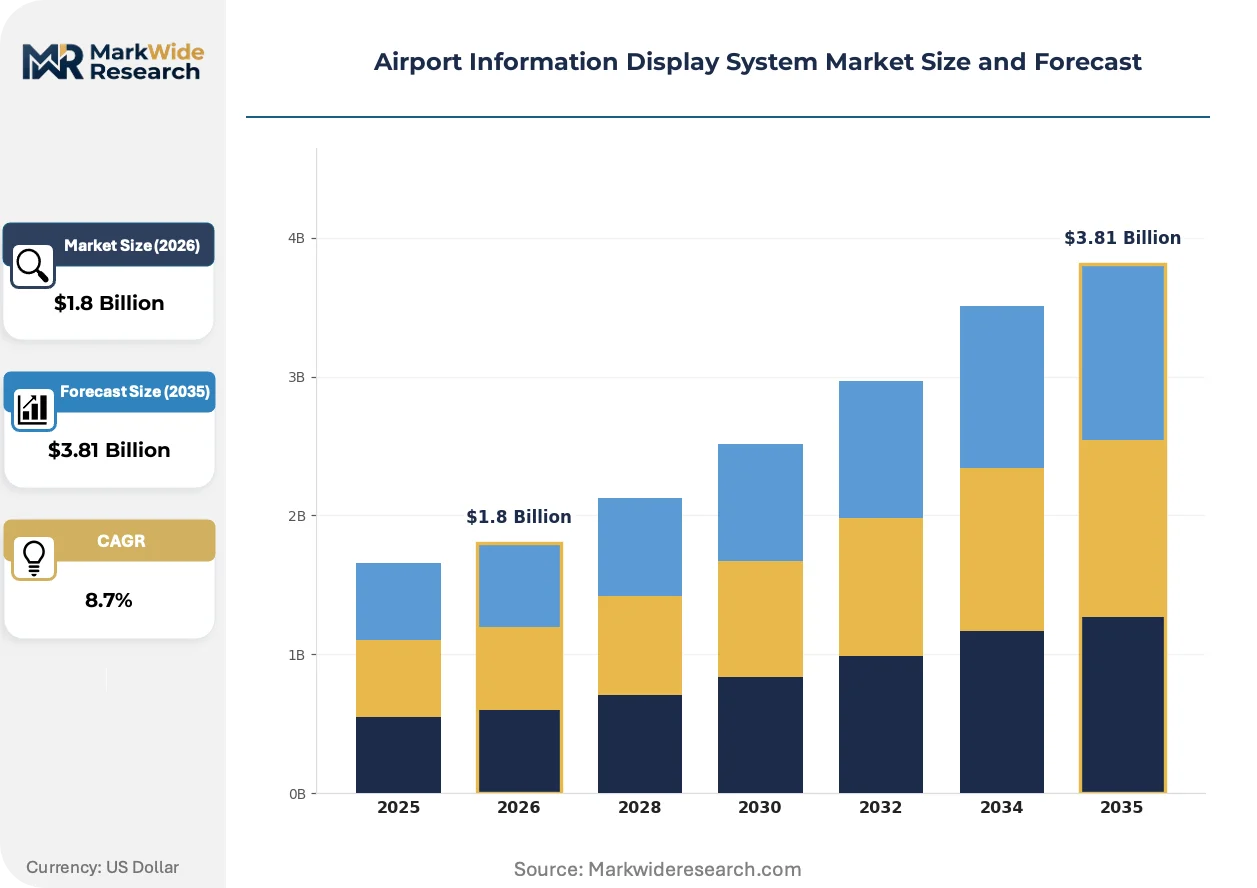
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Signage, LED Displays, LCD Monitors, Kiosks Technology: IoT, Cloud-Based Solutions, Automation, Wireless Communication End User: Airlines, Airports, Ground Handlers, Security Services Installation Type: Fixed, Portable, Integrated, Modular |
| Companies Covered | SITA, Amadeus IT Group SA, Honeywell International Inc., Thales Group, Indra Sistemas, Siemens AG, ADB SAFEGATE, Collins Aerospace, RESA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Information Display System Market Strategic Shifts
Display hardware architectures are converging with building automation and passenger processing systems, eliminating standalone procurement categories. This integration pressure is reshaping vendor competitive boundaries and technical specification development.
MicroLED pixel technology is consolidating high-ambient-light performance leadership in flagship terminal deployments. Dubai International and Singapore Changi have specified microLED flight information walls for primary concourse visibility zones. The technology is consolidating premium-tier procurement away from traditional SMD LED configurations by delivering superior luminance uniformity at reduced power density.
The EU Green Deal's extended producer responsibility amendments now cover commercial display equipment lifecycle impacts. Manufacturers must document carbon footprint across raw material extraction through end-of-life recycling for CE marking renewal. European hub operators are responding by inserting circular economy clauses into multi-year display fleet maintenance contracts.
Airline consortium procurement of terminal infrastructure is displacing individual airport authority purchasing for co-located carrier facilities. Star Alliance and oneworld member airlines at London Heathrow and Tokyo Narita now coordinate display specification standardization through joint technical committees. This concentration is most visible in North American and European hub markets where alliance ground operations dominate terminal tenancy patterns.
Airport Information Display System Market Segmentation
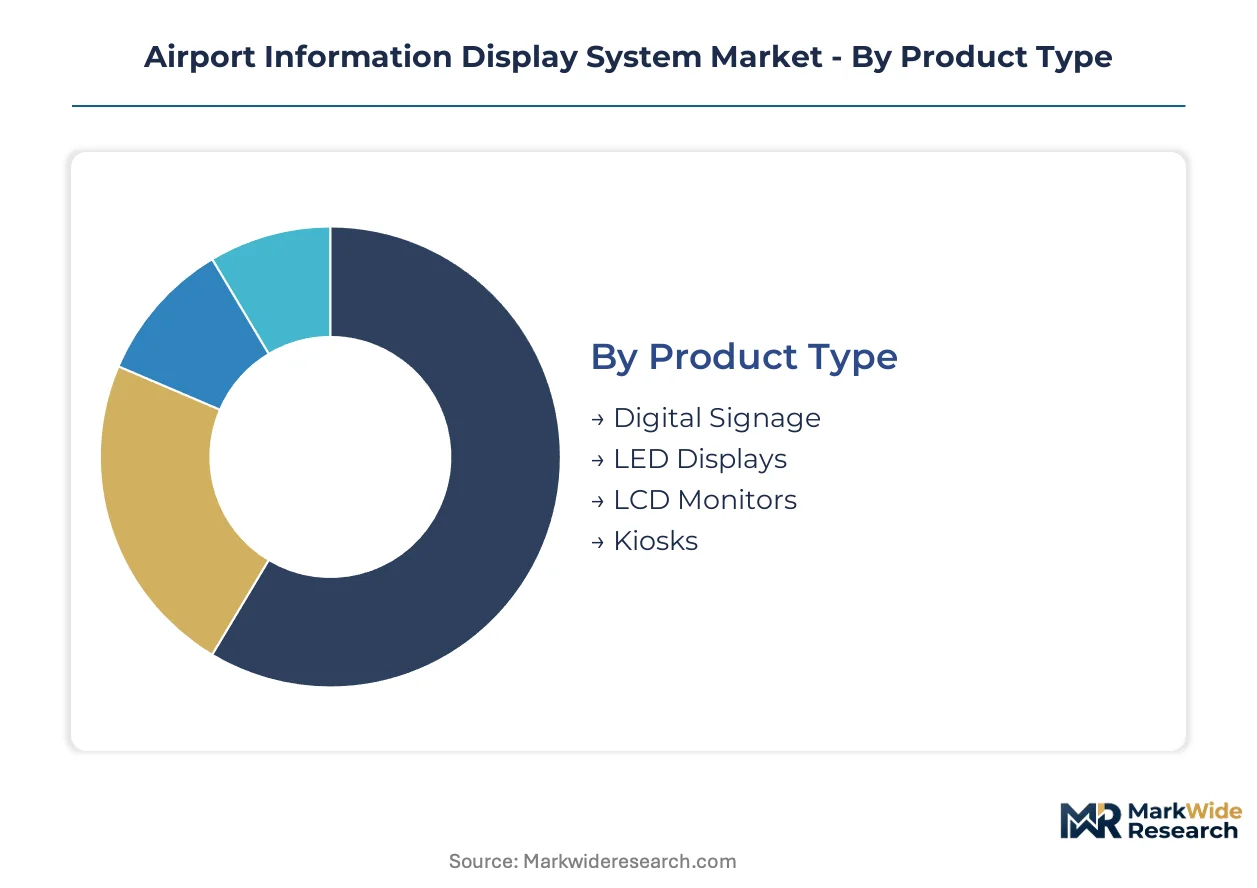
Airport information display procurement diverges sharply by operational scale and integration depth. Hub operators prioritize ecosystem-wide deployments, while regional facilities favor modular architectures that defer capital commitment.
Product Type:
Buyers in this category separate by ambient-light tolerance requirements and lifecycle cost sensitivity rather than initial capital outlay alone.
- LED Displays:High-brightness matrices engineered for 24/7 operation in direct solar exposure dominate flagship terminal deployments. Frankfurt Airport and Singapore Changi specify these for primary concourse zones where luminance uniformity reduces passenger eye strain during extended dwell times.
- Digital Signage:Networked content management platforms enabling real-time flight data syndication across distributed screen arrays. Demand concentrates among alliance carrier co-locations at London Heathrow and Tokyo Narita, where standardized passenger communication reduces rebooking friction during irregular operations.
- LCD Monitors:Backlit panels with limited outdoor readability serve gate holdrooms and baggage claim interiors where ambient illumination remains controlled.
- Kiosks:Interactive wayfinding terminals with integrated biometric boarding alignment at Dubai International and Denver International.
Volume sits with LED Displays; growth tilts toward Digital Signage.
Technology:
Adoption patterns in this dimension track IT infrastructure maturity and cybersecurity risk tolerance across airport operator profiles.
- Cloud-Based Solutions:SaaS architectures eliminating on-premise server maintenance attract greenfield airports in India and Southeast Asia. Chennai and Kolkata bypass legacy infrastructure entirely, subscribing to managed content delivery that shifts capital expenditure to operational budgets.
- IoT:Sensor-integrated displays enabling predictive maintenance contracts and condition-based servicing revenue streams. Lufthansa Technik and SITA bundle hardware with uptime guarantees at Munich and Zurich.
- Automation:Flight data processor synchronization reducing manual gate reassignment latency.
- Wireless Communication:5G-enabled screen networks for rapid temporary gate configuration during construction phases.
Cloud-Based Solutions expand most quickly among mid-tier operators; IoT commands premium pricing in European hub renewals.
End User:
Procurement authority fragmentation creates divergent specification priorities across stakeholder groups with conflicting performance metrics.
- Airports:Infrastructure owners optimizing passenger throughput and commercial concession revenue per square meter. Charles de Gaulle and Amsterdam Schiphol specify integrated display-building automation bundles through Honeywell and Siemens frameworks.
- Airlines:Carriers demanding gate-flexible systems that reduce minimum connection time penalties. Star Alliance members at Frankfurt and Chicago O'Hare coordinate fleet-wide display standardization through joint technical committees.
- Ground Handlers:Service providers requiring apron-facing displays synchronized with turnaround milestone tracking.
- Security Services:Checkpoint queue management screens integrated with passenger flow analytics.
Airports dominate absolute unit deployment; airlines drive specification convergence through alliance procurement.
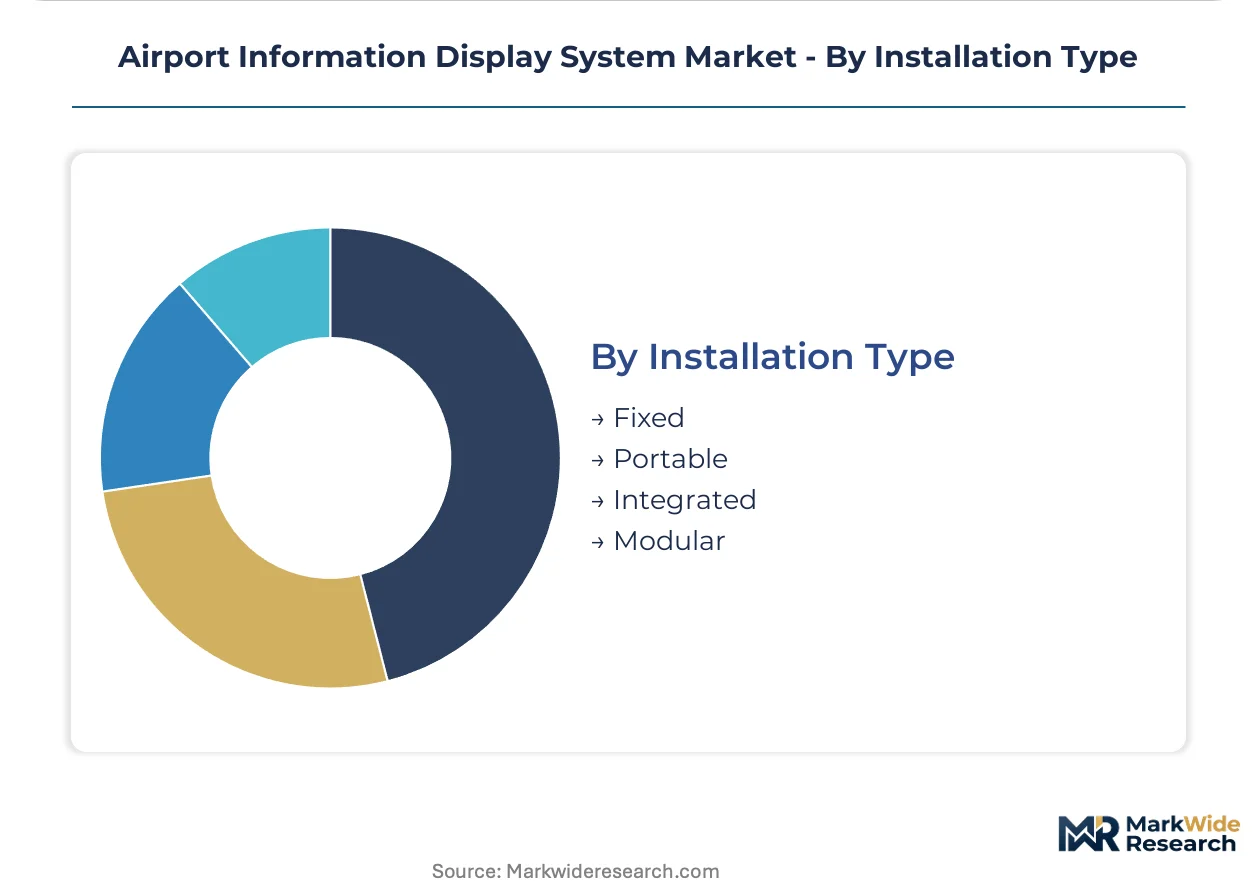
Installation Type:
Capital deployment flexibility separates retrofit-constrained legacy hubs from greenfield developments with unconstrained infrastructure planning.
- Fixed:Permanent structural installations with embedded power and data infrastructure. These anchor revenue concentration in established hubs where 20-year depreciation schedules favor durable LED wall configurations.
- Modular:Phased deployment architectures enabling incremental terminal expansion without operational disruption. India's Airports Authority of India mandates these at Ahmedabad and Kolkata brownfield modernizations where construction sequencing prohibits single-phase commissioning.
- Portable:Battery-powered units for emergency gate reassignments and remote apron operations.
- Integrated:Display systems hardwired into building management and fire safety infrastructure.
Fixed installations retain value concentration; modular configurations gain share fastest in emerging market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hub modernization programs concentrate procurement authority among major international airports, while regulatory fragmentation across jurisdictions shapes technology deployment timelines and specification requirements.
United States
FAA visibility mandates and airline operational demands for gate flexibility drive LED retrofit urgency across aging infrastructure. The FAA's electromagnetic interference testing requirements extend project delivery cycles. Dallas-Fort Worth International and Chicago O'Hare anchor concentrated procurement through alliance carrier coordination.
Germany
EU Green Deal energy performance thresholds accelerate terminal-wide LED conversions at Frankfurt and Munich airports. EASA continuing airworthiness frameworks shape display system redundancy specifications. Bavaria's industrial automation cluster supplies building automation integration expertise for Honeywell and Siemens deployments.
India
Airports Authority of India brownfield modernization at Chennai, Kolkata, and Ahmedabad creates modular display demand with phased capital deployment. The PLI scheme for electronics manufacturing reduces import dependency for LED components. Telangana and Maharashtra host emerging domestic assembly operations serving Southeast Asian markets.
United Arab Emirates
Dubai International's microLED flight information walls set flagship terminal visibility standards across the Gulf. MOHAP aviation infrastructure guidelines influence procurement specifications. Dubai and Abu Dhabi anchor premium-tier deployment concentration through biometric boarding alignment requirements.
Singapore
Changi Airport's microLED concourse specifications consolidate high-ambient-light performance leadership in Asia-Pacific. The Civil Aviation Authority of Singapore's smart airport framework mandates IoT-integrated display networks. The city-state serves as specification reference point for Southeast Asian greenfield developments.
Airport Information Display System Market Competitive Environment
European producers anchor one tier through building automation heritage; US specialists hold position via air traffic management integration and baggage handling software bundling. Market structure tilts toward consolidated procurement patterns as airline alliance committees standardize specifications across co-located carrier facilities. Three archetypes dominate: diversified industrial conglomerates with terminal automation portfolios, aviation-specific IT vendors leveraging operational software integration, and display hardware specialists pursuing ecosystem partnerships. Competitive moves concentrate on strategic partnerships with airport authorities and technology licensing for cloud-native content management architectures.
Within the aviation IT tier, SITA and Amadeus IT Group SA exemplify vendors bundling display hardware with passenger processing and baggage sortation software. Honeywell International Inc. and Siemens AG occupy positions linking building automation infrastructure into integrated terminal visual systems. Thales Group represents the air traffic management integration archetype, feeding display products directly from flight data processors.
| Leading Market Players |
|---|
| SITA |
| Amadeus IT Group SA |
| Honeywell International Inc. |
| Thales Group |
| Indra Sistemas |
| Siemens AG |
| ADB SAFEGATE |
| Collins Aerospace |
| RESA |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between FAA-mandated safety-critical displays and commercial-grade signage manifests in parallel pricing architectures and supplier qualification tiers. Premium LED matrices for flight information systems command substantial markups over gate-holdroom LCD panels, while foundry allocation priority for driver ICs concentrates in Taiwan and South Korea.
Pricing Analysis
Volume concentration in fixed LED installations anchors margin stability for established vendors, while modular retrofit configurations face sharper price competition from emerging Asian assemblers. Three-tier pricing structure across premium, standard, and economy levels separates microLED flagship deployments from SMD LED workhorse systems and projection-based temporary configurations. Cost compression in modular segments intensifies as India's PLI scheme enables domestic LED assembly operations. Regional airports exhibit highest price sensitivity due to capital budget fragmentation; alliance-coordinated hub procurements leverage volume for specification premiums.
Supply Chain Analysis
Dual-sourcing requirements for LED driver ICs and high-brightness diodes now appear in Frankfurt Airport and Singapore Changi procurement clauses, forcing qualification of secondary foundry relationships beyond dominant Taiwan and South Korea suppliers. Raw material dependencies center on gallium nitride substrates, aluminum heat-dissipation frameworks, and IP-rated enclosure polymers. Single-source vulnerability in advanced LED packaging creates exposure to foundry allocation volatility. Distribution runs through aviation-specific system integrators rather than direct OEM channels, with SITA and Amadeus bundling hardware into operational software contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity constraints for LED driver ICs prop pricing power for qualified vendors, creating a supply-constrained market structure favoring incumbent ecosystem players with secured allocation.
For Market Incumbents: Anticipate cloud-native display management platform consolidation by acquiring SaaS content management specialists before alliance procurement committees standardize specifications. Defensive positioning requires backward integration into LED packaging capacity and EASA cybersecurity certification investment ahead of diverging TSA-EASA framework reconciliation. For New Entrants and Emerging Players: Launch via modular display architecture partnerships with India's Airports Authority of India brownfield modernization program, where phased capital deployment requirements favor flexible procurement. White-space concentration appears in predictive maintenance service contracts and biometric boarding alignment integration for mid-tier Southeast Asian airports bypassing legacy infrastructure entirely. For Investors and Strategic Acquirers: Re-rating potential sits with aviation-IT vendors possessing baggage handling software heritage given alliance carrier demand for synchronized passenger-facing and operational systems. Long-term viability favors acquisition targets with EASA continuing airworthiness certification and established foundry allocation relationships. Monitor FAA electromagnetic interference testing backlog as inflection signal for project delivery timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | SaaS architectures reduce IT overhead for Chennai and Kolkata greenfield deployments. |
| Predictive Maintenance Service Bundling | IoT sensor integration enables Lufthansa Technik uptime guarantee contracts at Munich. |
| MicroLED Technology Licensing | Dubai International specifications establish premium-tier performance benchmarks regionally. |
| Biometric Boarding Alignment | Facial recognition gate synchronization creates specification bundling at Denver International. |
| EU Green Deal Compliance Certification | Extended producer responsibility documentation secures CE marking renewal for European hub contracts. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across airport operations directors, airline alliance procurement committees, aviation IT integration specialists, and LED display system engineers. FAA certification documentation, EASA continuing airworthiness frameworks, EU Green Deal energy performance mandates, and Airports Authority of India modernization tender documents supplied secondary validation. Bottom-up installation tracking across hub, regional, and cargo airport tiers triangulated against top-down vendor revenue aggregation.
Granularity-level modeling addressed product type segmentation at the display technology tier, technology adoption at the deployment architecture level, and end-user procurement authority fragmentation across airport authorities, airline consortiums, and ground handling operators. CAGRs derived from annual installation unit projections and average selling price trajectories across fixed, modular, and portable configurations. Cloud migration economics, semiconductor foundry allocation cycles, and regulatory certification timeline friction served as industry-specific forecast inputs across the projection horizon.
Semiconductor supply disruption, FAA certification timeline extension, and alliance procurement committee specification divergence are the dominant revision risks. Deviation in foundry allocation priority for LED driver ICs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Middle-East and Africa Smart Airport Market
Airport Technologies
Advanced Airport Technologies Market
Airport Technologies
Global Remote Towers Market
Airport Technologies
Smart Airport Market
Airport Technologies
Global Airport Baggage Handling System Market
Airport Technologies
Airport Runway Foreign Object Debris (FOD) Detection Systems Market
Airport Technologies
Airport Cargo Community Digital Collaboration Platforms Market
Airport Technologies
Airport Smart Lighting Market
Airport Technologies
Airport Baggage Conveyor System Market
Airport Technologies
Smart Airport 4.0 Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Asia-Pacific Airport Baggage Handling Systems Market
Airport Technologies
Smart Airport 3.0 Market
Airport Technologies
Bird Detection System for Airports Market