
 Asia Pacific Aerosol Cans Market | 2026-2036
Asia Pacific Aerosol Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Aerosol Cans Market Outlook
Asset-light leasing models for can-forming equipment is tilting competitive dynamics toward mid-tier regional converters. Ball Aerosol Packaging India leverages its backward integration into aluminum slug supply to sustain margin control across South Asian markets. Toyo Seikan anchors technical leadership through precision necking and shaping capabilities for high-pressure applications. CANPACK India competes on scale economics at its integrated beverage and aerosol complexes in Maharashtra and Uttar Pradesh.
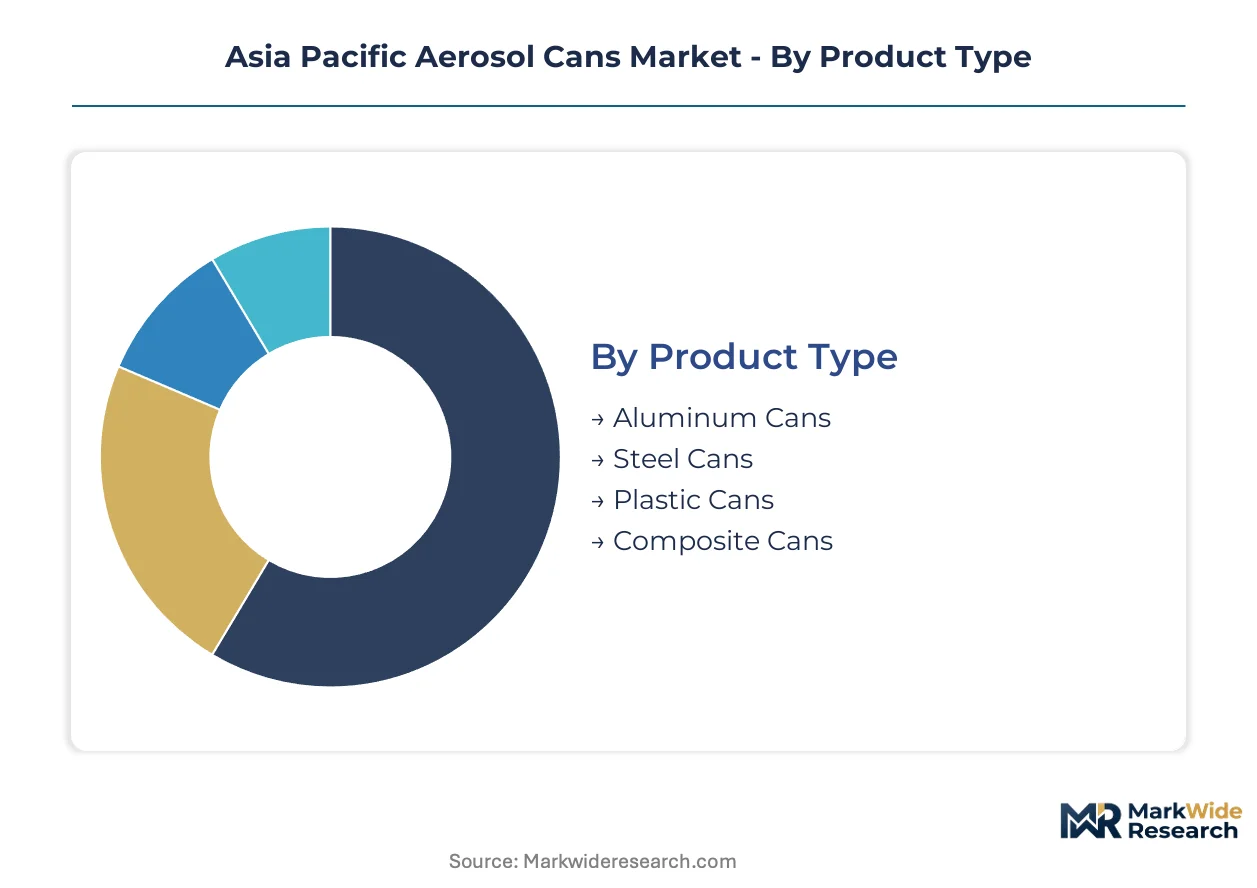
Asia Pacific aerosol cans are cylindrical pressurized containers, typically fabricated from aluminum or tinplate steel with internal epoxy or phenolic coatings, designed to store and dispense products through a metered valve system using liquefied or compressed propellants. These containers serve personal care, household, automotive, and industrial sectors where portable, contamination-free dispensing determines product utility. Aluminum Cans dominate value capture due to superior recyclability credentials and lightweight logistics economics across fragmented Asian distribution networks. Steel Cans retain cost-sensitive volume in agricultural and industrial sprays where corrosion resistance and puncture tolerance outweigh material premiums. Spray Technology leads functional deployment, though Foam Technology gains traction in shaving and cleaning applications where viscosity control and expansion ratios command formulation partnerships.
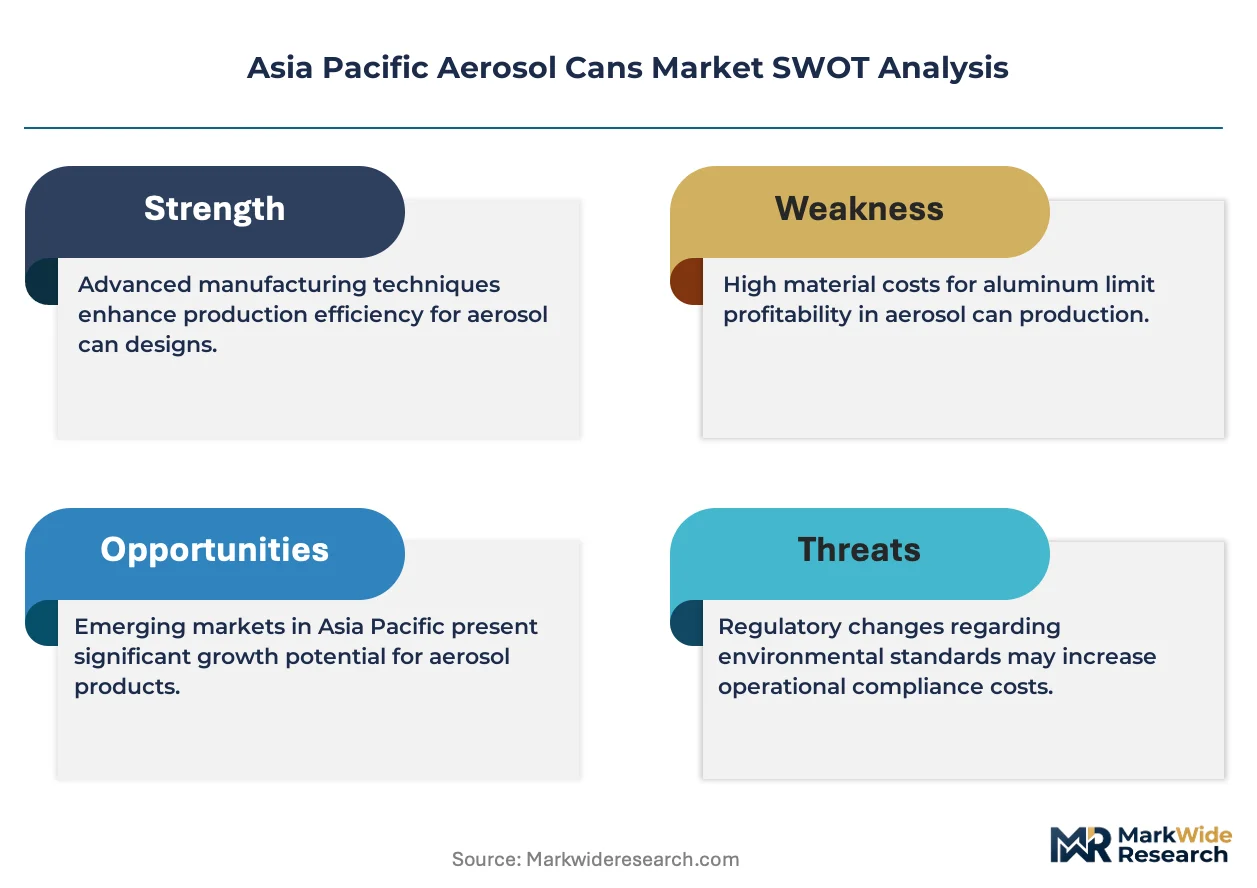
China's SAMR enforces GB standards on aerosol packaging safety and propellant composition, while India's BIS mandates dimensional and pressure-testing protocols for domestic and import sales. Japan's METI maintains JIS certification requirements that constrain market entry for uncertified Southeast Asian suppliers. REACH-aligned substance restrictions in formulations indirectly shape can lining specifications across export-oriented ASEAN producers. Stakeholders must monitor how evolving extended producer responsibility frameworks across the region redefine collection infrastructure obligations and material recovery economics.
Market Dynamics
China's GB packaging recyclability mandates are forcing aluminum can adoption across personal care supply chains while India's BIS quality protocols tighten dimensional tolerances for domestic converters. This dual-regulatory compression is restructuring procurement relationships between brand owners and regional fabricators.
Growth Catalysts
- Personal care aerosol expansion:Deodorant and dry shampoo brands are migrating pump formats to pressurized aluminum systems. Formulation houses in Maharashtra and Gujarat now maintain dedicated aerosol filling lines for contract manufacturing.
- REACH-aligned lining specifications:Export-oriented ASEAN producers are upgrading epoxy and phenolic coatings to meet substance restrictions. This compliance investment opens EU-bound personal care and pharmaceutical dispensing contracts.
- India's western manufacturing corridor:Contract packaging clusters from Pune to Ahmedabad serve domestic FMCG brands and Middle East export buyers with integrated slitting, coating, and filling capabilities.
Market Restraints
- Aluminum slug supply concentration:Primary aluminum ingot pricing volatility transmits directly to can fabricator margins. Ball Aerosol Packaging India's backward integration into slug casting provides insulation unavailable to independent converters.
- Steel can corrosion limitations:Agricultural and industrial spray formulations with aggressive solvents degrade tinplate interiors faster than aluminum alternatives. This technical ceiling constrains steel's penetration in premium household care.
- Japan's METI certification barriers:JIS pressure-testing and dimensional protocols exclude uncertified Southeast Asian suppliers from technical aerosol segments. Thai and Vietnamese fabricators face 18-24 month approval timelines.
Strategic Opportunities
- Philippines personal care underpenetration:Deodorant and hair spray per-capita consumption remains below regional averages. Local distributors are seeking toll-manufacturing partnerships with established ASEAN can suppliers.
- Foam technology convergence:Shaving and cleaning applications are adopting valve systems that control expansion ratios and viscosity. Formulation partnerships between can makers and chemical suppliers are creating captive supply arrangements.
- India's PLI scheme for packaging:Production-linked incentives for advanced materials and precision manufacturing are subsidizing necking and shaping equipment upgrades for domestic converters.
Industry Challenges
- Precision necking equipment scarcity:High-pressure aerosol applications require shaping tolerances below 0.05mm. Toyo Seikan's technical leadership in this capability has created a bottleneck for mid-tier competitors seeking pharmaceutical and automotive contracts.
- Extended producer responsibility compliance:Evolving collection infrastructure mandates across China, India, and ASEAN require fabricators to document material recovery rates. Data systems integration with municipal waste operators demands capital investment and personnel training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Aerosol Cans Market |
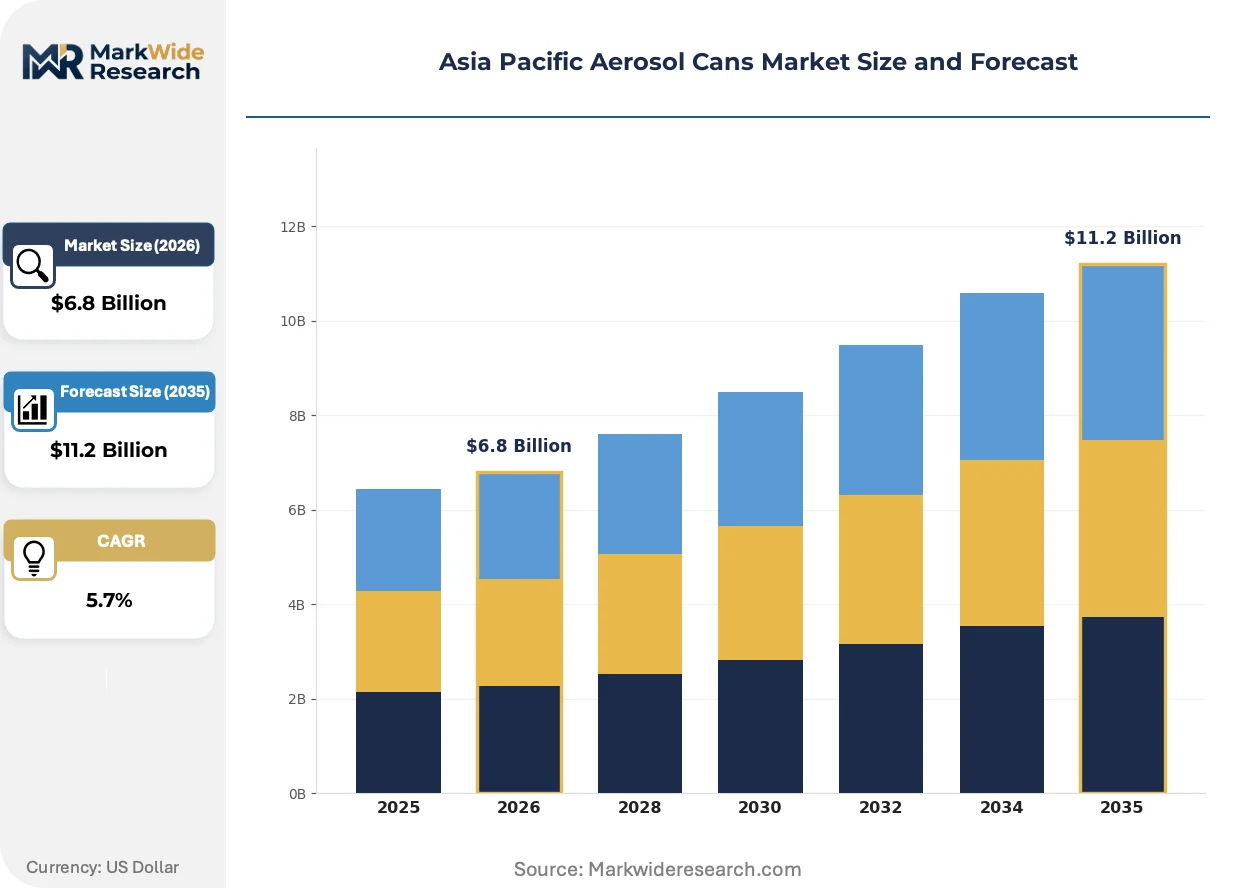
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Cans, Plastic Cans, Composite Cans End Use Industry: Personal Care, Household, Automotive, Paints Capacity: Below 100 ml, 100-300 ml, 300-500 ml, Above 500 ml Technology: Spray Technology, Foam Technology, Gel Technology, Others |
| Companies Covered | Ball Aerosol Packaging India Pvt. Ltd, Toyo Seikan Co. Ltd, CANPACK India Private Limited, CCL Industries Inc., Trivium Packaging B.V., Hindustan Tin Works Ltd, Casablanca Industries Pvt. Ltd, Alumatic Cans Pvt. Ltd, Swan Industries (Thailand) Co. Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Aerosol Cans Market Strategic Shifts
Digital manufacturing controls and sustainable material specifications are compressing product development cycles while fragmenting the traditional equipment supply chain. Regional converters now access precision forming capabilities through asset-light leasing rather than capital ownership.
Digital twin simulation software is virtualizing can design validation before physical tooling commitment. Personal care brand technical teams in Shanghai and Mumbai are adopting cloud-based finite element modeling to predict pressure performance and coating adhesion. This virtualization is compressing new product introduction timelines from 14 months to 7 months while reducing prototype scrap rates.
China's SAMR is enforcing updated GB standards on propellant composition and valve system safety testing. Domestic aerosol brands must submit formulation stability data and pressure-cycle test results for product registration. This regulatory tightening is accelerating consolidation among uncertified regional fillers who lack in-house testing laboratories.
Brand procurement teams are unbundling specification-setting from manufacturing execution. Large personal care multinationals now retain design authority while awarding production to lowest-qualified bidders across India, Thailand, and Vietnam. This disintermediation of technical control from fabrication is visible most acutely in deodorant and hair care segments where formulation complexity has standardized.
Asia Pacific Aerosol Cans Market Segmentation
Material specifications, formulation compatibility, and dispensing mechanics fragment demand across distinct technical tiers in Asia Pacific aerosol packaging. Procurement teams segment supplier qualification by pressure rating, lining chemistry, and recyclability credentials rather than unit cost alone.
Product Type:
Personal care brands specify aluminum for premium deodorant lines while agricultural distributors default to steel for solvent-based crop protection sprays.
- Aluminum Cans:Fabricated from drawn-and-ironed aluminum slugs with epoxy or phenolic interior coatings. Maharashtra and Gujarat contract packers specify these for deodorant and dry shampoo exports to Middle Eastern markets where recyclability mandates tighten procurement criteria.
- Steel Cans:Tinplate construction with double-seamed bottoms and corrosion-resistant linings. India's western manufacturing corridor retains steel volume for agricultural and industrial sprays where puncture tolerance outweighs weight penalties.
- Plastic Cans:PET or HDPE barrier constructions with multilayer coextrusion for chemical resistance. Limited penetration in personal care due to pressure rating constraints and BIS dimensional testing protocols.
- Composite Cans:Paperboard-film-laminate cylinders with metal or plastic ends. Niche applications in promotional sampling and travel-size personal care where cost minimization dominates specification.
The dominant share belongs to Aluminum Cans, while Composite Cans are gaining share fastest in sampling and travel retail formats.
End Use Industry:
Formulation viscosity and propellant chemistry determine can specification more than volume scale across these demand verticals.
- Personal Care:Deodorant, hair spray, and dry shampoo applications command precision necking tolerances for valve crimp integrity. China's SAMR registration requirements for propellant stability testing filter uncertified fillers from this premium segment.
- Household:Surface cleaners, air fresheners, and insecticides span aqueous to solvent-based formulations. REACH-aligned lining upgrades among ASEAN producers open EU-bound contract manufacturing for this mid-tier category.
- Automotive:Brake cleaners, lubricants, and touch-up sprays require high-pressure ratings and chemical-resistant coatings. Toyo Seikan's precision shaping capabilities dominate technical qualification for this specification-intensive segment.
- Paints:Architectural and automotive refinish aerosols demand specialized valve systems for viscosity control and overspray minimization. India's PLI scheme subsidizes equipment upgrades for domestic converters targeting this application.
Personal Care commands the largest value share, though Automotive applications carry the steepest margin premiums per unit.
Capacity:
Distribution economics and consumption patterns fragment procurement by fill volume across retail, professional, and industrial channels.
- Below 100 ml:Travel retail and promotional sampling formats. Airlines and hospitality procurement specify these for amenity kits where TSA compliance and weight reduction drive selection.
- 100-300 ml:Standard retail personal care and household formats. This capacity band concentrates contract packaging volume in Pune-Ahmedabad clusters serving domestic FMCG and export buyers.
- 300-500 ml:Professional salon and automotive service applications. Higher fill volumes require reinforced sidewall specifications for safe pressure containment.
- Above 500 ml:Industrial and agricultural bulk sprays. Steel can construction dominates this segment due to structural load requirements and cost sensitivity in B2B procurement.
The 100-300 ml range anchors volume throughput, while Below 100 ml formats expand most quickly in travel retail recovery.
Technology:
Valve engineering and propellant selection determine functional performance across dispensing modalities.
- Spray Technology:Conventional mechanical breakup valves using liquefied propellants for fine particle dispersion. This mature technology retains dominance across personal care and household applications in India and Southeast Asia.
- Foam Technology:Expansion chamber designs controlling viscosity and aeration ratios. Shaving and cleaning formulations in Japan and South Korea adopt these systems for texture differentiation and reduced propellant loading.
- Gel Technology:Thickened formulation dispensing through wide-orifice valves with positive shutoff. Limited penetration in hair styling and topical pharmaceutical applications where flow control outweighs spray coverage.
- Others:Bag-on-valve and piston barrier systems for sensitive formulations. Premium pharmaceutical and cosmetic applications in Australia and Japan specify these for oxygen exclusion and contamination prevention.
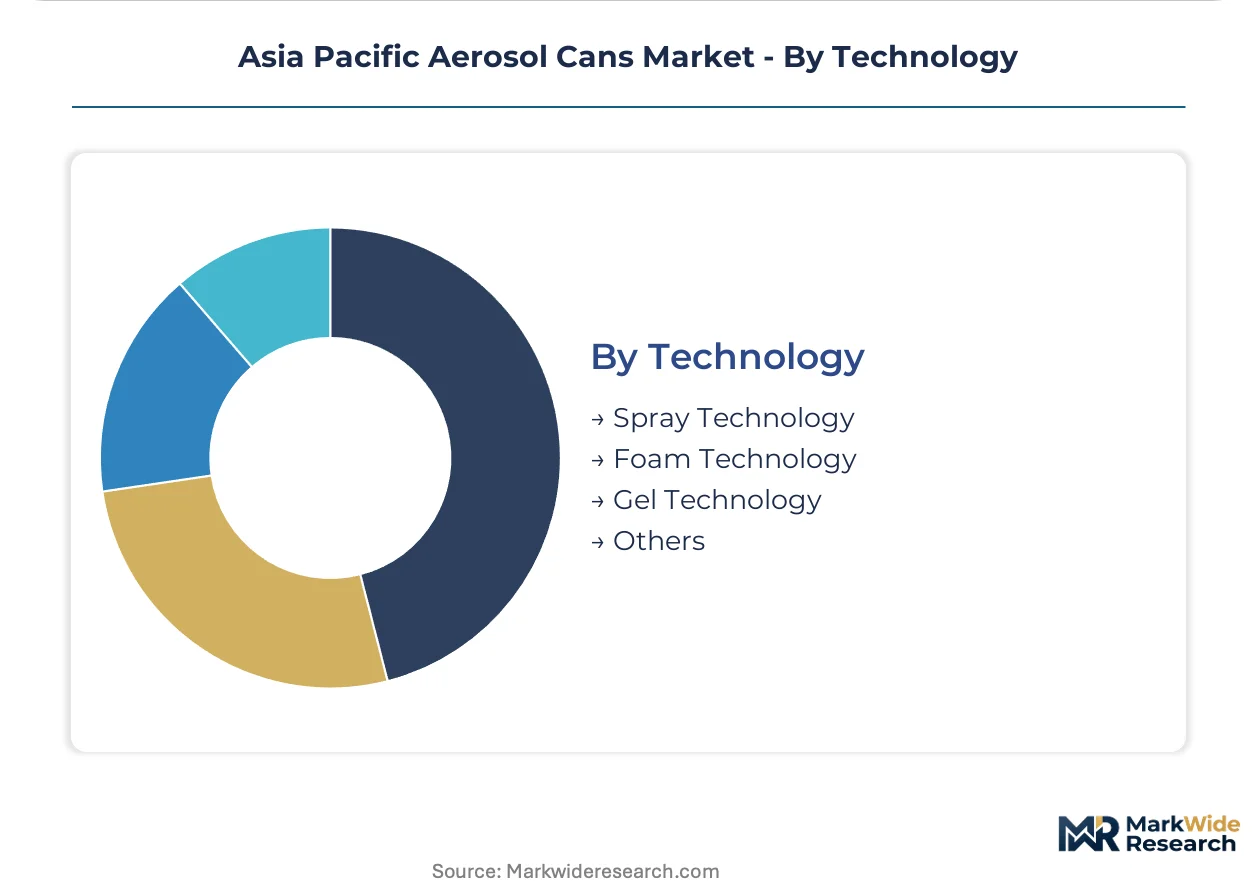
Spray Technology retains the installed base majority, though Foam Technology climbs fastest in premium personal care segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing power through aluminum slug supply control while Indian converters absorb margin compression from BIS compliance costs. This asymmetry shapes procurement negotiations across the region's personal care supply chains.
China
Deodorant and dry shampoo brands drive aluminum can demand through e-commerce expansion and domestic premiumization. SAMR enforces updated GB standards on propellant composition and pressure-cycle testing for product registration. Yangtze River Delta fabricators cluster around Shanghai to serve both domestic FMCG brands and export-oriented contract manufacturers.
India
Maharashtra-to-Gujarat contract packaging corridors process volume for domestic and Middle East export buyers. BIS dimensional and pressure-testing protocols filter uncertified converters from pharmaceutical and personal care segments. Pune-Ahmedabad industrial zones concentrate integrated slitting, coating, and filling capabilities for regional brand owners.
Japan
High-pressure automotive and precision pharmaceutical applications sustain demand for technically certified can fabrication. METI maintains JIS certification requirements that constrain market entry for uncertified Southeast Asian suppliers. Kanto and Kansai manufacturing belts host formulation houses requiring sub-0.05mm necking tolerances for valve crimp integrity.
Vietnam
Export-oriented ASEAN producers upgrade epoxy and phenolic coatings to meet REACH-aligned substance restrictions for EU-bound contracts. Agricultural and household spray formulations retain steel can preference for cost-sensitive domestic distribution. Ho Chi Minh City industrial parks attract toll-manufacturing partnerships from Philippine personal care distributors seeking capacity expansion.
Thailand
Automotive service and industrial lubricant applications require high-pressure ratings that favor precision shaping capabilities. Uncertified fabricators face 18-24 month METI approval timelines that exclude them from technical aerosol segments. Bangkok-Rayong manufacturing corridors serve regional automotive aftermarket brands with specialized coating specifications.
Asia Pacific Aerosol Cans Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in slug supply and precision equipment. The vendor base organizes around three archetypes: backward-integrated aluminum suppliers, precision necking specialists, and scale-driven integrated complexes. Consolidation pressures favor converters with captive raw material access or technical differentiation in high-pressure applications. Dominant competitive moves include equipment leasing partnerships that reduce capital barriers for mid-tier entrants, and formulation alliances that lock in valve system specifications.
Among Japan-based precision fabricators, Toyo Seikan Co. Ltd exemplifies the technical-specialist archetype through its positioning in high-pressure shaping capabilities. Ball Aerosol Packaging India Pvt. Ltd represents backward-integrated supply control, with its India-domiciled structure signaling regional market commitment. CANPACK India Private Limited occupies the scale-driven tier, leveraging integrated beverage and aerosol complexes across multiple Indian states. These three anchors illustrate how geographic positioning and supply chain architecture determine competitive access across the region's fragmented procurement landscape.
| Leading Market Players |
|---|
| Ball Aerosol Packaging India Pvt. Ltd |
| Toyo Seikan Co. Ltd |
| CANPACK India Private Limited |
| CCL Industries Inc. |
| Trivium Packaging B.V. |
| Hindustan Tin Works Ltd |
| Casablanca Industries Pvt. Ltd |
| Alumatic Cans Pvt. Ltd |
| Swan Industries (Thailand) Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
China's Yangtze River Delta aluminum slug foundries concentrate upstream supply control, transmitting ingot price volatility directly to can fabricator margins across India and Southeast Asia. This geographic asymmetry positions Ball Aerosol Packaging India's captive casting capacity as a margin pool that independent Maharashtra and Gujarat converters cannot replicate.
Pricing Analysis
Configured-to-order pricing for precision-necked pharmaceutical and automotive cans commands 40-60% premiums over standard personal care formats. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified Japanese fabricators from BIS-compliant Indian mid-tiers and uncertified Vietnamese steel can producers. Cost compression in standard deodorant and household segments is intensifying because brand procurement teams unbundle design authority from manufacturing execution. Agricultural distributors in India's western corridor exhibit highest price sensitivity, while Japanese automotive formulation houses show least sensitivity due to sub-0.05mm tolerance requirements.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk calculations for aluminum slug procurement. Raw material flows draw from Chinese primary ingot smelters, Indian secondary recycling streams, and Australian bauxite sources. Component dependencies center on epoxy and phenolic coating chemistries from South Korean and German specialty chemical suppliers, plus precision necking equipment from Japanese and Italian machinery builders. Single-source vulnerability concentrates in high-pressure shaping tooling where Toyo Seikan's technical specifications have created captive supplier relationships. Distribution runs through Maharashtra-Gujarat contract packaging clusters for domestic Indian and Middle East export markets, with Ho Chi Minh City industrial parks serving Philippine toll-manufacturing demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific aerosol packaging sits at a high-growth inflection as China's SAMR GB standard enforcement on propellant composition and pressure-cycle testing accelerates consolidation among uncertified regional fillers.
For Market Incumbents: Harden technical certification moats by securing JIS pressure-testing protocols for Japanese pharmaceutical and automotive segments before Southeast Asian competitors complete 18-24 month METI approval timelines. Deepen backward integration into aluminum slug casting to insulate margin pools from Chinese ingot price volatility that independent converters cannot hedge. Prioritize captive supply arrangements with foam technology valve system partners to lock in shaving and cleaning formulation alliances. For New Entrants and Emerging Players: Build out toll-manufacturing partnerships with Philippine personal care distributors seeking capacity expansion for deodorant and hair spray segments where per-capita consumption trails regional averages. Target India's PLI-subsidized precision equipment upgrade pathway to qualify for domestic pharmaceutical and paint aerosol contracts. Lead with asset-light leasing models for necking and shaping machinery that reduce capital barriers against integrated beverage-aerosol complexes. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian contract packaging platforms that consolidated during BIS compliance investment waves. Five-to-ten year viability hinges on extended producer responsibility framework positioning as collection infrastructure mandates across China, India and ASEAN redefine material recovery economics. Watch for SAMR registration database expansion signaling accelerated uncertified filler exits and corresponding contract volume migration to certified fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Slug Supply | Captive casting capacity insulates Ball Aerosol Packaging India from Chinese ingot volatility. |
| Precision Necking Equipment Leasing Partnerships | Asset-light models enable mid-tier Maharashtra converters to qualify for pharmaceutical contracts. |
| Foam Technology Valve System Alliances | Formulation partnerships with chemical suppliers create captive supply in shaving applications. |
| JIS Certification Investment for METI Compliance | Japanese automotive formulation houses require sub-0.05mm tolerance capabilities. |
| Extended Producer Responsibility Data Integration | Documentation systems with municipal waste operators satisfy evolving China-India-ASEAN mandates. |
Study Parameters
Operator-level perspectives from can fabrication plant managers, personal care brand procurement leads, coating chemistry R&D directors, and Maharashtra-Gujarat contract packaging executives anchored the qualitative base. Secondary validation drew from SAMR GB standard filings, BIS dimensional testing protocols, METI JIS certification registers, and ASEAN customs trade records. Bottom-up triangulation across regional converter capacity assessments and top-down aluminum slug demand modeling cross-verified volume estimates.
Scenario-bracketing framed conservative and expansion cases across the analysis window without year-specific milestones. Segmentation dimensions modeled include material specification tiers, end-use industry verticals, capacity bands, and dispensing technology modalities. CAGRs derived from aluminum can value capture trajectories against steel can volume retention patterns, with formulation viscosity trends and propellant chemistry shifts as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed aluminum smelters or accelerated SAMR enforcement would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Chitin Market
Specialty Chemicals
Global Foam Blowing Agents Market
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
Naphthol AS-IRG Market
Specialty Chemicals
Solar Cell Front Side Silver Paste Market
Specialty Chemicals
Dimethyl Succinyl Succinate Market
Specialty Chemicals
North America Non-Phthalate Plasticizers Market
Specialty Chemicals
High-K and CVD ALD Metal Precursors Market
Specialty Chemicals
Anhydroxylitol Market
Specialty Chemicals
Specialty Oxidants Market
Specialty Chemicals
Isophytol Market
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
Halogen-Free Flame Retardants Market
Specialty Chemicals
Natural Ingredient Insect Repellent Market
Specialty Chemicals
Global Tetrakis (Hydroxymethyl) Phosphonium Sulfate Market
Specialty Chemicals
Alkoxide Market