
 Asia Pacific Industrial Solvents Market | 2026-2036
Asia Pacific Industrial Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Industrial Solvents Market Outlook
Modular solvent blending is shifting buyer procurement patterns across Asia Pacific industrial markets. Sinopec Group leverages integrated refinery-petrochemical complexes to supply standardized base solvent packages at scale. Mitsubishi Chemical Holdings Corporation specializes in high-purity electronic-grade formulations for semiconductor clients in Japan and Taiwan. Reliance Industries Limited anchors its position through backward integration into cracker operations at its Jamnagar complex.
Industrial solvents comprise organic liquids with defined boiling points, flash points, and solubility parameters that dissolve, suspend, or extract other materials without chemical alteration. Alcohols dominate volume consumption across paints and coatings applications where fast evaporation rates enable efficient film formation. Pharmaceutical-grade solvents command premium pricing due to stringent residual impurity limits and batch certification requirements that exclude commodity producers. The automotive end-user segment generates concentrated demand for cleaning and degreasing formulations at assembly plants in Thailand and Indonesia.
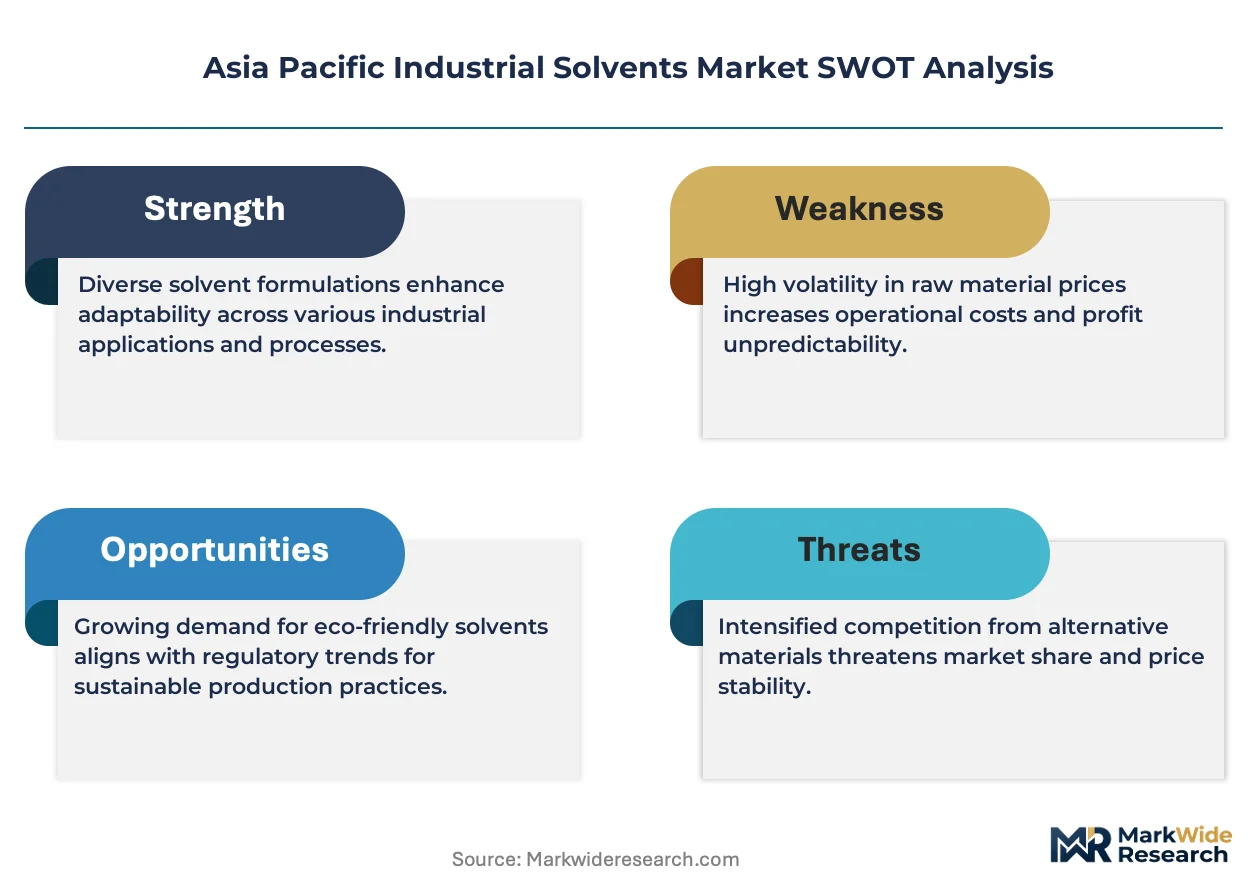
China's MEE enforces GB standards limiting benzene and toluene content in consumer-facing coatings, redirecting formulation demand toward oxygenated solvents. India's BIS mandates solvent purity specifications for food-grade and pharmaceutical applications that restrict import sourcing to certified refiners. South Korea's MFDS aligns with ICH Q3C residual solvent guidelines for active pharmaceutical ingredient manufacturing, shaping exporter qualification protocols. Stakeholders must monitor regulatory divergence between national standards frameworks as formulation registration costs fragment supply chain economics.
Market Dynamics
China's MEE enforcement of GB 38508-2020 VOC limits is forcing solvent producers to abandon aromatic formulations and retool toward oxygenated alternatives, compressing margins for refiners lacking bio-based capabilities while opening premium positioning for compliant specialists.
Growth Catalysts
- Semiconductor fabrication expansion:South Korea's Samsung Electronics and SK Hynix drive consumption of high-purity electronic-grade solvents for wafer cleaning and photoresist stripping, with Taiwan's TSMC fabs adding parallel demand for ultra-low moisture formulations.
- India's PLI scheme for specialty chemicals:Production-linked incentives for domestic manufacturing of pharmaceutical intermediates attract solvent producers to Gujarat and Maharashtra industrial corridors, reducing import dependence for IPA and acetone derivatives.
- Thailand's Eastern Economic Corridor:Automotive assembly plants at Rayong and Chonburi generate concentrated demand for metal degreasing and surface preparation solvents, with Japanese OEM suppliers localizing blending operations to serve just-in-time production schedules.
Market Restraints
- Naphtha feedstock volatility:Crackers at Singapore's Jurong Island and South Korea's Yeosu complex face margin compression when regional naphtha benchmarks spike, forcing solvent producers to absorb cost swings or risk volume losses to Asian competitors.
- MEE emission quota enforcement:China's provincial-level VOC discharge permits create production caps for aromatic solvent manufacturers in Shandong and Jiangsu, constraining supply elasticity during demand surges.
- Aqueous cleaning system substitution:Precision electronics assemblers in Malaysia's Penang cluster trial water-based flux removers that eliminate solvent waste disposal costs, threatening traditional alcohol-based degreaser volumes.
Strategic Opportunities
- Vietnam's northern industrial zones:Samsung Display and LG Electronics panel manufacturing at Bac Ninh and Hai Phong create unmet demand for electronic-grade solvents, with local blending capacity lagging behind consumption growth.
- Indonesia's biodiesel mandate spillover:Palm oil methyl ester production generates glycerin coproduct streams that specialty chemical producers convert to bio-based propylene glycol ethers, qualifying for preferential procurement by sustainability-conscious coatings formulators.
- Australia's TGA pharmaceutical export pathway:GMP-certified solvent refiners in Victoria and New South Wales gain qualification for active pharmaceutical ingredient manufacturing supply chains serving Southeast Asian generic drug producers.
Industry Challenges
- Cross-contamination control in multi-product plants:Solvent blenders serving both industrial and pharmaceutical grades must segregate production lines to meet MFDS and BIS residual impurity limits, doubling facility capital requirements.
- Legacy aromatic inventory stranding:Producers holding toluene and xylene stocks face accelerated write-downs as China's consumer-facing coatings sector completes formulation transitions ahead of MEE compliance deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Industrial Solvents Market |
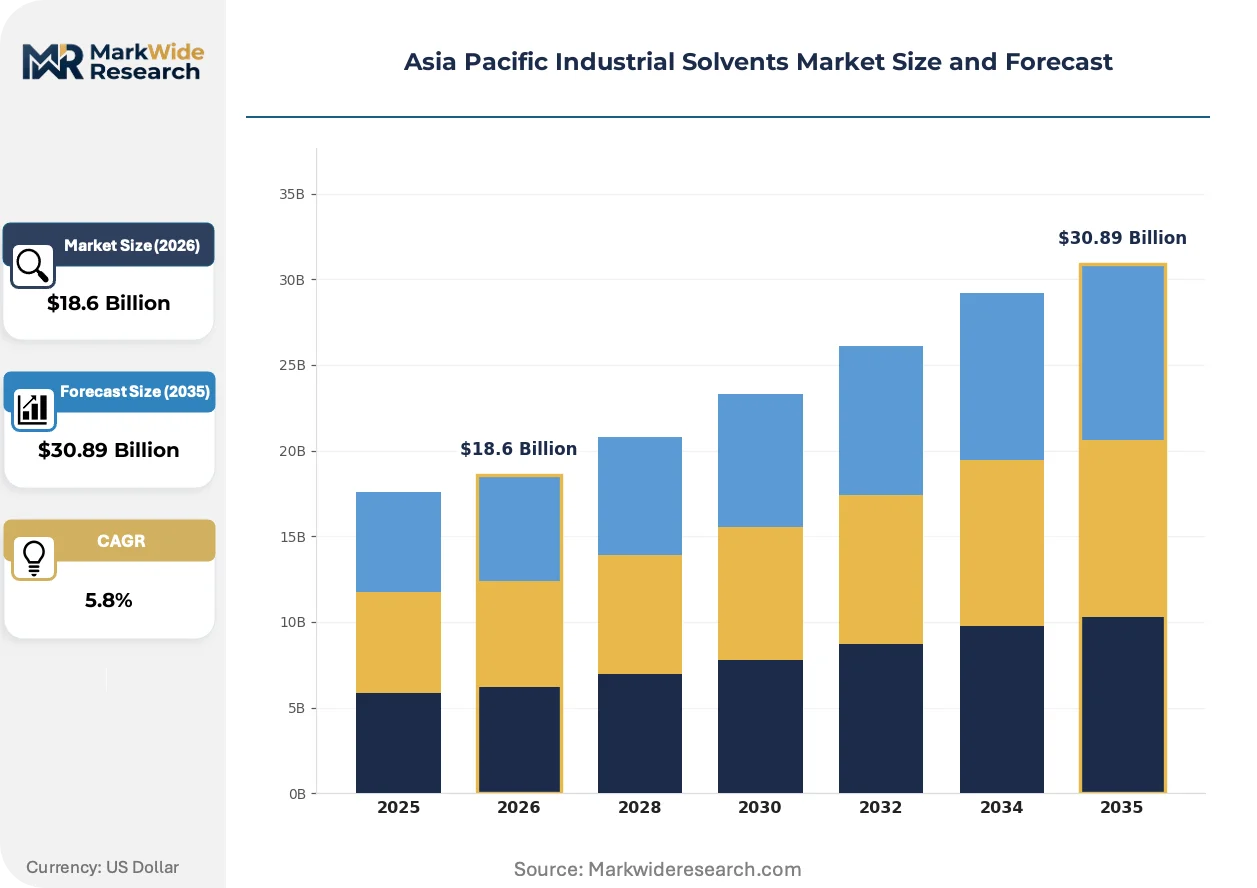
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Aromatics, Aliphatic, Alcohols, Esters Grade: Industrial Grade, Food Grade, Pharmaceutical Grade, Cosmetic Grade Application: Paints, Coatings, Adhesives, Cleaning Agents End User: Manufacturing, Construction, Automotive, Electronics |
| Companies Covered | China National Petroleum Corporation (CNPC), Sinopec Group, Formosa Plastics Corporation, Reliance Industries Limited, Mitsubishi Chemical Holdings Corporation, Sumitomo Chemical Co., Ltd., LG Chem Ltd., BASF SE, LyondellBasell Industries, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Industrial Solvents Market Strategic Shifts
Digital process control systems are penetrating solvent manufacturing at accelerating velocity, compressing batch-to-batch variability and enabling real-time quality certification that reduces customer qualification timelines.
Closed-loop solvent recovery systems are automating distillation and purification cycles at electronics manufacturing service providers in Taiwan's Taoyuan Science Park. Foxconn and Pegatron facilities deploy membrane separation modules that reclaim isopropyl alcohol from wafer cleaning operations at rates exceeding traditional open-loop disposal. This technology is automating cost recovery while tightening environmental compliance without production line shutdowns.
China's MEE is tightening GB 30982-2014 enforcement for architectural coatings, extending VOC limits to interior wood finishes and automotive refinish products previously exempted. Formulators in Guangdong and Zhejiang provinces accelerate methyl acetate and acetate ester substitutions for aromatic thinners. Waterborne alkyd resin demand accelerates as coating manufacturers pre-position for anticipated 2025 standard revisions.
Consolidated procurement platforms are displacing fragmented distributor networks across Asia Pacific industrial solvent purchasing. Large automotive OEMs in Thailand and Indonesia mandate direct-supplier relationships with certified refiners, bypassing traditional trading houses that added margin layers without technical support. Japanese chemical majors respond by embedding technical service teams at customer formulation laboratories, converting transactional supply into specification partnerships.
Asia Pacific Industrial Solvents Market Segmentation
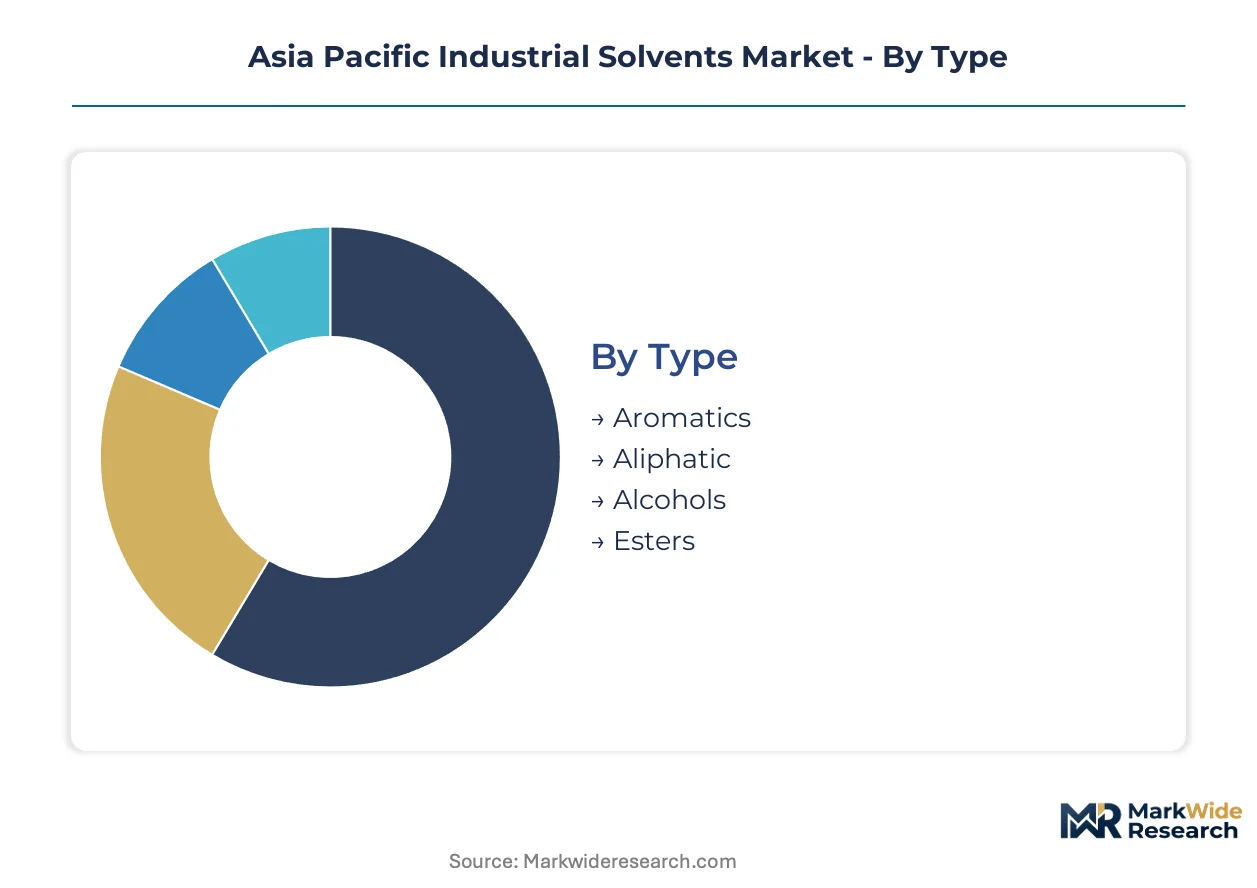
Industrial solvent procurement decisions across Asia Pacific diverge sharply by technical specification and regulatory burden. Buyers in semiconductor fabrication prioritize ultra-low moisture grades while coatings formulators optimize for evaporation rates and VOC compliance thresholds.
Type:
Buyers select solvent families based on solubility parameters, evaporation profiles, and emission compliance costs rather than price alone.
- Alcohols:Isopropanol and ethanol formulations dominate volume consumption in electronics cleaning and pharmaceutical extraction. Samsung Electronics and TSMC fabs in South Korea and Taiwan drive concentrated demand for semiconductor-grade isopropyl alcohol with moisture content below 100 ppm.
- Esters:Acetate esters and methyl acetate gain share in architectural coatings as China's MEE enforces GB 38508-2020 VOC limits. Guangdong formulators accelerate substitution of aromatic thinners with oxygenated alternatives that meet consumer-facing product standards.
- Aromatics:Toluene and xylene volumes contract under regulatory pressure despite superior solvency power for industrial coatings.
- Aliphatic:Mineral spirits and hexane serve degreasing applications at Thailand's Rayong automotive assembly plants where flash point requirements constrain alternatives.
Alcohols lead on scale across Asia Pacific manufacturing; esters lead on momentum as MEE compliance deadlines approach.
Grade:
Certification tier determines accessible end-use markets and pricing power, with pharmaceutical and food grades commanding substantial premiums over industrial specifications.
- Pharmaceutical Grade:Residual solvent limits under ICH Q3C and MFDS guidelines require dedicated production lines and batch certification. India's BIS mandates purity specifications that restrict import sourcing to certified refiners in Gujarat and Maharashtra corridors.
- Industrial Grade:Bulk solvents for paints, coatings, and metal cleaning operate on specification-tender contracts with minimal certification overhead. Sinopec Group supplies standardized base solvent packages at scale through integrated refinery-petrochemical complexes.
- Food Grade:Extraction solvents for edible oils and flavor compounds face national purity mandates that vary across Asia Pacific jurisdictions.
- Cosmetic Grade:Personal care formulators in South Korea and Japan demand low-odor, low-residue specifications for skin-contact applications.
Industrial grade dominates volume throughput; pharmaceutical grade captures the steepest expansion trajectory as domestic API manufacturing expands under India's PLI scheme.
Application:
Formulation function dictates solvent selection criteria from film formation speed to substrate compatibility and regulatory exposure.
- Paints:Architectural and industrial coatings consume the largest solvent volumes, with waterborne alkyd resins accelerating as formulators pre-position for anticipated MEE standard revisions in China.
- Cleaning Agents:Precision electronics assemblers in Malaysia's Penang cluster trial water-based flux removers that threaten traditional alcohol-based degreaser volumes.
- Coatings:Automotive refinish and protective coatings maintain solvent demand at Thailand's Eastern Economic Corridor assembly plants.
- Adhesives:Pressure-sensitive and structural bonding formulations require tailored solvent blends for viscosity control and open-time management.
Paints anchor regional consumption; cleaning agents face the most acute substitution pressure from aqueous system trials.
End User:
Customer industry concentration shapes supply chain configuration, with electronics and automotive sectors driving premium-grade demand while construction absorbs commodity volumes.
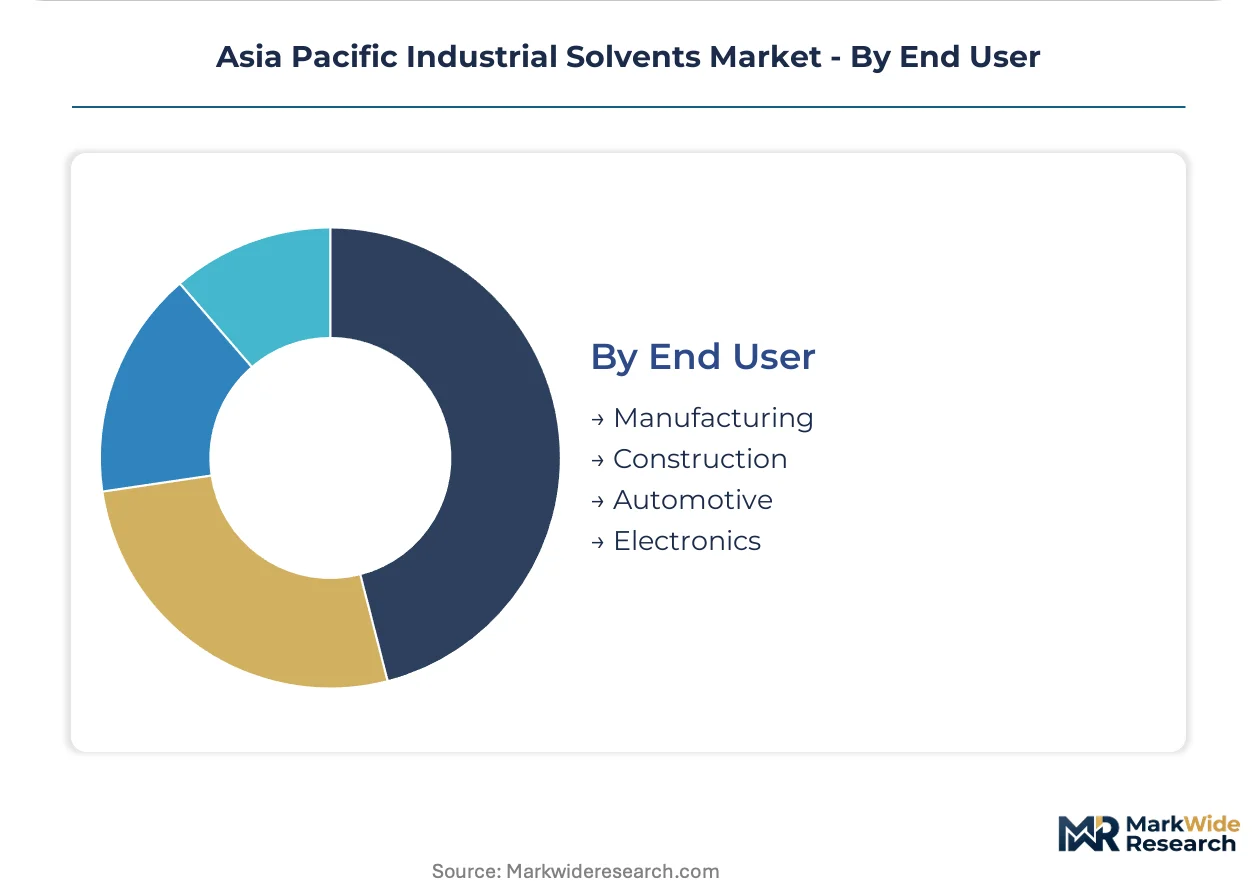
- Electronics:Semiconductor fabrication and display panel production in South Korea, Taiwan, and Vietnam's northern industrial zones generate concentrated demand for high-purity electronic-grade solvents. Samsung Display and LG Electronics operations at Bac Ninh and Hai Phong create supply gaps as local blending capacity lags consumption growth.
- Automotive:Assembly plants in Thailand and Indonesia generate systematic demand for metal degreasing and surface preparation solvents. Japanese OEM suppliers localize blending operations to serve just-in-time production schedules at Rayong and Chonburi facilities.
- Manufacturing:General industrial applications span metalworking, plastics processing, and equipment maintenance across diverse facility scales.
- Construction:Architectural coatings and adhesives consumption tracks building activity cycles in China's eastern coastal provinces and Southeast Asian urban centers.
Electronics commands the highest purity premiums; automotive delivers the most predictable volume contracts through embedded supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial solvent production across Asia Pacific traces its modern lineage to Japan's post-war petrochemical buildout in the 1950s, followed by South Korea's and Taiwan's electronics-focused expansions in the 1980s. China's subsequent integration into global supply chains transformed the region into the world's largest solvent consumption bloc. Today, national regulatory divergence and end-use specialization fragment competitive dynamics across the region.
China
Semiconductor fabrication at SMIC and display panel production at BOE Technology drive concentrated demand for electronic-grade isopropyl alcohol. MEE enforcement of GB 38508-2020 VOC limits is forcing Shandong and Jiangsu aromatic solvent producers toward oxygenated alternatives. The Yangtze River Delta petrochemical clusters supply downstream manufacturing hubs in Shanghai and Suzhou with standardized base solvent packages.
South Korea
Samsung Electronics and SK Hynix fabs generate systematic consumption of ultra-low moisture solvents for wafer cleaning and photoresist stripping. MFDS alignment with ICH Q3C residual solvent guidelines shapes exporter qualification protocols for pharmaceutical-grade formulations. The Yeosu petrochemical complex anchors domestic supply with integrated cracker-to-solvent production chains.
Japan
Mitsubishi Chemical Holdings and Sumitomo Chemical serve Taiwan's TSMC and domestic semiconductor clients with high-purity electronic-grade formulations. METI oversight of chemical substance management under CSCL mandates notification requirements for new solvent introductions. The Chubu region around Nagoya hosts precision electronics assemblers demanding sub-100 ppm moisture specifications.
India
The PLI scheme for specialty chemicals attracts solvent producers to Gujarat and Maharashtra industrial corridors for pharmaceutical intermediate manufacturing. BIS mandates solvent purity specifications for food-grade and pharmaceutical applications that restrict import sourcing to certified refiners. Reliance Industries' Jamnagar complex supplies backward-integrated feedstock for domestic IPA and acetone derivative production.
Vietnam
Samsung Display and LG Electronics panel manufacturing at Bac Ninh and Hai Phong create unmet demand for electronic-grade solvents as local blending capacity lags consumption growth. The country's Ministry of Natural Resources and Environment is drafting industrial emission standards modeled on China's MEE framework. Northern industrial zones around Hanoi lack qualified refiners capable of meeting semiconductor-grade moisture specifications.
Asia Pacific Industrial Solvents Market Competitive Environment
The competitive structure tilts toward integrated petrochemical conglomerates with captive feedstock supply. National oil companies and diversified chemical majors control approximately two-thirds of regional base solvent capacity through refinery-petrochemical complex integration. Three archetypes dominate: state-backed energy majors with backward integration into cracker operations, Japanese and Korean diversified chemical groups with electronic-grade specialization, and Indian conglomerates leveraging domestic feedstock advantages. Capacity expansion and portfolio diversification toward bio-based formulations represent the dominant competitive moves as MEE compliance deadlines approach.
Among state-backed energy majors, China National Petroleum Corporation and Sinopec Group exemplify the integrated refinery-petrochemical model with standardized base solvent supply at scale. Within the diversified chemical tier, Mitsubishi Chemical Holdings Corporation and Sumitomo Chemical Co., Ltd. occupy positions emphasizing high-purity electronic-grade specialization for semiconductor clients. Reliance Industries Limited anchors the Indian competitive vector through backward integration into Jamnagar cracker operations. These three archetypes represent distinct strategic postures: feedstock security, technical specification leadership, and domestic market vertical integration respectively.
| Leading Market Players |
|---|
| China National Petroleum Corporation (CNPC) |
| Sinopec Group |
| Formosa Plastics Corporation |
| Reliance Industries Limited |
| Mitsubishi Chemical Holdings Corporation |
| Sumitomo Chemical Co., Ltd. |
| LG Chem Ltd. |
| BASF SE |
| LyondellBasell Industries |
| Others |
Value Chain & Pricing Dynamics
Backward integration into cracker operations anchors pricing power for Asia Pacific solvent producers, with Sinopec Group and Reliance Industries leveraging captive naphtha supply to compress feedstock volatility while independent blenders absorb spot market swings. China's MEE emission quotas and India's BIS certification mandates fragment procurement economics, forcing buyers to navigate tiered supplier qualifications that separate integrated majors from trading-house intermediaries.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, electronic, and industrial grades separates premium solvent valuations by certification burden rather than feedstock cost alone. Price differentiation hinges on ICH Q3C residual solvent compliance and moisture specifications below 100 ppm, with Samsung Electronics and TSMC fabs paying substantial premiums for semiconductor-grade isopropyl alcohol. Cost compression in aromatic formulations is intensifying because China's GB 38508-2020 transition strands legacy toluene inventories. Automotive assemblers in Thailand's Eastern Economic Corridor exhibit highest price sensitivity due to just-in-time procurement volumes, while pharmaceutical API manufacturers accept premium positioning to secure batch certification.
Supply Chain Analysis
Certification gating through MFDS, BIS, and MEE frameworks restricts qualified refiner pools to integrated petrochemical complexes in China, South Korea, and India. Raw material flows draw from Singapore's Jurong Island naphtha terminals, Yeosu cracker output, and Jamnagar feedstock streams. Single-source vulnerability concentrates at Shandong and Jiangsu aromatic production hubs where provincial VOC discharge permits cap supply elasticity. Distribution runs through direct-supplier relationships that Japanese chemical majors embed at customer formulation laboratories, displacing traditional trading house networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific industrial solvents function as a geographic-arbitrage play where India's PLI scheme subsidies and China's MEE compliance costs create divergent margin structures across otherwise comparable production bases.
For Market Incumbents: Extend electronic-grade capacity in Vietnam's northern industrial zones before Samsung Display and LG Electronics panel consumption outpaces local blending qualification. Deepen backward integration into bio-based feedstock streams to defend margin position against Indonesia's glycerin-to-propylene-glycol-ether conversion economics. Lock long-term offtake agreements with pharmaceutical intermediate producers in Gujarat and Maharashtra corridors before BIS certification requirements tighten import sourcing windows. For New Entrants and Emerging Players: Begin with aqueous cleaning system substitution trials at Malaysia's Penang precision electronics cluster, where Foxconn and Pegatron facilities pilot membrane separation modules that threaten traditional alcohol-based degreaser volumes. Target Vietnam's Bac Ninh and Hai Phong industrial zones where semiconductor-grade solvent demand runs three years ahead of qualified domestic supply. Lead with closed-loop solvent recovery technology partnerships rather than commodity blending capacity. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap pharmaceutical-grade specialists because India's PLI scheme and China's MEE enforcement simultaneously expand addressable demand and raise facility capital barriers for new entrants. Target refiners with dedicated production line segregation serving both industrial and pharmaceutical grades under MFDS and BIS residual impurity limits. Watch for inflection where provincial VOC discharge permit trading opens in Shandong and Jiangsu, signaling regulatory market formation that rewards early compliance positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cracker Operations | Reliance Industries' Jamnagar complex supplies captive feedstock that insulates margin from naphtha benchmark volatility. |
| Bio-Based Formulation Transition | Indonesia's palm oil methyl ester glycerin coproducts enable propylene glycol ether production qualifying for MEE-compliant coatings procurement. |
| Electronic-Grade Capacity Expansion | Vietnam's Samsung Display and LG Electronics operations at Bac Ninh and Hai Phong outpace local blending qualification by three years. |
| Closed-Loop Solvent Recovery Deployment | Foxconn and Pegatron facilities in Taiwan's Taoyuan Science Park reclaim isopropyl alcohol through membrane separation modules. |
| Pharmaceutical Certification Investment | India's BIS mandates restrict food-grade and pharmaceutical solvent import sourcing to certified Gujarat and Maharashtra refiners. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at Sinopec Group and Mitsubishi Chemical Holdings complexes, procurement leads at Samsung Electronics and TSMC fabs, distribution channel partners across Thailand's Eastern Economic Corridor, and technical R&D directors formulating for China's MEE compliance transitions. Secondary validation drew from China customs trade data, ACC solvent consumption reports, SEC 10-K filings of diversified chemical majors, and GB standard revision notices from MEE. Bottom-up capacity assessments and top-down end-use consumption estimates triangulated to constrain forecast variance.
Historical reference periods anchored the projection horizon to pre-pandemic baseline capacity utilization and post-MEE enforcement demand shifts, with CAGRs derived from segment-level modeling across pharmaceutical grade, electronic grade, and industrial grade tiers; alcohol, ester, aromatic, and aliphatic type families; and electronics, automotive, manufacturing, and construction end-use concentrations. Naphtha feedstock price volatility indices and provincial VOC discharge permit allocation schedules fed directly into margin compression scenarios for Shandong and Jiangsu aromatic producers.
Caveats apply where MEE standard revision timing or PLI scheme disbursement delays could materially shift the outlook for oxygenated solvent substitution and domestic API manufacturing expansion. A model refresh is warranted upon material change in China's provincial emission permit trading mechanism or India's BIS pharmaceutical solvent purity specification enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Para Nitrochlorobenzene Market
Solvents
Decanol Market
Solvents
Butane Market
Solvents
Hydrophobic Solvents Market
Solvents
Diethylene Glycol Monobutyl Ether Acetate Market
Solvents
Global Glycol Market
Solvents
Mesitylene Market
Solvents
Asia-Pacific Ethane Market
Solvents
India High Purity Solvents Market
Solvents
Ionic Liquids Market
Solvents
Global Solvents Market
Solvents
Mineral Turpentine Market
Solvents
2,2-Dimethylbutyryl Chloride Market
Solvents
North America Acetonitrile Market
Solvents
Diethanolamine (DEA) Market
Solvents
Ethyl Pyruvate Market