
 Halogen-Free Flame Retardants Market | 2026-2036
Halogen-Free Flame Retardants Market Size, Share, and Industry Trends Forecast 2026-2036
Halogen-Free Flame Retardants Market Outlook
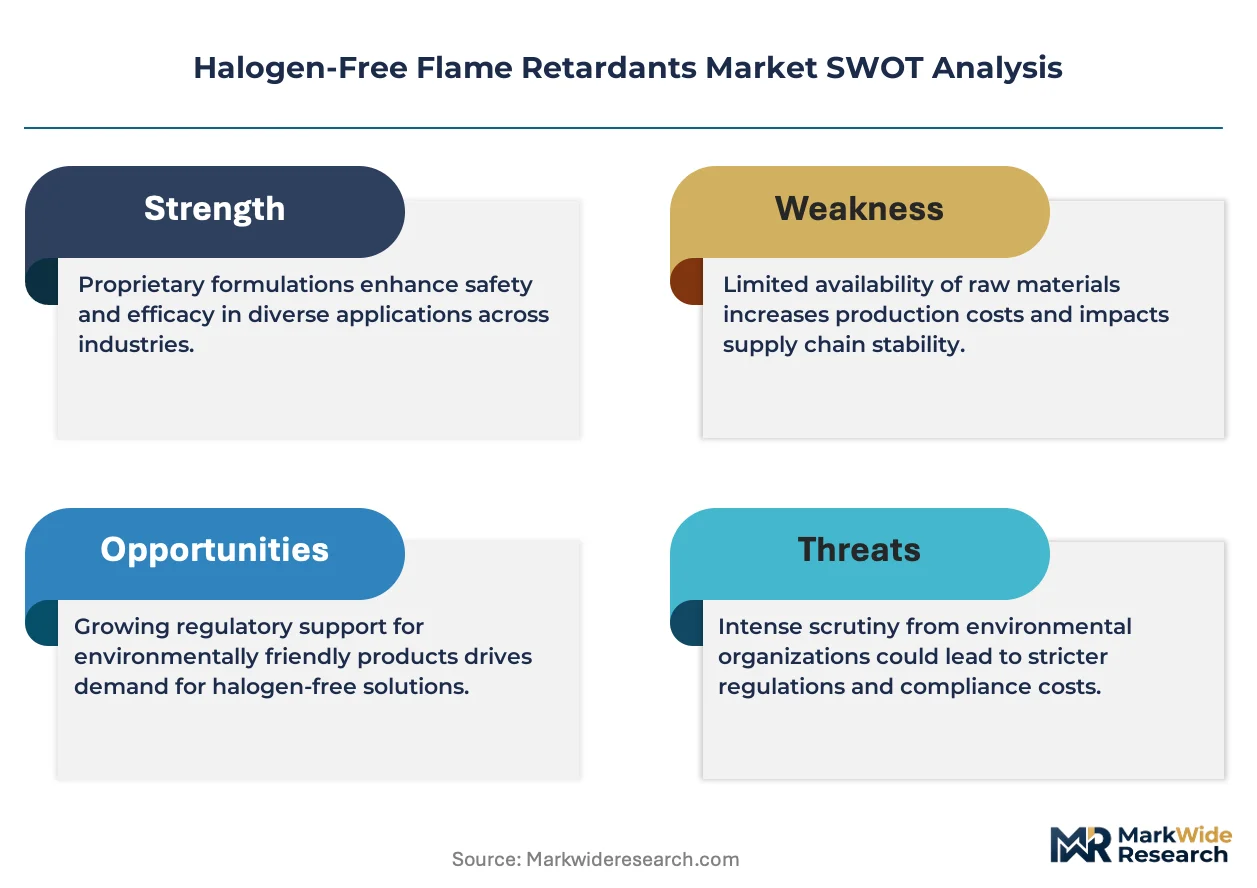
Modular formulation bundling is recalibrating how compounders specify flame retardant packages for polymer systems. Albemarle Corporation leverages its bromine heritage to pivot phosphorus-based alternatives through captive mineral sourcing. Clariant AG anchors European supply through tailored intumescent masterbatches for construction polymers. LANXESS competes on thermal stability performance in automotive underhood applications.
Halogen-free flame retardants are chemical additives formulated without chlorine or bromine, typically incorporating phosphorus, nitrogen, or mineral compounds such as aluminum or magnesium hydroxide, designed to suppress combustion through char formation, endothermic decomposition, or gas-phase radical quenching. Their primary purpose is to meet flammability standards in plastics, textiles, and coatings while avoiding corrosive smoke and toxic gas emissions associated with halogenated chemistries. Phosphorus-based formulations dominate value capture due to compatibility with engineering thermoplastics and lower loadings required for UL-94 V-0 ratings. Mineral-based grades occupy the volume tier in polyolefin wire and cable sheathing where cost sensitivity overrides performance premiums. Intumescent systems sustain the fastest expansion trajectory as building codes tighten across multiple jurisdictions for structural steel and insulation applications.
REACH restrictions on persistent organic pollutants and RoHS substance limits in electrical equipment reshape European formulation choices toward approved chemistries. EPA Significant New Use Rules and state-level flame retardant prohibitions in California and Washington direct North American product development away from legacy halogenated additives. China's GB standards and MEE enforcement on hazardous substance discharge push domestic manufacturers toward mineral and phosphorus alternatives. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification timelines for cross-border material supply.
Market Dynamics
Phosphorus-based formulations are capturing share from mineral alternatives as electrical and electronics manufacturers tighten thermal performance specifications for compact device housings and high-density circuit boards.
Growth Catalysts
- REACH substance restrictions:ECHA's persistent organic pollutant classifications are forcing compounders in Germany, France, and the Netherlands to eliminate brominated additives from construction and wire applications.
- Electric vehicle battery enclosures:Automotive OEMs specify intumescent coatings for lithium-ion pack housings to meet UN ECE R100 thermal runaway propagation standards.
- China's dual carbon targets:MEE enforcement on hazardous substance discharge accelerates domestic substitution toward aluminum hydroxide and phosphorus esters in appliance manufacturing.
Market Restraints
- Phosphorus feedstock volatility:Yellow phosphorus production concentrates in Yunnan and Guizhou provinces, exposing formulators to electricity rationing and export quota disruptions.
- Technical loading thresholds:Mineral hydroxides require 50-65% polymer loading to achieve UL-94 V-0 ratings, degrading mechanical properties in thin-wall electronics components.
- RoHS compliance friction:Legacy brominated inventory in European distribution channels creates stranded asset risk for compounders mid-reformulation.
Strategic Opportunities
- India's BIS certification expansion:Mandatory flame retardancy standards for building insulation and public transport seating create first-mover positioning for intumescent system suppliers.
- 5G infrastructure rollouts:Base station antenna housings and fiber optic cable sheathing demand phosphorus-nitrogen synergists compatible with polyamide processing temperatures.
- EU Green Deal construction renovation:Energy-efficient building retrofits require fire-safe insulation materials, expanding addressable volume for intumescent masterbatch producers.
Industry Challenges
- Formulation chemist scarcity:Phosphorus-nitrogen synergy optimization and polymer compatibility testing require specialized expertise that outpaces European and North American technical training pipelines.
- Recertification timeline compression:OEM qualification cycles for new flame retardant packages extend 18-24 months, delaying revenue recognition despite regulatory urgency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Halogen-Free Flame Retardants Market |
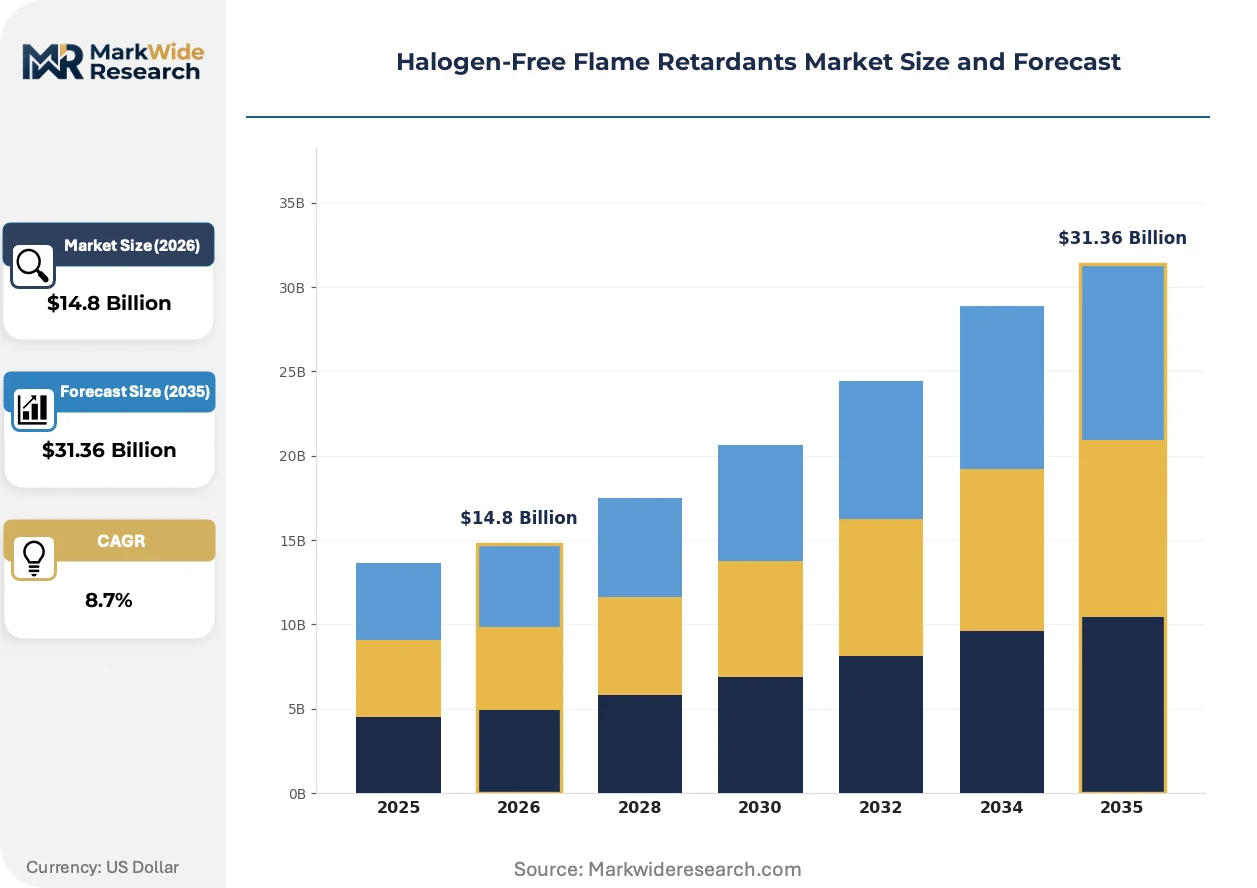
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphorus-Based, Nitrogen-Based, Mineral-Based, Intumescent Application: Building Materials, Electrical and Electronics, Textiles, Transportation End User: Construction, Automotive, Consumer Goods, Aerospace Form: Granules, Powders, Liquids, Coatings |
| Companies Covered | Albemarle Corporation, J.M. Huber Corporation, Clariant AG, Akzo Nobel N.V., Nabaltec AG, LANXESS, ICL Industrial Products, Italmatch Chemicals, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Halogen-Free Flame Retardants Market Strategic Shifts
Reactive phosphorus monomers are redefining permanence standards for flame retardant integration, while regulatory stringency fragments across jurisdictions and procurement patterns concentrate among tier-one compounders.
Microencapsulated red phosphorus is absorbing thermal stability limitations that previously restricted its use in nylon and polyester engineering resins. Automotive underhood component suppliers in Germany and Japan are qualifying these grades for charge air cooler housings and connector systems. The technology is absorbing market share from traditional ammonium polyphosphate in applications where hydrolytic resistance and color consistency command premium positioning.
EPA Significant New Use Rules on halogenated flame retardants are redirecting North American formulation development toward phosphorus and mineral chemistries. State-level prohibitions in California and Washington compound federal pressure, forcing wire and cable manufacturers to redesign sheathing compounds ahead of compliance deadlines. Electrical equipment OEMs are responding with accelerated supplier audits and dual-source qualification for halogen-free alternatives.
Specification consolidation among tier-one polymer compounders is compressing the viable supplier base for flame retardant masterbatches. Brand owners in consumer electronics and appliances now mandate pre-certified material packages, shifting technical validation burden upstream to additive suppliers. This pattern is most pronounced in South Korea and Taiwan, where original design manufacturers coordinate directly with formulation houses to lock in multi-year supply agreements.
Halogen-Free Flame Retardants Market Segmentation
Halogen-free flame retardant procurement splits between standalone additive packages and pre-compounded polymer systems. Compounders and OEMs specify differently across electrical enclosures, construction materials, and transportation components, with integration depth determining formulation complexity and qualification timelines.
Product Type:
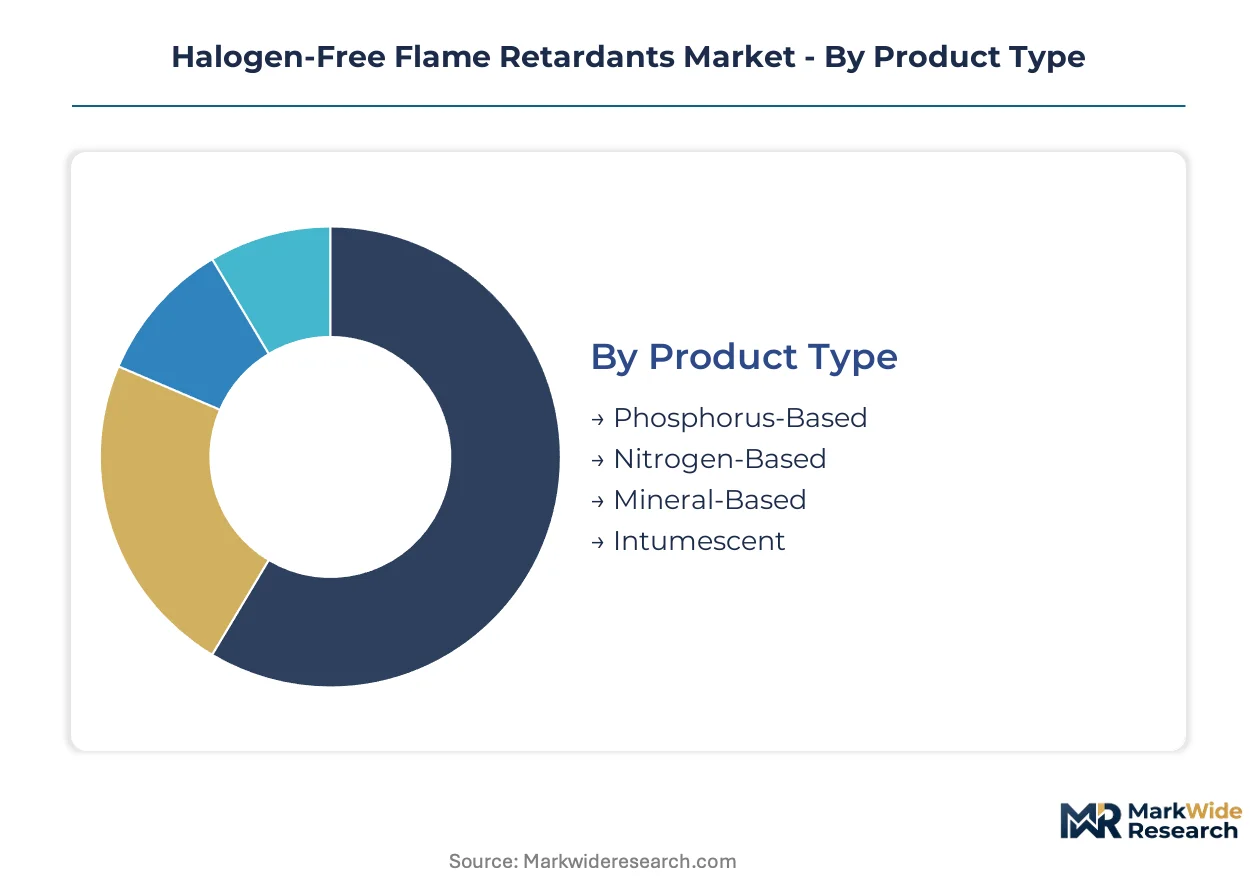
Standalone phosphorus and mineral formulations serve compounders with in-house blending capability, while intumescent and nitrogen-based systems increasingly arrive as embedded masterbatches from specialized suppliers.
- Phosphorus-Based:These formulations incorporate phosphates, phosphonates, or phosphinates that char polymer surfaces under thermal stress. Electrical and electronics manufacturers in Germany and Taiwan specify phosphorus-based grades for thin-wall device housings where low loadings preserve mechanical properties. REACH substance restrictions on brominated alternatives accelerate procurement shifts toward these chemistries in European wire and cable applications.
- Mineral-Based:Aluminum and magnesium hydroxides decompose endothermically to release water vapor and suppress combustion. Polyolefin cable sheathing producers in China favor mineral grades for cost-sensitive infrastructure projects despite the 50-65% loadings required for UL-94 V-0 compliance. MEE enforcement on hazardous substance discharge reinforces domestic substitution toward these mineral alternatives.
- Nitrogen-Based:Melamine derivatives and guanidine compounds operate through intumescent synergies and gas-phase dilution. Construction insulation formulators blend nitrogen-based additives with phosphorus sources for enhanced char stability.
- Intumescent:These systems expand under heat to form insulating foams that protect underlying substrates. Steel coating applicators and lithium-ion battery enclosure suppliers specify intumescent packages to meet escalating fire safety codes.
Volume placements concentrate in Mineral-Based grades for mass-market polyolefin applications; the faster expansion belongs to Intumescent systems for battery and construction protection.
Application:
Cost tier differentiation separates specification-intensive electrical components from commodity construction materials, with transportation applications commanding premium thermal performance validation.
- Building Materials:Structural steel coatings, insulation foams, and wood-plastic composites incorporate halogen-free retardants to satisfy EU Green Deal renovation mandates and evolving national building codes. Intumescent coatings for steel protection absorb disproportionate R&D investment as energy-efficient retrofits expand across Germany and France.
- Electrical and Electronics:Circuit board laminates, connector housings, and appliance enclosures demand phosphorus-based formulations compatible with lead-free soldering temperatures. Consumer electronics brands in South Korea and Taiwan mandate pre-certified material packages, compressing the viable supplier base for compounders serving this segment.
- Textiles:Synthetic fiber treatments for upholstery, workwear, and public transport seating rely on phosphorus-nitrogen synergists applied through padding or exhaustion processes. India's BIS certification expansion for flame-retardant seating creates qualification urgency for textile chemical suppliers.
- Transportation:Automotive underhood components, aircraft interiors, and rail vehicle materials require thermal stability beyond standard electrical grades. German automotive OEMs specify intumescent coatings for electric vehicle battery enclosures to satisfy UN ECE R100 propagation standards.
Specification density peaks in Electrical and Electronics; the steepest expansion trajectory runs through Transportation as electrification intensifies thermal management requirements.
End User:
Customer type fragmentation separates project-driven construction procurement from continuous automotive and consumer goods manufacturing, with aerospace demanding the most extensive qualification documentation.
- Construction:Insulation manufacturers, steel fabricators, and wood treatment facilities specify halogen-free retardants for structural and decorative applications. EU Green Deal construction renovation drives volume concentration in Germany, France, and the Netherlands where energy-efficient building codes tighten simultaneously.
- Automotive:Tier suppliers produce battery enclosures, interior trim, and underhood components with thermal runaway containment specifications. Electric vehicle platforms in Germany and Japan absorb increasing phosphorus-based formulation volumes as OEMs redesign pack architectures.
- Consumer Goods:Appliance housings, furniture, and electronics enclosures represent high-volume, price-sensitive demand. Original design manufacturers in Taiwan and South Korea coordinate directly with formulation houses for multi-year supply agreements.
- Aerospace:Cabin interiors, cargo liners, and electrical systems require FAR 25.853 compliance with extensive toxicity and smoke density testing. Qualification cycles extend 18-24 months, delaying revenue recognition despite regulatory urgency.
Procurement volume concentrates in Construction; margin capture peaks in Aerospace where certification barriers limit supplier participation.
Form:
Supply concentration varies by physical state, with powder handling infrastructure determining regional supply capabilities and liquid formulations serving specialized coating applicators.
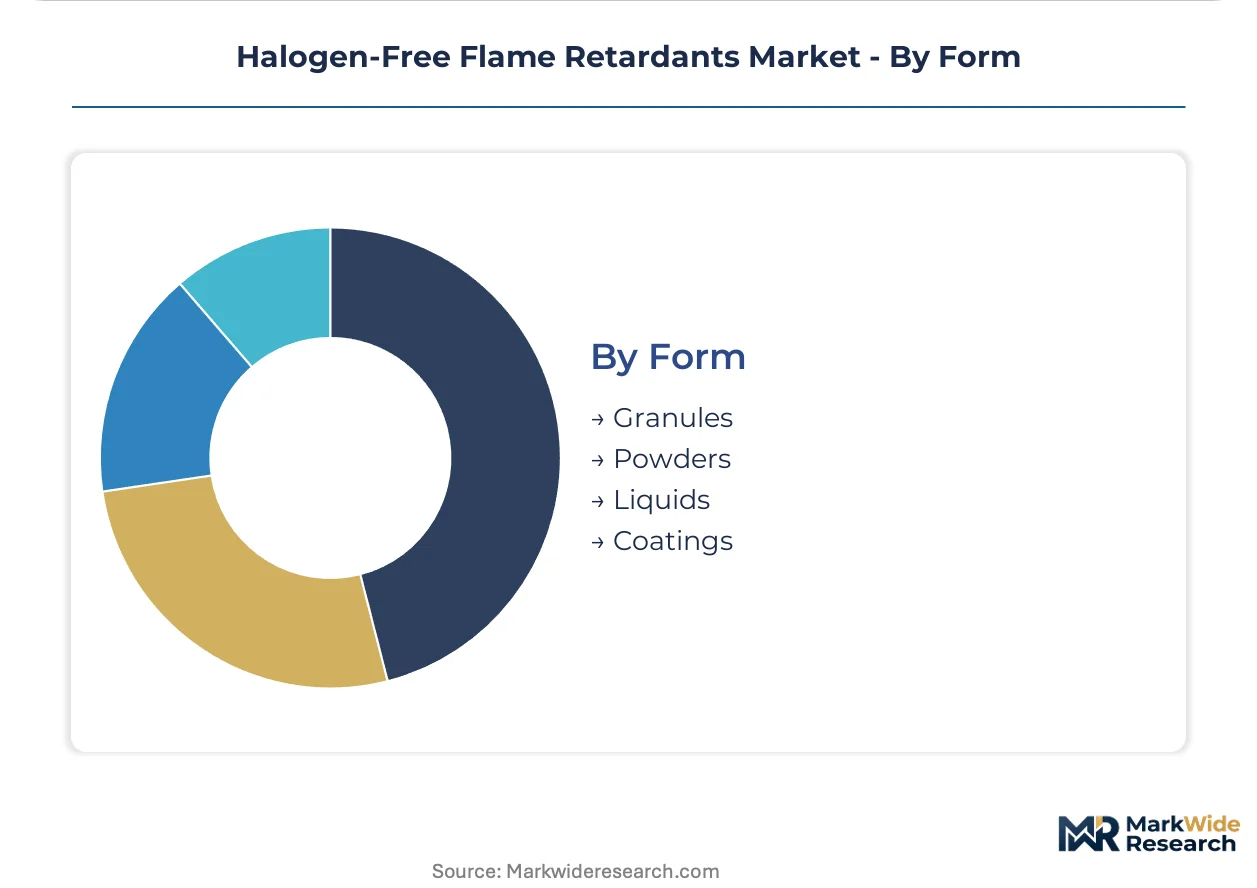
- Granules:Dust-free masterbatch pellets integrate directly into polymer compounding extruders. Major compounders in Germany and the United States prefer granule formats for automated handling and consistent dispersion.
- Powders:Fine-ground mineral hydroxides and phosphorus compounds serve PVC and polyolefin processors with established powder handling systems. Chinese cable manufacturers process aluminum hydroxide powders at scale for domestic infrastructure projects.
- Liquids:Phosphorus esters and reactive monomers enable textile padding and coating line application. Upholstery and automotive fabric treaters specify liquid formats for uniform substrate penetration.
- Coatings:Pre-formulated intumescent paints and varnishes arrive ready for steel and substrate application. Specialized applicators in Germany and France apply these coatings for EU Green Deal renovation projects.
Shipment volumes concentrate in Powders for mineral-based cable applications; the fastest share gains belong to Granules as masterbatch consolidation accelerates among tier-one compounders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones along China's eastern seaboard concentrate phosphorus refining capacity and mineral processing infrastructure, creating cost advantages for regional compounders serving electronics and construction end markets.
China
Yellow phosphorus production clusters in Yunnan and Guizhou provinces supply feedstock for phosphate ester manufacturing. MEE enforcement on hazardous substance discharge accelerates domestic substitution toward aluminum hydroxide in appliance wire sheathing. Qingdao and Shanghai port zones export mineral-based formulations to Southeast Asian cable manufacturers.
Germany
Automotive OEMs in Stuttgart and Munich specify intumescent coatings for electric vehicle battery enclosures to satisfy UN ECE R100 standards. REACH substance restrictions on brominated additives force compounders in the Ruhr industrial belt to reformulate construction polymers. BASF and LANXESS anchor European supply through captive phosphorus sourcing.
United States
EPA Significant New Use Rules redirect formulation development away from legacy halogenated chemistries in wire and cable applications. State-level prohibitions in California and Washington compress compliance timelines for electrical equipment manufacturers. Gulf Coast petrochemical corridors process mineral hydroxides for infrastructure-grade polyolefin sheathing.
India
BIS certification expansion for flame-retardant public transport seating and building insulation creates qualification urgency for textile chemical suppliers. Maharashtra and Gujarat industrial zones host compounding facilities serving domestic appliance and automotive tier suppliers. DGFT import monitoring on phosphorus derivatives shapes local sourcing strategies.
South Korea
Original design manufacturers in Seoul and Suwon coordinate directly with formulation houses for multi-year supply agreements on pre-certified material packages. Consumer electronics brands mandate UL-94 V-0 compatible phosphorus grades for compact device housings. KIS certification alignment with international flammability standards streamlines export qualification.
Halogen-Free Flame Retardants Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where scale-driven mineral processors serve commodity cable markets and targeted additive houses capture premium electronics specifications. The vendor base separates into three strategic archetypes: integrated chemical majors with captive phosphorus supply, specialized masterbatch compounders with polymer compatibility expertise, and regional mineral processors with cost-optimized hydroxide grades. Competitive moves concentrate on backward integration into phosphorus mining and strategic partnerships with tier-one polymer compounders seeking pre-qualified material packages.
Among diversified chemical majors, Albemarle Corporation and BASF SE occupy positions spanning mineral sourcing through formulated additive supply, while Clariant AG exemplifies the specialized masterbatch archetype with tailored intumescent systems for European construction polymers. LANXESS represents the performance-focused tier competing on thermal stability validation for automotive underhood applications. These three anchors illustrate how competitive positioning diverges between scale-driven commodity supply and specification-intensive premium formulation.
| Leading Market Players |
|---|
| Albemarle Corporation |
| J.M. Huber Corporation |
| Clariant AG |
| Akzo Nobel N.V. |
| Nabaltec AG |
| LANXESS |
| ICL Industrial Products |
| Italmatch Chemicals |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Performance-grade divergence between UL-94 V-0 certified phosphorus formulations and commodity mineral hydroxides manifests in pricing premiums of 40-60% for electronics-grade packages, while supply chain configurations split between captive phosphorus refiners in Yunnan and distributed aluminum hydroxide processors serving infrastructure cable markets. Buyers in automotive and aerospace segments absorb these premiums through long-term offtake contracts, whereas construction compounders optimize landed costs via regional mineral sourcing.
Pricing Analysis
Short lead-time premiums command 15-25% markups over standard contract pricing as compounders face 18-24 month OEM qualification cycles that compress inventory flexibility. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden differentiation, with UL-94 V-0 and FAR 25.853 validated grades capturing margin at the top. Pricing pressure stems from yellow phosphorus electricity rationing in Guizhou province that sporadically disrupts phosphate ester availability. Wire and cable manufacturers exhibit highest price sensitivity, while electric vehicle battery enclosure suppliers prioritize thermal performance validation over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from South Korean consumer electronics brands, while regional distributors serve mid-tier compounders across European construction markets. Production gravity centers on China for phosphorus refining and mineral hydroxide processing, with Germany and the United States anchoring formulated masterbatch supply. Raw material flows draw from Yunnan yellow phosphorus, Guizhou phosphate rock, and Australian bauxite for aluminum hydroxide feedstock. Single-source vulnerability concentrates in Chinese phosphorus derivatives subject to MEE environmental enforcement actions. Distribution runs through specialized chemical distributors in Europe and direct mill relationships in Asian electronics manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a vertical-integration race where captive phosphorus sourcing and pre-certified masterbatch capabilities determine competitive viability. Players are pursuing upstream control over mineral and phosphorus feedstocks to secure formulation cost positions against regulatory-driven demand surges.
For Market Incumbents: Lock in multi-year phosphate rock offtake agreements with Yunnan and Guizhou producers before electricity rationing intensifies. Expand granule masterbatch capacity in Germany and South Korea to capture specification consolidation among tier-one compounders. Defend against emerging Chinese mineral processors by accelerating REACH and RoHS pre-certification investments that extend qualification lead times for challengers. For New Entrants and Emerging Players: Microencapsulated red phosphorus technology offers a defensible entry path into automotive underhood and nylon engineering resin applications where hydrolytic resistance commands premium positioning. Target India's BIS certification expansion for public transport seating and building insulation as the most penetrable regulatory window. Pursue direct partnerships with Maharashtra and Gujarat compounding facilities to bypass established distributor networks. For Investors and Strategic Acquirers: Re-rating potential sits with specialized intumescent masterbatch producers given EU Green Deal renovation mandates and UN ECE R100 battery enclosure standards accelerating specification pull-through. Long-term viability over a 5-10 year horizon favors players with backward integration into phosphorus mining or captive mineral hydroxide processing. Monitor ECHA persistent organic pollutant classification announcements as the critical signal for reformulation-driven demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Mining | Captive Yunnan phosphate rock supply secures formulation cost positions against MEE enforcement volatility. |
| Intumescent Masterbatch Capacity Expansion | Dedicated European production lines capture EU Green Deal steel coating and battery enclosure demand. |
| Pre-Certified Material Package Development | UL-94 V-0 validated offerings shift technical burden upstream to additive suppliers serving South Korean electronics brands. |
| Long-Term OEM Supply Agreements | Multi-year contracts with German automotive OEMs de-risk qualification timeline compression. |
| Joint Venture with Regional Compounders | Partnerships in Maharashtra and Gujarat industrial zones establish local presence for India's BIS certification expansion. |
Study Parameters
Document review covered customs and trade data, SEC 10-K filings, ECHA substance restriction notifications, and ACC industry reports, complemented by interviews with plant managers at phosphorus refiners, procurement leads at wire and cable OEMs, technical R&D directors at masterbatch compounders, and distribution channel partners across European chemical markets. Bottom-up volume estimates triangulated against top-down regulatory impact assessments to validate demand projections.
Cross-referencing historical substitution patterns with expert panel input on reformulation timelines anchored the analytical framework across the projection horizon. Segmentation modeling incorporated grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs derived from regression analysis of patent filing trajectories, capacity expansion announcements, and OEM specification shifts. Industry-specific inputs included ECHA substance restriction calendars and UN ECE R100 adoption timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt phosphorus export quota restrictions or accelerated REACH substance bans. Periodic stress-testing of base assumptions is recommended, particularly regarding MEE enforcement intensity and OEM qualification cycle compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Lignin Products Market
Specialty Chemicals
Germany Starch Derivatives Market
Specialty Chemicals
Coconut Derived Emollients Market
Specialty Chemicals
Zinc Ricinoleate Market
Specialty Chemicals
Squalene Market
Specialty Chemicals
Esterquats Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Croscarmellose Sodium Market
Specialty Chemicals
Eitelite Market
Specialty Chemicals
Ytterbium Fluoride Market
Specialty Chemicals
North America Chromatography Resins Market
Specialty Chemicals
Cubeb Oil Market
Specialty Chemicals
Barium Sulfate Market
Specialty Chemicals
Preparative Chromatography Market
Specialty Chemicals
Tubatoxin Market