
 Specialty Oxidants Market | 2026-2036
Specialty Oxidants Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Oxidants Market Outlook
REACH chemical registration is repositioning the cost-of-entry calculus for European specialty oxidant suppliers. Lanxess leverages its integrated bromine-derivatives chain to sustain margin structures under tighter substance authorization rules. Nouryon anchors its competitive stance through electrochemical manufacturing scale across the Rhine-Ruhr corridor. Solvay differentiates via peroxygen technology leadership in electronics-grade hydrogen peroxide segments.
Specialty oxidants are high-purity or functionally enhanced chemical species with controlled active-oxygen content, typically manufactured through anthraquinone auto-oxidation, chlor-alkali electrolysis, or catalytic gas-phase processes, serving as selective electron-transfer agents in industrial oxidation, disinfection, and bleaching operations. Hydrogen peroxide dominates value generation across water treatment and electronics cleaning applications where ultralow metal-ion specifications command premium positioning. Sodium hypochlorite retains volume leadership in municipal disinfection but faces margin compression from electrochemical oxidation alternatives in advanced wastewater reuse plants. Chlorine dioxide occupies specialized niches in pulp bleaching and food-surface sanitation where trihalomethane formation must be eliminated.
EPA drinking water regulations and EU F-Gas restrictions are tightening permissible byproduct thresholds for oxidant-intensive processes, redirecting procurement toward advanced oxidation technologies that minimize residual halogenated species. FDA food-contact substance notifications and ECHA biocidal product authorization timelines extend market access barriers for new active-oxygen formulations entering North American and European jurisdictions. China's MEE discharge standards and GB water quality benchmarks are accelerating domestic substitution of imported specialty oxidants in Yangtze River basin industrial zones. Stakeholders must monitor evolving substance restriction lists and electrochemical technology cost curves to align capacity investments with shifting regulatory compliance thresholds.
Market Dynamics
Electrochemical oxidation systems are compressing legacy chlor-alkali capacity as water treatment utilities prioritize residual-free disinfection under tightening EPA and EU Drinking Water Directive standards. This technology pivot is redrawing supplier economics across the hydrogen peroxide value chain.
Growth Catalysts
- EU F-Gas Regulation phase-down:Cold-sterilization demand in pharmaceutical aseptic processing is accelerating hydrogen peroxide vapor adoption as fluorinated gas alternatives face supply constraints.
- Semiconductor fabrication expansion:South Korean and Taiwanese chip foundries are scaling electronics-grade peroxide procurement for wafer-cleaning protocols at sub-10nm nodes.
- REACH substance authorization timelines:Biocidal Product Regulation compliance deadlines are consolidating active-oxygen supplier bases toward pre-registered formulation portfolios.
Market Restraints
- Anthraquinone feedstock volatility:Quinone derivative supply interruptions from Chinese chemical parks are transmitting cost spikes to European peroxide manufacturers.
- Bromine derivatives concentration:Dead Sea and Arkansas brine operations control 70% of elemental bromine for specialty oxidant precursors, creating single-source vulnerability.
- Trihalomethane formation constraints:EPA Stage 2 Disinfectants and Disinfection Byproducts Rule limits chlorine dioxide deployment in surface-water treatment plants.
Strategic Opportunities
- On-site electrochemical generation:Containerized sodium hypochlorite and peracetic acid production units are penetrating remote mining and oilfield water treatment camps.
- India's MEE discharge enforcement:Textile and tannery clusters in Tamil Nadu and Gujarat are substituting imported oxidants with domestic electrochemical systems.
- Peracetic acid-food surface sanitation convergence:FDA Food Contact Substance notifications for no-rinse applications are opening post-harvest produce processing segments.
Industry Challenges
- Electrochemical cell engineering talent scarcity:Specialized membrane electrode assembly expertise concentrates at German and Japanese industrial gas suppliers, constraining new entrant scale-up.
- ECHA biocidal product dossier compilation:Active substance approval timelines extending beyond 36 months are freezing formulation innovation pipelines for SMEs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Oxidants Market |
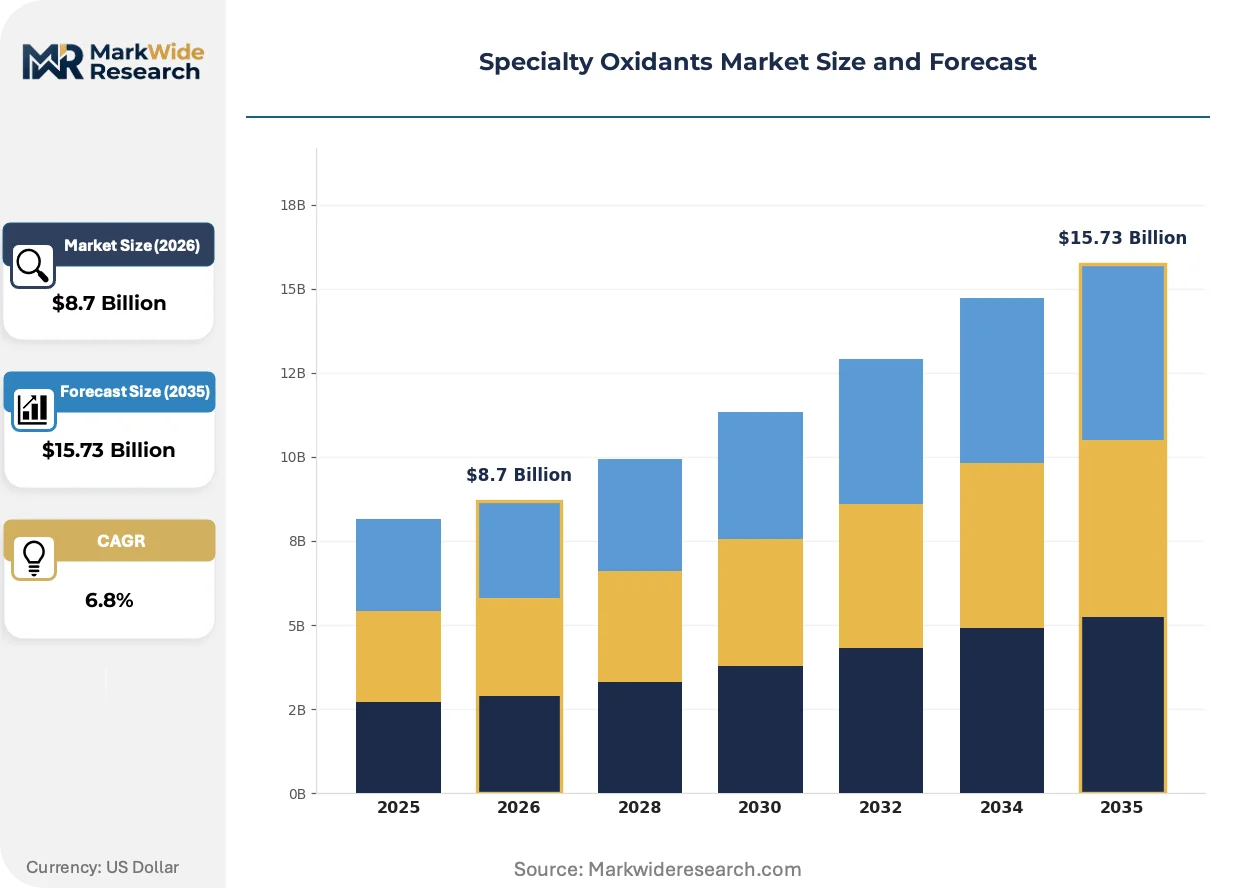
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogen Peroxide, Sodium Hypochlorite, Potassium Permanganate, Chlorine Dioxide Application: Water Treatment, Textile Processing, Pulp & Paper, Chemical Synthesis End User: Utilities, Pharmaceuticals, Agriculture, Food & Beverage Technology: Oxidative Processes, Electrochemical Oxidation, Catalytic Oxidation, Advanced Oxidation |
| Companies Covered | Lanxess, BASF, Nouryon, Solvay, Aditya Birla Chemicals, Arkema Group, Mitsubishi Gas Chemical Company, Evonik, Gujarat Alkalies and Chemicals Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Oxidants Market Strategic Shifts
Membrane-based electrochemical generation is compressing centralized chemical supply chains as distributed oxidation capacity reshapes logistics economics. This shift is accelerating capital redeployment from bulk chemical terminals toward modular skid-mounted systems.
Electrochemical advanced oxidation processes are overtaking bulk-delivered peroxide in municipal wastewater reuse facilities. California's Orange County Water District and Singapore's NEWater plants now specify on-site ozone-peroxide hybrid systems for pharmaceutical micropollutant destruction. The technology is overtaking conventional oxidation by eliminating transport costs and metal-ion contamination risks from tanker-delivered reagents.
EU F-Gas Regulation restrictions on hydrofluorocarbon propellants are forcing cold-sterilization equipment retrofits in pharmaceutical fill-finish operations. Hydrogen peroxide vapor generators are displacing ethylene oxide and steam sterilization in biologics manufacturing suites. German and Swiss contract manufacturing organizations are prioritizing peroxide-compatible isolator technology to maintain EU GMP Annex 1 compliance.
Specification-driven procurement now dominates electronics-grade oxidant sourcing as semiconductor fabs consolidate supplier audits. South Korean memory manufacturers are requiring sub-100ppt metal-ion certificates for hydrogen peroxide used in 3D NAND stringer cleaning. This behavior is compressing qualified supplier lists to three electrochemical specialists with captive ultra-purification capabilities.
Specialty Oxidants Market Segmentation
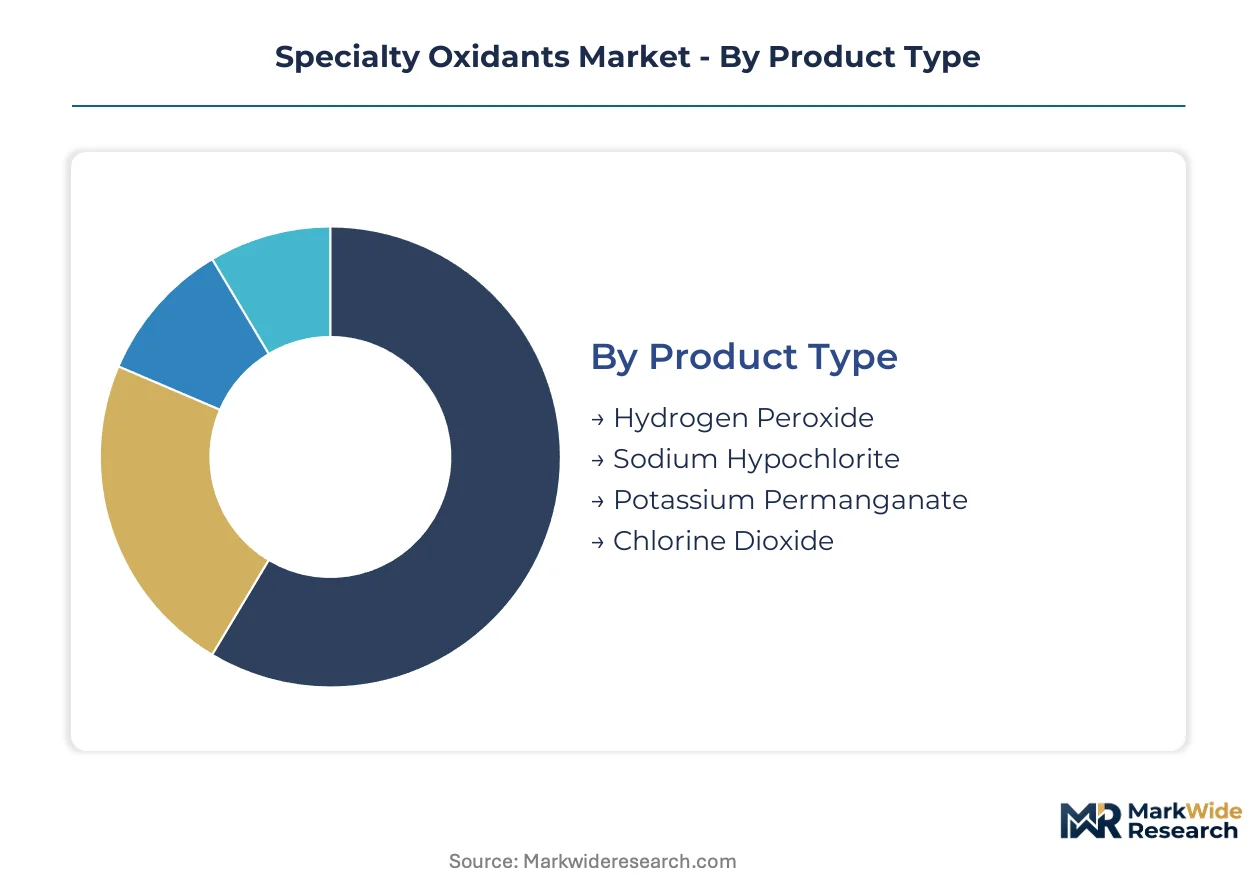
Specialty oxidant procurement splits across certification regimes that segment suppliers by purity grade and end-use authorization. Product registration timelines with EPA, ECHA, and FDA create tiered market access where electronics-grade specifications command fundamentally different supplier economics than commodity water treatment volumes.
Product Type:
Certification burdens stratify sharply: electronics-grade hydrogen peroxide demands sub-100ppt metal-ion certificates and FDA Food Contact Substance notifications, while commodity sodium hypochlorite faces lighter EPA disinfectant registration pathways. REACH substance authorization and ECHA biocidal product dossiers further segment bromine-derived oxidants from peroxygen alternatives.
- Hydrogen Peroxide:Anthraquinone auto-oxidation yields ultrapure grades with controlled active-oxygen content. South Korean semiconductor fabs in Hwaseong and Pyeongtaek concentrate demand for wafer-cleaning protocols at sub-10nm nodes where metal-ion contamination risks destroy yield. EU F-Gas Regulation phase-down accelerates vapor-phase adoption in pharmaceutical aseptic processing as fluorinated gas alternatives face supply constraints.
- Sodium Hypochlorite:Chlor-alkali electrolysis produces the volume workhorse of municipal disinfection. German and Dutch water treatment utilities under tightened EU Drinking Water Directive standards are expanding procurement, though electrochemical oxidation alternatives compress margins in advanced wastewater reuse plants.
- Potassium Permanganate:Manganese-based oxidation for specialized groundwater remediation and drinking water iron-manganese removal carries lighter registration burdens than halogenated alternatives.
- Chlorine Dioxide:Pulp bleaching and food-surface sanitation applications require EPA and EFSA approvals where trihalomethane formation must be eliminated; EPA Stage 2 Disinfectants and Disinfection Byproducts Rule constrains surface-water treatment deployment.
Leading the category by volume: Sodium Hypochlorite. Growing fastest: Hydrogen Peroxide.
Application:
Application segments diverge by customer procurement sophistication — municipal utilities negotiate long-term supply contracts while semiconductor fabs conduct multi-year supplier qualification audits.
- Water Treatment:Municipal utilities and industrial wastewater plants drive baseline demand. California's Orange County Water District and Singapore's NEWater plants specify on-site ozone-peroxide hybrid systems for pharmaceutical micropollutant destruction, eliminating transport costs and tanker-delivered reagent contamination risks.
- Textile Processing:Bleaching and dye-oxidation applications in Tamil Nadu and Gujarat clusters substitute imported oxidants with domestic electrochemical systems under India's MEE discharge enforcement.
- Pulp & Paper:Chlorine dioxide retains niche positioning in elemental chlorine-free bleaching sequences where trihalomethane formation must be eliminated.
- Chemical Synthesis:Selective oxidation reagents for fine chemical and pharmaceutical intermediate production command premium positioning based on active-oxygen specificity.
Dominant by contract value: Water Treatment. Expanding most quickly: Chemical Synthesis.
End User:
End-user segments separate by regulatory exposure — food-contact and pharmaceutical applications carry FDA and EMA compliance burdens that commodity industrial users avoid.
- Utilities:Municipal water and wastewater treatment operators under EPA and EU Drinking Water Directive standards drive volume procurement of sodium hypochlorite and hydrogen peroxide.
- Pharmaceuticals:Aseptic fill-finish operations and biologics manufacturing suites in German and Swiss contract manufacturing organizations prioritize peroxide-compatible isolator technology to maintain EU GMP Annex 1 compliance.
- Agriculture:Post-harvest produce processing and irrigation system disinfection applications are opening through FDA Food Contact Substance notifications for no-rinse peracetic acid formulations.
- Food & Beverage:Cold-sterilization equipment retrofits displace ethylene oxide and steam sterilization as EU F-Gas Regulation restricts hydrofluorocarbon propellants.
Largest procurement scale: Utilities. Steepest expansion trajectory: Pharmaceuticals.
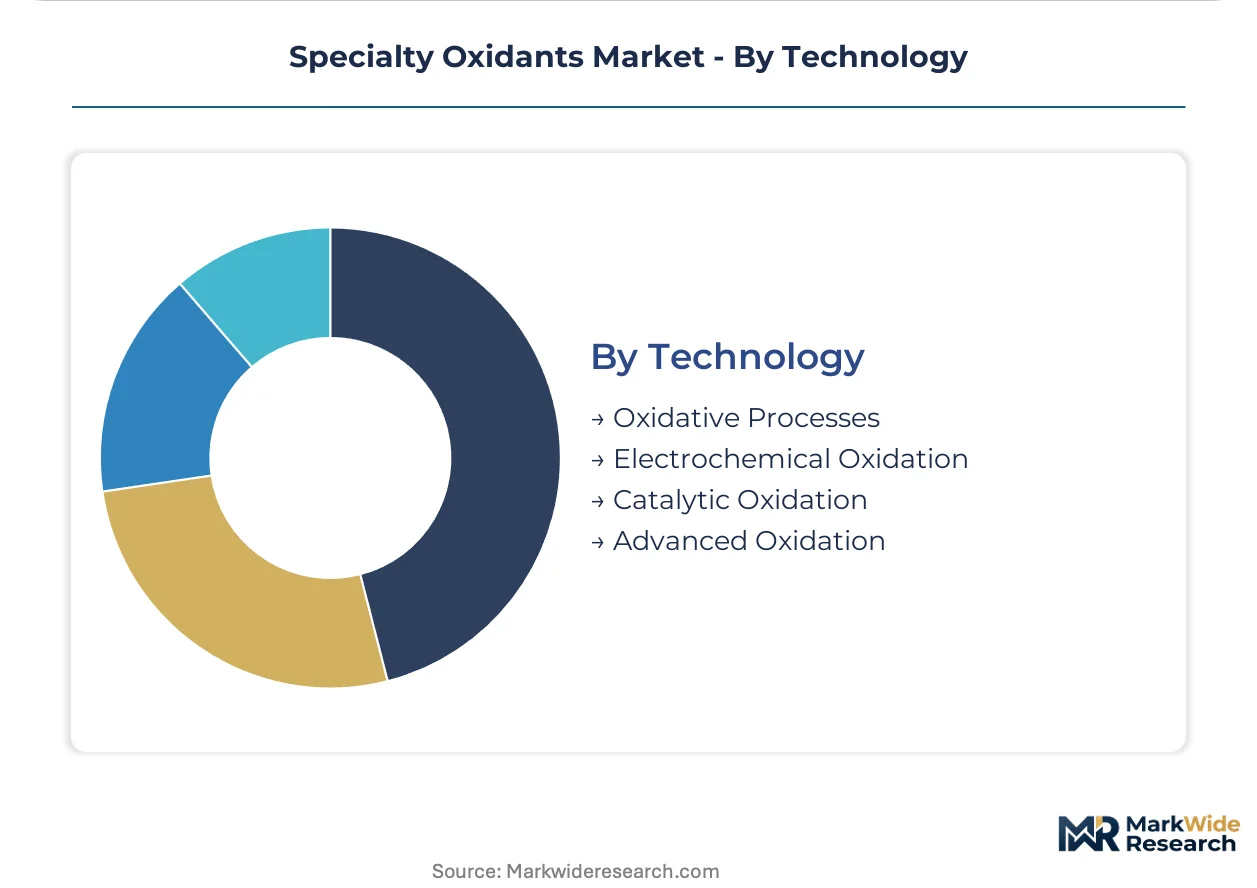
Technology:
Technology segments map to capital intensity gradients — centralized chemical manufacturing versus distributed electrochemical generation reshapes logistics economics and supplier margin structures.
- Oxidative Processes:Conventional bulk chemical delivery of hydrogen peroxide, sodium hypochlorite, and chlorine dioxide from centralized anthraquinone or chlor-alkali plants faces compression from on-site generation alternatives.
- Electrochemical Oxidation:Membrane-based systems are penetrating remote mining and oilfield water treatment camps through containerized sodium hypochlorite and peracetic acid production units. German and Japanese industrial gas suppliers concentrate specialized membrane electrode assembly expertise.
- Catalytic Oxidation:Gas-phase processes for specialty oxidant precursors depend on quinone derivative feedstocks vulnerable to supply interruptions from Chinese chemical parks.
- Advanced Oxidation:Ozone-peroxide and UV-peroxide hybrid systems for pharmaceutical micropollutant destruction in municipal wastewater reuse facilities are overtaking conventional oxidation by eliminating transport costs and metal-ion contamination risks.
Highest installed base: Oxidative Processes. Gaining share fastest: Electrochemical Oxidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hwaseong's semiconductor cluster in South Korea's Gyeonggi Province concentrates electronics-grade hydrogen peroxide demand through tax incentives for advanced node fabrication.
United States
California's Orange County Water District and Arizona's semiconductor fabs drive dual demand streams. EPA Stage 2 Disinfectants and Disinfection Byproducts Rule constrains chlorine dioxide deployment. Houston's petrochemical corridor sustains anthraquinone-based peroxide production for Gulf Coast industrial consumers.
Germany
Rhine-Ruhr electrochemical manufacturing scales serve Dutch and domestic water utilities under tightened EU Drinking Water Directive standards. REACH substance authorization timelines consolidate active-oxygen supplier bases. Leverkusen's integrated chemical parks anchor bromine-derivative oxidation capacity for European pulp and pharmaceutical clients.
China
Yangtze River basin industrial zones accelerate domestic substitution of imported specialty oxidants under MEE discharge standards. GB water quality benchmarks tighten permissible byproduct thresholds for oxidation-intensive processes. Shanghai's chemical parks concentrate quinone derivative production despite intermittent supply interruptions.
South Korea
Pyeongtaek and Hwaseong semiconductor fabrication centers scale electronics-grade peroxide procurement for sub-10nm wafer-cleaning protocols. MFDS pharmaceutical regulations accelerate hydrogen peroxide vapor adoption in aseptic fill-finish operations. Busan's port infrastructure supports tanker-delivered reagent logistics for memory manufacturers.
India
Tamil Nadu and Gujarat textile clusters substitute imported oxidants with domestic electrochemical systems under MEE discharge enforcement. BIS certification requirements extend market access timelines for foreign formulation suppliers. Ankleshwar's chemical hub develops captive peracetic acid capacity for food-surface sanitation applications.
Specialty Oxidants Market Competitive Environment
German producers anchor one tier; South Korean and Japanese specialists hold electronics-grade purification capabilities. The supplier base stratifies across three tiers: integrated bromine-derivative chains, electrochemical scale operators, and regional formulation blenders. Strategic moves concentrate on backward integration into anthraquinone feedstocks and membrane electrode assembly technology licensing.
Within the integrated chemical conglomerate tier, Lanxess and BASF exemplify European producers leveraging captive bromine and peroxygen technology positions. Nouryon occupies a distinct archetype as an electrochemical manufacturing scale specialist across the Rhine-Ruhr corridor. These three represent divergent strategic postures under REACH compliance pressure.
| Leading Market Players |
|---|
| Lanxess |
| BASF |
| Nouryon |
| Solvay |
| Aditya Birla Chemicals |
| Arkema Group |
| Mitsubishi Gas Chemical Company |
| Evonik |
| Gujarat Alkalies and Chemicals Ltd |
| Others |
Value Chain & Pricing Dynamics
Electronics-grade versus commodity-grade bifurcation creates parallel pricing universes where sub-100ppt metal-ion certificates command order-of-magnitude premiums over municipal water treatment volumes, and this divergence manifests in supply chains through dedicated ultra-purification assets versus shared bulk chemical terminals.
Pricing Analysis
Short lead-time premiums dominate contract structures for South Korean semiconductor fabs requiring just-in-time peroxide delivery, while spot inventory discounts attract price-sensitive Indian textile processors. Contract-based long-term offtake anchors utility procurement, with price differentiation driven by certification grade and volume scale. Cost compression in commodity sodium hypochlorite intensifies because electrochemical oxidation alternatives eliminate transport economics. Municipal utilities exhibit highest price sensitivity; pharmaceutical aseptic processors show least.
Supply Chain Analysis
Qualification gating through REACH substance authorization and FDA Food Contact Substance notifications restricts qualified supplier lists to pre-registered formulation portfolios. Geographic supply concentrates in Germany, China, and South Korea. Anthraquinone derivatives, elemental bromine, and membrane electrode assemblies constitute critical input dependencies. Single-source vulnerability runs through Dead Sea and Arkansas brine operations controlling elemental bromine. Distribution runs through regional chemical terminals and containerized on-site generation units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
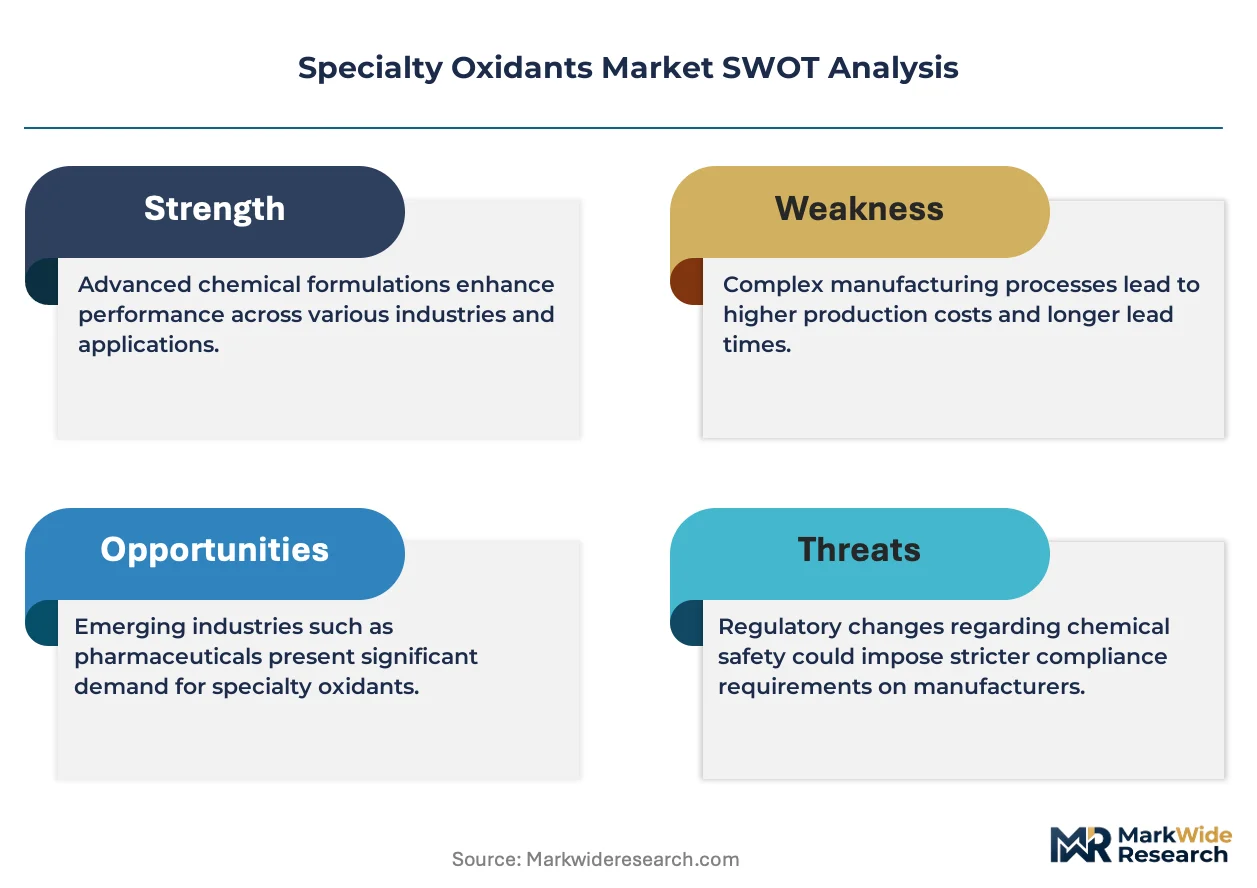
REACH substance authorization timelines erect a cost-of-compliance moat that consolidates active-oxygen supplier bases toward pre-registered formulation portfolios, freezing out SMEs and rewarding early regulatory investment.
For Market Incumbents: Anticipate margin compression from electrochemical oxidation alternatives by securing captive anthraquinone feedstock positions and deepening membrane electrode assembly expertise. Backward integration into quinone derivatives defends against Chinese chemical park supply interruptions. Electrochemical manufacturing scale across the Rhine-Ruhr corridor anchors European market position. For New Entrants and Emerging Players: India's MEE discharge enforcement in Tamil Nadu and Gujarat textile clusters opens a window for containerized on-site generation units serving remote mining and oilfield camps. Domestic electrochemical systems substitution creates the most penetrable white-space. Partner with German or Japanese membrane electrode assembly technology licensors to accelerate qualification timelines. For Investors and Strategic Acquirers: Re-rating potential sits with electrochemical scale specialists given semiconductor fabrication expansion and EU F-Gas Regulation phase-down accelerating hydrogen peroxide vapor adoption. Long-term viability favors operators with captive ultra-purification capabilities and pre-registered REACH portfolios. Monitor ECHA biocidal product authorization timelines as inflection indicator for formulation innovation pipeline thaw.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Anthraquinone Feedstocks | Captive supply of quinone derivatives insulates European peroxide manufacturers from Chinese chemical park interruptions. |
| Membrane Electrode Assembly Technology Licensing | German and Japanese industrial gas suppliers concentrate specialized expertise that constrains new entrant scale-up. |
| Electronics-Grade Ultra-Purification Capacity Addition | Sub-100ppt metal-ion certificates qualify suppliers for South Korean 3D NAND stringer cleaning procurement. |
| Containerized On-Site Generation Deployment | Modular skid-mounted systems penetrate remote mining camps and eliminate tanker-delivered reagent contamination risks. |
| REACH Pre-Registration Portfolio Investment | Biocidal Product Regulation compliance deadlines consolidate active-oxygen supplier bases toward authorized formulation portfolios. |
Study Parameters
Document review covered SEC 10-K filings, ECHA substance authorization databases, customs and trade data, and semiconductor industry capex disclosures, complemented by interviews with plant managers at specialty oxidant manufacturers, procurement leads at South Korean memory fabs, water utility technical directors, and pharmaceutical regulatory affairs specialists. Bottom-up demand modeling triangulated against top-down industry association data from ACC and Cefic.
Output metrics span product type, application, end user, and technology segments across the projection horizon, with CAGRs derived from regression analysis against semiconductor node migration rates and water treatment capital expenditure cycles. Electrochemical technology cost curves and REACH authorization timeline probabilities served as key forecast inputs.
The model assumes a particular electrochemical oxidation adoption path; alternative pathways for membrane-based on-site generation would alter the outlook for centralized chemical supply chains. Forecasts reflect assumptions about EU Drinking Water Directive enforcement intensity and Chinese MEE discharge standard implementation. A model refresh is warranted upon material change in ECHA biocidal product authorization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Hydroxyproline Market
Specialty Chemicals
Shikimic Acid Market
Specialty Chemicals
Cyclomethicone Market
Specialty Chemicals
Fatty Alcohol Alkoxylates Market
Specialty Chemicals
Ricinoleic Acid Market
Specialty Chemicals
Bio-Based Aromatics Market
Specialty Chemicals
Ferrous Gluconate Market
Specialty Chemicals
VCI Aerosol Market
Specialty Chemicals
US Post Laser Recovery Products Market
Specialty Chemicals
Sandarac Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
Propyl Isovalerate Market
Specialty Chemicals
Multimodal Chromatography Columns Market
Specialty Chemicals
Micronized PTFE Market
Specialty Chemicals
Washable Marker Market
Specialty Chemicals
Niacin and Niacinamide Market