
 Natural Insect Repellent Market | 2026-2036
Natural Insect Repellent Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Insect Repellent Market Outlook
The gap between premium botanical formulations and commodity citronella offerings is shifting as ingredient transparency becomes a decisive purchase criterion. Wondercide LLC leverages USDA-certified organic supply chains to anchor its position in the premium tier. Spectrum Brands Holdings, Inc. competes through mass retail distribution density and household brand recognition. Murphy's Naturals, Inc. differentiates by specializing in American-manufactured, plant-based oil blends with explicit active ingredient disclosure.
Natural insect repellents are topical formulations that utilize plant-derived volatile oils—typically citronella, eucalyptus, or lavender at concentrations between 5% and 30%—to interfere with arthropod olfactory receptors, manufactured through cold-press extraction or steam distillation followed by emulsification. Their primary commercial purpose is to provide personal protection against mosquitoes, ticks, and biting flies without synthetic neurotoxic actives. Sprays dominate volume due to application convenience and dose consistency, while oils capture premium margin pools through perceived purity and extended duration claims. DEET-Free positioning now leads active ingredient marketing, though eucalyptus-based formulations represent the fastest-growing chemistry subset as travelers seek CDC-recognized alternatives.
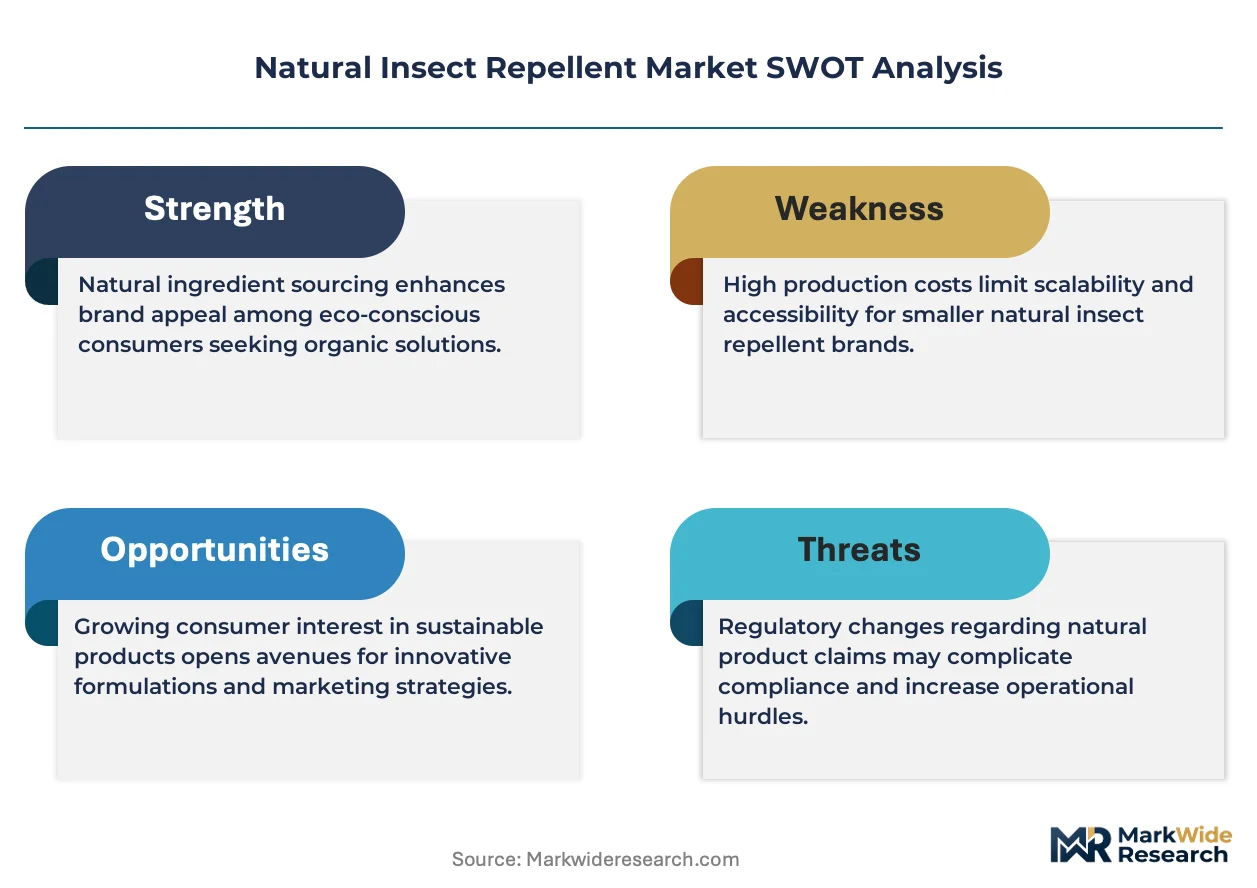
EPA regulates natural repellents under FIFRA, requiring efficacy data and label claims substantiation that shapes product development timelines and market access costs. USDA organic certification and state-level restrictions on synthetic pesticide use in public spaces reinforce demand for botanical alternatives. Stakeholders must monitor evolving EPA guidance on minimum risk pesticide exemptions and state preemption conflicts that could reshape formulation strategies and channel eligibility.
Market Dynamics
EPA registration requirements under FIFRA for botanical active ingredients are compressing product development timelines and raising capital barriers for new entrants, reshaping competitive positioning toward vertically integrated suppliers with captive testing infrastructure.
Growth Catalysts
- FIFRA efficacy mandates:EPA registration requirements for plant-derived actives are filtering out undercapitalized competitors and concentrating market share among established formulators with dedicated toxicology teams.
- Outdoor recreation expansion:Camping and hiking participation surges are pulling DEET-free repellent demand through specialty retail channels and direct-to-consumer platforms.
- State-level synthetic restrictions:Municipal bans on conventional pesticides in public parks and school grounds are mandating botanical alternatives for grounds maintenance contracts.
Market Restraints
- Active ingredient cost volatility:Cold-pressed citronella oil prices fluctuate with Indonesian and Sri Lankan harvest cycles, compressing margin predictability for mid-tier brands.
- Duration-performance gap:Botanical formulations require reapplication every 2-4 hours versus 8-12 hours for synthetic alternatives, limiting adoption in military and expedition use cases.
- Supply concentration risk:Steam distillation capacity for eucalyptus and lemongrass oils clusters in Southeast Asian processing facilities vulnerable to climate disruption.
Strategic Opportunities
- Travel retail expansion:Airport duty-free channels in Singapore, Dubai, and Frankfurt are capturing premium eucalyptus-based formulations targeting international travelers seeking CDC-recognized alternatives.
- Subscription commerce models:Direct-to-consumer auto-replenishment programs are locking in household purchase frequency and reducing customer acquisition costs for emerging brands.
- Veterinary application crossovers:Equine and companion animal repellent formulations represent adjacent demand pools with lower regulatory barriers than human topical products.
Industry Challenges
- Formulation chemist scarcity:Expertise in plant oil emulsification and stability testing is concentrated among legacy personal care specialists, constraining R&D velocity for new entrants.
- Label claim substantiation timelines:EPA review cycles for efficacy data extend 18-24 months, freezing capital in inventory and delaying revenue recognition for reformulated products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Insect Repellent Market |
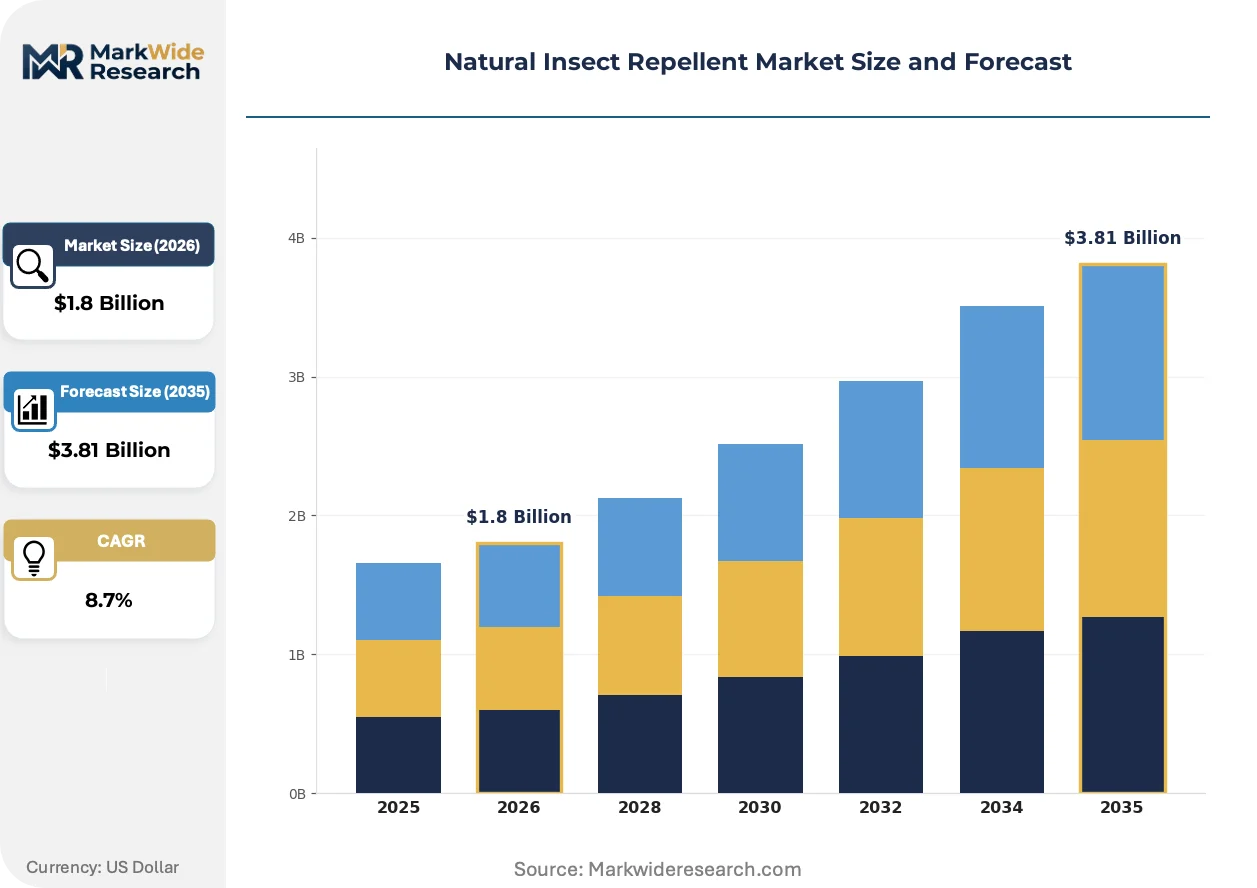
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprays, Creams, Oils, Wipes Active Ingredient: Citronella, DEET-Free, Lavender, Eucalyptus Application: Outdoor Use, Indoor Use, Gardening, Camping Consumer Type: Families, Outdoor Enthusiasts, Travelers, Eco-Conscious Users |
| Companies Covered | The Procter & Gamble Company, EARTHLEY, Wondercide LLC, Spectrum Brands Holdings, Inc., 3 Moms Organics LLC, The Coleman Company, Inc., Quantum Health, Inc., Murphy’s Naturals, Inc., W.S. Badger Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Insect Repellent Market Strategic Shifts
Ingredient transparency requirements and performance verification demands are converging to reshape product architecture, with formulation science and packaging innovation racing to meet evolving buyer expectations.
Encapsulated essential oil delivery systems are overtaking conventional spray formats in premium positioning. These microsphere technologies extend volatile oil release from 2 hours to 6-8 hours. Outdoor outfitters and international travelers are adopting them at accelerating rates. This technology is compressing the performance gap with synthetic actives while commanding 40-60% price premiums over standard botanical sprays.
REACH registration requirements for biocidal products in the European Union are forcing reformulation of citronella-based products sold across member states. The regulation's efficacy and safety data requirements have eliminated several legacy suppliers from the EU market. German and French formulators are responding by consolidating testing resources through shared toxicology consortia to defray compliance costs.
Ingredient disclosure preferences are shifting purchase authority toward parents of young children and pet owners seeking explicit active concentration labeling. Amazon and specialty outdoor retailers are capturing this demand through filterable search attributes and third-party certification badges. This pattern is most visible in United States coastal metropolitan markets where organic purchasing indices exceed national baselines.
Natural Insect Repellent Market Segmentation
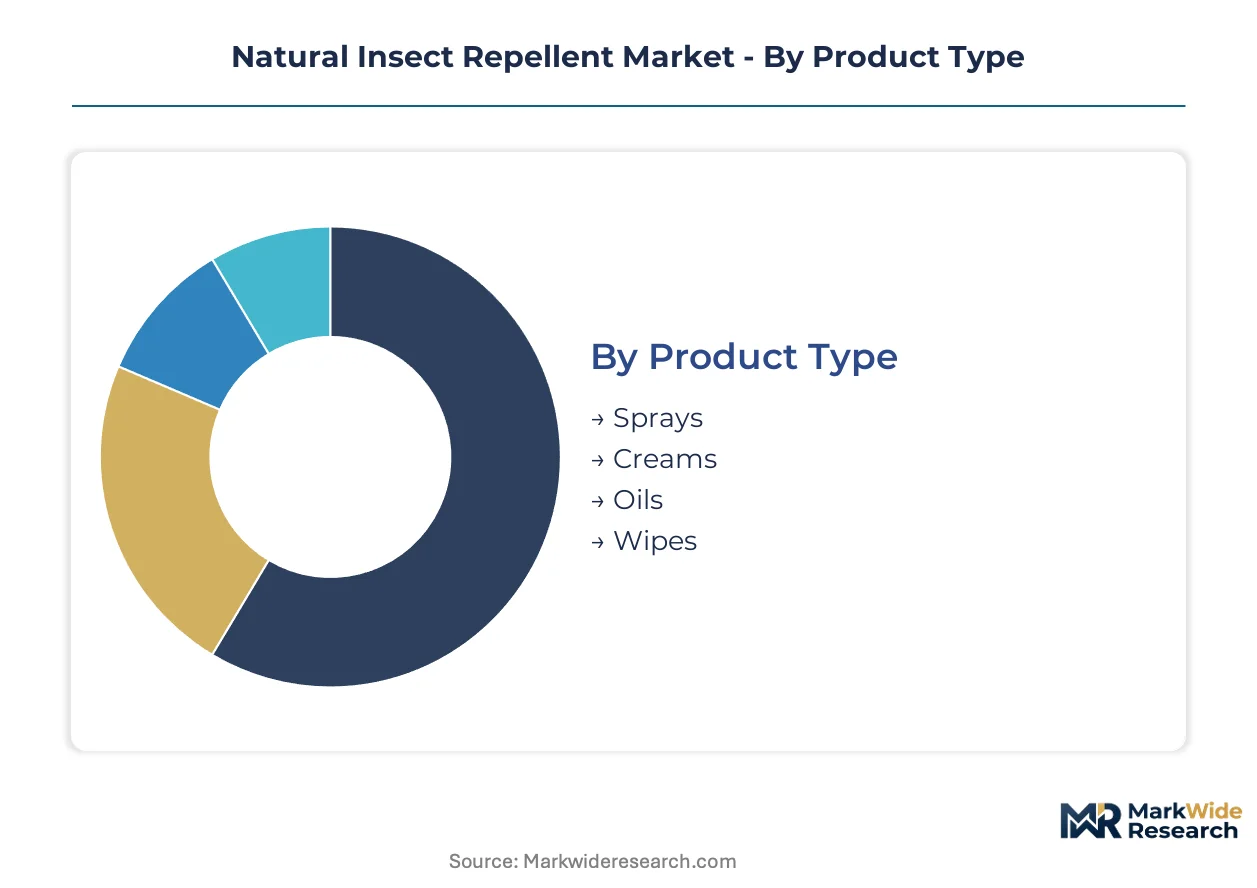
Product architecture in natural insect repellents reflects divergent user rituals and performance expectations. Purchase patterns split between convenience-driven formats and purity-seeking applications, with active ingredient chemistry and use context further stratifying commercial opportunity.
Product Type:
Upgrade cycles accelerate as consumers trade up from basic formats to extended-release technologies and targeted delivery systems.
- Sprays:Pump and aerosol dispensers dominate household penetration due to rapid coverage and dose metering precision. Demand clusters in suburban United States markets where families prioritize application speed for backyard activities. EPA registration requirements for pressurized formulations sustain barriers against private-label entrants lacking dedicated compliance infrastructure.
- Oils:Roll-on and dropper formats capture premium positioning through perceived concentration purity and skin-conditioning adjacencies. Outdoor enthusiasts in Colorado and Pacific Northwest hiking corridors drive adoption, willing to accept reapplication frequency in exchange for ingredient minimalism and portable packaging.
- Creams:Emulsion-based formats offer controlled spread and localized protection for targeted body areas. Pediatric applications in Florida and Texas metropolitan zones sustain volume.
- Wipes:Single-use sachets address TSA-compliant travel needs and gym bag portability. Airport retail in Atlanta and Dallas-Fort Worth hubs moves significant volume.
Volume placements concentrate in Sprays; the faster expansion belongs to Oils.
Active Ingredient:
Cost tiers separate commodity botanicals from certified-organic supply chains and clinically validated alternatives.
- DEET-Free:Positioning as synthetic-active avoidance anchors mainstream marketing, encompassing diverse botanical bases under unified clean-label positioning. Mass retail channels in California and New York metropolitan areas stock these formulations as default alternatives, with shelf placement often adjacent to conventional repellents to capture comparison shoppers.
- Eucalyptus:Oil of Lemon Eucalyptus (OLE) and synthetic PMD variants command traveler loyalty through CDC recognition for disease-endemic destinations. International departure terminals in Miami and Houston generate disproportionate sales velocity for TSA-sized formats.
- Citronella:Legacy botanical active faces margin compression from Indonesian supply volatility and duration limitations relative to newer chemistries. Budget-tier positioning persists in seasonal retail.
- Lavender:Dual-purpose positioning as insect deterrent and aromatherapy ingredient drives gift-set bundling and wellness channel placement. Boutique hospitality amenities in Santa Fe and Sedona feature these formulations.
Commercial gravity sits with DEET-Free positioning; the steepest expansion trajectory belongs to Eucalyptus.
Application:
Customer type and use intensity determine repurchase frequency and format preferences across residential and recreational contexts.
- Outdoor Use:Backyard entertaining and patio dining occasions drive consistent replenishment cycles in temperate-climate suburbs. Mosquito pressure in Minnesota and Wisconsin lake regions sustains seasonal demand spikes.
- Camping:Multi-day wilderness exposure demands higher-concentration formulations with extended duration claims. Specialty retailers in Denver and Portland serve this segment with technical product education.
- Indoor Use:Screened-porch and bedroom applications favor low-odor, fast-drying formats. Urban apartment dwellers in Chicago and Philadelphia purchase smaller package sizes.
- Gardening:Extended sun-and-soil exposure combines with tick concern in Northeast and Mid-Atlantic states. Co-merchandising with sun care and first aid categories lifts basket size.
Volume concentrates in Outdoor Use; Camping gains share fastest through specialty channel expansion.
Consumer Type:
Margin profiles diverge between price-sensitive household stock-up purchasing and values-driven premium acquisition.
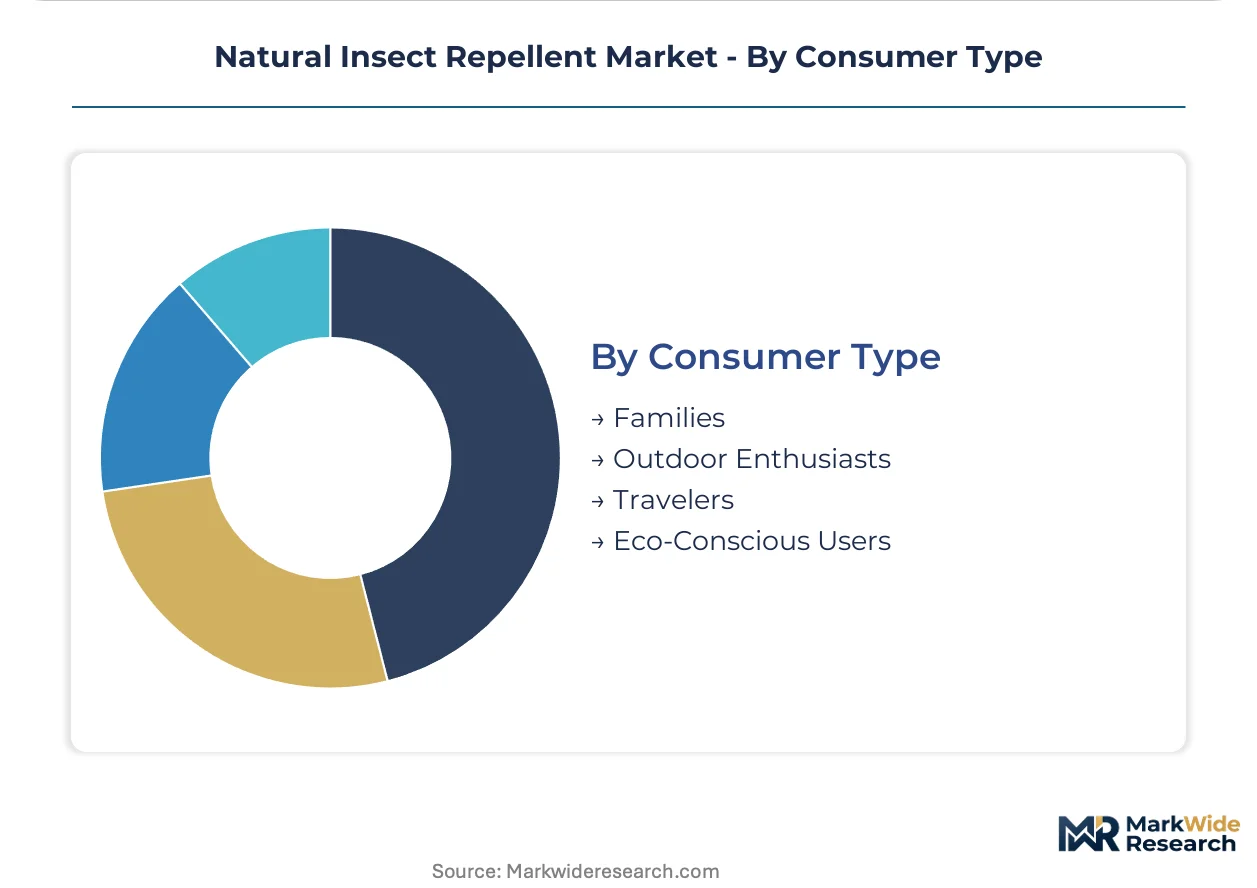
- Families:Multi-person households with children under twelve drive bulk purchasing and subscription adoption, prioritizing pediatrician-recommended ingredient profiles. School district pesticide policies in Maryland and Connecticut municipalities reinforce botanical preferences.
- Eco-Conscious Users:Certification-driven purchasers demand USDA Organic and Leaping Bunny verification, accepting substantial price premiums for supply chain transparency. Coastal metropolitan markets in Seattle and San Francisco over-index on these attributes.
- Outdoor Enthusiasts:Technical performance requirements and pack-weight constraints shape format selection for hiking, fishing, and hunting applications. Regional outfitter chains in Montana and Idaho cultivate brand loyalty through staff expertise.
- Travelers:Destination-specific disease risk awareness and airline liquid restrictions drive compact-format purchasing in airport and hotel retail. Cruise embarkation ports in Fort Lauderdale and Galveston generate concentrated demand.
Volume placements concentrate in Families; Eco-Conscious Users climb the fastest on certification premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Atlanta's Hartsfield-Jackson International Airport anchors travel-retail velocity for compact botanical repellent formats, while suburban backyard demand concentrates in temperate-climate corridors across four distinct national markets.
United States
Suburban families in Minnesota and Wisconsin lake regions drive seasonal replenishment cycles for backyard entertaining. EPA registration requirements under FIFRA filter out undercapitalized entrants, concentrating market share among established formulators with dedicated toxicology teams. The Denver-Boulder corridor hosts specialty outdoor retailers serving technical camping segments with higher-concentration formulations.
Germany
REACH registration requirements for biocidal products have eliminated several legacy citronella suppliers from the EU market. German formulators respond by consolidating testing resources through shared toxicology consortia to defray compliance costs. The Frankfurt airport duty-free channel captures premium eucalyptus-based formulations targeting international travelers.
France
Parisian metropolitan consumers over-index on certification-driven purchasing, demanding explicit USDA Organic and Leaping Bunny verification. ANSM and CNIL oversight of cosmetic-biocide hybrids shapes product architecture for dual-purpose lavender formulations. The Provence-Alpes-Côte d'Azur region supplies raw botanical materials while hosting boutique hospitality amenities featuring aromatherapy-positioned repellents.
United Kingdom
London's coastal metropolitan markets exceed national baselines for organic purchasing indices, driving filterable search attributes on Amazon and specialty outdoor platforms. The country's national pesticide regulator enforces efficacy data requirements that extend product development timelines. Scotland's Highlands corridor supports outdoor enthusiast segments willing to accept reapplication frequency for ingredient minimalism.
Australia
Queensland and New South Wales metropolitan zones sustain pediatric applications for emulsion-based formats with controlled spread characteristics. TGA oversight of therapeutic goods classifications creates regulatory overlap with cosmetic positioning for plant-derived actives. Sydney's airport retail captures outbound traveler demand for CDC-recognized alternatives to tropical disease-endemic destinations.
Natural Insect Repellent Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification tier and distribution density, with USDA-certified organic supply chains commanding substantial price premiums over standard botanical bases. The vendor base organizes around three strategic archetypes: mass retail distributors leveraging household brand recognition, specialty formulators emphasizing American manufacturing and ingredient transparency, and vertically integrated suppliers with captive testing infrastructure. Dominant competitive moves include subscription commerce models locking in household purchase frequency and travel retail expansion capturing premium positioning in airport duty-free channels.
Within the specialty-formulator tier, Wondercide LLC anchors premium positioning through organic supply chain credentials, while Murphy's Naturals, Inc. exemplifies the American-manufactured transparency archetype with explicit active ingredient disclosure. Spectrum Brands Holdings, Inc. occupies the mass-retail density position, competing through shelf placement adjacency to conventional repellents in California and New York metropolitan markets.
| Leading Market Players |
|---|
| The Procter & Gamble Company |
| EARTHLEY |
| Wondercide LLC |
| Spectrum Brands Holdings, Inc. |
| 3 Moms Organics LLC |
| The Coleman Company, Inc. |
| Quantum Health, Inc. |
| Murphy's Naturals, Inc. |
| W.S. Badger Company |
| Others |
Value Chain & Pricing Dynamics
Cold-pressed citronella oil spot prices from Indonesian and Sri Lankan commodity exchanges cascade through formulation tiers, compressing margins for mid-tier brands while amplifying premium capture for USDA-certified organic supply chains with long-term grower contracts.
Pricing Analysis
Duration-based performance anchors value capture, with encapsulated essential oil delivery systems commanding 40-60% premiums over standard sprays by extending protection from 2 hours to 6-8 hours. Three-tier pricing structure separates premium organic-certified formulations from standard botanical blends and commodity citronella offerings. Cost compression in the mid-tier intensifies as Indonesian harvest volatility feeds raw material uncertainty. Families with children under twelve show highest price sensitivity, while eco-conscious coastal metropolitan buyers accept substantial premiums for supply chain transparency.
Supply Chain Analysis
Reverse-logistics infrastructure remains underdeveloped for natural insect repellents, with limited refill programs and packaging take-back schemes constraining circular economy positioning. Steam distillation capacity for eucalyptus and lemongrass oils clusters in Indonesia, Sri Lanka, and Vietnam, drawing from cold-press extraction and steam distillation equipment networks. Raw material dependencies center on citronella grass, oil of lemon eucalyptus, and lavender biomass. Single-source vulnerability in Southeast Asian processing facilities exposed to monsoon disruption threatens supply continuity. Distribution runs through mass retail chains, specialty outdoor outfitters, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA registration requirements under FIFRA are compressing product development timelines and raising capital barriers, forcing undercapitalized competitors toward exit or acquisition by established formulators with captive toxicology infrastructure.
For Market Incumbents: Acquire dedicated toxicology testing assets to compress EPA review cycles and lock out emerging competitors lacking 18-24 month capital endurance. Consolidate backward integration into Indonesian and Sri Lankan cold-press extraction facilities to secure citronella supply against harvest volatility. Defend against subscription-commerce entrants by locking household purchase frequency through auto-replenishment programs with pediatrician endorsement partnerships. For New Entrants and Emerging Players: REACH registration requirements in the European Union open a window for German and French formulators consolidating testing resources through shared toxicology consortia. White-space targets concentrate in veterinary application crossovers for equine and companion animal formulations with lower regulatory barriers than human topical products. Airport duty-free channels in Singapore, Dubai, and Frankfurt represent the most penetrable geography for premium eucalyptus-based CDC-recognized alternatives. Go-to-market execution should emphasize TSA-compliant compact formats with explicit active ingredient disclosure for international travelers. For Investors and Strategic Acquirers: The window for entry favors vertically integrated suppliers with captive testing infrastructure and USDA-certified organic supply chain credentials. Long-term viability hinges on consolidation of mid-tier brands facing margin compression from raw material volatility and EPA compliance cost escalation. Acquisition target archetype: specialty formulators with American-manufactured positioning and explicit ingredient transparency protocols. Monitor EPA guidance evolution on minimum risk pesticide exemptions and state preemption conflicts as inflection indicators for formulation strategy pivot requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulated Essential Oil Technology Licensing | Microsphere delivery systems compress the performance gap with synthetic actives while sustaining 40-60% price premiums in premium channels. |
| Subscription Commerce Model Launch | Auto-replenishment programs reduce customer acquisition costs and lock in household purchase frequency against mass retail competitors. |
| USDA Organic Certification Investment | Organic supply chain credentials anchor premium tier positioning and command substantial price premiums in coastal metropolitan markets. |
| Airport Duty-Free Channel Expansion | Singapore, Dubai, and Frankfurt terminals capture outbound traveler demand for CDC-recognized alternatives to disease-endemic destinations. |
| Veterinary Formulation Crossover Development | Equine and companion animal repellents access adjacent demand pools with lower regulatory barriers than human topical EPA registrations. |
Study Parameters
Independent corroboration across EPA registration databases, USDA organic certification records, and customs trade data underwrites the qualitative findings. Primary interviews with formulation chemists, regulatory affairs specialists at FIFRA-registered establishments, specialty outdoor retail category buyers, and botanical oil procurement managers combined with secondary validation from FIFRA Section 3 registration filings, state-level pesticide restriction databases, and Nielsen retail audit data. Bottom-up segment sizing and top-down market triangulation cross-validated volume and value estimates.
Rate-of-change decomposition across product type, active ingredient chemistry, application context, and consumer archetype segments structured the analytical framework. CAGRs were derived from segment-level growth trajectory modeling and reconciliation with macro-level market expansion. Forecast inputs incorporated EPA review cycle timelines for efficacy data, Indonesian and Sri Lankan citronella harvest yield projections, and outdoor recreation participation indices across temperate-climate corridors.
The model assumes a particular technology adoption path; alternative pathways for encapsulated microsphere delivery systems would alter the outlook if cost curves compress faster than projected. Forecasts reflect assumptions about FIFRA regulatory stability and Southeast Asian climate patterns. Practitioners should monitor EPA guidance on minimum risk pesticide exemptions, REACH biocidal product registration evolution in the European Union, and Indonesian agricultural policy shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Stearates Market
Specialty Chemicals
Stearyl Alcohol Market
Specialty Chemicals
US Post Laser Recovery Products Market
Specialty Chemicals
Sodium Hyaluronate Market
Specialty Chemicals
Global Prepacked Chromatography Columns Market
Specialty Chemicals
Cellulose Derivatives Market
Specialty Chemicals
Bio-Wax Market
Specialty Chemicals
Marine Hyaluronic Acid Market
Specialty Chemicals
Global Chitin Market
Specialty Chemicals
Global Immersion Oil Market
Specialty Chemicals
Fabric Softener and Conditioner Market
Specialty Chemicals
Europe Non-Phthalate Plasticizers Market
Specialty Chemicals
Dipentene (Limonene) Market
Specialty Chemicals
Global Spray Polyurethanes Foam Market
Specialty Chemicals
Ethyl Cellulose Market
Specialty Chemicals
Multimodal Chromatography Columns Market