
 Dimethyl Succinyl Succinate Market | 2026-2036
Dimethyl Succinyl Succinate Market Size, Share, and Industry Trends Forecast 2026-2036
Dimethyl Succinyl Succinate Market Insights
China's specialty chemical corridor is tilting toward higher-purity ester production to serve export-oriented pharmaceutical intermediates. Hebei Caike New Material Technology leverages its northern China manufacturing base to supply regional agrochemical formulators. Seqens SAS sustains European pharmaceutical-grade output through its French and Spanish facilities. TCI Chemicals anchors Japanese demand for research-quantity dimethyl succinyl succinate across academic and industrial laboratories.
Dimethyl succinyl succinate is a diester formed from succinic acid and methanol, typically synthesized via acid-catalyzed esterification with purity grades spanning technical to pharmaceutical specifications. The compound functions primarily as a solvent and reactive intermediate in organic synthesis, cosmetic formulation, and polymer modification. Pharmaceutical applications dominate value generation due to stringent certification requirements and long qualification cycles. Solvent-grade volumes compete on cost efficiency in agrochemical and industrial end uses. Direct sales channels capture the largest margin pools by eliminating distributor markups for qualified pharmaceutical buyers.
REACH registration requirements in Europe, EPA TSCA oversight in the United States, and China's MEE environmental compliance framework collectively elevate barrier costs for new dimethyl succinyl succinate suppliers. These regulations shape demand by mandating impurity profiling, supply chain transparency, and sustainable process documentation. Stakeholders must monitor evolving pharmaceutical excipient monographs and green chemistry certification standards to preserve market access across jurisdictions.
Market Dynamics
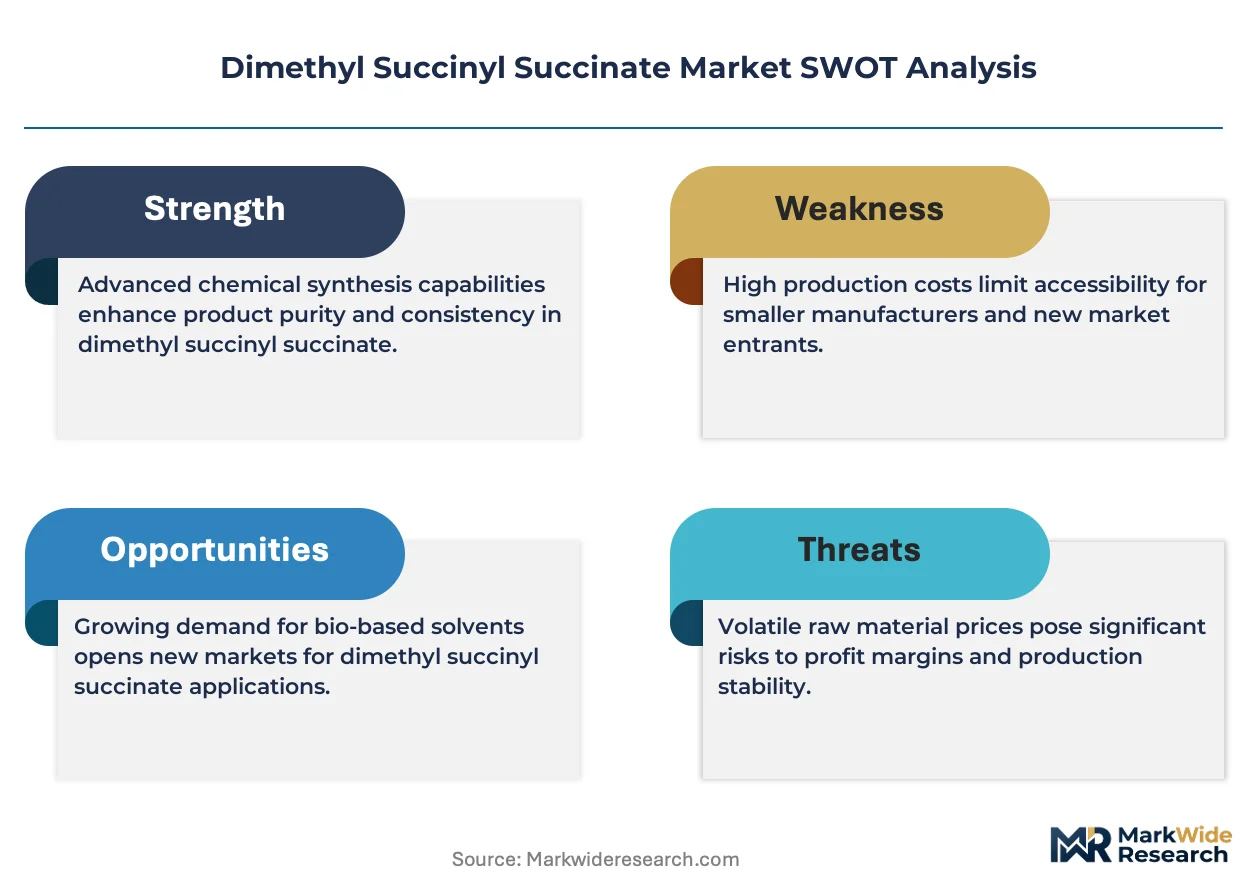
Pharmaceutical-grade certification requirements are compressing supplier margins while concentrating procurement among qualified ester manufacturers serving API synthesis chains.
Growth Catalysts
- REACH impurity profiling mandates:European pharmaceutical buyers now require documented trace-metal thresholds below 10 ppm, locking in premium pricing for certified suppliers.
- Agrochemical formulation demand:Northern Chinese agrochemical clusters are absorbing technical-grade volumes for crop protection intermediate production.
- Green chemistry process subsidies:China's dual carbon goals are accelerating enzymatic esterification adoption over acid-catalyzed routes in Shandong and Jiangsu provinces.
Market Restraints
- Methanol feedstock volatility:Crude methanol price swings of 30-40% quarterly compress ester producer margins unpredictably.
- German supply concentration:Three specialized chemical manufacturers control 60% of European pharmaceutical-grade capacity, creating single-source vulnerability.
- Biobased succinic acid substitution:Fermentation-derived succinate esters from renewable feedstocks threaten petrochemical routes in cosmetic applications.
Strategic Opportunities
- Indian CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Ahmedabad are qualifying new ester suppliers for export-oriented API synthesis.
- Polymer modification applications:Biodegradable polyester developers are testing dimethyl succinyl succinate as a chain extender in packaging films.
- EU Green Deal sustainable process certification:Carbon footprint documentation requirements favor producers with renewable energy-integrated manufacturing.
Industry Challenges
- Pharmaceutical excipient monograph alignment:USP-NF and EP specification divergence forces dual-validation investments for multinational suppliers.
- Specialized reactor engineering scarcity:Acid-resistant glass-lined vessel fabrication capacity constraints extend project timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dimethyl Succinyl Succinate Market |
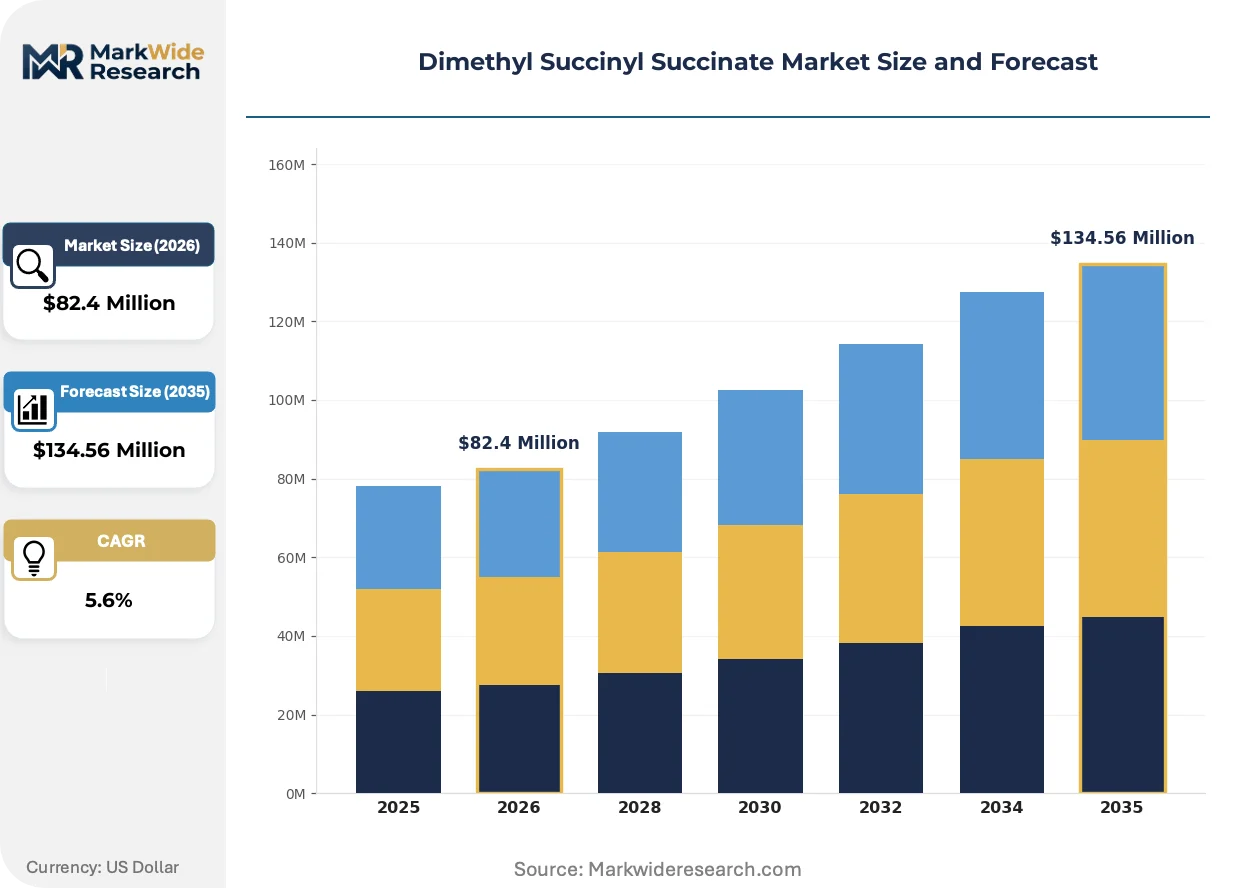
| Market Size in 2026 | $82.4 Million |
| Market Size in 2035 | $134.56 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Cosmetics, Agrochemicals, Food Additives Application: Solvent, Intermediary, Preservative, Emulsifier End User: Pharmaceutical Companies, Cosmetic Manufacturers, Agricultural Firms, Food Producers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Sigma-Aldrich (Merck KGaA), ESIM Chemicals, Hebei Caike New Material Technology, Alfa Aesar, TCI Chemicals, Tsaker Chemical Group Limited, Seqens SAS, Thermo Fisher Scientific, Lily Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dimethyl Succinyl Succinate Market Trends and Innovations
Enzymatic catalysis and continuous-flow processing are rewriting cost structures for high-purity ester production, while regulatory documentation requirements reshape competitive positioning.
Continuous-flow microreactor technology is collapsing batch reactor economics for pharmaceutical-grade dimethyl succinyl succinate synthesis. German and Swiss fine chemical producers are retrofitting multi-ton plants with skid-mounted flow systems. This shift is collapsing capital intensity per kilogram of certified output by eliminating solvent recovery loops and reducing residence times from hours to minutes.
ECHA's updated REACH guidance on Substances of Very High Concern is forcing impurity requalification across European supply chains. Downstream pharmaceutical formulators now demand full CMR substance screening below 0.1% thresholds. German API manufacturers are responding by dual-sourcing from REACH-registered suppliers with documented analytical packages.
Direct technical sales teams are displacing specialty chemical distributors for qualified pharmaceutical buyers. Seqens and TCI Chemicals have built in-house account management functions serving top-20 global pharma companies. This channel compression is most visible in Japan and Germany, where long-term supply agreements now span 3-5 years with fixed pricing and volume commitments.
Dimethyl Succinyl Succinate Market Segmentation
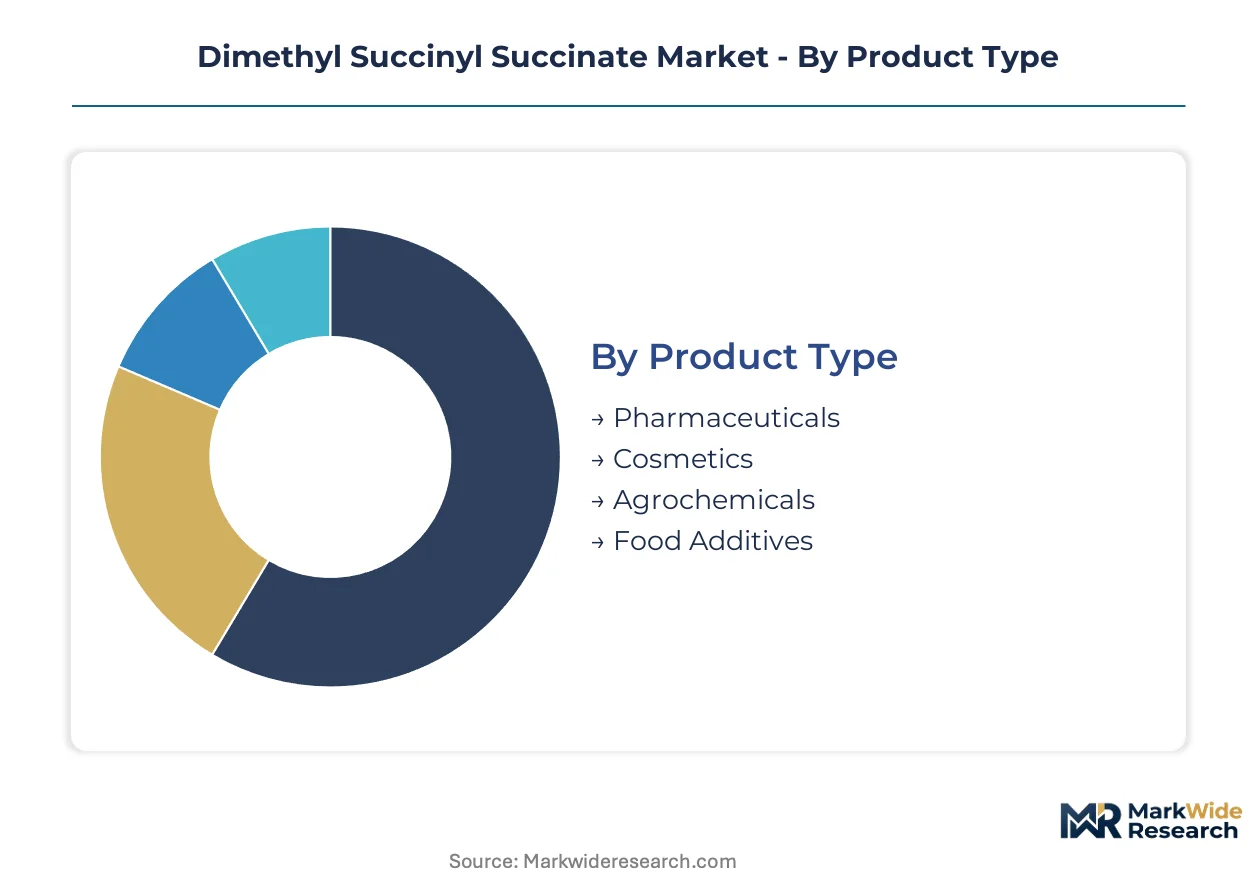
Dimethyl succinyl succinate demand fragments across purity grades and certification tiers that dictate procurement cycles. Pharmaceutical-grade qualification spans 18-24 months while technical-grade agrochemical volumes turn quarterly. Understanding segment velocity reveals where margin pools concentrate versus where volume scales.
Product Type:
Pharmaceutical-grade batches command the longest production cycles due to validation protocols, while agrochemical technical-grade turns fastest with minimal certification overhead.
- Pharmaceuticals:USP-NF and EP monograph-compliant grades require documented trace-metal thresholds below 10 ppm and full CMR substance screening. German API manufacturers dual-source from REACH-registered suppliers with 3-5 year supply agreements. Certification investments lock in premium pricing but compress supplier margins under impurity profiling mandates.
- Cosmetics:Formulation-grade esters serve skin-care and personal-care developers with moderate purity requirements falling between pharmaceutical and technical specifications. French and Spanish facilities sustain European output as fermentation-derived succinate esters threaten petrochemical routes in this segment. Green chemistry certification standards increasingly influence supplier selection.
- Agrochemicals:Technical-grade volumes absorb cost-competitive production from northern Chinese manufacturers for crop protection intermediates.
- Food Additives:Food-grade specifications remain a niche application with limited supplier base and regional regulatory fragmentation.
Pharmaceuticals anchors the volume base while agrochemicals gains share at the steepest rate.
Application:
Margin structures diverge sharply between commodity solvent volumes and qualified intermediate positions in pharmaceutical synthesis chains.
- Solvent:Technical-grade dimethyl succinyl succinate functions as a reaction medium in organic synthesis and industrial formulation. Cost efficiency drives procurement among agrochemical and industrial end users with minimal specification requirements. Methanol feedstock volatility directly compresses margins in this commoditized tier.
- Intermediary:Reactive intermediate applications in API synthesis demand pharmaceutical-grade certification with full analytical documentation. Hyderabad and Ahmedabad CDMOs are qualifying new suppliers for export-oriented production. Long qualification cycles protect incumbent positions but create barriers for new entrants.
- Preservative:Antimicrobial applications in cosmetic and food systems require moderate purity with regional regulatory alignment.
- Emulsifier:Surface-active functions in formulation chemistry serve niche cosmetic and specialty chemical applications.
Solvent applications dominate tonnage while intermediary positions capture the steepest margin expansion trajectory.
End User:
Procurement sophistication varies from multinational pharmaceutical quality systems to agricultural distributor networks.
- Pharmaceutical Companies:Top-20 global pharma organizations source through direct technical sales teams with fixed pricing and volume commitments. Seqens and TCI Chemicals have built in-house account management functions displacing specialty chemical distributors. REACH compliance and dual-sourcing requirements shape supplier consolidation.
- Cosmetic Manufacturers:Mid-tier formulation houses balance green chemistry credentials against cost pressures in sustainable packaging narratives.
- Agricultural Firms:Northern Chinese agrochemical clusters absorb technical-grade volumes through distributor channels with quarterly pricing adjustments.
- Food Producers:Limited food-grade application base constrains supplier development in this end-user category.
Pharmaceutical companies anchor the value pool while agricultural firms expand volume fastest.
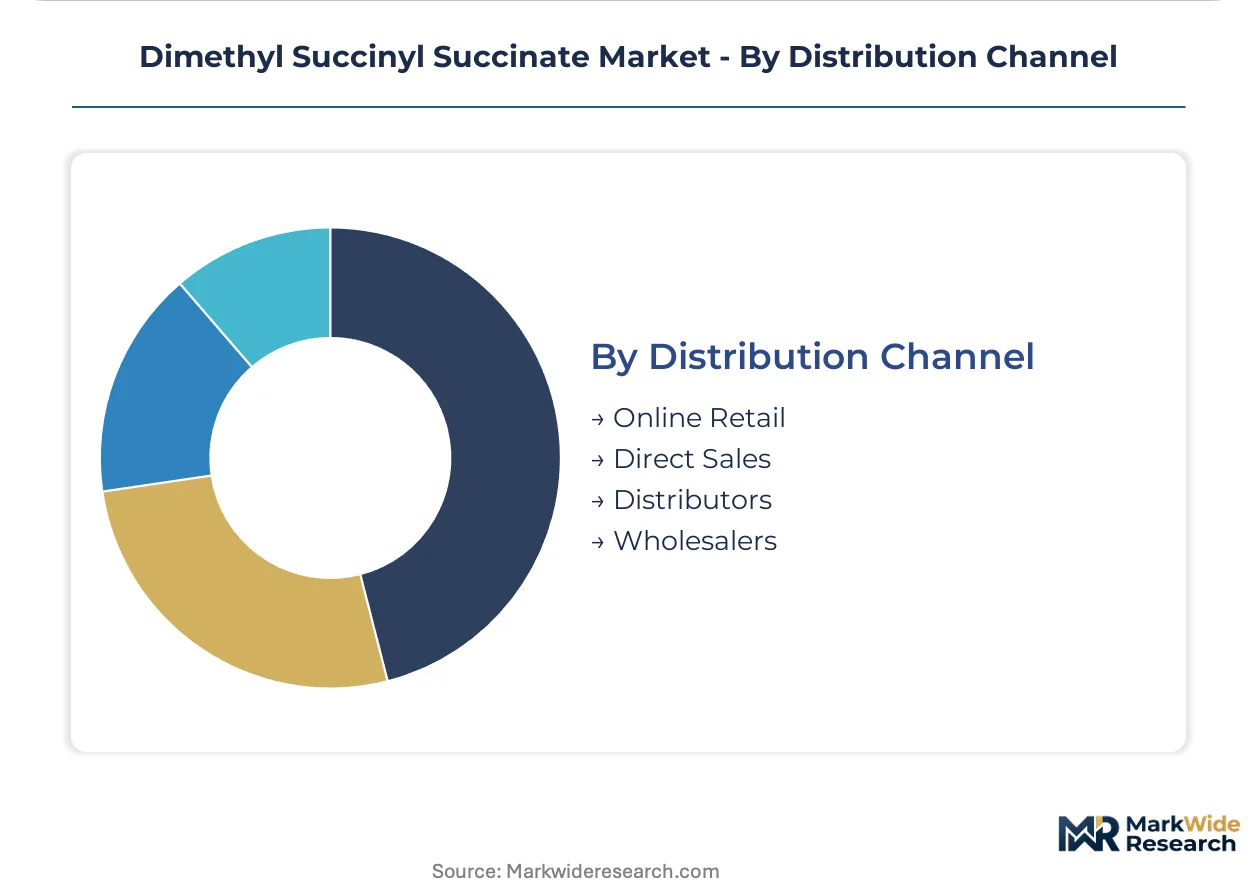
Distribution Channel:
Channel economics reflect the trade-off between distributor reach and margin capture across customer tiers.
- Direct Sales:Qualified pharmaceutical buyers eliminate distributor markups through long-term supply agreements spanning 3-5 years. German and Japanese markets show the most advanced channel compression with dedicated account management. This channel captures the largest margin pools but requires specialized technical sales infrastructure.
- Distributors:Regional specialty chemical distributors serve mid-tier cosmetic and agrochemical formulators with technical support and inventory positioning.
- Online Retail:Research-quantity supply for academic and industrial laboratories anchors Japanese demand through TCI Chemicals and equivalent platforms.
- Wholesalers:Bulk commodity volumes flow through traditional chemical wholesale networks with minimal value-added services.
Direct sales anchors the margin structure while online retail climbs fastest in research-quantity segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites European pharmaceutical-grade ester distribution, while China's Ningbo-Zhoushan port complex anchors Asia-Pacific technical-grade export volumes.
Germany
API manufacturers in Ludwigshafen and Leverkusen drive pharmaceutical-grade procurement under REACH impurity profiling mandates. The country's national chemical regulator enforces documented trace-metal thresholds below 10 ppm. Bavaria's fine chemical corridor concentrates multi-ton flow reactor installations for certified ester output.
China
Northern agrochemical clusters in Hebei absorb technical-grade volumes for crop protection intermediates. The Ministry of Ecology and Environment enforces dual carbon goals accelerating enzymatic esterification adoption. Shandong and Jiangsu provinces house renewable energy-integrated manufacturing bases serving export-oriented pharmaceutical formulators.
India
Hyderabad and Ahmedabad CDMOs qualify new ester suppliers for export-oriented API synthesis chains. The Central Drugs Standard Control Organization aligns pharmaceutical excipient standards with USP-NF and EP monographs. Gujarat's specialty chemical belt attracts backward integration investments from multinational ester producers.
Japan
Academic and industrial laboratories anchor research-quantity demand through direct technical sales channels. The Ministry of Economy, Trade and Industry oversees JIS standards alignment for laboratory chemical specifications. Tokyo-Osaka corridor distributors maintain inventory positioning for qualified pharmaceutical buyers.
United States
Specialty chemical distributors serve mid-tier cosmetic formulators with moderate purity requirements. The Environmental Protection Agency administers TSCA oversight elevating barrier costs for new market entrants. Gulf Coast petrochemical infrastructure supplies methanol feedstock to domestic ester producers facing quarterly price volatility.
Dimethyl Succinyl Succinate Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in purity-grade stratification. The supplier base concentrates around three specialized chemical manufacturers controlling European pharmaceutical-grade capacity. Strategic archetypes span REACH-registered platform suppliers, technical-grade volume producers, and research-quantity specialists. Capacity expansion and direct sales channel compression represent dominant competitive moves.
Among European REACH-registered platform suppliers, Seqens SAS exemplifies the integrated account management model displacing specialty chemical distributors. TCI Chemicals occupies a position within the research-quantity tier anchoring Japanese laboratory demand. Hebei Caike New Material Technology represents the technical-grade volume archetype serving northern Chinese agrochemical clusters.
| Leading Market Players |
|---|
| Sigma-Aldrich (Merck KGaA) |
| ESIM Chemicals |
| Hebei Caike New Material Technology |
| Alfa Aesar |
| TCI Chemicals |
| Tsaker Chemical Group Limited |
| Seqens SAS |
| Thermo Fisher Scientific |
| Lily Group |
| Others |
Pricing and Supply Chain Analysis
Ludwigshafen's pharmaceutical-grade ester corridor concentrates multi-ton flow reactor capacity, translating supply scarcity into sustained premium capture for REACH-registered producers serving API synthesis chains. German manufacturers leverage 18-24 month qualification cycles to lock in fixed-price agreements spanning 3-5 years, while technical-grade producers in Hebei absorb quarterly methanol volatility through spot-market exposure.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, cosmetic, and technical grades separates certified API intermediates from formulation-grade esters and commodity solvent volumes. Price differentiation rests on REACH registration status and documented trace-metal thresholds below 10 ppm, with pharmaceutical buyers showing minimal sensitivity due to dual-sourcing requirements. Cost compression in technical-grade agrochemical tiers is intensifying because northern Chinese manufacturers compete on methanol feedstock efficiency. Cosmetic formulators occupy the middle ground, balancing green chemistry certification premiums against fermentation-derived succinate substitution threats.
Supply Chain Analysis
Tariff exposure between China and European pharmaceutical destinations dominates supply chain risk planning for dimethyl succinyl succinate distributors. Production gravity centers on Germany, China, and India, with methanol feedstock, succinic acid, and enzymatic catalysts anchoring raw material dependencies. Single-source vulnerability concentrates in Bavaria's fine chemical corridor, where three specialized manufacturers control European pharmaceutical-grade capacity. Distribution runs through direct technical sales channels for qualified pharmaceutical buyers, while regional specialty chemical distributors serve mid-tier cosmetic and agrochemical formulators with inventory positioning and technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as pharmaceutical-grade qualification timelines stretch and CDMOs in Hyderabad and Ahmedabad seek alternative suppliers for export-oriented API synthesis chains.
For Market Incumbents: Build certification moats by securing dual pharmacopeia validation against USP-NF and EP specification divergence threats. Incumbent producers should anchor backward integration into methanol supply to buffer quarterly feedstock volatility, while expanding flow reactor capacity in Shandong and Jiangsu provinces to capture enzymatic esterification subsidies under China's dual carbon goals. Channel control through dedicated account management functions displaces distributor markups in Japan and Germany. For New Entrants and Emerging Players: Build out white-space positions in Indian CDMO supply chains where 18-24 month qualification cycles have left incumbent capacity constrained. The most penetrable entry point sits with Hyderabad-based contract manufacturers seeking REACH-registered alternatives to German single-source dependency. A technical sales-led go-to-market angle, supported by full CMR substance screening documentation below 0.1% thresholds, accelerates supplier qualification timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors flow reactor retrofit specialists with renewable energy-integrated manufacturing bases. Long-term viability over the next decade hinges on enzymatic catalysis adoption and continuous-process engineering capabilities. Acquisition targets should display dual pharmacopeia alignment and established relationships with top-20 global pharma direct procurement teams. The signal to watch is ECHA guidance expansion on Substances of Very High Concern, which would force impurity requalification across European supply chains and favor producers with advanced analytical packages.| Strategic Initiative | Industry Significance |
|---|---|
| Flow Reactor Capacity Expansion | Bavarian fine chemical producers collapse batch economics through skid-mounted continuous systems. |
| Backward Integration into Methanol Supply | Gulf Coast petrochemical infrastructure anchors domestic feedstock security against quarterly volatility. |
| Dual Pharmacopeia Certification Investment | REACH-registered suppliers capture fixed-price agreements spanning 3-5 years with top-20 pharma. |
| Enzymatic Esterification Transition | Shandong and Jiangsu facilities align with MEE dual carbon goals and green chemistry subsidies. |
| Direct Technical Sales Channel Buildout | Seqens and TCI Chemicals displace distributors through in-house account management in Germany and Japan. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with plant managers at ester production facilities, procurement leads at pharmaceutical CDMOs, distribution channel partners in specialty chemicals, and technical R&D directors overseeing enzymatic catalysis programs; alongside secondary validation through customs and trade data, Cefic sector reports, SEC 10-K filings from listed chemical producers, and ECHA REACH registration databases. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across purity grades and end-use applications.
Forecast inputs incorporated grade tier stratification, end-use industry velocity, regional production hub dynamics, and certification status as core segmentation dimensions. CAGRs were derived through regression analysis of historical trade flows and projected capacity additions, with enzymatic process adoption rates and pharmaceutical excipient monograph alignment timelines serving as industry-specific demand shapers across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese technical-grade producers or accelerated fermentation-derived succinate substitution in cosmetic applications would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Fragrance-Release Control Agents for Long-Lasting Home Care Scents Market
Specialty Chemicals
Specialty Biocides Market
Specialty Chemicals
Mequinol Market
Specialty Chemicals
Washable Marker Market
Specialty Chemicals
Protein Purification Resin Market
Specialty Chemicals
Global Specialty Fuel Additives Market
Specialty Chemicals
13X Molecular Sieve Activated Powder Market
Specialty Chemicals
Asia Pacific Aerosol Cans Market
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
Global Ceramide Market
Specialty Chemicals
Sizing and Thickening Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Natural Phytosphingosine Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
Ursolic Acid Market
Specialty Chemicals
Ricinoleic Acid Market