
 Global Chitin Market | 2026-2036
Global Chitin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chitin Market Analysis
The price-performance gap between pharmaceutical-grade chitosan and commodity chitin for agricultural use is hardening as purification costs diverge. Primex Ingredients ASA leverages its Norwegian marine sourcing to sustain premium positioning in medical-grade supply chains. Golden-Shell Pharmaceutical anchors volume production through integrated crustacean processing in Zhejiang province. Heppe Medical Chitosan GmbH differentiates via ultra-pure chitosan grades that meet European Pharmacopoeia monograph standards.
Chitin is a linear aminopolysaccharide composed of N-acetylglucosamine units linked by beta-1,4-glycosidic bonds, typically extracted from crustacean shells through sequential demineralization and deproteinization steps. Deacetylation yields chitosan, the primary commercially functional derivative used across biomedical, agricultural, and food preservation applications. Chitosan dominates value capture due to its solubility in dilute acids and film-forming properties that enable pharmaceutical encapsulation and wound dressing formulations. Chitin oligosaccharides represent the fastest-expanding product category, driven by emerging research into prebiotic and plant elicitor functions that command higher margins than bulk chitin flakes.
FDA oversight of chitosan-based medical devices and EMA regulation of marine-derived excipients create dual compliance thresholds that filter market access. Japan's PMDA maintains distinct pharmacopeial standards for chitosan viscosity and endotoxin limits, shaping export requirements for Asian processors. Stakeholders must monitor evolving biopolymer certification schemes and marine sustainability traceability rules that will determine which extraction operations retain supply contracts with regulated end users.
Market Dynamics
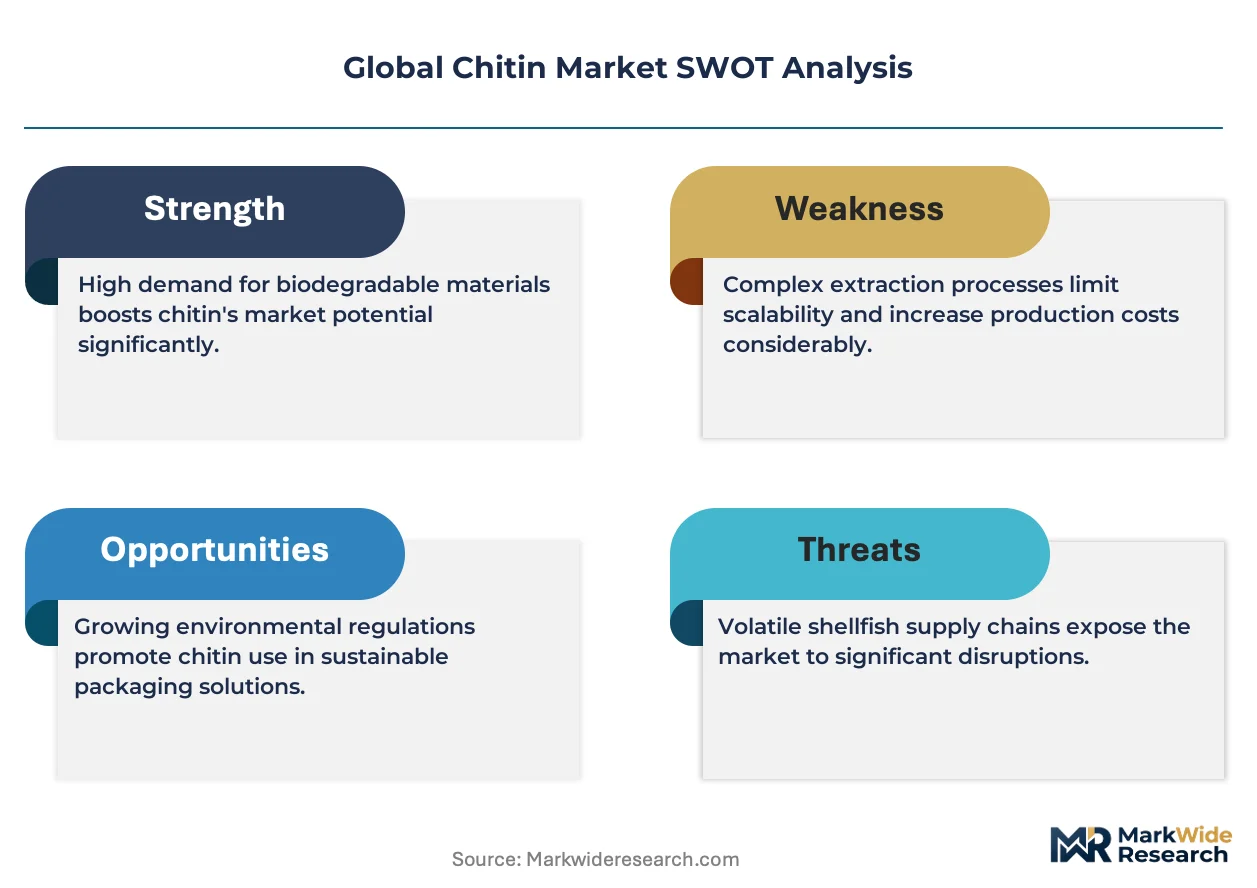
Pharmaceutical-grade purification costs are diverging from commodity agricultural grades, creating a bifurcated value chain where certification standards determine supplier viability more than raw material access.
Growth Catalysts
- EU Green Deal marine valorization mandates:Processors across Spain, France, and Italy must adopt certified extraction methods to access European pharmaceutical supply chains, accelerating capital deployment into enzymatic deproteinization systems.
- Japan METI biopolymer initiatives:Domestic refinement subsidies for medical-grade chitosan are absorbing regional crustacean waste streams and establishing export-quality benchmarks for viscosity and endotoxin limits.
- Controlled-release drug delivery pipelines:Formulation scientists at major pharmaceutical developers are specifying chitosan derivatives for oral and injectable depot systems, creating pull-through demand for ultra-pure grades.
Market Restraints
- Calcium carbonate input cost volatility:Demineralization acid consumption and waste neutralization costs fluctuate with industrial chemical pricing, compressing margins for commodity-grade producers in Vietnam and Indonesia.
- Seasonal crustacean supply concentration:Processing capacity clusters around Zhejiang and Shandong provinces in China, creating geographic single-point vulnerability for global flake supply.
- Cellulose and alginate substitution in food preservation:Lower-cost biopolymers are capturing shelf-life extension applications where chitosan antimicrobial properties are not explicitly specified by buyers.
Strategic Opportunities
- Brazilian aquaculture waste valorization:Underutilized shrimp processing byproducts in Ceará and Rio Grande do Sul offer virgin feedstock for processors willing to build extraction capacity outside Asian supply clusters.
- Chitin oligosaccharide plant elicitor applications:Emerging agricultural biotechnology research in the Netherlands and Israel is validating induced systemic resistance in specialty crops, opening premium pricing tiers for low-molecular-weight fractions.
- EMA marine-derived excipient traceability rules:New documentation requirements for polymer chain-of-custody are creating first-mover advantage for operations with integrated fishery partnerships and blockchain-enabled sourcing verification.
Industry Challenges
- Enzymatic deacetylation specialist scarcity:The intersection of carbohydrate chemistry and pharmaceutical GMP compliance requires talent pools concentrated in Basel, Boston, and Osaka, creating recruitment bottlenecks for new market entrants.
- European Pharmacopoeia certification timelines:Chitosan viscosity grade approval cycles extend 18-24 months, locking working capital in qualification batches before revenue recognition.
- Legacy batch processing equipment retrofit:Continuous flow reactor adoption for deproteinization demands capital reallocation that conflicts with depreciation schedules at established crustacean processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chitin Market |
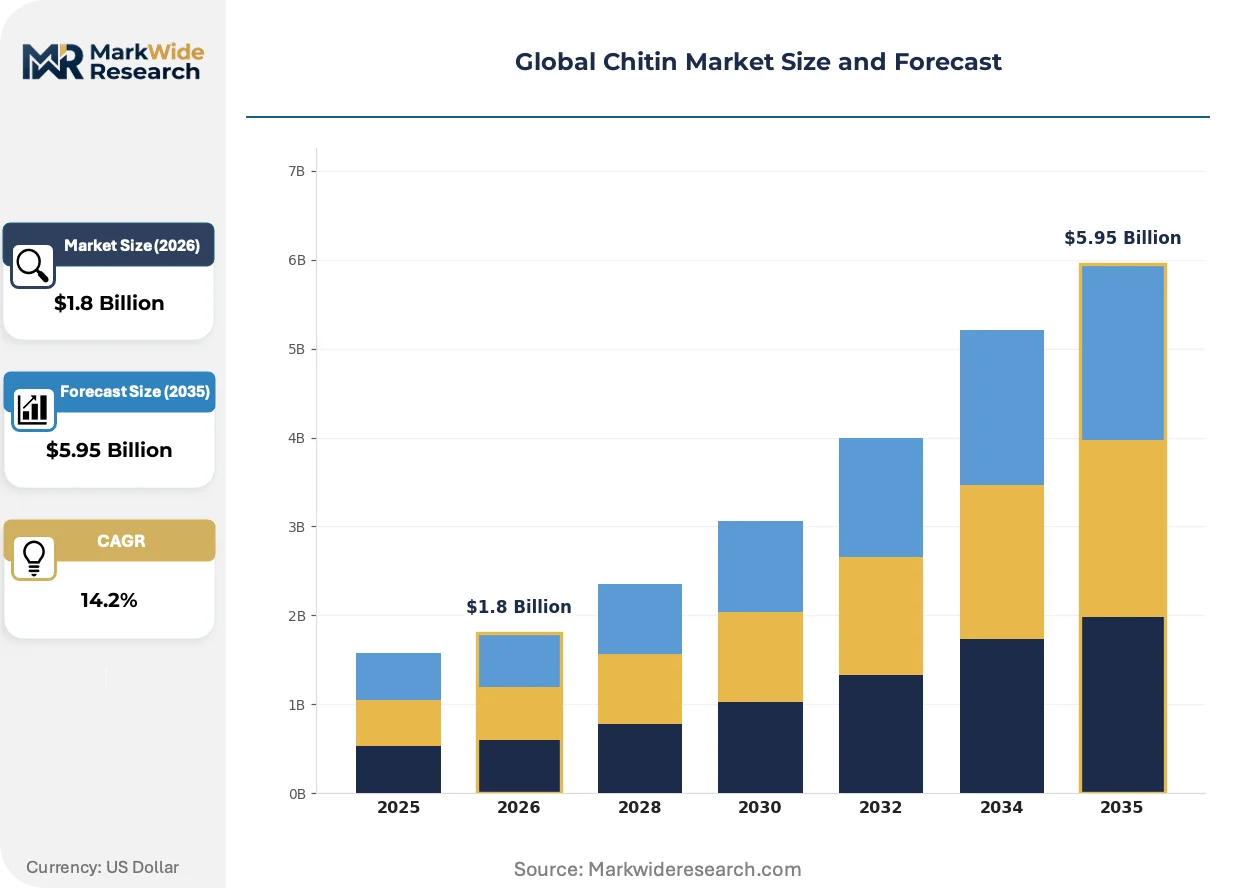
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chitin, Chitosan, Chitin Oligosaccharides, N-acetylglucosamine Application: Food & Beverages, Pharmaceuticals, Agriculture, Cosmeceuticals End User: Food Manufacturers, Healthcare Providers, Agricultural Companies, Cosmetic Brands Form: Powder, Granules, Solution, Flakes |
| Companies Covered | Novamatrix, Golden-Shell Pharmaceutical, Primex Ingredients ASA, Kunpoong Bio Co., Ltd., Zhejiang Fengrun Biotech, Kitozyme, Biopharm, Advanced Biopolymers AS, Heppe Medical Chitosan GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chitin Market Emerging Trajectories
Enzymatic extraction technologies and precision fermentation alternatives are compressing the traditional acid-base processing paradigm, while regulatory traceability requirements are rewriting procurement specifications across medical-grade supply tiers.
Enzymatic deproteinization using engineered protease cocktails is rewriting the economics of high-purity chitin production. Pharmaceutical excipient manufacturers in Germany and Switzerland are adopting these systems to eliminate residual protein contamination without harsh alkaline conditions. The technology is compressing qualification timelines for European Pharmacopoeia compliance and enabling smaller batch sizes for personalized medicine applications.
REACH framework amendments on marine polymer traceability are forcing supply chain documentation upgrades across EU-based medical device manufacturers. Processors must now certify fishery origin, seasonal harvest windows, and demineralization acid batch records to maintain excipient supplier status. The heaviest compliance burden falls on Spanish and Portuguese operations serving wound dressing and surgical sealant formulators.
Prebiotic ingredient buyers are consolidating procurement around chitin oligosaccharide suppliers with human clinical trial data packages. Dietary supplement brands in California and Tokyo are displacing generic bulk purchases with specification-driven contracts tied to molecular weight distribution certificates and human microbiome study results. This behavioral shift is most visible in direct-to-consumer gut health brands that market specific chain-length fractions rather than generic chitosan content claims.
Global Chitin Market Segmentation
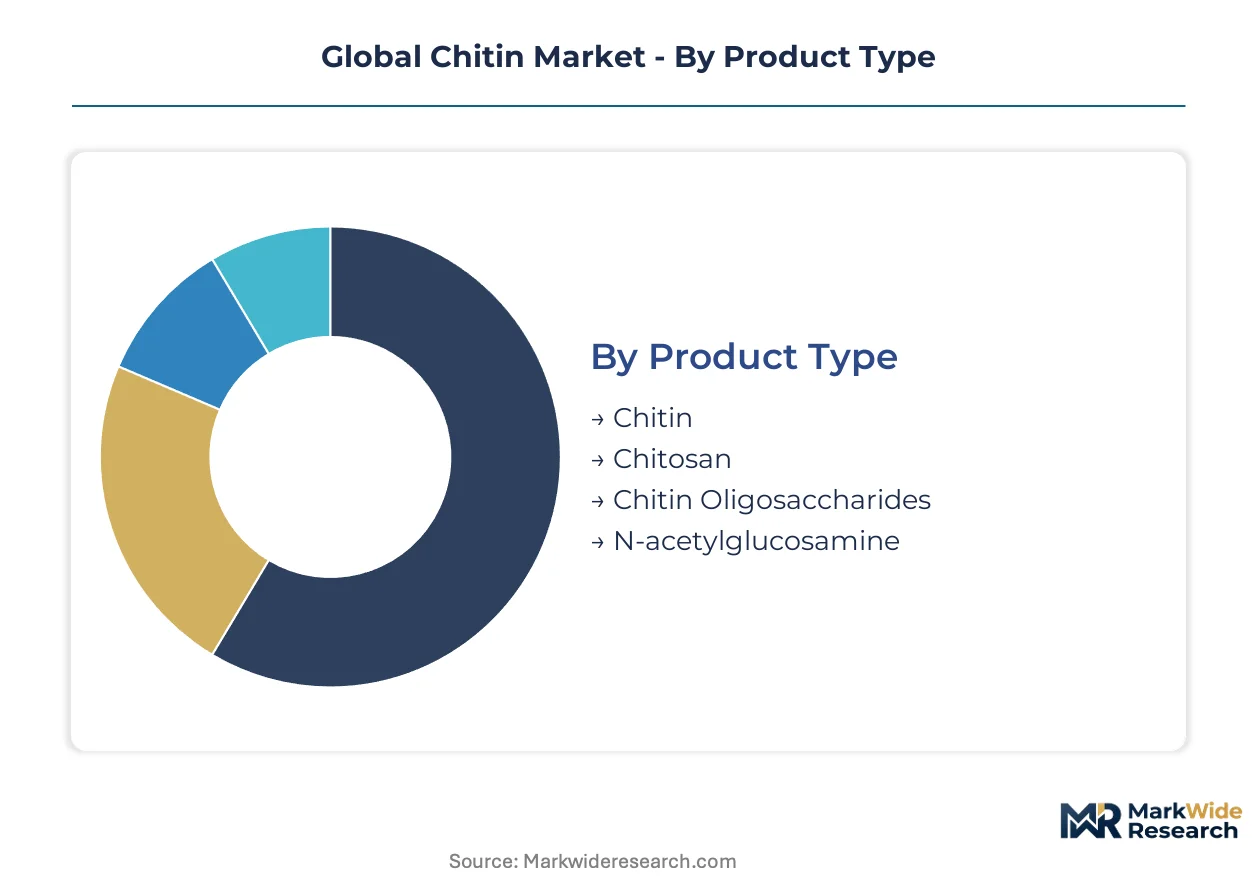
Segmentation in the chitin market reflects divergent purification economics and regulatory thresholds that separate pharmaceutical-grade supply chains from commodity agricultural flows. Buyers select grades based on endotoxin limits, viscosity specifications, and traceability documentation rather than price alone.
Product Type:
Purchasing decisions in this category pivot on deacetylation degree and molecular weight distribution, which determine solubility profiles and functional performance across end-use applications.
- Chitin:The native aminopolysaccharide retains N-acetylglucosamine units in rigid crystalline structures. Demand concentrates in Japanese wound dressing manufacturers seeking raw material for controlled deacetylation to precise medical-grade specifications.
- Chitosan:Partially deacetylated derivatives exhibit solubility in dilute acids essential for pharmaceutical encapsulation. European oral drug delivery formulators in Basel and Oxfordshire are specifying ultra-pure grades with endotoxin limits below 0.25 EU/g.
- Chitin Oligosaccharides:Low-molecular-weight fractions command premium pricing in Dutch and Israeli agricultural biotechnology trials validating plant systemic resistance induction.
- N-acetylglucosamine:Monomer units serve nutraceutical joint health formulations with specifications tightening around heavy metal content and microbial limits.
Volume sits with chitosan intermediates; growth tilts toward chitin oligosaccharides.
Application:
Application selection tracks regulatory burden intensity, with pharmaceutical and food pathways requiring GMP compliance while agricultural channels operate under lighter residue monitoring frameworks.
- Food & Beverages:Film-forming and antimicrobial properties extend shelf life in Japanese and Korean seafood packaging. Processors in Busan and Osaka specify chitosan coatings for premium sashimi export lines.
- Pharmaceuticals:Controlled-release depot systems and mucoadhesive drug delivery platforms absorb high-purity chitosan derivatives. FDA and EMA excipient master file submissions are concentrating procurement around certified European and North American suppliers.
- Agriculture:Seed treatment and soil amendment applications in Vietnam and Indonesia utilize commodity-grade flakes where antimicrobial efficacy outweighs purity requirements.
- Cosmeceuticals:Moisture-retention and film-forming properties drive incorporation into Korean and French skincare formulations with claims around barrier function support.
Revenue concentrates in pharmaceutical pathways; expansion accelerates fastest in cosmeceutical incorporation.
End User:
End user categories separate by technical specification capability, with healthcare and food manufacturers maintaining analytical laboratories for incoming raw material verification.
- Food Manufacturers:Japanese seafood processors and European plant-based meat developers specify chitosan for moisture retention and antimicrobial surface treatments.
- Healthcare Providers:Hospital networks and surgical product distributors in Germany and Switzerland source wound dressing materials with documented biocompatibility testing.
- Agricultural Companies:Brazilian and Thai integrated aquaculture operations utilize chitin-rich waste streams for in-house soil amendment production.
- Cosmetic Brands:Korean beauty conglomerates and French luxury skincare houses formulate with low-ash chitosan grades for premium positioning.
Procurement scale favors food manufacturers; specification intensity peaks with healthcare providers.
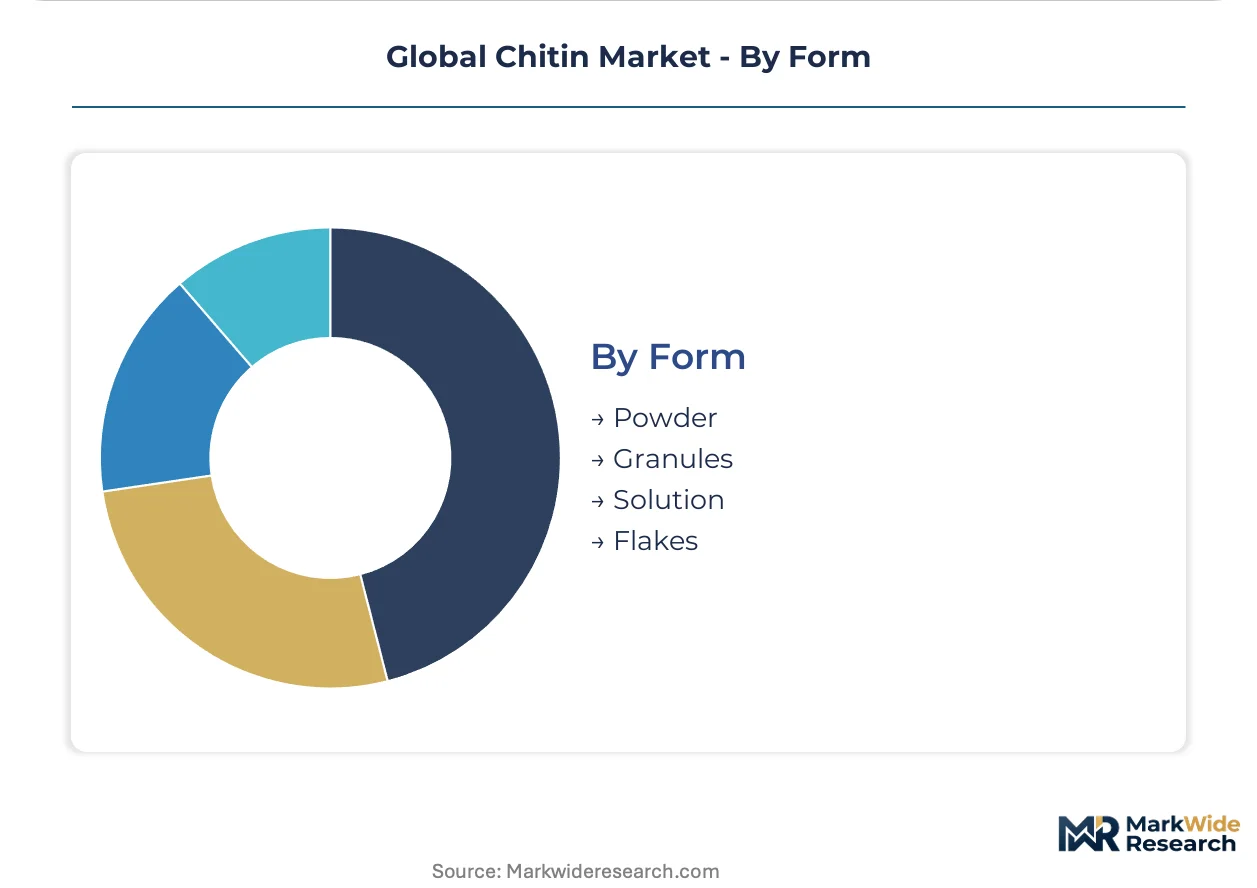
Form:
Physical form selection determines handling economics and dissolution kinetics, with powder and solution formats commanding logistics premiums for specialized transport requirements.
- Powder:Fine particulate grades enable precise dosing in pharmaceutical tableting and dry blend nutraceutical formulations. Milling to specified particle size distributions is concentrating production in German and Swiss toll processing facilities.
- Granules:Intermediate particle sizes facilitate controlled dissolution in agricultural seed coating equipment and slow-release fertilizer matrices.
- Solution:Pre-dissolved acidic chitosan formats eliminate on-site hydration steps for food coating lines and cosmetic formulation suites.
- Flakes:Intermediate processing feedstock for downstream deacetylation operations, with Zhejiang and Shandong processors dominating bulk supply.
Processing throughput centers on flake intermediates; value capture climbs fastest in solution formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang province anchors crustacean processing throughput, with Shaoxing and Ningbo clusters refining shell waste into pharmaceutical-grade chitosan intermediates. Japanese medical device manufacturers source heavily from this corridor, while European formulators diversify toward certified Spanish and Portuguese operations.
China
Pharmaceutical-grade chitosan demand from Basel and Oxfordshire formulators pulls volume through Zhejiang and Shandong extraction facilities. NMPA oversight of marine-derived excipient imports is tightening documentation requirements for endotoxin certification. The Yangtze River Delta concentration around Shanghai creates single-point vulnerability for global flake supply during seasonal processing peaks.
Japan
METI biopolymer subsidies absorb domestic crustacean waste streams into medical-grade refinement operations. PMDA pharmacopeial standards for chitosan viscosity and endotoxin limits exceed EMA thresholds, filtering supplier access for Asian processors. Osaka and Tokyo formulation clusters specify ultra-pure grades for wound dressing and drug delivery applications.
Germany
EMA marine-derived excipient traceability rules are concentrating procurement around operations with integrated fishery partnerships. Heppe Medical Chitosan GmbH exemplifies the European Pharmacopoeia compliance tier that Basel pharmaceutical developers require. Bavarian and Baden-Württemberg toll processing facilities are retrofitting enzymatic deproteinization systems to compress qualification timelines.
Spain
EU Green Deal marine valorization mandates are accelerating capital deployment into certified extraction methods across Galician and Andalusian processing zones. REACH framework amendments on polymer chain-of-custody documentation are creating compliance bottlenecks for wound dressing material suppliers. Valencia and Barcelona clusters are adopting blockchain-enabled sourcing verification to maintain excipient supplier status.
Brazil
Underutilized shrimp processing byproducts in Ceará and Rio Grande do Sul offer virgin feedstock for extraction capacity outside Asian supply clusters. ANVISA pharmaceutical regulator alignment with ICH excipient standards is opening pathway for medical-grade chitosan exports. São Paulo formulation developers are testing regional supply for antimicrobial food coating applications.
Global Chitin Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade stratification, with European Pharmacopoeia compliance separating viable pharmaceutical suppliers from agricultural-grade processors. The vendor base organizes into three strategic archetypes: integrated crustacean processors with captive waste streams, toll refinement specialists with GMP-certified facilities, and enzymatic technology licensors enabling qualification acceleration. Competitive moves center on backward integration into fishery partnerships and portfolio diversification toward chitin oligosaccharide fractions commanding agricultural biotechnology premiums.
Within the integrated processing tier, Golden-Shell Pharmaceutical and Zhejiang Fengrun Biotech represent scale-driven operations anchored in Zhejiang province crustacean waste concentration. Heppe Medical Chitosan GmbH occupies a position exemplifying European Pharmacopoeia compliance specialization. Primex Ingredients ASA sits within the premium-tier vector leveraging Norwegian marine sourcing for medical-grade supply chain positioning. Kunpoong Bio Co., Ltd. and Novamatrix represent alternative geography-based anchors for regional procurement diversification.
| Leading Market Players |
|---|
| Novamatrix |
| Golden-Shell Pharmaceutical |
| Primex Ingredients ASA |
| Kunpoong Bio Co., Ltd. |
| Zhejiang Fengrun Biotech |
| Kitozyme |
| Biopharm |
| Advanced Biopolymers AS |
| Heppe Medical Chitosan GmbH |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical formulators in Basel and Oxfordshire demanding European Pharmacopoeia certification for chitosan excipients are forcing extraction operations to absorb enzymatic deproteinization costs, compressing margins for commodity-grade producers while enabling premium capture by certified suppliers.
Pricing Analysis
Outcome-based pricing tied to endotoxin compliance and viscosity performance anchors value capture in pharmaceutical-grade supply tiers. Three-tier pricing structure across premium, standard, and economy levels separates ultra-pure medical grades from agricultural flakes and feedstock intermediates. Cost compression in commodity agricultural tiers is intensifying because Vietnamese and Indonesian processors face calcium carbonate input volatility. Food manufacturers exhibit highest price sensitivity, while pharmaceutical developers prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-formulator channels handle pharmaceutical-grade volume, while bulk flake distribution runs through Zhejiang and Shandong processing clusters to toll refiners. Supply concentrates in China, Vietnam, and Indonesia for crustacean waste feedstock, with enzymatic deproteinization equipment sourcing from Germany and Switzerland. Hydrochloric acid for demineralization, engineered protease cocktails, and filtration membranes constitute critical input dependencies. Single-source vulnerability in Yangtze River Delta processing creates geographic concentration risk during seasonal harvest peaks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over fishery waste streams and GMP-certified refinement capacity determines supplier viability more than extraction technology alone.
For Market Incumbents: Extend certification coverage into Japanese PMDA pharmacopeial tiers to preempt Asian competitor access. Deepen backward integration into Norwegian and Brazilian fishery partnerships to secure traceable feedstock under EMA chain-of-custody rules. Cellulose and alginate substitution in food preservation applications threatens commodity chitosan volumes, necessitating portfolio pivot toward chitin oligosaccharide fractions. For New Entrants and Emerging Players: Brazilian aquaculture operators seeking localized soil amendment supply represent the most penetrable buyer archetype. Ceará and Rio Grande do Sul shrimp processing clusters offer virgin feedstock access outside Asian supply concentration. Dutch and Israeli agricultural biotechnology developers provide entry pathway through plant elicitor trial partnerships with lower certification barriers than pharmaceutical channels. For Investors and Strategic Acquirers: The window for entry favors toll refinement specialists with existing GMP infrastructure and European Pharmacopoeia compliance track records. Long-term viability hinges on acquisition targets possessing integrated fishery partnerships rather than standalone extraction technology. EMA marine-derived excipient traceability rule enforcement velocity serves as the critical inflection indicator for certification-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fishery Partnerships | Secures traceable crustacean waste feedstock required for EMA chain-of-custody documentation. |
| Enzymatic Deproteinization Capacity Expansion | Enables European Pharmacopoeia compliance with compressed qualification timelines for Basel formulators. |
| Chitin Oligosaccharide Fractionation Investment | Captures premium pricing from Dutch and Israeli agricultural biotechnology plant elicitor trials. |
| PMDA Pharmacopeial Certification Pathway | Unlocks Japanese medical device manufacturer procurement specifications exceeding EMA thresholds. |
| Blockchain-Enabled Sourcing Verification | Satisfies REACH framework amendments on polymer traceability for Spanish wound dressing suppliers. |
Methodological Framework
Trade databases, customs records, and European Pharmacopoeia certification registries formed the secondary backbone for supply-side mapping. Primary interviews with extraction plant managers, pharmaceutical formulation scientists, fishery procurement leads, and toll processing facility operators validated capacity estimates and qualification timelines. Bottom-up and top-down triangulation reconciled Zhejiang province processing volume data against Basel and Oxfordshire formulator demand signals.
Bottom-up modeling aggregated segment-level volume and value outputs across the analysis window. Segmentation dimensions included product type, application pathway, end-user technical capability, and physical form. CAGRs derived from regression analysis against pharmaceutical pipeline progression and agricultural biotechnology trial expansion. Forecast inputs incorporated METI biopolymer subsidy disbursement patterns and EU Green Deal marine valorization mandate implementation velocity.
Revisions become necessary when EMA traceability rule enforcement accelerates, enzymatic deproteinization technology licensing costs shift, or Brazilian ANVISA alignment with ICH excipient standards advances faster than projected. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Ceramide Market
Specialty Chemicals
Bond Breaker Market
Specialty Chemicals
Global Lactobionic Acid Market
Specialty Chemicals
Keratin Products Market
Specialty Chemicals
Photoinitiators Market
Specialty Chemicals
Organosilicon Electrolyte Market
Specialty Chemicals
Biobased Propylene Glycol Market
Specialty Chemicals
Asia Pacific Aerosol Cans Market
Specialty Chemicals
Ricinoleic Acid Market
Specialty Chemicals
Global Cyclodextrin Market
Specialty Chemicals
Sugarcane Wax Market
Specialty Chemicals
LAMEA Metal Biocides Market
Specialty Chemicals
Naphthol AS-IRG Market
Specialty Chemicals
Global Baking Soda Substitute Market
Specialty Chemicals
Dimethyl Silicone Market
Specialty Chemicals
Perms and Relaxants Market