
 Australia and New Zealand Aerosol Market | 2026-2036
Australia and New Zealand Aerosol Market Size, Share, and Industry Trends Forecast 2026-2036
Australia and New Zealand Aerosol Market Outlook
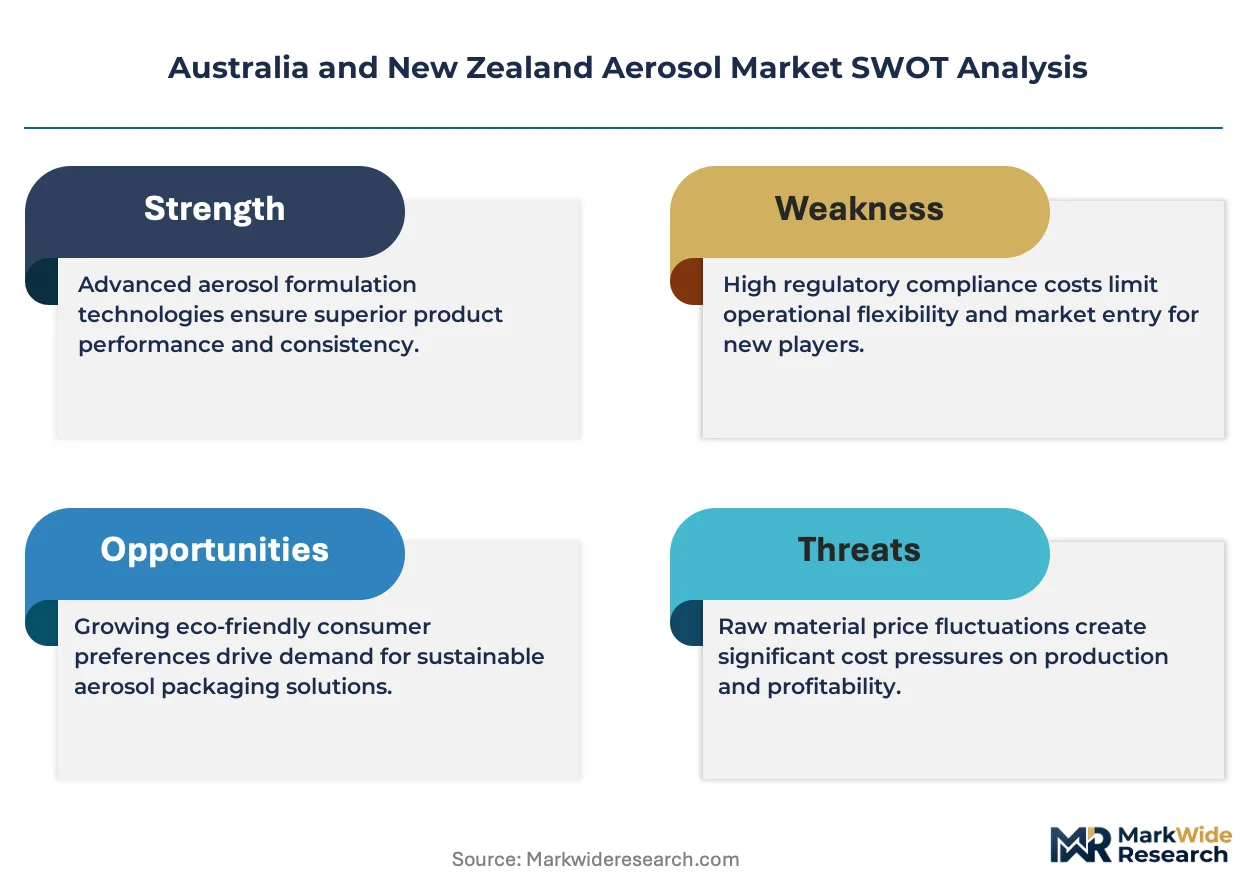
Pharmaceutical-grade and food-contact specification tiers is bifurcating the Australia and New Zealand Aerosol Market into premium-validated and general-purpose supply streams. BASF leverages its specialty chemicals portfolio to serve industrial coating aerosols across Australian automotive clusters. Henkel AG & Co. KGaA anchors the household segment through concentrated distribution in Australasian retail channels. PPG Industries Inc. competes in protective coating aerosols for infrastructure maintenance throughout both countries.
An aerosol is a colloidal suspension of fine solid particles or liquid droplets in a gas, typically packaged under pressure between 2 and 10 bar within a sealed container with a valve-actuated release mechanism. The formulation combines an active product concentrate with a liquefied or compressed gas propellant to deliver controlled, metered dispersion for surface coating, personal application, or space treatment. Personal Care commands the largest value pool due to deodorant and hair care penetration in Australian supermarkets, while Industrial aerosols are expanding fastest from mining equipment maintenance demand in Western Australia and Queensland. Aluminum material dominates can fabrication because of its compatibility with corrosion-sensitive formulations and established recycling infrastructure across both nations.
TGA regulates therapeutic aerosols in Australia, while New Zealand's EPA administers the Hazardous Substances and New Organisms Act governing propellant classifications and labeling standards. Australia's alignment with Montreal Protocol phase-down schedules for hydrofluorocarbon propellants is tightening formulation compliance costs for local blenders. Stakeholders must monitor evolving state-level waste recovery mandates and propellant transition timelines to secure sustained market access across the trans-Tasman regulatory environment.
Market Dynamics
Australia's mandatory phase-down of hydrofluorocarbon propellants under national environmental protocols is compressing formulation timelines and forcing capital redeployment toward low-GWP alternatives across the trans-Tasman manufacturing base.
Growth Catalysts
- Propellant Transition Mandates:Australia's alignment with Montreal Protocol schedules creates first-mover advantage for domestic blenders mastering hydrocarbon and dimethyl ether formulations ahead of compliance deadlines.
- Mining Equipment Maintenance:Western Australia's iron ore and Queensland's coal operations generate sustained demand for industrial lubricant and protective coating aerosols in remote field conditions.
- Urban Personal Care Penetration:Sydney and Melbourne supermarket chains are expanding shelf space for deodorant and hair styling aerosols among density-concentrated apartment dwellers.
Market Restraints
- Aluminum Can Supply Concentration:Domestic can fabrication relies on a limited importer base, exposing converters to freight cost volatility and extended lead times from Southeast Asian suppliers.
- Propellant R&D Cost Burden:Low-GWP formulation development requires specialized pressure-testing infrastructure that mid-tier blenders cannot self-finance without external capital.
- Solid and Pump Spray Substitution:Stick deodorants and trigger-spray household cleaners are capturing shelf space in Australasian retail channels, particularly among environmentally positioning private labels.
Strategic Opportunities
- New Zealand Underpenetration:Auckland and Christchurch retail channels carry narrower aerosol assortments than Australian equivalents, presenting whitespace for personal care and automotive maintenance lines.
- Food-Contact Certification Tier:TGA and New Zealand EPA pathways for pharmaceutical-grade and food-contact specifications enable premium pricing separation from general-purpose supply streams.
- Direct E-Commerce Channels:Subscription-based replenishment models for industrial maintenance aerosols are bypassing traditional distributor markups in Western Australian mining towns.
Industry Challenges
- Propellant Handling Certification:Australia's state-level dangerous goods licensing creates fragmented compliance training requirements for warehouse and transport operators.
- Legacy Equipment Retrofit Costs:Existing filling lines require pressure-vessel modifications to handle next-generation propellant chemistries, straining capital allocation for family-owned blenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia and New Zealand Aerosol Market |
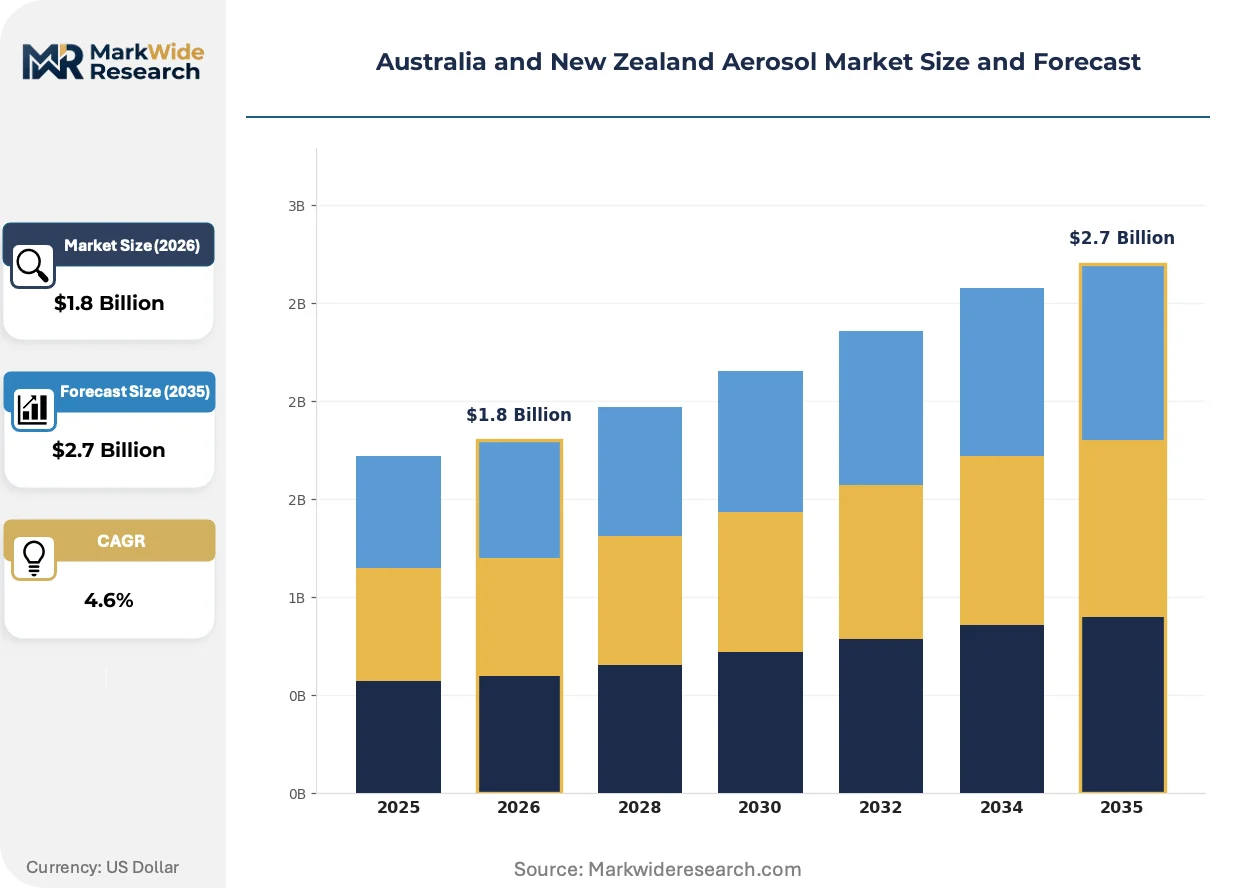
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Care, Household, Industrial, Paints Application: Cosmetics, Cleaning Products, Food Packaging, Automotive Material: Aluminum, Steel, Plastic, Glass End User: Retailers, Manufacturers, Distributors, Consumers |
| Companies Covered | PPG Industries Inc., BASF, Unilever, Aerosolve, AkzoNobel N.V., Reckitt Benckiser Group PLC, Honeywell International Inc., Chemz Limited, Henkel AG & Co. KGaA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia and New Zealand Aerosol Market Strategic Shifts
Compressed gas propellant systems and valve miniaturization are converging to reshape product performance benchmarks across personal care and industrial applications in both markets.
Bag-on-valve technology is separating the product concentrate from the propellant using a laminated film pouch, enabling water-based and solvent-sensitive formulations previously incompatible with traditional pressure packaging. Australian sunscreen and cosmetic brands are adopting this system for preservative-free and natural-positioned lines. The technology is miniaturizing dose precision and expanding the addressable formulation space beyond conventional hydrocarbon limits.
TGA's therapeutic goods administration and New Zealand EPA's Hazardous Substances and New Organisms Act are tightening labeling and propellant classification requirements in parallel with Australia's Montreal Protocol implementation. Local blenders face dual-track compliance costs for trans-Tasman product registration. Industrial coating aerosols are absorbing the heaviest documentation burden as both regulators scrutinize volatile organic compound emissions in occupational settings.
Buyers in Australian automotive aftermarket channels are consolidating purchase decisions through integrated fleet maintenance contracts that bundle aerosol lubricants with broader consumable supply agreements. Independent auto parts retailers are losing volume to direct procurement relationships between mining contractors and industrial aerosol specialists. This concentration is most visible in Western Australia's Pilbara region where fly-in-fly-out workforce logistics favor consolidated supplier relationships over fragmented retail purchasing.
Australia and New Zealand Aerosol Market Segmentation
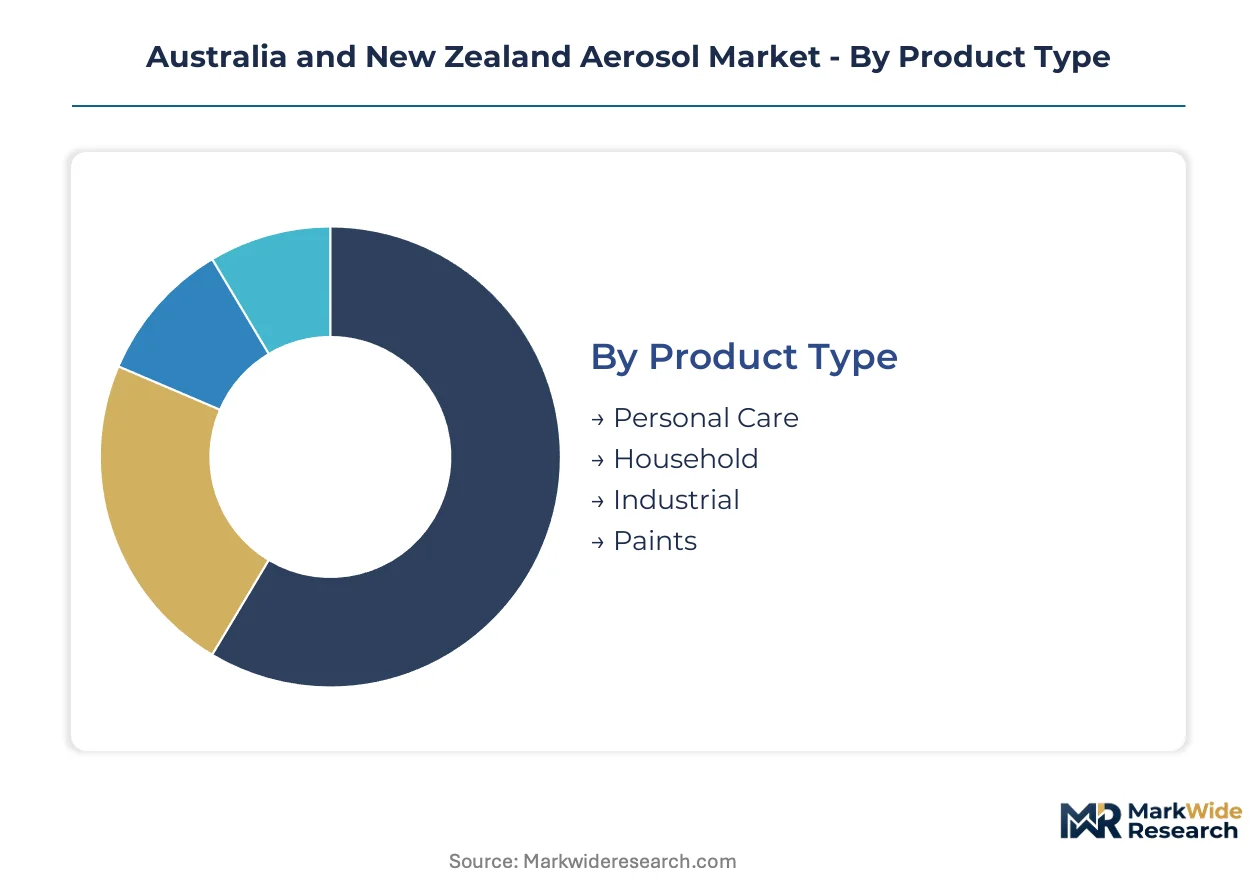
Channel configuration in Australia and New Zealand aerosol distribution varies sharply by segment, with personal care flowing through supermarket chains while industrial lines bypass retail entirely. Understanding these pathway distinctions enables targeted margin capture and inventory positioning.
Product Type:
Supermarket chains in Sydney and Melbourne carry concentrated personal care assortments, whereas industrial aerosols move through direct mining contractor relationships in Western Australia's Pilbara region.
- Personal Care:Deodorant and hair styling formulations dominate shelf space in Australian supermarkets, driven by apartment-dwelling urban consumers in Melbourne and Sydney seeking convenience formats. TGA labeling requirements for therapeutic claims add compliance layers distinct from cosmetic-only lines.
- Industrial:Lubricant and protective coating aerosols serve remote mining equipment maintenance across Western Australia's iron ore operations and Queensland's coal fields, where fly-in-fly-out workforce logistics favor consolidated supplier contracts over fragmented retail purchasing.
- Household:Cleaning and disinfectant aerosols distribute through Australasian retail channels with concentrated placement in Coles and Woolworths networks.
- Paints:Decorative and touch-up spray paints reach consumers through hardware chains and automotive aftermarket specialists.
Personal Care dominates installed base. Industrial is where expansion concentrates.
Application:
Cost tiers separate cosmetic applications from food-contact specifications, with the latter commanding premium validation pathways through TGA and New Zealand EPA.
- Cosmetics:Sunscreen and skincare aerosols adopt bag-on-valve technology for preservative-free positioning, particularly among Australian natural-positioned brands targeting clean-label consumers.
- Automotive:Aftermarket lubricant and coating aerosols in Australia are consolidating through fleet maintenance contracts that bundle consumables, displacing independent auto parts retailers in mining regions.
- Cleaning Products:Surface disinfectant and specialty cleaner aerosols face substitution pressure from trigger-spray formats in environmentally positioning private labels.
- Food Packaging:Cooking spray and food-release formulations require food-contact certification tiers that enable pricing separation from general-purpose supply streams.
Cosmetics commands premium shelf positioning. Automotive is climbing the fastest on mining demand.
Material:
Volume concentration in aluminum reflects established recycling infrastructure across both nations, while alternative materials serve niche corrosion-sensitive or visibility requirements.
- Aluminum:Dominates can fabrication due to compatibility with corrosion-sensitive formulations and mature recycling systems throughout Australia and New Zealand.
- Steel:Serves industrial coating applications where puncture resistance outweighs weight considerations in remote field conditions.
- Plastic:Emerging in trigger-spray hybrid formats that bypass traditional pressure packaging for household cleaning segments.
- Glass:Limited to pharmaceutical-grade therapeutic aerosols requiring inert container properties for stability-critical formulations.
Aluminum dominates installed base. Plastic is gaining share fastest through format substitution.
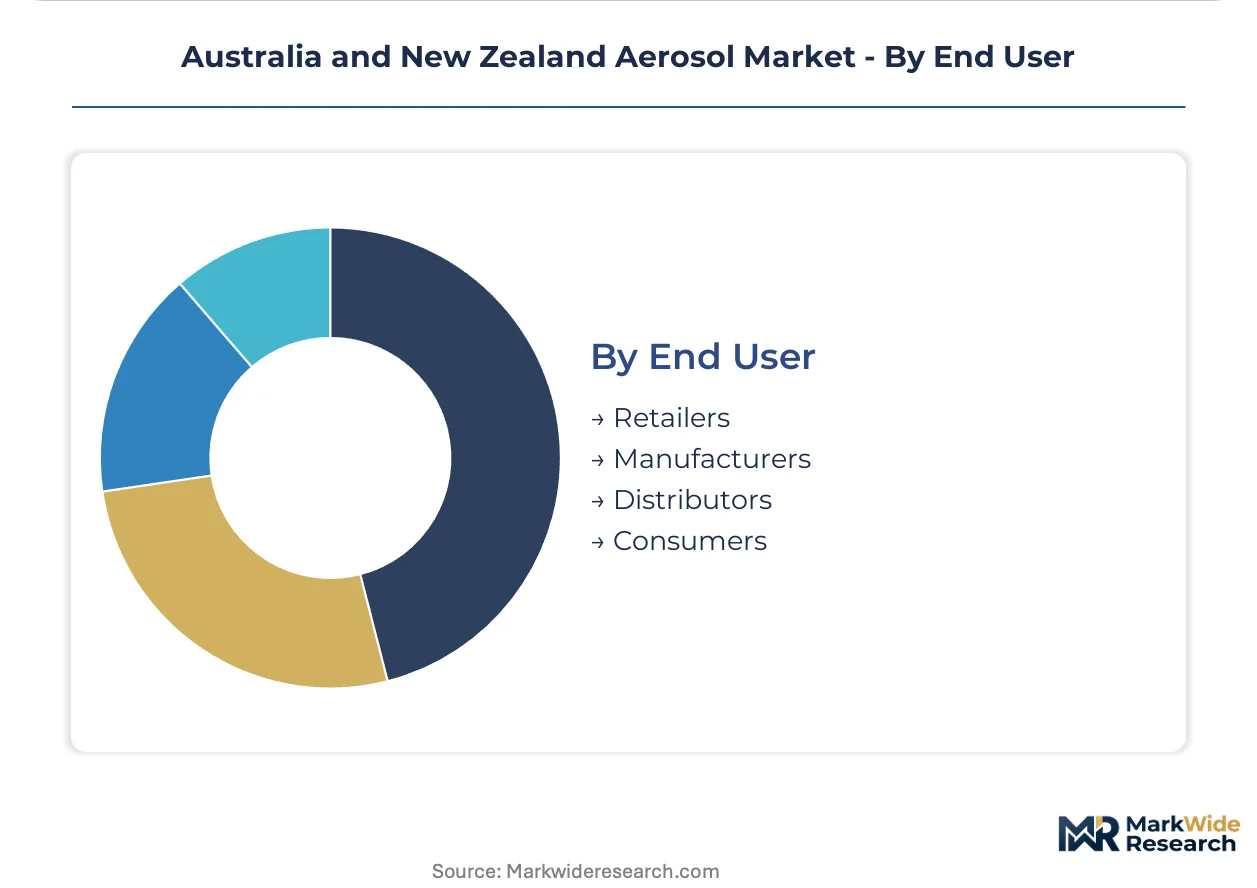
End User:
Customer type determines procurement pattern fragmentation, with mining contractors consolidating volumes while consumer channels fragment across retail touchpoints.
- Retailers:Coles, Woolworths, and Countdown in New Zealand control personal care and household aerosol shelf space, demanding promotional support and category management services.
- Manufacturers:Brand owners and contract blenders in Victoria and New South Wales source empty cans and propellants, facing aluminum supply concentration from Southeast Asian importers.
- Distributors:Industrial specialists serve Western Australian mining towns through direct relationships, bypassing traditional wholesale tiers.
- Consumers:E-commerce subscription models for automotive maintenance aerosols are emerging in remote Australian regions with limited retail access.
Retailers dominate volume throughput. Distributors are expanding most quickly in industrial channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia and New Zealand operate a modest trade deficit in aerosol packaging components, importing aluminum cans and specialty propellants from Southeast Asian suppliers while exporting finished personal care formulations to Pacific Island markets. The trans-Tasman regulatory alignment under the Australia New Zealand Food Standards Code and mutual recognition agreements streamlines cross-border product registration, though propellant phase-down timelines diverge slightly between jurisdictions.
New South Wales
Sydney's concentrated retail footprint drives personal care aerosol volumes through Coles and Woolworths headquarters operations, with deodorant and hair styling lines commanding premium shelf positioning. The state's Environment Protection Authority enforces hazardous substances storage protocols that exceed federal baselines for warehouse operators handling hydrocarbon propellants. Manufacturing clusters in Western Sydney and the Central Coast host contract blenders serving both domestic consumption and export markets across the Pacific.
Victoria
Melbourne's apartment-dwelling demographic sustains demand for convenience-format personal care aerosols, with supermarket chains expanding dedicated category space in inner-urban locations. WorkSafe Victoria administers dangerous goods licensing for propellant handling facilities, creating compliance training obligations for transport and warehouse operators. The southeastern manufacturing corridor spanning Melbourne to Geelong concentrates blending capacity for industrial coating aerosols serving automotive aftermarket channels.
Western Australia
The Pilbara mining region generates concentrated demand for industrial lubricant and protective coating aerosols, with fly-in-fly-out workforce logistics favoring consolidated supplier contracts over fragmented retail purchasing. The state's Department of Mines, Industry Regulation and Safety monitors occupational chemical exposure in remote field conditions where aerosol application occurs without ventilation infrastructure. Perth serves as distribution hub for maintenance consumables flowing to iron ore operations across the state's northwest.
Queensland
Coal mining operations in the Bowen Basin and metallurgical facilities sustain industrial aerosol consumption for equipment maintenance in high-dust environments. The Queensland Department of Environment and Science administers waste recovery mandates that affect aerosol can disposal pathways for mining contractors operating under extended site licenses. Brisbane anchors distribution networks serving both the state's resources sector and northern agricultural regions where veterinary and crop protection aerosols find application.
New Zealand
Auckland and Christchurch retail channels carry narrower aerosol assortments than Australian equivalents, presenting whitespace for personal care and automotive maintenance line expansion. The Environmental Protection Authority administers the Hazardous Substances and New Organisms Act, governing propellant classifications and labeling standards that largely mirror Australian TGA frameworks. Wellington's concentrated government and corporate presence supports specialty demand for pharmaceutical-grade therapeutic aerosols requiring stability-critical formulation standards.
Australia and New Zealand Aerosol Market Competitive Environment
Concentration sits with diversified chemical conglomerates and specialized coating suppliers that span multiple application segments across both markets. The vendor base separates into three functional tiers: multinational chemical majors with integrated propellant and formulation capabilities, regional specialists concentrating on industrial maintenance lines, and private-label contract manufacturers serving supermarket chains. Competitive dynamics revolve around propellant transition readiness and direct procurement relationships with mining contractors that bypass traditional distribution markups.
Among the multinational chemical majors, BASF and Henkel AG & Co. KGaA occupy positions exemplifying divergent strategic emphases within the trans-Tasman market. BASF represents the industrial coating and specialty chemicals archetype, while Henkel AG & Co. KGaA anchors the household and personal care segment through established retail channel presence. PPG Industries Inc. sits within the protective coatings specialist tier, serving infrastructure maintenance demand throughout both countries.
| Leading Market Players |
|---|
| PPG Industries Inc. |
| BASF |
| Unilever |
| Aerosolve |
| AkzoNobel N.V. |
| Reckitt Benckiser Group PLC |
| Honeywell International Inc. |
| Chemz Limited |
| Henkel AG & Co. KGaA |
| Others |
Value Chain & Pricing Dynamics
Dimethyl ether propellant substitution for hydrofluorocarbon formulations is simultaneously shifting raw material sourcing toward Southeast Asian petrochemical hubs and compressing margin structures for Australian blenders absorbing R&D retrofit costs. This dual displacement reshapes both procurement geography and pricing economics across the trans-Tasman manufacturing base.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for mining maintenance aerosols, while personal care flows through per-unit transactional retail channels. Three-tier pricing structure across pharmaceutical-grade, food-contact, and general-purpose specification tiers separates TGA-validated formulations from commodity supply streams. Cost compression in mid-tier household segments is intensifying because trigger-spray substitutes are capturing shelf space at Coles and Woolworths. Mining contractors show least price sensitivity due to fly-in-fly-out logistics premiums, whereas urban supermarket consumers demonstrate highest elasticity to promotional cycling.
Supply Chain Analysis
Strategic stockpiling of aluminum can inventories dominates converter behavior given extended lead times from Thai and Vietnamese fabrication facilities. Raw material flows draw from Malaysian propellant refineries, Indonesian aluminum sheet mills, and domestic Victoria-based blending capacity. Single-source vulnerability concentrates in Southeast Asian can imports exposed to freight rate volatility and port congestion. Distribution runs through Coles and Woolworths headquarters networks for personal care, while industrial lines bypass wholesale tiers via direct procurement relationships with Pilbara mining contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
First-mover advantage in low-GWP propellant formulation represents a scarce technical capability that mid-tier blenders cannot self-finance, creating consolidation pressure across the trans-Tasman supplier base.
For Market Incumbents: Consolidate backward integration into aluminum can sourcing through captive arrangements with Southeast Asian fabricators, insulating against freight volatility that strains converter margins. Deepen TGA certification pipelines for pharmaceutical-grade tiers, defending against emerging private-label entrants targeting therapeutic aerosol white space. Lock in multi-year offtake agreements with Western Australian mining contractors before direct e-commerce channels displace distributor relationships. For New Entrants and Emerging Players: TGA fast-track pathways for sunscreen and cosmetic bag-on-valve formats offer the most penetrable entry point, as Australian natural-positioned brands seek preservative-free alternatives. Target Auckland and Christchurch retail channels where narrower aerosol assortments present whitespace against established Australian supermarket networks. Pursue subscription-based replenishment models for automotive maintenance lines in remote Western Australian towns with limited retail access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with family-owned Victorian blenders lacking capital for propellant transition compliance, presenting buyout opportunities for private equity platforms with chemical sector expertise. Five-to-ten-year viability hinges on Montreal Protocol alignment completion and low-GWP formulation mastery. Watch for TGA enforcement actions on therapeutic labeling as an inflection signal for premium-tier valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Can Sourcing | Captive aluminum supply from Thai fabricators mitigates freight cost volatility for Australian converters. |
| TGA Certification Investment | Pharmaceutical-grade validation separates premium pricing from commodity household aerosol supply streams. |
| Direct E-Commerce Channel Launch | Subscription models bypass distributor markups in Western Australian mining towns with sparse retail presence. |
| Low-GWP Formulation Transition | Hydrocarbon and dimethyl ether mastery aligns with Australia's Montreal Protocol phase-down deadlines. |
| New Zealand Retail Expansion | Auckland and Christchurch underpenetration offers whitespace for personal care and automotive maintenance lines. |
Study Parameters
A standing panel of contract blending plant managers, Coles and Woolworths category buyers, Western Australian mining procurement officers, and TGA regulatory affairs specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from Australian Bureau of Statistics trade data, EPA hazardous substances filings, customs import records for aluminum cans, and SEC disclosures from multinational chemical parents. Bottom-up volume builds for each product segment were triangulated against top-down market sizing from propellant consumption trends.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, application, material, and end-user channel, with propellant chemistry transition timelines and TGA compliance cost trajectories as industry-specific forecast inputs. CAGRs were derived from segment-level growth drivers rather than aggregate market extrapolation.
Underlying assumptions cover Montreal Protocol phase-down adherence, aluminum import tariff stability, and mining sector capital expenditure continuity, with deviation risk concentrated in propellant R&D cost overruns and state-level dangerous goods licensing fragmentation. Revision becomes warranted when TGA enforcement intensity or low-GWP formulation adoption rates cross thresholds that materially alter competitive positioning dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Acesulfame Potassium Market
Specialty Chemicals
Solanesol Market
Specialty Chemicals
Phenoxycycloposphazene Market
Specialty Chemicals
Rosin Market
Specialty Chemicals
Global Specialty Resins Market
Specialty Chemicals
Eco-Friendly Plasticizers Market
Specialty Chemicals
Organometallics Market
Specialty Chemicals
Bromocyclopentane Market
Specialty Chemicals
Bio Polyol and Green Polyol Market
Specialty Chemicals
Colloidal Silver Market
Specialty Chemicals
4-Benzoylbutyric Acid Market
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
VCI Aerosol Market
Specialty Chemicals
Spiroglycol Market
Specialty Chemicals
Dipentene (Limonene) Market
Specialty Chemicals
Natural Phytosphingosine Market