
 Anhydroxylitol Market | 2026-2036
Anhydroxylitol Market Size, Share, and Industry Trends Forecast 2026-2036
Anhydroxylitol Market Analytics
Buyer concentration among cosmetics formulators is rebalancing as mid-tier brands diversify supply sources beyond established multinationals. Roquette Frères leverages its carbohydrate processing heritage to anchor European supply chains for anhydroxylitol derivatives. Seppic competes through specialized emollient portfolios that integrate the ingredient into high-performance skin care. DuPont de Nemours extends its biotech platform to sustain quality consistency across pharmaceutical-grade specifications.
Anhydroxylitol is a dehydrated sugar alcohol derived from xylitol, typically appearing as a white crystalline powder with hygroscopic properties and a melting point near 92 degrees Celsius, manufactured through acid-catalyzed dehydration of xylitol feedstock for use as a humectant, stabilizer, and moisture-binding agent across personal care and therapeutic applications. Powder formulations dominate current volume owing to handling efficiency in bulk compounding operations, while liquid variants represent the fastest-expanding category as ready-to-use solutions gain traction among contract manufacturers. The Nutraceuticals application segment commands premium positioning due to stringent certification requirements, whereas Cosmetics channels generate the broadest demand base across distribution tiers.
REACH registration in Europe mandates comprehensive toxicological dossiers for cosmetic-grade anhydroxylitol, while the FDA exercises oversight through cosmetic ingredient safety guidelines that shape product liability exposure for US market entrants. China's SAMR enforces GB standards for food additive derivatives that constrain cross-application sourcing flexibility. Stakeholders must monitor regulatory divergence between pharmaceutical and cosmetic classification regimes to anticipate reformulation costs and market access barriers.
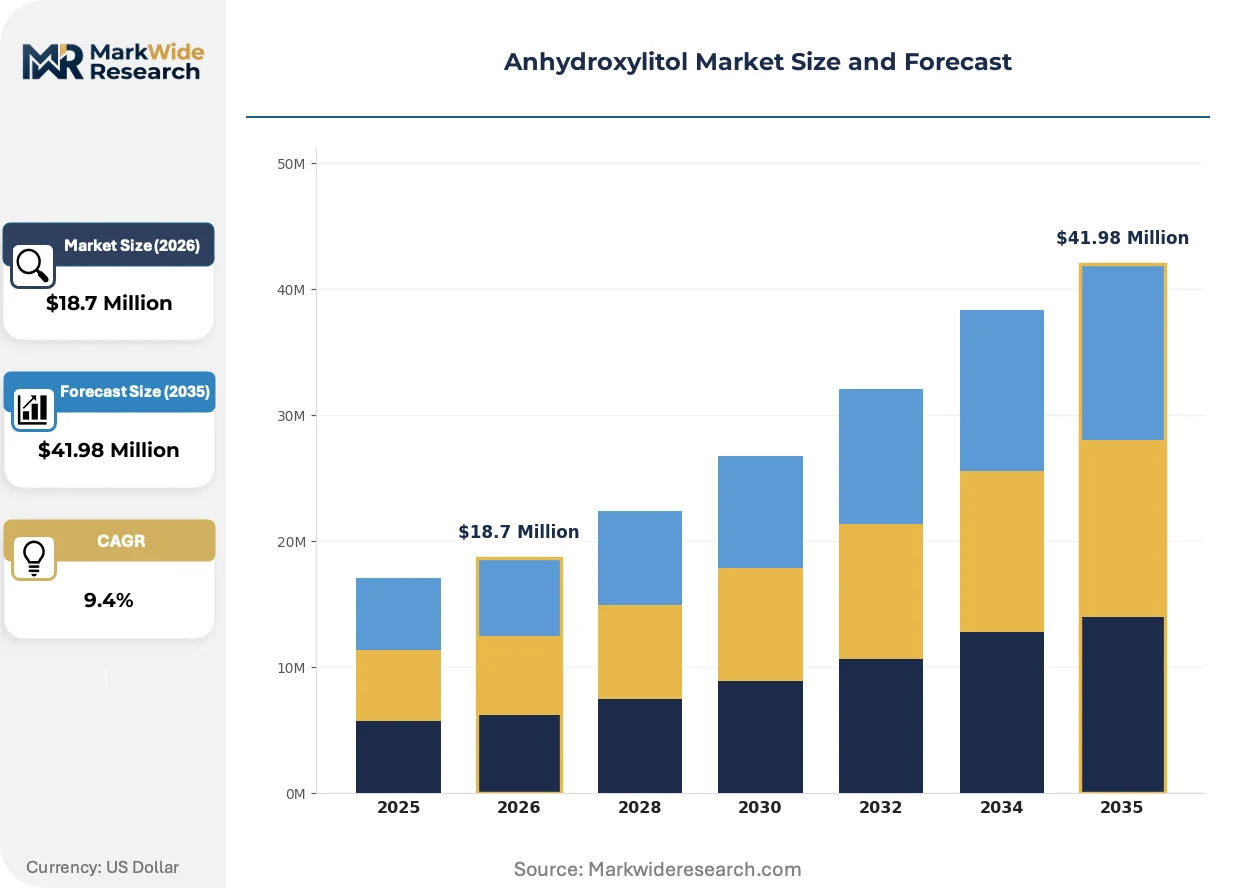
Market Dynamics
Cosmetics manufacturers are consolidating procurement around carbohydrate-derived humectants as REACH compliance and green chemistry mandates tighten purity specifications across European and Asian supply chains.
Growth Catalysts
- Biobased feedstock mandates:EU Green Deal targets are accelerating substitution of petroleum-derived moisturizers with plant-based sugar alcohol derivatives in personal care formulations.
- South Korea's beauty cluster expansion:K-beauty OEMs are scaling anhydroxylitol integration into multi-step skincare routines for export markets.
- Acid-catalyzed dehydration advances:Continuous processing technologies are reducing xylitol conversion costs and enabling pharmaceutical-grade purity at commercial scale.
Market Restraints
- Xylitol feedstock volatility:Birch wood and corn cob supply fluctuations in Nordic and North American regions create input cost instability for derivative production.
- Chinese pharmaceutical corridor concentration:Overreliance on Shandong and Jiangsu province manufacturing clusters exposes buyers to localized environmental enforcement disruptions.
- Technical substitution pressure:Ectoine and saccharide isomerates are displacing anhydroxylitol in premium dermocosmetic formulations requiring extended moisture retention.
Strategic Opportunities
- India's nascent cosmetics manufacturing:PLI scheme incentives for personal care ingredient localization are opening contract manufacturing demand for imported anhydroxylitol formulations.
- Nutraceutical encapsulation convergence:Lipid-sugar alcohol hybrid delivery systems are creating dual-use demand across functional food and topical therapeutic segments.
- Direct-to-brand digital channels:E-procurement platforms are enabling mid-tier cosmetics formulators to bypass traditional distributor markups on specialty humectants.
Industry Challenges
- REACH dossier compilation timelines:Extended toxicological study requirements for cosmetic-grade registration are delaying European market entry for new suppliers.
- Cross-application certification complexity:Divergent GB standards under SAMR and FDA cosmetic ingredient guidelines force parallel compliance investments for multi-territory brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anhydroxylitol Market |
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $41.98 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granule, Liquid, Tablet Application: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals End User: Manufacturers, Retailers, Distributors, Online Sellers Distribution Channel: Direct Sales, E-commerce, Wholesale, Retail |
| Companies Covered | BeOnMe, PureBulk, Seppic, The Mom's Co., St.Botanica, AXIS-Y, Roquette Frères, DuPont de Nemours, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anhydroxylitol Market Evolving Landscape
Technology integration and regulatory fragmentation are simultaneously compressing formulation cycles and expanding purity requirement tiers across personal care and pharmaceutical applications.
Continuous flow dehydration systems are consolidating xylitol-to-anhydroxylitol conversion economics. Contract manufacturers in South Korea's Incheon cluster are adopting these systems to serve K-beauty brands demanding pharmaceutical-grade consistency. The technology is consolidating mid-tier producers into fewer, higher-capability supply nodes capable of dual cosmetic-pharmaceutical certification.
REACH registration updates under ECHA's 2023-2027 substance evaluation roadmap are expanding toxicological data requirements for cosmetic-grade sugar alcohol derivatives. Formulators must now submit extended dermal sensitization studies to maintain market access. European mid-tier brands are responding by consolidating supplier relationships with established REACH-registered producers rather than qualifying new entrants.
Long-term supply agreements with volume-tier pricing are displacing spot-market purchasing among cosmetics OEMs. South Korean and Chinese formulators are locking eighteen-to-twenty-four-month contracts to secure anhydroxylitol allocations amid feedstock volatility. This pattern is most visible in Shanghai's contract manufacturing corridor, where procurement teams are trading price flexibility for supply security.
Anhydroxylitol Market Segmentation
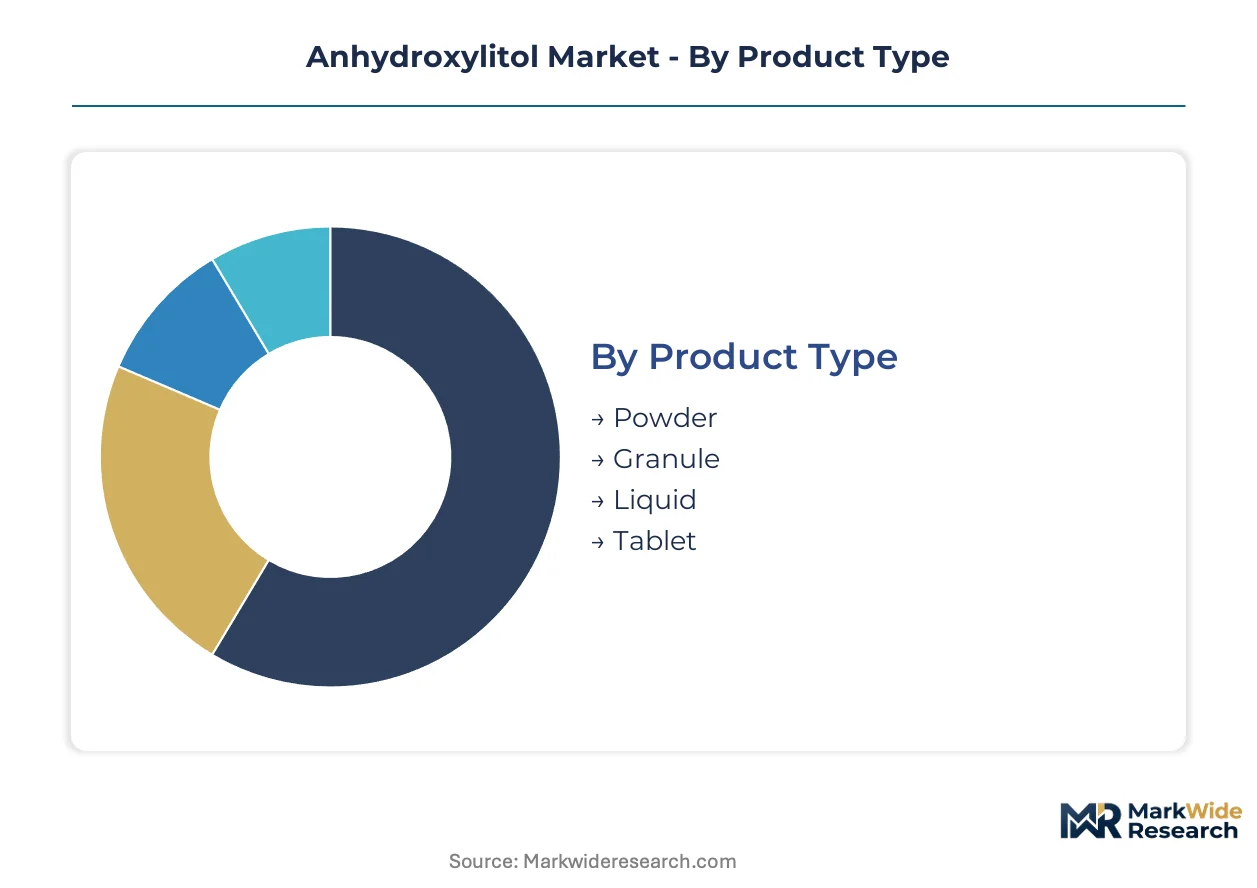
Segmentation in anhydroxylitol tracks how physical form, regulatory classification, and channel access fragment pricing power and certification requirements across overlapping end-use markets. Each axis reveals distinct margin structures and compliance burdens that shape supplier strategy.
Product Type:
Physical state determines handling infrastructure, shelf stability, and formulation integration costs for downstream compounders.
- Powder:White crystalline material with hygroscopic properties and melting point near 92 degrees Celsius, manufactured through acid-catalyzed dehydration of xylitol feedstock. Bulk compounders in China's pharmaceutical corridor favor powder for handling efficiency in high-volume operations, though moisture sensitivity necessitates climate-controlled warehousing.
- Liquid:Ready-to-use aqueous solutions eliminating reconstitution steps for contract manufacturers. South Korean K-beauty OEMs are scaling liquid procurement fastest as multi-step skincare routines demand seamless humectant integration.
- Granule:Intermediate particle size offering flowability advantages for tableting operations. Nutraceutical encapsulators in India's emerging manufacturing cluster specify granule grades for direct compression applications.
- Tablet:Pre-compressed dosage forms serving therapeutic and functional food segments requiring precise unit dosing. SAMR's GB standards for food additive derivatives constrain cross-application sourcing flexibility for this format.
Powder leads on scale; liquid leads on momentum.
Application:
Regulatory jurisdiction and certification tier create divergent purity requirements and pricing bands across end-use categories.
- Cosmetics:Broadest demand base spanning mass-market skincare through premium dermocosmetics. REACH registration mandates comprehensive toxicological dossiers that consolidate procurement around established European suppliers.
- Nutraceuticals:Lipid-sugar alcohol hybrid delivery systems are creating dual-use demand across functional food and topical therapeutic segments, commanding premium positioning due to stringent certification requirements.
- Pharmaceuticals:Excipient and active ingredient applications governed by pharmacopeial monographs. EMA and FDA oversight shapes product liability exposure and forces parallel compliance investments.
- Food & Beverage:Humectant and stabilizer functions in processed foods subject to EFSA and FSSAI additive approvals. Green chemistry mandates under EU Green Deal are accelerating substitution of petroleum-derived alternatives.
Cosmetics leads on scale; nutraceuticals leads on momentum.
End User:
Procurement sophistication and volume scale separate volume-tier contract negotiations from spot-market fragmentation.
- Manufacturers:Cosmetics formulators and pharmaceutical compounders locking eighteen-to-twenty-four-month supply agreements to secure allocations amid xylitol feedstock volatility.
- Distributors:Traditional channel intermediaries facing margin compression as e-procurement platforms enable direct brand relationships.
- Retailers:Finished goods sellers with limited ingredient sourcing exposure, primarily relevant for private-label nutraceutical lines.
- Online Sellers:Digital-native brands leveraging direct-to-manufacturer procurement to bypass traditional distributor markups on specialty humectants.
Manufacturers lead on scale; online sellers lead on momentum.
Distribution Channel:
Channel selection reflects buyer scale, geographic reach requirements, and technical service needs for formulation support.
- Direct Sales:Long-term agreements with volume-tier pricing dominating procurement among South Korean and Chinese formulators trading price flexibility for supply security.
- Wholesale:Regional distributors serving mid-tier brands lacking scale for manufacturer-direct relationships.
- E-commerce:B2B platforms consolidating mid-tier producer access for buyers seeking pharmaceutical-grade consistency without established supplier relationships.
- Retail:Minimal relevance for bulk ingredient procurement, limited to small-scale nutraceutical and cosmetic compounders.
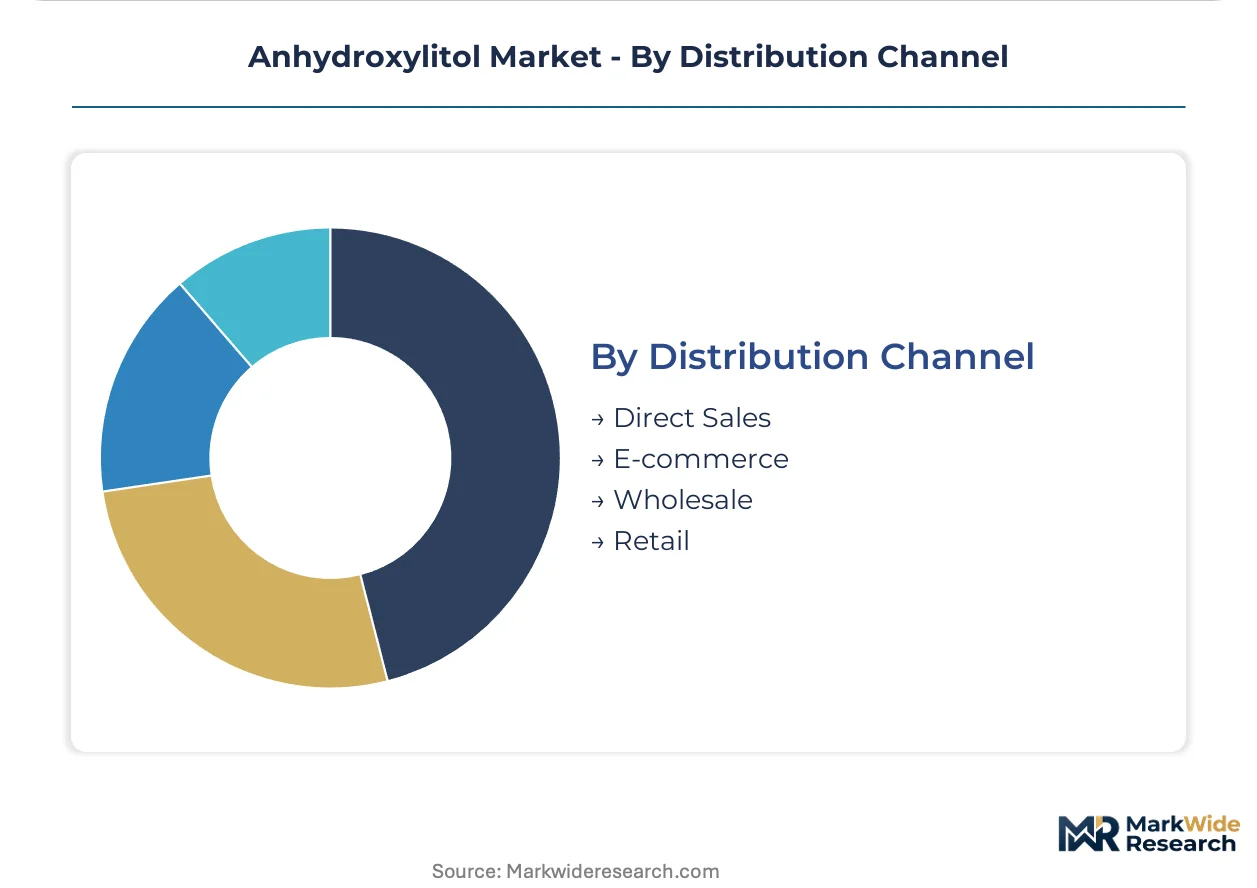
Direct sales leads on scale; e-commerce leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled formulation chemists cluster in South Korea's Incheon beauty corridor and China's Shandong pharmaceutical belt, anchoring anhydroxylitol demand across dual cosmetic-pharmaceutical supply chains.
South Korea
K-beauty OEMs scale anhydroxylitol integration into multi-step skincare routines for export markets. MFDS cosmetic ingredient safety guidelines shape product liability frameworks for domestic formulators. The Incheon manufacturing cluster adopts continuous flow dehydration systems to serve brands demanding pharmaceutical-grade humectant consistency.
China
Shandong and Jiangsu province manufacturers concentrate xylitol-to-anhydroxylitol conversion capacity for domestic and export pharmaceutical corridors. SAMR's GB standards for food additive derivatives constrain cross-application sourcing flexibility. Environmental enforcement disruptions in these coastal clusters periodically expose buyers to localized supply interruptions.
United States
Contract manufacturers serving clean beauty brands accelerate procurement of plant-derived humectants as petroleum-substitution preferences harden. FDA cosmetic ingredient safety guidelines shape liability exposure for market entrants. Midwest corn belt proximity to xylitol feedstock sources supports derivative production economics for regional compounders.
Germany
REACH-registered European suppliers consolidate procurement relationships as mid-tier brands avoid new entrant qualification delays. ECHA's substance evaluation roadmap expands toxicological data requirements for cosmetic-grade sugar alcohol derivatives. The country's carbohydrate processing heritage anchors supply chain credibility for pharmaceutical-grade specifications.
India
PLI scheme incentives for personal care ingredient localization open contract manufacturing demand for imported anhydroxylitol formulations. FSSAI additive approvals govern humectant applications in processed food derivatives. Maharashtra and Gujarat emerging manufacturing clusters specify granule grades for nutraceutical encapsulation and direct compression operations.
Anhydroxylitol Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered certification requirements. Market structure consolidates around established REACH-registered producers capable of dual cosmetic-pharmaceutical compliance. Three archetypes dominate: carbohydrate heritage processors leveraging feedstock integration, specialized emollient portfolio builders, and biotech platform operators sustaining quality consistency. Capacity expansion and strategic partnerships constitute the dominant competitive vectors as feedstock volatility pressures supply security.
Within the carbohydrate heritage tier, Roquette Frères exemplifies European supply chain anchoring through feedstock processing integration. Seppic occupies a position among specialized emollient portfolio builders competing through high-performance skin care integration. DuPont de Nemours sits within the biotech platform operator archetype extending quality consistency frameworks across pharmaceutical-grade specifications.
| Leading Market Players |
|---|
| BeOnMe |
| PureBulk |
| Seppic |
| The Mom's Co. |
| St.Botanica |
| AXIS-Y |
| Roquette Frères |
| DuPont de Nemours |
| Cargill |
| Others |
Value Network & Pricing Analysis
Family-owned Nordic birch processors anchor upstream xylitol supply, translating feedstock scarcity into disciplined contract pricing that favors long-term offtake over spot-market volatility. Their ownership structure sustains patient capital allocation toward acid-catalyzed dehydration capacity, compressing margin flexibility for downstream derivative buyers locked into eighteen-to-twenty-four-month procurement cycles.
Pricing Analysis
Bundled technical service contracts separate premium-tier suppliers from commodity traders, with REACH-registered European producers commanding 15-25% uplifts for toxicological dossier inclusion. Pharmaceutical-grade certification and volume scale differentiate pricing bands, while cost compression in standard cosmetic grades intensifies as Chinese Shandong manufacturers expand continuous-flow capacity. Mid-tier K-beauty OEMs exhibit highest price sensitivity, whereas nutraceutical encapsulators accept premium positioning for dual-use lipid-sugar alcohol hybrid systems.
Supply Chain Analysis
Xylitol feedstock rests on Nordic birch wood and North American corn cob suppliers, with derivative conversion concentrating in China's Shandong-Jiangsu corridor and South Korea's Incheon cluster. Acid-catalyzed dehydration catalysts, climate-controlled warehousing infrastructure, and MFDS-compliant quality systems constitute critical input dependencies. Single-source vulnerability in Chinese coastal manufacturing exposes buyers to localized environmental enforcement disruptions. Distribution runs through direct manufacturer relationships for volume-tier formulators, supplemented by B2B e-procurement platforms serving mid-tier brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anhydroxylitol functions as a stable compounder, with biobased feedstock mandates under the EU Green Deal ensuring steady substitution demand across personal care formulations.
For Market Incumbents: Acquire continuous-flow dehydration technology assets to consolidate conversion economics and defend against ectoine substitution in premium dermocosmetics. Lock long-term birch and corn cob supply agreements in Nordic and North American regions to neutralize input volatility. Prioritize dual cosmetic-pharmaceutical certification investments to maintain REACH-registered supplier status as ECHA expands toxicological data requirements. For New Entrants and Emerging Players: Begin with India's PLI scheme-incentivized contract manufacturing corridor, where granule-grade nutraceutical encapsulation demand outstrips local supply capability. Target Maharashtra and Gujarat emerging clusters for direct compression applications. Establish e-procurement platform presence to bypass traditional distributor markups and capture mid-tier cosmetics formulator procurement shifts. For Investors and Strategic Acquirers: Carbohydrate heritage processors with integrated feedstock positions are the most active acquirer in this space, seeking pharmaceutical-grade certification capabilities. Five-to-ten-year viability hinges on backward integration into xylitol production and dual-use lipid-sugar alcohol hybrid delivery system development. Monitor ECHA substance evaluation roadmap acceleration as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Xylitol Feedstock | Captive birch and corn cob supply neutralizes Nordic and North American input cost volatility for derivative producers. |
| Continuous Flow Dehydration Capacity Expansion | South Korean Incheon cluster adoption enables pharmaceutical-grade purity at commercial scale for K-beauty OEMs. |
| Dual Cosmetic-Pharmaceutical Certification Investment | REACH registration and MFDS compliance unlock premium pricing tiers across European and Asian regulatory jurisdictions. |
| Long-term Supply Agreement Structuring | Eighteen-to-twenty-four-month contracts with volume-tier pricing secure allocations amid Shandong environmental enforcement disruptions. |
| Lipid-Sugar Alcohol Hybrid Delivery System Development | Nutraceutical encapsulation convergence creates dual-use demand across functional food and topical therapeutic segments. |
Research Methodology
Bottom-up cosmetics and nutraceuticals formulation modeling reconciled against top-down carbohydrate derivative production tracking forms the analytical core of this study. Primary interviews with plant managers at xylitol conversion facilities, procurement leads at K-beauty OEMs, technical R&D directors at humectant formulators, and distribution channel partners in South Korea and China were validated against secondary sources including ECHA REACH registrations, SAMR GB standards filings, customs and trade data for sugar alcohol derivatives, and SEC 10-K disclosures from diversified chemical producers.
Historical trendline analysis of xylitol-to-anhydroxylitol conversion capacity additions, feedstock price movements, and certification timeline completions informed the projection framework. Segmentation modeling tracked physical form, application regulatory tier, and end-user procurement sophistication across the analysis window. CAGRs were derived from volume-weighted average growth trajectories, with specific inputs including EU Green Deal biobased mandate implementation pace and South Korean beauty cluster export expansion rates.
Several conditions sit outside the modeled scope, including unforeseen ECHA regulatory acceleration, birch wood supply disruptions from Nordic forestry policy shifts, and breakthrough substitution by saccharide isomerates in premium segments. Forecasts reflect documented assumptions about continuous processing technology diffusion and contract manufacturing localization incentives. A small set of named triggers warrants ongoing watch: EMA pharmacopeial monograph updates, SAMR cross-application sourcing restriction tightening, and MFDS cosmetic ingredient safety guideline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Myrcene Market
Specialty Chemicals
Fe EDDHA Market
Specialty Chemicals
Viscoelastic Agents Market
Specialty Chemicals
Global Non-Halogenated Flame Retardants Market
Specialty Chemicals
Sandarac Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Microcrystalline Wax Market
Specialty Chemicals
Pyrrolidone Market
Specialty Chemicals
Undecylenic Acid Market
Specialty Chemicals
Ricinoleic Acid Market
Specialty Chemicals
LAMEA Metal Biocides Market
Specialty Chemicals
GLDA Market
Specialty Chemicals
Dehazer Market
Specialty Chemicals
Acesulfame Potassium Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Magnesium Gluconate Market