
 High-K and CVD ALD Metal Precursors Market | 2026-2036
High-K and CVD ALD Metal Precursors Market Size, Share, and Industry Trends Forecast 2026-2036
High-K and CVD ALD Metal Precursors Market Intelligence
Specialty chemical producers in South Korea and Japan are decoupling precursor synthesis from bulk chemical sourcing, aiming to secure supply chains for next-generation fabs. This shift creates distinct competitive arenas. Entegris, Inc. specializes in high-purity material handling and delivery systems integral to precursor use. Air Liquide leverages its vast industrial gas infrastructure to supply both carrier gases and precursor materials, while Sumitomo Chemical Co., Ltd. competes through its development of novel organometallic compounds for advanced ALD processes.
High-k and CVD ALD metal precursors are organometallic or metal-halide compounds engineered for high volatility and thermal stability. Their primary purpose is to serve as the chemical source material in atomic layer deposition (ALD) and chemical vapor deposition (CVD) processes for creating atomically precise thin films. Within the product landscape, hafnium oxide precursors dominate due to their critical role in transistor gate dielectrics. Demand for titanium nitride precursors is also significant for creating conductive barriers and electrodes in advanced interconnect applications.
The handling and transport of these volatile chemicals are governed by stringent regulations, including the EU's REACH framework and US EPA rules on chemical substance reporting. Furthermore, ISO 9001 quality management standards are critical for ensuring the ultra-high purity required by semiconductor manufacturers. Strategic decisions for suppliers will center on navigating the increasing regionalization of semiconductor supply chains while protecting intellectual property for novel precursor formulations.
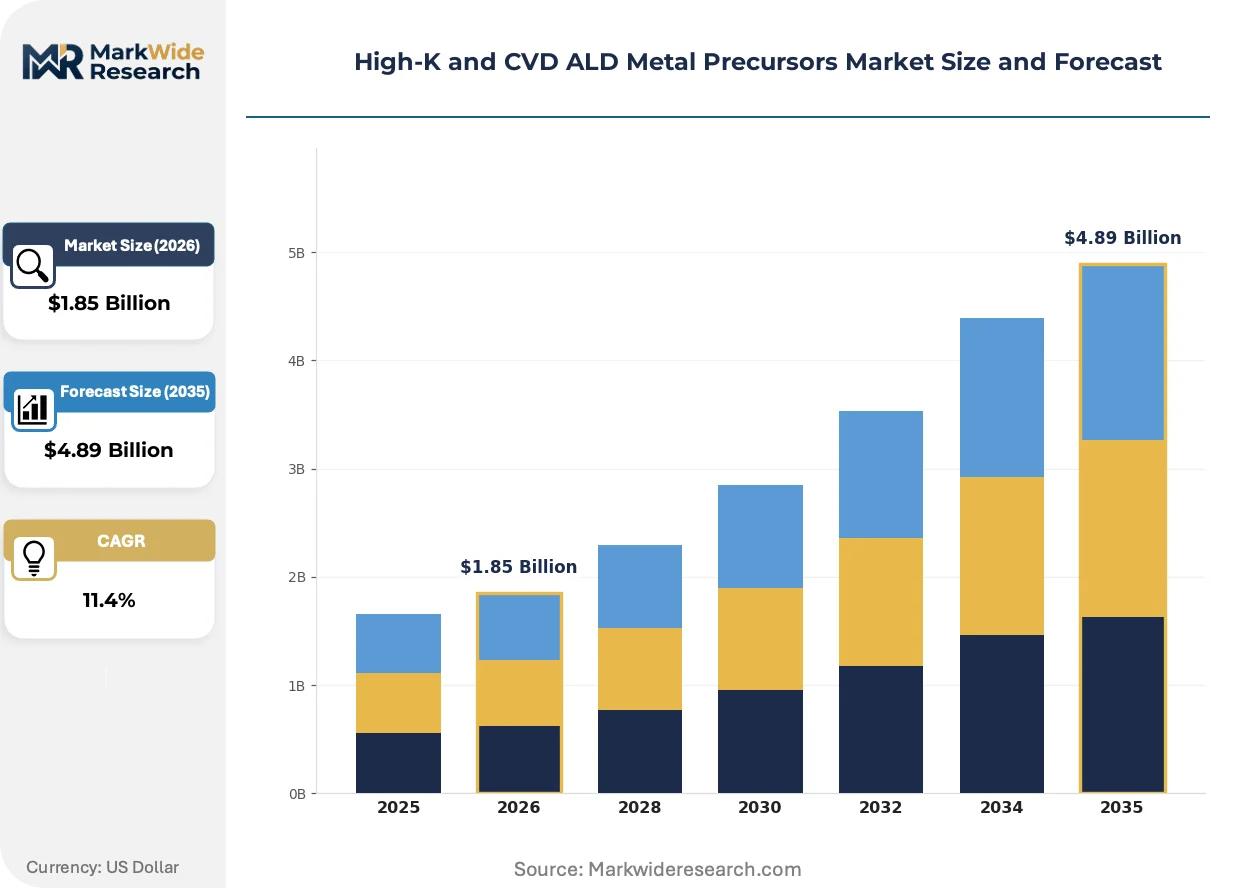
Market Dynamics
The transition to gate-all-around (GAA) transistor architectures is the central force shaping the market. This technological inflection requires entirely new classes of metal precursors to construct atomic-scale device components, driving intense R&D and supply chain realignment.
Growth Catalysts
- Gate-All-Around (GAA) Adoption:The shift to GAA logic architectures requires new material sets, stimulating demand for novel hafnium and ruthenium organometallic compounds.
- 3D Memory Scaling:Higher layer counts in 3D NAND and DRAM boost volume consumption of tungsten and titanium nitride precursors for critical deposition steps.
- Foundry Investment in Asia:Concentrated capital spending on new fabs in Taiwan and South Korea creates geographically dense demand for high-volume precursor supply.
Market Restraints
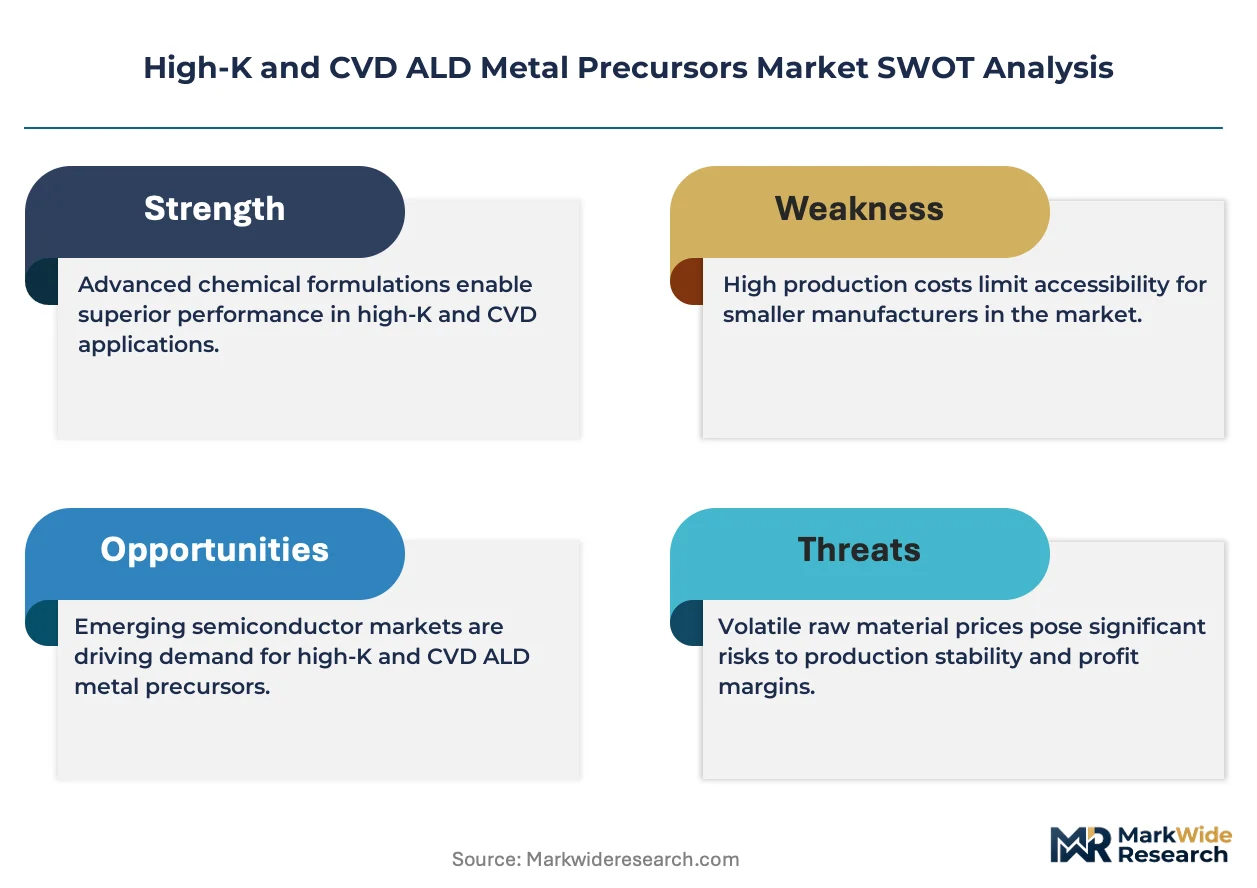
- Input Metal Volatility:The supply of critical metals like hafnium is highly concentrated, creating price instability and supply risk for precursor producers.
- Hazardous Material Logistics:Strict transport regulations under frameworks like REACH increase shipping costs and compliance burdens for volatile organometallics.
- Purity-Driven Yield Loss:Achieving the required parts-per-billion purity for advanced nodes is difficult, leading to lower synthesis yields and higher manufacturing costs.
Strategic Opportunities
- Next-Generation Memory Materials:Developing precursors for emerging memories like MRAM, which use materials such as cobalt, offers a significant new growth vector.
- Regional Synthesis Hubs:US and EU chip-manufacturing incentives create opportunities to build precursor plants closer to new fabs, localizing the supply chain.
- Advanced Delivery Systems:Innovating liquid injection systems that provide better flow control than traditional bubblers presents a key opportunity for process enhancement.
Industry Challenges
- Intellectual Property Protection:Balancing collaborative R&D with foundries against the risk of IP leakage for novel precursor formulations is a persistent operational challenge.
- Talent Scarcity:A shortage of organometallic chemists with experience in ultra-high-purity synthesis constrains industry growth and innovation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-K and CVD ALD Metal Precursors Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Oxide, Hafnium Oxide, Tantalum Nitride, Titanium Nitride End User: Semiconductor Manufacturers, Research Laboratories, Electronic Device Makers, Academia Delivery Mode: Liquid Delivery, Solid Delivery, Vapor Delivery, Gas Delivery Application: Transistors, Capacitors, Interconnects, Dielectrics |
| Companies Covered | The Dow Chemical Company, Entegris, Inc., Air Liquide, JSR Corporation, ADEKA Corporation, Linde plc, Samsung Electronics, Sumitomo Chemical Co., Ltd., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-K and CVD ALD Metal Precursors Market Strategic Shifts & Innovations
Intensifying material science requirements for atomic-scale manufacturing are fundamentally altering the precursor market. The focus is shifting from bulk chemical supply to the co-development of precisely engineered molecules designed for specific integration challenges in next-generation semiconductor devices.
Selective deposition precursors are compounds engineered for material growth only on specific surfaces, such as metal, while preventing it on dielectrics. Advanced logic manufacturers are rapidly adopting these materials to simplify fabrication and reduce defectivity. This bottom-up, additive approach is overtaking traditional subtractive etch processes for creating critical device features.
The European Union's Corporate Sustainability Reporting Directive (CSRD) compels chemical suppliers to provide extensive data on their products' environmental lifecycle. This forces precursor manufacturers to quantify the carbon footprint of synthesis, purification, and logistics. Suppliers to European fabs are now investing in lifecycle assessment tools to ensure compliance and maintain market access.
A shift toward deep co-development partnerships between foundries and precursor suppliers is standard for leading-edge nodes. This model supplants transactional purchasing by embedding supplier chemists within fab R&D teams to accelerate bespoke material qualification. This collaborative trend is most visible in Taiwan and South Korea, where foundries require custom formulations for proprietary process flows.
High-K and CVD ALD Metal Precursors Market Segmentation
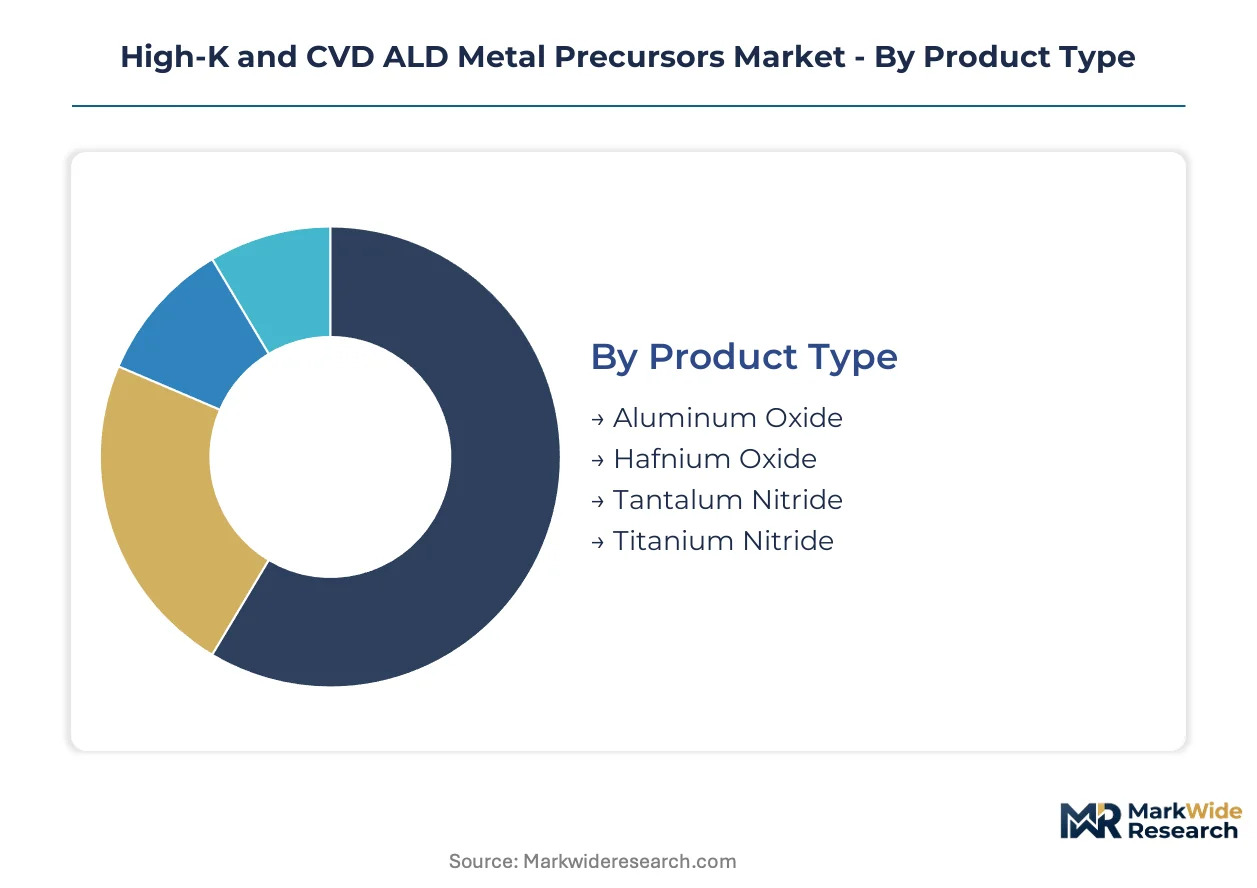
Segmentation reveals how different material compositions and delivery methods address specific manufacturing challenges in advanced semiconductor fabrication. Understanding these distinctions helps suppliers align product development with evolving process requirements. This market analysis categorizes precursors by their chemical nature, target users, handling methods, and ultimate device function.
Product Type:
The capital intensity associated with producing high-purity metal precursors varies significantly across different product types, reflecting the complexity of synthesis and purification processes.
- Hafnium Oxide:These organometallic compounds serve as gate dielectrics in advanced transistors, providing superior insulation and enabling smaller device geometries. Demand concentrates in leading-edge foundry production within Taiwan, driven by the shift to gate-all-around architectures.
- Titanium Nitride:Used as a conductive barrier layer and electrode material, titanium nitride precursors enhance device performance and reliability in interconnect applications. Its use is critical for scaling 3D NAND memory and advanced logic devices.
- Aluminum Oxide:Precursors for aluminum oxide provide robust insulating layers and passivation films in various semiconductor components.
- Tantalum Nitride:These compounds form diffusion barriers and adhesion layers in advanced metallization schemes for integrated circuits.
Hafnium Oxide precursors absorb the bulk of installed capacity due to their widespread use; Titanium Nitride precursors are expanding most quickly for advanced interconnects.
End User:
The volume requirements for high-k and CVD ALD metal precursors differ substantially across various end-user categories, directly influencing procurement strategies.
- Semiconductor Manufacturers:These entities require ultra-high purity precursors in large volumes for mass production of integrated circuits, including logic, memory, and power devices. Demand is concentrated in major semiconductor hubs like South Korea and Taiwan, supporting advanced node fabrication.
- Electronic Device Makers:Companies producing specialized electronic components or modules often source precursors for in-house advanced packaging or sensor fabrication. Their requirements can be highly customized for specific product lines and integration challenges.
- Research Laboratories:These facilities utilize precursors for material science investigations, process optimization, and prototype development of novel device structures.
- Academia:Universities and educational institutions employ precursors for fundamental research, student training, and exploring new material applications in nanotechnology.
Semiconductor Manufacturers represent the largest consumer base for these advanced materials; Electronic Device Makers are gaining share fastest as they integrate more complex components.
Delivery Mode:
The choice of precursor delivery mode is dictated by the specific application's requirements for precise dosing, material stability, and process integration complexity.
- Liquid Delivery:This method involves bubbling a carrier gas through a liquid precursor or using a liquid injection system, offering precise flow control and high material utilization. It is widely adopted for organometallic compounds requiring controlled evaporation into the reaction chamber.
- Vapor Delivery:Precursors delivered as a pure vapor stream, often generated from a heated solid or liquid source, ensure high purity and consistent deposition rates. This mode is critical for atomic layer deposition processes requiring precise, pulsed material introduction.
- Solid Delivery:Solid precursors are sublimated or evaporated directly into the process chamber, suitable for compounds with appropriate vapor pressure characteristics.
- Gas Delivery:Precursors that are gaseous at room temperature are delivered directly, offering simplicity for certain chemical vapor deposition applications.
Liquid Delivery systems remain foundational for many ALD processes; Vapor Delivery is climbing the fastest as next-generation ALD techniques mature.
Application:
The margin profile for high-k and CVD ALD metal precursors varies significantly across different applications, reflecting the value added by precise material integration.
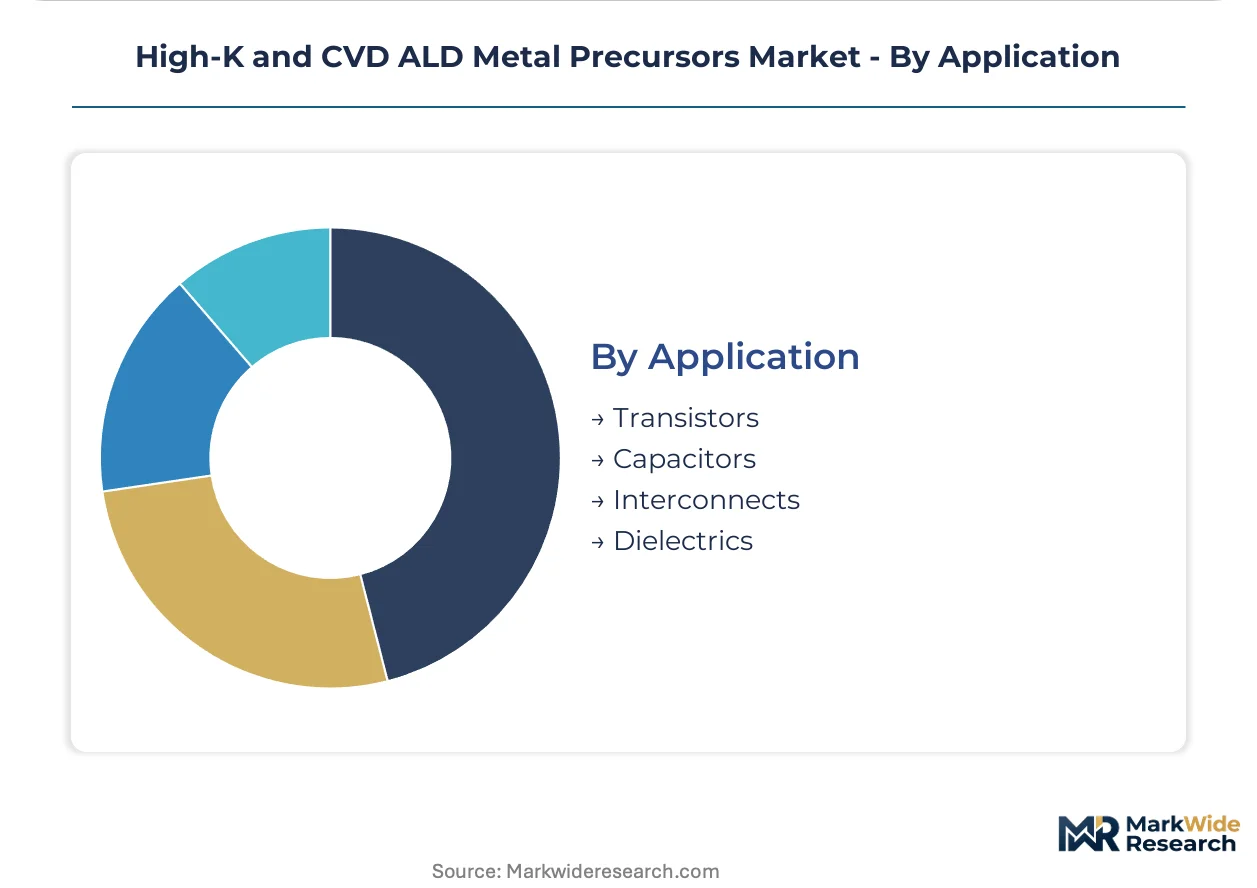
- Transistors:Precursors are essential for forming high-k gate dielectrics and metal gates in advanced logic and memory transistors, enabling higher performance and lower power consumption. The demand for these materials is directly linked to the scaling of GAA architectures.
- Interconnects:Metal precursors are used to create conductive lines, vias, and diffusion barriers within the complex wiring layers of integrated circuits. This application drives demand for materials like titanium nitride and tungsten precursors, crucial for signal integrity.
- Capacitors:Precursors form high-capacitance dielectric layers in memory devices and passive components, enhancing charge storage density.
- Dielectrics:These materials are used to create insulating layers throughout the semiconductor device structure, preventing electrical leakage and crosstalk.
Transistors represent the largest application area for high-k and CVD ALD metal precursors; Interconnects are on the steepest expansion trajectory as device complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan anchors global demand for high-k and CVD ALD metal precursors due to its dominant advanced semiconductor manufacturing. Its leading foundries drive the transition to gate-all-around (GAA) architectures. This necessitates a continuous supply of novel compounds.
Taiwan
Advanced foundry operations in Taiwan drive demand for hafnium oxide and ruthenium precursors for GAA logic architectures. Taiwan's Industrial Innovation Act incentivizes local R&D and manufacturing. Hsinchu Science Park remains a critical hub for material suppliers co-developing custom formulations.
South Korea
South Korean manufacturers require high volumes of titanium nitride and tungsten precursors for scaling 3D NAND and advanced DRAM. The nation's K-Semiconductor Strategy supports domestic material production. Foundries in Gyeonggi-do province intensify co-development efforts with chemical producers.
United States
New fab investments across the United States stimulate demand for advanced ALD metal precursors, especially for emerging memory materials. The US CHIPS and Science Act funds localization of semiconductor manufacturing and material supply. Arizona and New York are seeing new precursor plant developments.
Japan
Japanese specialty chemical producers innovate novel organometallic compounds for advanced ALD processes, serving domestic and international foundries. Japan's economic security legislation strengthens critical material supply chains and protects intellectual property. Kyushu remains a key area for precursor synthesis and R&D.
Germany
European chip manufacturing incentives foster demand for high-k and CVD ALD metal precursors, particularly for advanced logic. The EU's Corporate Sustainability Reporting Directive compels chemical suppliers to provide environmental data. Dresden is a central hub for semiconductor R&D, attracting precursor material investments.
High-K and CVD ALD Metal Precursors Market Key Industry Players
Global majors compete with regional champions across the high-purity material supply chain for advanced semiconductor manufacturing. The market exhibits a tiered structure, with established industrial gas companies, specialty chemical producers, and material handling specialists forming distinct competitive archetypes. Strategic moves involve securing supply chains for next-generation fabs, fostering deep co-development partnerships with leading foundries, and expanding regional synthesis hubs to localize production.
Specialists in high-purity material handling and delivery systems, such as Entegris, Inc., occupy a critical position in ensuring the precise use of volatile precursors. Industrial gas giants like Air Liquide leverage their extensive infrastructure to supply both carrier gases and precursor materials, exemplifying a broad service archetype that spans multiple supply chain nodes. Sumitomo Chemical Co., Ltd. represents the segment of specialty chemical producers focused on developing novel organometallic compounds, crucial for advanced ALD processes and next-generation device integration.
| Leading Market Players |
|---|
| The Dow Chemical Company |
| Entegris, Inc. |
| Air Liquide |
| JSR Corporation |
| ADEKA Corporation |
| Linde plc |
| Samsung Electronics |
| Sumitomo Chemical Co., Ltd. |
| Merck KGaA |
| Others |
Cost & Logistics Intelligence
Vertical integration into precursor synthesis anchors both the supply position and the pricing power for leading chemical suppliers. This strategic choice allows greater control over ultra-high purity material sourcing and advanced formulation IP.
Pricing Analysis
Warranty and service-level agreements are often bundled with precursor pricing, reflecting the critical need for ultra-high purity and consistent performance. The dominant pricing structure is contract-based long-term offtake, driven by substantial qualification costs and bespoke formulations. Price differentiation stems from material purity grades and the level of technical support provided. Pricing softness reflects intense competition for high-volume contracts in established segments, while semiconductor manufacturers remain least price-sensitive for leading-edge materials.
Supply Chain Analysis
Dual-sourcing requirements are standard practice for critical materials like hafnium and ruthenium precursors, mitigating supply risks for advanced fabs. Geographic supply concentration centers on Taiwan, South Korea, and Japan for high-volume production, creating regional dependencies. Raw material dependencies include hafnium, ruthenium, and tungsten, whose supply is highly concentrated and subject to commodity price volatility. Distribution runs through specialized logistics providers equipped for hazardous material transport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high-k and CVD ALD metal precursors market is in a vertical-integration race, with suppliers pursuing upstream control over critical raw material sourcing. This strategy ensures both purity and security of supply for advanced semiconductor manufacturing.
For Market Incumbents: Anchor existing relationships with leading foundries through embedded R&D teams and custom formulation co-development. Incumbents should expand regional synthesis hubs in the US and Europe to mitigate hazardous material logistics costs and regulatory scrutiny. This defends against emerging entrants targeting localized supply.
For New Entrants and Emerging Players: Begin with niche applications in emerging memories like MRAM, leveraging novel cobalt precursors where material qualification cycles may be shorter. New entrants should target electronic device makers seeking customized solutions for specialized packaging. A go-to-market angle focused on superior process integration offers differentiation.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty chemical producers with proprietary precursor synthesis or advanced delivery system IP. Long-term viability rests on securing critical raw material supply chains and deep co-development partnerships. A signal to watch is successful qualification of novel organometallic compounds for GAA architectures at high volume.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Regional Synthesis Hubs | Localizing precursor production in the US mitigates hazardous material logistics costs for regional fabs. |
| Deepen Foundry Co-Development | Embedding chemists within Taiwan's leading fabs accelerates custom material qualification for advanced process flows. |
| Invest in Advanced Delivery Systems | Innovating liquid injection systems improves flow control and material utilization for organometallic compounds. |
| Secure Critical Raw Material Offtakes | Long-term agreements for hafnium and ruthenium reduce input metal volatility risks for precursor producers. |
| Develop Novel Precursors for MRAM | Creating specialized cobalt compounds for emerging memory technologies offers a new growth vector for material suppliers. |
Research Approach
Multi-period observation of market growth rates and technology adoption curves anchored the trend analysis, supplemented by interviews with semiconductor manufacturing executives, material science R&D directors, and supply chain managers. Secondary validation drew from industry association reports, patent filings, and regulatory body publications from EPA and ECHA. The approach integrated bottom-up data collection with top-down market sizing triangulation.
Segment-weighting models were applied to project market expansion across the analysis window, considering product type, end user, delivery mode, and application. The framework also integrated regional economic growth and semiconductor capital expenditure plans. Compound annual growth rates were derived by assessing historical trends and anticipated technological advancements. Key forecast inputs included GAA transistor adoption rates and 3D NAND layer count projections.
Underlying measurement precision varies by segment; hafnium oxide and titanium nitride precursors carry tighter precision than others due to their established market presence. Forecasts reflect assumptions regarding technological roadmaps and geopolitical stability. Deviation in semiconductor capital expenditure or raw material supply could shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
Bismaleimide Market
Specialty Chemicals
Zinc Methionine Chelates Market
Specialty Chemicals
Sphingolipids Market
Specialty Chemicals
Europe Squalene Market
Specialty Chemicals
Eco-Friendly Plasticizers Market
Specialty Chemicals
Medical Propellants Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Global Tetrakis (Hydroxymethyl) Phosphonium Sulfate Market
Specialty Chemicals
Solar Cell Front Side Silver Paste Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Polycarboxylate Ethers (Pces) Market
Specialty Chemicals
US Post Laser Recovery Products Market
Specialty Chemicals
Global Prepacked Chromatography Columns Market