
 Isophytol Market | 2026-2036
Isophytol Market Size, Share, and Industry Trends Forecast 2026-2036
Isophytol Market Intelligence
China's expanding terpene chemistry base is reshaping isophytol feedstock availability for downstream formulators. BASF SE leverages its Ludwigshafen integrated aromatics complex to sustain captive isophytol output for vitamin E and fragrance precursors. Merck KGaA anchors pharmaceutical-grade supply chains with tight specification control for nutraceutical encapsulation. Haihang Industry competes on fermentation-derived routes, positioning cost-advantaged natural isophytol for Asian cosmetic manufacturers.
Isophytol is an acyclic diterpene alcohol with the molecular formula C20H34O, typically synthesized via geranylacetone reduction or extracted from plant-derived phytol through selective hydrogenation; it functions primarily as a fragrance intermediate, vitamin E precursor, and flavor carrier with characteristic floral-woody odor profile. Synthetic isophytol dominates volume throughput due to scale economies in petrochemical feedstock conversion, while natural isophytol commands premium positioning in clean-label fragrance and cosmetic additive segments where formulation houses restrict petrochemical-derived inputs. The nutraceutical application channel is gaining structural importance as pharmaceutical companies adopt isophytol in tocopherol synthesis for dietary supplement matrices.
ECHA REACH registrations govern substance identity and impurity thresholds for isophytol placed on the European market, while FDA oversight under 21 CFR applies to flavoring agent and cosmetic additive uses in the United States, creating divergent compliance burdens for multi-territory suppliers. China's SAMR enforces GB standards for food-grade terpene additives, affecting export eligibility for domestic manufacturers serving cross-border food and beverage clients. Stakeholders must monitor evolving biobased certification schemes and regional purity mandates to secure formulation partnerships ahead of specification tightening.
Market Dynamics
REACH compliance under ECHA is tightening purity thresholds for cosmetic-grade isophytol, forcing reformulators to recertify supply chains and concentrate procurement around Ludwigshafen-based producers with integrated hydrogenation capabilities.
Growth Catalysts
- Fine fragrance expansion:French and German fragrance houses are expanding procurement volumes for high-end perfume formulations, pulling pharmaceutical-grade material into cosmetic channels.
- Vitamin E precursor demand:Nutraceutical manufacturers are structurally increasing offtake for tocopherol synthesis as dietary supplement matrices diversify beyond synthetic antioxidants.
- Fermentation-derived routes:Bioprocess advances in Asian manufacturing bases are unlocking cost-advantaged natural isophytol for clean-label cosmetic additive segments.
Market Restraints
- Geranylacetone feedstock volatility:Petrochemical-derived precursors face price instability tied to cracker operating rates and naphtha arbitrage flows.
- Supply concentration risk:Captive production at Ludwigshafen and select Chinese terpene corridors creates geographic vulnerability for non-integrated formulators.
- Natural-synthetic specification divergence:Clean-label fragrance houses restrict petrochemical-derived inputs, fragmenting procurement pools and complicating inventory management.
Strategic Opportunities
- Biobased certification tailwinds:Emerging EU Green Deal-aligned schemes for renewable chemical content create premium positioning pathways for fermentation-derived producers.
- Asian cosmetic manufacturing:Underpenetrated demand from South Korean and Japanese skincare formulators offers volume expansion beyond European fragrance corridors.
- Encapsulation technology convergence:Advances in lipid nanoparticle delivery systems for nutraceuticals are opening pharmaceutical-grade specification contracts.
Industry Challenges
- REACH registration timelines:ECHA substance identity dossiers require 18-24 month certification cycles that delay new supplier market entry.
- Analytical chemistry skill scarcity:Diterpene alcohol impurity profiling at ppm thresholds demands specialized chromatography expertise concentrated at legacy producers.
- Multi-territory compliance burden:Divergent FDA 21 CFR and SAMR GB standards force parallel specification maintenance for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isophytol Market |
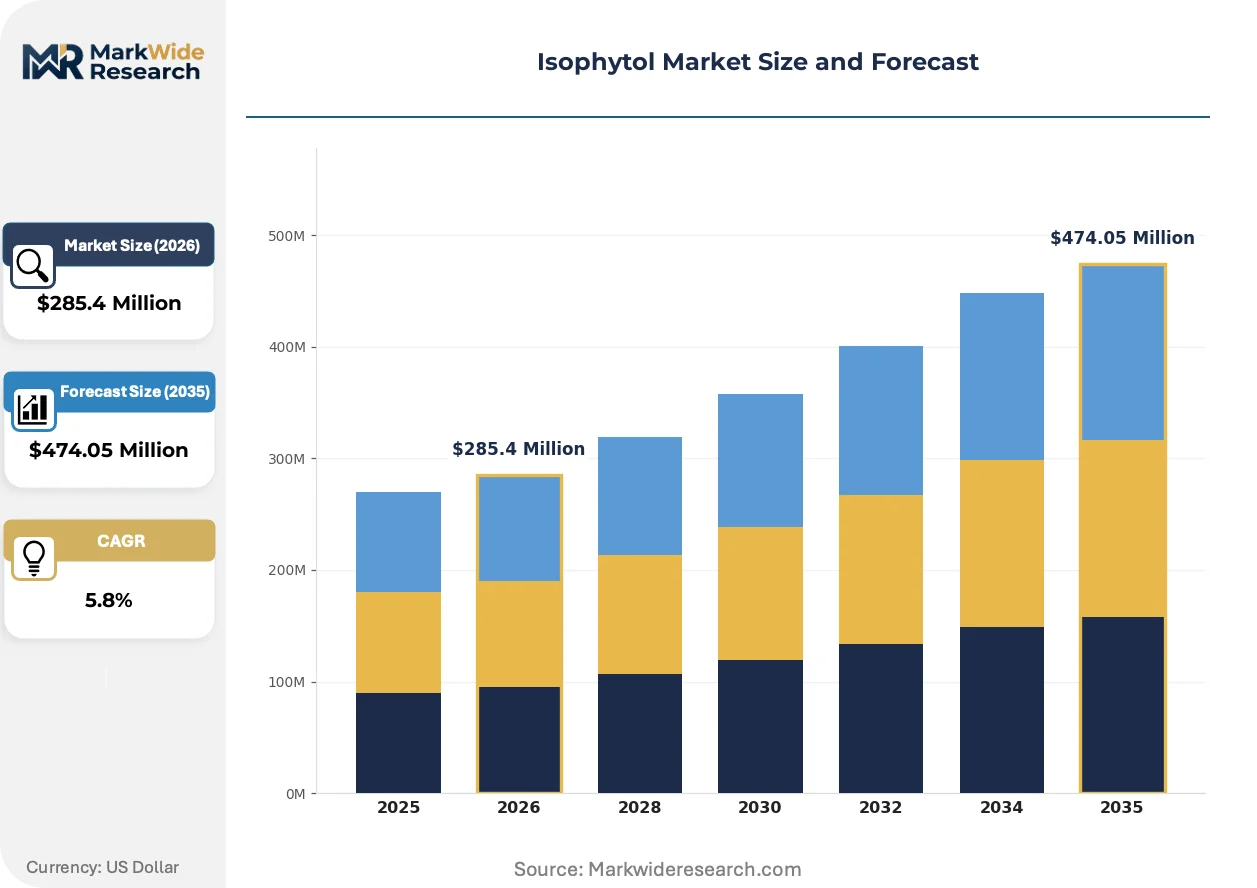
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Isophytol, Synthetic Isophytol, Isophytol Derivatives, Formulated Isophytol Application: Fragrance, Flavoring Agent, Cosmetic Additive, Nutraceutical End User: Personal Care Manufacturers, Food & Beverage Industry, Pharmaceutical Companies, Chemical Manufacturers Distribution Channel: Direct Sales, Distributors, Online Retail, Specialty Shops |
| Companies Covered | BASF SE, Thermo Fisher Scientific, Merck KGaA, Augustus Oils Ltd., Haihang Industry, Hefei TNJ Chemical Industry Co. Ltd., Biosynth Carbosynth, Molekula Group, Vigon International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isophytol Market Strategic Shifts & Innovations
Biocatalytic hydrogenation pathways are actively displacing conventional chemical reduction methods, compressing the cost structure for natural-grade material while forcing legacy petrochemical routes into commodity positioning.
Continuous-flow photochemical reduction of geranylacetone is rendering obsolete batch hydrogenation reactors in specialty chemical production. Mid-scale fragrance compounders in the Netherlands and Switzerland are piloting these systems to reduce solvent waste and thermal degradation of sensitive terpene structures. The technology is compressing capital intensity for entrants while eroding the scale advantages of integrated aromatics complexes.
ECHA REACH authorization amendments for CMR-classified impurities are tightening analytical thresholds for cosmetic-grade isophytol placed on the European market. The regulation is forcing reformulators to dual-source from registered suppliers with validated impurity profiles, disqualifying spot-market procurement. German and French fragrance houses are responding by locking multi-year offtake agreements with Ludwigshafen-based producers.
Direct contracting between fermentation-derived producers and clean-label formulators is bypassing traditional chemical distributor networks. Asian cosmetic manufacturers are establishing specification partnerships with bioprocess specialists, disintermediating European trading houses that historically controlled terpene alcohol flows. This channel compression is most visible in South Korean skincare supply chains, where formulation houses audit production facilities directly rather than relying on distributor certificates of analysis.
Isophytol Market Segmentation
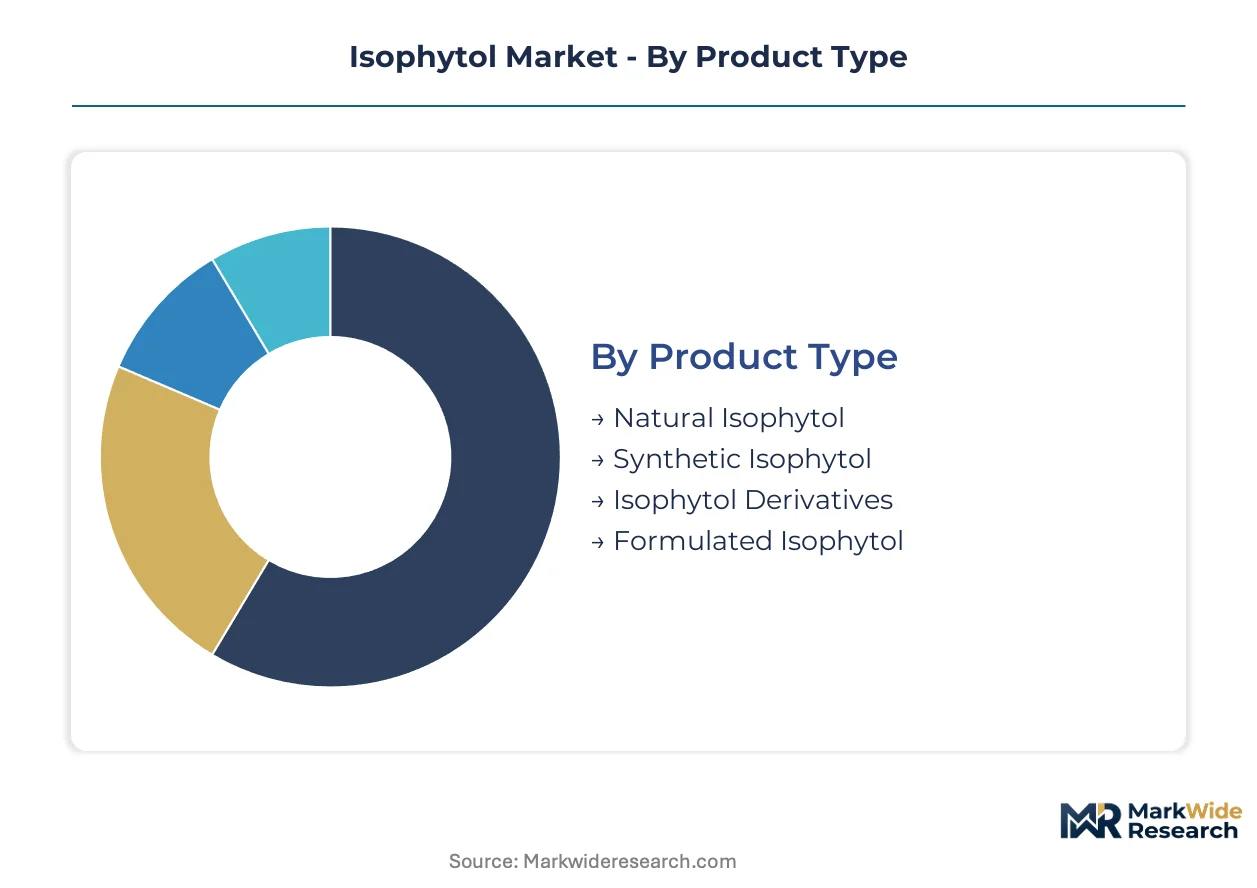
Isophytol procurement patterns diverge sharply across specification grades and end-use channels, with fragrance houses demanding pharmaceutical-grade purity while nutraceutical formulators prioritize tocopherol conversion efficiency. Segmentation clarity enables suppliers to align hydrogenation capabilities with the divergent analytical thresholds of cosmetic versus food-grade applications.
Product Type:
Mature petrochemical routes dominate volume throughput while fermentation-derived grades capture premium positioning in clean-label formulations.
- Natural Isophytol:Extracted from plant-derived phytol through selective hydrogenation, this grade commands price premiums in European fragrance corridors where ECHA REACH restrictions on petrochemical inputs are tightening. French and German perfume houses are locking multi-year offtake agreements with bioprocess specialists to secure supply chain transparency.
- Synthetic Isophytol:Manufactured via geranylacetone reduction in integrated aromatics complexes, this segment sustains captive output for vitamin E precursor synthesis at scale. BASF SE's Ludwigshafen facility anchors supply security for nutraceutical manufacturers requiring consistent tocopherol feedstock specifications.
- Isophytol Derivatives:Functionalized variants including esters and ethers serve specialized encapsulation applications in lipid nanoparticle delivery systems.
- Formulated Isophytol:Pre-blended concentrates reduce handling complexity for mid-scale cosmetic compounders in South Korea and Japan.
Synthetic Isophytol retains volume leadership; Natural Isophytol holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity flavoring uses from specification-intensive fragrance and pharmaceutical channels.
- Fragrance:Fine perfume formulations in France and Germany drive demand for high-purity material with sub-ppm impurity profiles, pulling pharmaceutical-grade supply into cosmetic channels as REACH thresholds tighten.
- Nutraceutical:Tocopherol synthesis for dietary supplement matrices is gaining structural importance as manufacturers diversify beyond synthetic antioxidants, with Merck KGaA anchoring pharmaceutical-grade specification control.
- Flavoring Agent:Food-grade applications under FDA 21 CFR and China's SAMR GB standards serve beverage and confectionery manufacturers.
- Cosmetic Additive:Skincare formulators in Asian markets audit production facilities directly, bypassing traditional distributor networks.
Fragrance commands premium pricing tiers; Nutraceutical applications are climbing the fastest.
End User:
Customer type determines specification stringency, with pharmaceutical companies imposing the tightest analytical thresholds and chemical manufacturers absorbing commodity-grade volume.
- Personal Care Manufacturers:South Korean and Japanese skincare formulators are establishing direct specification partnerships with fermentation-derived producers, disintermediating European trading houses.
- Pharmaceutical Companies:Nutraceutical encapsulation demands validated impurity profiles at ppm thresholds, concentrating procurement around legacy producers with specialized chromatography expertise.
- Food & Beverage Industry:Cross-border suppliers face parallel specification maintenance under divergent FDA and SAMR standards.
- Chemical Manufacturers:Mid-scale fragrance compounders in the Netherlands and Switzerland pilot continuous-flow photochemical reduction systems.
Personal Care Manufacturers are gaining share fastest; Pharmaceutical Companies retain specification leadership.
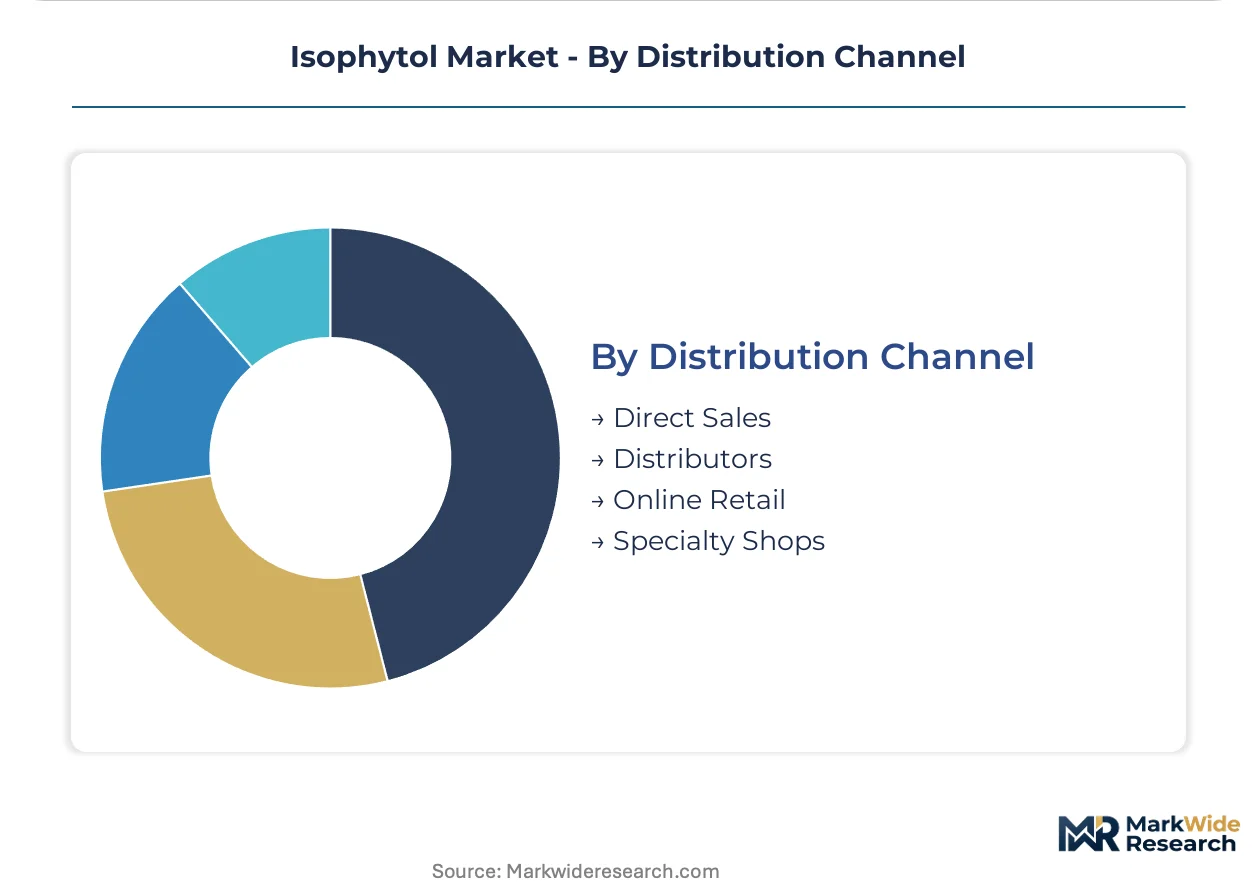
Distribution Channel:
Supply concentration shapes channel selection, with integrated producers favoring direct relationships while fragmented formulators rely on distributor networks.
- Direct Sales:Clean-label formulators in Asia are contracting fermentation-derived producers directly, compressing channel margins historically captured by European trading houses.
- Distributors:Spot-market procurement is disqualifying under ECHA REACH authorization amendments as reformulators dual-source from registered suppliers with validated dossiers.
- Online Retail:Small-volume cosmetic additive purchases by independent formulators are migrating to digital platforms.
- Specialty Shops:Niche fragrance ingredient suppliers in Paris and Grasse serve artisanal perfumers with curated natural-grade portfolios.
Direct Sales are expanding most quickly; Distributors retain legacy volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH registrations anchor European procurement protocols, with Ludwigshafen-based producers commanding specification leadership across fragrance and nutraceutical channels. Regional demand concentrates where integrated aromatics complexes and fermentation-derived bioprocess capabilities overlap.
Germany
Fine fragrance houses in Grasse and Paris source pharmaceutical-grade material through Rhine corridor logistics. ECHA authorization amendments for CMR-classified impurities tighten analytical thresholds, disqualifying spot-market procurement. BASF SE's Ludwigshafen facility sustains captive hydrogenation output for vitamin E precursor synthesis.
France
Perfume compounders in Paris and Grasse drive demand for sub-ppm impurity profiles in high-end formulations. ANSM cosmetic safety standards align with ECHA REACH dossier requirements, forcing dual-sourcing from registered suppliers. The Provence-Alpes-Côte d'Azur corridor concentrates artisanal natural-grade procurement.
China
Fermentation-derived producers in Zhejiang and Jiangsu provinces unlock cost-advantaged natural isophytol for Asian cosmetic manufacturers. SAMR GB standards for food-grade terpene additives govern export eligibility. The Yangtze River Delta bioprocess cluster is expanding fermentation capacity for clean-label fragrance feedstocks.
United States
Nutraceutical manufacturers under FDA 21 CFR oversight prioritize tocopherol conversion efficiency in dietary supplement matrices. Flavoring agent applications face divergent specification maintenance versus European cosmetic-grade requirements. New Jersey and California formulation hubs import registered European material for pharmaceutical-grade contracts.
South Korea
Skincare formulators in Seoul and Busan establish direct specification partnerships with fermentation-derived producers, bypassing European distributor networks. MFDS cosmetic safety regulations drive facility audit protocols rather than reliance on distributor certificates of analysis. The Seoul Capital Area concentrates encapsulation technology development for nutraceutical applications.
Isophytol Market Key Industry Players
Integrated petrochemical specialists and fermentation-derived bioprocess operators split the market between scale-driven synthetic output and premium natural-grade positioning. The vendor base concentrates around legacy hydrogenation capabilities in European chemical corridors and emerging Asian fermentation clusters. Three archetypes dominate: captive integrated producers with aromatics complex synergies, bioprocess specialists leveraging enzymatic routes, and mid-scale compounders piloting continuous-flow photochemical systems. Competitive moves center on backward integration into geranylacetone feedstock security and multi-year offtake agreements with REACH-registered suppliers.
Among Germany-based integrated producers, BASF SE exemplifies the captive hydrogenation archetype anchored to Ludwigshafen infrastructure. Merck KGaA represents pharmaceutical-grade specification control for nutraceutical encapsulation channels. Haihang Industry occupies a position within the Asian fermentation-derived tier, competing on natural-grade cost structures for cosmetic additive segments.
| Leading Market Players |
|---|
| BASF SE |
| Thermo Fisher Scientific |
| Merck KGaA |
| Augustus Oils Ltd. |
| Haihang Industry |
| Hefei TNJ Chemical Industry Co. Ltd. |
| Biosynth Carbosynth |
| Molekula Group |
| Vigon International |
| Others |
Cost & Logistics Intelligence
REACH registration timelines at ECHA determine both the three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and industrial-grade levels and the geographic configuration of approved supplier networks. Single-source dependency on Ludwigshafen-based hydrogenation capacity compresses margins for non-integrated formulators while amplifying premium capture for registered producers with validated impurity dossiers.
Pricing Analysis
Price spreads between German pharmaceutical-grade material and Chinese fermentation-derived cosmetic-grade supply exceed 40 percent on a per-kilogram basis. Contract-based long-term offtake agreements dominate high-purity channels, while spot procurement persists only for industrial-grade flavoring applications. Price differentiation hinges on REACH certification status and volume scale, with pharmaceutical companies least sensitive to cost and mid-scale fragrance compounders most exposed to margin compression. Pricing pressure stems from biocatalytic hydrogenation advances in Asian manufacturing bases eroding the cost advantage of legacy petrochemical routes.
Supply Chain Analysis
Tariff exposure between China and the European Union complicates procurement planning for cross-border cosmetic manufacturers. Supply concentrates in Germany, China, and Switzerland, with raw material flows drawing from geranylacetone petrochemical streams and plant-derived phytol fermentation stocks. Single-source vulnerability around BASF SE's Ludwigshafen integrated aromatics complex creates geographic concentration risk for vitamin E precursor supply. Distribution runs through direct sales partnerships for clean-label formulators and specialty chemical distributors for mid-scale compounders without REACH registration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The isophytol market sits in early-cycle expansion as fermentation-derived routes unlock cost-advantaged natural-grade supply for Asian cosmetic manufacturers previously restricted to synthetic petrochemical inputs.
For Market Incumbents: Insulate specification leadership by deepening backward integration into geranylacetone feedstock security and accelerating multi-year offtake agreements with French fragrance houses before REACH authorization amendments fully disqualify spot-market procurement. Lock in analytical chemistry talent concentrated at legacy producers to defend against biocatalytic hydrogenation entrants eroding technical moats. For New Entrants and Emerging Players: South Korean skincare formulators seeking direct facility audit partnerships represent the most penetrable entry point for fermentation-derived producers bypassing European distributor networks. Japanese encapsulation technology developers offer a secondary white-space target for pharmaceutical-grade specification contracts. Lead with biobased certification credentials aligned to EU Green Deal schemes rather than competing on unit cost against integrated petrochemical giants. For Investors and Strategic Acquirers: ECHA REACH authorization amendments for CMR-classified impurities reshape the acquisition landscape toward registered suppliers with validated dossiers and established chromatography expertise. Five-to-ten year viability favors fermentation-derived bioprocess specialists with enzymatic route patents and Asian manufacturing footprints. Watch for dual-sourcing mandates from German and French fragrance houses as the inflection signal for premium positioning capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Geranylacetone Feedstock | Captive precursor supply secures margin control against naphtha price volatility at Ludwigshafen. |
| Fermentation Capacity Expansion in Yangtze River Delta | Zhejiang and Jiangsu bioprocess clusters unlock cost-advantaged natural-grade output for Asian cosmetics. |
| REACH Registration Dossier Investment | ECHA substance identity certification enables premium pricing in European fragrance corridors. |
| Direct Specification Partnerships with Seoul Formulators | MFDS-aligned facility audits bypass European trading house margins in South Korean skincare. |
| Continuous-Flow Photochemical Reduction Pilot | Netherlands and Switzerland compounders reduce solvent waste and thermal degradation in terpene processing. |
Research Approach
Cross-validation between primary interviews with fragrance house procurement directors, nutraceutical formulators, and fermentation process engineers and secondary validation through ECHA REACH registration databases, customs trade flows, and SEC filings anchors the qualitative findings. Bottom-up triangulation across hydrogenation capacity assessments and top-down reconciliation against vitamin E precursor demand curves ensures segmentation consistency. The analysis draws from technical discussions with chromatography specialists at legacy producers and regulatory affairs leads navigating FDA 21 CFR and SAMR GB parallel compliance.
Calibration against historical price spreads between synthetic and natural grades and verified capacity announcements at Ludwigshafen and Yangtze River Delta facilities informs the projection framework. Segmentation dimensions span product type, application channel, end-user specification tier, and regional regulatory cluster. CAGRs derive from elasticity modeling across tocopherol synthesis demand and fine fragrance formulation trends. Industry-specific inputs include geranylacetone cracker operating rates and biobased certification scheme adoption curves.
Practitioners should monitor REACH authorization amendment timelines and fermentation yield improvements for early signals of supply chain reconfiguration. Forecasts reflect assumptions around ECHA dossier approval cycles and Asian bioprocess scale-up trajectories. Macroeconomic commodity volatility, regulatory threshold tightening, or biocatalytic hydrogenation breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Lithium Difluoro(Oxalato)Borate Market
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
Global Tetrahexyldecyl Ascorbate Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Global Baking Soda Substitute Market
Specialty Chemicals
Antifouling Agent Market
Specialty Chemicals
Cellulose Esters and Ethers Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Bio-Wax Market
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
Eco-Friendly Plasticizers Market
Specialty Chemicals
Global Molecular Weight Marker Market
Specialty Chemicals
Methyl Salicylate Market
Specialty Chemicals
Fabric Softener and Conditioner Market
Specialty Chemicals
Keratin Products Market