
 Global Foam Blowing Agents Market | 2026-2036
Global Foam Blowing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Foam Blowing Agents Market Foresight
Subscription-based technical service agreements for blowing agent formulation optimization is recalibrating how chemical suppliers monetize their portfolios. Honeywell International Inc. leverages its fluorocarbon technology leadership to anchor premium service contracts with insulation manufacturers. Daikin Industries Ltd. competes through integrated supply chains that extend from refrigerant-grade precursors to customized foam blends.
Foam blowing agents are low-boiling-point substances that generate cellular structures in polymers through controlled gas nucleation during expansion, typically requiring boiling points between minus fifty and plus fifty degrees Celsius for effective processing. Their primary commercial purpose centers on reducing material density while improving thermal insulation performance in rigid polyurethane and polystyrene systems. Hydrocarbons now lead product type demand due to negligible global warming potential and compatibility with existing appliance manufacturing lines. Insulation panels dominate application volumes, though automotive components represent the fastest-growing segment as lightweighting mandates intensify. Construction absorbs the largest end user industry share, with transportation equipment offering the highest margin pool for next-generation low-GWP formulations.
The US EPA Significant New Alternatives Policy program restricts high-GWP blowing agent chemistries in domestic appliance and construction applications. REACH registration requirements in Europe and China's GB standards for building materials collectively shape formulation choices across major manufacturing bases. Japan's METI energy efficiency benchmarks for commercial buildings further tighten thermal performance specifications that cascade into blowing agent selection criteria. Stakeholders must monitor regulatory synchronization between Kigali phase-down schedules and regional building code revisions to anticipate formulation transition timelines.
Market Dynamics
The Kigali Amendment's hydrofluorocarbon phase-down mandates are compressing formulation timelines and forcing capital reallocation toward hydrocarbon and inorganic alternatives before patent cliffs expire on incumbent fluorocarbon portfolios.
Growth Catalysts
- REACH F-Gas Regulation:The European Union's progressive fluorinated gas restrictions are accelerating manufacturer migration to pentane and cyclopentane systems in appliance insulation lines.
- China construction output:Tier-one cities including Shanghai and Shenzhen are enforcing stricter GB standards for building envelope thermal performance, concentrating rigid polyurethane panel demand.
- Formulation-as-a-service:Technical optimization contracts are embedding suppliers deeper into customer R&D cycles, extending revenue duration beyond commodity chemical sales.
Market Restraints
- Propane feedstock volatility:Hydrocarbon blowing agent economics remain tethered to natural gas liquid pricing swings, compressing margin predictability for blenders without backward integration into petrochemical feedstocks.
- Equipment lock-in:Appliance manufacturers face stranded asset risk from existing HFC-245fa injection systems that require full line retooling for flammable hydrocarbon alternatives.
- Regional supply concentration:Cyclopentane production capacity clusters in Northeast China and the US Gulf Coast, exposing formulators to concentrated logistics disruption.
Strategic Opportunities
- India appliance manufacturing:PLI scheme incentives for domestic refrigerator and air conditioner production are creating virgin formulation demand as OEMs localize supply chains away from China.
- Transcritical CO2 integration:Convergence of supercritical carbon dioxide systems with polyurethane foam expansion is opening non-flammable pathways for high-performance insulation in commercial cold chain.
- Japan METI efficiency mandates:Commercial building energy performance standards are tightening thermal conductivity specifications, favoring next-generation low-GWP formulations with lambda values below 20 mW/m·K.
Industry Challenges
- Flammability engineering talent:Hydrocarbon adoption requires process safety specialists capable of managing ATEX compliance and explosion protection documentation, creating recruitment bottlenecks.
- Multi-jurisdiction certification lag:New inorganic formulations face sequential EPA SNAP approval, EU REACH registration, and China MEE environmental assessment, extending commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Foam Blowing Agents Market |
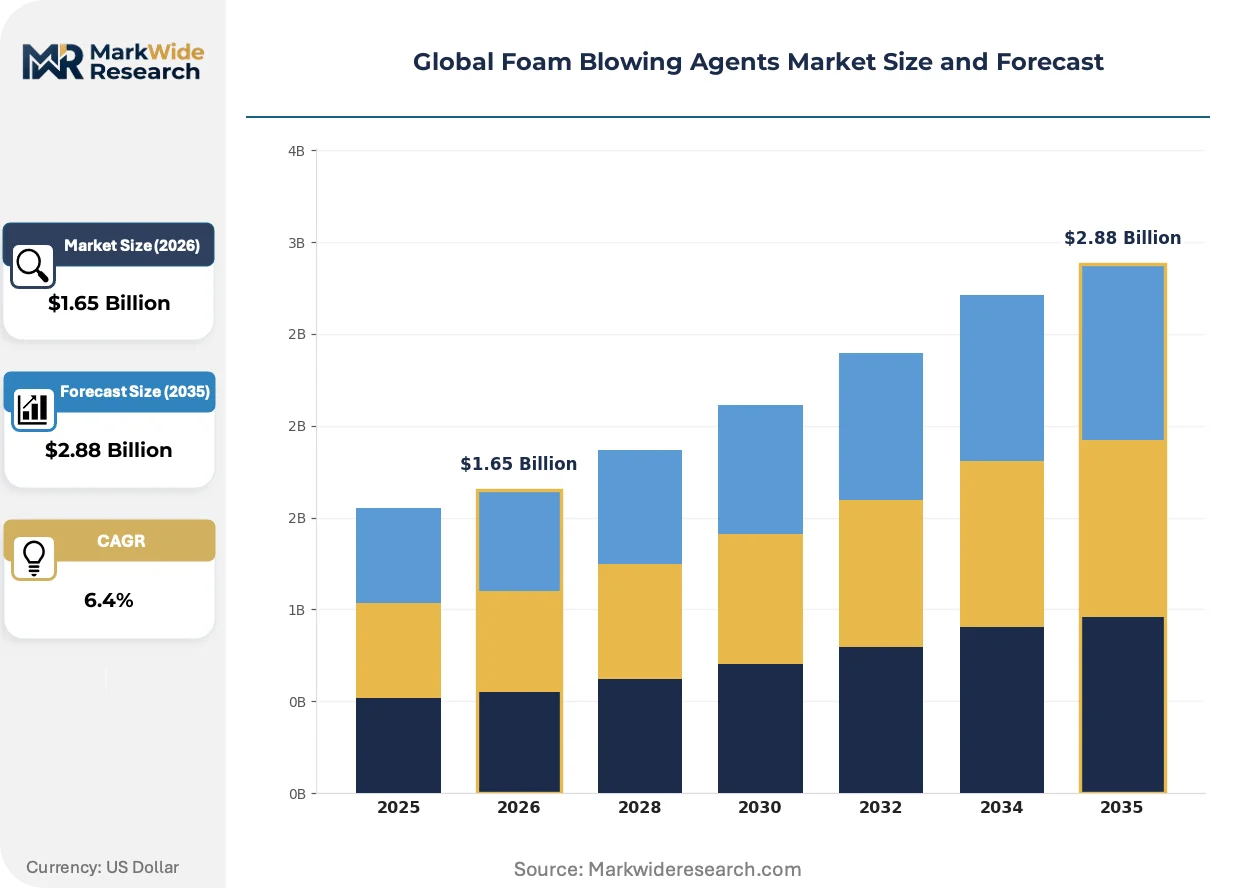
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrofluorocarbons, Hydrochlorofluorocarbons, Hydrocarbons, Inorganics Application: Insulation Panels, Packaging Materials, Automotive Components, Furniture Manufacturing End User Industry: Construction, Consumer Goods, Transportation Equipment, Home Furnishings Form: Liquid, Gas, Solid, Blends |
| Companies Covered | E.I. du Pont de Nemours & Company, Daikin Industries Ltd., Arkema S.A., Linde Group, Zeon Corporation, Honeywell International Inc., Solvay S.A., The Chemours Company, Exxon Mobil Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Foam Blowing Agents Market Shifts & Advancements
Formulation science is pivoting from molecular substitution toward system-level thermal performance optimization, embedding blowing agent selection within broader insulation engineering workflows rather than treating it as an isolated procurement decision.
Water-blown polyurethane systems incorporating polycarbonate polyols are rewriting thermal conductivity benchmarks for appliance insulation. European white goods manufacturers are piloting these formulations in premium refrigerator lines. The technology is compressing the performance gap between hydrocarbon and fluorocarbon alternatives while eliminating flammancy handling costs.
The US EPA Significant New Alternatives Policy program is restricting HFC-245fa and HFC-365mfc in domestic appliance and construction applications. This regulatory compression is forcing blenders to sunset legacy formulations ahead of patent expiration. Appliance OEMs in the Midwest manufacturing corridor are accelerating hydrocarbon line conversions to maintain SNAP listing compliance.
Building envelope specification is consolidating around performance-based procurement where thermal lambda values dominate over blowing agent chemistry disclosure. German and Austrian passive house certifiers are driving this preference shift. The specification model is displacing traditional chemical-grade purchasing in commercial construction across Northern Europe.
Global Foam Blowing Agents Market Segmentation
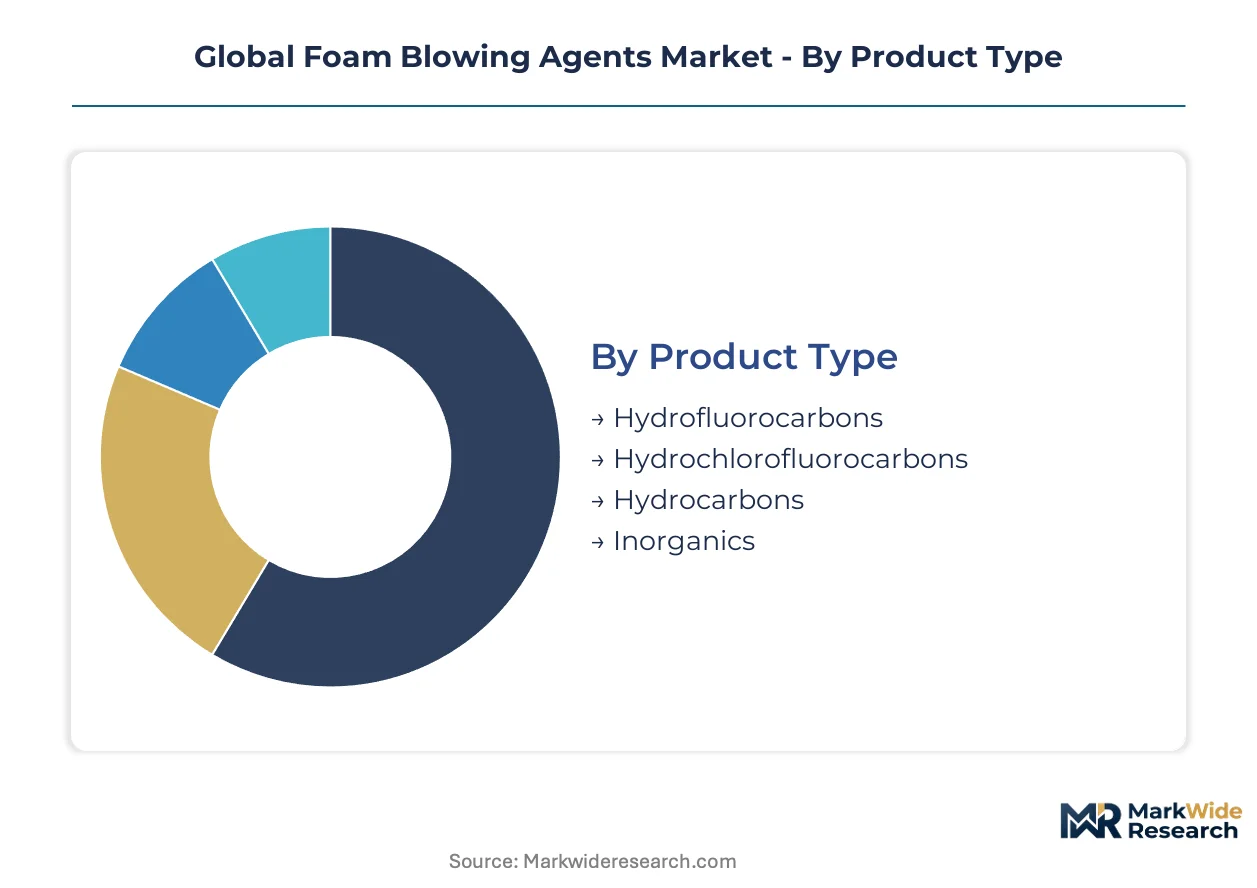
Segmentation in foam blowing agents reveals how regulatory phase-downs and thermal performance requirements reshape procurement priorities across chemistry classes and end-use applications. Understanding these divides exposes where formulation investments concentrate and which customer segments command premium pricing for next-generation low-GWP systems.
Product Type:
Upgrade cycles in blowing agent chemistry track directly to Montreal Protocol phase-down schedules and patent cliff timing for incumbent fluorocarbon portfolios.
- Hydrocarbons:Pentane and cyclopentane formulations dominate new capacity investment due to negligible global warming potential and compatibility with existing appliance manufacturing infrastructure. China's refrigerator OEMs in Hefei and Qingdao have completed line conversions to cyclopentane systems ahead of GB standard tightening.
- Inorganics:Carbon dioxide and water-blown systems are gaining traction in commercial cold chain applications where flammancy restrictions exclude hydrocarbon alternatives. European passive house certifiers in Germany and Austria are specifying these formulations for lambda values below 20 mW/m·K.
- Hydrofluorocarbons:HFC-245fa and HFC-365mfc face accelerated phase-out under US EPA SNAP restrictions and EU F-Gas Regulation compression timelines.
- Hydrochlorofluorocarbons:HCFC-141b persists in limited developing economy applications where capital constraints delay hydrocarbon retooling.
Hydrocarbons sits at the top of the volume ranking, with Inorganics climbing the fastest.
Application:
Application demand splits according to thermal conductivity specifications and flammancy tolerance thresholds that vary sharply between building codes and transportation safety standards.
- Insulation Panels:Rigid polyurethane boards for commercial building envelopes absorb the largest absolute volumes, driven by Japan METI efficiency mandates and China GB standards for envelope performance. German and Austrian passive house projects are specifying water-blown systems with polycarbonate polyols.
- Automotive Components:Lightweighting mandates from NHTSA and EU fleet efficiency targets are expanding polyurethane foam use in seat cushions, headliners, and bumper cores. Tier-one suppliers in Michigan and Stuttgart are qualifying next-generation low-GWP formulations.
- Packaging Materials:Expandable polystyrene systems for protective packaging rely on hydrocarbon blowing agents where flammancy controls permit.
- Furniture Manufacturing:Flexible polyurethane foams for mattresses and upholstered seating use water-blown or hydrocarbon systems depending on regional fire safety codes.
Insulation Panels holds the dominant share, while Automotive Components gains share fastest on lightweighting compliance pressure.
End User Industry:
Customer margin pools diverge sharply between construction procurement—where thermal lambda values dominate specification—and transportation equipment, where formulation premiums attach to crash performance and weight reduction.
- Construction:Commercial building envelope projects in Shanghai, Shenzhen, and Tokyo are consolidating procurement around performance-based specifications that prioritize thermal conductivity over chemistry disclosure. This shift favors suppliers with formulation-as-a-service capabilities.
- Transportation Equipment:Automotive and aerospace OEMs represent the highest-margin customer segment, with Boeing and Airbus qualification timelines for interior foam systems creating multi-year revenue visibility for approved suppliers.
- Consumer Goods:Refrigerator and freezer manufacturers in China's appliance belt are localizing supply chains under PLI-equivalent incentives, creating formulation demand for hydrocarbon and water-blown systems.
- Home Furnishings:Mattress and furniture producers in Vietnam and Indonesia are expanding capacity for export markets, driving hydrocarbon blowing agent offtake.
Construction commands the largest absolute volumes, with Transportation Equipment expanding most quickly on lightweighting mandates.
Form:
Physical state selection hinges on injection equipment compatibility and storage safety requirements that vary by manufacturing scale and regional regulatory enforcement intensity.
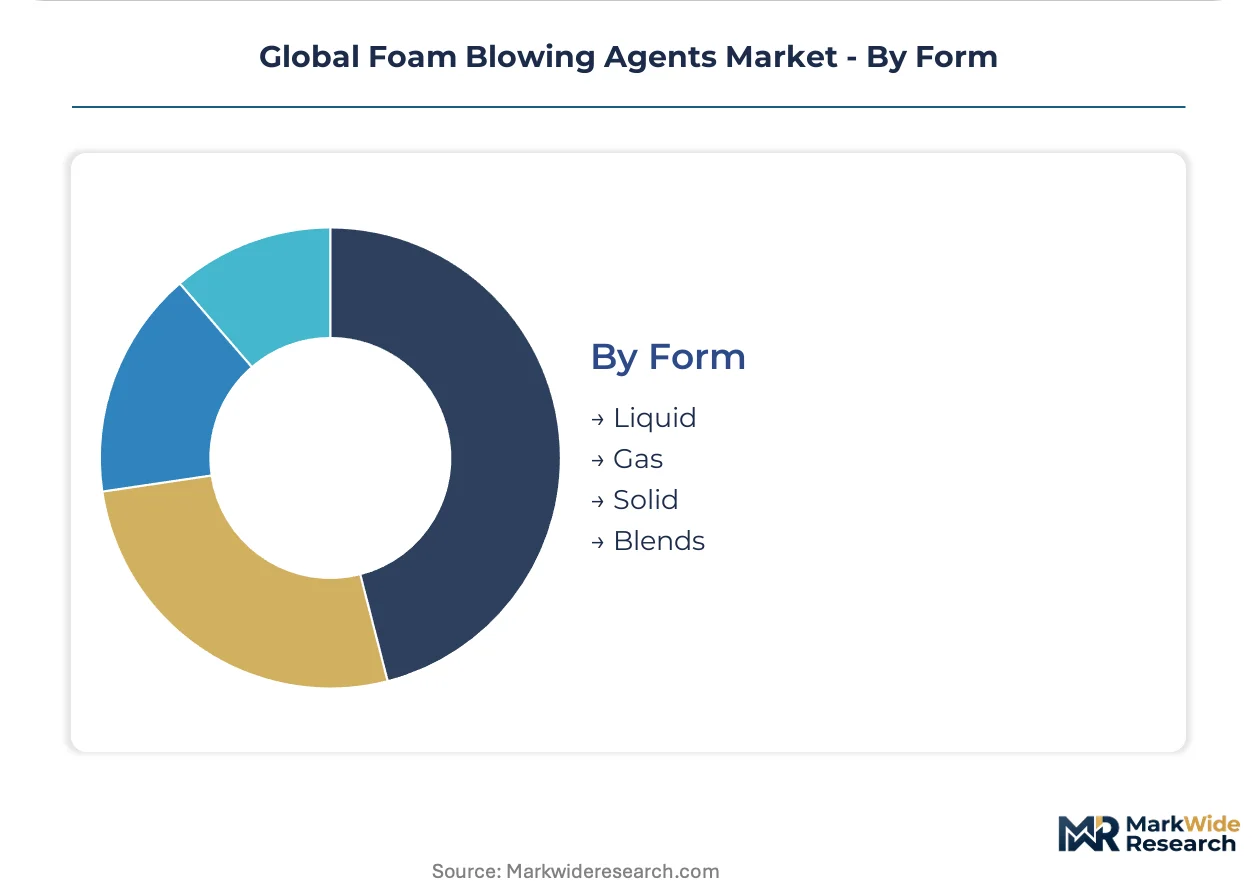
- Liquid:Cyclopentane and HFC-245fa in liquid form dominate appliance insulation lines due to precise metering compatibility with existing high-pressure equipment.
- Gas:Carbon dioxide in supercritical or gaseous state enables transcritical systems for commercial cold chain applications where flammancy is prohibited.
- Solid:Encapsulated blowing agent masterbatches serve specialty applications requiring extended shelf stability or controlled release kinetics.
- Blends:Custom hydrocarbon-HFC mixtures bridge performance gaps during formulation transitions, though EPA SNAP and REACH F-Gas restrictions are compressing their commercial lifespan.
Liquid formulations lead on installed base, with Gas gaining fastest on transcritical CO2 system adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs larger blowing agent volumes than the United States, yet formulation premiums concentrate in Japanese and German markets where METI efficiency mandates and passive house standards command lambda values below 20 mW/m·K.
United States
Appliance OEMs in the Midwest manufacturing corridor accelerate hydrocarbon line conversions to maintain EPA SNAP listing compliance for refrigerator and construction insulation applications. The EPA Significant New Alternatives Policy program restricts HFC-245fa and HFC-365mfc chemistries, compressing formulation transition timelines. Michigan-based tier-one automotive suppliers qualify next-generation low-GWP formulations for seat cushion and headliner applications under NHTSA lightweighting mandates.
China
Refrigerator manufacturers in Hefei and Qingdao complete cyclopentane system conversions ahead of GB standard tightening for building envelope thermal performance. The Ministry of Ecology and Environment conducts environmental assessments for new inorganic formulations entering commercial cold chain applications. Construction output in Shanghai and Shenzhen enforces stricter GB standards, concentrating rigid polyurethane panel demand in tier-one cities.
Germany
Passive house certifiers in Germany and Austria specify water-blown systems with polycarbonate polyols for lambda values below 20 mW/m·K. The EU F-Gas Regulation accelerates manufacturer migration to pentane and cyclopentane systems in appliance insulation lines. Industrial clusters along the Rhine corridor embed formulation-as-a-service capabilities within customer R&D cycles.
Japan
Commercial building projects in Tokyo and Osaka tighten thermal conductivity specifications under METI energy efficiency benchmarks. The Ministry of Economy, Trade and Industry mandates cascade into blowing agent selection criteria for high-performance insulation systems. Japanese appliance manufacturers localize hydrocarbon formulation supply chains to serve premium refrigerator export markets.
India
PLI scheme incentives for domestic refrigerator and air conditioner production create virgin formulation demand as OEMs localize supply chains. The Bureau of Indian Standards develops alignment with international phase-down schedules for high-GWP chemistries. Manufacturing corridors in Maharashtra and Gujarat attract hydrocarbon blending capacity to serve expanding appliance output.
Global Foam Blowing Agents Market Competitive Landscape
Top-tier vendors anchor premium formulation services, while mid-scale blenders compete on hydrocarbon supply security and regional logistics coverage. The market structure reflects patent cliff pressures on fluorocarbon portfolios alongside capital reallocation toward hydrocarbon and inorganic alternatives. Three archetypes dominate: integrated chemical conglomerates with refrigerant-grade precursor positions, specialty gas suppliers with transcritical CO2 system expertise, and regional hydrocarbon blenders with backward integration into petrochemical feedstocks. Competitive moves concentrate on capacity expansion in cyclopentane production clusters and technology licensing agreements for water-blown polyurethane systems.
Within the integrated chemical tier, Honeywell International Inc. and Daikin Industries Ltd. occupy positions reflecting fluorocarbon technology leadership and refrigerant-to-foam supply chain integration. Arkema S.A. and Solvay S.A. exemplify European specialty chemical archetypes with REACH registration capabilities and passive house certification relationships. These named entities represent strategic positioning patterns rather than specific market share claims or operational assertions.
| Leading Market Players |
|---|
| E.I. du Pont de Nemours & Company |
| Daikin Industries Ltd. |
| Arkema S.A. |
| Linde Group |
| Zeon Corporation |
| Honeywell International Inc. |
| Solvay S.A. |
| The Chemours Company |
| Exxon Mobil Corporation |
| Others |
Supply & Pricing Matrix
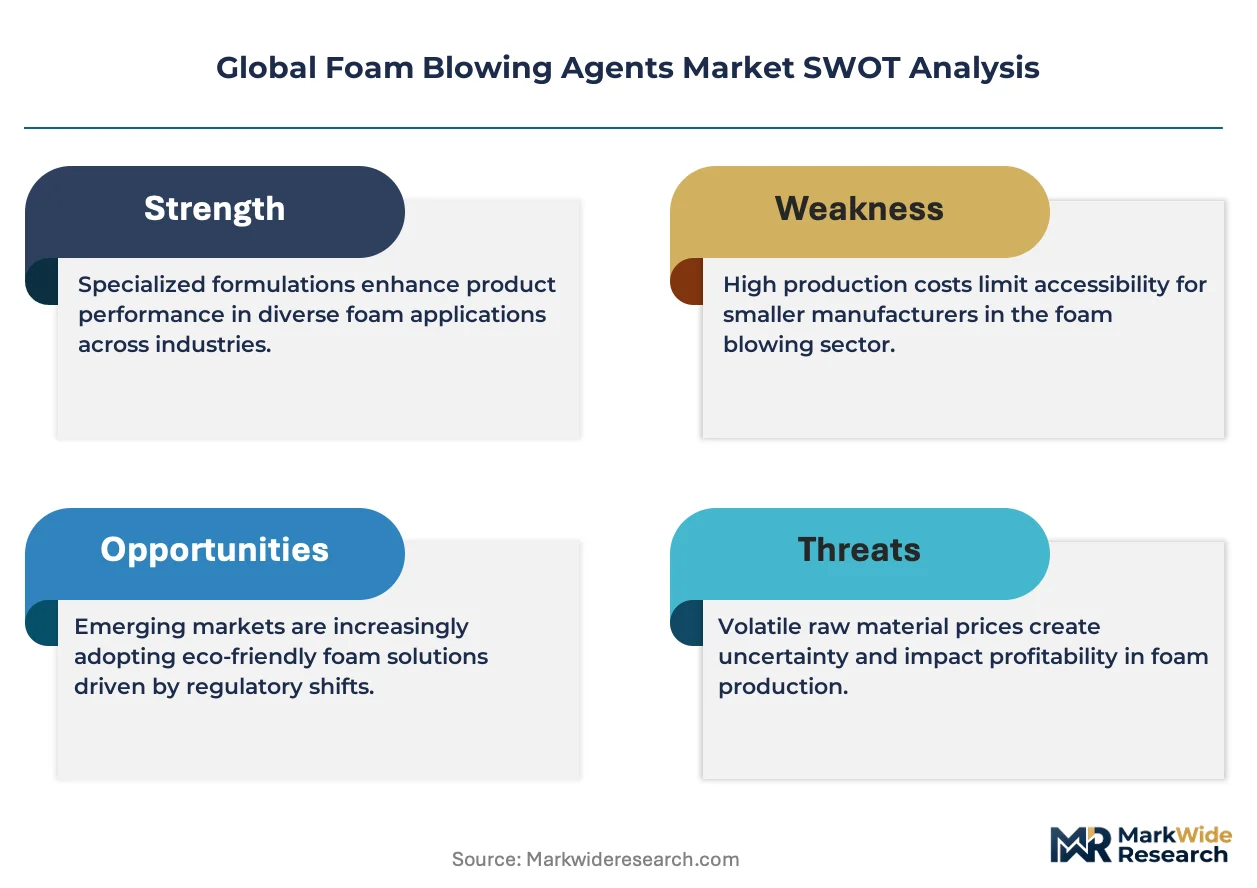
Japan METI efficiency mandates for commercial building thermal performance are compressing procurement timelines and forcing blenders to absorb certification costs for lambda values below 20 mW/m·K, which in turn concentrates pricing power with suppliers holding REACH registration and passive house certification relationships.
Pricing Analysis
Capacity additions in Northeast China are reshaping price floors for cyclopentane formulations as Hefei and Qingdao appliance OEMs complete hydrocarbon line conversions. Three-tier pricing structure across premium low-GWP formulations, standard hydrocarbon blends, and economy-grade HFC systems separates suppliers by certification tier and technical service bundling. Cost compression in standard hydrocarbon tiers is intensifying because propane feedstock volatility ties blender margins to natural gas liquid pricing swings. Appliance manufacturers with stranded HFC-245fa injection equipment represent the most price-sensitive buyers, while aerospace OEMs qualifying interior foam systems for Boeing and Airbus command the least.
Supply Chain Analysis
Regional distribution centers along the US Gulf Coast and Rhine corridor operate hub-and-spoke patterns feeding appliance manufacturing clusters in Michigan and Stuttgart. Cyclopentane production capacity concentrates in Northeast China, the US Gulf Coast, and Germany, with formulators drawing from concentrated petrochemical feedstock nodes. Raw material dependencies span natural gas liquids for hydrocarbon precursors, refrigerant-grade fluorocarbon intermediates, and polycarbonate polyols for water-blown systems. Single-source vulnerability runs through China's Ministry of Ecology and Environment environmental assessment gates for new inorganic formulations. Distribution runs through integrated chemical conglomerates with captive blending assets and regional hydrocarbon specialists with backward integration into petrochemical feedstocks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in foam blowing agents rests on Kigali Amendment phase-down timelines compressing incumbent fluorocarbon returns while premium pricing attaches to low-GWP formulations with sub-20 mW/m·K lambda certification.
For Market Incumbents: Deploy formulation-as-a-service contracts to embed technical optimization deeper into customer R&D cycles and extend revenue duration beyond commodity chemical sales. Anchor premium positioning through REACH registration capabilities and passive house certification relationships with German and Austrian certifiers. Counter stranded asset risk from HFC patent cliffs by accelerating hydrocarbon capacity additions in Northeast China and the US Gulf Coast before EPA SNAP restrictions sunset legacy formulations. For New Entrants and Emerging Players: Transcritical CO2 integration with polyurethane foam expansion offers a technology-first wedge into commercial cold chain applications where flammancy restrictions exclude hydrocarbon alternatives. Target India's PLI scheme appliance manufacturing corridors in Maharashtra and Gujarat as the most penetrable geography, where domestic refrigerator and air conditioner localization creates virgin formulation demand. Enter through technical partnerships with European passive house certifiers seeking non-flammable pathways for lambda values below 20 mW/m·K. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty gas suppliers holding transcritical CO2 system expertise and regional hydrocarbon blenders with backward integration into petrochemical feedstocks. Long-term viability over the projection horizon favors assets with dual REACH and China MEE registration capabilities as multi-jurisdiction certification lag extends commercialization timelines for new entrants. Monitor EPA SNAP approval velocity for inorganic formulations as the inflection indicator for hydrocarbon displacement pace in domestic appliance applications.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Cyclopentane additions in Northeast China serve Hefei and Qingdao appliance OEM conversions ahead of GB standard tightening. |
| Backward Integration | Captive natural gas liquid processing insulates blenders from propane feedstock volatility compressing margin predictability. |
| Green Manufacturing Transition | Water-blown polyurethane systems with polycarbonate polyols eliminate flammancy handling costs while meeting passive house lambda benchmarks. |
| Long-term Supply Agreement | Technical service contracts embed suppliers into customer R&D cycles and extend revenue duration beyond commodity sales. |
| Joint Venture | Transcritical CO2 partnerships with commercial cold chain operators open non-flammable pathways for high-performance insulation systems. |
Research Methodology
Coverage spans China, the United States, Germany, Japan, and India, with primary inputs from each market's appliance manufacturing clusters and construction regulatory bodies. The approach combines primary interviews with plant managers at cyclopentane blending facilities, procurement leads at refrigerator OEMs, technical R&D directors at insulation panel manufacturers, and distribution channel partners serving the Rhine corridor. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated chemical conglomerates, and EPA SNAP program dockets. Bottom-up demand modeling from end-use applications triangulates against top-down supply capacity assessments across hydrocarbon and inorganic production nodes.
Rate-of-change decomposition separates volume growth from value expansion across the analysis window, with segmentation modeled by chemistry class, application thermal conductivity specification, end-use industry margin pool, and regional regulatory cluster. CAGRs derive from installed base conversion timelines for HFC equipment, patent cliff schedules for incumbent fluorocarbon portfolios, and Kigali Amendment phase-down compliance deadlines. Industry-specific forecast inputs include Japan METI efficiency mandate adoption curves, China GB standard enforcement intensity in tier-one cities, and India PLI scheme localization incentives for appliance manufacturing.
The model holds under stable regulatory synchronization between Kigali schedules and regional building code revisions; deviation in EPA SNAP approval velocity or China MEE environmental assessment gates would shift formulation transition timelines. Forecasts reflect assumptions about hydrocarbon line conversion rates, flammancy engineering talent availability, and multi-jurisdiction certification lag duration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Fabric Softener and Conditioner Market
Specialty Chemicals
Acesulfame K Market
Specialty Chemicals
Glucono Delta Lactone Market
Specialty Chemicals
Caryophyllene Market
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
Bio-Based Aromatics Market
Specialty Chemicals
North America Sulfonylureas Market
Specialty Chemicals
Global Fabric Softener Sheet Market
Specialty Chemicals
Organo-Modified Bentonite Market
Specialty Chemicals
Microcrystalline Wax Market
Specialty Chemicals
Halogen-Free Flame Retardants Market
Specialty Chemicals
UV/IR Blocker Market
Specialty Chemicals
Acesulfame Potassium Market
Specialty Chemicals
Salt Hydrate Market
Specialty Chemicals
Epoxidized Soybean Oil Market
Specialty Chemicals
Sizing and Thickening Market