
 Companion Animal Vaccines Market | 2026-2036
Companion Animal Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Companion Animal Vaccines Market Analysis
Subscription-based wellness plans bundled with core vaccination schedules is realigning how veterinary practices monetize preventive care. Zoetis Inc. leverages its vertically integrated manufacturing network to sustain supply security across multiple antigen lines. Merck Animal Health anchors its position through R&D intensity in recombinant vector platforms. Boehringer Ingelheim Animal Health competes on geographic dominance, particularly across European Union member states where its distribution infrastructure reaches independent practitioners.
Companion animal vaccines are biological preparations containing attenuated, inactivated, or recombinant antigenic material designed to induce active immunity against specific canine, feline, and equine pathogens, with formulations stabilized in liquid or lyophilized matrices for parenteral, oral, or mucosal delivery. Their primary commercial purpose is reducing morbidity in owned pets while limiting zoonotic transmission risks within household environments. Live attenuated products retain structural leadership in core protocol adoption due to durable cell-mediated responses, while recombinant segments attract investment from manufacturers seeking to bypass maternal antibody interference. Injectable formulations occupy the dominant margin pool because of established cold-chain infrastructure and clinician familiarity, though intranasal delivery is gaining traction for respiratory disease complexes.
The FDA Center for Veterinary Medicine and USDA APHIS Center for Veterinary Biologics jointly govern product licensing, purity standards, and post-marketing surveillance in the United States, creating compliance barriers that favor incumbents with dedicated regulatory affairs divisions. The European Medicines Agency coordinates centralized marketing authorizations through its veterinary committee, while national competent authorities execute batch-release testing that extends time-to-market for novel candidates. Stakeholders must monitor evolving USDA guidelines on autogenous vaccine exemptions and state-level rabies vaccination mandates, as these frameworks determine addressable market boundaries for both established and emerging players.
Market Dynamics
Subscription-based wellness plans bundled with core vaccination schedules are compressing traditional per-dose margins while locking in multi-year patient volumes across veterinary practice networks. This shift toward predictable recurring revenue is redistributing value capture from manufacturers to service providers.
Growth Catalysts
- Rabies vaccination mandates:State-level compulsory immunization laws in the United States create non-discretionary demand with fixed renewal cycles. These statutes eliminate price elasticity for core canine and feline protocols.
- Pet insurance penetration:Reimbursement coverage for preventive care in the United States removes out-of-pocket friction for premium vaccine uptake. Insured households complete vaccination series at higher rates than uninsured counterparts.
- Recombinant vector platforms:DNA-based antigen expression systems circumvent maternal antibody interference in juvenile animals. This technology extends effective vaccination windows for high-value pedigreed populations.
Market Restraints
- Cold-chain infrastructure costs:Lyophilized and liquid formulations require continuous 2-8°C storage through distribution. Temperature excursion risks concentrate liability with veterinary distributors in warmer climates.
- Lot-release testing timelines:The FDA Center for Veterinary Medicine and USDA APHIS Center for Veterinary Biologics impose extended batch-verification protocols. These regulatory gates delay commercial launch for novel candidates by 12-18 months.
- Autogenous vaccine exemptions:USDA guidelines permit custom biologics for herd-specific pathogens, fragmenting demand for standardized commercial products in large breeding operations.
Strategic Opportunities
- Intranasal delivery formats:Mucosal administration for respiratory disease complexes addresses needle-averse pet owners. This route stimulates local IgA responses that injectable formulations cannot replicate.
- Equine expansion:Underpenetrated horse populations in recreational and competitive segments present whitespace beyond saturated canine-feline markets. Equine influenza and herpesvirus protocols command premium pricing.
- Telemedicine-tethered protocols:Remote veterinary consultations bundled with home-delivered vaccines are emerging in urban United States markets. This channel bypasses clinic congestion while maintaining compliance documentation.
Industry Challenges
- Veterinary immunology specialization:Diagnostic interpretation of vaccine titer testing requires advanced training that general practitioners often lack. Misapplication of serology results leads to over- or under-vaccination.
- Multi-valent formulation stability:Combining antigens from divergent pathogen classes risks interference effects that reduce immunogenicity. Manufacturers sacrifice coverage breadth for reliability in core combination products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Companion Animal Vaccines Market |
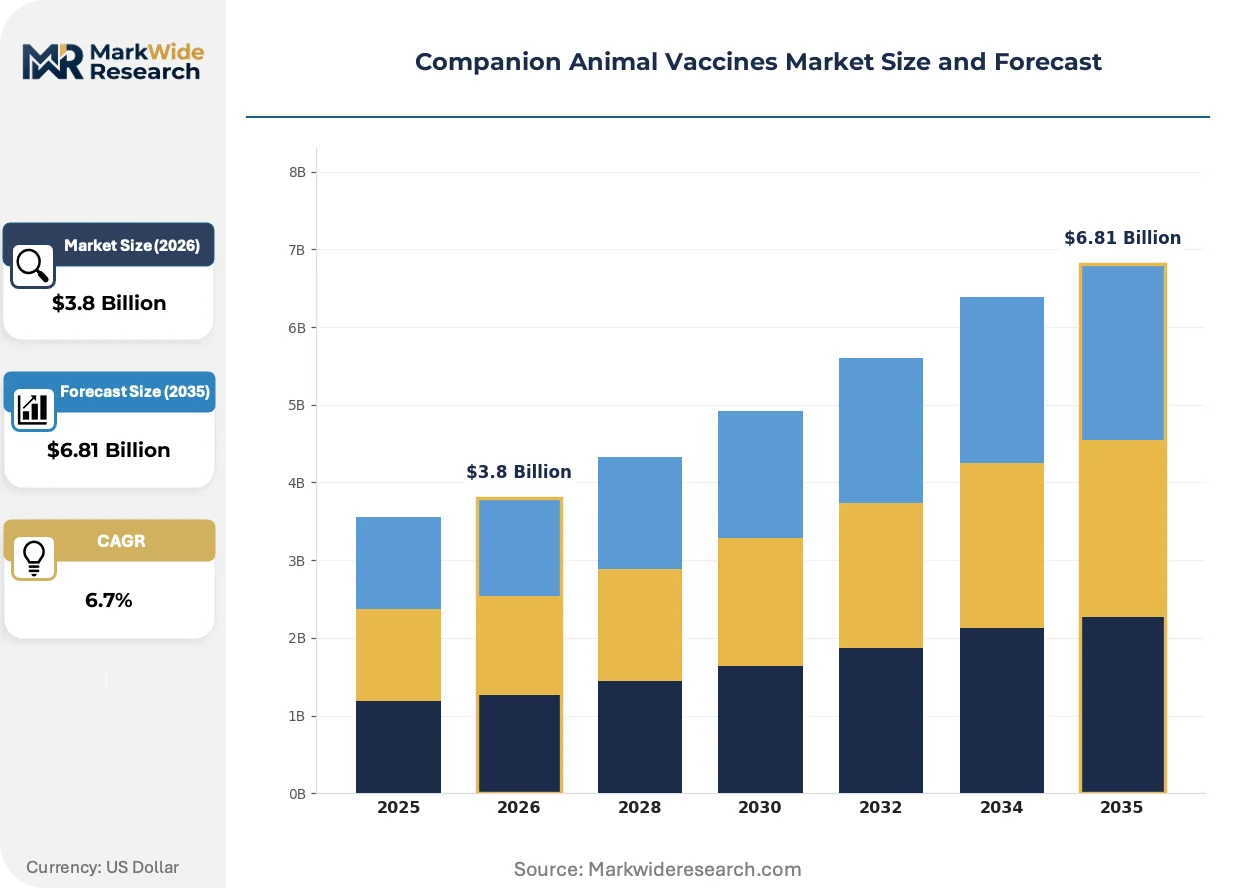
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inactivated, Live Attenuated, Recombinant, DNA Formulation: Injectable, Oral, Intranasal, Combination End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Pet Owners Distribution Channel: Online Stores, Veterinary Distributors, Pharmacies, Direct Sales |
| Companies Covered | Zoetis Inc., Merck Animal Health, Boehringer Ingelheim Animal Health, Elanco Animal Health, Virbac, Ceva Santé Animale, Phibro Animal Health Corporation, Neogen Corporation, Bimeda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Companion Animal Vaccines Market Emerging Trajectories
Antigen delivery technologies and diagnostic-enabled personalization are fragmenting the one-size-fits-all vaccination paradigm that dominated veterinary medicine for decades. These shifts are compressing protocol standardization while expanding segment-specific product lines.
Recombinant canarypox-vectored platforms are expanding into feline retroviral and canine melanoma indications previously dominated by killed or modified-live preparations. Specialty oncology practices and academic veterinary hospitals are adopting these platforms at accelerating rates for therapeutic immunization protocols. This expansion is enabling premium pricing tiers that conventional prophylactic vaccines cannot command.
The European Medicines Agency's veterinary committee has tightened environmental risk assessments for genetically modified organism-derived vaccines, extending centralized marketing authorization timelines. This regulatory friction disproportionately affects novel viral-vectored candidates seeking EU-wide distribution. Manufacturers are responding with parallel-track submissions that prioritize United States FDA clearance before European rollout.
Pet owners are consolidating purchasing decisions through subscription wellness platforms that bundle diagnostics, nutrition, and vaccination into single monthly fees. Veterinary clinics in metropolitan United States markets are displacing transactional visit models with these membership structures. This consolidation shifts vaccine procurement from practice-level discretion to corporate formulary committees at platform operators.
Companion Animal Vaccines Market Segmentation
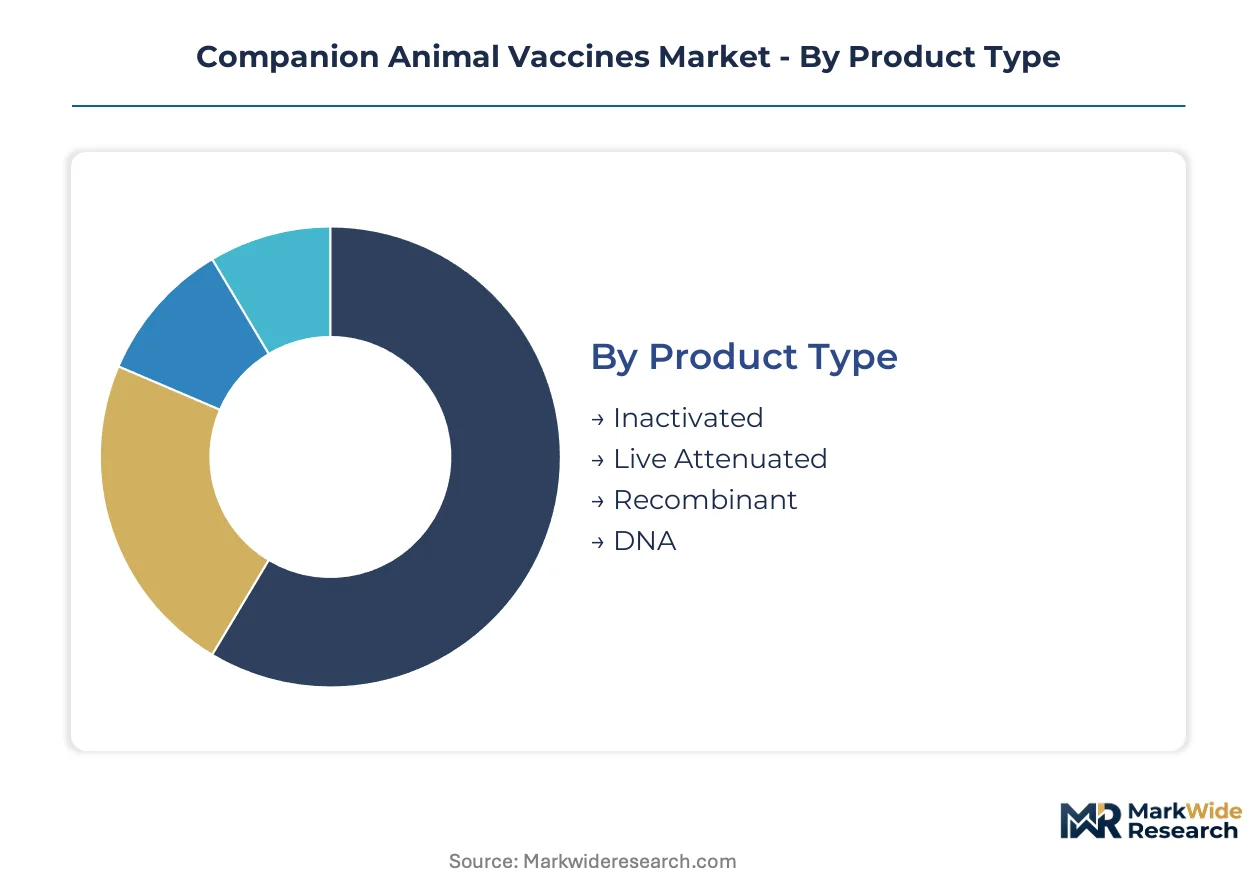
Segmentation in companion animal vaccines reveals how antigen technology, delivery format, and channel structure shape procurement patterns across veterinary settings. Manufacturers configure product portfolios around species-specific immunology while distributors optimize cold-chain logistics for each formulation type.
Product Type:
The customization-to-standardization spectrum spans killed products requiring adjuvant optimization versus platform-based recombinant systems with modular antigen insertion.
- Live Attenuated:Modified-live pathogens retain limited replication capacity to stimulate cell-mediated immunity without causing disease. Veterinary clinics in the United States deploy these formulations for core canine distemper and feline panleukopenia protocols where durable protection outweighs handling complexity.
- Recombinant:Viral vector platforms expressing target antigens bypass maternal antibody interference in juvenile animals. DNA-based expression systems are gaining traction in specialty practices managing high-value pedigreed populations with precise vaccination windows.
- Inactivated:Killed pathogen preparations with aluminum hydroxide adjuvants dominate rabies compliance markets.
- DNA:Plasmid-based vaccines remain experimental outside oncology therapeutic applications.
Leading the category by volume: Live Attenuated. Growing fastest: Recombinant.
Formulation:
Cost tier differentiation separates premium lyophilized injectables from economy oral formats, with mucosal delivery commanding mid-tier positioning.
- Injectable:Parenteral delivery in liquid or lyophilized formats leverages established cold-chain infrastructure and clinician familiarity. The FDA's Center for Veterinary Medicine mandates stringent sterility testing for these formulations, concentrating procurement among distributors with validated temperature monitoring systems.
- Intranasal:Mucosal administration stimulates local IgA responses for respiratory pathogens like Bordetella bronchiseptica. Metropolitan veterinary practices report higher client compliance with needle-free protocols for anxious or aggressive patients.
- Oral:Enteric-coated preparations suit mass administration in shelter environments.
- Combination:Multi-valent cocktails reduce clinic visit frequency but risk antigen interference.
Highest margin capture: Injectable. Steepest expansion trajectory: Intranasal.
End User:
Application maturity varies from protocol-driven institutional buyers to discretionary individual purchasers with divergent price sensitivity.
- Veterinary Clinics:Primary care practices execute bulk procurement through group purchasing organizations while maintaining formulary autonomy for specialty protocols. Subscription wellness plans are compressing per-dose margins while locking in multi-year patient volumes across United States metropolitan networks.
- Animal Hospitals:Emergency and referral centers stock intensive-care vaccines for unvaccinated trauma admissions. These facilities prioritize rapid immune response over cost optimization given reimbursement through pet insurance channels.
- Research Laboratories:Academic veterinary hospitals and contract research organizations require custom titers for immunogenicity studies.
- Pet Owners:Direct-to-consumer channels serve rural households distant from veterinary infrastructure.
Volume concentration: Veterinary Clinics. Fastest-growing demand: Animal Hospitals.
Distribution Channel:
Geographic reach and regulatory compliance capability determine channel viability, with direct sales reserved for institutional accounts.
- Veterinary Distributors:Specialized wholesalers maintain 2-8°C cold chains from manufacturer to clinic, assuming liability for temperature excursions. McKesson Veterinary Supply and Patterson Veterinary dominate United States logistics with same-day delivery to metropolitan practices.
- Online Stores:E-commerce platforms enable home delivery of rabies vaccines to pet owners in remote counties lacking clinic access. State veterinary medical boards scrutinize these channels for compliance with prescription requirements.
- Pharmacies:Human retail chains with veterinary divisions serve over-the-counter demand for select products.
- Direct Sales:Manufacturer field representatives manage corporate accounts and academic institutions.
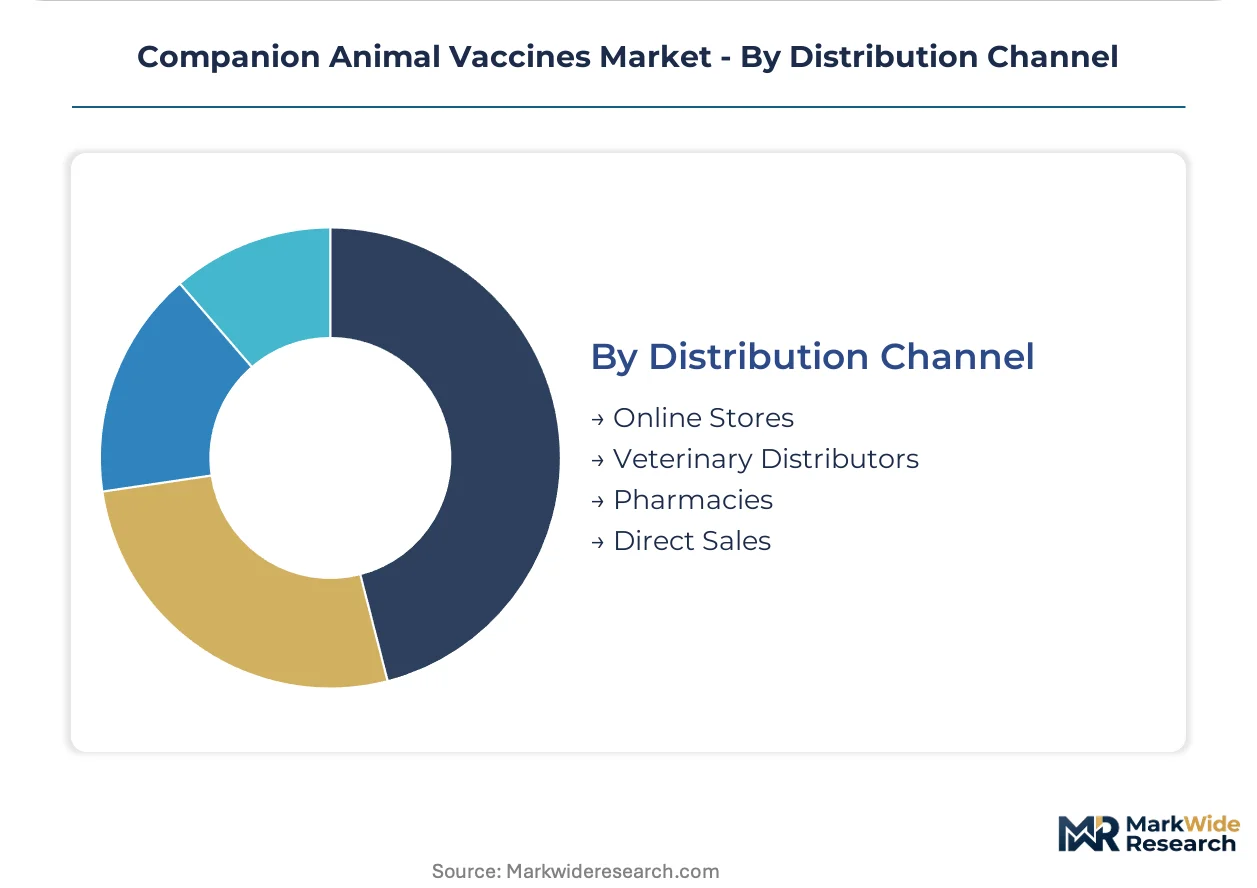
Channel leadership by volume: Veterinary Distributors. Gaining share fastest: Online Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in the United States and Germany, while consumption spreads across veterinary networks in Canada, France, and Japan where pet insurance penetration and specialty practice density drive premium uptake.
United States
Subscription wellness plans and corporate veterinary consolidations concentrate vaccine procurement through group purchasing organizations. The FDA Center for Veterinary Medicine and USDA APHIS Center for Veterinary Biologics enforce stringent lot-release testing that extends time-to-market for novel candidates. Metropolitan networks in California, Texas, and New York deploy telemedicine-tethered protocols with home-delivered vaccines.
Germany
Independent practitioner density and equine recreational populations sustain demand for premium recombinant formulations. The European Medicines Agency veterinary committee coordinates centralized marketing authorizations with extended environmental risk assessments for genetically modified organism-derived products. Manufacturing clusters in Baden-Württemberg and Bavaria supply cold-chain distribution across EU member states.
Canada
Rural veterinary access gaps and shelter medicine programs drive oral and intranasal format adoption. Health Canada and the Pest Management Regulatory Agency govern biologic licensing with batch-release protocols aligned to USDA standards. Ontario and Quebec veterinary distributors maintain validated temperature monitoring systems for same-day metropolitan delivery.
France
High feline ownership rates and specialty oncology practice expansion support therapeutic vaccine uptake. ANSM and the national veterinary regulator enforce pharmacovigilance reporting for viral-vectored platforms. The Lyon and Paris veterinary hospital clusters pioneer recombinant canarypox-vectored protocols for canine melanoma indications.
Japan
Declining veterinary school graduates and aging pet populations compress clinic visit frequency while elevating combination product preference. The Ministry of Agriculture, Forestry and Fisheries and PMDA govern import licensing with extended stability testing requirements. Tokyo and Osaka metropolitan practices consolidate procurement through corporate platform operators with membership-based wellness structures.
Companion Animal Vaccines Market Vendor Landscape
Top-tier vendors anchor premium recombinant and modified-live portfolios, while mid-tier specialists compete on geographic coverage and cold-chain reliability. The vendor base stratifies across three archetypes: vertically integrated pharmaceutical conglomerates with captive manufacturing networks, regional distributors with validated logistics infrastructure, and niche biotechnology firms focused on therapeutic immunization platforms. Competitive moves concentrate on M&A-driven portfolio diversification and strategic partnerships with corporate veterinary platform operators.
Within the integrated pharmaceutical tier, Zoetis Inc., Merck Animal Health, and Boehringer Ingelheim Animal Health exemplify archetypes of supply security and R&D intensity. Zoetis represents vertically integrated manufacturing dominance across multiple antigen lines. Merck occupies a position anchored in recombinant vector platform development. Boehringer Ingelheim exemplifies geographic dominance through distribution infrastructure reach. These three entities collectively illustrate how regulatory affairs scale and cold-chain liability concentration shape competitive positioning in biological product markets.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Merck Animal Health |
| Boehringer Ingelheim Animal Health |
| Elanco Animal Health |
| Virbac |
| Ceva Santé Animale |
| Phibro Animal Health Corporation |
| Neogen Corporation |
| Bimeda |
| Others |
Supply Flow & Price Mechanics
Cold-chain sustainability mandates from the European Medicines Agency and FDA Center for Veterinary Medicine gate qualified supply access, concentrating premium-tier pricing power among manufacturers with validated 2-8°C logistics infrastructure. These environmental compliance barriers filter out distributors lacking temperature-monitoring capabilities, compressing margin capture toward vertically integrated incumbents.
Pricing Analysis
Margin tightening in standard-tier injectable formulations reflects subscription wellness plan consolidation across United States metropolitan veterinary networks. Three-tier pricing structure across premium recombinant, standard modified-live, and economy inactivated levels segments buyers by protocol complexity and pet insurance coverage depth. Cost-down pressure accelerates as corporate veterinary platforms displace practice-level formulary autonomy with centralized procurement committees. Uninsured rural pet owners exhibit highest price sensitivity, while specialty oncology practices with insured clientele absorb premium therapeutic vaccine pricing.
Supply Chain Analysis
Dual-sourcing requirements from corporate veterinary platform operators mandate multi-manufacturer qualification for core antigen lines, fragmenting procurement concentration. Manufacturing gravity centers on the United States, Germany, and France, with Baden-Württemberg and Bavaria clusters feeding EU distribution networks. Production draws from live virus seed stocks, recombinant vector substrates, and aluminum hydroxide adjuvants, with cold-chain liability concentrating in specialized veterinary distributors. Single-source vulnerability persists for canarypox-vectored platforms under extended EMA environmental risk assessments. Distribution runs through McKesson Veterinary Supply and Patterson Veterinary for same-day metropolitan delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA Center for Veterinary Medicine's lot-release testing protocols erect a 12-18 month regulatory moat that entrenches compliant incumbents while excluding capital-constrained entrants lacking dedicated regulatory affairs divisions.
For Market Incumbents: Acquire intranasal delivery technology specialists to preempt needle-averse pet owner migration toward mucosal administration formats. Consolidate backward integration into recombinant vector substrate production to secure supply against single-source bioreactor constraints. Channel control through exclusive distribution agreements with corporate wellness platform operators defends against generic inactivated product commoditization. For New Entrants and Emerging Players: DNA-based therapeutic immunization platforms for canine oncology indications offer white-space penetration beyond saturated prophylactic markets. Target equine influenza and herpesvirus protocols in underpenetrated recreational horse populations across Germany and France. Telemedicine-tethered home delivery partnerships with urban United States veterinary networks provide regulatory-compliant go-to-market velocity without clinic infrastructure investment. For Investors and Strategic Acquirers: USDA APHIS autogenous vaccine exemption guideline revisions are the leading indicator that demand fragmentation will intensify for standardized commercial products, compressing addressable market boundaries. Long-term viability hinges on manufacturers with diversified species coverage spanning canine, feline, and equine immunology. Watch for state-level rabies mandate enforcement shifts as inflection signals for core protocol volume concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Vector Platform Expansion | Canarypox-vectored systems bypass maternal antibody interference in juvenile pedigreed populations. |
| Cold-Chain Infrastructure Investment | Validated 2-8°C logistics secure distribution contracts with corporate veterinary platform operators. |
| Intranasal Delivery Format Development | Mucosal administration stimulates local IgA responses unmatched by injectable formulations. |
| Equine Therapeutic Vaccine Pipeline | Equine influenza and herpesvirus protocols command premium pricing in recreational segments. |
| Telemedicine Protocol Integration | Remote consultation bundling bypasses clinic congestion while maintaining compliance documentation. |
Methodological Framework
Document review covered FDA Center for Veterinary Medicine lot-release records, USDA APHIS biologics licensing data, and European Medicines Agency veterinary committee submissions, complemented by interviews with regulatory affairs directors at major manufacturers, procurement leads at corporate veterinary platform operators, and specialty practice veterinarians managing therapeutic immunization protocols. Secondary validation drew from veterinary distributor financial disclosures, pet insurance reimbursement databases, and state veterinary medical board prescription compliance reports. Bottom-up patient volume modeling and top-down manufacturer revenue triangulation anchored segmentation outputs.
Historical shipment data cross-referenced against panel input from cold-chain logistics providers and group purchasing organization contract managers informed the analytical framework across the projection horizon. Segmentation dimensions spanned antigen technology type, delivery format, species application, end-user channel, and regional regulatory cluster. CAGRs derived from trend extrapolation of insured pet household growth, specialty practice expansion rates, and recombinant platform adoption curves in academic veterinary hospitals.
Several conditions sit outside the modeled scope, including autogenous vaccine exemption enforcement variability, novel zoonotic pathogen emergence requiring emergency protocol revision, and raw material bioreactor contamination events disrupting seed stock availability. Forecasts assume sustained pet insurance penetration trajectories and stable state rabies mandate frameworks. Deviation in USDA APHIS guideline interpretation or EMA environmental risk assessment stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Canine Separation Anxiety Treatment Market
Veterinary
Veterinary Intravenous (IV) Solutions Market
Veterinary
Veterinary CRO and CDMO Market
Veterinary
Global Animal Antimicrobials and Antibiotics Market
Veterinary
Global Veterinary Holters Market
Veterinary
Feline Atopic Dermatitis Treatment Market
Veterinary
Veterinary in Vitro Fertilization Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
Veterinary Wound Sprays Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Veterinary Clostridium Vaccine Market
Veterinary
North America Veterinary Healthcare Market
Veterinary
ASEAN Poultry Vaccines Market
Veterinary
Europe Dog Dewormers Market
Veterinary
Pet DNA Testing Market
Veterinary
Veterinary Hospitals Market