
 Serological Pipettes Market | 2026-2036
Serological Pipettes Market Size, Share, and Industry Trends Forecast 2026-2036
Serological Pipettes Market Outlook
Buyer concentration among pharmaceutical companies and contract research organizations is hardening as biologics manufacturing scales up. Thermo Fisher Scientific leverages its integrated life sciences platform to dominate North American supply chains. Corning Incorporated anchors its position through deep specialization in cell culture workflows where serological pipettes serve as essential consumables. Eppendorf competes on precision liquid handling technology that extends into automated pipetting systems.
Serological pipettes are graduated cylindrical tubes, typically manufactured from polystyrene or borosilicate glass, designed to measure and transfer liquid volumes between 1 mL and 25 mL with accuracy tolerances governed by ISO 8655 standards. These instruments serve as fundamental tools in cell culture media exchange, reagent preparation, and sterile liquid handling across life sciences workflows. Single-channel plastic pipettes lead the product type landscape due to their disposability and cost efficiency in high-throughput settings, while multi-channel variants capture expanding demand in automated liquid handling platforms. Polypropylene material segments are gaining traction where chemical resistance and thermal stability matter, particularly in pharmaceutical quality control laboratories.
FDA quality system regulations and ISO 13485 medical device standards shape manufacturing protocols and traceability requirements for serological pipettes distributed in the United States. The EPA's emerging single-use plastics framework and REACH substance restrictions in Europe are pressuring manufacturers toward sustainable material transitions and extended producer responsibility schemes. Stakeholders must monitor evolving calibration mandates and circular economy legislation that will determine which material platforms and regional production footprints prove viable.
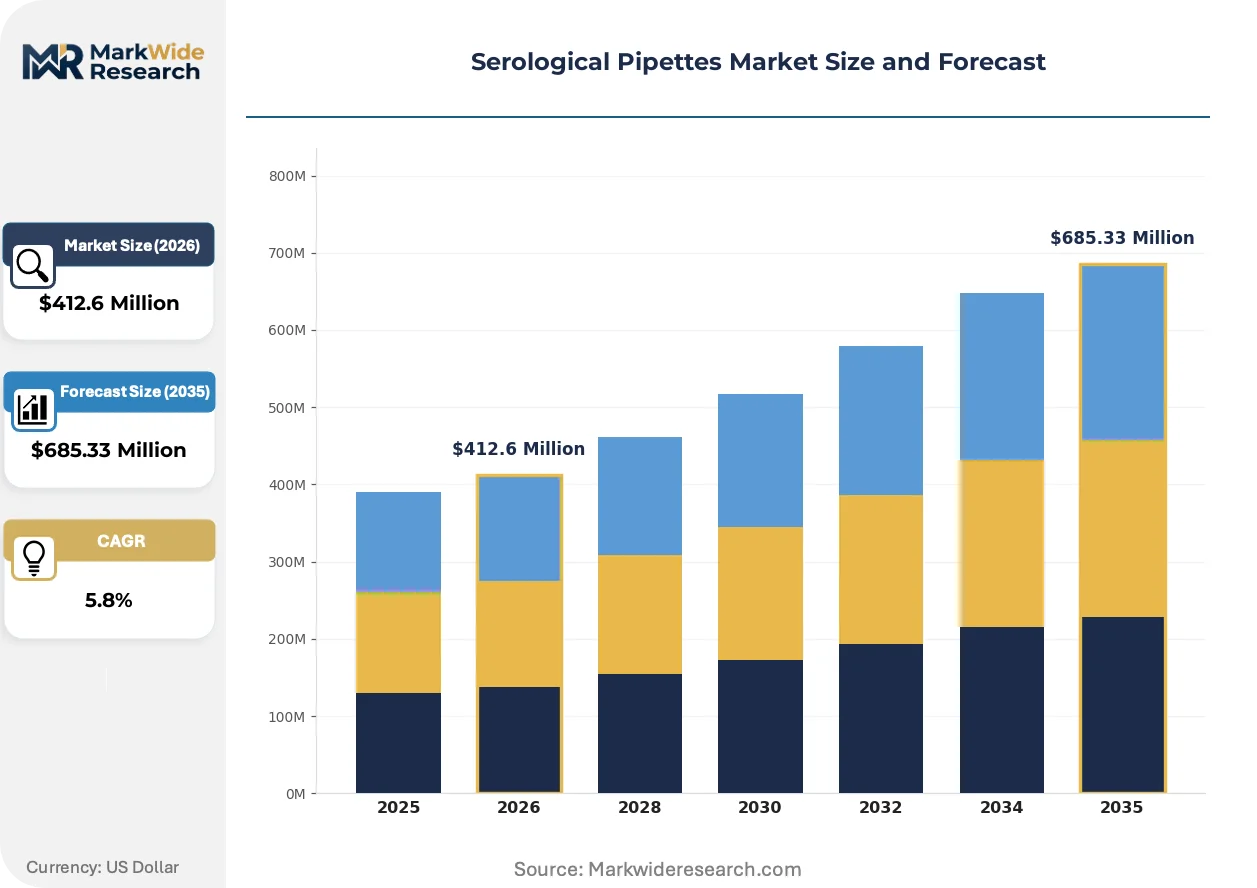
Market Dynamics
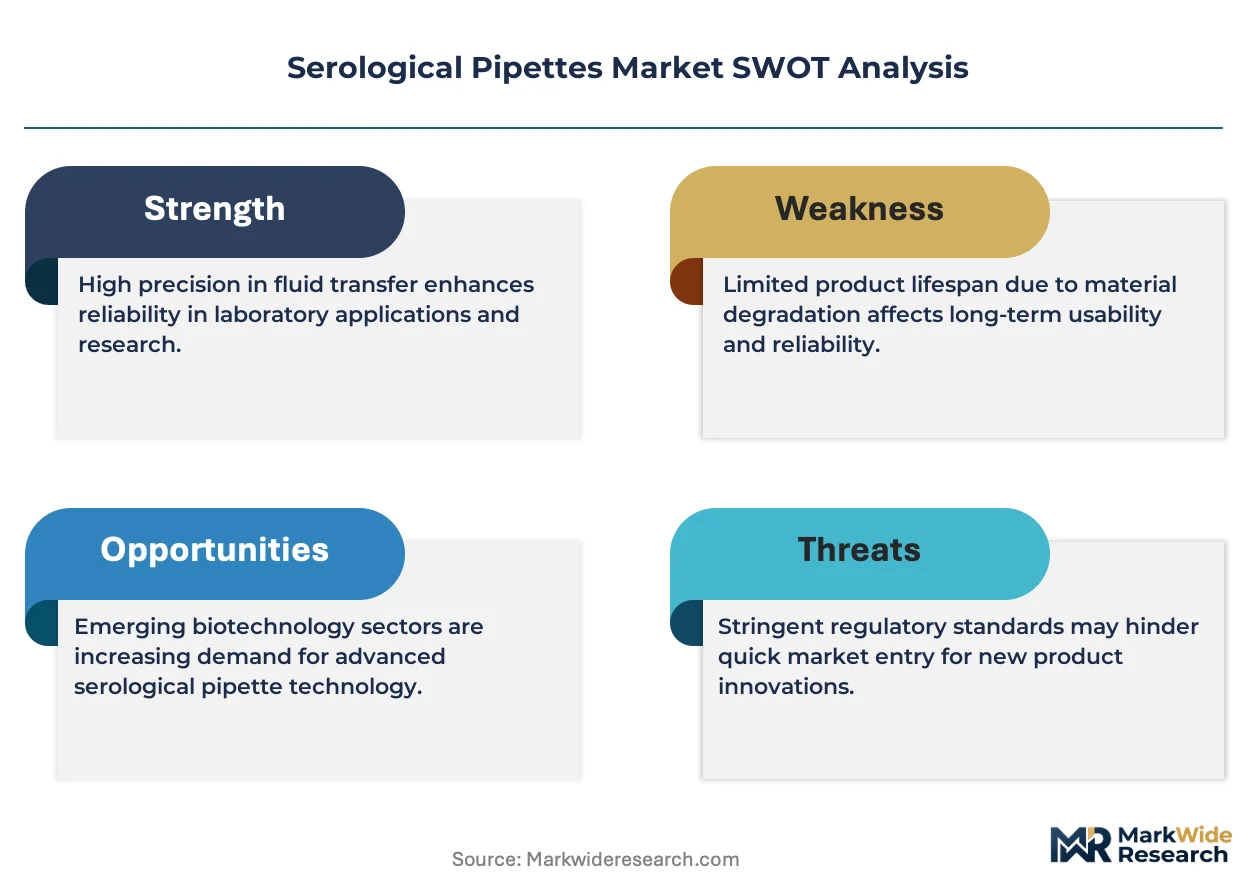
Biologics manufacturing scale-up is concentrating procurement power among pharmaceutical contract manufacturers, forcing serological pipette suppliers to align with ISO 8655 calibration mandates and single-use plastic compliance timelines.
Growth Catalysts
- Biologics manufacturing expansion:Cell culture workflows in monoclonal antibody production consume serological pipettes at elevated volumes, with pharmaceutical companies standardizing on disposable plastic formats to eliminate cross-contamination risk.
- REACH substance restrictions:European chemical regulations are accelerating material transitions toward bio-based polystyrene alternatives, creating first-mover advantages for manufacturers with certified sustainable supply chains.
- Academic research funding:United States NIH grant allocations are expanding laboratory infrastructure at research universities, directly lifting serological pipette procurement in cell biology and virology departments.
Market Restraints
- Petrochemical feedstock volatility:Polystyrene resin prices fluctuate with crude oil benchmarks, compressing margins for manufacturers locked into fixed-price hospital supply contracts.
- Single-supplier concentration:Borosilicate glass pipette production clusters in German industrial regions, exposing buyers to geographic supply disruption from energy cost spikes.
- Manual pipetting substitution:Electronic liquid handling systems are capturing volume in high-throughput screening facilities, displacing serological pipettes in applications above 5 mL transfer volumes.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO regulatory harmonization with ISO standards is opening import pathways for calibrated serological pipettes serving domestic vaccine production facilities.
- Automated platform integration:Multi-channel serological pipette variants are converging with robotic liquid handling systems in contract research organizations, enabling new specification tiers.
- Extended producer responsibility schemes:Germany's single-use plastic regulations are creating compliance-service revenue streams for manufacturers offering take-back programs and material traceability.
Industry Challenges
- ISO 8655 calibration technician shortage:Certified metrology labs face capacity constraints as pharmaceutical quality control departments demand documented accuracy verification for every pipette lot.
- Legacy equipment compatibility:Automated pipetting systems require dimensional standardization that conflicts with legacy serological pipette tolerances, forcing dual-sku maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serological Pipettes Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Channel, Multi-Channel, Adjustable Volume, Fixed Volume Material: Plastic, Glass, Polypropylene, Polystyrene End User: Laboratories, Hospitals, Research Institutions, Pharmaceutical Companies Volume Capacity: 1 mL, 5 mL, 10 mL, 25 mL |
| Companies Covered | Thermo Fisher Scientific, Corning Incorporated, Eppendorf, Merck KGaA, Sartorius, Greiner Bio-One, VWR (Avantor), Sarstedt, BRAND GMBH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serological Pipettes Market Strategic Shifts
Material science breakthroughs and regulatory compliance automation are restructuring how serological pipettes are specified, sourced, and validated across life sciences workflows.
Graduated bio-based polystyrene formulations are rewriting material selection criteria in European pharmaceutical quality control laboratories. Sanofi and Roche manufacturing sites are piloting these alternatives to preempt REACH compliance deadlines. The technology is rewriting supplier qualification protocols by introducing renewable content certification as a mandatory bid requirement.
EPA's emerging single-use plastics framework is pressuring manufacturers toward mass-balance accounting and recycled content verification. Industrial consequence includes mandatory supply chain documentation for federal procurement contracts. Academic research institutions in California and Massachusetts are most affected, with purchasing departments now requiring sustainability scorecards alongside ISO 8655 certificates.
Direct-to-laboratory ecommerce platforms are compressing distributor margins and accelerating switching cycles among small research groups. Amazon Business and VWR's digital storefronts are displacing traditional medical supply house relationships in university settings. This pattern is most visible in United States academic medical centers, where procurement autonomy has shifted to principal investigators managing grant-funded equipment budgets.
Serological Pipettes Market Segmentation
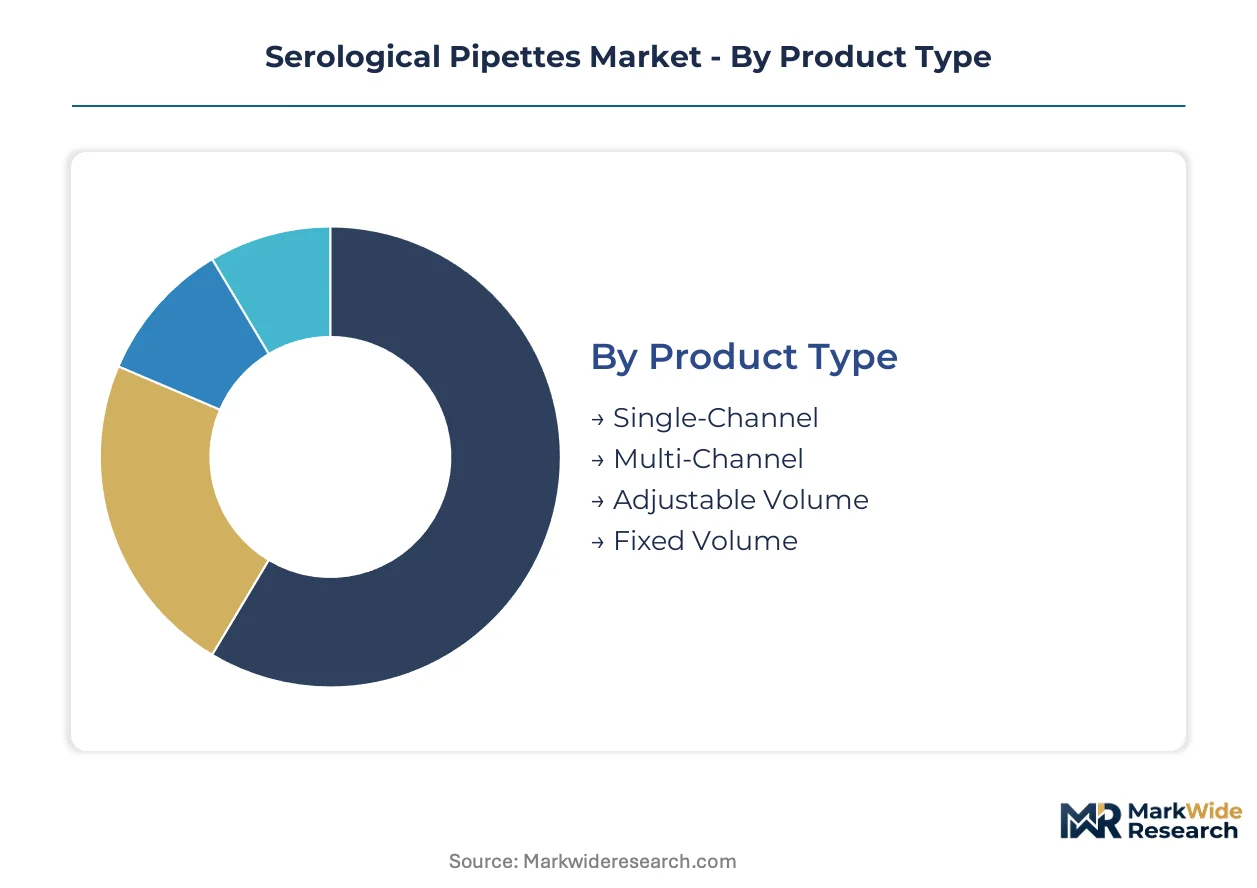
Serological pipette specification varies sharply across workflow requirements, with material chemistry and channel architecture determining compatibility with automated platforms and sterile handling protocols. Procurement patterns diverge between high-throughput pharmaceutical manufacturing and grant-funded academic research, creating distinct performance tiers.
Product Type:
Volume concentration favors single-use disposable formats, while premium positioning attaches to precision-adjustable and multi-channel variants serving automated workflows.
- Single-Channel:Disposable polystyrene construction dominates cell culture media exchange and reagent preparation in pharmaceutical quality control laboratories. Thermo Fisher Scientific and Corning Incorporated anchor supply chains serving United States biologics manufacturers with ISO 8655-certified lots.
- Multi-Channel:Eight- and twelve-channel configurations integrate with robotic liquid handling platforms at contract research organizations, commanding specification premiums for dimensional tolerances that ensure tip alignment. Demand concentrates in automated high-throughput screening facilities displacing manual pipetting above 5 mL volumes.
- Adjustable Volume:Thumb-wheel or plunger-based volume selection serves method development laboratories requiring flexibility across protocol ranges.
- Fixed Volume:Factory-calibrated single-volume designs minimize operator error in clinical diagnostics workflows with standardized transfer requirements.
Mature deployment sits with Single-Channel formats. Newer deployment is concentrated in Multi-Channel variants.
Material:
Cost structure and chemical resistance requirements split procurement between commodity thermoplastics and specialized polymers.
- Plastic:Virgin polystyrene resin dominates disposable manufacturing, with bio-based formulations gaining traction at Sanofi and Roche European sites to preempt REACH compliance deadlines. Petrochemical feedstock volatility compresses margins for manufacturers locked into fixed-price hospital supply contracts.
- Polypropylene:Thermal stability and solvent resistance serve pharmaceutical quality control laboratories handling aggressive reagents or autoclaving protocols. CDSCO regulatory harmonization in India is opening import pathways for calibrated polypropylene pipettes serving domestic vaccine production facilities.
- Glass:Borosilicate construction retains niche demand for solvent compatibility and reusability in analytical chemistry workflows.
- Polystyrene:Optical clarity and moldability support graduated marking precision in high-volume disposable production.
Procurement gravity centers on Plastic for disposability. Specification premiums attach to Polypropylene where chemical resistance matters.
End User:
Funding mechanisms and contamination risk tolerance create distinct purchasing behaviors across institutional categories.
- Pharmaceutical Companies:Biologics manufacturing scale-up concentrates procurement power among contract manufacturers, forcing alignment with ISO 8655 calibration mandates and single-use plastic compliance timelines. Monoclonal antibody production consumes serological pipettes at elevated volumes with standardized disposable formats.
- Research Institutions:United States NIH grant allocations expand laboratory infrastructure at research universities, directly lifting procurement in cell biology and virology departments. Principal investigators managing grant-funded equipment budgets now drive purchasing autonomy through Amazon Business and VWR digital storefronts.
- Laboratories:Clinical diagnostics volume operates on distributor contracts with stringent lot traceability requirements.
- Hospitals:Sterile liquid handling for patient sample processing demands compliance with FDA quality system regulations and ISO 13485 medical device standards.
Volume concentration sits with Pharmaceutical Companies. Fastest expansion trajectory runs through Research Institutions.
Volume Capacity:
Workflow scale and liquid handling precision determine specification across the graduated range.
- 5 mL:Mid-range capacity balances handling ergonomics with sufficient volume for cell culture media exchange in biologics manufacturing, serving as the workhorse specification for pharmaceutical quality control departments.
- 10 mL:Extended length designs accommodate deep vessel access in large-scale reagent preparation, with demand concentrating at contract research organizations automating buffer formulation workflows.
- 1 mL:Precision applications in micro-volume reagent preparation and clinical diagnostics.
- 25 mL:Bulk media transfer in vaccine production and industrial cell culture scale-up.
Procurement scale peaks at 5 mL. Automation compatibility investments concentrate at 10 mL.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polystyrene resin production clusters along the US Gulf Coast anchor raw material flows into serological pipette manufacturing. Pharmaceutical biologics output and academic research funding intensity determine regional demand hierarchies.
United States
NIH grant allocations exceeding historical baselines expand laboratory infrastructure at Johns Hopkins, Stanford, and MIT cell biology departments. FDA quality system regulations and ISO 13485 medical device standards govern traceability for hospital and diagnostic laboratory procurement. The Boston-Cambridge biotech corridor concentrates monoclonal antibody manufacturing, consuming disposable plastic pipettes at elevated volumes for media exchange workflows.
Germany
Borosilicate glass pipette production concentrates in industrial regions facing energy cost volatility from natural gas price spikes. REACH substance restrictions and emerging single-use plastic regulations under extended producer responsibility schemes accelerate bio-based polystyrene transitions. The Rhine-Main cluster around Frankfurt anchors pharmaceutical quality control laboratories piloting certified sustainable supply chains at Sanofi and Roche manufacturing sites.
China
Domestic vaccine production scale-up drives import demand for calibrated serological pipettes as CDSCO-equivalent standards harmonize with ISO 8655. NMPA medical device regulations and GB standards shape local manufacturing protocols for export-oriented producers. The Yangtze River Delta around Shanghai concentrates contract research organizations automating liquid handling platforms with multi-channel pipette specifications.
India
CDSCO regulatory harmonization with ISO standards opens import pathways for calibrated pipettes serving domestic vaccine production at Serum Institute and Bharat Biotech facilities. Central government PLI scheme incentives for pharmaceutical manufacturing expand laboratory infrastructure in Hyderabad and Bangalore. The Genome Valley cluster in Telangana anchors contract research organization demand for precision liquid handling consumables.
Japan
PMDA pharmaceutical manufacturing standards and METI industrial policy support precision liquid handling technology adoption in regenerative medicine workflows. Academic research funding through Japan Society for the Promotion of Science sustains university laboratory procurement in cell biology applications. The Kansai region around Osaka concentrates specialized polymer processing for thermal-stable polypropylene pipettes serving quality control laboratories.
Serological Pipettes Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue automated platform integration and sustainable material certifications. The vendor base stratifies across three tiers: integrated life sciences conglomerates with full-platform offerings, specialized cell culture consumable manufacturers, and precision liquid handling technology developers. Two dominant competitive moves are reshaping positioning: strategic partnerships with robotic liquid handling system vendors, and backward integration into certified metrology services for ISO 8655 calibration documentation.
Among diversified life sciences conglomerates, Thermo Fisher Scientific and Corning Incorporated exemplify platform-anchored positioning that bundles serological pipettes within integrated cell culture workflows. Eppendorf occupies a specialist tier focused on precision liquid handling technology extending into automated pipetting systems. These three entities represent distinct archetypes—full-platform integration, deep workflow specialization, and precision instrumentation—rather than direct substitutability in procurement decisions.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Corning Incorporated |
| Eppendorf |
| Merck KGaA |
| Sartorius |
| Greiner Bio-One |
| VWR (Avantor) |
| Sarstedt |
| BRAND GMBH |
| Others |
Value Chain & Pricing Dynamics
Certified ISO 8655 calibration technician pools in Germany and the United States create labor-cost differentials that widen pricing-tier spreads between premium certified lots and standard disposable formats. European REACH compliance investments and resin feedstock volatility further stratify cost structures across manufacturing footprints.
Pricing Analysis
Volume concentration in single-channel disposable formats compresses margins at the economy tier, while multi-channel precision variants command specification premiums through ISO 8655 certification tiers and robotic platform compatibility. Price differentiation hinges on calibration documentation depth and material chemistry—bio-based polystyrene alternatives carry cost premiums over virgin resin formats. Pricing pressure stems from petrochemical feedstock volatility squeezing manufacturers locked into fixed-price hospital supply contracts. Academic research institutions exhibit highest price sensitivity through grant-funded budgets and direct-to-laboratory ecommerce switching, whereas pharmaceutical contract manufacturers prioritize lot traceability and calibration compliance over unit cost.
Supply Chain Analysis
Workforce availability for precision molding and metrology certification concentrates in Germany, the United States, and China, shaping regional production economics and export capacity. Virgin polystyrene resin and borosilicate glass tubing serve as primary raw material anchors, with bio-based polymer feedstocks emerging as compliance-driven alternatives. Supply chain risk centers on single-source concentration for borosilicate glass production in German industrial regions exposed to energy cost spikes. Distribution runs through integrated life sciences distributors, direct-to-laboratory ecommerce platforms, and specialized cell culture consumable channels serving pharmaceutical quality control laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The serological pipettes market is becoming a vertical-integration race, with manufacturers pursuing backward integration into certified metrology services to lock in ISO 8655 calibration documentation capabilities.
For Market Incumbents: Anchor market position through captive metrology lab investments that secure calibration technician capacity against industry-wide shortages threatening lot release timelines. Deepen specialization in cell culture workflow bundling to defend against electronic liquid handling system substitution in high-throughput screening applications. Prioritize bio-based polystyrene supply chain certification to preempt REACH compliance deadlines and capture pharmaceutical sustainability procurement mandates. For New Entrants and Emerging Players: Begin with automated platform integration partnerships targeting contract research organizations in the Yangtze River Delta and Genome Valley clusters where robotic liquid handling adoption outpaces legacy supply relationships. Exploit calibration documentation backlogs at incumbent metrology labs by offering expedited ISO 8655 certification services as a service wedge. Pursue white-label supply arrangements with Indian vaccine manufacturers navigating CDSCO regulatory harmonization. For Investors and Strategic Acquirers: The window for entry favors precision liquid handling technology developers with embedded software capabilities and automated platform compatibility. Long-term viability hinges on consolidation of fragmented metrology service providers into scalable calibration documentation platforms. Monitor EPA single-use plastics framework implementation velocity and extended producer responsibility scheme adoption in Germany as inflection signals for material transition investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metrology Services | Captive ISO 8655 calibration capacity secures lot release timelines against technician shortages constraining pharmaceutical quality control departments. |
| Bio-Based Polystyrene Supply Chain Certification | Renewable content verification preempts REACH compliance deadlines and unlocks Sanofi and Roche sustainable procurement mandates. |
| Robotic Platform Integration Partnerships | Multi-channel dimensional standardization aligns with automated liquid handling adoption at contract research organizations displacing manual pipetting. |
| Direct-to-Laboratory Ecommerce Channel Expansion | Amazon Business and VWR digital storefronts capture principal investigator purchasing autonomy in NIH-funded research universities. |
| Extended Producer Responsibility Program Launch | Germany's single-use plastic regulations create compliance-service revenue streams through take-back programs and material traceability offerings. |
Study Parameters
Regulatory filings from FDA, ECHA, and CDSCO, trade databases tracking polystyrene resin flows, and pharmaceutical manufacturing capacity announcements formed the secondary backbone for this analysis. Primary interviews with quality control laboratory managers, biomedical procurement officers at academic medical centers, calibration metrology technicians, and contract research organization automation engineers validated demand assumptions and pricing dynamics. Bottom-up triangulation across product type, material chemistry, and end-user segmentations was cross-checked against top-down macro indicators including NIH grant allocations and biologics manufacturing capacity expansion announcements.
Historical trendline analysis of serological pipette procurement patterns across pharmaceutical, academic research, and clinical diagnostic end-use segments established baseline growth trajectories. The analytical framework modeled volume and value outputs across the projection horizon through segmentation dimensions including channel architecture, material compliance tier, calibration certification level, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating biologics manufacturing scale-up rates and automated platform penetration assumptions in high-throughput screening facilities.
Underlying measurement precision varies by segment; multi-channel precision variants and pharmaceutical company procurement carry tighter precision than economy-tier academic research volumes. Forecasts reflect documented assumptions regarding REACH substance restriction timelines and EPA single-use plastics framework implementation. Material deviation in biologics manufacturing capital expenditure cycles, energy cost volatility affecting German glass production, or calibration technician training program expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Disposable Blood Bags Market
Medical Supplies
Disposable Hospital Supplies Market
Medical Supplies
Medical Plastics Market
Medical Supplies
Medical Gauze and Tapes Market
Medical Supplies
Custom Procedure Packs (CPT) Market
Medical Supplies
X-Ray Aprons Market
Medical Supplies
Mortuary Bags Market
Medical Supplies
Yankauer Suction Tips Market
Medical Supplies
Disposable Medical Supplies Market
Medical Supplies
Japan Hospital Supplies Market
Medical Supplies
Esophageal Obturator Airway Kits Market
Medical Supplies
Cryopreservation & Fertilization Media Market
Medical Supplies
Lavage Kits Market
Medical Supplies
Global Needles Market
Medical Supplies
Catheter Tip Syringe Market
Medical Supplies
Medical Tourniquets Market