
 Cough and Cold Preparations Market | 2026-2036
Cough and Cold Preparations Market Size, Share, and Industry Trends Forecast 2026-2036
Cough and Cold Preparations Market Insights
Aftermarket service revenue from patient support programs and adherence monitoring is rewriting how OTC respiratory brands capture lifetime value. Johnson & Johnson leverages its consumer health spin-off structure to sustain focused R&D intensity in nasal decongestant formulations. GlaxoSmithKline plc anchors its portfolio through geographic dominance in European pharmacy channels, while Pfizer competes via manufacturing scale across multi-symptom combination therapies.
Cough and cold preparations comprise pharmacologically active formulations—typically containing expectorants such as guaifenesin, antitussives such as dextromethorphan, or decongestants such as pseudoephedrine—manufactured through wet granulation or direct compression processes to achieve specified dissolution profiles for rapid symptom relief. Their primary commercial purpose centers on enabling self-directed management of acute upper respiratory symptoms without prescription oversight. Antitussives and expectorants together occupy the largest margin pools within product type segmentation, driven by recurring seasonal demand and established clinical familiarity among prescribers and consumers. Liquid and syrup formulations lead in pediatric and geriatric use cases where swallowing tablets presents adherence barriers, while tablet formats dominate adult convenience-oriented purchasing through drugstore and supermarket channels.
The FDA oversees OTC monograph reform that determines which active ingredients remain generally recognized as safe and effective, directly constraining permissible formulations and labeling claims for US-marketed products. The EPA regulates certain volatile organic compounds in propellant-based nasal delivery systems, shaping inhaler and spray product development pathways. EMA's evolving stance on codeine-containing antitussives in pediatric populations creates divergent formulation requirements across Atlantic markets. Stakeholders must monitor pending monograph updates and propellant phase-out timelines to align R&D pipelines with compliant commercialization pathways.
Market Dynamics
Retail pharmacy chains are aggressively consolidating private-label manufacturing capacity to capture margin pools previously held by branded OTC respiratory players, compressing formulation differentiation into supply-chain execution speed.
Growth Catalysts
- Self-medication behavioral normalization:Post-pandemic consumer comfort with symptom self-assessment sustains OTC purchasing velocity through pharmacy and supermarket channels without clinician gatekeeping.
- FDA OTC monograph reform momentum:Streamlined ingredient recognition pathways accelerate time-to-market for novel decongestant and antitussive formulations previously stalled in regulatory backlog.
- Pediatric formulation gaps:Unmet need for alcohol-free, dye-free liquid preparations in children under six creates dedicated R&D investment from specialized contract manufacturers.
Market Restraints
- Pseudoephedrine precursor controls:DEA tracking mandates and purchase-quantity limits impose inventory management complexity on retailers, elevating operational costs in multi-state distribution networks.
- API supply concentration:Guaifenesin and dextromethorphan active pharmaceutical ingredient production clusters in specific Asian manufacturing zones, exposing formulators to single-source disruption risk.
- Propellant phase-out timelines:EPA volatile organic compound restrictions on chlorofluorocarbon-based nasal spray delivery systems force capital-intensive reformulation of established metered-dose products.
Strategic Opportunities
- Rural pharmacy underserved segments:Independent drugstores in non-metropolitan United States counties lack private-label alternatives, creating white-space for regional contract manufacturing partnerships.
- Digital therapeutics convergence:Integration of symptom-tracking smartphone applications with adherence-optimized packaging formats enables subscription-based recurring revenue models.
- Clean-label ingredient mandates:Retailer-imposed restrictions on artificial sweeteners and synthetic colorants in pediatric segments reward early reformulation with shelf-placement premiums.
Industry Challenges
- Skilled formulation chemist scarcity:Wet granulation expertise for rapid-dissolution tablet engineering concentrates among aging specialists, constraining capacity expansion at mid-tier contract manufacturers.
- Multi-jurisdiction labeling complexity:Divergent FDA and EMA pediatric codeine warnings force parallel SKU maintenance, fragmenting production runs and elevating quality-assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cough and Cold Preparations Market |
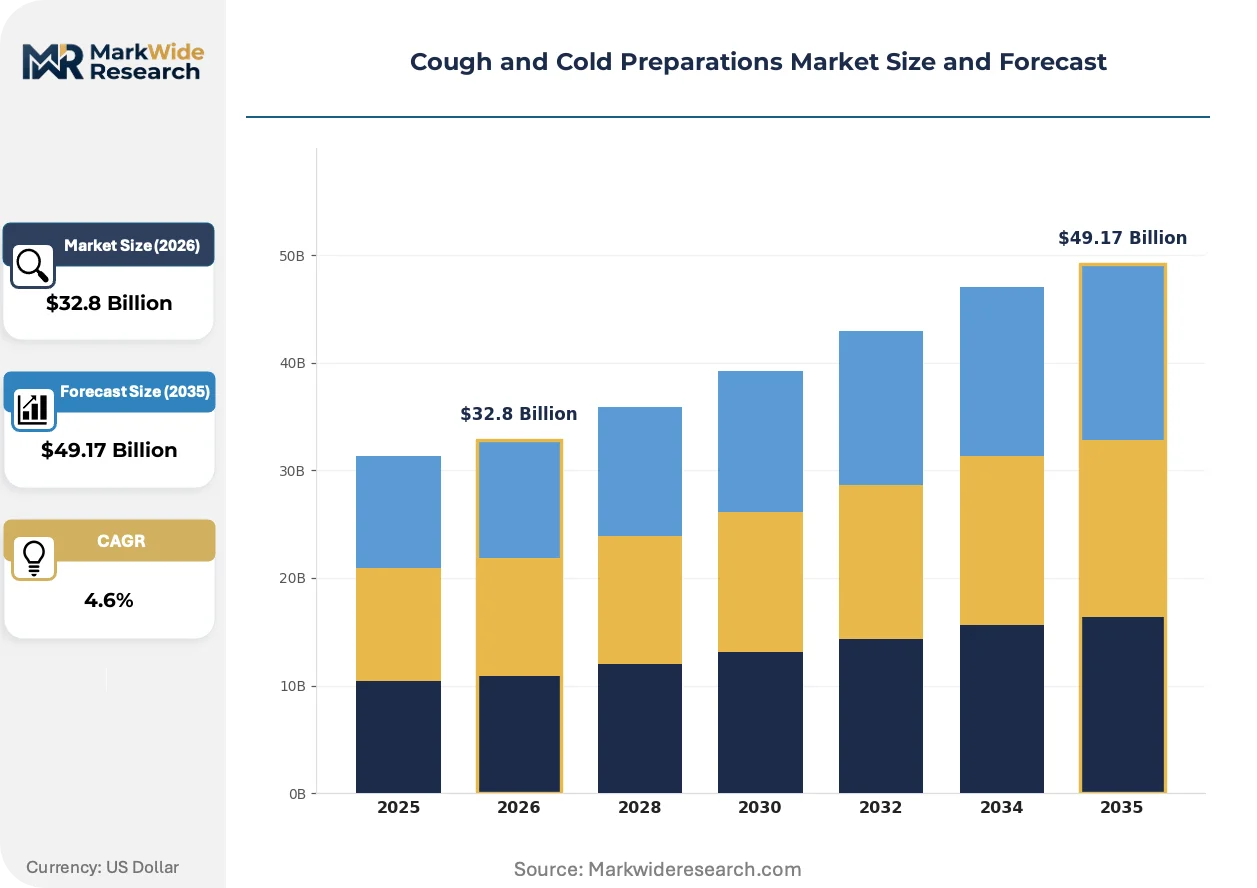
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Expectorants, Antitussives, Decongestants, Antihistamines End User: Retail Customers, Hospitals, Pharmacies, Clinics Formulation: Liquid, Tablet, Syrup, Powder Distribution Channel: Online, Offline, Supermarkets, Drugstores |
| Companies Covered | Johnson & Johnson, GlaxoSmithKline plc, Procter & Gamble, Bayer AG, Pfizer, Novartis AG, Reckitt Benckiser Group plc, Sun Pharmaceutical Industries Ltd., AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cough and Cold Preparations Market Trends and Innovations
Formulation science and distribution architecture are undergoing simultaneous compression, collapsing traditional boundaries between symptom-specific and multi-symptom product categories while digital channels rewire how consumers discover and replenish respiratory remedies.
Hot-melt extrusion technology for solid-dose cough suppressants is collapsing the dissolution-rate gap between premium immediate-release tablets and economy-tier alternatives. Pediatric and geriatric-focused contract manufacturers in the United States Midwest are adopting these systems to serve private-label pharmacy chains demanding bioequivalence at compressed price points. The technology is collapsing three-tier pricing stratification into two performance-differentiated tiers, eliminating mid-market positioning.
EMA's evolving restrictions on codeine-containing antitussives for pediatric populations are forcing European formulators toward dextromethorphan-only and phytochemical alternatives. Manufacturers serving German and French pharmacy channels must maintain parallel inventory systems to satisfy divergent national interpretations of pediatric safety thresholds. Liquid formulation specialists are responding with alcohol-free, single-active-ingredient SKUs that simplify regulatory compliance across Atlantic markets.
Direct-to-consumer subscription models for seasonal respiratory preparedness kits are displacing acute symptom-driven pharmacy visits among urban millennial households. These bundled offerings combine diagnostic thermometers, rapid-test strips, and multi-symptom preparations with automated replenishment algorithms. The shift is most visible in United States coastal metropolitan markets where same-day delivery infrastructure supports just-in-time inventory positioning ahead of viral seasonality.
Cough and Cold Preparations Market Segmentation
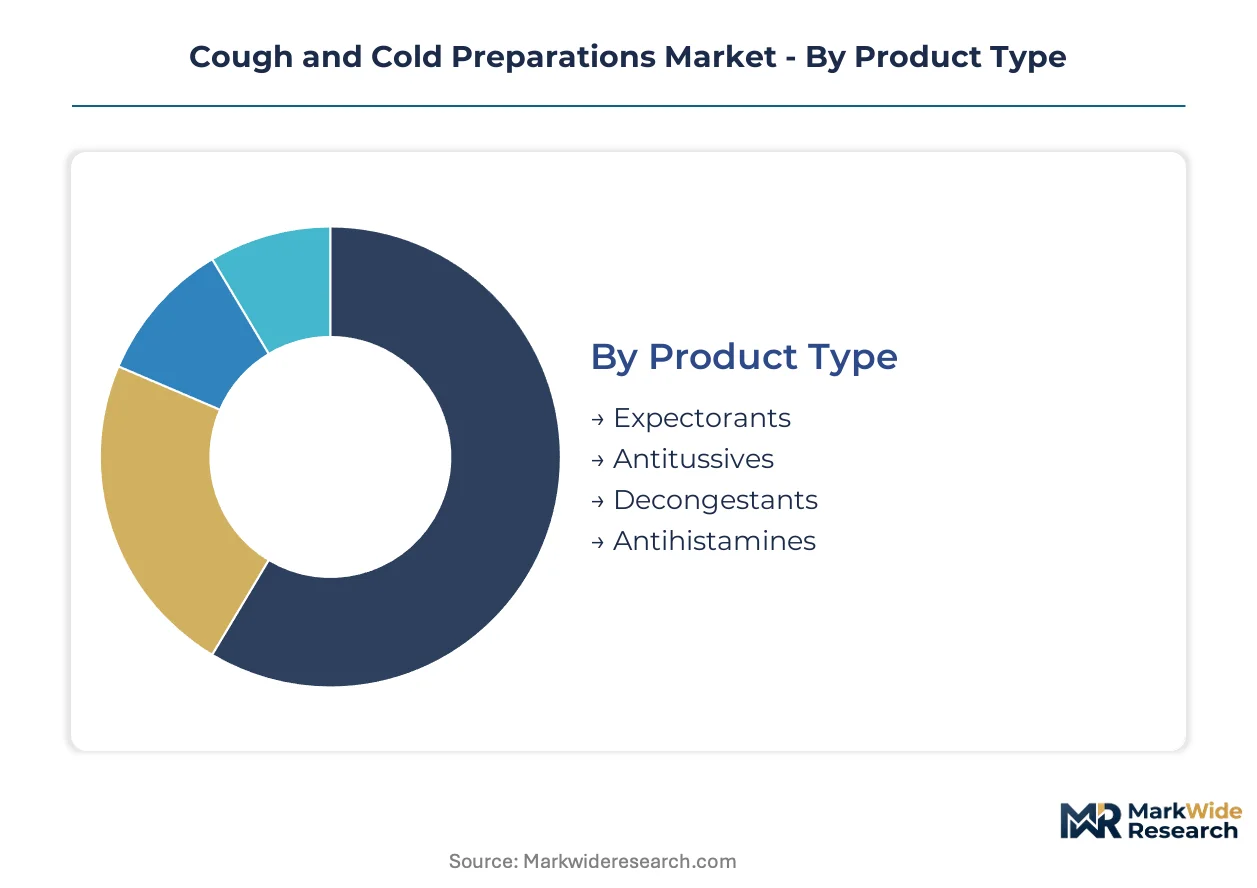
Respiratory remedy manufacturers configure production lines around formulation physics and channel velocity rather than therapeutic class alone. Inventory turnover varies dramatically across liquid syrups versus solid tablets, forcing working capital allocation decisions that shape margin capture.
Product Type:
Cycle times compress fastest for single-ingredient decongestants during acute viral surges, while multi-symptom combinations maintain steadier year-round throughput.
- Expectorants:Guaifenesin-based formulations thin bronchial secretions through osmotic action in respiratory epithelium. Demand concentrates in United States retail pharmacy chains where self-directed chest congestion management drives repeat purchase velocity during winter respiratory seasons.
- Antitussives:Dextromethorphan suppresses cough reflex through sigma-1 receptor agonism in the medulla. European pharmacy channels in Germany and France absorb volume as EMA pediatric codeine restrictions redirect prescribing toward non-narcotic alternatives.
- Decongestants:Pseudoephedrine and phenylephrine formulations shrink nasal mucosa through alpha-adrenergic agonism; DEA purchase tracking in the United States imposes inventory friction that slows turnover versus other product types.
- Antihistamines:First-generation compounds like diphenhydramine address rhinorrhea through H1 receptor antagonism; nighttime formulations sustain shelf presence in supermarket cough-and-cold aisles.
Expectorants anchor the volume base while antitussives gain share at the steepest rate.
End User:
Procurement authority and formulary control separate institutional buyers from self-pay consumers, creating price tier stratification that doubles margin spreads.
- Retail Customers:Direct-to-consumer purchasers select symptom-specific SKUs without clinical gatekeeping; United States direct-to-consumer advertising sustains brand premium capture in this channel.
- Hospitals:Inpatient formulary committees standardize on multi-symptom combinations to reduce nursing administration complexity; purchasing concentrates through group purchasing organizations in metropolitan United States health systems.
- Pharmacies:Community and chain drugstores serve both acute walk-in demand and seasonal stockpiling behavior; private-label penetration runs highest here as retailers capture margin from branded alternatives.
- Clinics:Urgent care and primary care settings dispense limited OTC portfolios for immediate symptom relief; reimbursement friction constrains volume relative to pharmacy channels.
Retail customers dominate absolute volume while hospital procurement expands most quickly as health systems consolidate formulary management.
Formulation:
Manufacturing capital intensity and packaging economics drive channel placement, with liquids requiring blow-fill-seal equipment that excludes smaller contract manufacturers.
- Liquid:Aqueous suspensions and solutions enable dose titration for pediatric populations; alcohol-free variants command shelf-placement premiums in United States retailers imposing clean-label mandates.
- Tablet:Direct-compression and wet-granulation solid doses dominate adult convenience purchasing through drugstore and supermarket channels; hot-melt extrusion technology collapses dissolution-rate differentiation between tiered price points.
- Syrup:Viscous preparations with sweetening agents improve palatability for geriatric and pediatric adherence; viscosity specifications vary by national pharmacopeia, fragmenting SKU requirements.
- Powder:Sachet and effervescent formats address travel and on-the-go consumption occasions; manufacturing concentrates in Asian contract manufacturers serving private-label importers.
Tablets anchor the volume base while liquid formulations climb the fastest as clean-label pediatric demand intensifies.
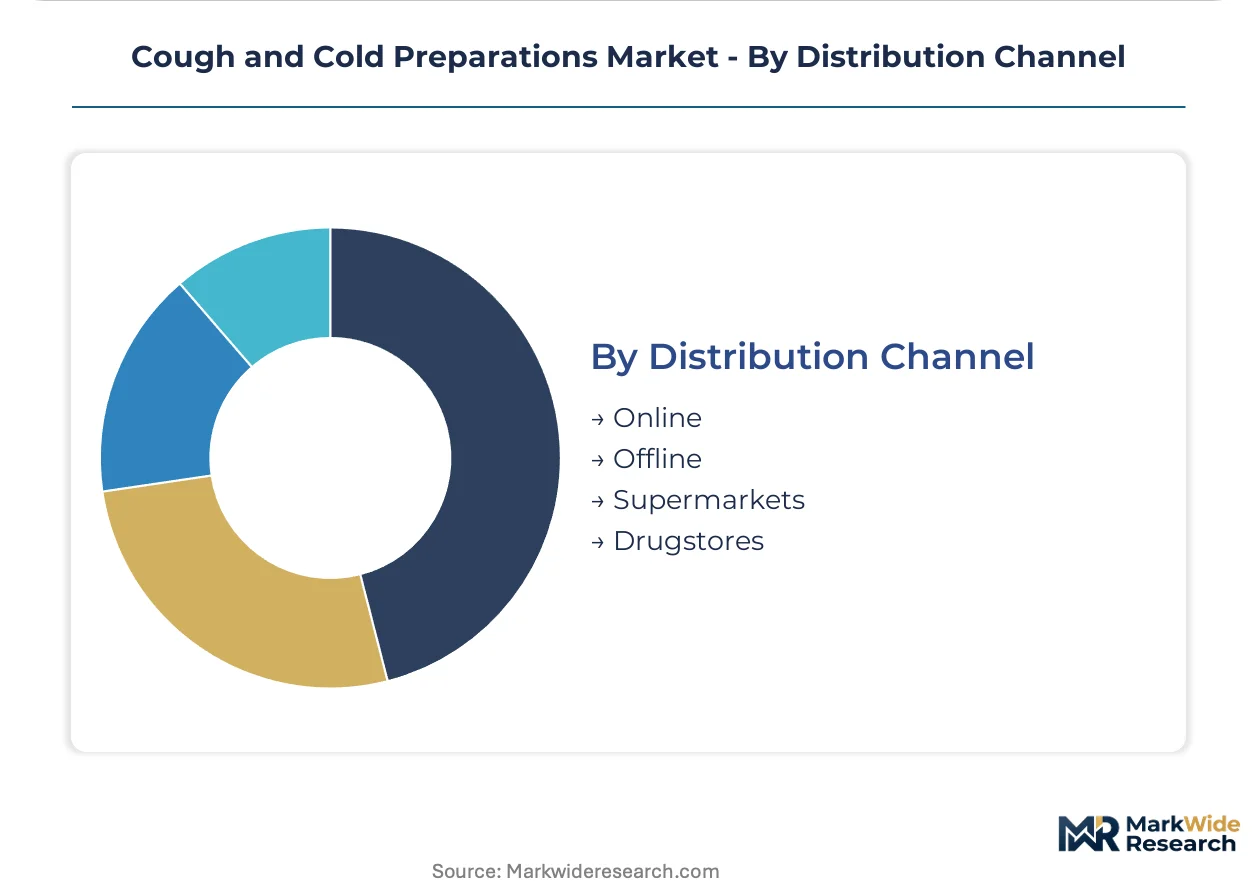
Distribution Channel:
Fulfillment speed and inventory carrying cost separate digital-native from brick-and-mortar economics, with same-day delivery infrastructure determining urban market capture.
- Online:E-commerce platforms and pharmacy-owned digital storefronts enable subscription-based seasonal preparedness kits; automated replenishment algorithms sustain recurring revenue in United States coastal metropolitan markets.
- Offline:Traditional wholesale-to-retail distribution maintains reach in rural United States counties lacking same-day delivery density; independent drugstores in non-metropolitan regions depend on this channel exclusively.
- Supermarkets:Mass merchandisers combine cough-and-cold sets with broader grocery shopping trips; seasonal display placement ahead of viral seasonality drives impulse velocity.
- Drugstores:Pharmacy chains leverage private-label manufacturing partnerships to capture margin pools previously held by branded OTC players; formulation differentiation compresses into supply-chain execution speed.
Drugstores anchor the volume base while online channels expand most quickly as subscription models displace acute symptom-driven purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing for guaifenesin and dextromethorphan concentrates in Chinese and Indian chemical clusters, exposing formulators to concentrated supply disruption risk. Finished dose production disperses across United States, European, and Asian markets with distinct regulatory compliance requirements.
United States
Direct-to-consumer advertising sustains brand premium capture in pharmacy and supermarket channels, with per-capita OTC consumption exceeding other developed markets. FDA OTC monograph reform accelerates novel decongestant approvals while DEA pseudoephedrine tracking mandates elevate retailer operational costs. New Jersey and Pennsylvania host concentrated formulation R&D facilities serving private-label pharmacy chains.
Germany
EMA pediatric codeine restrictions redirect prescribing toward dextromethorphan-only alternatives, expanding antitussive volume in pharmacy channels. Germany's national pharmaceutical regulator enforces strict alcohol-content labeling for pediatric liquid preparations. Bavaria and North Rhine-Westphalia anchor European contract manufacturing capacity for alcohol-free, dye-free formulations.
China
Domestic API production clusters in Shandong and Jiangsu provinces supply global guaifenesin and dextromethorphan requirements. NMPA oversight of OTC monograph categories constrains permissible active ingredient combinations for domestic-marketed products. Yangtze River Delta chemical parks are upgrading environmental compliance standards for propellant-based nasal spray component manufacturing.
India
Cost-competitive contract manufacturing attracts private-label sourcing from United States and European pharmacy chains seeking margin compression. CDSCO pediatric safety warnings on codeine-containing preparations align formulation portfolios with EMA standards. Gujarat and Maharashtra host concentrated effervescent and powder sachet production for export markets.
United Kingdom
Pharmacy channel consolidation limits independent drugstore access to private-label alternatives, preserving branded OTC market structure. MHRA post-Brexit regulatory divergence from EMA creates parallel compliance pathways for codeine-containing antitussives. Southeast England maintains formulation development clusters serving subscription-based direct-to-consumer respiratory kit providers.
Cough and Cold Preparations Market Competitive Landscape
Multinational consumer health conglomerates and specialized pharmaceutical manufacturers split the market between scale-driven brand portfolios and agile contract formulation services. Three strategic archetypes dominate: diversified healthcare conglomerates with spun-off consumer divisions, European pharmacy-channel specialists with geographic density advantages, and Asian contract manufacturers capturing private-label margin pools. Competitive positioning depends on M&A activity consolidating manufacturing capacity and strategic partnerships securing API supply continuity.
Among diversified healthcare conglomerates, Johnson & Johnson and GlaxoSmithKline plc exemplify divergent structural approaches to respiratory OTC positioning. Johnson & Johnson's consumer health spin-off architecture enables focused R&D intensity in nasal decongestant categories. GlaxoSmithKline plc occupies a position anchored through European pharmacy channel dominance. Pfizer represents the manufacturing-scale archetype across multi-symptom combination therapies, sitting within the tier prioritizing production volume and distribution breadth over formulation specialization.
| Leading Market Players |
|---|
| Johnson & Johnson |
| GlaxoSmithKline plc |
| Procter & Gamble |
| Bayer AG |
| Pfizer |
| Novartis AG |
| Reckitt Benckiser Group plc |
| Sun Pharmaceutical Industries Ltd. |
| AstraZeneca |
| Others |
Pricing and Supply Chain Analysis
Chinese and Indian API manufacturing clusters for guaifenesin and dextromethorphan concentrate upstream supply leverage, directing margin capture toward finished-dose formulators with DEA-compliant distribution infrastructure and pediatric formulation certifications.
Pricing Analysis
FDA OTC monograph reform dictates the pricing tier structure across expectorant, antitussive, and decongestant categories. Three-tier pricing structure across premium, standard, and economy levels separates certified alcohol-free pediatric liquids from conventional tablet formulations. Cost compression in private-label tablet segments is intensifying because hot-melt extrusion technology collapses dissolution-rate differentiation. Hospital group purchasing organizations exhibit lowest price sensitivity while independent rural pharmacies face acute margin pressure.
Supply Chain Analysis
Upstream feedstock dependence on Shandong and Jiangsu province chemical parks for guaifenesin API exposes formulators to environmental compliance upgrade timelines. Dextromethorphan production draws from Gujarat and Maharashtra contract manufacturers, with phenylephrine sourcing concentrated in European specialist facilities. Single-source vulnerability in Asian API supply creates inventory disruption risk during regulatory inspection cycles. Distribution runs through wholesale-to-retail networks for rural coverage and direct-to-pharmacy arrangements for private-label chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through pharmacy chain consolidation and hospital group purchasing organization expansion, fragmenting pricing authority away from branded manufacturers toward procurement intermediaries with formulary control.
For Market Incumbents: Pre-empt private-label displacement by securing exclusive API supply agreements with Shandong and Jiangsu manufacturers before contract manufacturers capture backward integration. Lock in pediatric formulation certifications ahead of retailer-imposed clean-label mandates. Channel control through direct-to-pharmacy distribution partnerships represents the critical defensive lever against margin compression. For New Entrants and Emerging Players: Rural United States counties lacking same-day delivery infrastructure represent the most penetrable entry point for independent drugstore-focused contract manufacturing. Alcohol-free, dye-free liquid formulations for children under six offer unmet need positioning with regulatory differentiation. A go-to-market angle anchored in subscription-based seasonal preparedness kits bypasses entrenched pharmacy shelf competition. For Investors and Strategic Acquirers: Capital is best deployed toward specialized pediatric liquid formulation manufacturers with established FDA monograph compliance and existing pharmacy chain private-label relationships. Long-term viability hinges on regulatory adaptation velocity rather than scale economies alone. The signal to watch is EMA pediatric codeine restriction expansion into additional European markets, which would accelerate dextromethorphan-only formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Certification | FDA alcohol-free liquid approvals secure shelf-placement premiums at major pharmacy chains. |
| API Supply Agreement | Captive guaifenesin sourcing from Shandong manufacturers insulates against single-source disruption. |
| Direct-to-Consumer Subscription Launch | Automated replenishment algorithms sustain recurring revenue in coastal metropolitan markets. |
| Clean-Label Reformulation | Dye-free, artificial-sweetener-free SKUs satisfy retailer-imposed pediatric segment mandates. |
| Hot-Melt Extrusion Adoption | Rapid-dissolution tablet technology collapses price-performance gaps between tiered offerings. |
Research Methodology
A standing panel of regulatory affairs directors at OTC manufacturers, pharmacy chain category buyers, pediatric formulation specialists, and hospital formulary committee members provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with these stakeholders against secondary validation through FDA OTC monograph filings, DEA controlled substance tracking data, EMA pediatric safety assessments, and pharmacy retail audit databases. Bottom-up volume modeling and top-down market sizing triangulated to produce segment-level outputs.
Scenario-bracketing around FDA monograph reform timelines and EMA pediatric codeine restriction expansion shaped the analytical framework. Segmentation dimensions modeled include product type, end user, formulation physics, and distribution channel velocity across the projection horizon. CAGRs derived from historical prescription-to-OTC switch patterns and seasonal demand elasticity coefficients. Forecast inputs incorporated API supply concentration risk weightings and private-label penetration trajectory assumptions.
Practitioners should monitor FDA monograph update announcements and EMA pediatric safety committee rulings for early signals of formulation requirement shifts. Cross-checking against IMS Health retail audit data and pharmacy inventory turnover benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Travel Vaccines Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Global Erectile Dysfunction Drugs Market
Pharmaceuticals
Decongestants Market
Pharmaceuticals
Repurposed Human Immunosuppressants Market
Pharmaceuticals
Oral Anticoagulant Market
Pharmaceuticals
Pharmaceutical Elixir Market
Pharmaceuticals
Prostaglandin Analogs Market
Pharmaceuticals
Inotropic Agent Market
Pharmaceuticals
Saline Laxative Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
H1N1 Vaccination Market
Pharmaceuticals
Cough Syrup Market
Pharmaceuticals
Germany Pneumococcal Vaccines Market
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Nesiritide Market