
 Global Animal Parasiticides Market | 2026-2036
Global Animal Parasiticides Market Size, Share, and Industry Trends Forecast 2026-2036
Global Animal Parasiticides Market Foresight
Indian API manufacturing clusters for veterinary actives is hardening as a supply bottleneck for formulators worldwide. Zoetis leverages its integrated discovery-to-distribution architecture to secure channel access across Latin American cattle markets. Boehringer Ingelheim anchors its position through captive biotechnology platforms for recombinant vaccines against parasitic vectors. Ceva Sante Animale competes by concentrating its manufacturing footprint in European regulatory jurisdictions with stringent residue monitoring protocols.
Animal parasiticides comprise pharmaceutical and biological agents engineered to prevent, control, or eliminate parasitic infections in vertebrate hosts, typically formulated as pour-on solutions, oral drenches, or sustained-release injectables containing macrocyclic lactones, benzimidazoles, or neonicotinoid derivatives. Their primary commercial purpose centers on maintaining feed conversion efficiency in food-producing animals and extending quality-adjusted life years in companion species. Endectocides occupy the deepest margin pools due to their broad-spectrum nematocidal and arthropodicidal activity, while ectoparasiticide demand accelerates fastest in companion animal channels where pet owner willingness-to-pay for topical convenience exceeds livestock procurement thresholds. Injectable formulations sustain premium pricing positions in aquaculture settings where water-mediated dosing complicates bioavailability control.
The US FDA Center for Veterinary Medicine and the EU EMA jointly shape market access through residue limit harmonization and mutual recognition of good manufacturing practice audits, compelling exporters to maintain dual-compliance documentation systems. India's CDSCO enforces phased manufacturing inspections under its revised veterinary drug registration framework, extending approval timelines for foreign applicants. Stakeholders must monitor evolving regulatory divergence between jurisdictions on environmental risk assessments for topical parasiticides, as divergent ecotoxicity standards threaten to fragment formulation strategies and complicate global product registration portfolios.
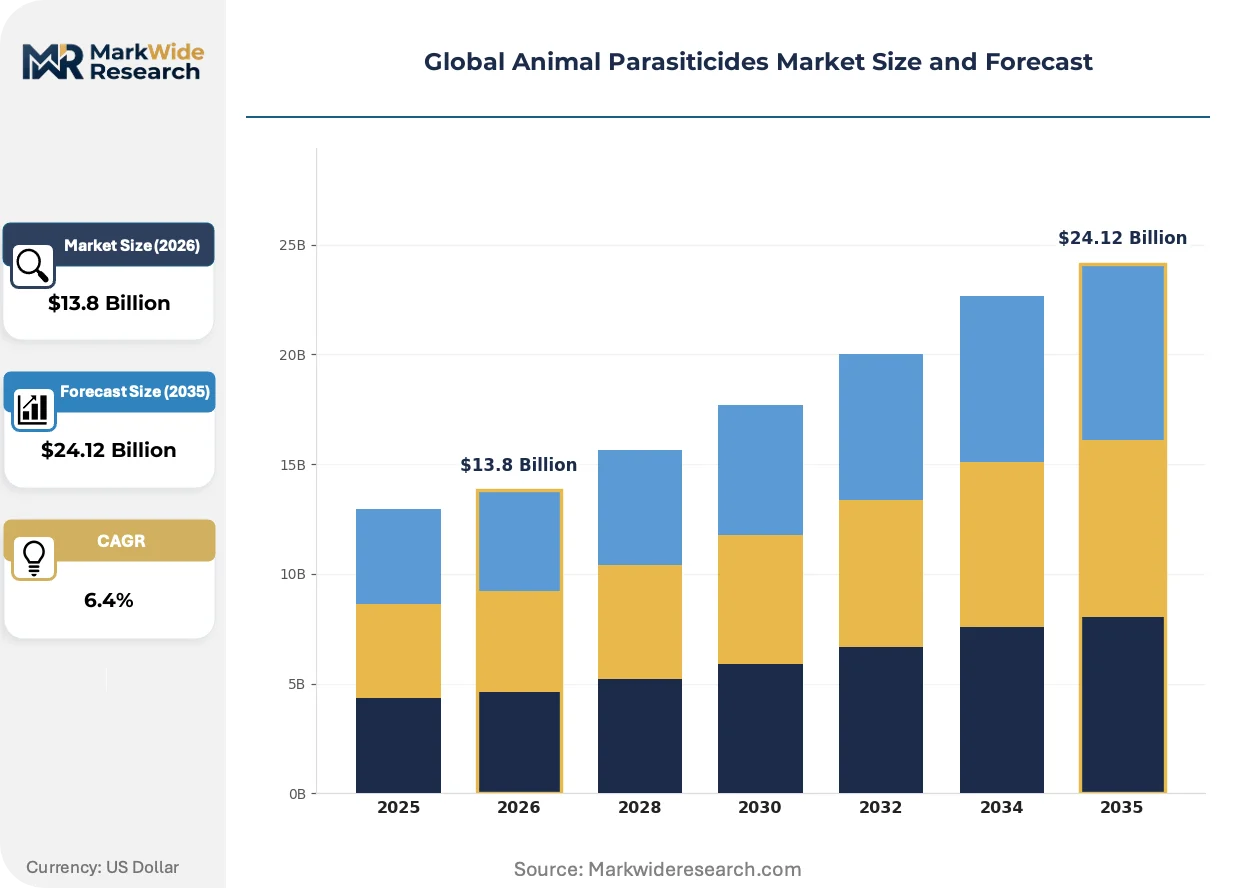
Market Dynamics
Ectoparasiticide resistance management protocols from the EU Green Deal are redirecting R&D investment toward novel active ingredients, fundamentally altering how formulators prioritize pipeline candidates and manufacturing partnerships.
Growth Catalysts
- EU Green Deal resistance protocols:Mandatory rotation requirements for macrocyclic lactones in cattle operations are accelerating demand for alternative chemistries and combination therapies.
- Commercial livestock productivity standards:Brazilian feedlot operators are tightening procurement specifications for endectocides to protect feed conversion ratios in intensive beef production systems.
- Semi-urban veterinary clinic expansion:Government-backed livestock health programs in India are widening distribution networks beyond traditional agricultural supply cooperatives.
Market Restraints
- API supply concentration:Indian manufacturing clusters for veterinary actives are hardening as supply bottlenecks, exposing formulators to single-source dependency risks for benzimidazole precursors.
- Dual-compliance documentation burden:Harmonization gaps between FDA Center for Veterinary Medicine and EMA residue limit protocols force exporters to maintain parallel quality systems, elevating regulatory overhead.
- Ectoparasiticide resistance substitution threat:Pyrethroid-resistant mite populations in companion animal channels are driving premature product obsolescence in topical formulations.
Strategic Opportunities
- Recombinant vaccine-biologic convergence:Captive biotechnology platforms for vector-targeted immunization offer white space adjacent to traditional pharmaceutical parasiticides.
- Aquaculture injectable premiumization:Water-mediated dosing complications in shrimp and finfish operations sustain pricing power for long-acting parenteral formulations.
- CDSCO registration pathway optimization:Foreign applicants who pre-negotiate phased manufacturing inspections under India's revised veterinary drug framework can compress approval timelines versus competitors.
Industry Challenges
- Ecotoxicology assessment capability scarcity:Divergent environmental risk assessment standards between jurisdictions on topical parasiticide runoff are fragmenting formulation strategies and complicating global product registration portfolios.
- Residue monitoring protocol integration:European regulatory jurisdictions with stringent maximum residue limit enforcement require manufacturing footprint co-location, elevating capital intensity for market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Animal Parasiticides Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endectocides, Anthelmintics, Insecticides, Ectoparasiticides Application: Livestock, Companion Animals, Aquaculture, Poultry Formulation: Liquid, Powder, Tablet, Injectable End User: Veterinary Clinics, Livestock Farms, Pet Owners, Aquaculture Facilities |
| Companies Covered | Elanco Animal Health, Ceva Sante Animale, Zoetis, Dechra Pharmaceuticals, Vetoquinol, Boehringer Ingelheim, Virbac, Norbrook, Merck Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Animal Parasiticides Market Shifts & Advancements
Active ingredient discovery pipelines are pivoting toward biologic-vector control hybrids as chemical resistance profiles harden across major livestock species, reshaping competitive positioning around captive biotechnology capabilities rather than formulation chemistry alone.
RNA interference-based antiparasitic platforms are converging with conventional macrocyclic lactone delivery systems, enabling precision targeting of nematode gene expression without broad-spectrum ecological disruption. Large-scale cattle operations in Brazil and Australia are piloting these combination protocols through veterinary prescription channels. This convergence is compressing the traditional ten-year development cycle for novel anthelmintics by allowing repurposing of existing delivery infrastructure.
REACH authorization requirements for neonicotinoid derivatives are forcing reformulation of companion animal topical products ahead of scheduled sunset dates for key actives. The European Chemicals Agency's cumulative exposure assessments are triggering substitution mandates across the ectoparasiticide category. German and French veterinary distributors are accelerating inventory transitions toward isoxazoline-class alternatives, reshaping procurement specifications for retail channel suppliers.
Companion animal owners are consolidating purchasing decisions through subscription-based tele-veterinary platforms that bundle diagnostic testing with parasiticide prescriptions. This channel shift is disintermediating traditional retail pharmacy relationships and concentrating volume with vertically integrated service providers. Urban markets in the United States and United Kingdom exhibit the fastest migration toward these integrated health management models.
Global Animal Parasiticides Market Segmentation
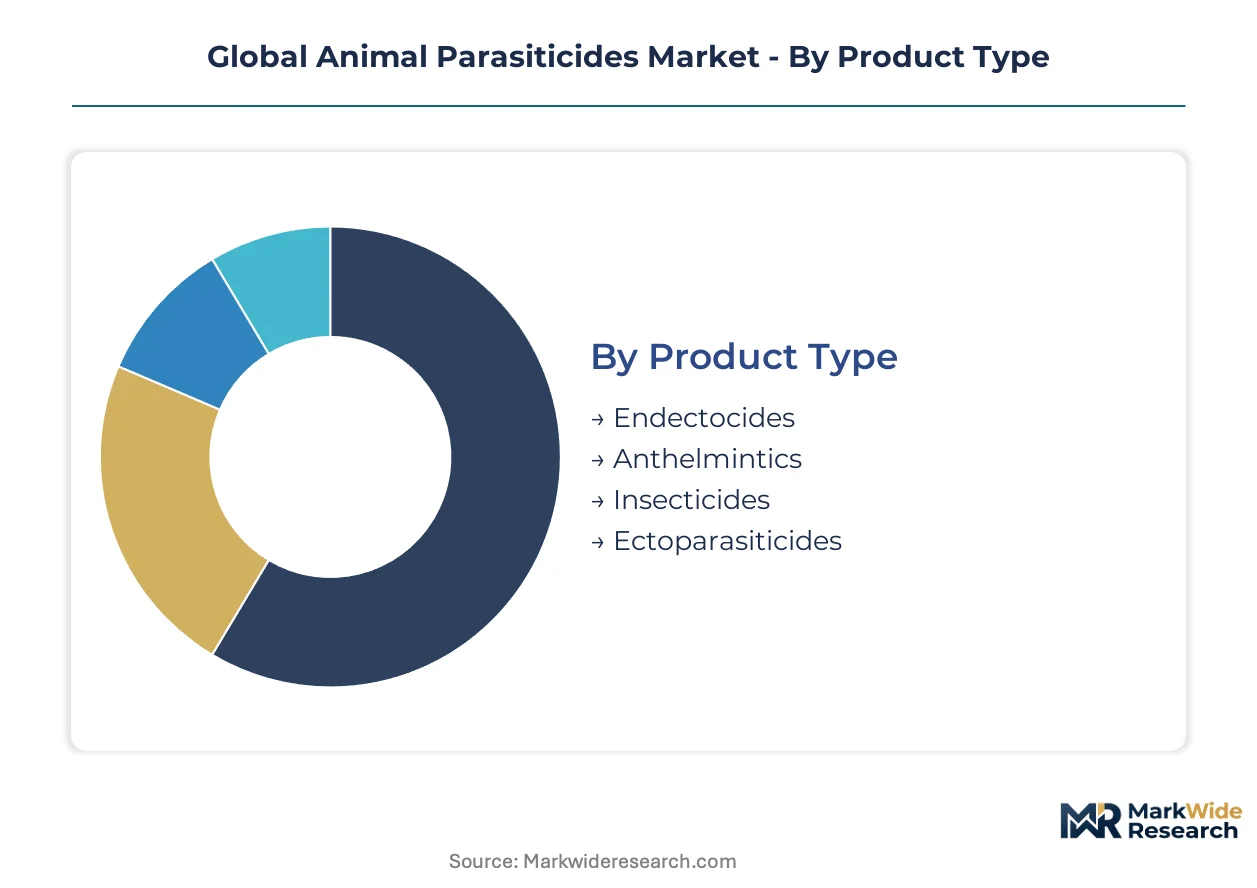
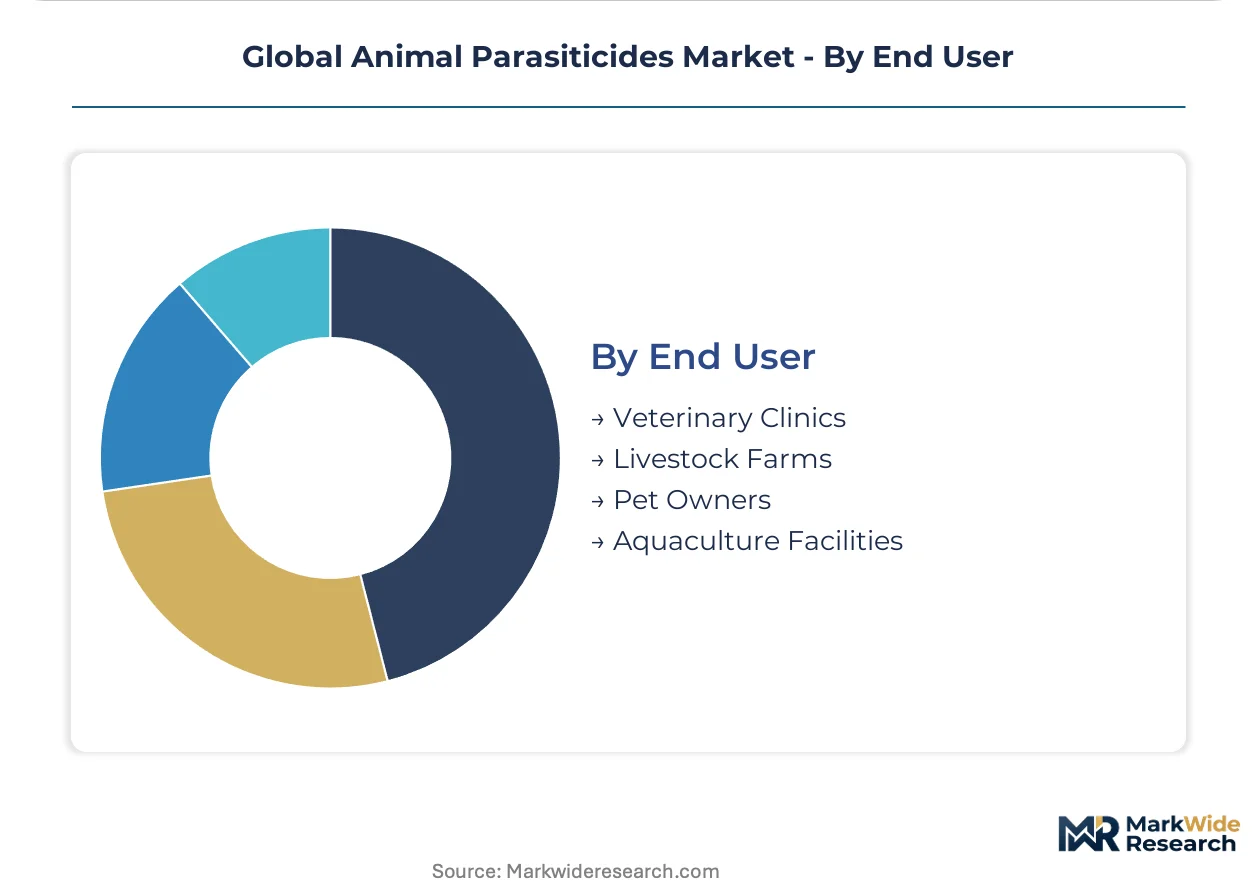
Parasiticide procurement patterns diverge sharply between intensive livestock operations and companion animal channels, with formulation requirements and dosing convenience driving fundamentally different specification priorities across end-user categories.
Product Type:
Standalone pharmaceutical actives dominate procurement volumes, while combination chemistries and biologic hybrids increasingly embed into integrated health management protocols.
- Endectocides:Macrocyclic lactone formulations deliver simultaneous nematocidal and arthropodicidal activity through single-dose administration. Brazilian cattle feedlots concentrate procurement here to protect feed conversion ratios under tightening productivity standards. The broad-spectrum efficacy commands premium positioning against narrow-spectrum alternatives.
- Anthelmintics:Benzimidazole and imidazothiazole derivatives target gastrointestinal nematodes with established resistance profiles requiring rotation protocols. Indian government-backed livestock programs are widening distribution networks for these actives into semi-urban veterinary clinics serving smallholder dairy operations.
- Insecticides:Organophosphate and pyrethroid compounds address fly and tick burdens in pasture-based systems.
- Ectoparasiticides:Topical formulations face substitution pressure from isoxazoline-class alternatives under REACH authorization timelines.
Volume placements concentrate in Endectocides; the faster expansion belongs to Ectoparasiticides in companion animal channels.
Application:
Cost tier segmentation separates commodity livestock procurement from premium companion animal spending, with aquaculture occupying an intermediate position defined by bioavailability constraints.
- Livestock:Cattle, sheep, and swine operations consume parasiticides as production inputs where cost-per-dose directly impacts margin calculations. Brazilian commercial feedlot expansion is tightening procurement specifications for endectocides to maintain competitive yield metrics.
- Companion Animals:Canine and feline channels prioritize dosing convenience and residual efficacy over unit economics. Urban pet owners in the United States and United Kingdom are migrating toward subscription-based tele-veterinary platforms that bundle parasiticide prescriptions with diagnostic testing.
- Aquaculture:Shrimp and finfish operations require water-stable formulations where water-mediated dosing complicates pharmacokinetic control.
- Poultry:Layer and broiler houses employ in-feed anthelmintics and spray-applied ectoparasiticides under integrated pest management protocols.
Livestock captures the deepest volume base; companion animal channels are climbing the fastest on willingness-to-pay premiums.
Formulation:
Application method determines bioavailability profiles and labor requirements, with liquid and injectable formats commanding manufacturing complexity premiums over solid dose alternatives.
- Liquid:Pour-on solutions and oral drenches dominate cattle operations for rapid administration at scale. Australian pastoral companies are piloting RNA interference platforms delivered through repurposed macrocyclic lactone liquid infrastructure.
- Injectable:Long-acting parenteral formulations sustain premium pricing in aquaculture settings where water-mediated dosing threatens therapeutic consistency.
- Powder:In-feed premixes integrate with automated ration systems in intensive poultry and swine facilities.
- Tablet:Palatable chewable formats target companion animal compliance and owner convenience preferences.
Liquid formulations hold the largest installed base; injectable formats are gaining share fastest in aquaculture premiumization.
End User:
Customer type fragmentation creates divergent purchasing behaviors, from institutional tender processes at livestock farms to discretionary retail decisions by individual pet owners.
- Veterinary Clinics:Professional prescription channels concentrate volume in companion animal parasiticides with diagnostic validation requirements. Semi-urban expansion in India is reshaping distribution geography beyond traditional agricultural supply cooperatives.
- Livestock Farms:Commercial operations in Brazil and Australia deploy parasiticides as production inputs with feed conversion efficiency as the primary efficacy metric.
- Pet Owners:Direct-to-consumer subscription models are disintermediating traditional retail pharmacy relationships in United States and United Kingdom urban markets.
- Aquaculture Facilities:Intensive shrimp and finfish operations require specialized formulation expertise for water-mediated delivery systems.
Livestock Farms anchor procurement volumes; Veterinary Clinics are expanding most quickly through channel consolidation and telehealth integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian API manufacturing clusters for veterinary actives supply formulators across Brazil, Europe, and North America. Brazilian commercial livestock operations anchor South American demand. European regulatory stringency redirects R&D investment toward novel chemistries.
Brazil
Commercial feedlot expansion in Mato Grosso and São Paulo states tightens procurement specifications for endectocides to protect feed conversion ratios. ANVISA enforces residue monitoring protocols aligned with export market access requirements. Campinas anchors formulation manufacturing for distribution throughout Mercosur cattle operations.
United States
Companion animal subscription platforms in urban markets disintermediate traditional retail pharmacy relationships. The FDA Center for Veterinary Medicine harmonizes residue limits with EMA protocols, compelling dual-compliance documentation systems. Kansas City veterinary distribution hubs consolidate volume for Midwest livestock operations.
Germany
REACH authorization timelines for neonicotinoid derivatives force inventory transitions toward isoxazoline-class alternatives. The EMA and ECHA jointly shape environmental risk assessment standards for topical parasiticide runoff. Leverkusen manufacturing facilities serve as regulatory compliance anchors for EU market access.
India
Government-backed livestock health programs widen distribution networks for anthelmintics into semi-urban veterinary clinics. CDSCO enforces phased manufacturing inspections under revised veterinary drug registration frameworks, extending approval timelines for foreign applicants. Hyderabad and Ahmedabad API clusters harden as supply bottlenecks for benzimidazole precursors.
Australia
Pastoral companies pilot RNA interference platforms delivered through repurposed macrocyclic lactone infrastructure. The TGA aligns veterinary chemical registration with OECD ecotoxicity standards for export market compatibility. Queensland cattle stations concentrate demand for pour-on endectocide formulations.
Global Animal Parasiticides Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biologic-vector control hybrids adjacent to traditional pharmaceutical parasiticides. Market structure consolidates around integrated discovery-to-distribution architectures and captive biotechnology platforms. Three archetypes dominate: vertically integrated multinationals with regulatory co-location capabilities, API-dependent formulators exposed to single-source supply risks, and biologic specialists converging recombinant vaccines with conventional delivery systems. Competitive moves concentrate on manufacturing footprint optimization and strategic partnerships to secure channel access.
Within the integrated multinational tier, Zoetis and Boehringer Ingelheim exemplify divergent strategic positioning. Zoetis leverages its discovery-to-distribution architecture to secure channel access across Latin American cattle markets. Boehringer Ingelheim anchors its position through captive biotechnology platforms for recombinant vaccines against parasitic vectors. Ceva Sante Animale occupies a position concentrated in European regulatory jurisdictions with stringent residue monitoring protocols, representing the regulatory co-location archetype.
| Leading Market Players |
|---|
| Elanco Animal Health |
| Ceva Sante Animale |
| Zoetis |
| Dechra Pharmaceuticals |
| Vetoquinol |
| Boehringer Ingelheim |
| Virbac |
| Norbrook |
| Merck Animal Health |
| Others |
Supply & Pricing Matrix
Brazilian commercial feedlot operators concentrate procurement volumes for endectocides, anchoring a contract-based long-term offtake model where annual volume commitments lock in preferential unit economics against spot-market volatility. This buyer concentration amplifies pricing power asymmetry toward large integrated formulators capable of underwriting multi-year supply security.
Pricing Analysis
Service bundling separates diagnostic-validated prescription protocols from unbundled commodity procurement, with veterinary clinic channels commanding premium positioning through compliance monitoring included in subscription frameworks. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation complexity and residue certification tier. Price differentiation hinges on EU REACH authorization status and captive API production. Cost compression in pyrethroid-based ectoparasiticides is intensifying because of resistance-driven substitution toward isoxazoline alternatives. Livestock farm procurement exhibits highest price sensitivity; companion animal tele-veterinary subscriptions show lowest.
Supply Chain Analysis
Reverse logistics for expired or recalled veterinary products flows through specialized hazardous waste handlers with temperature-chain documentation requirements, creating compliance cost layers absent in forward distribution. API manufacturing concentrates in India, China, and Germany, with Hyderabad and Ahmedabad clusters feeding benzimidazole precursors to global formulators. Finished formulation depends on macrocyclic lactone fermentation capacity, neonicotinoid derivative stocks, and recombinant protein expression systems. Single-source vulnerability for Indian benzimidazole precursors exposes formulators to supply interruption. Distribution runs through veterinary distribution hubs consolidating volume for clinic and farm channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API manufacturing capacity constraints in Indian clusters prop pricing power for integrated formulators with captive precursor supply, creating a supply-constrained market structure favoring backward-integrated incumbents.
For Market Incumbents: Deploy captive biotechnology platform investment to preempt RNA interference-based substitution threats from emerging biologic-vector control hybrids. Secure manufacturing footprint co-location in European regulatory jurisdictions with stringent residue monitoring protocols to defend channel access against API-dependent formulators exposed to single-source risks. Deepen backward integration into benzimidazole precursor production to neutralize Indian supply bottleneck exposure. For New Entrants and Emerging Players: CDSCO registration pathway optimization in India opens a window for foreign applicants who pre-negotiate phased manufacturing inspections, compressing approval timelines versus competitors. Target semi-urban veterinary clinic expansion in Indian government-backed livestock health programs as the most penetrable distribution geography. Pursue aquaculture injectable premiumization as a white-space application with sustained pricing power and limited incumbent specialization. For Investors and Strategic Acquirers: The window for entry favors API-dependent formulators with established regulatory dossiers and distressed valuation profiles from supply chain compression. Long-term viability centers on acquisition targets with captive fermentation capacity or recombinant vaccine platforms adjacent to pharmaceutical parasiticides. Monitor EMA-FDA residue limit harmonization gaps as the signal for regulatory arbitrage opportunity expansion or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Manufacturing | Captive benzimidazole precursor production neutralizes Indian supply concentration risk for formulators. |
| Regulatory Co-location in EU Jurisdictions | Manufacturing footprint alignment with EMA residue protocols secures premium channel access across European veterinary clinics. |
| Biologic-Pharmaceutical Hybrid Development | RNA interference platform convergence with macrocyclic lactone delivery infrastructure accelerates development timelines. |
| CDSCO Registration Pathway Pre-negotiation | Phased manufacturing inspection agreements compress approval timelines for foreign applicants entering Indian distribution networks. |
| Aquaculture Injectable Formulation Scale-up | Long-acting parenteral capacity expansion captures premium pricing in shrimp and finfish operations with bioavailability constraints. |
Research Methodology
Document review covered FDA Center for Veterinary Medicine filings, EMA regulatory submissions, CDSCO veterinary drug registration records, and OECD ecotoxicity standards, complemented by interviews with veterinary pharmaceutical R&D directors, regulatory affairs leads at animal health companies, feedlot procurement managers in Brazil, and distribution channel partners across Latin American cattle markets. Secondary validation drew from customs trade data for API movements, SEC 10-K disclosures from listed animal health companies, and ANVISA residue monitoring protocols. Bottom-up segmentation modeling triangulated against top-down market sizing from production volume estimates.
Output generation applied a demand-side elasticity framework across the projection horizon, with value trajectories built from unit economics by formulation type and volume flows by species application. Segmentation dimensions encompassed product type, application species, formulation route, and end-user channel, with regional regulatory cluster differentiation. CAGRs derived from iterative convergence of historical trajectory analysis and forward-looking capacity expansion announcements. Forecast inputs incorporated EU Green Deal resistance protocol implementation timelines and Indian livestock health program budget allocations.
The model assumes a particular technology adoption path; alternative pathways for RNA interference platform penetration would alter the outlook for conventional macrocyclic lactone demand trajectories. Forecasts embed assumptions regarding REACH authorization sunset schedules for neonicotinoid derivatives and CDSCO inspection capacity expansion rates. Material deviation in API supply chain stability or EMA-FDA harmonization progress warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Progesterone Testing Market
Veterinary
ASEAN Poultry Vaccines Market
Veterinary
Veterinary Excipients Market
Veterinary
Clostridium Vaccine (Animal Health) Market
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
US Companion Animal Diagnostics Market
Veterinary
Veterinary Intravenous (IV) Solutions Market
Veterinary
Rabies Veterinary Vaccines Market
Veterinary
USA Animal Model Market
Veterinary
Global Veterinary Grooming Aids Market
Veterinary
North America and Europe Veterinary Telehealth Market
Veterinary
Companion Animal Vaccines Market
Veterinary
Veterinary Biologicals Biobank Market
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
Homeopathic Veterinary Medicines Market
Veterinary
Pet DNA Testing Market