
 Patient Infotainment Terminals Market | 2026-2036
Patient Infotainment Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Infotainment Terminals Market Analysis
EU MDR is pivoting the cost-of-entry calculus for bedside terminal manufacturers by mandating enhanced cybersecurity validation and clinical data interoperability. Siemens Healthineers leverages its imaging informatics heritage to anchor integrated room solutions that bridge diagnostic and entertainment workflows. Advantech competes through industrial computing scale, supplying hardened touch panels that sustain 24/7 clinical duty cycles. Barco specializes in display calibration technology, differentiating its patient-facing screens with color accuracy protocols drawn from surgical visualization standards.
Patient infotainment terminals are bedside interactive computing devices combining touchscreen displays, network connectivity, and multimedia software to deliver entertainment, clinical information, and nurse-call integration to hospitalized individuals; typical specifications include antimicrobial housings, IEC 60601-1 electrical safety certification, and PoE+ power delivery to reduce cable clutter in critical care environments. Touchscreen Displays dominate hardware shipments due to their direct integration into headwall infrastructure and overbed mounting systems. Cloud-Based Solutions represent the fastest-expanding technology segment as hospitals seek centralized content management and remote firmware updates across multi-site networks. Hospitals command the largest end-user share, though Rehabilitation Centers are gaining traction as post-acute facilities invest in longer-stay patient engagement tools.
FDA 510(k) clearance requirements and IEC 60601-1 third-edition safety standards govern US market access, while the EU AI Act and MDR framework impose additional algorithmic transparency obligations on terminals with predictive health monitoring features. Health Canada and TGA maintain mutual recognition agreements that streamline approval for devices already cleared by FDA or EMA, reducing redundant certification costs for multinational suppliers. Stakeholders must monitor evolving cybersecurity disclosure rules across North American and European jurisdictions to anticipate retrofit liabilities and design-cycle adjustments.
Market Dynamics
EU MDR cybersecurity mandates are compressing vendor margins while forcing bedside terminal manufacturers to reengineer hardware architectures for IEC 60601-1 third-edition compliance and interoperability certification.
Growth Catalysts
- EU Medical Device Regulation:MDR interoperability requirements accelerate hospital procurement of cloud-integrated bedside systems that interface directly with electronic health record infrastructure.
- Touchscreen Displays:Antimicrobial panel technology advances reduce infection control liabilities in intensive care environments, driving replacement cycles in tertiary hospitals.
- Germany:Acute care facilities in Bavaria and North Rhine-Westphalia expand headwall-mounted terminal deployments to meet patient satisfaction benchmarks tied to reimbursement formulas.
Market Restraints
- Semiconductor supply concentration:Touch controller and PoE+ power management chip fabrication concentrates in East Asian foundries, exposing European terminal assemblers to lead-time volatility.
- IEC 60601-1 third-edition compliance costs:Electrical safety retesting for patient proximity applications adds eighteen to twenty-four months to product development cycles.
- Smartphone substitution:Patient-owned devices with hospital Wi-Fi access reduce perceived necessity for dedicated bedside hardware in short-stay wards.
Strategic Opportunities
- Rehabilitation Centers:Post-acute facilities in France and Belgium underinvest in patient engagement infrastructure, creating first-mover advantages for modular terminal suppliers.
- Cloud-Based Solutions:Centralized firmware management and content distribution platforms enable recurring revenue models distinct from hardware sales.
- EU AI Act:Algorithmic transparency requirements for predictive health monitoring features create certification barriers that favor incumbent terminal manufacturers with compliance resources.
Industry Challenges
- Cybersecurity engineering talent scarcity:Embedded systems security expertise required for MDR-mandated penetration testing outstrips supply in European labor markets.
- Legacy EHR integration complexity:Proprietary data exchange protocols at individual hospital systems force costly custom middleware development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Infotainment Terminals Market |
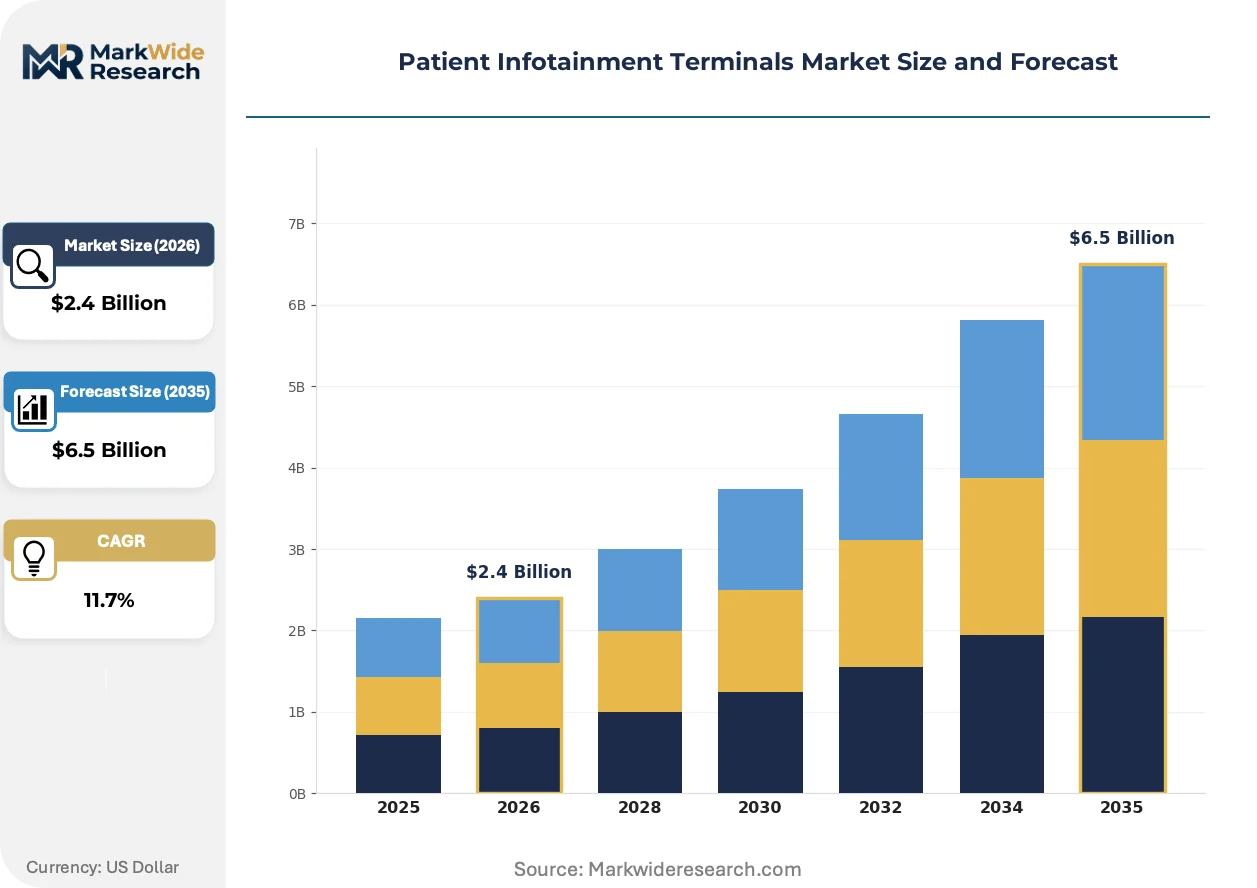
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touchscreen Displays, Kiosks, Interactive Panels, Digital Signage End User: Hospitals, Clinics, Rehabilitation Centers, Senior Living Facilities Technology: Cloud-Based Solutions, On-Premise Systems, Multimedia Solutions, Hybrid Systems Application: Patient Education, Entertainment Services, Information Access, Health Monitoring |
| Companies Covered | ClinicAll, Advantech, ConnectedCare GmbH, ITI Technology, BEWATEC, Onyx Healthcare, Barco, Siemens Healthineers, PDi Communication, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Infotainment Terminals Market Emerging Trajectories
Bedside terminal architecture is pivoting from standalone entertainment units toward clinical workflow nodes, with hardware specifications increasingly dictated by infection control protocols and cybersecurity frameworks rather than consumer electronics benchmarks.
Android-based embedded operating systems are consolidating control over patient-facing interfaces in Western European hospitals, replacing legacy Windows Embedded platforms that face end-of-life security vulnerabilities. Tertiary care centers in Germany and the Netherlands prioritize these hardened OS environments for their streamlined patch management and reduced attack surface. The shift is compressing differentiation among hardware suppliers and elevating software ecosystem partnerships as the primary competitive variable.
EU AI Act algorithmic transparency obligations are forcing terminal manufacturers to document decision logic for any predictive health monitoring features, such as fall-risk scoring or deterioration alerts. Industrial designers must now embed explainability interfaces directly into patient-facing screens, adding UI complexity and testing burden. Rehabilitation centers deploying these advanced functions face the steepest compliance ramps, as their lower IT staffing levels struggle with documentation requirements.
Hospital procurement committees are unbundling after-sales service contracts from hardware purchases, negotiating separate agreements for cybersecurity monitoring and content licensing. French public hospital networks pioneered this bifurcation, and the model is spreading to NHS trusts in England. Vendors accustomed to bundled margins must restructure pricing architectures or cede service revenue to specialized cybersecurity firms and content aggregators.
Patient Infotainment Terminals Market Segmentation
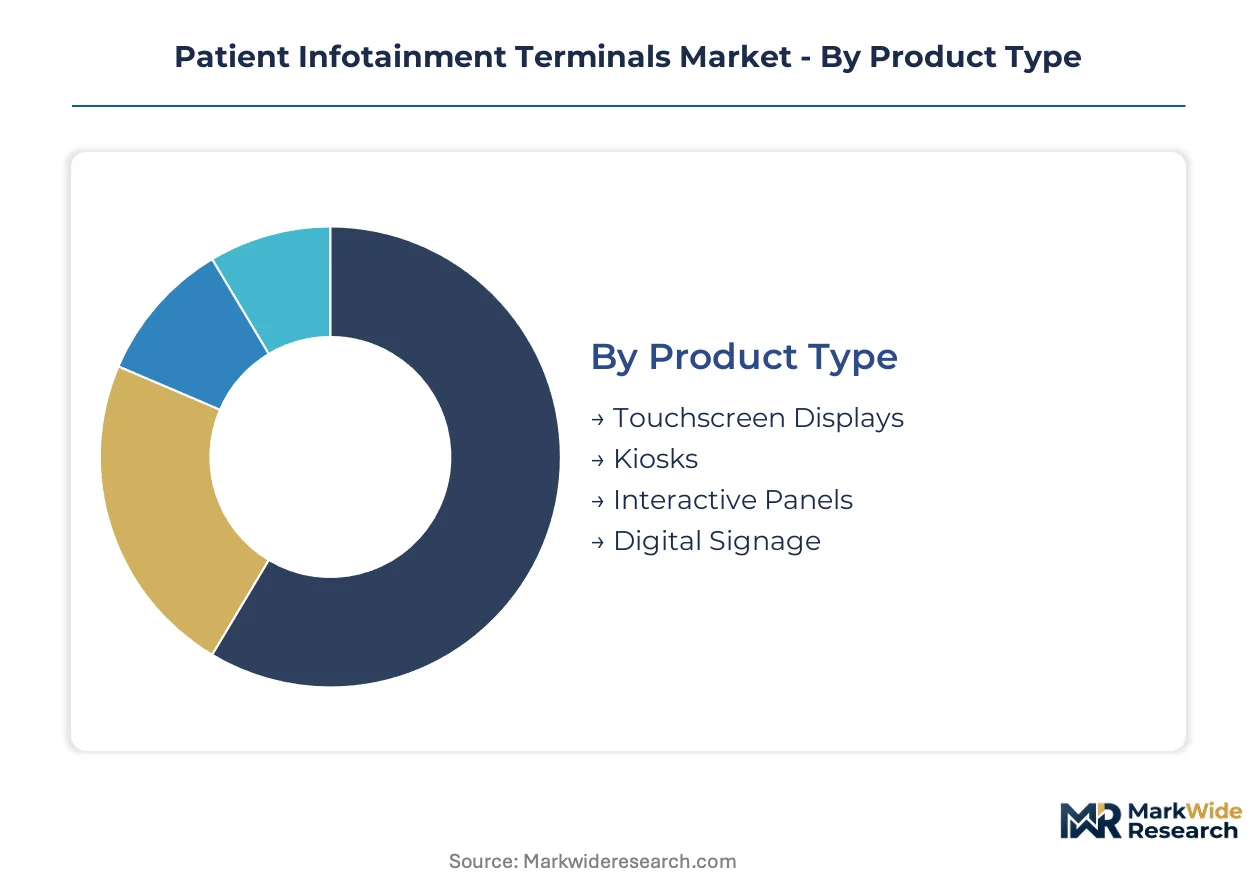
Segmentation in patient infotainment terminals reveals how procurement committees prioritize hardware durability, software interoperability, and total cost of ownership across acute and post-acute care environments. Understanding these divides exposes where vendors can capture margin premiums versus competing on volume.
Product Type:
Supply concentration in antimicrobial panel fabrication and IEC 60601-1 certified power management favors manufacturers with captive touch controller sourcing or long-term foundry partnerships.
- Touchscreen Displays:Headwall-mounted and overbed units with antimicrobial glass and PoE+ power delivery dominate tertiary hospital deployments in Germany and France. Bavarian acute care networks specify these for 24/7 clinical duty cycles tied to patient satisfaction reimbursement formulas.
- Interactive Panels:Wall-integrated systems with nurse-call bridging and EHR interface capabilities concentrate in Dutch and Belgian hospitals pursuing room-standardization strategies. These command hardware premiums but reduce per-room installation labor.
- Kiosks:Freestanding units for lobbies and outpatient corridors.
- Digital Signage:Large-format screens for wayfinding and departmental communication.
Today's leader: Touchscreen Displays. Tomorrow's challenger: Interactive Panels.
End User:
Cost tier stratification separates capital-rich tertiary hospitals from post-acute facilities operating on fixed reimbursement rates, dictating divergent procurement rhythms and service contract structures.
- Hospitals:Acute care facilities in the United Kingdom, Germany, and France drive procurement volume through centralized NHS trust and public hospital network tenders. EU MDR interoperability mandates accelerate replacement of legacy Windows Embedded systems with Android-based hardened platforms.
- Rehabilitation Centers:Post-acute facilities in France and Belgium currently underinvest in bedside engagement infrastructure. Longer patient stays create ROI justification for modular terminal deployments with predictive health monitoring features.
- Clinics:Outpatient and ambulatory surgical centers with shorter patient encounters.
- Senior Living Facilities:Residential care environments prioritizing resident autonomy and family communication tools.
Capital deployment concentrates in Hospitals. Steepest expansion trajectory emerges in Rehabilitation Centers.
Technology:
Volume deployment patterns favor centralized management architectures that reduce per-site IT staffing burdens across multi-hospital health systems.
- Cloud-Based Solutions:Firmware-over-the-air and content distribution platforms enable recurring revenue models distinct from hardware sales. French public hospital networks pioneered unbundled service contracts for these systems, spreading to NHS trusts in England.
- Hybrid Systems:Edge-computing terminals with local processing and cloud synchronization address cybersecurity latency concerns in critical care. German hospitals favor these for ICU deployments where network interruption cannot disable nurse-call functions.
- On-Premise Systems:Fully localized infrastructure for isolated network environments.
- Multimedia Solutions:Content-heavy platforms emphasizing entertainment over clinical integration.
Current procurement favors Cloud-Based Solutions. Hybrid Systems gain share fastest where network resilience is non-negotiable.
Application:
Customer type differentiation separates clinically validated workflows from convenience-oriented deployments, with regulatory burden concentrating in health monitoring functions.
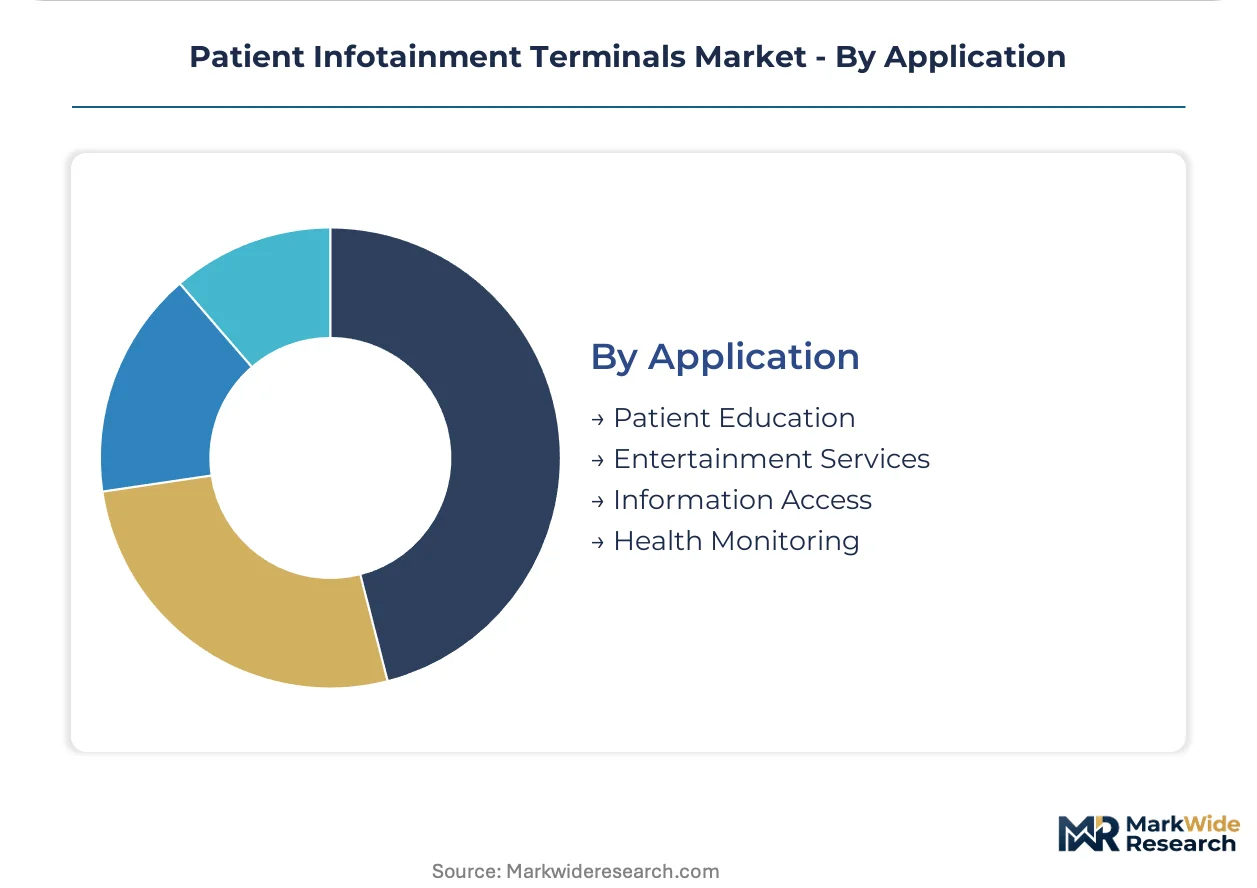
- Patient Education:Interactive discharge instruction and medication adherence modules reduce readmission penalties. NHS trusts in England embed these in bundled payment programs for chronic disease management.
- Health Monitoring:Fall-risk scoring and deterioration alert functions trigger EU AI Act algorithmic transparency obligations. Rehabilitation centers face steepest compliance ramps due to limited IT documentation capacity.
- Entertainment Services:Video streaming and gaming for patient satisfaction metrics.
- Information Access:Meal ordering, environmental controls, and service requests.
Patient Education anchors current deployments. Health Monitoring carries the heaviest regulatory tailwind.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient infotainment terminals emerged from European acute care digitization initiatives in the early 2000s, with German and Dutch hospital networks pioneering bedside interactive systems before regulatory frameworks formalized interoperability requirements.
Germany
Bavarian and North Rhine-Westphalian acute care networks drive procurement through patient satisfaction benchmarks tied to DRG reimbursement formulas. KBA medical device oversight and BfArM cybersecurity guidance shape terminal certification timelines. Munich-based Siemens Healthineers anchors integrated room solutions bridging diagnostic imaging and patient engagement workflows.
United Kingdom
NHS trusts in England unbundle service contracts from hardware purchases, negotiating separate cybersecurity monitoring and content licensing agreements. MHRA post-Brexit device regulations maintain alignment with EU MDR interoperability mandates. London and Birmingham hospital clusters accelerate Android-based hardened platform deployments to replace legacy Windows Embedded systems.
France
Public hospital networks in Île-de-France pioneered cloud-based firmware management platforms, spreading unbundled procurement models to regional centers. ANSM device oversight and CNIL data protection requirements impose dual compliance burdens on predictive health monitoring features. Lyon and Marseille rehabilitation centers underinvest in bedside infrastructure, creating expansion opportunities for modular terminal suppliers.
Netherlands
Dutch tertiary hospitals pursue room-standardization strategies favoring wall-integrated interactive panels with nurse-call bridging and EHR interface capabilities. Health and Youth Care Inspectorate medical device regulations emphasize IEC 60601-1 third-edition electrical safety validation. Eindhoven industrial computing clusters supply hardened touch controllers for 24/7 clinical duty cycles.
Belgium
Post-acute facilities in Flanders and Wallonia lag in patient engagement infrastructure investment despite longer average patient stays. FAMHP device regulations implement EU MDR cybersecurity mandates with national notification requirements. Brussels hospital networks test hybrid edge-computing terminals addressing network resilience concerns in critical care environments.
Patient Infotainment Terminals Market Vendor Landscape
The competitive structure tilts toward diversified medical technology conglomerates with imaging informatics heritage. Siemens Healthineers leverages diagnostic workflow integration to anchor premium-tier positioning, while industrial computing specialists compete on manufacturing scale and foundry relationships. Three archetypes dominate: integrated health technology platforms, hardened embedded systems fabricators, and display calibration specialists. Consolidation pressure intensifies through strategic partnerships for EHR middleware development and geographic expansion into underpenetrated rehabilitation markets.
Among diversified health technology platforms, Siemens Healthineers occupies a position exemplifying imaging-to-bedside workflow integration. Advantech and Barco represent contrasting specialization vectors—Taiwan-based industrial computing scale versus Belgian display calibration heritage drawn from surgical visualization standards. ConnectedCare GmbH anchors the German mid-market tier, while BEWATEC and PDi Communication exemplify regional European fabricators with focused acute care penetration. ClinicAll and Onyx Healthcare occupy positions within the North American supply base, with ITI Technology representing specialized nurse-call integration expertise.
| Leading Market Players |
|---|
| ClinicAll |
| Advantech |
| ConnectedCare GmbH |
| ITI Technology |
| BEWATEC |
| Onyx Healthcare |
| Barco |
| Siemens Healthineers |
| PDi Communication |
| Others |
Supply Flow & Price Mechanics
Touch controller silicon spot pricing volatility cascades through European terminal assemblers into three distinct hardware tiers, with PoE+ power management module costs compressing margins on economy-grade units while IEC 60601-1 third-edition certification investments sustain premiums on clinical-hardened platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Siemens Healthineers' integrated room solutions from modular panel suppliers and generic kiosk manufacturers. Certification grade and after-sales service bundling drive the widest price spreads, with EU MDR cybersecurity validation adding substantial compliance premiums to top-tier offerings. Cost compression in economy segments intensifies because smartphone substitution erodes perceived value in short-stay wards. Rehabilitation centers exhibit highest price sensitivity due to fixed reimbursement rates, while German tertiary hospitals under DRG-linked satisfaction formulas absorb premium pricing with minimal procurement friction.
Supply Chain Analysis
Refurbishment flows for antimicrobial touch panels and nurse-call bridging modules create secondary supply channels that undercut OEM pricing in replacement cycles, particularly for Dutch and Belgian hospitals operating on extended depreciation schedules. Taiwan, South Korea, and Germany anchor fabrication of touch controllers, PoE+ power management chips, and hardened embedded systems respectively. Supply chains draw from East Asian foundries for semiconductor inputs, medical-grade glass substrates, and antimicrobial coating chemicals. Single-source vulnerability concentrates in Taiwan-based touch controller fabrication, exposing European assemblers to lead-time volatility. Distribution runs through hospital GPOs in the United Kingdom, direct public tenders in Germany and France, and specialized medical device distributors in the Netherlands and Belgium.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through cloud-based recurring revenue unbundling from hardware sales, with French public hospital network procurement models spreading to NHS trusts and compressing pure-play equipment margins.
For Market Incumbents: Deploy cloud-based firmware management platforms to capture recurring service revenue as French and English procurement committees unbundle cybersecurity monitoring from terminal purchases. Siemens Healthineers should deepen EHR middleware partnerships to lock out modular competitors, while Advantech must secure captive foundry allocations for touch controllers to hedge East Asian supply volatility. Smartphone substitution in short-stay wards threatens dedicated bedside hardware necessity.
For New Entrants and Emerging Players: Rehabilitation center IT staffing gaps create partnership openings with predictive health monitoring software specialists who can bundle EU AI Act compliance documentation. France and Belgium post-acute facilities represent the most penetrable geography, with Lyon and Marseille clusters showing systematic underinvestment in patient engagement infrastructure. Target modular terminal architectures that reduce per-room installation labor for Dutch room-standardization strategies.
For Investors and Strategic Acquirers: Asymmetric upside sits with industrial computing specialists possessing captive cybersecurity engineering talent pools, as MDR-mandated penetration testing expertise outstrips European labor market supply. Five-to-ten year viability favors vendors who have already absorbed IEC 60601-1 third-edition retesting cycles and can leverage compliance documentation across product refreshes. Watch NHS trust unbundling velocity as the signal indicating whether cloud-based service revenue models achieve sufficient scale to offset hardware margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Deep EHR integration with Siemens Healthineers anchors premium-tier positioning against modular competitors. |
| CE Marking Pathway | EU MDR cybersecurity validation compresses vendor margins while creating certification barriers for new entrants. |
| Software Companion Development | Predictive health monitoring features trigger EU AI Act algorithmic transparency obligations favoring incumbents. |
| Strategic Partnership | Cloud-based content distribution platforms enable recurring revenue distinct from hardware sales in French networks. |
| Backward Integration | Captive touch controller sourcing hedges East Asian foundry concentration for 24/7 clinical duty cycle reliability. |
Methodological Framework
Coverage spans Germany, the United Kingdom, France, the Netherlands, and Belgium, with primary inputs from each market's hospital procurement committees, biomedical engineers, GPO contracts managers, and rehabilitation center IT directors. Secondary validation drew from EU MDR implementation guidance, ANSM device oversight filings, NHS trust tender databases, and KBA medical device registration records. Bottom-up terminal shipment estimates triangulated against top-down healthcare IT capex projections.
Granularity-level modeling addressed product type, end user, technology deployment model, and application across the analysis window, with regional regulatory clusters and reimbursement formula variations as cross-cutting dimensions. CAGRs derived from shipment volume trajectories weighted by average selling price evolution, incorporating PoE+ power management chip lead times and antimicrobial panel replacement cycle data as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act implementation timelines and East Asian semiconductor supply stability. Forecasts reflect documented assumptions regarding MDR compliance cost absorption and cloud migration velocity among post-acute facilities. Practitioners should monitor NHS trust unbundling adoption rates and Taiwan foundry capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Bedpan Washer Disinfectors Market
Healthcare Equipment
US Medical Cold Storage Market
Healthcare Equipment
Skin Cooling Systems Market
Healthcare Equipment
North America Healthcare Machine Vision System Market
Healthcare Equipment
Ophthalmic Examination Chairs Market
Healthcare Equipment
Patient Recliner Chair Market
Healthcare Equipment
Clinical Mobility Market
Healthcare Equipment
Patient Recliner Market
Healthcare Equipment
Iraq Intensive Care Unit (ICU) Beds and Surfaces Market
Healthcare Equipment
Medical Chairs Market
Healthcare Equipment
India Healthcare Machine Vision System Market
Healthcare Equipment
Middle East and Africa Hospital Furniture Market
Healthcare Equipment
Veterinary Furniture Market
Healthcare Equipment
Physiotherapy Equipment Market
Healthcare Equipment
Emergency Hospital Beds Market
Healthcare Equipment
Specialty Medical Chairs Market