
 Bovine Respiratory Disease Treatment Market | 2026-2036
Bovine Respiratory Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Bovine Respiratory Disease Treatment Market Intelligence
mRNA vaccine platform development is reshaping how preventive solutions are built for bovine respiratory disease, shifting development timelines and manufacturing requirements across the industry. Zoetis leverages its vertically integrated biologics infrastructure to anchor supply security for large-scale cattle operations. Boehringer Ingelheim competes through sustained R&D investment in combination respiratory vaccines covering multiple viral and bacterial pathogens. Merck Animal Health differentiates via its global distribution network, controlling channel access across North American and Latin American livestock markets.
Bovine respiratory disease treatment encompasses pharmaceutical and biological interventions designed to prevent, control, or resolve polymicrobial respiratory infections in cattle, typically involving Mannheimia haemolytica, Pasteurella multocida, Histophilus somni, and bovine viral diarrhea virus in complex etiological presentations. These treatments function to reduce mortality, improve feed conversion efficiency, and minimize carcass condemnation in commercial beef and dairy production systems. Antibiotics and vaccines together constitute the dominant product categories, with antibiotics carrying mature margin profiles while vaccines represent the faster-growing segment driven by preventive management adoption. Among delivery modes, injectable administration occupies the largest share due to assured dosing accuracy in clinical settings, though oral and transdermal alternatives are gaining traction in cow-calf operations where labor constraints favor simplified handling protocols.
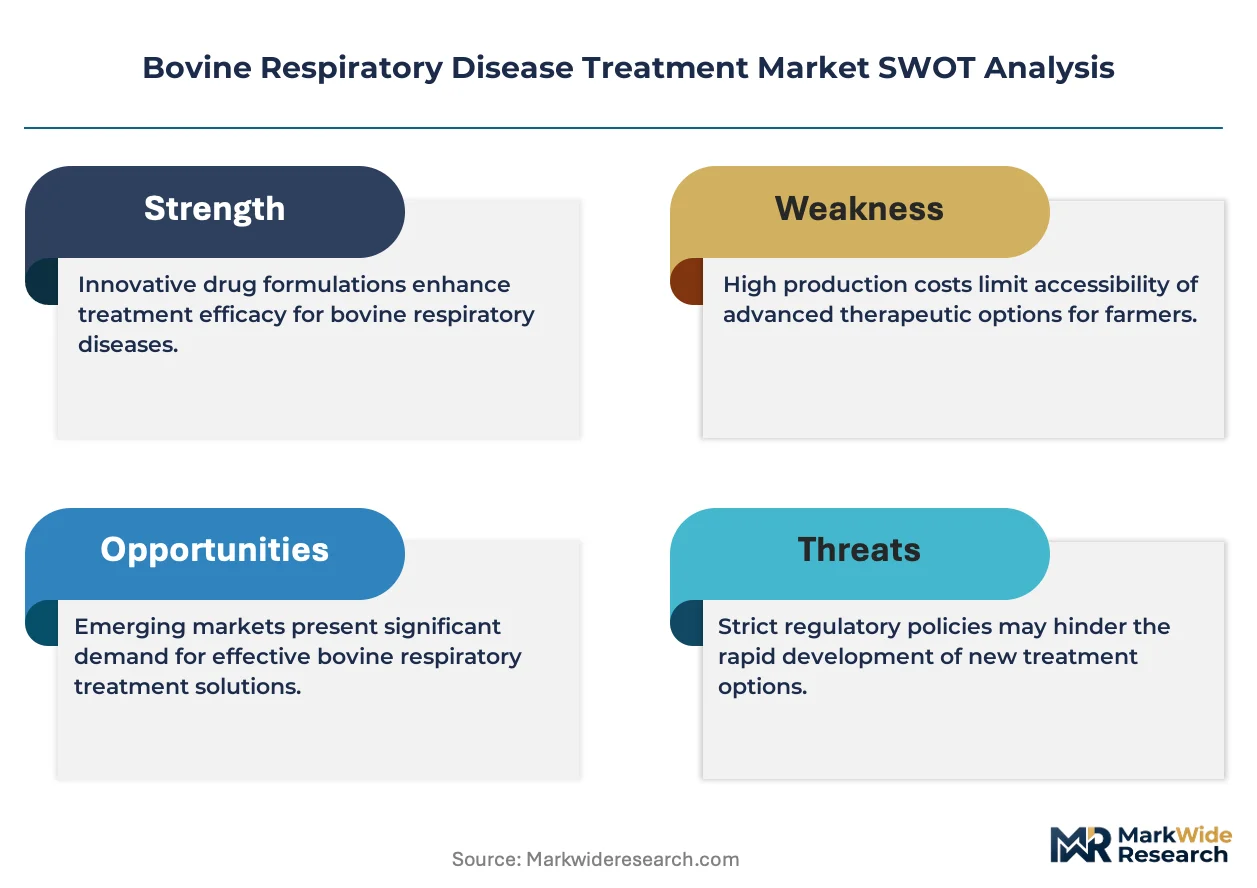
The FDA's Veterinary Feed Directive restricts over-the-counter antimicrobial use in feed, compelling producers toward prescription-based therapeutic protocols and accelerating vaccine investment. USDA Animal and Plant Health Inspection Service traceability requirements further shape product registration and interstate movement compliance for treated cattle. Stakeholders must monitor evolving antimicrobial stewardship frameworks and platform technology transitions to align portfolio development with regulatory trajectories and shifting producer economics.
Market Dynamics
The Veterinary Feed Directive has compressed antimicrobial availability in US feed channels, forcing producers to restructure preventive protocols around biological interventions and prescription-based therapeutics. This regulatory pivot is redistributing value capture from generic antibiotic manufacturers toward vaccine developers with rapid platform adaptability.
Growth Catalysts
- High-density finishing systems:Brazilian feedlot operators are expanding pen capacity to meet export-grade beef specifications, elevating respiratory disease risk profiles and pharmaceutical consumption intensity per animal unit.
- USDA traceability mandates:Interstate movement documentation requirements for treated cattle are standardizing electronic health record adoption, embedding pharmaceutical products into compliance infrastructure.
- mRNA platform maturation:Reduced development timelines for multivalent respiratory vaccines are enabling faster response to emerging pathogen strains in commercial cattle populations.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for tetracyclines and macrolides clusters in Chinese chemical hubs, exposing formulators to export license volatility and freight cost swings.
- Antimicrobial resistance surveillance:FDA's expanded National Antimicrobial Resistance Monitoring System testing protocols are extending registration timelines for new antibiotic submissions by 18-24 months.
- Vaccine cold chain requirements:mRNA and modified-live viral vaccines demand continuous 2-8°C distribution, limiting reach in Brazilian interior ranching regions with unreliable refrigeration infrastructure.
Strategic Opportunities
- Uruguayan pasture finishing:Premium grass-fed beef export protocols in this underpenetrated market are creating demand for respiratory prevention programs that avoid pharmaceutical residues detectable in EU import testing.
- Needle-free transdermal delivery:Combination of electroporation devices with reformulated antigens is opening cow-calf sector adoption where labor scarcity constrains traditional injectable protocols.
- Brazilian MAPA telemedicine authorization:Federal veterinary prescription via remote consultation is expanding pharmaceutical access to remote Mato Grosso operations previously underserved by field veterinarians.
Industry Challenges
- Veterinary diagnostic capacity:Polymerase chain reaction pathogen identification requires laboratory infrastructure scarce in Paraguayan and Bolivian border regions where cross-border cattle trade concentrates.
- Biologics manufacturing scale-up:Cell culture capacity constraints at contract manufacturing organizations are extending lead times for commercial batches of multivalent respiratory vaccines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bovine Respiratory Disease Treatment Market |
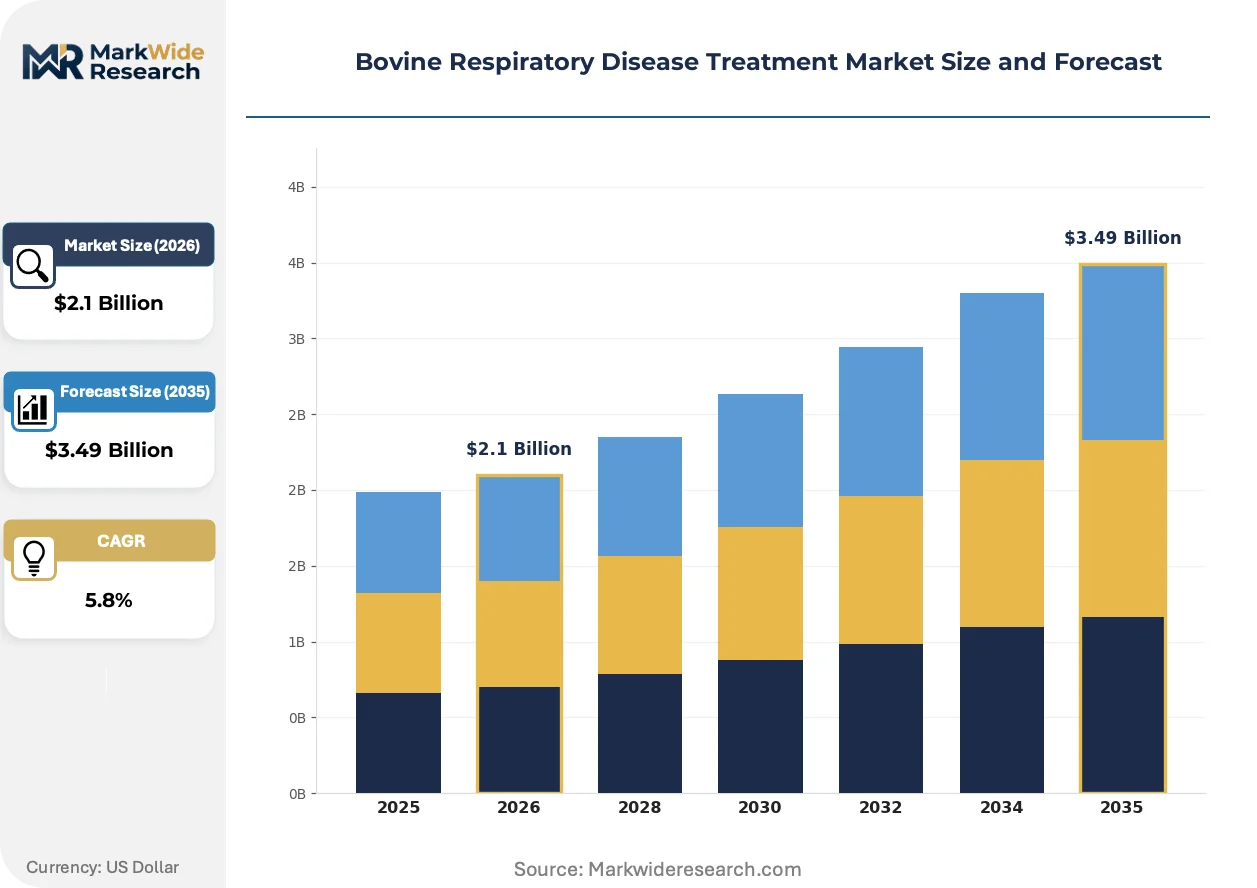
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Vaccines, Anti-Inflammatories, Immunomodulators, Supportive Care Application: Feedlot Cattle, Cow-Calf Operations, Stocker Cattle, Dairy Replacement Heifers, Breeding Bulls End User: Veterinary Clinics, Livestock Farms, Animal Health Centers, Research Institutes, Agricultural Cooperatives Delivery Mode: Injectable, Oral Administration, Inhalation, Topical, Transdermal |
| Companies Covered | Zoetis, Boehringer Ingelheim, Merck Animal Health, Elanco Animal Health, Bayer AG, Virbac, Ceva Santé Animale, Vetoquinol, Huvepharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bovine Respiratory Disease Treatment Market Strategic Shifts & Innovations
Platform biotechnology is compressing product development cycles while regulatory frameworks restructure distribution economics. These forces are converging to redefine competitive advantage around manufacturing flexibility and compliance architecture rather than molecule exclusivity alone.
Multivalent respiratory vaccine formulation is migrating from traditional inactivated whole-cell platforms toward subunit and vectored constructs that enable simultaneous protection against Mannheimia haemolytica, bovine viral diarrhea virus, and infectious bovine rhinotracheitis. Large-scale feedlot operators in Texas and Kansas are piloting these advanced formulations during receiving protocols. The technology shift is compressing the competitive window for single-pathogen products while rewarding developers with modular antigen insertion capabilities.
EMA's revised veterinary medicinal product regulation is mandating environmental risk assessments for all new antibiotic marketing authorizations across EU member states. This framework is elevating development costs for systemic respiratory therapeutics intended for export cattle entering European supply chains. Irish and Dutch pharmaceutical registrants are responding by prioritizing narrow-spectrum bacteriophage candidates with favorable ecotoxicology profiles.
Integrated animal health contracting is displacing transactional product purchasing among vertically coordinated beef systems. Tyson Foods and JBS are consolidating pharmaceutical procurement through multi-year preventive health agreements that bundle diagnostics, vaccines, and technical services. This pattern is most pronounced in US Plains states where packer-owned feedlots dominate finished cattle supply.
Bovine Respiratory Disease Treatment Market Segmentation
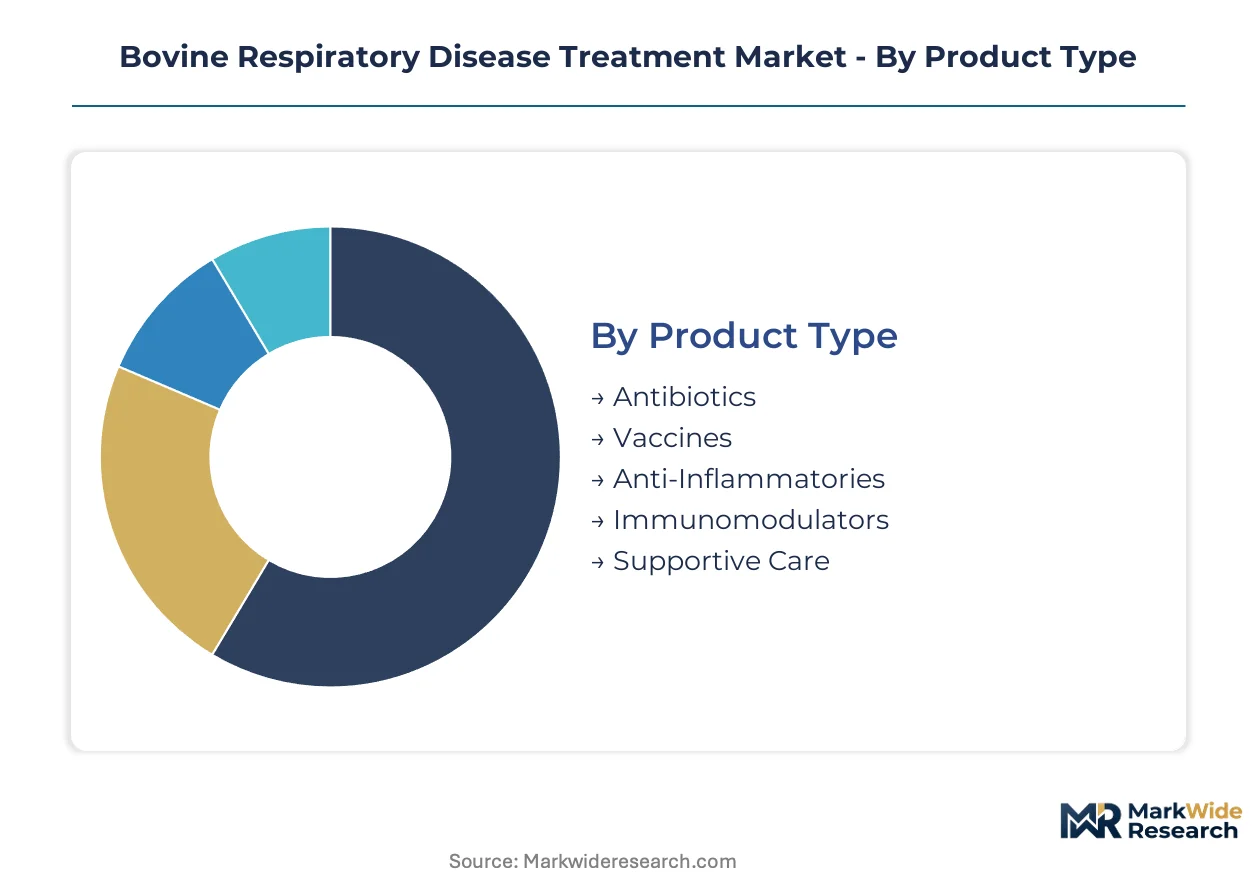
The Bovine Respiratory Disease Treatment Market fragments across four functional dimensions that determine procurement patterns and margin architecture. Product type and application segments drive the majority of purchasing decisions, while delivery mode and end-user channels reshape distribution economics and compliance requirements.
Product Type:
Mature antibiotic formulations coexist with emerging biologics platforms across this category, creating divergent margin profiles and development timelines.
- Antibiotics:Tetracyclines, macrolides, and cephalosporins constitute the established therapeutic backbone for acute bacterial pneumonia cases in commercial feedlots. Demand concentrates in Brazilian finishing systems where export-grade carcass specifications tolerate residue withdrawal protocols. FDA's Veterinary Feed Directive has compressed over-the-counter availability, forcing prescription-based procurement through accredited veterinarians.
- Vaccines:Modified-live viral, inactivated bacterial, and emerging mRNA platforms deliver preventive protection against Mannheimia haemolytica, bovine viral diarrhea virus, and infectious bovine rhinotracheitis. Kansas and Texas feedlot operators are piloting multivalent subunit formulations during receiving protocols to reduce metaphylactic antibiotic dependence.
- Anti-Inflammatories:Corticosteroids and NSAIDs manage pyrexia and lung consolidation in clinical BRD cases.
- Immunomodulators:Cytokine modulators and toll-like receptor agonists represent developmental adjuncts to core antimicrobial protocols.
- Supportive Care:Electrolyte solutions, bronchodilators, and nutritional supplements address dehydration and respiratory distress in hospitalized cattle.
Antibiotics handle the majority of throughput; Vaccines are expanding most quickly on share as preventive protocols displace reactive treatment.
Application:
Production system intensity determines disease pressure and pharmaceutical consumption patterns across this category.
- Feedlot Cattle:High-density finishing environments concentrate respiratory pathogen transmission risk during receiving and adaptation phases. Brazilian operators expanding pen capacity to meet export specifications drive the steepest consumption intensity per animal unit. USDA traceability mandates for interstate movement documentation embed pharmaceutical products into compliance infrastructure.
- Cow-Calf Operations:Pasture-based breeding herds experience lower pathogen pressure but require handling-efficient delivery formats due to labor constraints. Remote Mato Grosso ranching regions with unreliable cold chain infrastructure limit mRNA vaccine reach, favoring thermostable alternatives.
- Stocker Cattle:Backgrounding operations on wheat pasture and native range present intermediate disease risk profiles.
- Dairy Replacement Heifers:Pre-weaned and growing heifer populations in confinement facilities require respiratory protection integrated with reproductive health protocols.
- Breeding Bulls:High-value seedstock operations prioritize residue-free preventive programs to preserve semen quality and international sales eligibility.
Feedlot Cattle dominates absolute consumption volume; Cow-Calf Operations are gaining share fastest as needle-free delivery technologies reduce labor barriers.
End User:
Channel structure varies by cattle operation scale and veterinary service accessibility across this category.
- Veterinary Clinics:Private practitioners and corporate veterinary networks deliver prescription therapeutics and technical consultation to commercial producers. Federal telemedicine authorization by Brazil's MAPA is expanding pharmaceutical access to remote operations previously underserved by field veterinarians.
- Livestock Farms:Vertically coordinated beef systems including Tyson Foods and JBS-owned feedlots consolidate procurement through multi-year preventive health agreements bundling diagnostics, vaccines, and technical services.
- Animal Health Centers:University-affiliated referral hospitals and diagnostic laboratories manage complex cases requiring polymerase chain reaction pathogen identification.
- Research Institutes:Agricultural experiment stations and pharmaceutical field trial sites generate efficacy data for regulatory submissions.
- Agricultural Cooperatives:Member-owned purchasing alliances aggregate demand for generic antibiotics and core vaccines across smaller independent producers.
Livestock Farms command the largest procurement volumes; Veterinary Clinics are climbing fastest as prescription requirements tighten.
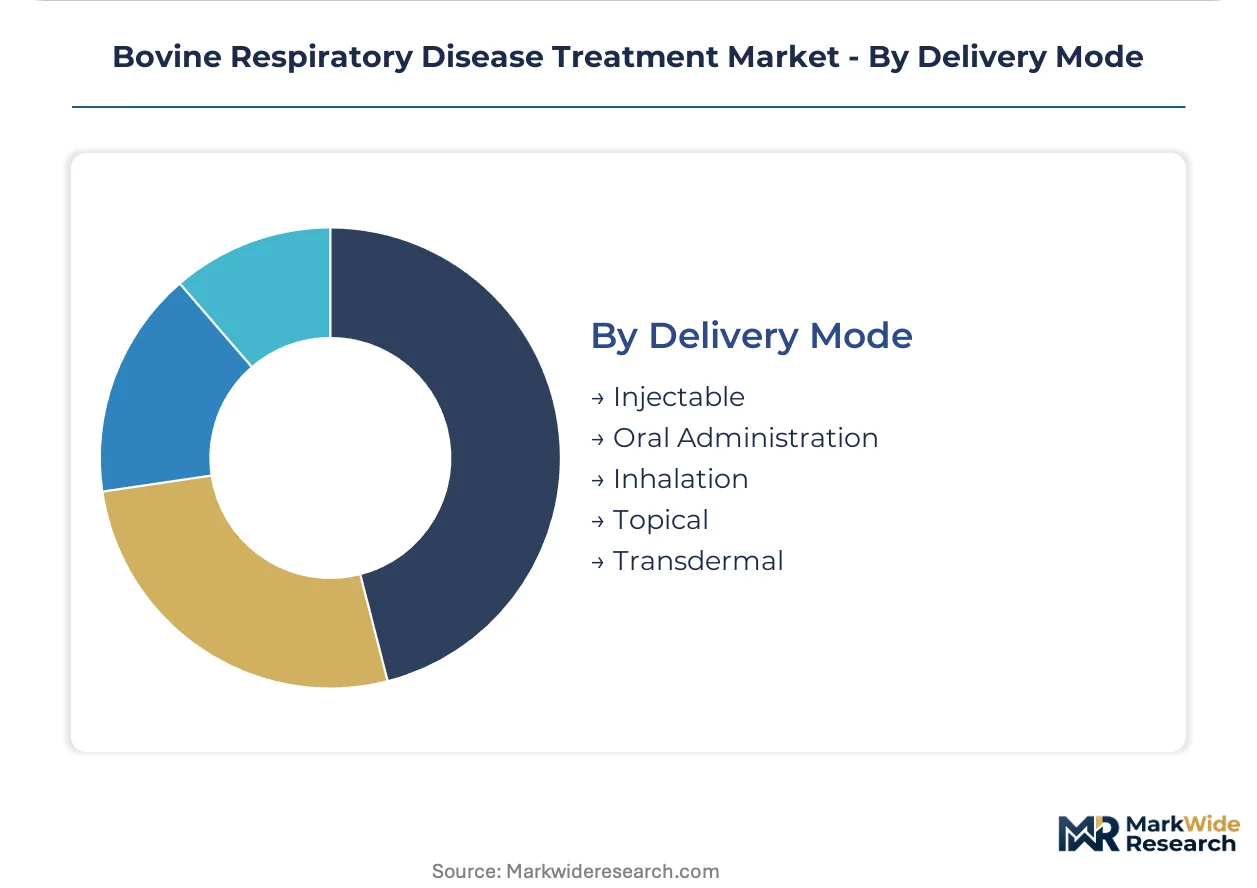
Delivery Mode:
Administrative efficiency and dosing assurance trade off across this category's technical alternatives.
- Injectable:Subcutaneous and intramuscular administration ensures precise dosing and rapid systemic absorption in clinical settings. Injectable formats dominate US Plains states feedlot receiving protocols where labor availability supports chute-side handling.
- Oral Administration:Feed-grade antibiotics and water-soluble therapeutics suit mass medication scenarios in pen-based systems. EMA's environmental risk assessment requirements for new antibiotic authorizations are elevating development costs for oral formulations targeting EU export cattle.
- Inhalation:Nebulized antibiotics and bronchodilators target localized lung delivery in hospitalized cases.
- Topical:Nasal vaccines and intranasal immunomodulators stimulate mucosal immunity at pathogen entry points.
- Transdermal:Electroporation devices combined with reformulated antigens are opening cow-calf sector adoption where labor scarcity constrains traditional handling protocols.
Injectable retains the dominant share; Transdermal is gaining traction fastest as needle-free technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feedlot operators and veterinary pharmaceutical distributors concentrate procurement decisions in five national markets where cattle production intensity and export orientation create differentiated demand profiles for respiratory disease interventions.
United States
High-density finishing operations in Texas and Kansas drive antibiotic and vaccine consumption through chute-side receiving protocols. The FDA's Veterinary Feed Directive compels prescription-based procurement, embedding accredited veterinarians into pharmaceutical distribution channels. Kansas-based feedlot clusters pilot multivalent subunit vaccines to reduce metaphylactic antibiotic dependence during cattle receiving.
Brazil
Expanding pen capacity in Mato Grosso and São Paulo elevates respiratory pathogen transmission risk and pharmaceutical intensity per animal unit. Brazil's MAPA federal telemedicine authorization expands prescription access to remote ranching regions previously underserved by field veterinarians. São Paulo-state feedlot operators consolidate demand for residue-free preventive programs meeting EU export specifications.
Germany
Specialized dairy replacement heifer operations in Bavaria and Lower Saxony integrate respiratory protection with reproductive health protocols. The EMA's revised veterinary medicinal product regulation mandates environmental risk assessments, elevating development costs for systemic antibiotics targeting export cattle. Baden-Württemberg pharmaceutical registrants prioritize narrow-spectrum bacteriophage candidates with favorable ecotoxicology profiles.
China
Intensifying beef production in Shandong and Henan provinces generates demand for respiratory therapeutics in confinement finishing systems. The country's national pharmaceutical regulator tightens antimicrobial residue monitoring in food animal products, accelerating vaccine investment over antibiotic protocols. Shandong Peninsula feedlot clusters adopt imported multivalent vaccines during high-risk receiving periods.
Australia
Grass-fed and grain-fed beef export operations in New South Wales and Queensland require respiratory prevention programs preserving EU and US market access. The country's Department of Agriculture enforces electronic identification and treatment traceability for interstate cattle movement. Queensland feedlot corridors near Roma and Dalby concentrate procurement of thermostable vaccine alternatives suited to remote refrigeration constraints.
Bovine Respiratory Disease Treatment Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base clusters around three strategic archetypes: vertically integrated biologics manufacturers with captive antigen production, diversified animal health conglomerates with global distribution networks, and regional formulation specialists serving price-sensitive generic antibiotic segments. Dominant competitive moves include backward integration into cell culture manufacturing capacity and strategic partnerships with large-scale packer-owned feedlot systems.
Within the integrated biologics tier, Zoetis and Boehringer Ingelheim occupy positions defined by platform technology control and multivalent vaccine development capabilities. Merck Animal Health represents the distribution-architype competitor, anchoring channel access across North American and Latin American livestock markets through veterinary clinic networks and direct procurement agreements with vertically coordinated beef systems.
| Leading Market Players |
|---|
| Zoetis |
| Boehringer Ingelheim |
| Merck Animal Health |
| Elanco Animal Health |
| Bayer AG |
| Virbac |
| Ceva Santé Animale |
| Vetoquinol |
| Huvepharma |
| Others |
Cost & Logistics Intelligence
Cell culture undercapacity at contract manufacturing organizations is compressing lead times for commercial batches of multivalent respiratory vaccines while simultaneously elevating price premiums for guaranteed slot allocations. This utilization squeeze rewards developers with captive biologics infrastructure and forces generic antibiotic formulators into raw material cost pass-through negotiations.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate tetracycline and macrolide procurement agreements between Brazilian feedlot operators and generic formulators. Pricing stratifies across premium branded subunit vaccines, standard modified-live viral platforms, and economy-tier inactivated bacterial alternatives. Cost compression in the antibiotic segment is intensifying because Chinese API export license volatility exposes formulators to freight cost swings. Cow-calf operations in remote Mato Grosso ranching regions exhibit the highest price sensitivity due to unreliable cold chain infrastructure, while vertically integrated packer-owned feedlots in Texas and Kansas demonstrate the lowest sensitivity through multi-year preventive health agreement bundling.
Supply Chain Analysis
Export control regimes on dual-use biologics manufacturing equipment limit cell culture capacity expansion in emerging pharmaceutical hubs, constraining global vaccine supply elasticity. Active pharmaceutical ingredient manufacturing for veterinary antibiotics concentrates in Chinese chemical hubs, Indian formulation clusters, and specialized European fermentation facilities. Production rests on tetracycline fermentation feedstocks, macrolide precursor chemicals, and cell culture media components. Single-source vulnerability pervades the API tier where tetracycline manufacturing clusters in specific coastal provinces. Distribution runs through accredited veterinary clinic networks in the United States, MAPA-authorized telemedicine platforms in Brazil, and agricultural cooperative purchasing alliances across smaller independent producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bovine respiratory disease treatment market functions as a defensive-moat arena where regulatory entrenchment around FDA Veterinary Feed Directive compliance and USDA traceability mandates creates substantial switching costs for commercial feedlot operators.
For Market Incumbents: Build regulatory data moats by embedding pharmaceutical products into USDA electronic health record compliance infrastructure and MAPA telemedicine authorization workflows. Backward integration into cell culture manufacturing capacity secures supply security against contract manufacturing organization bottlenecks. mRNA platform patent estates and multivalent vaccine antigen insertion capabilities defend against emerging biotech entrants with modular construct technologies. For New Entrants and Emerging Players: Thermostable vaccine alternatives for Brazilian interior ranching regions with unreliable refrigeration infrastructure represent the most penetrable entry point for platform biotechnology specialists. Uruguayan pasture finishing operations seeking residue-free preventive programs for EU export compliance offer a second white-space target. Needle-free transdermal delivery device partnerships with cow-calf sector equipment distributors provide a differentiated go-to-market angle bypassing incumbent injectable channel control. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated biologics manufacturers with captive antigen production and multi-year preventive health agreements with packer-owned feedlot systems. Long-term viability over the projection horizon favors developers with modular mRNA platform adaptability and rapid strain response capabilities. Acquisition targets should display cell culture manufacturing scale or Brazilian MAPA regulatory registration expertise. The signal to watch is FDA National Antimicrobial Resistance Monitoring System protocol expansion accelerating vaccine investment displacement of antibiotic protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Cell Culture Manufacturing Scale-Up | Captive biologics production insulates against contract manufacturing organization capacity constraints and slot allocation premiums. |
| Multivalent Vaccine Platform Development | Modular antigen insertion capabilities compress competitive windows for single-pathogen products in feedlot receiving protocols. |
| Telemedicine Regulatory Authorization | MAPA federal veterinary prescription via remote consultation expands pharmaceutical access to underserved Mato Grosso operations. |
| Needle-Free Transdermal Delivery Partnership | Electroporation device alliances reduce labor barriers in cow-calf sectors where chute-side handling constraints limit injectable adoption. |
| Integrated Preventive Health Contracting | Multi-year agreements bundling diagnostics, vaccines, and technical services displace transactional purchasing in vertically coordinated beef systems. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with veterinary pharmaceutical executives, regulatory affairs specialists at animal health registrants, feedlot procurement managers, and MAPA compliance officers; and secondary validation through FDA Veterinary Feed Directive guidance documents, USDA Animal and Plant Health Inspection Service traceability protocols, EMA veterinary medicinal product regulation filings, and Brazilian agricultural export certification databases. Bottom-up segmentation modeling triangulated against top-down market sizing from customs trade data and pharmaceutical distribution channel audits.
Forecast inputs considered high-density finishing system expansion rates, mRNA platform technology adoption curves, antimicrobial stewardship framework evolution, and cold chain infrastructure development across Brazilian interior ranching regions. Segmentation dimensions modeled included product type, application intensity, delivery mode efficiency, and end-user channel structure. CAGRs were derived from regression analysis of historical pharmaceutical consumption intensity per animal unit against projected feedlot capacity additions.
Practitioners should monitor FDA National Antimicrobial Resistance Monitoring System testing protocol expansion, Chinese API export license volatility, and Brazilian MAPA telemedicine authorization scope revisions for early signals of forecast deviation. Forecasts reflect assumptions around regulatory trajectory continuity and platform technology maturation timelines. Material shifts in antimicrobial stewardship enforcement intensity or biologics manufacturing capacity constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Ultrasound Market
Veterinary
Animal Microchip Implant Market
Veterinary
Veterinary Thermography Market
Veterinary
Clostridium Vaccine (Animal Health) Market
Veterinary
North America Veterinary Healthcare Market
Veterinary
Veterinary Endodontics Market
Veterinary
Veterinary Intravenous (IV) Solutions Market
Veterinary
Companion Animal Vaccines Market
Veterinary
Veterinary in Vitro Fertilization Market
Veterinary
Asia-Pacific Veterinary Vaccine Market
Veterinary
OTC Cat Medicines Market
Veterinary
Global Cattle Vaccines Market
Veterinary
Canine Arthritis Market
Veterinary
Pet Cancer Therapeutics Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Veterinary Biologicals Biobank Market