
 Ascites Market | 2026-2036
Ascites Market Size, Share, and Industry Trends Forecast 2026-2036
Ascites Market Analysis
Albumin is decoupling from older plasma volume expanders in ascites management, reshaping cost structures across hospital formularies. Pfizer Inc. leverages its manufacturing scale to supply diuretic portfolios across multiple geographies. Novartis AG anchors its position through sustained R&D investment in hepatology pipelines. Fresenius SE & Co. KGaA dominates parenteral solution production, controlling critical supply chains for albumin-dependent protocols.
Ascites denotes pathological fluid accumulation within the peritoneal cavity, typically exceeding 25 milliliters under normal physiologic conditions but progressing to several liters in decompensated states; its primary clinical purpose centers on symptom palliation, infection prevention, and hemodynamic stabilization in portal hypertension. Diuretics occupy the largest therapeutic share among product types, reflecting established guideline endorsement and oral administration convenience. Albumin solutions command premium positioning in paracentesis protocols, particularly for large-volume procedures where circulatory dysfunction risk escalates. Transjugular intrahepatic portosystemic shunt represents the fastest-expanding intervention category, driven by interventional radiology specialization and refractory case volumes.
The FDA regulates ascites therapies through its Center for Drug Evaluation and Research, enforcing efficacy benchmarks for diuretic and albumin indications, while the EMA's Committee for Medicinal Products for Human Use harmonizes hepatology drug standards across European member states. These frameworks elevate clinical trial costs but simultaneously compress time-to-market for therapies demonstrating meaningful survival or hospitalization reductions. Stakeholders must monitor reimbursement evolution for albumin in large-volume paracentesis, as payer scrutiny intensifies around cost-effectiveness thresholds for portal hypertension interventions.
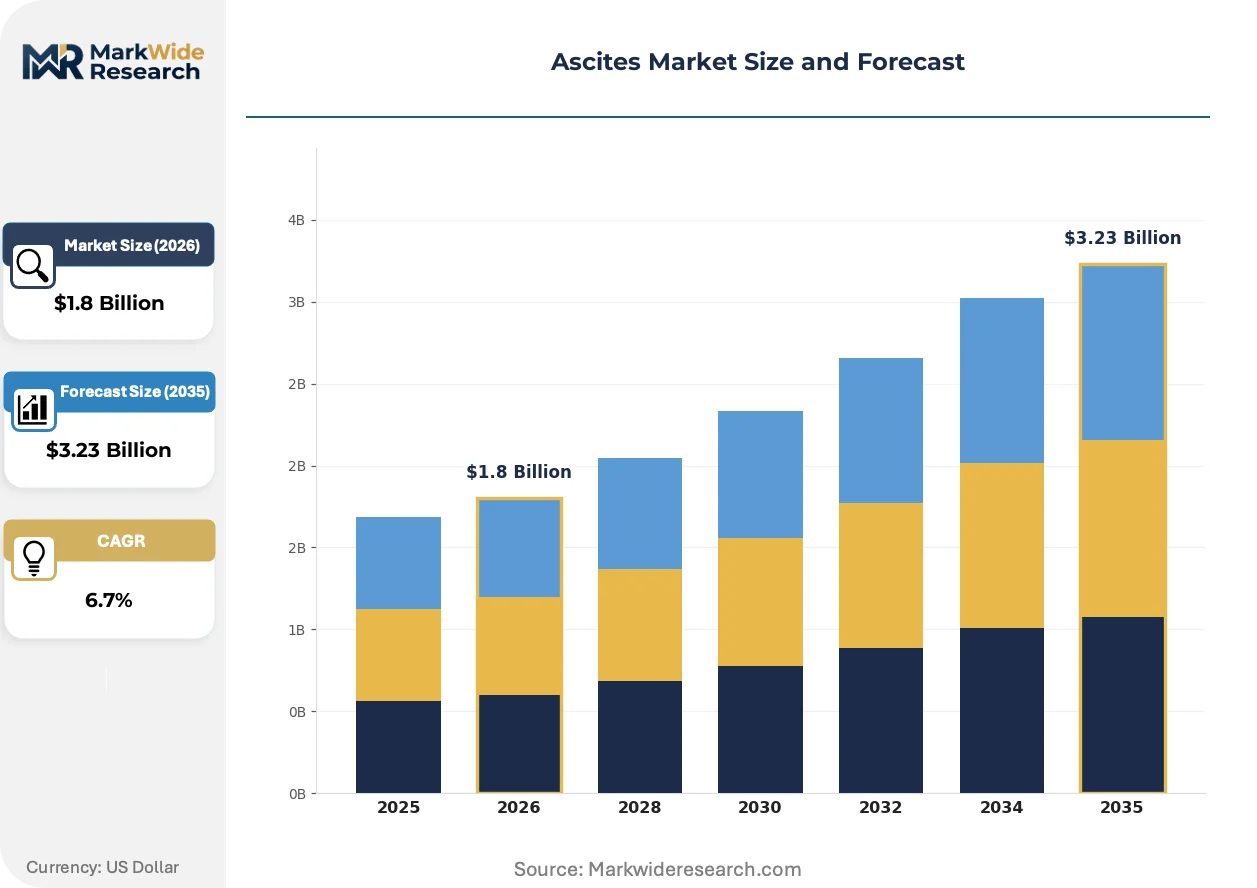
Market Dynamics
Hospital procurement of albumin solutions and paracentesis kits is concentrating purchasing power among integrated delivery networks, compressing margins for standalone suppliers while favoring manufacturers with captive plasma fractionation capabilities.
Growth Catalysts
- FDA Orphan Drug Incentives:Breakthrough therapy designations accelerate novel therapeutic development timelines for refractory ascites populations.
- Interventional Radiology Infrastructure:United States tertiary care centers expand transjugular intrahepatic portosystemic shunt procedural capacity to manage decompensated liver disease volumes.
- Plasma Collection Networks:Fractionators secure upstream control over albumin raw material through owned donor centers, stabilizing supply for large-volume paracentesis protocols.
Market Restraints
- Albumin Cost Volatility:Plasma-derived human albumin faces input cost pressure from donor recruitment expenses and viral safety testing requirements.
- Reimbursement Scrutiny:United States payers apply cost-effectiveness thresholds to large-volume paracentesis albumin coverage, creating formulary access friction.
- Diuretic Ceiling Effects:Spironolactone and furosemide combinations hit pharmacologic limits in refractory cases, forcing escalation to invasive interventions.
Strategic Opportunities
- Automated Paracentesis Devices:Closed-system fluid removal technologies reduce infection risk and nursing labor in United States hospital settings.
- India Tertiary Care Expansion:Decompensated liver disease case accumulation in metropolitan hospital chains creates demand for albumin-dependent protocols.
- Cell-Based Albumin Alternatives:Recombinant and plant-derived plasma expanders converge with bioprocessing advances to challenge plasma fractionation economics.
Industry Challenges
- Interventional Radiology Talent Pipeline:Transjugular intrahepatic portosystemic shunt specialization requires fellowship-trained operators, constraining procedural capacity expansion.
- Legacy EMR Integration:Ascites management protocols face workflow friction when hospital information systems lack hepatology-specific order sets for diuretic titration and paracentesis scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ascites Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paracentesis Kits, Albumin Solutions, Diuretics, Transjugular Intrahepatic Portosystemic Shunt End User: Hospitals, Clinics, Homecare, Ambulatory Surgical Centers Indication: Liver Cirrhosis, Cancer, Heart Failure, Infection Delivery Mode: Intravenous, Oral, Injection, Others |
| Companies Covered | F. Hoffmann-La Roche Ltd., Pfizer Inc., Novartis AG, Sanofi, Merck & Co., Inc., AstraZeneca, GSK plc, Teva Pharmaceutical Industries Ltd., Fresenius SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ascites Market Emerging Trajectories
Point-of-care diagnostics and minimally invasive interventions are redrawing clinical workflows in ascites management, shifting site-of-care decisions from inpatient wards toward ambulatory and interventional radiology settings.
Bedside ultrasound guidance for paracentesis is decentralizing procedural authority from specialized interventional suites to general hospital floors and emergency departments. Internal medicine residents and hospitalists adopt compact ultrasound systems for real-time needle visualization, reducing complication rates and consult dependency. This capability diffusion is compressing revenue capture for standalone interventional radiology practices while expanding throughput for high-volume medical services.
EMA's Committee for Medicinal Products for Human Use harmonizes hepatology drug standards across European member states, elevating clinical evidence requirements for albumin indications. Manufacturers must demonstrate meaningful survival or hospitalization reductions to secure reimbursement parity with existing protocols. German and French hospital formularies respond by tightening albumin allocation criteria to large-volume paracentesis with documented circulatory dysfunction risk.
Hospital supply chains consolidate albumin purchasing through prime vendor agreements with integrated delivery networks, displacing fragmented wholesaler relationships. Procurement committees centralize decision rights for plasma-derived products, bundling albumin with parenteral nutrition and coagulation factor contracts. This concentration is most visible in United States multi-hospital systems, where standardized protocols reduce brand-level physician preference variation.
Ascites Market Segmentation
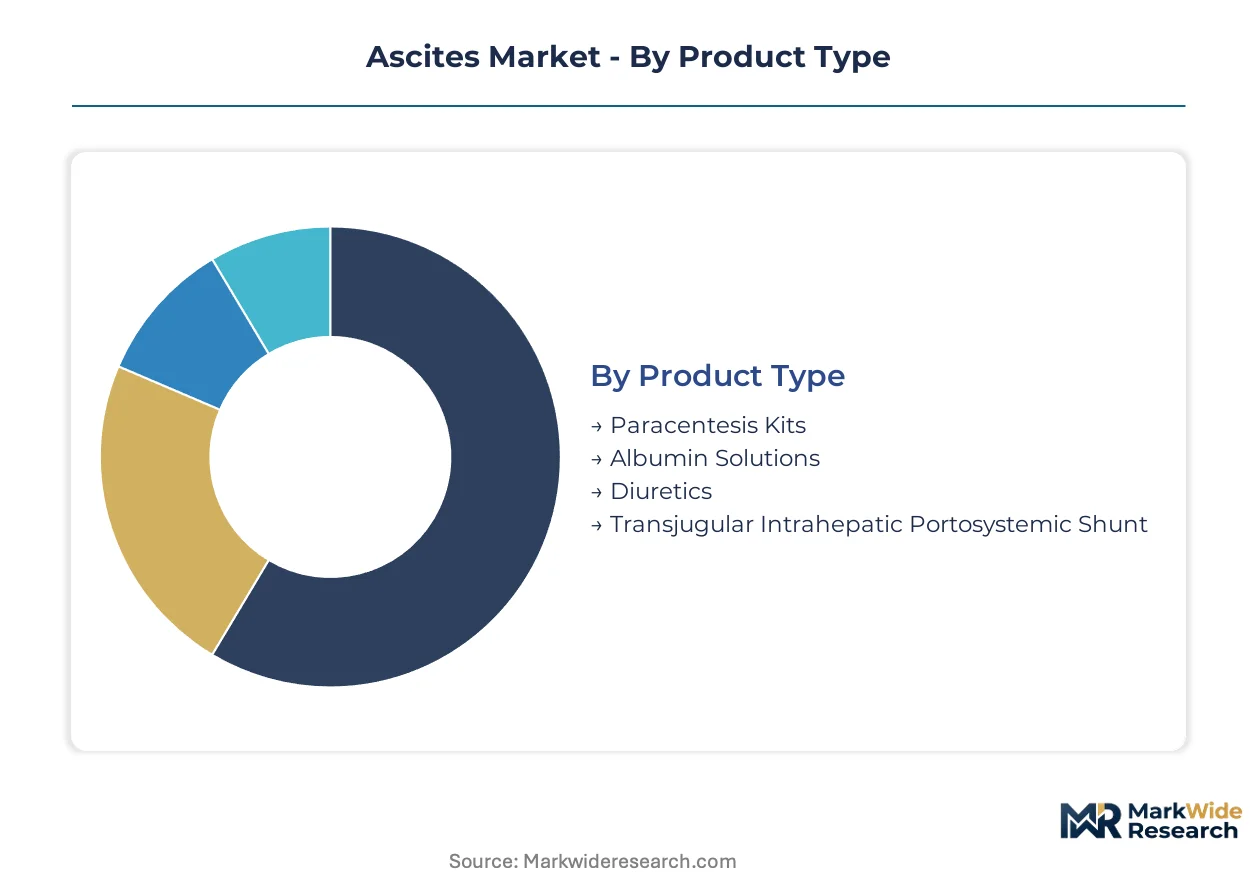
Hospital procurement committees segment ascites therapies by procedural workflow and reimbursement compatibility. Product selection hinges on paracentesis volume thresholds, diuretic response failure, and interventional radiology capacity.
Product Type:
Procurement committees prioritize supply security and protocol standardization when allocating budgets across therapeutic categories.
- Diuretics:Oral spironolactone and furosemide combinations remain first-line therapy for uncomplicated ascites. United States hospital formularies favor generic prescribing due to established guideline endorsement and minimal nursing supervision requirements.
- Albumin Solutions:Plasma-derived human albumin prevents post-paracentesis circulatory dysfunction in large-volume procedures. Fresenius SE and Grifols control fractionation capacity, constraining supply elasticity when tertiary care demand surges.
- Paracentesis Kits:Disposable drainage systems with vacuum-assisted collection reduce infection risk in bedside procedures.
- Transjugular Intrahepatic Portosystemic Shunt:Interventional radiology placement of expandable metal stents diverts portal blood flow in refractory cases.
Volume sits with Diuretics; growth tilts toward Transjugular Intrahepatic Portosystemic Shunt.
End User:
Site-of-care economics and procedural complexity determine facility-level adoption patterns.
- Hospitals:Tertiary medical centers concentrate refractory case management, interventional radiology suites, and albumin inventory. Medicare reimbursement for large-volume paracentesis with albumin replacement anchors revenue capture in United States academic institutions.
- Ambulatory Surgical Centers:Same-day paracentesis with ultrasound guidance shifts low-risk procedures from inpatient wards. United States freestanding centers exploit facility fee differentials for diagnostic taps under local anesthesia.
- Clinics:Outpatient hepatology practices manage diuretic titration and surveillance paracentesis.
- Homecare:Palliative drainage catheter maintenance extends to hospice-eligible patients with recurrent malignant ascites.
Revenue concentrates in Hospitals; throughput expansion favors Ambulatory Surgical Centers.
Indication:
Underlying etiology dictates treatment intensity, recurrence probability, and survival prognosis.
- Liver Cirrhosis:Portal hypertension drives sodium retention and splanchnic vasodilation in decompensated hepatocellular function. United States transplant centers apply MELD score stratification to prioritize TIPS candidacy.
- Cancer:Peritoneal carcinomatosis produces refractory malignant ascites requiring repeated drainage or tunneled catheters. Gynecologic oncology units and pancreatic cancer services generate concentrated demand for palliative intervention.
- Heart Failure:Elevated right-sided pressures transmit to hepatic veins and peritoneum.
- Infection:Spontaneous bacterial peritonitis complicates cirrhotic ascites with mortality escalation.
Procedure volume clusters in Liver Cirrhosis; intervention complexity peaks in Cancer.
Delivery Mode:
Pharmacokinetic requirements and procedural setting constrain administration route selection.
- Oral:Diuretic tablets enable outpatient self-administration with weight-based dose adjustment. United States pharmacy benefit managers apply prior authorization requirements to branded loop diuretics.
- Intravenous:Albumin infusion mandates infusion center capacity or inpatient admission for hemodynamic monitoring. United States hospital outpatient departments bill separately for drug and administration under APC reimbursement.
- Injection:Subcutaneous furosemide alternatives address bioavailability limitations in edematous patients.
- Others:Intraperitoneal chemotherapy and palliative sclerosants complete the modality spectrum.
Utilization dominance rests with Oral; value capture concentrates in Intravenous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States tertiary care centers concentrate the highest procedure volumes for refractory ascites management, with interventional radiology infrastructure and Medicare reimbursement anchoring market value capture.
United States
Academic medical centers in Boston, Houston, and Los Angeles drive TIPS procedure standardization through fellowship-trained operator pipelines. The FDA's breakthrough therapy designation accelerates novel therapeutic development timelines for orphan indications. Cleveland Clinic and Mayo Clinic anchor multi-site albumin procurement networks that consolidate purchasing power across integrated delivery systems.
Germany
University hospitals in Berlin, Munich, and Hamburg manage the highest European caseloads of decompensated liver disease requiring large-volume paracentesis. EMA's Committee for Medicinal Products for Human Use harmonizes hepatology drug standards across member states, elevating clinical evidence requirements. The Ruhr region concentrates plasma fractionation capacity through Fresenius SE production facilities serving Central European hospital formularies.
India
Metropolitan hospital chains in Mumbai, Delhi, and Bangalore accumulate decompensated cirrhosis cases from underserved rural catchments. The country's national pharmaceutical regulator enforces viral safety testing requirements for plasma-derived products under CDSCO oversight. Apollo Hospitals and Max Healthcare expand interventional radiology suites to capture escalating demand for minimally invasive portal hypertension management.
Japan
Liver transplant centers in Tokyo, Osaka, and Nagoya apply MELD-Na score stratification to prioritize TIPS candidacy in aging cirrhotic populations. METI coordinates domestic plasma collection networks to reduce import dependency for albumin solutions. The Kansai region hosts specialized hepatology units that pioneer ultrasound-guided paracentesis protocols for outpatient settings.
United Kingdom
NHS England's specialized commissioning framework concentrates refractory ascites management at designated liver centers in London, Birmingham, and Manchester. NICE technology appraisals apply cost-effectiveness thresholds to albumin reimbursement in large-volume paracentesis. The Oxford-Cambridge arc anchors hepatology research networks that feed early-phase therapeutic trials into the EMA centralized procedure.
Ascites Market Vendor Landscape
Capacity expansion dominates the current landscape as plasma fractionators secure upstream control over albumin raw material through owned donor centers. The vendor base concentrates among integrated healthcare conglomerates with captive bioprocessing capabilities, creating tiered supply security for hospital procurement committees. Three strategic archetypes define positioning: plasma-derived biologics specialists, diversified pharmaceutical manufacturers with hepatology portfolios, and interventional device suppliers. Competitive moves center on backward integration into plasma collection networks and geographic expansion of fractionation footprint.
Among Swiss-based pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd. and Novartis AG exemplify the diversified therapeutic developer archetype, anchoring hepatology pipelines through sustained R&D investment. Pfizer Inc. represents the scale-driven manufacturing model, leveraging global distribution infrastructure to supply diuretic portfolios across multiple geographies. Fresenius SE & Co. KGaA occupies a distinct position as a German healthcare group with integrated plasma fractionation capabilities, controlling critical supply chains for albumin-dependent protocols.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Pfizer Inc. |
| Novartis AG |
| Sanofi |
| Merck & Co., Inc. |
| AstraZeneca |
| GSK plc |
| Teva Pharmaceutical Industries Ltd. |
| Fresenius SE & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
Plasma collection costs cascade through albumin pricing tiers as fractionation economics tether hospital procurement to donor center density and viral safety testing burdens. United States integrated delivery networks exploit volume concentration to compress per-unit albumin expenditure while standalone hospitals absorb premium markups from fragmented wholesaler relationships.
Pricing Analysis
High-volume paracentesis protocols generate thin margins on diuretic co-prescribing while albumin replacement captures disproportionate value per procedure. Three-tier pricing structure across premium plasma-derived, standard volume-expanded, and economy synthetic colloid levels segments buyer archetypes by circulatory dysfunction risk tolerance. Pricing pressure stems from Medicare reimbursement compression on large-volume paracentesis with albumin coverage. Ambulatory surgical centers exhibit highest price sensitivity due to facility fee differentials; tertiary transplant centers show lowest sensitivity given bundled transplant pathway economics.
Supply Chain Analysis
Unused paracentesis kit components and expired albumin vials flow back through hospital reverse-logistics networks for credit reconciliation with prime vendors. Plasma fractionation concentrates in Germany, Spain, and the United States through Fresenius SE and Grifols captive donor center networks. Raw material dependencies center on source plasma collection, viral inactivation reagents, and sterile disposable manufacturing. Single-source vulnerability pervades albumin supply given plasma collection geographic constraints. Distribution runs through integrated delivery network prime vendor agreements displacing fragmented regional wholesaler relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where plasma fractionators secure upstream donor center control to anchor hospital procurement loyalty. Backward integration into plasma collection networks represents the decisive competitive lever separating supply-secure incumbents from margin-compressed challengers.
For Market Incumbents: Anticipate reimbursement compression on albumin indications by diversifying into recombinant albumin development and automated paracentesis device portfolios. CDSCO regulatory harmonization in India threatens premium pricing on imported plasma derivatives. Capacity addition in Indian metropolitan hospital chains secures early-mover positioning in fastest-expanding demand geography. For New Entrants and Emerging Players: The price-point gap between premium plasma-derived albumin and economy synthetic colloids creates white-space opportunity for cell-based recombinant alternatives. Palliative malignant ascites drainage in United States hospice settings offers most penetrable application given formulary flexibility and limited incumbent presence. Direct hospital system partnerships bypass GPO contracting friction for automated paracentesis technologies. For Investors and Strategic Acquirers: FDA breakthrough therapy designation for refractory ascites candidates is the leading indicator that hepatology pipeline value is concentrating in late-stage assets. Long-term viability favors vertically integrated bioprocessing platforms with captive plasma supply over standalone device or pharmaceutical developers. Acquisition target archetype: mid-cap plasma fractionators with underutilized donor center networks in emerging geographies. Monitor EMA centralized procedure approval timelines for albumin indication expansions as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | Fresenius SE secures upstream raw material control through owned donor centers in Central Europe. |
| Automated Paracentesis Device Launch | Closed-system fluid removal technologies reduce infection liability in United States hospital wards. |
| Recombinant Albumin Development | Cell-based alternatives challenge plasma fractionation economics as viral safety testing costs escalate. |
| TIPS Procedural Capacity Buildout | Apollo Hospitals expands interventional radiology suites to capture Indian metropolitan demand. |
| Orphan Drug Designation Pursuit | FDA incentives compress development timelines for refractory ascites therapeutic candidates. |
Methodological Framework
FDA filings, EMA centralized procedure records, and ClinicalTrials.gov hepatology trial databases formed the secondary backbone for therapeutic pipeline mapping and regulatory pathway assessment. Primary interviews with hepatology division chiefs, hospital formulary directors, interventional radiology fellowship program directors, and plasma fractionation procurement managers validated demand assumptions and pricing dynamics. Bottom-up procedure volume estimates from Medicare claims data combined with top-down market sizing from plasma fractionation capacity disclosures to anchor value projections.
Historical trendline analysis of paracentesis procedure volumes, albumin unit shipments, and TIPS placement rates informed baseline trajectory assumptions across the analysis window. Segmentation modeling incorporated product type, end-user facility tier, underlying indication etiology, and regional regulatory cluster dimensions. CAGRs derived from exponential smoothing of procedure growth rates adjusted for interventional radiology training pipeline constraints and reimbursement policy evolution. Forecast inputs included MELD score distribution projections and decompensated cirrhosis incidence modeling.
Inputs from CMS Medicare claims, GPO contract databases, and plasma industry association reports were available through the study window; gaps in real-time hospital inventory positioning and confidential pricing negotiations introduce uncertainty bands around near-term volume assumptions. Forecasts reflect documented assumptions regarding interventional radiology workforce expansion and albumin reimbursement stability. Practitioners should monitor NICE technology appraisal outcomes and CDSCO plasma product registration timelines for early signals of pricing and access trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Histoplasmosis Treatment Market
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Porphyria Treatment Market
Medical Treatment
China Nose Reconstruction Market
Medical Treatment
Anaphylaxis Treatment Market
Medical Treatment
Malaria Treatment Market
Medical Treatment
Single-Dose Therapy Market
Medical Treatment
Hypogonadism Treatment Market
Medical Treatment
Radiation Proctitis Treatment Market
Medical Treatment
Cysticercosis (Taeniasis) Treatment Market
Medical Treatment
Histiocytosis Treatment Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Encephalitis Treatment Market
Medical Treatment
Rotator Cuff Injury Treatment Market