
 Single-Dose Therapy Market | 2026-2036
Single-Dose Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Dose Therapy Market Analytics
Pharmaceutical-grade lyophilization standards are unwinding legacy multi-dose vial conventions across infectious disease and oncology supply chains. Gilead Sciences, Inc. leverages its antiviral manufacturing depth to dominate injectable single-dose formats for hepatitis and HIV indications. Bristol-Myers Squibb Company anchors its immuno-oncology portfolio with pre-filled syringe presentations that reduce compounding variability in hospital settings.
Single-dose therapy denotes pharmaceutical preparations containing one complete treatment course in a sealed, ready-to-administer unit, typically manufactured through aseptic filling, blow-fill-seal, or lyophilization processes with specified sterility assurance levels and extractables-leachables profiles. Its primary commercial purpose eliminates multi-dose preservative concerns, reduces microbial contamination risk, and enables precise dose tracking in accountable care environments. Injectable presentations lead current revenue pools due to biologic stability requirements and parenteral administration of monoclonal antibodies, while subcutaneous autoinjector formats represent the fastest-expanding administration route as self-administration protocols expand into home care settings. Oncology commands the largest therapy area share driven by cytotoxic agent handling protocols, though infectious disease single-dose regimens are gaining formulary placement through directly observed therapy analogs.
FDA unit-dose packaging regulations, EMA serialization directives under the Falsified Medicines Directive, and USP <797> sterile compounding standards collectively shape product design, labeling investments, and market access timelines for single-dose manufacturers. The Drug Supply Chain Security Act track-and-trace requirements further mandate unit-level identifiers that favor single-unit packaging over bulk containers. Stakeholders must monitor evolving USP <825> radiopharmaceutical standards and WHO prequalification pathways for single-dose antimalarials as these frameworks determine which manufacturing configurations achieve reimbursable status across integrated delivery networks and national procurement programs.
Market Dynamics
Hospital procurement departments are consolidating formularies around ready-to-administer formats to eliminate compounding variability and satisfy USP sterile compounding standards. This structural pull is compressing multi-dose vial shelf presence while accelerating blow-fill-seal and pre-filled syringe capacity investments.
Growth Catalysts
- FDA Unit-Dose Packaging Mandates:The agency's serialization and track-and-trace requirements under the Drug Supply Chain Security Act favor single-unit packaging configurations over bulk containers.
- Integrated Delivery Networks:Hospital systems and specialty pharmacy networks prioritize pre-filled presentations to reduce medication errors and waste in accountable care environments.
- Lyophilization Process Maturation:Pharmaceutical-grade freeze-drying standards now enable stable single-dose formats for temperature-sensitive biologics previously restricted to multi-dose vials.
Market Restraints
- Glass and Polymer Input Volatility:Borosilicate glass and cyclic olefin polymer prices fluctuate with energy costs, squeezing margins on pre-filled syringe and vial production.
- European Manufacturing Concentration:Aseptic filling capacity clusters in Germany, Switzerland, and Ireland, creating supply vulnerability during regional disruptions.
- EMA Serialization Compliance Burden:The Falsified Medicines Directive's verification system demands capital-intensive line upgrades that mid-tier manufacturers struggle to fund.
Strategic Opportunities
- Home Care Self-Administration:Subcutaneous autoinjector formats for chronic disease management open patient populations outside hospital settings.
- India's National Health Mission:Government procurement programs for single-dose antimalarials and vaccines create volume anchors for qualified suppliers.
- WHO Prequalification Pathways:Alignment with international procurement standards unlocks access to global health fund purchasing pools.
Industry Challenges
- Aseptic Processing Talent Scarcity:Qualified personnel for isolator-based filling operations remain concentrated at established manufacturing hubs.
- Extractables-Leachables Validation:Container closure system qualification timelines extend development cycles for novel drug-device combinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Dose Therapy Market |
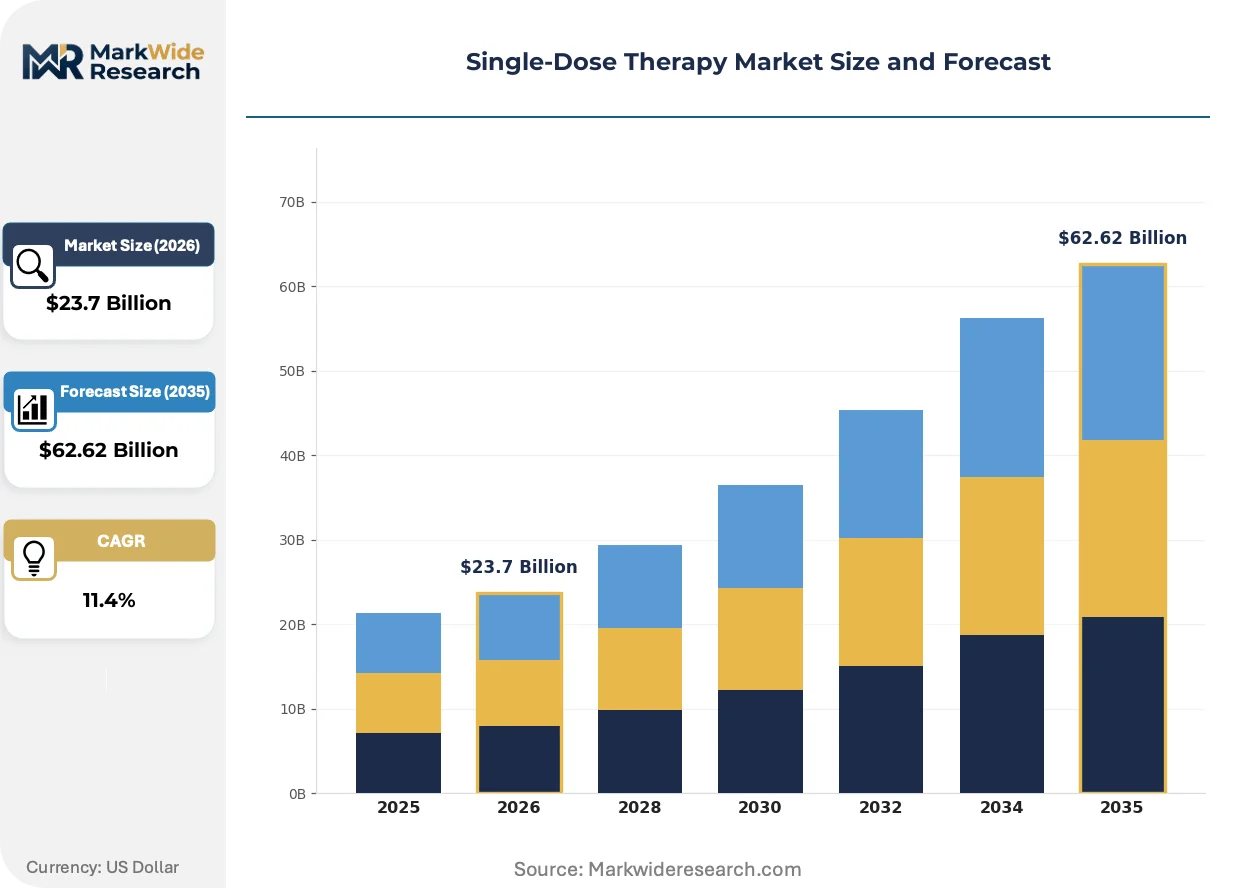
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injections, Capsules, Vials, Tablets Therapy Area: Oncology, Pain Management, Infectious Diseases, Cardiovascular End User: Hospitals, Clinics, Pharmacies, Home Care Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular |
| Companies Covered | AbbVie Co., AstraZeneca plc, Bayer AG, BioCryst Pharmaceuticals, Inc., Bristol-Myers Squibb Company, Gilead Sciences, Inc., Merck & Co., Novartis AG, Pfizer, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Dose Therapy Market Evolving Landscape
Technology convergence between device engineering and formulation science is collapsing the traditional separation between primary packaging and drug delivery systems. This integration is redefining competitive advantage around platform flexibility rather than commodity fill-finish scale.
Blow-fill-seal technology is bifurcating the liquid sterile products market between high-volume commodity presentations and complex biologic formats requiring specialized polymer formulations. Contract manufacturers in the United States and Germany are retrofitting lines for both throughput and flexibility. The structural consequence is compressing legacy glass vial demand in ophthalmic and respiratory categories while enabling new therapeutic classes.
EMA serialization directives under the Falsified Medicines Directive are forcing line-level investments in aggregation software and tamper-evident features. Industrial consequence includes extended validation timelines and higher per-unit packaging costs. Oncology and high-value biologic segments absorb these costs fastest through premium positioning, while generic injectables face margin compression.
Specialty pharmacy networks are consolidating purchasing authority around pre-negotiated formularies that exclude multi-dose alternatives. Hospital outpatient departments and home infusion services increasingly specify ready-to-administer units to minimize compounding liability. The United States exhibits the most pronounced channel concentration, with integrated delivery networks capturing disproportionate single-dose volume through centralized procurement.
Single-Dose Therapy Market Segmentation
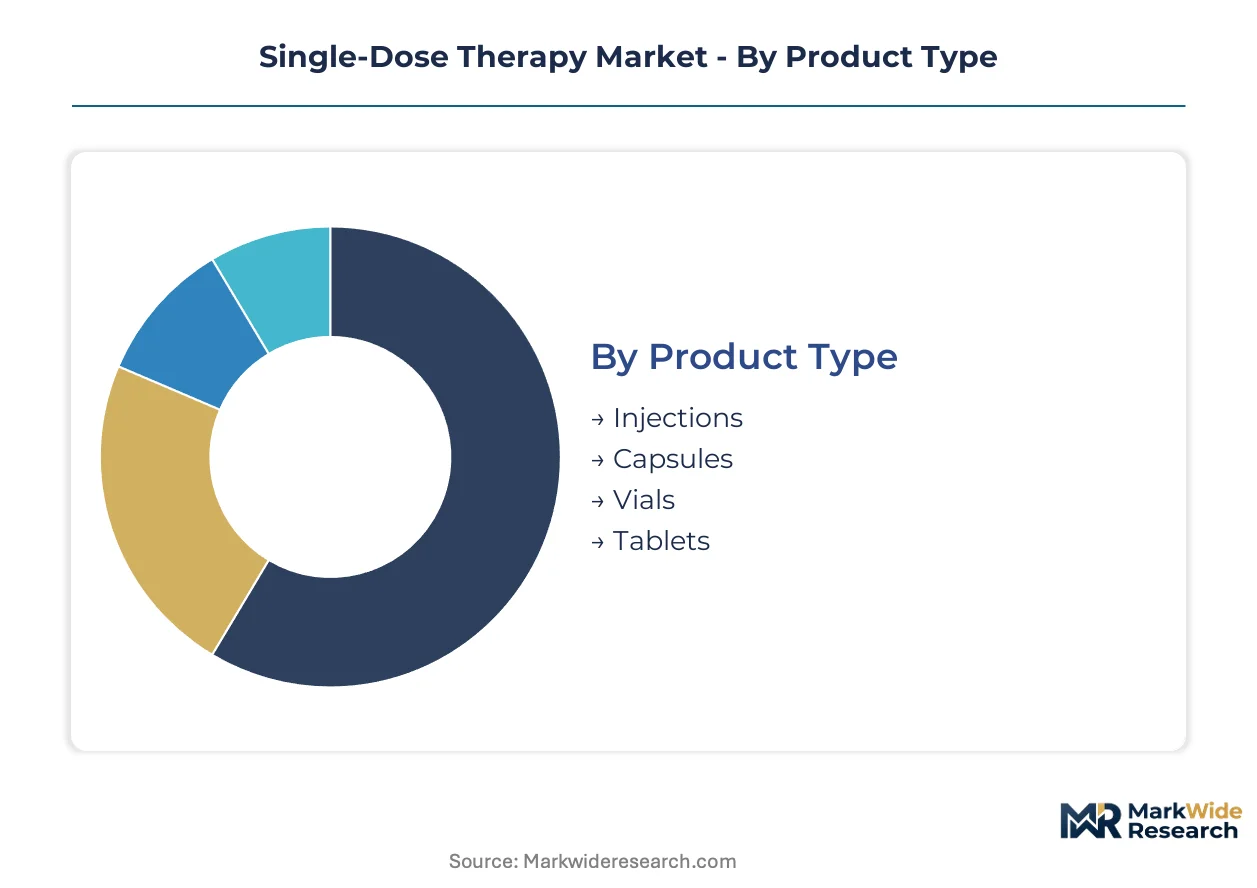
Single-dose therapy configurations vary sharply across regulatory jurisdictions, with FDA serialization mandates favoring unit-dose injectables while EMA track-and-trace requirements accelerate pre-filled adoption in European hospital networks. Product design decisions cascade through therapy area selection, end-user procurement protocols, and administration route feasibility.
Product Type:
FDA unit-dose packaging regulations and USP sterile compounding standards create divergent compliance burdens across primary container formats, with isolator-based filling requirements and extractables-leachables validation timelines varying by presentation.
- Injections:Pre-filled syringes and autoinjectors manufactured through aseptic filling or blow-fill-seal processes dominate biologic stability requirements. Demand concentrates in United States specialty pharmacy networks where USP 797 standards eliminate compounding liability for parenteral monoclonal antibodies.
- Vials:Pharmaceutical-grade lyophilization enables stable single-dose formats for temperature-sensitive oncology agents. German and Swiss aseptic filling clusters supply European hospital procurement departments under EMA serialization directives.
- Capsules:Blister-packaged oral solids with tamper-evident features satisfy Drug Supply Chain Security Act track-and-trace mandates for outpatient dispensing.
- Tablets:Unit-dose strip packaging reduces medication errors in accountable care environments with barcoded unit identifiers.
Injections handle the majority of throughput; vials are the fastest mover on share as lyophilization process maturation unlocks biologic categories.
Therapy Area:
Cost tier differentiation separates premium-positioned biologic segments from commodity infectious disease regimens, with pricing power determining which categories absorb packaging compliance investments fastest.
- Oncology:Cytotoxic agent handling protocols and occupational safety requirements drive pre-filled syringe adoption in hospital infusion centers. United States integrated delivery networks specify ready-to-administer units to minimize compounding variability for high-value immuno-oncology therapies.
- Infectious Diseases:Directly observed therapy analogs and government procurement programs for single-dose antimalarials create volume anchors. WHO prequalification pathways determine reimbursable status across national health missions in India and sub-Saharan Africa.
- Pain Management:Opioid diversion controls favor unit-dose packaging with tamper-evident features in United States hospital formularies.
- Cardiovascular:Chronic disease management protocols increasingly specify subcutaneous autoinjector formats for home care self-administration.
Oncology commands the dominant revenue position; infectious disease regimens are expanding most quickly through international procurement alignment.
End User:
Customer type determines packaging complexity, with institutional procurement demanding aggregation-ready configurations and retail channels prioritizing patient-facing unit-dose convenience.
- Hospitals:Centralized pharmacy operations and sterile compounding liability concerns consolidate formulary decisions around blow-fill-seal and pre-filled syringe presentations. United States health systems capture disproportionate volume through GPO-negotiated contracts.
- Home Care:Self-administration protocols for chronic biologics require patient-centric autoinjector designs with intuitive actuation mechanisms. Subcutaneous formats bypass infusion center capacity constraints.
- Clinics:Outpatient oncology and infectious disease administration favors ready-to-use vials reducing per-dose preparation time.
- Pharmacies:Specialty pharmacy networks exclude multi-dose alternatives from pre-negotiated formularies, concentrating single-dose dispensing authority.
Hospitals process the highest absolute volume; home care is gaining share fastest as administration shifts beyond institutional settings.
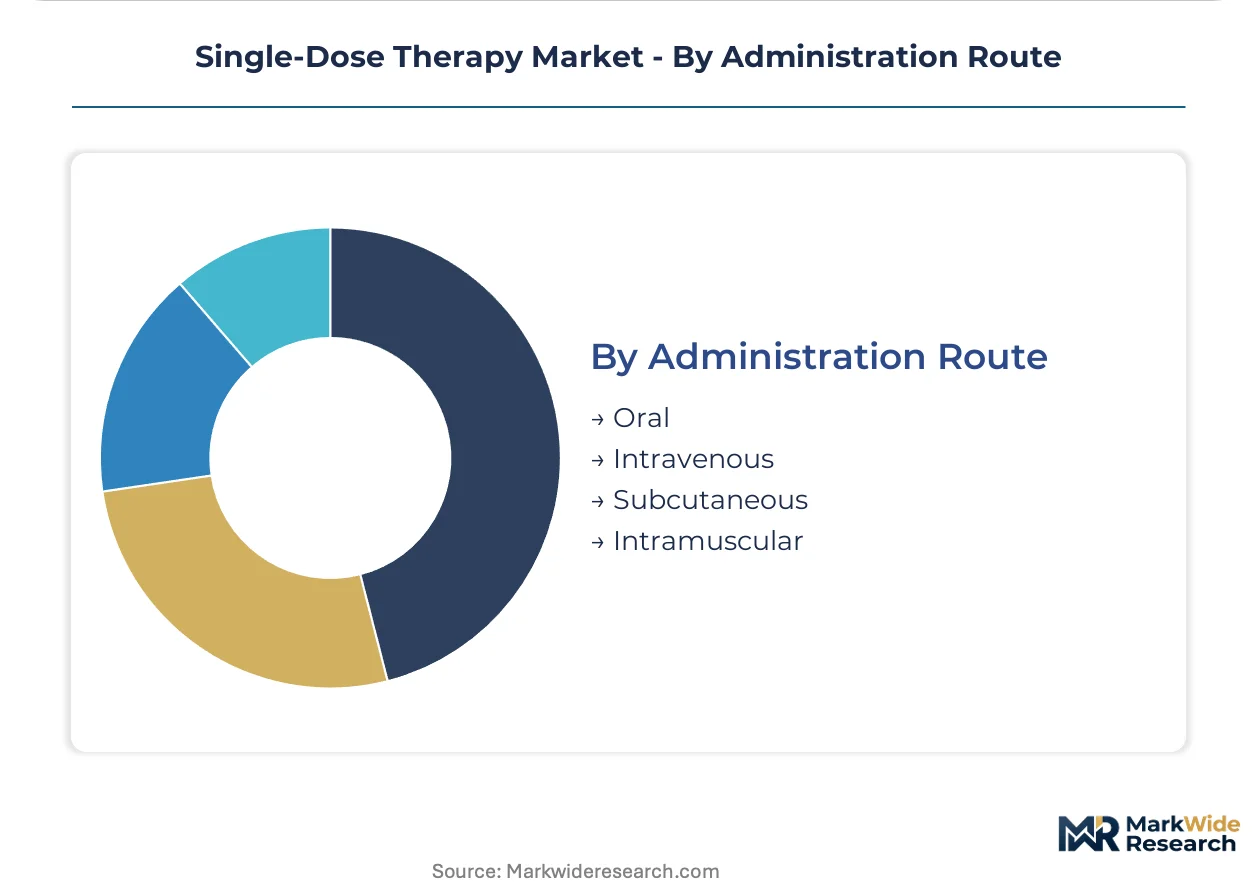
Administration Route:
Supply concentration in parenteral filling capacity creates geographic dependencies, with intravenous and subcutaneous formats tied to German, Swiss, and Irish manufacturing clusters.
- Intravenous:Lyophilized vials and pre-mixed infusion bags require compounding pharmacy infrastructure concentrated in United States hospital systems. EMA serialization compliance extends validation timelines for European-sourced products.
- Subcutaneous:Autoinjector platforms enable self-administration outside clinical settings, collapsing the traditional separation between primary packaging and drug delivery systems. Device engineering capabilities concentrate in United States and German manufacturing bases.
- Oral:Unit-dose blister and strip packaging satisfies FDA track-and-trace requirements for outpatient pharmacy dispensing with lower capital intensity than parenteral formats.
- Intramuscular:Pre-filled syringe presentations for vaccine and long-acting injectable categories align with WHO prequalification standards for global health procurement.
Intravenous retains the largest installed base; subcutaneous autoinjectors show the steepest expansion trajectory as chronic disease management migrates to home settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of single-dose therapies concentrate in German and Swiss aseptic filling clusters, while the United States maintains a persistent import dependency for lyophilized biologics despite substantial domestic blow-fill-seal capacity. India's government procurement programs and WHO prequalification alignment position it as an emerging volume exporter for infectious disease regimens.
United States
Specialty pharmacy networks and integrated delivery networks consolidate purchasing authority around pre-filled syringe presentations to satisfy USP sterile compounding standards. The FDA's Drug Supply Chain Security Act mandates unit-level serialization that favors single-unit packaging configurations over bulk containers. Boston and San Francisco biotech clusters anchor demand for autoinjector platforms enabling home care self-administration of chronic biologics.
Germany
Hospital procurement departments across Baden-Württemberg and Bavaria specify ready-to-administer formats to eliminate compounding variability in oncology infusion centers. EMA serialization directives under the Falsified Medicines Directive force capital-intensive line upgrades in aseptic filling operations. The Rhine-Main pharmaceutical manufacturing corridor concentrates isolator-based capacity for temperature-sensitive lyophilized products.
Switzerland
Swissmedic regulatory alignment with EMA standards accelerates prequalification timelines for high-value biologic single-dose formats. Basel and Zürich host contract manufacturing organizations specializing in blow-fill-seal technology for complex polymer formulations. Domestic producers export disproportionately to European hospital networks seeking serialization-compliant supply.
India
The National Health Mission's procurement programs for single-dose antimalarials and vaccines create volume anchors for qualified suppliers meeting WHO prequalification standards. CDSCO manufacturing licensing requirements and DGFT export incentives shape capacity investments in Gujarat and Maharashtra pharmaceutical clusters. Hyderabad and Mumbai manufacturing bases supply sub-Saharan African national health programs through global health fund purchasing pools.
China
NMPA serialization mandates under the national drug traceability system accelerate compliance investments by domestic manufacturers serving hospital procurement channels. Yangtze River Delta pharmaceutical clusters in Shanghai and Suzhou expand isolator-based filling capacity for oncology and infectious disease single-dose regimens. Domestic demand concentrates in tier-one city hospital systems prioritizing ready-to-administer formats to reduce medication errors.
Single-Dose Therapy Market Competitive Landscape
Concentration sits with large-cap pharmaceutical manufacturers possessing captive aseptic filling infrastructure and biologic formulation depth. The competitive structure tiers between integrated innovators with device-presentation capabilities, mid-scale specialists in lyophilization process technology, and contract manufacturing organizations supplying serialization-compliant capacity. Strategic moves center on backward integration into primary packaging materials and technology licensing for autoinjector platform expansion.
Within the integrated innovator tier, Gilead Sciences, Inc. and Bristol-Myers Squibb Company exemplify archetypes leveraging antiviral manufacturing depth and immuno-oncology portfolio scale respectively. These entities occupy positions where pre-filled syringe presentations reduce compounding variability in hospital settings. AstraZeneca plc represents the geographic diversification pattern among UK-headquartered manufacturers with substantial serialization-compliant capacity across multiple regulatory jurisdictions.
| Leading Market Players |
|---|
| AbbVie Co. |
| AstraZeneca plc |
| Bayer AG |
| BioCryst Pharmaceuticals, Inc. |
| Bristol-Myers Squibb Company |
| Gilead Sciences, Inc. |
| Merck & Co. |
| Novartis AG |
| Pfizer, Inc. |
| Others |
Value Network & Pricing Analysis
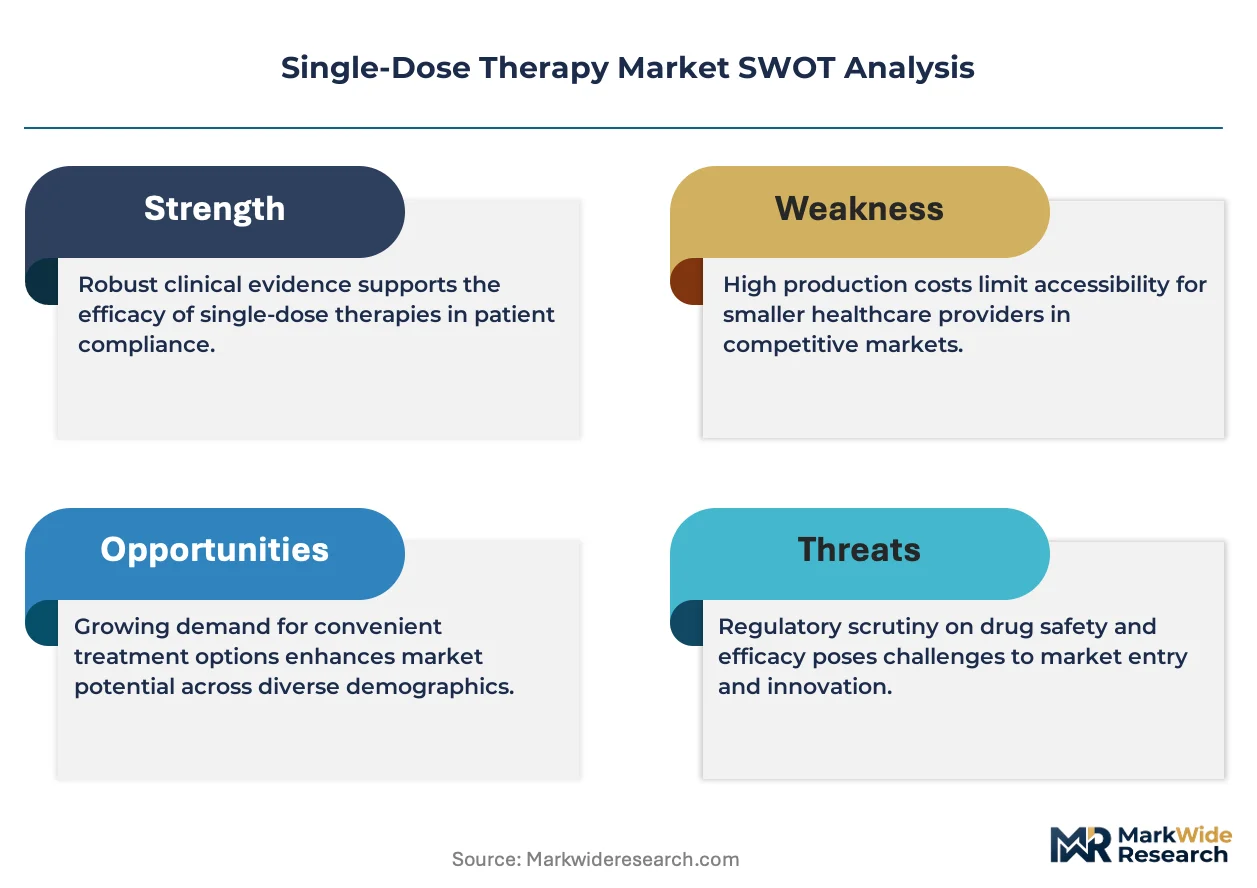
Ninety-day inventory buffers for borosilicate glass and cyclic olefin polymer feedstocks compress margin recovery timelines for pre-filled syringe manufacturers, concentrating pricing power with German and Swiss aseptic filling clusters that control lyophilization capacity for temperature-sensitive biologics.
Pricing Analysis
Hospital procurement departments anchor three-tier pricing structure across premium, standard, and economy levels, with oncology biologics commanding premium positioning due to cytotoxic handling protocols and occupational safety requirements. Price differentiation hinges on serialization compliance tier and autoinjector platform sophistication, with FDA Drug Supply Chain Security Act adherence adding per-unit packaging overhead. Cost compression in generic injectables intensifies because EMA Falsified Medicines Directive line upgrades burden mid-tier manufacturers, while integrated delivery networks exhibit lowest price sensitivity due to compounding liability reduction.
Supply Chain Analysis
Strategic stockpile preferences dominate borosilicate glass procurement as energy cost volatility disrupts just-in-time polymer sourcing for blow-fill-seal operations. Supply concentrates in Germany, Switzerland, and Ireland for isolator-based filling, drawing from cyclic olefin polymer, elastomeric closures, and pharmaceutical-grade glass tubing inputs. Single-source vulnerability in European aseptic processing talent pools threatens capacity expansion timelines. Distribution runs through specialty pharmacy networks and integrated delivery network centralized procurement in the United States, with WHO prequalification pathways unlocking government procurement channels in India and sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network formulary consolidation and specialty pharmacy network pre-negotiated contracts, fragmenting multi-dose vial alternatives from reimbursable status.
For Market Incumbents: Fortify serialization-compliant capacity in the Rhine-Main corridor and Basel-Zürich clusters to defend against contract manufacturing organization encroachment. Deepen backward integration into cyclic olefin polymer compounding to offset glass input volatility. Prioritize autoinjector platform licensing to capture home care self-administration volume migrating beyond hospital settings.
For New Entrants and Emerging Players: Anchor in India's National Health Mission procurement programs for single-dose antimalarials and vaccines, where WHO prequalification pathways create volume anchors absent incumbent saturation. Target sub-Saharan African national health programs through global health fund purchasing pools. Pursue blow-fill-seal technology licensing from German contract manufacturers to bypass isolator-based filling talent scarcity.
For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical parents divesting non-core aseptic filling infrastructure as they consolidate around captive biologic capacity. Long-term viability favors mid-scale lyophilization specialists with EMA serialization compliance and Indian CDSCO licensing. Watch FDA USP 825 radiopharmaceutical standard finalization as inflection indicator for new therapy area expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA unit-dose packaging mandates accelerate compliance investments by pre-filled syringe manufacturers. |
| Manufacturing Scale-Up | Blow-fill-seal line retrofits in United States and Germany capture ophthalmic and respiratory category migration. |
| Backward Integration | Captive cyclic olefin polymer compounding insulates margins from energy-linked input volatility. |
| Licensing Agreement | Autoinjector platform technology transfers enable home care self-administration protocol expansion. |
| Pipeline Diversification | Subcutaneous format development for cardiovascular chronic disease management opens retail pharmacy channels. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with formulary directors, hospital procurement managers, regulatory affairs leads, and aseptic filling operations heads; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up volume modeling across product type, therapy area, end user, and administration route segments triangulated with top-down regulatory framework analysis.
Across the projection horizon, the analytical framework modeled treatment line, dosage form, and regional regulatory cluster dimensions. CAGRs derived from historical volume trajectories and policy-driven demand inflection points incorporated USP sterile compounding standard enforcement timelines and EMA serialization directive implementation phases.
Decision-makers should treat outputs as directional under assumptions of sustained FDA Drug Supply Chain Security Act enforcement and stable WHO prequalification pathway access; material deviation would warrant model refresh. Revision becomes warranted when borosilicate glass supply disruption or EMA verification system mandate delays cross operational thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Scoliosis Management Market
Medical Treatment
Hereditary Amyloidosis Treatment Market
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Disseminated Intravascular Coagulation (DIC) Treatment Market
Medical Treatment
Leprosy Treatment Market
Medical Treatment
Non-Infectious Diarrhea Treatment Market
Medical Treatment
Histiocytosis Treatment Market
Medical Treatment
Surgical Procedures Volume Market
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Achalasia Treatment Market
Medical Treatment
Thyroid Gland Disorders Treatment Market
Medical Treatment
Hemorrhagic Shock Treatment Market
Medical Treatment
Global Fabry Disease Treatment Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
US and Japan Platelet Rich Plasma Market
Medical Treatment
Facial Spasm Treatment Market