
 Histoplasmosis Treatment Market | 2026-2036
Histoplasmosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Histoplasmosis Treatment Market Foresight
Fixed-dose combination packaging is pivoting toward patient-centric blister configurations that improve adherence in outpatient settings. Pfizer Inc. leverages its manufacturing scale to supply amphotericin B formulations across endemic regions. Merck & Co., Inc. anchors its position through sustained investment in triazole R&D pipelines. Gilead Sciences differentiates via specialized lipid complex delivery technologies that reduce nephrotoxicity profiles.
Histoplasmosis treatment encompasses pharmaceutical interventions targeting the dimorphic fungus Histoplasma capsulatum, with therapeutic protocols spanning induction-phase amphotericin B and consolidation-phase itraconazole or voriconazole regimens. The primary purpose centers on reducing mortality in disseminated disease while preventing relapse in immunocompromised hosts. Antifungal agents command the dominant revenue pool given their first-line status in severe presentations, while combination therapy segments show accelerated uptake where resistance patterns complicate monotherapy outcomes. Oral medications sustain the largest volume share due to extended maintenance requirements, though injectable medications retain premium positioning for ICU and step-down facility administration.
The FDA's orphan drug designation framework and priority review voucher program accelerate novel antifungal development timelines, while the EPA's environmental remediation guidelines for bird and bat droppings influence exposure reduction strategies in endemic zones. WHO fungal priority pathogens lists elevate histoplasmosis visibility within national essential medicines committees. Stakeholders must monitor evolving resistance surveillance data and reimbursement pathways for long-duration oral therapy to align portfolio investments with shifting treatment site migration from inpatient to home healthcare settings.
Market Dynamics
The migration of histoplasmosis care from inpatient wards to home-based oral therapy is compressing hospital pharmacy margins while expanding retail and specialty pharmacy procurement volumes across endemic regions.
Growth Catalysts
- FDA orphan drug incentives:Priority review vouchers and tax credits accelerate novel antifungal development timelines, drawing venture investment into previously neglected therapeutic areas.
- Immunocompromised population expansion:Rising transplant volumes and biologic therapy use in oncology and rheumatology create sustained demand pools for prophylactic and maintenance antifungal protocols.
- Ohio and Mississippi River valley endemicity:Persistent environmental reservoirs in these watershed regions ensure stable incidence baselines that underpin recurring treatment demand.
Market Restraints
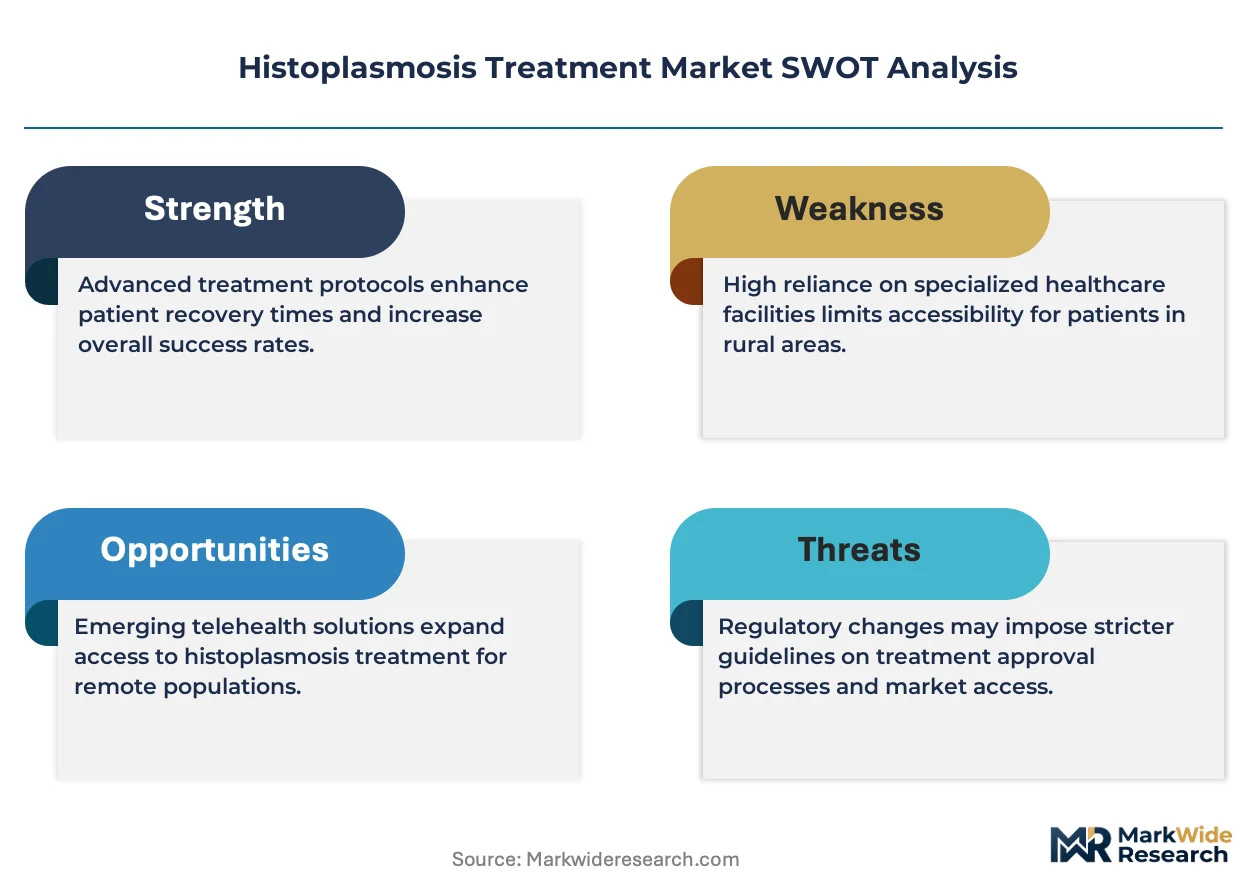
- Amphotericin B supply concentration:Manufacturing complexity and sterile production requirements limit qualified suppliers, creating vulnerability to batch contamination or facility shutdown events.
- Triazole drug-drug interaction burden:CYP450-mediated interactions with immunosuppressants, statins, and anticoagulants complicate co-prescribing in transplant and HIV patient populations.
- Diagnostic underdetection:Histoplasma antigen testing availability concentrates at tertiary referral centers, delaying treatment initiation in community settings where disease first presents.
Strategic Opportunities
- Point-of-care antigen testing expansion:Lateral flow immunoassay deployment in urgent care and rural clinics could compress time-to-diagnosis and expand addressable treatment windows.
- Lipid complex formulation innovation:Reduced nephrotoxicity profiles enable outpatient infusion center administration, displacing inpatient amphotericin B requirements.
- WHO fungal priority pathogen designation:Elevated visibility within national essential medicines committees unlocks procurement funding and surveillance infrastructure in low-resource settings.
Industry Challenges
- Specialized mycology workforce scarcity:Clinical microbiology fellowship programs produce insufficient histoplasma-specific expertise to support expanded diagnostic testing ambitions.
- Long-duration oral therapy adherence:Six-to-twelve month itraconazole consolidation regimens suffer dropout rates that elevate relapse risk in disseminated disease.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Histoplasmosis Treatment Market |
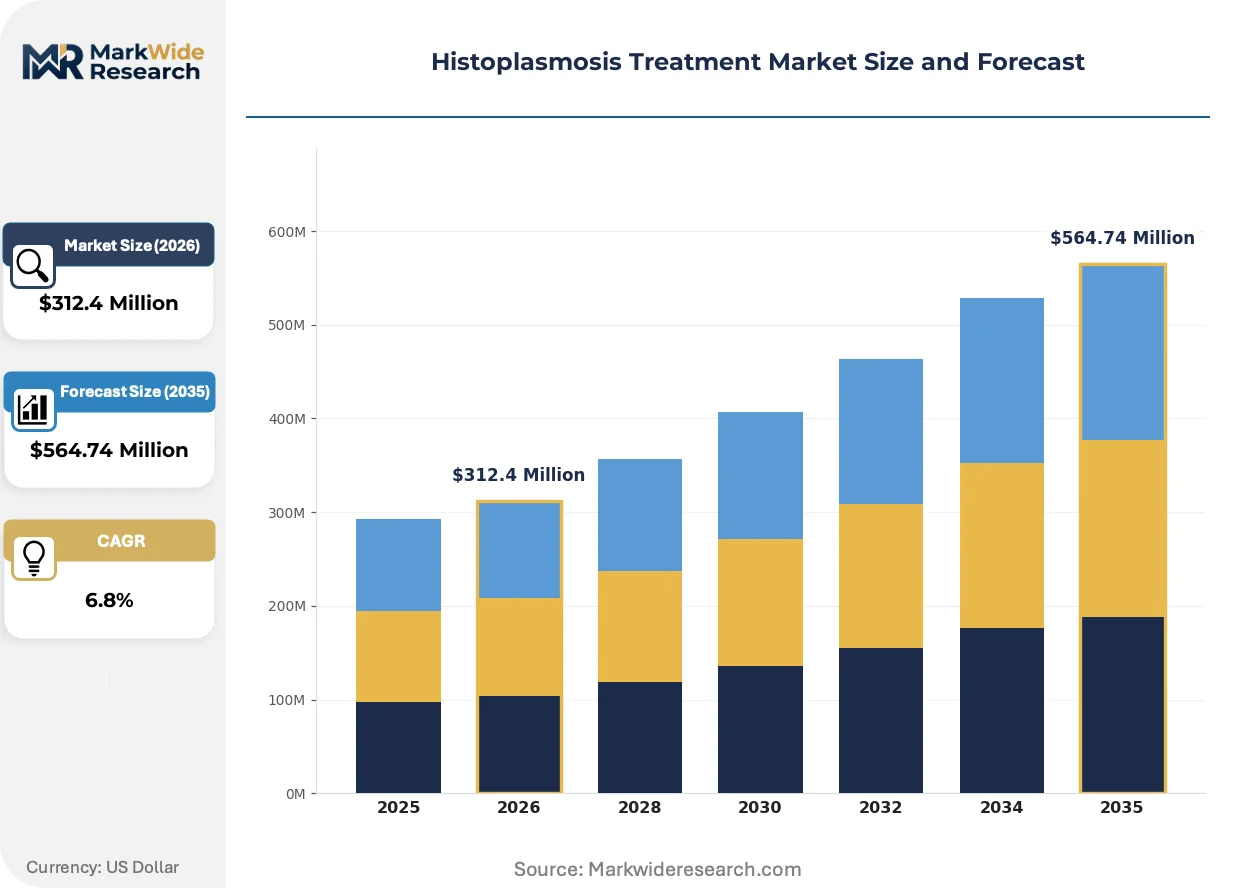
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifungal Agents, Combination Therapy, Oral Medications, Injectable Medications Delivery Mode: Intravenous, Oral, Inhalation, Topical End User: Hospitals, Clinics, Long-term Care Facilities, Home Healthcare Therapy Area: Respiratory Infections, Systemic Infections, Fungal Infections, Infectious Diseases |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Sanofi, Bristol Myers Squibb, Novartis AG, Gilead Sciences, Abbott Laboratories, Astellas Pharma US Inc., Johnson & Johnson Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Histoplasmosis Treatment Market Shifts & Advancements
Therapeutic protocols are fragmenting across severity strata and immune status, with technology and policy shifts simultaneously enabling precision dosing and constraining reimbursement pathways for extended oral regimens.
Therapeutic drug monitoring platforms are automating real-time itraconazole level assessment in transplant centers, enabling dose optimization that reduces breakthrough infection risk. Large academic medical centers in endemic regions deploy these systems most aggressively. The technology is automating what previously required send-out laboratory turnaround, compressing clinical decision cycles from days to hours.
EPA environmental remediation guidelines for bird and bat droppings are mandating abatement protocols in construction and spelunking tourism sectors across endemic counties. These rules elevate employer liability exposure and drive demand for personal protective equipment and prophylactic awareness programs. Commercial cave operators in Kentucky and Missouri report the most intensive compliance adaptation requirements.
Specialty pharmacy carve-outs are consolidating oral antifungal dispensing for immunocompromised outpatients, displacing traditional retail channels that lack prior authorization navigation capabilities. Payers favor these arrangements for their embedded adherence monitoring and clinical pharmacist consultation services. Medicare Advantage plans in the Ohio River valley show the most pronounced channel concentration effects.
Histoplasmosis Treatment Market Segmentation
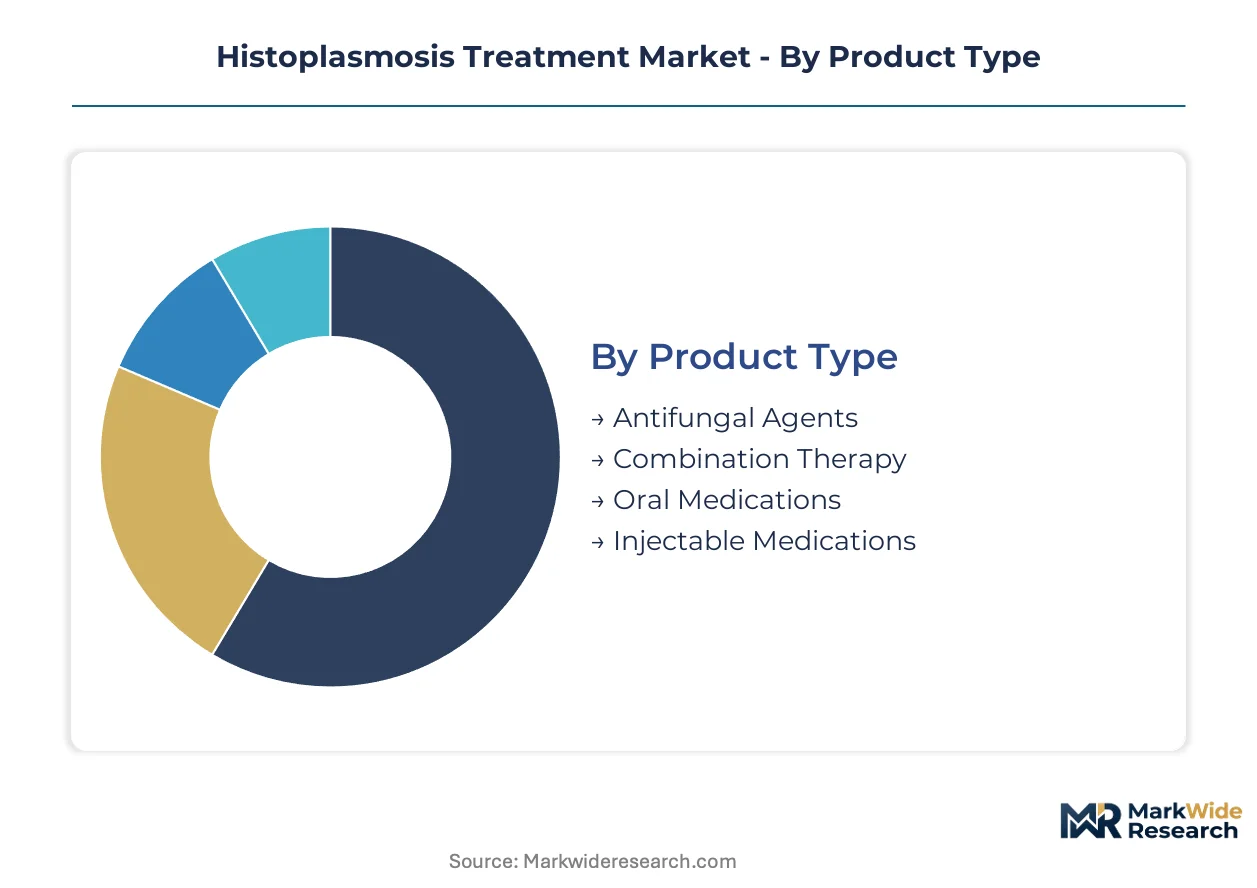
Histoplasmosis treatment protocols fragment across severity gradients and care settings, with product selection governed by immune status, organ involvement, and site of care migration. Segmentation reveals how formulation innovation and channel consolidation reshape procurement patterns across endemic regions.
Product Type:
Replacement cycles in antifungal therapy accelerate as resistance surveillance and nephrotoxicity concerns drive clinicians toward next-generation formulations with improved safety margins.
- Antifungal Agents:Polyene and azole compounds constitute the pharmacologic backbone, with amphotericin B lipid complexes and itraconazole commanding first-line protocols. Hospital pharmacies in the Ohio River valley concentrate procurement of these agents for immunocompromised admissions.
- Combination Therapy:Dual-agent regimens deploy where monotherapy resistance patterns complicate outcomes, particularly in disseminated disease with CNS involvement. Transplant centers in Missouri and Tennessee favor these protocols for breakthrough infection management.
- Oral Medications:Extended consolidation-phase dispensing dominates maintenance therapy, with specialty pharmacy channels capturing volume from traditional retail.
- Injectable Medications:Sterile formulation requirements limit qualified manufacturing sites, creating supply concentration vulnerability for critical-care induction protocols.
Oral medications sit at the top of the volume ranking, with combination therapy climbing the fastest.
Delivery Mode:
Cost tier differentiation separates inpatient infusion requirements from outpatient self-administration, with reimbursement pathways determining channel economics.
- Intravenous:Lipid complex formulations enable step-down facility administration, reducing nephrotoxicity profiles that previously mandated intensive monitoring. Infusion centers in Kentucky and Indiana report expanded amphotericin B capacity.
- Oral:Capsule and solution formulations sustain twelve-month maintenance regimens, though adherence monitoring requirements elevate specialty pharmacy penetration.
- Inhalation:Pulmonary delivery targets localized respiratory presentations, with limited uptake outside academic medical center protocols.
- Topical:Cutaneous manifestations in disseminated disease drive niche demand, concentrated at dermatology referral networks.
Oral delivery commands the volume base, while intravenous maintains premium positioning for acute presentations.
End User:
Customer type migration from inpatient wards to home-based care compresses hospital pharmacy margins while expanding retail and specialty channel procurement.
- Hospitals:Tertiary centers in endemic regions anchor diagnostic and induction-phase capacity, with antigen testing availability concentrating at referral institutions.
- Clinics:Urgent care and rural health facilities represent underpenetrated diagnostic access points where point-of-care testing deployment could expand treatment windows.
- Long-term Care Facilities:Immunocompromised residents in skilled nursing settings require prophylactic protocols, though antifungal interaction management complicates prescribing.
- Home Healthcare:Oral maintenance therapy and remote monitoring platforms enable discharge acceleration, with Medicare Advantage plans favoring embedded adherence services.
Hospitals retain the highest acuity concentration, with home healthcare gaining share fastest as site-of-care migration accelerates.
Therapy Area:
Application severity stratifies across pulmonary limitation versus multi-organ dissemination, with immune status determining protocol intensity and duration.
- Respiratory Infections:Acute pulmonary histoplasmosis in immunocompetent hosts typically resolves without antifungal intervention, limiting pharmaceutical penetration in this stratum.
- Systemic Infections:Disseminated disease with hepatic, splenic, or bone marrow involvement mandates extended induction and consolidation protocols, driving revenue concentration.
- Fungal Infections:Broad categorization captures histoplasmosis within differential diagnoses that require antigen or culture confirmation before targeted therapy initiation.
- Infectious Diseases:Academic infectious disease consultation services guide complex case management, particularly in HIV and transplant populations.
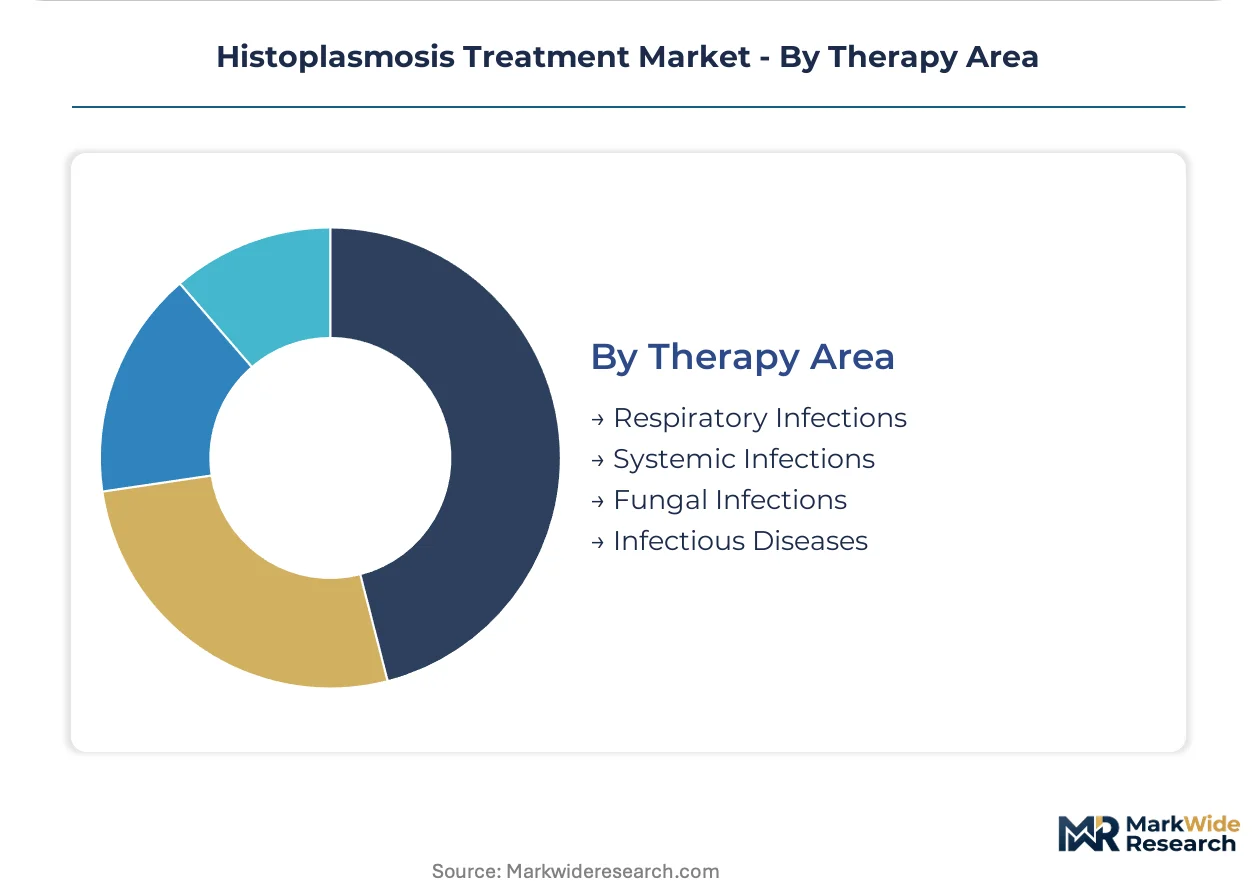
Systemic infections anchor the value pool, with respiratory presentations showing the shallowest pharmaceutical penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Histoplasmosis treatment infrastructure first consolidated in the United States during the mid-20th century as endemic disease recognition drove antifungal development. The Ohio and Mississippi River valleys established the clinical and commercial foundation for therapeutic protocols now migrating toward outpatient delivery models.
United States
FDA orphan drug incentives and priority review vouchers accelerate novel antifungal development timelines for immunocompromised populations. The EPA mandates environmental remediation protocols for bird and bat droppings across endemic counties. Cincinnati and St. Louis anchor diagnostic capacity and hospital pharmacy procurement networks serving the Ohio River valley.
Brazil
ANVISA regulatory pathways for antifungal registration support expanded access programs in HIV-endemic regions. The Ministry of Health integrates histoplasmosis into national AIDS management guidelines. São Paulo and Rio de Janeiro concentrate tertiary referral capacity and transplant center demand for prophylactic protocols.
Mexico
COFEPRIS expedited review mechanisms address antifungal supply security for disseminated disease presentations. National health institutes prioritize endemic mycosis surveillance in southern states with cave tourism exposure. Mexico City anchors infectious disease consultation networks managing complex case referrals.
Canada
Health Canada streamlined access programs for lipid complex formulations reduce nephrotoxicity in induction-phase therapy. Provincial formularies negotiate reimbursement for extended oral maintenance regimens. Ontario and Quebec concentrate academic medical center capacity and specialty pharmacy distribution networks.
Argentina
ANMAT registration requirements for antifungal agents align with MERCOSUR harmonization efforts. National infectious disease programs target underdetection through expanded antigen testing availability. Buenos Aires anchors diagnostic reference laboratory capacity and clinical trial site infrastructure.
Histoplasmosis Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and sterile manufacturing capability. The market structures around three tiers: multinational pharmaceutical conglomerates with integrated antifungal portfolios, specialty biopharmaceutical firms with lipid delivery technologies, and generic manufacturers supplying oral azole maintenance therapy. Consolidation pressures concentrate manufacturing capacity for amphotericin B sterile formulations while oral generic competition compresses pricing for itraconazole consolidation regimens. Strategic moves center on therapeutic drug monitoring platform partnerships and specialty pharmacy channel carve-outs.
Within the multinational tier, Pfizer Inc. and Merck & Co., Inc. occupy positions defined by manufacturing scale and sustained R&D investment. Gilead Sciences exemplifies the specialty biopharmaceutical archetype through differentiated delivery technology positioning. These three anchors represent distinct competitive vectors: scale-driven supply security, pipeline depth in azole chemistry, and formulation innovation reducing toxicity profiles.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Sanofi |
| Bristol Myers Squibb |
| Novartis AG |
| Gilead Sciences |
| Abbott Laboratories |
| Astellas Pharma US Inc. |
| Johnson & Johnson Ltd. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialty pharmacy networks now control oral antifungal dispensing across the Ohio River valley, compressing generic itraconazole pricing while extracting service fees from payers that offset margin erosion in pure product distribution.
Pricing Analysis
Three-tier pricing structure across premium lipid complex formulations, standard generic azoles, and economy blister-pack maintenance regimens governs procurement decisions in hospital and retail channels. Price differentiation rests on nephrotoxicity profiles and therapeutic drug monitoring requirements, with transplant centers absorbing premium positioning for safety-critical induction therapy. Cost compression in oral maintenance tiers intensifies because Medicare Advantage plans drive channel consolidation toward specialty pharmacies with embedded adherence services. Community health centers exhibit the highest price sensitivity, while academic medical centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Regional distribution centers in Kentucky, Indiana, and Missouri anchor hub-and-spoke patterns serving endemic counties with bird and bat exposure risk. Manufacturing of amphotericin B lipid complexes concentrates in the United States, Ireland, and Puerto Rico, with sterile formulation requirements limiting qualified sites. Raw material dependencies span phospholipid excipients from Germany, polyene fermentation feedstocks from domestic corn-processing streams, and specialized packaging films from Japan. Single-source vulnerability for sterile injectable capacity creates exposure to FDA facility inspection delays. Distribution runs through specialty pharmacy carve-outs for oral maintenance, bypassing traditional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in histoplasmosis treatment hinges on site-of-care migration toward outpatient oral therapy, where adherence monitoring services capture value beyond commodity drug pricing.
For Market Incumbents: Deploy therapeutic drug monitoring platform partnerships to lock in transplant center loyalty against generic azole commoditization. Secure lipid complex manufacturing capacity through long-term sterile production agreements that preempt competitor facility qualification. Consolidate specialty pharmacy relationships in the Ohio River valley to defend against Amazon-PillPack disruption in oral maintenance dispensing. For New Entrants and Emerging Players: Specialty pharmacy benefit managers represent the most penetrable channel partners for point-of-care antigen testing deployment in urgent care networks. Target rural health clinics in Kentucky and Tennessee where diagnostic underdetection delays treatment initiation and expands addressable windows. Pursue FDA orphan drug designation pathways to accelerate novel antifungal timelines and capture priority review voucher value. For Investors and Strategic Acquirers: Valuations sit cheapest among generic oral azole manufacturers facing reimbursement compression, while lipid delivery technology specialists command scarcity premiums. Long-term viability favors platforms with integrated diagnostic-therapeutic positioning across endemic regions. Watch WHO fungal priority pathogen funding commitments as the signal indicating procurement infrastructure buildout in Brazil and Mexico.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA priority review vouchers accelerate novel antifungal timelines for immunocompromised populations. |
| Specialty Pharmacy Carve-Out | Medicare Advantage plans in the Ohio River valley favor embedded adherence monitoring services. |
| Lipid Complex Manufacturing Scale-Up | Reduced nephrotoxicity profiles enable outpatient infusion center displacement of inpatient requirements. |
| Point-of-Care Diagnostic Partnership | Lateral flow immunoassay deployment in urgent care compresses time-to-treatment in endemic counties. |
| Environmental Remediation Service Line | EPA-mandated bird and bat dropping abatement protocols elevate employer liability exposure and PPE demand. |
Research Methodology
Coverage spans the United States, Brazil, Mexico, Canada, and Argentina, with primary inputs from each market's transplant center pharmacy directors, infectious disease specialists, specialty pharmacy procurement managers, and ANVISA regulatory affairs leads. Secondary validation draws from FDA orphan drug designation filings, EPA environmental remediation guidelines, WHO fungal priority pathogen lists, and hospital formulary databases. Bottom-up patient-volume modeling triangulates against top-down pharmaceutical expenditure tracking across endemic regions.
Rate-of-change decomposition separates volume expansion in immunocompromised populations from value migration toward premium formulations over the projection horizon. Segmentation dimensions include treatment phase, delivery mode, end-user site of care, and regional regulatory cluster. CAGRs derive from elasticity-adjusted pricing trajectories and patient flow modeling through induction and consolidation protocols. Forecast inputs incorporate transplant volume projections and biologic therapy penetration in oncology and rheumatology.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to antifungal resistance surveillance patterns and Medicare reimbursement pathway revisions for extended oral therapy. Outputs reflect documented assumptions around site-of-care migration velocity and specialty pharmacy channel concentration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Mesenteric Penniculitis Treatment Market
Medical Treatment
Molluscum Contagiosum (MC) Treatment Market
Medical Treatment
Spinal Cord Compression Market
Medical Treatment
Intensity Modulated Radiation Therapy Market
Medical Treatment
Tinea Pedis Treatment Market
Medical Treatment
Scalp Care Treatment Market
Medical Treatment
Systemic Sclerosis Treatment Market
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Hemorrhagic Shock Treatment Market
Medical Treatment
Radiation Therapy Market
Medical Treatment
Endovenous Laser Therapy Market
Medical Treatment
Single-Dose Therapy Market
Medical Treatment
Amyloidosis Treatment Market
Medical Treatment
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market