
 Artificial Intelligence in Telecommunication Market | 2026-2036
Artificial Intelligence in Telecommunication Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in Telecommunication Market Intelligence
Enterprise IoT connectivity is broadening the addressable base for AI-driven telecom solutions beyond traditional consumer mobile services. IBM Corporation leverages its Watson platform to anchor network automation contracts with tier-one operators globally. NVIDIA Corporation dominates AI training infrastructure supply for telecom edge deployments, while Huawei Technologies Co. Ltd. competes on integrated 5G-AI base station portfolios across Asian and Middle Eastern markets.
Artificial intelligence in telecommunication encompasses machine learning algorithms, neural network architectures, and natural language processing systems deployed to automate network operations, optimize radio frequency allocation, and enable predictive fault resolution in distributed infrastructure. Cloud-based deployment is capturing the fastest expansion as operators migrate away from capital-intensive on-premise hardware toward elastic compute models. Machine learning applications in network optimization currently occupy the deepest margin pools, though computer vision for tower and fiber inspection is registering the steepest adoption curve among emerging use cases.
The Federal Communications Commission shapes AI telecom deployment through spectrum auction rules and network reliability mandates, while the European Telecommunications Standards Institute and ETSI's industry specification group on experiential networked intelligence define cross-border interoperability frameworks for automated network management. China's Ministry of Industry and Information Technology governs AI-integrated telecom equipment certification through GB standards and dual carbon compliance requirements. Stakeholders must monitor whether divergent national AI governance regimes fragment vendor certification pathways or consolidate around shared technical benchmarks.
Market Dynamics
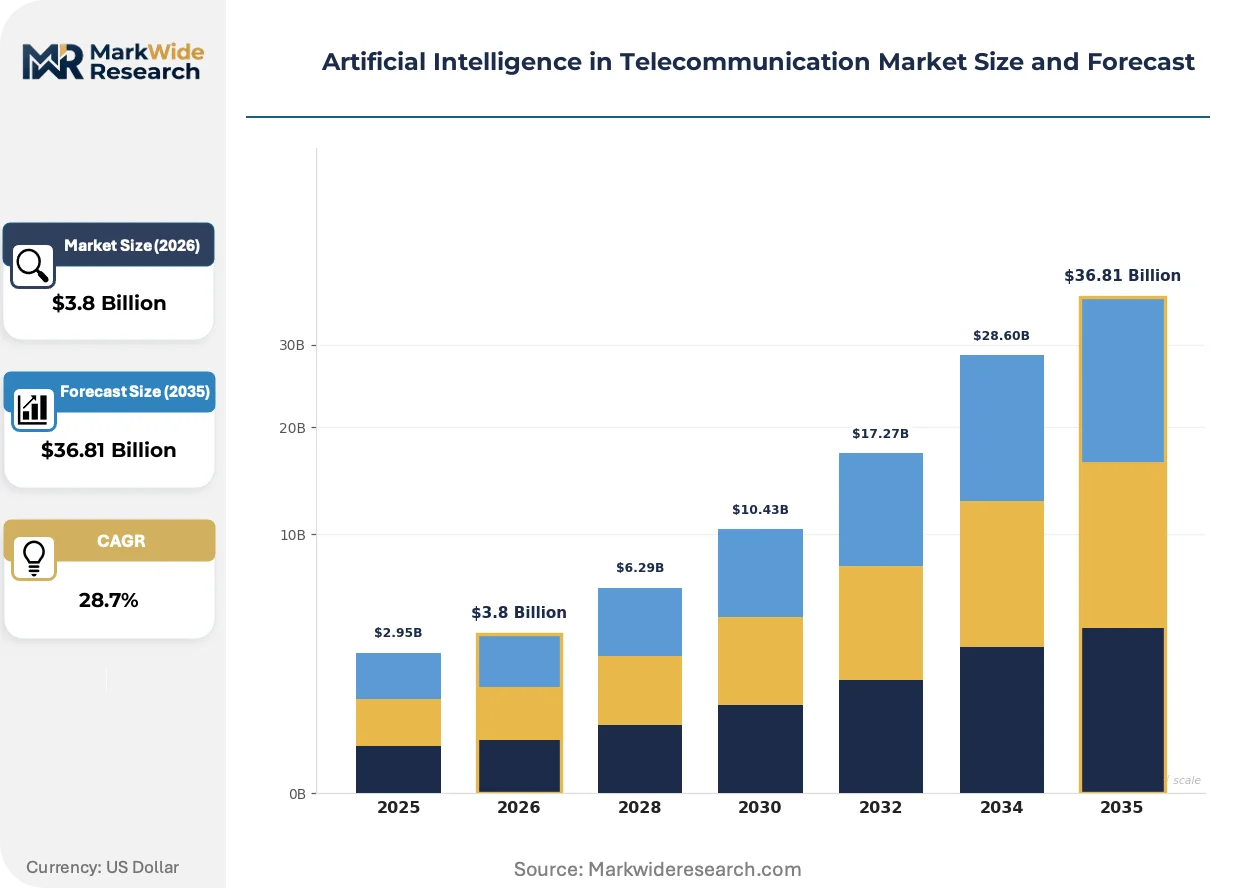
Network operators are dismantling legacy command-and-control architectures in favor of autonomous systems that self-optimize radio frequency allocation and predict equipment failures before service degradation occurs. This infrastructure transformation is compressing procurement cycles and forcing vendor consolidation across the telecom stack.
Growth Catalysts
- 5G Standalone Core Deployment:Mobile operators in Germany, China, and the United States are mandating AI-native network functions to manage massive machine-type communications and ultra-reliable low-latency traffic patterns.
- FCC Network Reliability Mandates:The Federal Communications Commission requires predictive outage management systems, accelerating operator investment in machine learning-based fault detection across distributed cell sites.
- Enterprise IoT Connectivity Expansion:Manufacturing, logistics, and energy utilities are procuring private 5G networks with embedded AI optimization, broadening the addressable base beyond consumer mobile services.
Market Restraints
- GPU Supply Concentration:AI training and inference hardware for telecom edge deployments depends on a concentrated semiconductor supply base, creating vulnerability to export control disruptions and foundry allocation constraints.
- Interoperability Fragmentation:Divergent national AI governance regimes across the United States, European Union, and China are fragmenting vendor certification pathways and delaying multi-country rollouts.
- Legacy Billing System Integration:Operator investments in AI-driven customer experience platforms face structural friction from decades-old charging and policy control infrastructure that resists API-based modernization.
Strategic Opportunities
- EU AI Act Compliance Services:The European Union's risk-based AI regulation creates demand for audit-ready network automation platforms, favoring vendors with embedded transparency and explainability features.
- India Digital Infrastructure Push:The country's production-linked incentive scheme for telecom equipment manufacturing is attracting AI-integrated base station assembly, creating localized supply opportunities.
- Digital Twin Network Convergence:The intersection of physics-based simulation with real-time telemetry is enabling predictive capacity planning that compresses capital deployment timelines for fiber and tower expansion.
Industry Challenges
- Multimodal Data Engineering Talent Scarcity:Operators struggle to recruit engineers capable of integrating radio frequency telemetry, customer behavior signals, and infrastructure performance metrics into unified machine learning pipelines.
- Edge-to-Cloud Orchestration Complexity:Managing distributed AI inference workloads across central data centers, regional edge nodes, and on-device execution requires new organizational capabilities that most operators lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in Telecommunication Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.81 Billion |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Neural Networks, Computer Vision Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: Telecom Operators, Enterprises, Regulatory Authorities, Service Providers Application: Network Optimization, Customer Experience, Predictive Maintenance, Fraud Detection |
| Companies Covered | IBM Corporation, Microsoft, Google LLC, Intel Corporation, Cisco Systems, Inc., AT&T, NVIDIA Corporation, Infosys Limited, Huawei Technologies Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in Telecommunication Market Strategic Shifts & Innovations
Foundation models trained on network telemetry are compressing the time required to identify root causes of service degradation from hours to minutes. This capability shift is forcing reorganization of network operations centers and redefinition of vendor service level agreements.
Radio intelligent controllers are converging with transformer-based neural architectures to enable zero-touch optimization of beamforming patterns in massive MIMO arrays. Tier-one operators in South Korea and Japan are deploying these systems in dense urban microcells where manual parameter tuning proved unsustainable. The technology is converging with open radio access network standards to displace proprietary optimization tools locked to single-vendor hardware stacks.
The European Telecommunications Standards Institute's experiential networked intelligence framework is mandating interoperable interfaces for automated network management across member states. Equipment vendors must now certify AI-driven functions against common benchmarks before deployment in cross-border infrastructure. German and French operators are responding by consolidating procurement specifications around ETSI-aligned requirements, compressing vendor qualification timelines for compliant suppliers.
Enterprise buyers are unbundling network management services from connectivity contracts, procuring AI-driven optimization as standalone software subscriptions rather than embedded features. This procurement pattern is disrupting traditional equipment vendor business models that relied on hardware-software bundling. The shift is most visible in United States manufacturing verticals where private cellular deployments require specialized quality-of-service guarantees that generic operator offerings cannot satisfy.
Artificial Intelligence in Telecommunication Market Segmentation
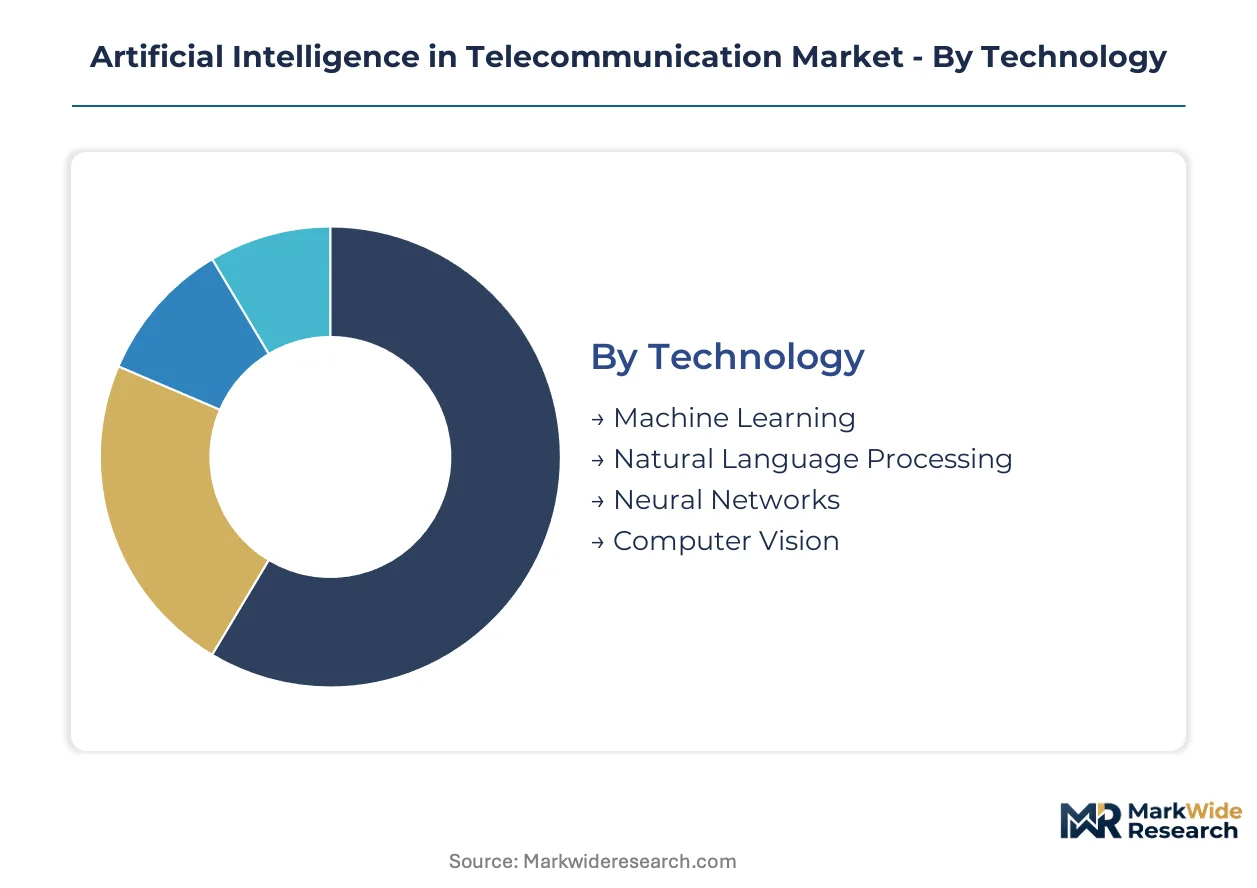
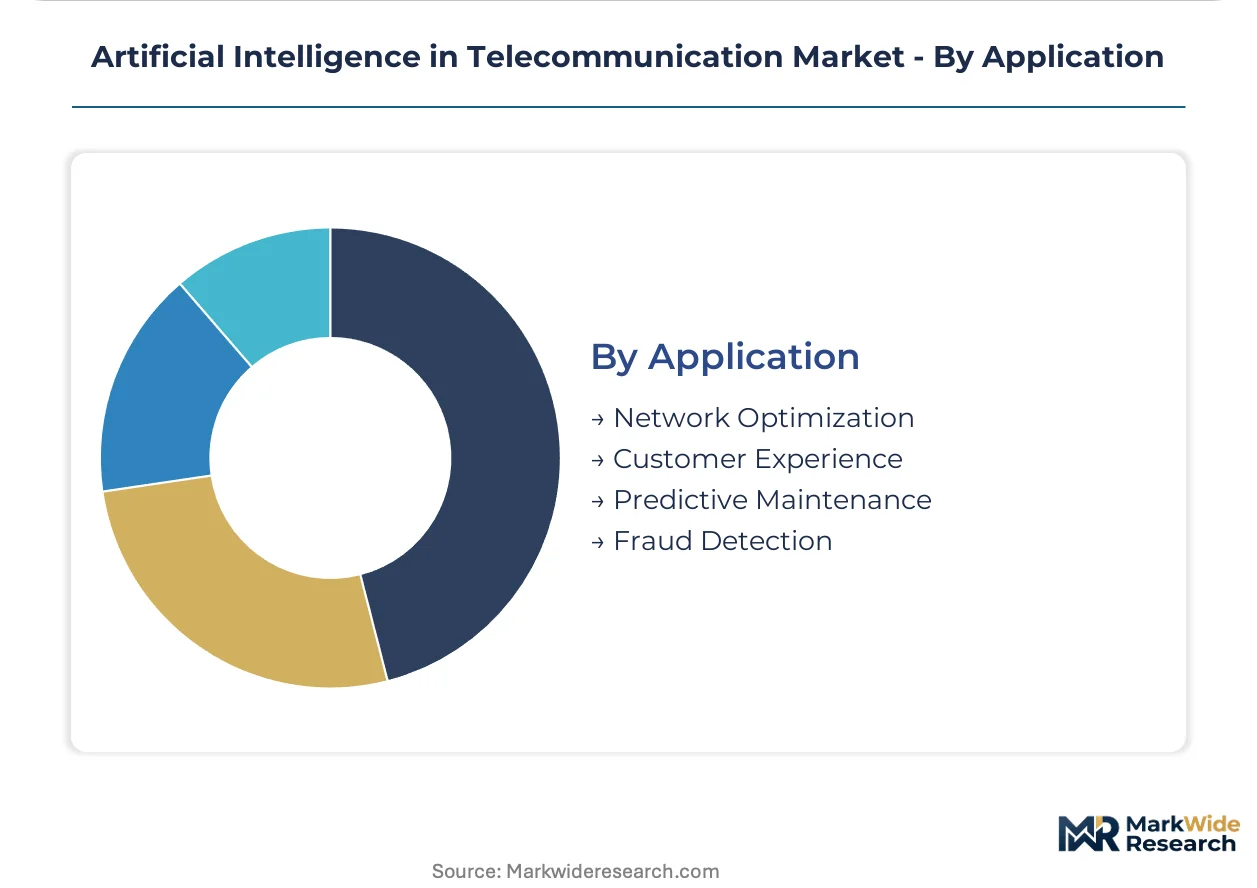
Segmentation reveals how AI investment priorities diverge across infrastructure layers and operational domains. Upgrade cycles in core network functions, edge deployment models, and customer-facing systems create distinct procurement rhythms and vendor competitive dynamics.
Technology:
Replacement cycles in AI telecom infrastructure vary dramatically by algorithmic maturity and computational requirements, with newer architectures displacing rule-based systems in high-frequency decision environments.
- Machine Learning:Statistical learning algorithms process network telemetry for traffic forecasting and anomaly detection. German operators deploy gradient-boosted models for radio access network load balancing, driven by FCC reliability mandates requiring predictive capacity management.
- Natural Language Processing:Transformer-based systems power conversational interfaces for subscriber support and network operations center automation. China Mobile integrates NLP chatbots across provincial customer service centers, responding to MIIT digital transformation targets for state-owned carriers.
- Neural Networks:Deep learning architectures enable complex pattern recognition in signal processing applications.
- Computer Vision:Convolutional networks automate visual inspection of cell towers, fiber routes, and data center infrastructure.
Machine Learning sits at the top of the volume ranking, with Computer Vision climbing the fastest as tower inspection automation expands across Asian markets.
Deployment:
Cost tier differentiation separates capital-intensive on-premise installations from elastic cloud consumption models, with hybrid architectures capturing mid-budget operators seeking staged migration paths.
- Cloud-Based:Elastic compute platforms eliminate hardware procurement cycles and enable rapid scaling of AI inference workloads. Verizon and AT&T migrated customer analytics platforms to AWS and Azure infrastructure, reducing time-to-deployment for personalization algorithms from quarters to weeks.
- Edge Computing:Distributed inference nodes process ultra-low-latency applications at radio access network boundaries. SK Telecom deploys NVIDIA GPU clusters at 5G base stations across Seoul metropolitan zones, supporting autonomous vehicle connectivity and industrial AR use cases.
- On-Premise:Dedicated hardware installations serve security-sensitive core network functions and sovereign data requirements.
- Hybrid:Split architectures route training workloads to cloud and inference to edge or on-premise based on latency sensitivity.
Cloud-Based deployment leads volume penetration, while Edge Computing expands most quickly as 5G standalone core rollouts accelerate.
End User:
Customer type segmentation exposes divergent procurement authority and technical sophistication, with enterprises increasingly bypassing operator intermediaries for direct AI platform acquisition.
- Telecom Operators:Tier-one carriers procure comprehensive AI stacks spanning network automation and customer experience domains. Deutsche Telekom consolidated vendor relationships around IBM Watson and proprietary German AI startups, centralizing procurement under a single chief data officer function.
- Enterprises:Manufacturing, logistics, and energy verticals acquire private 5G networks with embedded AI optimization. BMW's Leipzig plant deployed Ericsson AI-driven quality-of-service management for robotic assembly coordination, bypassing public network dependency.
- Service Providers:Systems integrators and managed service vendors package AI capabilities for mid-tier operators lacking in-house data science teams.
- Regulatory Authorities:Government agencies deploy AI for spectrum monitoring, interference detection, and compliance enforcement.
Telecom Operators dominate procurement volume, with Enterprises gaining share fastest as private cellular deployments proliferate.
Application:
Margin concentration varies by application maturity, with network optimization commanding premium pricing while fraud detection faces commoditization from standardized algorithmic approaches.
- Network Optimization:Real-time radio frequency allocation and traffic engineering deliver measurable capacity gains and energy savings. NTT Docomo's AI-powered massive MIMO beamforming reduced base station power consumption across Tokyo dense urban clusters, aligning with Japan METI carbon reduction directives for telecommunications infrastructure.
- Predictive Maintenance:Equipment failure forecasting minimizes truck rolls and service interruptions. China Tower Corporation deployed vibration analysis and thermal imaging AI across Guangdong province cell sites, cutting unplanned outages before MIIT reliability reporting requirements took effect.
- Customer Experience:Personalization engines and churn prediction models target subscriber retention and revenue optimization.
- Fraud Detection:Anomaly identification in signaling networks and billing systems protects revenue integrity.
Network Optimization commands the highest deployment volume, with Predictive Maintenance showing the steepest expansion trajectory as operator reliability mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping AI telecom deployment patterns, with vendors migrating certification efforts toward jurisdictions offering clearer compliance pathways. Cost-of-compliance gaps between the FCC's reliability mandates and China's MIIT certification regimes are concentrating R&D investment in markets with predictable approval timelines.
United States
Verizon and AT&T are driving cloud-based AI migration for customer analytics platforms, reducing deployment cycles from quarters to weeks. The FCC's network reliability mandates require predictive outage management systems, accelerating machine learning-based fault detection investment across distributed cell sites. Seattle and San Francisco anchor the western AI infrastructure cluster, where NVIDIA GPU clusters support 5G edge inference workloads for autonomous vehicle connectivity.
Germany
Deutsche Telekom consolidated vendor relationships around IBM Watson and domestic AI startups, centralizing procurement under a single chief data officer function. ETSI's experiential networked intelligence framework mandates interoperable interfaces for automated network management, compressing vendor qualification timelines for compliant suppliers. The Ruhr industrial corridor hosts private 5G deployments with embedded AI optimization for manufacturing robotics, bypassing public network dependency.
China
China Mobile integrates NLP chatbots across provincial customer service centers, responding to MIIT digital transformation targets for state-owned carriers. GB standards and dual carbon compliance requirements govern AI-integrated telecom equipment certification, shaping vendor product roadmaps. Guangdong province anchors the southern deployment cluster, where China Tower Corporation deployed vibration analysis and thermal imaging AI across cell sites to meet reliability reporting requirements.
Japan
NTT Docomo's AI-powered massive MIMO beamforming reduced base station power consumption across Tokyo dense urban clusters, aligning with METI carbon reduction directives for telecommunications infrastructure. Radio intelligent controllers converging with transformer-based neural architectures enable zero-touch optimization in massive MIMO arrays. Osaka and Nagoya form the central Japan cluster, where tier-one operators deploy autonomous systems in dense urban microcells where manual parameter tuning proved unsustainable.
South Korea
SK Telecom deploys NVIDIA GPU clusters at 5G base stations across Seoul metropolitan zones, supporting autonomous vehicle connectivity and industrial AR use cases. The country's production-linked incentive schemes for telecom equipment manufacturing attract AI-integrated base station assembly, creating localized supply opportunities. Busan-Ulsan anchors the southeastern cluster, where edge computing nodes process ultra-low-latency applications at radio access network boundaries for manufacturing verticals.
Artificial Intelligence in Telecommunication Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with cloud-native AI platforms capturing premium positioning against hardware-integrated incumbents. The vendor base organizes around three tiers: hyperscale cloud providers with elastic compute platforms, semiconductor specialists dominating training infrastructure supply, and systems integrators packaging capabilities for mid-tier operators. Consolidation pressures are forcing M&A activity between network automation software vendors and legacy equipment manufacturers, while strategic partnerships between GPU suppliers and telecom operators reshape procurement specifications for edge deployments.
Within the hyperscale cloud tier, IBM Corporation and Microsoft exemplify platform-centric positioning, anchoring network automation contracts through Watson and Azure AI services respectively. NVIDIA Corporation occupies a distinct position at the semiconductor-specialist pole, supplying GPU clusters for distributed inference workloads. These three companies represent the dominant competitive archetypes: platform integrators leveraging existing enterprise relationships, and infrastructure suppliers capturing value at the compute layer as operators migrate from capital-intensive hardware toward elastic consumption models.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft |
| Google LLC |
| Intel Corporation |
| Cisco Systems, Inc. |
| AT&T |
| NVIDIA Corporation |
| Infosys Limited |
| Huawei Technologies Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Operator procurement consolidation around AI-native network functions is compressing vendor margins and forcing semiconductor suppliers to reconfigure foundry allocation toward telecom-specific GPU variants. This demand-side concentration grants tier-one carriers substantial pricing leverage in multi-year framework agreements.
Pricing Analysis
Distributor margins in AI telecom infrastructure sit at 12-18% for hardware-integrated solutions versus 25-35% for cloud-native software subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates hyperscale platform integrators from regional systems integrators and commodity hardware assemblers. Pricing pressure stems from GPU supply concentration and foundry allocation constraints that limit vendor bargaining power. Mid-tier operators exhibit highest price sensitivity due to capital expenditure limitations, while tier-one carriers with sovereign data mandates accept premium pricing for on-premise deployments.
Supply Chain Analysis
India's production-linked incentive scheme for telecom equipment manufacturing is reshaping sourcing patterns for AI-integrated base station assembly, drawing component suppliers toward localized production. GPU clusters and specialized AI accelerators feed from Taiwan, South Korea, and the United States, with advanced packaging capacity concentrated in Southeast Asian facilities. Single-source vulnerability in EUV lithography equipment creates structural risk for inference hardware availability. Distribution runs through direct OEM relationships for tier-one operators and systems integrator channels for mid-tier carriers lacking procurement scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through cloud-based deployment migration, where elastic consumption models replace capital-intensive hardware procurement and compress customer acquisition costs.
For Market Incumbents: Extend platform integration capabilities to capture enterprise private 5G deployments, where AI optimization is unbundling from connectivity contracts. Consolidate vendor relationships around explainable AI frameworks to preempt EU AI Act compliance disruption. Invest in edge-to-cloud orchestration tooling to defend against hyperscaler encroachment into network automation stacks. For New Entrants and Emerging Players: Begin with computer vision applications for tower and fiber inspection, where algorithmic commodification has not yet eroded pricing power. Target manufacturing verticals in Germany and Japan pursuing private cellular deployments with specialized quality-of-service requirements. Position through channel partnerships with systems integrators serving mid-tier operators lacking in-house AI engineering capacity. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native AI platforms possessing embedded transparency features for regulatory compliance. Long-term viability favors vendors with demonstrated interoperability across open radio access network standards. Monitor ETSI certification timelines as inflection indicator for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | IBM Watson and Azure AI anchor multi-year network automation contracts with tier-one operators. |
| Edge Infrastructure Deployment | NVIDIA GPU clusters at 5G base stations support ultra-low-latency inference for autonomous vehicle connectivity. |
| Regulatory Compliance Certification | ETSI-aligned AI functions compress vendor qualification timelines for cross-border European deployments. |
| Strategic Partnership | Systems integrators package AI capabilities for mid-tier operators lacking data science teams. |
| Geographic Expansion | India's PLI scheme attracts AI-integrated base station assembly for localized supply opportunities. |
Research Approach
Multiple input streams — executive interviews with network operations leaders, procurement discussions with tier-one carrier CTOs, and validation sessions with AI infrastructure vendors — were reconciled against regulatory filings from the FCC, ETSI documentation, and MIIT certification records. Primary fieldwork encompassed conversations with cloud platform engineers, systems integrator technical directors, and semiconductor supply chain specialists. Secondary sources included hyperscaler capex disclosures, SEC 10-K filings from listed telecom equipment vendors, and ETSI industry specification group publications. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Historical deployment trajectories were cross-referenced against expert panel inputs regarding 5G standalone core rollout timelines and edge computing adoption curves. Segmentation modeling spanned technology type, deployment architecture, end-user category, and application domain across the projection horizon. CAGRs were derived from fitted growth curves anchored to disclosed operator AI investment commitments and infrastructure deployment schedules. Industry-specific inputs incorporated spectrum auction timelines, reliability mandate effective dates, and carbon compliance requirement phase-ins.
Several conditions sit outside the modeled scope, including potential export control expansion affecting GPU supply, divergent national AI governance regime fragmentation, and unforeseen legacy billing system integration failures. Forecasts reflect documented assumptions regarding operator migration timelines and vendor certification pathway convergence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI Task Manager App Market
Artificial Intelligence (AI)
Automotive Predictive Diagnostic System Market
Artificial Intelligence (AI)
AI Document Generator Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations (Aiops) Market
Artificial Intelligence (AI)
Underwater Autonomous Data Processor Market
Artificial Intelligence (AI)
Image Recognition Market
Artificial Intelligence (AI)
No-Code AI Platform Market
Artificial Intelligence (AI)
Artificial Intelligence in Big Data Analysis Market
Artificial Intelligence (AI)
AI Watermarking Market
Artificial Intelligence (AI)
Autonomous AI and Autonomous Agents Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Assisted Robots Market
Artificial Intelligence (AI)
North America and Europe Chatbot Market
Artificial Intelligence (AI)
Smart Home Digital Assistant [Voice] Market
Artificial Intelligence (AI)
AI in Project Management Market
Artificial Intelligence (AI)
Machine Learning in Pharmaceutical Industry Market
Artificial Intelligence (AI)
Embedded Intelligence Market