
 North America and Europe Chatbot Market | 2026-2036
North America and Europe Chatbot Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Chatbot Market Analytics
CE marking under the EU AI Act's risk-based classification is collapsing the window for uncertified chatbot deployments in European healthcare and financial services. Microsoft Corporation leverages its Azure AI infrastructure to sustain enterprise-grade compliance pipelines across both regions. Zendesk, Inc. anchors mid-market customer support with pre-built CRM integrations that reduce deployment friction. IBM Corporation differentiates through Watson's natural language understanding specialization in regulated industries.
A chatbot is a software application that simulates human conversation through rule-based scripting, natural language processing, or large language model architectures, typically operating via text or voice interfaces with response latency thresholds under two seconds for real-time engagement. The primary commercial purpose is automating customer interaction workflows while reducing live agent dependency in high-volume service environments. AI-powered product types are capturing disproportionate R&D investment as enterprises demand contextual reasoning beyond scripted decision trees. Cloud-based deployment models dominate new installations, though on-premises configurations persist in German banking and French healthcare where data residency requirements override cost considerations. Customer Support functionality generates the largest revenue pool, yet Sales Assistance is expanding fastest as conversational commerce matures in North American retail.
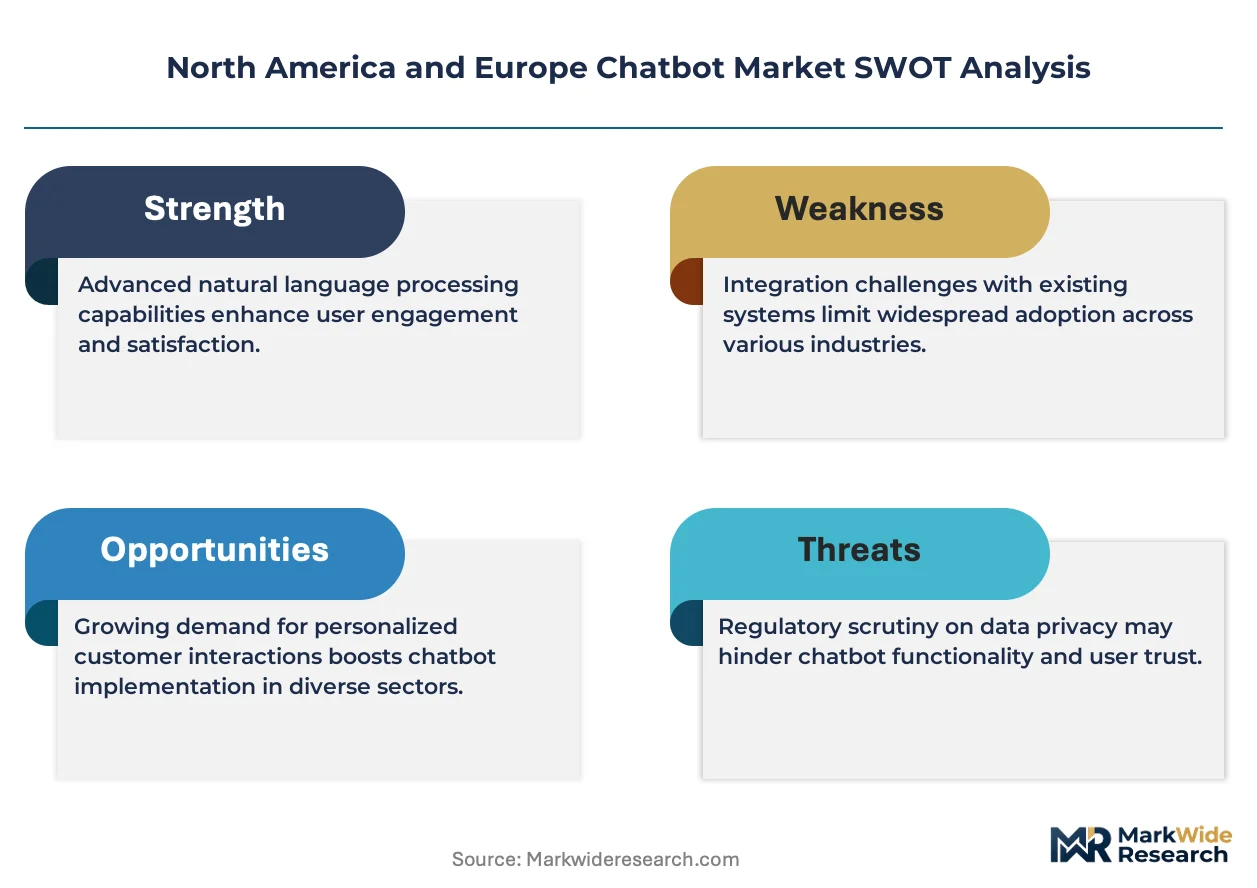
The EU AI Act and GDPR jointly constrain training data sourcing and automated profiling capabilities, while the FDA in the United States scrutinizes clinical decision-support chatbots as potential medical devices. These frameworks elevate compliance costs but also create structural barriers that favor established vendors with dedicated regulatory affairs teams. Stakeholders must monitor divergence between Brussels and Washington on algorithmic transparency mandates, as incompatible disclosure requirements could fragment product architectures and inflate localization expenses.
Market Dynamics
Large language model architectures are collapsing the cost of contextual reasoning across customer service workflows, forcing incumbent vendors to retrain or discard legacy rule-based engines that dominated the 2015-2022 installation wave.
Growth Catalysts
- EU AI Act compliance mandates:Risk classification protocols for high-stakes automated decision-making are compelling financial institutions to upgrade from legacy IVR to certified natural language processing platforms.
- German banking modernization:Customer authentication and payment query automation budgets are redirecting from voice menus to conversational AI with sub-two-second latency requirements.
- Cloud infrastructure maturation:Elastic compute provisioning is eliminating on-premises deployment cost barriers that previously constrained mid-market contact center adoption.
Market Restraints
- Training data sourcing constraints:GDPR Article 9 restrictions on processing special category personal data are fragmenting model development pipelines and inflating data acquisition costs.
- CE marking timeline compression:The EU AI Act's 2026 enforcement window for high-risk system certification is creating bottlenecks at notified bodies with limited AI-specific assessment capacity.
- Legacy system integration friction:French healthcare and German banking data residency requirements perpetuate on-premises configurations that forfeit cloud-native scalability advantages.
Strategic Opportunities
- Netherlands contact center modernization:Shifting budgets from legacy IVR to natural language processing platforms create first-mover advantages for vendors with pre-built Dutch language models.
- Conversational commerce in North American retail:Sales Assistance functionality is outpacing Customer Support as the fastest-expanding revenue pool as transactional chatbots mature.
- Hybrid deployment architectures:Edge-cloud partitioning enables compliance with French healthcare data residency rules while preserving inference cost economics.
Industry Challenges
- Regulatory affairs talent scarcity:Vendors struggle to hire specialists capable of navigating simultaneous EU AI Act risk classification and FDA clinical decision-support scrutiny.
- Algorithmic transparency documentation:Divergent Brussels and Washington disclosure mandates threaten to fragment product architectures and duplicate localization engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Chatbot Market |
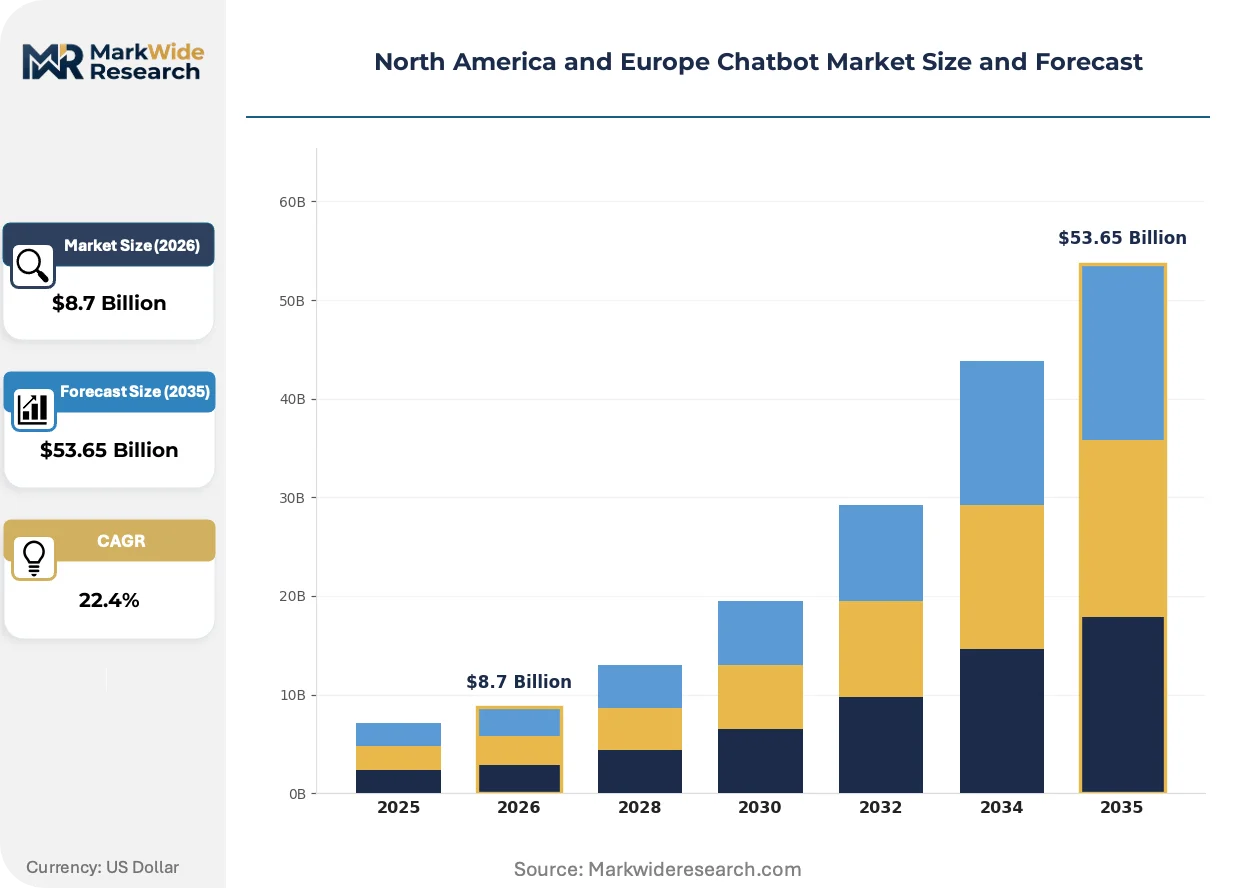
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Text-based, Voice-based, Hybrid, AI-powered Deployment Model: On-premises, Cloud-based, SaaS, Managed End User: Retail, Banking, Healthcare, Travel Functionality: Customer Support, Sales Assistance, Feedback Collection, Personalization |
| Companies Covered | Zendesk, Inc., Intercom, Microsoft Corporation, Pandorabots, Nuance Communications Inc., IBM Corporation, LivePerson, Inc., Cognigy, Google LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Chatbot Market Evolving Landscape
Transformer-based architectures are rewriting competitive economics by collapsing the engineering hours required to deploy context-aware conversational agents, compressing vendor margins on implementation services while expanding addressable market depth.
Retrieval-augmented generation is displacing fine-tuned proprietary models in enterprise deployments. Banking institutions in the United Kingdom and Germany are adopting RAG architectures at accelerating pace to ground responses in auditable document corpora. This technology shift is displacing the previous generation of black-box neural models that carried unacceptable litigation exposure under emerging liability frameworks.
The EU AI Act's risk-based classification system entered force with staggered implementation timelines that vary by application severity. High-risk chatbot deployments in healthcare and financial services now face mandatory conformity assessment procedures that add twelve to eighteen months to product launch schedules. French and Dutch regulators are issuing sector-specific guidance on natural language processing system validation that exceeds baseline Brussels requirements.
Buyer procurement patterns are gravitating toward API-first conversational platforms with consumption-based pricing. Mid-market contact centers in the Netherlands and France are abandoning perpetual-license voice platforms for metered natural language processing services. This shift is most visible in retail banking, where seasonal query volume spikes make fixed infrastructure commitments economically untenable.
North America and Europe Chatbot Market Segmentation
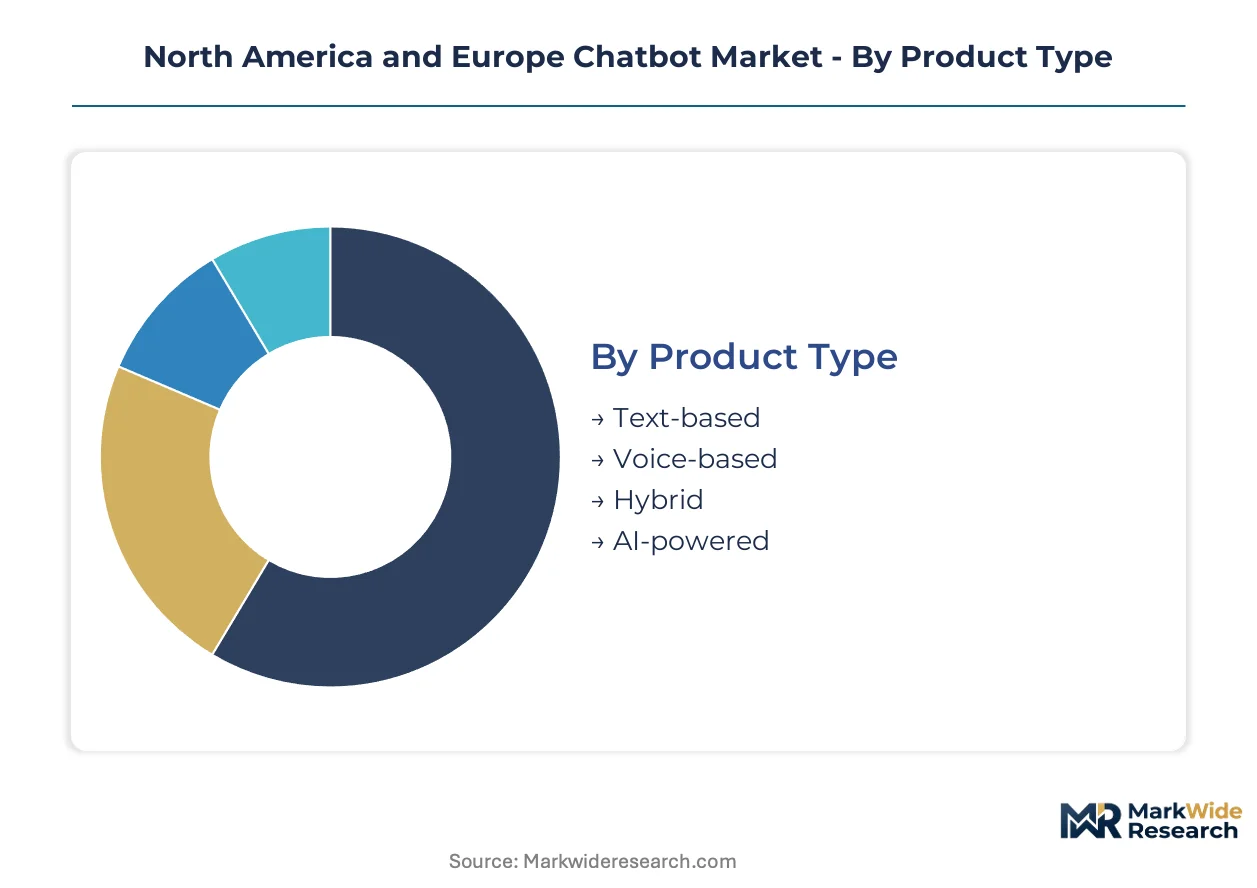
Chatbot architectures diverge sharply across North America and Europe based on regulatory exposure, latency requirements, and data residency mandates. Segment selection dictates compliance burden, infrastructure cost, and competitive positioning in these tightly regulated markets.
Product Type:
Domestic deployments favor voice and hybrid architectures in German banking and UK retail, while text-based exports serve lower-latency tolerance applications across the Netherlands and France.
- Text-based:Rule-based and natural language processing engines deliver sub-two-second response latency through lightweight API integrations. French healthcare systems deploy these for appointment scheduling where clinical decision-support scrutiny is minimal.
- Voice-based:Speech recognition pipelines with real-time transcription handle customer authentication workflows in German banking. GDPR Article 9 constraints on biometric data processing inflate compliance engineering costs for cross-border deployments.
- Hybrid:Multimodal interfaces combining text and voice inputs serve UK retail contact centers with seasonal volume spikes.
- AI-powered:Large language model architectures with retrieval-augmented generation grounding dominate new R&D investment across both regions.
Text-based systems command the established base. The steepest expansion runs through AI-powered architectures.
Deployment Model:
Cost tier stratification separates premium on-premises configurations from metered cloud consumption, with hybrid architectures emerging at the margin-to-volume intersection.
- On-premises:Hardware-resident inference engines satisfy French healthcare data residency requirements and German banking supervisory authority mandates. Fixed capital commitments and dedicated engineering staff elevate total cost of ownership 40-60% above cloud equivalents.
- Cloud-based:Elastic compute provisioning with regional EU data center residency enables Dutch and UK mid-market adoption without perpetual license overhead. Microsoft Azure and Amazon Web Services dominate infrastructure supply.
- SaaS:Pre-configured natural language processing platforms with consumption-based pricing attract Netherlands contact centers modernizing from legacy IVR.
- Managed:Vendor-operated deployments with bundled compliance documentation serve UK financial institutions navigating EU AI Act conformity assessment bottlenecks.
Cloud-based deployment captures volume leadership. SaaS models are climbing the fastest as procurement shifts from capital expenditure to operational expenditure.
End User:
Application maturity varies by sector regulatory density, with banking and healthcare requiring CE marking under EU AI Act high-risk classification while retail and travel operate under lighter oversight.
- Retail:Conversational commerce deployments in North American and UK markets automate product discovery and checkout workflows. Seasonal query spikes drive preference for metered API pricing over fixed infrastructure.
- Banking:Customer authentication and payment query automation in Germany and the UK face mandatory conformity assessment procedures extending launch timelines. CE marking requirements favor established vendors with dedicated regulatory affairs teams.
- Healthcare:Clinical decision-support chatbots face FDA scrutiny in the United States and ANSM/CNIL sector-specific guidance in France exceeding baseline Brussels requirements.
- Travel:Booking modification and itinerary management bots operate under lighter algorithmic transparency mandates, enabling faster deployment cycles in Dutch and UK markets.
Banking commands the established base. Retail is expanding most quickly as conversational commerce matures.
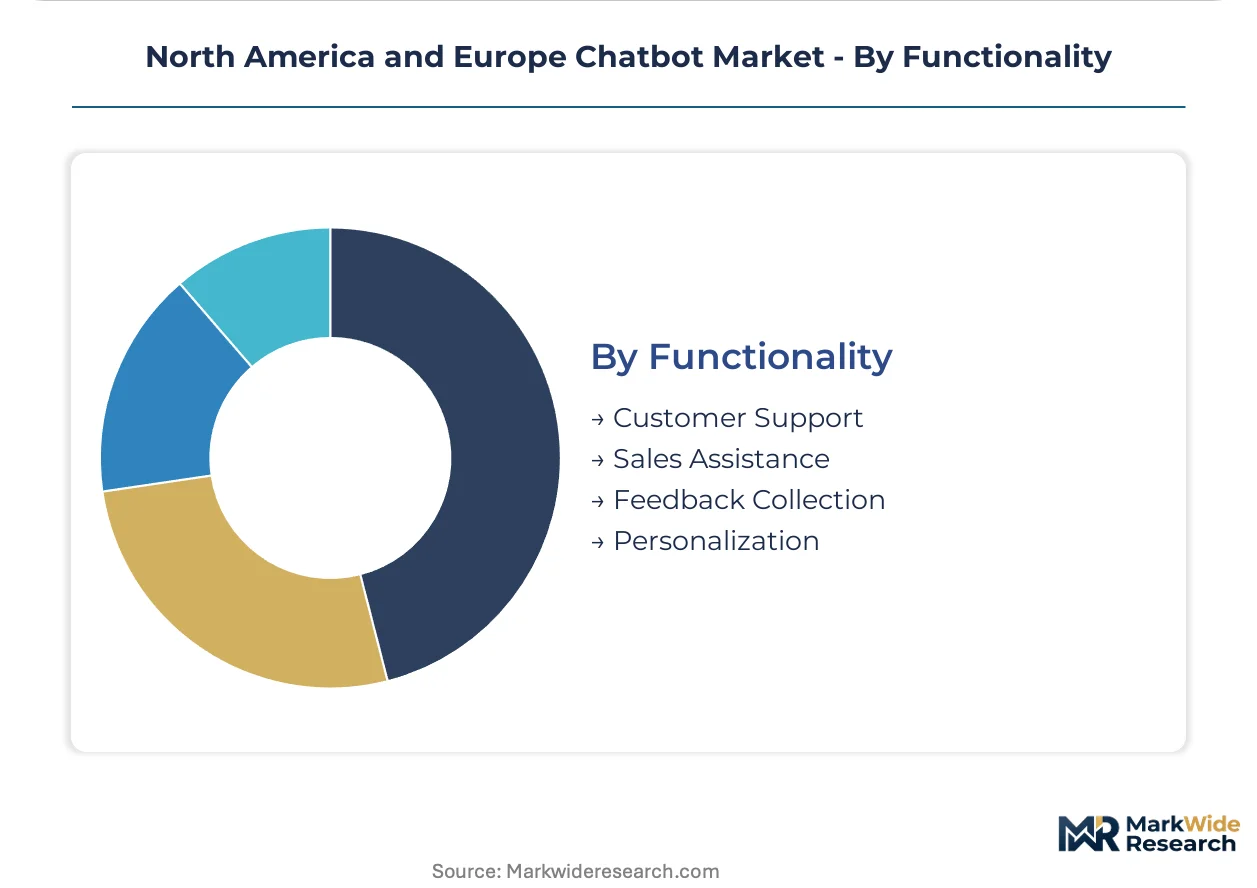
Functionality:
Customer-facing workflows concentrate investment in high-volume service environments, while back-office applications remain underpenetrated due to integration complexity with legacy CRM and ERP systems.
- Customer Support:Ticket deflection and live agent handoff automation generate the largest revenue pool across North American and European contact centers. Zendesk and Salesforce-native integrations reduce deployment friction for mid-market buyers.
- Sales Assistance:Transactional chatbots with product recommendation engines and cart recovery workflows are gaining share fastest in North American retail. API-first platforms with consumption pricing align with seasonal demand patterns.
- Feedback Collection:Post-interaction survey automation with sentiment analysis pipelines serves UK and French utilities with regulatory reporting obligations.
- Personalization:Context-aware response tailoring based on customer history and real-time behavior tracking faces GDPR Article 22 restrictions on automated profiling in EU deployments.
Customer Support commands the established base. Sales Assistance is gaining share fastest as transactional capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act's staggered enforcement timeline is accelerating procurement decisions across financial services and healthcare. Germany's KBA and France's ANSM are issuing sector-specific guidance that exceeds baseline Brussels requirements. National regulators in the United Kingdom and Netherlands are clarifying post-Brexit and GDPR-aligned compliance pathways for conversational AI deployments.
Germany
BaFin supervisory mandates are compelling retail banks to replace legacy IVR systems with certified natural language processing platforms. The KBA's automotive-grade quality standards are spilling into financial services compliance expectations. Frankfurt and Munich banking clusters are driving demand for on-premises deployments with sub-two-second latency guarantees.
United Kingdom
FCA guidance on algorithmic decision-making is reshaping procurement criteria for customer authentication chatbots. Post-Brexit divergence from EU conformity assessment procedures is creating dual-track compliance burdens for cross-border vendors. London's fintech concentration and Manchester's contact center modernization programs are absorbing disproportionate SaaS platform investment.
France
ANSM sector-specific validation requirements for clinical decision-support systems exceed baseline EU AI Act thresholds. CNIL enforcement actions on automated profiling are constraining personalization functionality in retail deployments. Paris healthcare systems and Lyon banking networks are prioritizing hybrid edge-cloud architectures for data residency compliance.
Netherlands
AFM prudential oversight is accelerating replacement of legacy voice menus in insurance and banking contact centers. The Dutch Digital Government Strategy is mandating natural language interfaces for public service delivery. Amsterdam and Rotterdam financial services hubs are shifting budgets toward metered API consumption models.
United States
FDA scrutiny of clinical decision-support chatbots as potential medical devices is extending validation timelines for healthcare vendors. State-level biometric privacy laws in Illinois and Texas are fragmenting voice-based deployment strategies. New York financial services and California technology clusters are driving R&D investment in retrieval-augmented generation architectures.
North America and Europe Chatbot Market Competitive Landscape
Listed leaders compete with private specialists across compliance infrastructure and deployment flexibility. The vendor base stratifies into three tiers: hyperscale cloud providers with dedicated regulatory affairs teams, mid-market SaaS platforms with pre-built CRM integrations, and specialized conversational AI vendors with vertical-specific language models. Competitive moves concentrate on M&A for regulatory talent acquisition and strategic partnerships for hybrid deployment architectures.
Within the hyperscale tier, Microsoft Corporation and Google LLC anchor enterprise-grade compliance pipelines across both regions. IBM Corporation exemplifies the regulated-industry specialist archetype with Watson's natural language understanding positioning. Zendesk, Inc. occupies the mid-market customer support segment with consumption-based pricing models that reduce deployment friction for Netherlands and UK contact centers.
| Leading Market Players |
|---|
| Zendesk, Inc. |
| Intercom |
| Microsoft Corporation |
| Pandorabots |
| Nuance Communications Inc. |
| IBM Corporation |
| LivePerson, Inc. |
| Cognigy |
| Google LLC |
| Others |
Value Network & Pricing Analysis
Consumption-based API metering locks in supply access for mid-market contact centers while anchoring price visibility against seasonal query volatility. Dutch and UK banking procurement teams favor this structure over perpetual licenses to align costs with fluctuating authentication workloads.
Pricing Analysis
Certification level under EU AI Act risk classification creates the primary spread between premium managed-service tiers and basic SaaS offerings. Three-tier pricing structure separates CE-marked high-risk deployments from standard cloud configurations and economy self-serve options. Pricing pressure stems from GDPR Article 9 compliance engineering inflating data acquisition costs for biometric voice systems. Mid-market Netherlands contact centers exhibit highest price sensitivity, while German BaFin-supervised institutions accept premium positioning for audit-ready documentation.
Supply Chain Analysis
GPU inventory lead times for training clusters have compressed from twelve weeks to four as hyperscalers expand European data center capacity. Inference hardware concentrates in Ireland, Germany, and the Netherlands where Microsoft Azure and Amazon Web Services anchor regional residency. Transformer model development draws from NVIDIA silicon, proprietary training datasets, and regulatory compliance documentation. Single-source vulnerability runs through Taiwan semiconductor fabrication for advanced AI accelerators. Distribution feeds through direct enterprise sales with managed deployment bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized regulatory affairs talent commands scarcity premiums as vendors compete for simultaneous EU AI Act and FDA navigation expertise. This capability gap separates hyperscale incumbents from mid-market challengers facing twelve-to-eighteen month certification delays.
For Market Incumbents: Consolidate regulatory documentation libraries to accelerate CE marking timelines for high-risk healthcare and financial services deployments. Acquire boutique compliance consultancies in Frankfurt and Paris to defend against emerging cloud-native entrants with leaner certification pipelines. Vertical integration into edge hardware manufacturing addresses French data residency requirements without forfeiting cloud economics. For New Entrants and Emerging Players: Post-interaction feedback automation with sentiment analysis represents an underserved service layer where Zendesk-native incumbents cede ground to API-first specialists. Target UK utilities and French water authorities with regulatory reporting obligations as the most penetrable vertical. Lead with consumption-based pricing that converts seasonal volume spikes into predictable operational expenditure. For Investors and Strategic Acquirers: Boutique conversational AI vendors with pre-built Dutch and German language models offer the most defensible acquisition profile as linguistic specialization becomes a bottleneck. Long-term viability hinges on retrieval-augmented generation architecture maturity grounding responses in auditable corpora. Monitor notified body capacity expansion as the inflection signal for certification timeline normalization.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Fast-Track Program | Compresses EU AI Act conformity assessment timelines for banking authentication workflows. |
| Hybrid Edge-Cloud Architecture | Enables French healthcare data residency compliance while preserving inference cost economics. |
| Regulatory Talent Acquisition | Addresses simultaneous Brussels and Washington algorithmic transparency mandate divergence. |
| RAG Platform Integration | Displaces black-box neural models with auditable document-grounded response generation. |
| Consumption Pricing Rollout | Aligns Netherlands contact center procurement with seasonal query volume fluctuations. |
Research Methodology
A standing panel of contact center operations directors, regulatory affairs leads at German BaFin-supervised banks, Dutch AFM compliance officers, and French ANSM validation specialists provided ongoing calibration against secondary sources including EU AI Act implementation guidance, CNIL enforcement actions, FCA algorithmic decision-making circulars, and hyperscaler capex disclosures. Bottom-up deployment counts triangulated against top-down addressable market sizing.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation modeling incorporated product architecture, deployment model, end-use vertical, and functionality tier dimensions. CAGRs derived from fitted growth curves applied to baseline adoption rates, with retrieval-augmented generation penetration and notified body capacity constraints as key industry-specific inputs.
Forecasts assume regulatory continuity in EU AI Act enforcement and FDA clinical decision-support scrutiny; material policy acceleration or relaxation would require re-modeling. Technology substitution risk from agentic AI architectures and data localization mandate expansion represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Legal AI Market
Artificial Intelligence (AI)
Text-To-Speech (TTS) Market
Artificial Intelligence (AI)
AI in Medical Writing Market
Artificial Intelligence (AI)
Content Automation AI Tools Market
Artificial Intelligence (AI)
Smart Virtual Personal Assistants Market
Artificial Intelligence (AI)
Enterprise Generative AI Market
Artificial Intelligence (AI)
Global Aiops Platform Market
Artificial Intelligence (AI)
Artificial Intelligence in Transportation Market
Artificial Intelligence (AI)
Conversational AI Market
Artificial Intelligence (AI)
Global Conversational Systems Market
Artificial Intelligence (AI)
AI in Life Sciences Market
Artificial Intelligence (AI)
Intelligent Virtual Assistant Market
Artificial Intelligence (AI)
Global Ambient Intelligence Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Hardware Market
Artificial Intelligence (AI)
Machine Learning in Pharmaceutical Industry Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Robotics Market