
 Australia and New Zealand Digital Transformation Market | 2026-2036
Australia and New Zealand Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Australia and New Zealand Digital Transformation Market Insights
Enterprise software distribution across Australia and New Zealand is tilting toward cloud-native reseller networks and hyperscaler marketplaces. Microsoft Corporation leverages its Azure footprint to anchor public-sector contracts across Australian state governments. IBM Corporation competes through hybrid-cloud consulting bundled with Red Hat OpenShift deployments. Datacom Group Limited dominates local managed-service relationships, particularly in Wellington and Auckland public infrastructure.
Australia and New Zealand Digital Transformation encompasses the strategic overhaul of business processes, operational models, and customer interfaces through integrated digital technologies, typically involving API-first architectures, microservices orchestration, and real-time data pipelines spanning edge-to-core infrastructure. Its primary commercial purpose is to compress decision latency, automate repetitive workflows, and unlock new revenue streams through software-defined value chains. Consulting and integration services capture the deepest margin pools as enterprises grapple with legacy-system decomposition, while AI deployments within financial services represent the fastest-expanding technology-end user intersection. Hybrid cloud retains structural dominance among regulated industries unwilling to surrender data sovereignty.
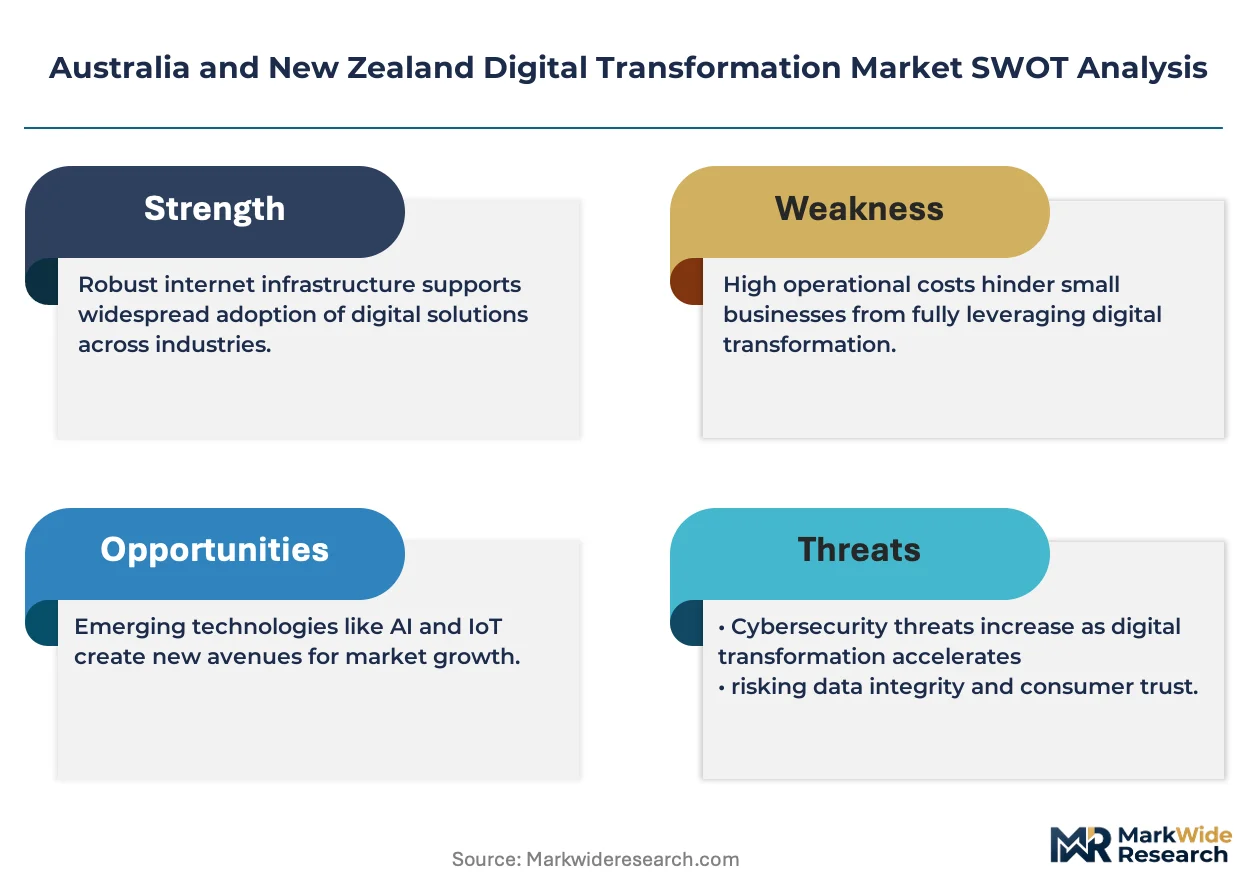
TGA data-governance requirements for healthcare software and Australia's Cyber Security Centre Essential Eight framework shape product certification pathways and procurement eligibility across federal agencies. New Zealand's Privacy Act 2020 amendments and the Australian Competition and Consumer Commission's digital-platform oversight further constrain how customer data architectures may be designed and monetized. Stakeholders must weigh compliance velocity against cloud-migration timelines, as regulatory divergence between Canberra and Wellington intensifies cross-border deployment complexity.
Market Dynamics
Cloud migration mandates from the Australian Digital Health Agency are compressing procurement cycles across public-sector infrastructure, forcing legacy system decomposition at unprecedented velocity.
Growth Catalysts
- TGA interoperability frameworks:Healthcare providers in New South Wales accelerate API-first architecture deployment to meet federal data-exchange standards.
- Edge computing expansion:Financial services institutions deploy real-time processing nodes to reduce decision latency in algorithmic trading workflows.
- Victoria's enterprise procurement concentration:Melbourne anchors technology absorption, with state government contracts driving hyperscaler marketplace adoption.
Market Restraints
- Specialized cloud-architect talent scarcity:Certification requirements for Australian Cyber Security Centre Essential Eight compliance outstrip qualified personnel supply.
- Cross-border regulatory divergence:Wellington and Canberra impose divergent data-sovereignty constraints, fragmenting unified deployment architectures.
- Legacy mainframe dependency:Banking and insurance retain COBOL-critical systems that resist microservices decomposition without catastrophic operational risk.
Strategic Opportunities
- New Zealand Privacy Act 2020 enforcement:Compliance tooling and consent-management platforms capture unmet demand across Auckland SME segments.
- AI-operations convergence:Predictive analytics layered atop hybrid-cloud infrastructure opens automation revenue streams in manufacturing quality control.
- Queensland public infrastructure lag:Underpenetrated state and local government contracts offer first-mover positioning for managed-service providers outside Sydney-Melbourne corridors.
Industry Challenges
- DevSecOps skill pipeline gaps:Australian universities produce insufficient security-embedded development practitioners to match enterprise hiring velocity.
- Multi-cloud orchestration complexity:Integration friction between Azure, AWS, and on-premise VMware environments extends project timelines and inflates consulting costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia and New Zealand Digital Transformation Market |
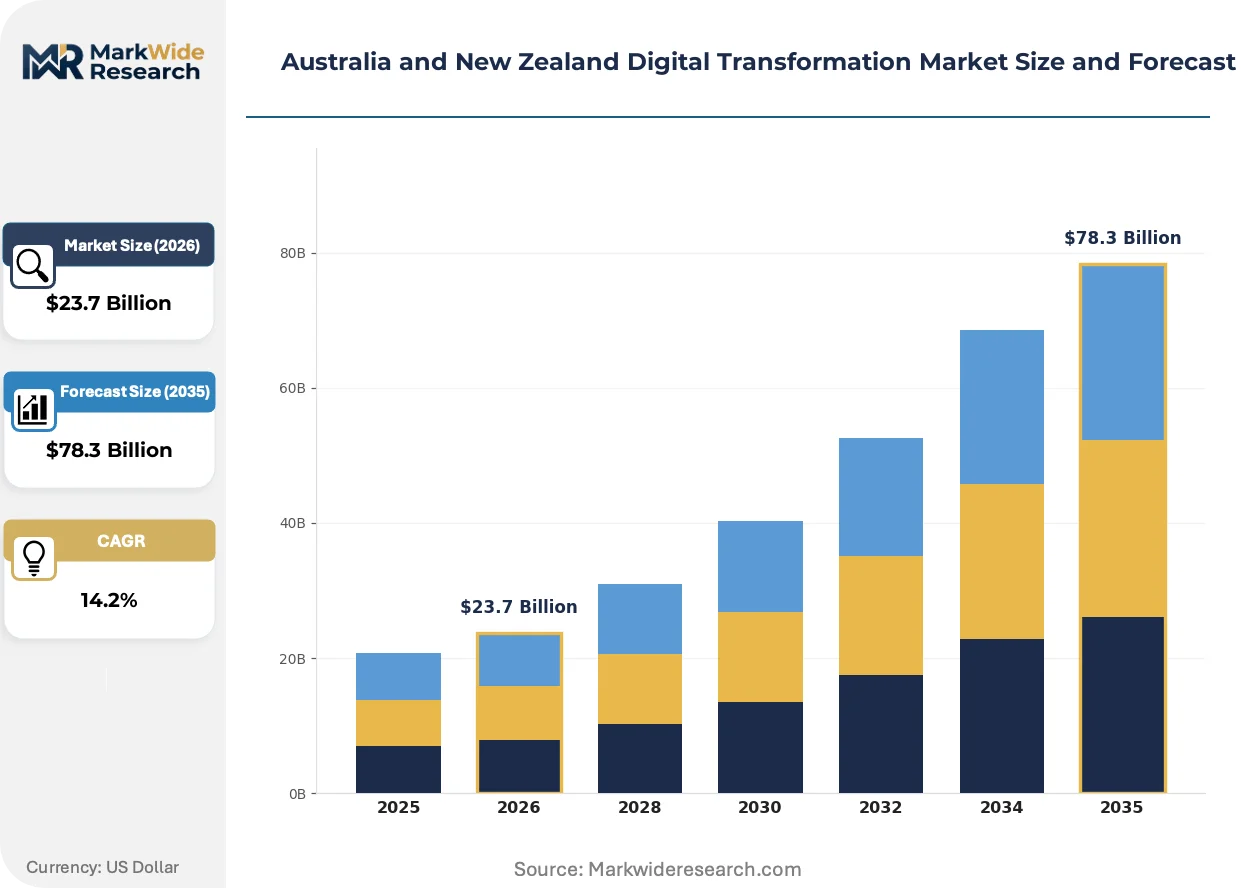
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $78.3 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Technology: AI, IoT, Blockchain, Big Data End User: Healthcare, Retail, Manufacturing, Financial Services Service Type: Consulting, Integration, Managed Services, Support |
| Companies Covered | Accenture plc, Microsoft Corporation, IBM Corporation, Google LLC (Alphabet Inc.), Amazon Web Services Inc., SAP SE, Oracle Corporation, Tata Consultancy Services Limited, Datacom Group Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia and New Zealand Digital Transformation Market Trends and Innovations
API-first architectures are displacing monolithic enterprise software, compressing the boundary between operational technology and information technology layers across Australian and New Zealand organizations.
Containerized microservices orchestration through Kubernetes is digitizing application deployment workflows. Major banks and insurers in Sydney adopt this infrastructure model aggressively, collapsing months-long release cycles into days. This compression is digitizing competitive differentiation in customer-facing digital products.
Australia's Cyber Security Centre Essential Eight maturity model mandates baseline security configurations for federal contractors. Procurement eligibility now hinges on demonstrated compliance, filtering vendor participation. Defence and critical infrastructure sectors face the steepest certification timelines, driving demand for automated compliance-validation tooling.
Subscription-based consumption models displace perpetual licensing in enterprise software procurement. New Zealand government agencies lead this transition through aggregated marketplace purchasing. Wellington's public-sector IT consolidation exemplifies how centralized procurement functions extract volume pricing from hyperscaler catalogs while reducing vendor-management overhead.
Australia and New Zealand Digital Transformation Market Segmentation
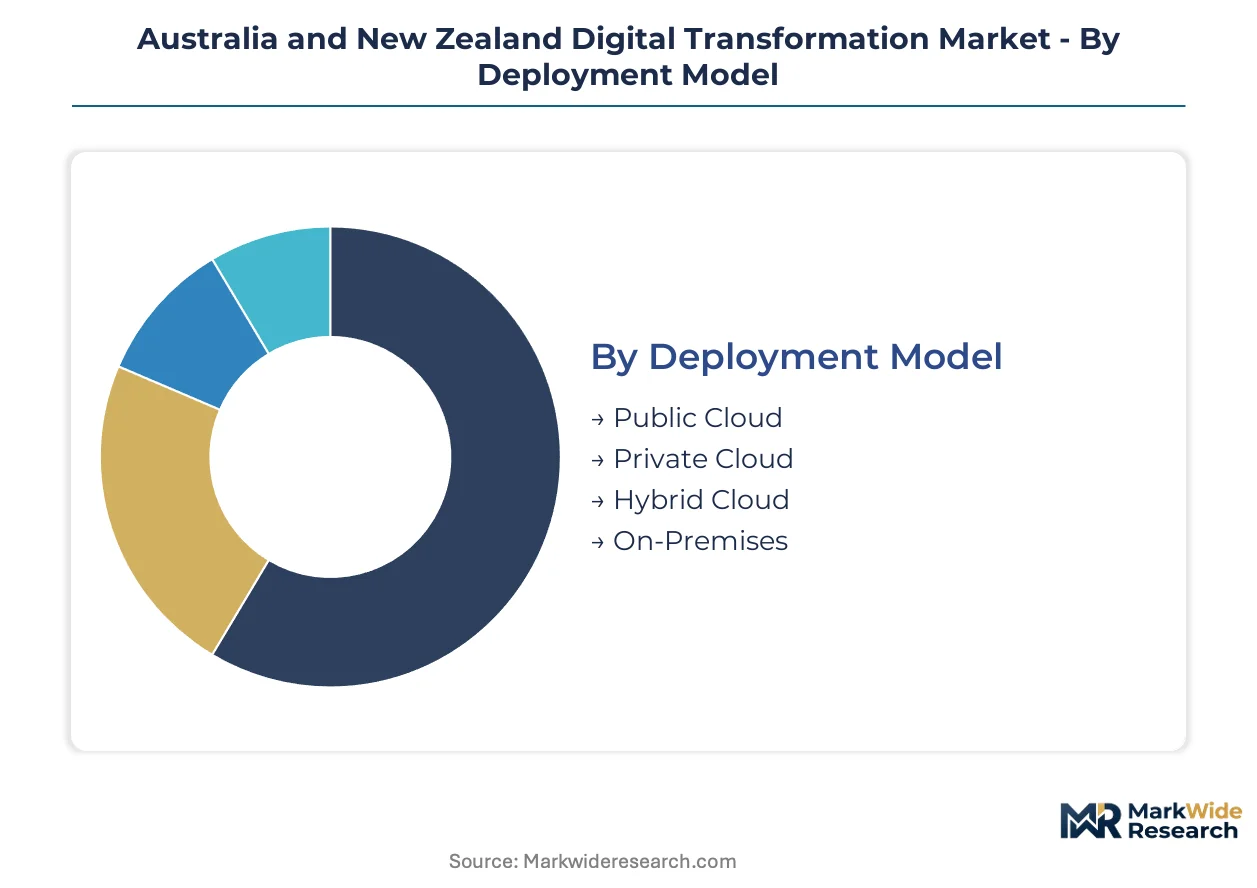
Segmentation reveals how digital transformation investments concentrate across infrastructure models and buyer archetypes in Australia and New Zealand. Understanding these divisions exposes where procurement budgets flow and which technology stacks capture enterprise commitment.
Deployment Model:
Mature public cloud offerings coexist with emerging sovereign-cloud alternatives as regulatory pressure reshapes infrastructure choices.
- Public Cloud:Hyperscaler platforms deliver elastic compute and storage without capital expenditure. New South Wales and Victoria government agencies drive procurement through centralized marketplace contracts, though data residency concerns constrain sensitive workload placement.
- Hybrid Cloud:Orchestration layers span on-premise VMware estates and Azure or AWS regions, enabling gradual legacy decomposition. Australian banks favor this architecture to retain core transaction processing on sovereign infrastructure while bursting customer-facing applications to public nodes.
- Private Cloud:Dedicated infrastructure serves defence contractors and critical infrastructure operators under Essential Eight mandates. Wellington public agencies deploy locally hosted OpenStack environments to satisfy Privacy Act 2020 data sovereignty requirements.
- On-Premises:Legacy mainframe and mid-range systems persist in insurance and manufacturing where cloud migration risk outweighs modernization benefits. Queensland regional councils maintain this footprint due to connectivity constraints and limited technical staffing.
Hybrid cloud handles the majority of throughput; public cloud is the fastest mover on share.
Technology:
Cost tier separates foundational data infrastructure from emerging trust and automation layers.
- AI:Machine learning operations platforms automate predictive maintenance in manufacturing and fraud detection in financial services. Melbourne insurers deploy natural language processing for claims automation, compressing processing cycles from weeks to hours.
- Big Data:Real-time data pipelines ingest telemetry from industrial equipment and customer touchpoints. Sydney retail chains leverage these architectures for demand forecasting and inventory optimization across distributed store networks.
- IoT:Sensor networks monitor agricultural assets in New Zealand and mining equipment in Western Australia. Edge gateways process telemetry locally before cloud aggregation, reducing bandwidth costs and decision latency.
- Blockchain:Distributed ledger pilots focus on supply chain provenance and cross-border trade documentation. Australian wine exporters experiment with immutable certification to satisfy Asian market authenticity requirements.
Big data commands the largest implementation budgets; AI is expanding most quickly as model deployment tooling matures.
End User:
Customer type determines solution complexity and procurement cycle length across regulated and competitive sectors.
- Financial Services:Algorithmic trading platforms and open banking APIs demand sub-millisecond latency and rigorous compliance documentation. Sydney and Melbourne anchor this segment, with major banks operating dedicated innovation labs.
- Healthcare:Electronic medical record interoperability and telehealth infrastructure absorb capital under TGA and Australian Digital Health Agency mandates. New South Wales Health leads procurement scale, with statewide patient identifier integration driving API-first architecture adoption.
- Retail:Omnichannel fulfillment and personalized recommendation engines compete for technology investment. Auckland consumer brands prioritize cloud-native commerce platforms to serve trans-Tasman customer bases.
- Manufacturing:Quality control automation and predictive maintenance lag other sectors in cloud adoption due to operational technology security concerns. Victorian automotive suppliers represent the most advanced deployments within this conservative vertical.
Financial services contributes the deepest project values; healthcare is climbing the fastest as federal interoperability deadlines approach.
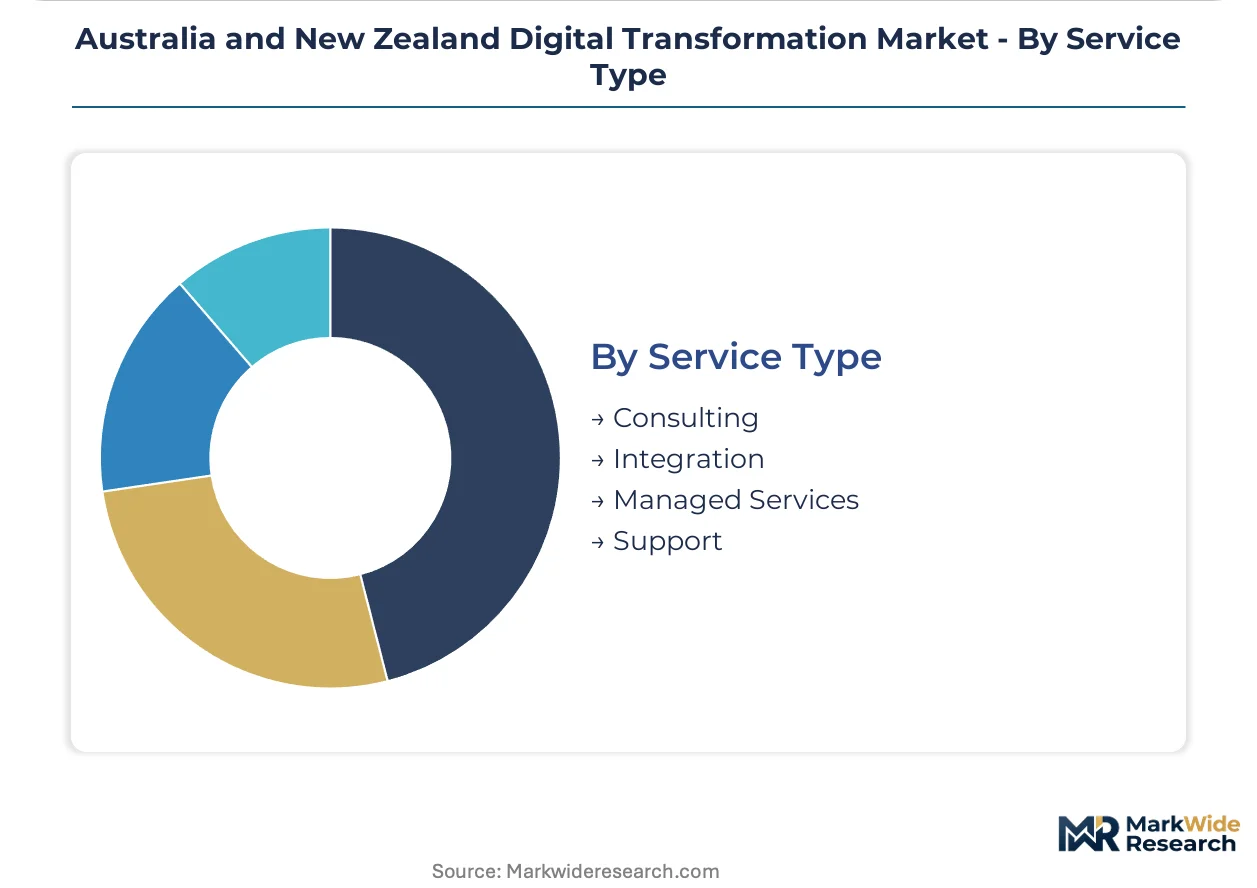
Service Type:
Margin structure separates high-touch advisory from recurring operational support.
- Consulting:Strategy and architecture advisory commands premium pricing as enterprises navigate legacy-to-cloud transitions. Major Australian banks retain boutique firms for mainframe decomposition planning alongside hyperscaler professional services.
- Managed Services:Operational handoff of infrastructure and application management dominates New Zealand public sector procurement. Wellington's centralized IT function aggregates demand across agencies to extract volume pricing from local providers.
- Integration:System interconnectivity projects bridge SaaS applications with on-premise ERP estates. Victoria's manufacturing mid-market drives demand for middleware and API management tooling.
- Support:Break-fix and maintenance contracts retain steady share despite cloud subscription growth. Queensland government agencies maintain substantial support spend for legacy systems awaiting replacement.
Managed services captures the greatest recurring revenue; consulting shows the steepest expansion trajectory as transformation complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Australia-Japan Cable and Southern Cross Cable Network interconnects underpin trans-Tasman digital infrastructure capacity, positioning Sydney and Auckland as primary data exchange nodes for enterprise cloud workloads.
New South Wales
Sydney's financial services sector drives hyperscaler marketplace procurement through concentrated banking and insurance headquarters. The Australian Cyber Security Centre Essential Eight framework mandates baseline security configurations for federal contractors, filtering vendor participation. Macquarie Park and North Sydney technology corridors host the densest concentration of cloud-native reseller networks serving enterprise clients.
Victoria
Melbourne anchors state government technology absorption with centralized procurement functions extracting volume pricing from hyperscaler catalogs. The Australian Digital Health Agency's interoperability mandates compress procurement cycles across public-sector infrastructure. Docklands and Southbank enterprise districts concentrate hybrid-cloud consulting engagements for legacy system decomposition.
Queensland
Brisbane's underpenetrated state and local government contracts offer first-mover positioning for managed-service providers outside Sydney-Melbourne corridors. Connectivity constraints and limited technical staffing maintain legacy on-premises footprints in regional councils. Fortitude Valley emerging technology precinct attracts edge computing deployments for resource sector applications.
Western Australia
Perth's mining and resources sector deploys IoT sensor networks with edge gateways processing telemetry locally before cloud aggregation. The state's geographic isolation drives demand for sovereign cloud alternatives to hyperscaler platforms. Karratha and Port Hedland industrial zones anchor real-time equipment monitoring infrastructure.
New Zealand
Wellington's centralized IT function aggregates demand across agencies to extract volume pricing from local providers under Privacy Act 2020 data sovereignty requirements. Auckland SME segments capture unmet demand for compliance tooling and consent-management platforms. Christchurch rebuild infrastructure embeds API-first architecture for resilient public service delivery.
Australia and New Zealand Digital Transformation Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying infrastructure and tooling layers. The vendor base organizes around three structural tiers: global hyperscalers anchoring public cloud consumption, multinational consultancies bundling hybrid-cloud advisory with implementation, and local managed service providers capturing operational handoff relationships. Consolidation pressure intensifies as procurement centralization favors scale, while regulatory divergence between Canberra and Wellington fragments unified deployment architectures. Competitive positioning depends on Essential Eight certification velocity and cross-border compliance tooling.
Within the global platform tier, Microsoft Corporation and Amazon Web Services Inc. anchor hyperscaler marketplace penetration across Australian state governments. IBM Corporation occupies a position bridging hybrid-cloud consulting with open-source infrastructure tooling. Datacom Group Limited exemplifies the local managed service provider archetype, anchoring Wellington and Auckland public infrastructure relationships through aggregated agency procurement. These three patterns—hyperscaler platform dominance, multinational consulting integration, and local operational specialization—capture the competitive structure compressing decision latency across trans-Tasman enterprise technology procurement.
| Leading Market Players |
|---|
| Accenture plc |
| Microsoft Corporation |
| IBM Corporation |
| Google LLC (Alphabet Inc.) |
| Amazon Web Services Inc. |
| SAP SE |
| Oracle Corporation |
| Tata Consultancy Services Limited |
| Datacom Group Limited |
| Others |
Pricing and Supply Chain Analysis
Essential Eight certification bottlenecks determine both pricing tier spreads and supply chain shape across Australian and New Zealand digital transformation procurement. Federal contractors face elongated vendor qualification timelines that compress margin structures for uncertified service providers while concentrating premium pricing power among accredited hyperscaler partners.
Pricing Analysis
Volume-discount tiering structures dominate public-sector procurement through centralized marketplace contracts. Three-tier pricing separates enterprise-grade managed services from mid-market integration packages and basic cloud consumption blocks. Price differentiation stems from Essential Eight maturity certification and geographic delivery density. Cost compression in mid-market consulting intensifies as boutique firms compete against hyperscaler professional services for legacy decomposition projects. State government agencies exhibit highest price sensitivity due to aggregated procurement mandates, while defence contractors accept premium tiers for sovereign-cloud isolation.
Supply Chain Analysis
Tariff exposure between Australia and China in semiconductor components constrains hardware provisioning timelines for edge computing deployments. Supply concentration centers on Taiwan for advanced processors, China for networking equipment, and the United States for enterprise software licensing. Raw material dependencies span silicon wafers, memory modules, and specialized cooling systems. Single-source vulnerability persists in sovereign-cloud infrastructure where domestic providers lack scale to replicate hyperscaler platform breadth. Distribution runs through Sydney and Melbourne technology corridors before radiating to Wellington and regional Australian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified cloud-architect scarcity defines competitive dynamics across trans-Tasman enterprise technology procurement. Organizations that secure pipeline access to Australian Cyber Security Centre-accredited talent gain disproportionate leverage in federal contracting.
For Market Incumbents: Entrench Essential Eight certification velocity as the primary defensive moat against hyperscaler encroachment. Invest in automated compliance-validation tooling to compress procurement eligibility timelines. Deepen Wellington and Auckland public infrastructure relationships through multi-year managed service agreements that aggregate agency demand. For New Entrants and Emerging Players: Queensland state and local government contracts represent the most penetrable entry point outside Sydney-Melbourne corridors. Mid-market manufacturing in Victoria offers second-mover positioning for API-first integration specialists. Lead with fixed-price legacy decomposition pilots to demonstrate capability without incumbent scale advantages. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated consultancies with sovereign-cloud deployment credentials. Long-term viability hinges on cross-border compliance tooling that bridges Canberra and Wellington regulatory divergence. Watch Essential Eight certification queue lengths as the inflection indicator for vendor pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Essential Eight Certification Acceleration | Automated compliance validation compresses federal contractor eligibility timelines against hyperscaler competition. |
| Sovereign-Cloud Infrastructure Buildout | Dedicated OpenStack environments capture Wellington agency demand under Privacy Act 2020 mandates. |
| Cross-Border Compliance Tooling | Unified data governance platforms reduce fragmentation costs for trans-Tasman enterprise deployments. |
| API-First Architecture Specialization | Microservices orchestration expertise commands premium pricing in New South Wales Health interoperability programs. |
| Edge Computing Partnership | Real-time processing nodes in Perth mining corridors reduce latency for resource sector telemetry analytics. |
Research Methodology
Operator-level perspectives from cloud architects, federal procurement officers, hyperscaler channel partners, and managed services executives anchored the qualitative base. Primary interviews combined with secondary validation drawn from Australian Cyber Security Centre publications, TGA guidance documents, New Zealand Privacy Commissioner rulings, and state government IT procurement disclosures. Bottom-up sizing of vendor-reported engagements triangulated against top-down budget allocation analysis across Australian state governments and New Zealand central agencies.
Scenario-bracketing framed projections across the analysis window with sensitivity testing for regulatory enforcement intensity and certification pipeline constraints. Segmentation modeling incorporated deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions. CAGRs derived from trend extrapolation of historical procurement cycles adjusted for mandated interoperability deadlines. Forecast inputs included Essential Eight compliance velocity assumptions and cross-border data sovereignty constraint evolution.
Practitioners should monitor Essential Eight certification queue lengths and trans-Tasman regulatory divergence indices for early signals of vendor pricing power shifts. Forecasts reflect documented assumptions regarding federal mandate enforcement timelines and hyperscaler marketplace penetration rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
South Korea Digital Transformation Market
Digital Transformation
Netherlands Digital Transformation Market
Digital Transformation
Digital Transformation in Supply Chain Market
Digital Transformation
Innovation Management Market
Digital Transformation
Qatar Digital Transformation Market
Digital Transformation
Enterprise 2.0 Technologies Market
Digital Transformation
Nigeria Digital Transformation Market
Digital Transformation
ASEAN Digital Transformation Market
Digital Transformation
Germany Digital Transformation Market
Digital Transformation
Contact Center Transformation Market
Digital Transformation
North America Digital Transformation Market
Digital Transformation
India Digital Transformation Market
Digital Transformation
APAC Digital Transformation Market
Digital Transformation
Europe Digital Transformation Market
Digital Transformation
UAE Digital Transformation Market
Digital Transformation
France Digital Transformation Market