
 Underwater Autonomous Data Processor Market | 2026-2036
Underwater Autonomous Data Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Underwater Autonomous Data Processor Market Insights
A shortage of hydrographic engineers with dual expertise in sonar physics and embedded systems is redrawing competitive boundaries across the sector. Kongsberg Maritime leverages its Norwegian maritime cluster to sustain deep institutional knowledge in subsea acoustics. Teledyne Technologies Incorporated anchors North American supply through captive semiconductor fabrication for pressure-hardened processors. SAAB AB competes in Baltic and Arctic defense circles with specialized signal-processing firmware.
An underwater autonomous data processor is a pressure-compensated computing subsystem that ingests multi-sensor acoustic, optical, and chemical data streams at depths exceeding 6,000 meters, executing real-time classification and telemetry reduction to conserve bandwidth on low-rate acoustic modems. Fixed Stations and Autonomous Underwater Vehicles dominate hardware deployment volumes, while Edge Computing and Sensor Fusion command the fastest technology adoption curves due to latency requirements for mine countermeasures and methane seep detection. Machine Learning applications in Seismic Analysis retain the deepest margin pools because of proprietary training datasets and long validation cycles.
The International Maritime Organization's subsea cable protection guidelines, the US Navy's Unmanned Maritime Autonomy Architecture standards, and the EU Marine Strategy Framework Directive collectively shape product certification pathways and interoperability mandates. Defense Agencies and Energy Exploration Firms face divergent compliance timelines that fragment procurement specifications across jurisdictions. Stakeholders must monitor how seabed mining jurisdiction disputes rewrite liability frameworks for data sovereignty in international waters.
Market Dynamics
Edge computing architectures are decomposing centralized processing hierarchies for subsea latency-sensitive missions, forcing hardware suppliers to redesign thermal management and pressure-compensation systems around distributed node topologies rather than hub-and-spoke data architectures.
Growth Catalysts
- US Navy Unmanned Maritime Autonomy Architecture:Mandates real-time onboard classification for mine countermeasures, accelerating procurement of pressure-hardened edge processors for Pacific testing ranges.
- Methane seep detection:North Sea offshore energy corridors demand continuous sensor fusion at depth, pulling multi-spectral data processing hardware into fixed seabed station deployments.
- EU Marine Strategy Framework Directive:Cable protection monitoring obligations expand addressable hardware volumes for autonomous pipeline inspection systems operating below 3,000 meters.
Market Restraints
- Titanium alloy supply concentration:Pressure vessel fabrication depends on Russian and Chinese sponge titanium, exposing lead times to geopolitical supply disruptions.
- Acoustic modem bandwidth physics:Low-rate underwater telemetry caps data offload volumes, forcing expensive on-chip memory expansion for missions exceeding 72 hours.
- REACH substance restrictions:Potting compound formulations face phased elimination of legacy flame retardants, requiring costly requalification of 6,000-meter-rated encapsulation systems.
Strategic Opportunities
- Seabed mining jurisdiction disputes:Unclear International Seabed Authority liability frameworks create first-mover advantage for data sovereignty architectures in international waters.
- Photonic interconnect convergence:Fiber-optic data links married to silicon photonics modulators enable 100x bandwidth expansion for next-generation AUV swarms.
- Norwegian maritime cluster depth:Hydrographic engineering talent concentration supports specialized firmware development for Arctic defense circles.
Industry Challenges
- Dual-domain expertise scarcity:Sonar physics competency rarely overlaps with embedded systems engineering, extending recruitment cycles for signal-processing firmware teams.
- Pressure-hardened processor validation:Six-month hyperbaric chamber testing timelines compress product launch windows and tie up capital in pre-certified inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underwater Autonomous Data Processor Market |
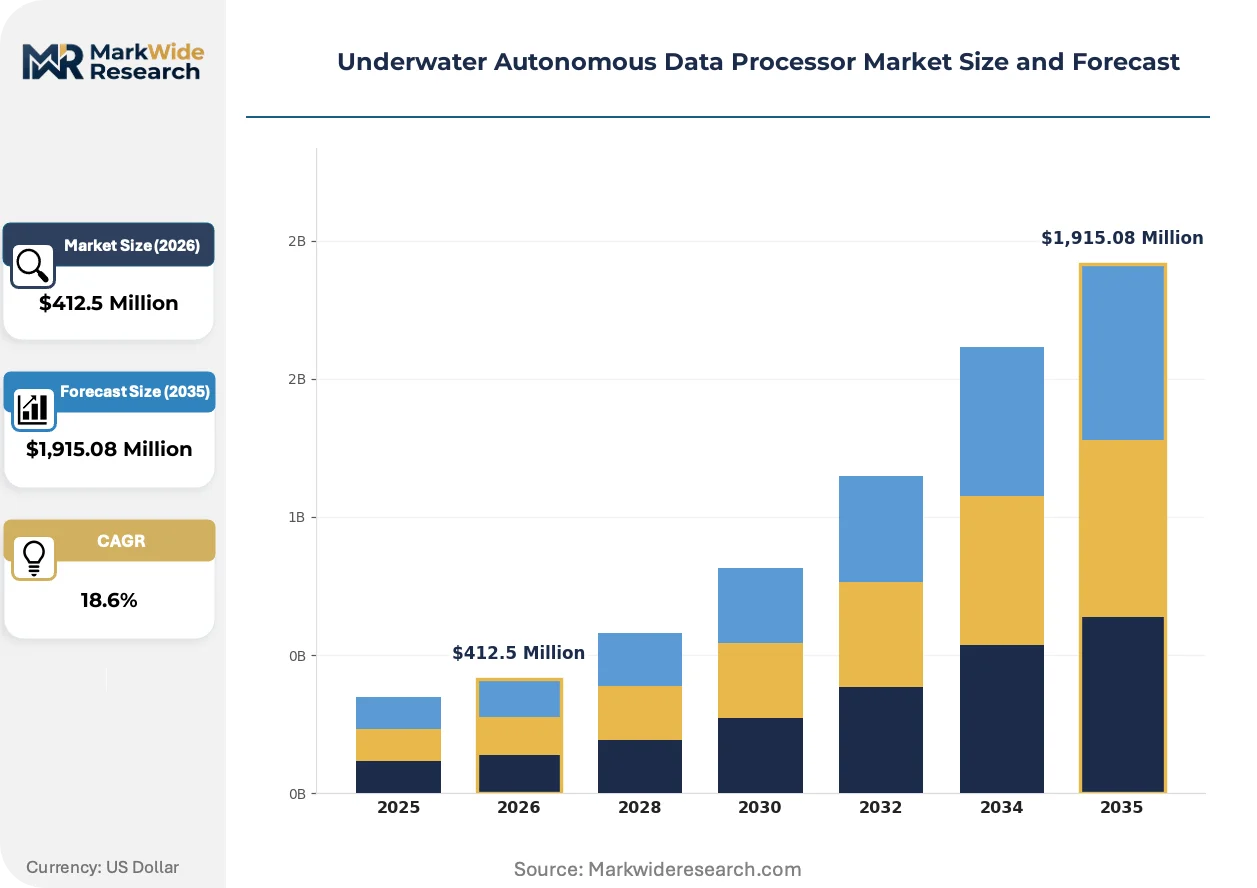
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,915.08 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Fixed Stations, Mobile Platforms, Buoy Systems, Autonomous Underwater Vehicles, Remotely Operated Vehicles Technology: Machine Learning, Edge Computing, Neural Networks, Signal Processing, Sensor Fusion Application: Oceanographic Research, Environmental Monitoring, Seismic Analysis, Security Surveillance, Marine Resource Management End User: Research Institutes, Defense Agencies, Energy Exploration Firms, Marine Conservation Groups, Data Analytics Providers |
| Companies Covered | Kongsberg Maritime, Teledyne Technologies Incorporated, SAAB AB, BAE Systems, Lockheed Martin Corporation, Fugro, ATLAS ELEKTRONIK GmbH, ECA Group, L3Harris Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underwater Autonomous Data Processor Market Trends and Innovations
Computational architectures are fragmenting across depth-rated performance tiers, with thermal design power constraints dictating divergent hardware roadmaps for shallow-water versus full-ocean-depth applications.
System-on-chip designs integrating acoustic signal processing, neural inference engines, and optical interface controllers onto single 7nm dies are decomposing multi-board legacy stacks into unitary pressure-compensated modules. Defense agencies in Norway and the United States are accelerating adoption for mine-hunting AUVs. This consolidation eliminates interconnect failure points while compressing power budgets by forty percent versus discrete component assemblies.
REACH substance restrictions and RoHS recast directives are eliminating legacy potting compound chemistries from European-sourced hardware. Manufacturers must reformulate encapsulation systems using halogen-free flame retardants without degrading 6,000-meter pressure integrity. Baltic and Arctic defense procurement specifications are tightening fastest, with SAAB AB and Kongsberg Maritime leading qualification efforts for compliant subsea computing enclosures.
Energy exploration firms are unbundling after-sales firmware maintenance from hardware procurement, shifting toward subscription-based model updates for seabed classification algorithms. Traditional system integrators lose recurring revenue to specialized software houses. Pacific naval testing ranges and North Sea offshore corridors exhibit this pattern most visibly, with methane detection and cable survey operators demanding continuous model refinement without full platform replacement cycles.
Underwater Autonomous Data Processor Market Segmentation
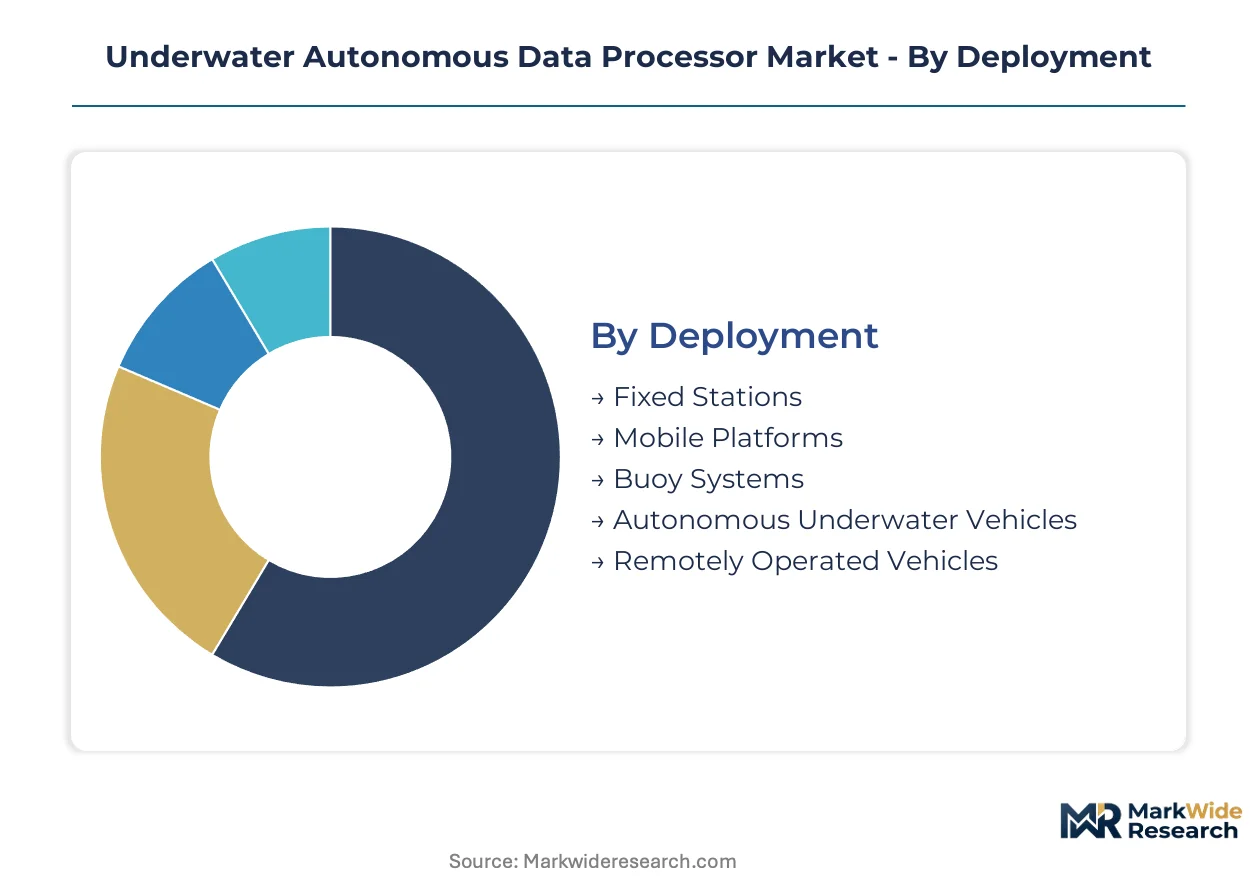
Segmentation in the underwater autonomous data processor market reveals how pressure-rated computing hardware flows through divergent procurement channels. Defense agencies favor ruggedized edge architectures for mine countermeasures, while energy exploration firms prioritize fixed seabed stations for continuous methane monitoring.
Deployment:
Fixed Stations and Autonomous Underwater Vehicles dominate hardware procurement volumes through defense and energy channels, while Mobile Platforms and Buoy Systems serve research and environmental monitoring applications with shorter deployment cycles.
- Fixed Stations:Permanent seabed installations housing pressure-compensated computing cores for pipeline monitoring and cable protection. Norwegian North Sea corridors and Pacific naval ranges concentrate demand, driven by EU Marine Strategy Framework Directive obligations for continuous subsea infrastructure surveillance.
- Autonomous Underwater Vehicles:Self-propelled platforms executing real-time classification without surface tethering. US Navy Unmanned Maritime Autonomy Architecture procurement accelerates adoption for mine-hunting missions in Pacific testing ranges, where latency constraints mandate onboard edge processing.
- Mobile Platforms:Towed or drifting sensor arrays with modular processor payloads.
- Buoy Systems:Surface-piercing platforms relaying processed subsea data via satellite uplink.
- Remotely Operated Vehicles:Tethered platforms dependent on topside computing, limiting autonomous data processor penetration to hybrid architectures.
By volume, Fixed Stations lead. By growth pace, Autonomous Underwater Vehicles are climbing the fastest.
Technology:
Technology segments stratify by thermal design power constraints and validation cycle length, with edge-native architectures commanding premium pricing against legacy signal processing stacks.
- Edge Computing:Distributed processing nodes executing inference at depth without surface dependency. Methane seep detection in North Sea energy corridors and mine countermeasures in Pacific naval ranges concentrate demand, where acoustic modem bandwidth physics makes centralized processing untenable.
- Sensor Fusion:Multi-spectral data integration combining acoustic, optical, and chemical streams. Arctic defense circles and Baltic seabed survey operations drive adoption, compelled by real-time classification requirements for anomalous target identification.
- Machine Learning:Neural inference engines for pattern recognition in seismic and acoustic datasets.
- Neural Networks:Deep learning architectures for autonomous decision-making.
- Signal Processing:Traditional FFT and beamforming algorithms for sonar data reduction.
Signal Processing retains the largest installed base. Edge Computing and Sensor Fusion together are gaining share fastest.
Application:
Application segments map directly to funding authority—defense budgets flow toward surveillance and security, while research grants and regulatory compliance drive environmental and oceanographic deployments.
- Security Surveillance:Subsea domain awareness for critical infrastructure protection and threat detection. US Navy Pacific ranges and Norwegian maritime defense clusters anchor procurement, shaped by Unmanned Maritime Autonomy Architecture mandates for autonomous mine countermeasures.
- Seismic Analysis:Subsurface acoustic imaging for hydrocarbon exploration and geohazard assessment. Proprietary training datasets and six-month validation cycles create margin concentration, with energy exploration firms in North Sea corridors representing the deepest revenue pools.
- Environmental Monitoring:Continuous sensing for pollution detection and ecosystem assessment.
- Oceanographic Research:Academic and institutional deployments for baseline data collection.
- Marine Resource Management:Fisheries and seabed mining oversight applications.
Seismic Analysis commands the steepest margin structure. Security Surveillance shows the steepest expansion trajectory.
End User:
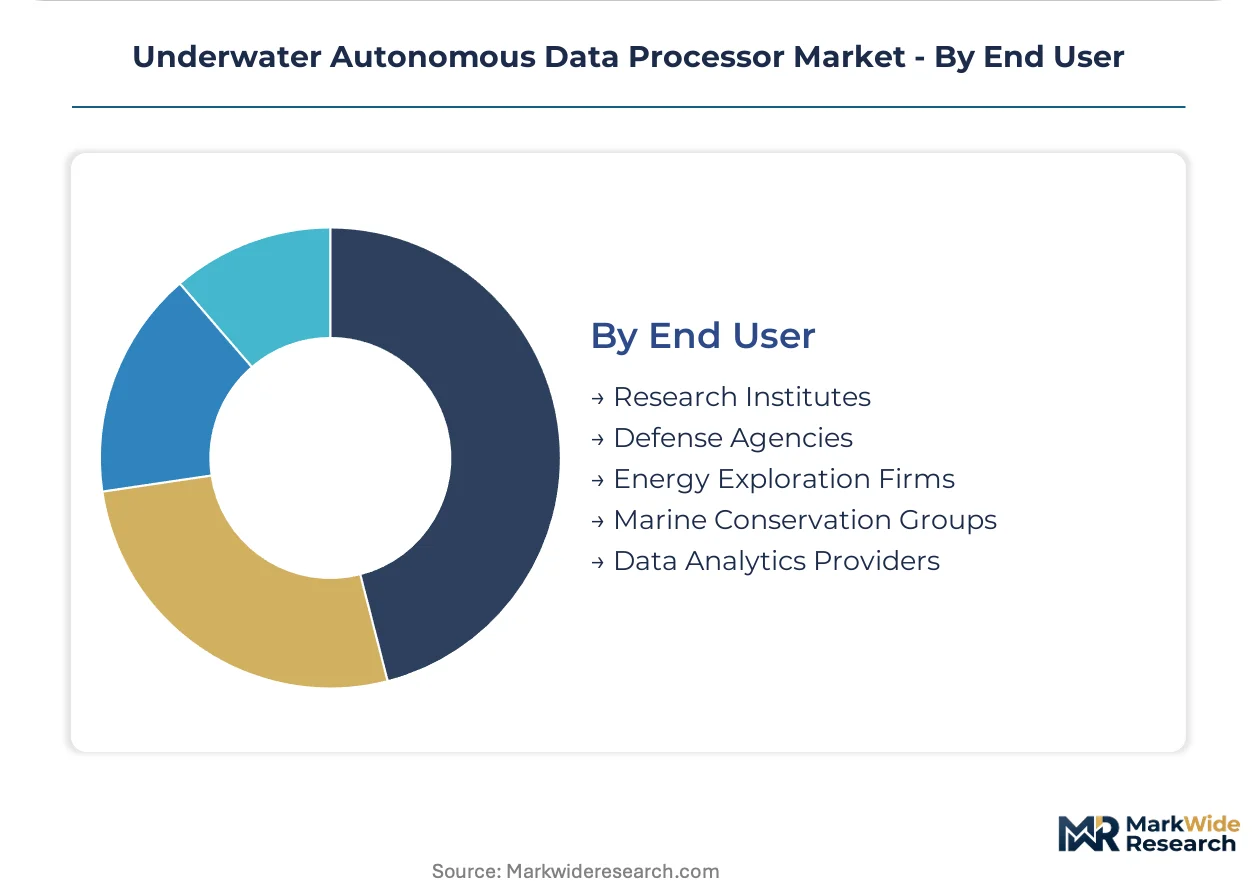
End user concentration varies by procurement sophistication—defense agencies specify hardened edge architectures, while research institutes prioritize reconfigurable platforms for multi-mission flexibility.
- Defense Agencies:Military and coast guard organizations requiring certified subsea computing for mine warfare and infrastructure protection. Norway and the United States anchor procurement volumes, with Pacific naval testing ranges and Arctic defense circles representing contiguous demand corridors.
- Energy Exploration Firms:Offshore operators deploying fixed seabed stations for pipeline integrity and methane leak detection. North Sea offshore energy corridors concentrate hardware volumes, where continuous sensor fusion obligations under EU Marine Strategy Framework Directive expand addressable market scope.
- Research Institutes:Academic and government laboratories conducting oceanographic and climate studies.
- Marine Conservation Groups:Non-governmental organizations monitoring protected areas and endangered species habitats.
- Data Analytics Providers:Specialized software houses unbundling firmware maintenance from hardware procurement.
Defense Agencies dominate absolute procurement spend. Data Analytics Providers are expanding most quickly through subscription-based algorithm update models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Navy's Unmanned Maritime Autonomy Architecture anchors procurement volumes across the Pacific naval testing ranges, where real-time onboard classification mandates for mine countermeasures concentrate hardware demand. Norway's maritime cluster sustains deep institutional knowledge in subsea acoustics, while EU regulatory frameworks reshape certification pathways for seabed infrastructure monitoring.
United States
Pacific naval testing ranges drive procurement of pressure-hardened edge processors for latency-sensitive mine-hunting missions. The US Navy's Unmanned Maritime Autonomy Architecture mandates real-time onboard classification, accelerating adoption of distributed computing nodes. Defense contractors cluster around coastal engineering corridors from Virginia to California.
Norway
North Sea offshore energy corridors demand continuous sensor fusion for methane seep detection and pipeline integrity monitoring. The Norwegian maritime cluster concentrates hydrographic engineering talent in Kongsberg and Horten, sustaining specialized firmware development for Arctic defense applications. EU Marine Strategy Framework Directive obligations expand fixed seabed station deployments.
Germany
Baltic seabed survey operations and naval modernization programs pull multi-spectral data processing hardware into defense procurement channels. ATLAS ELEKTRONIK GmbH anchors industrial capacity in Bremen, where REACH substance restrictions are eliminating legacy potting compound chemistries from European-sourced hardware. The country's central bank monitors capital flows into dual-use subsea technology.
United Kingdom
North Sea cable protection monitoring and offshore decommissioning surveys sustain demand for autonomous pipeline inspection systems. BAE Systems represents defense-industrial capacity concentrated in southern England, where the country's national maritime regulator enforces subsea infrastructure protection standards. Scottish waters host deep-water testing facilities for full-ocean-depth processor validation.
France
Mine countermeasure modernization and seabed warfare preparedness drive procurement through defense procurement agency channels. ECA Group exemplifies specialized industrial capacity in Toulon and Brittany, where photonic interconnect convergence research receives state-backed innovation funding. The country's environmental regulator enforces marine strategy obligations for continuous subsea surveillance.
Underwater Autonomous Data Processor Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated defense primes controlling high-volume procurement channels while niche engineering houses capture premium-margin firmware maintenance contracts. The market structure reflects dual-domain expertise scarcity, where sonar physics competency rarely overlaps with embedded systems engineering. Three archetypes dominate: vertically integrated maritime conglomerates with captive semiconductor fabrication, specialized defense electronics subsidiaries with classified program access, and software-focused algorithm houses unbundling subscription-based model updates. Competitive moves concentrate on strategic partnerships for photonic interconnect development and geographic expansion into Arctic defense circles.
Within the integrated maritime tier, Kongsberg Maritime and Teledyne Technologies Incorporated exemplify divergent supply chain strategies—one leveraging Norwegian cluster depth in subsea acoustics, the other anchoring North American capacity through pressure-hardened processor fabrication. SAAB AB occupies a specialist position in Baltic and Arctic defense procurement, representing the firmware-centric archetype where signal-processing intellectual property creates defensive moats against hardware commoditization.
| Leading Market Players |
|---|
| Kongsberg Maritime |
| Teledyne Technologies Incorporated |
| SAAB AB |
| BAE Systems |
| Lockheed Martin Corporation |
| Fugro |
| ATLAS ELEKTRONIK GmbH |
| ECA Group |
| L3Harris Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Silicon photonics modulators displacing copper interconnects in next-generation AUV swarms are simultaneously redrawing procurement geography toward Taiwan and South Korea while compressing margin structures for legacy signal-processing hardware. Defense agencies now demand 100x bandwidth expansion without proportional cost escalation, forcing tiered pricing stratification across pressure-rated performance tiers.
Pricing Analysis
Long-term offtake contracts dominate procurement between defense primes and titanium alloy suppliers, though spot purchasing persists for REACH-compliant potting compound formulations. Three-tier pricing structure across full-ocean-depth, mid-depth, and shallow-water certification levels reflects divergent thermal design power constraints and hyperbaric chamber validation timelines. Cost compression in mid-depth tiers is intensifying because energy exploration firms unbundle firmware maintenance from hardware procurement. Research institutes exhibit highest price sensitivity due to grant-funded procurement cycles, while defense agencies accept premium pricing for classified program access.
Supply Chain Analysis
Six-month hyperbaric chamber testing timelines tie up capital in pre-certified inventory, extending lead times for pressure-hardened processor modules. Fabrication concentrates in Norway, the United States, and Germany, drawing from Russian and Chinese sponge titanium, Japanese ceramic substrates, and Taiwanese 7nm foundry capacity. Single-source vulnerability around titanium alloy supply exposes lead times to geopolitical disruption. Distribution runs through defense procurement agencies and energy sector system integrators with divergent compliance timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photonic interconnect convergence threatens to commoditize legacy acoustic signal-processing hardware, forcing incumbents to defend proprietary firmware moats against silicon photonics-based substitutes.
For Market Incumbents: Consolidate backward integration into captive semiconductor fabrication for pressure-hardened processors, mirroring Teledyne Technologies Incorporated's North American supply anchoring. Deepen firmware subscription models to offset hardware margin compression from photonic interconnect substitutes. Prioritize REACH-compliant potting compound requalification to defend European defense procurement access. For New Entrants and Emerging Players: US Navy Unmanned Maritime Autonomy Architecture certification fast-tracks offer lowest barrier to entry for mine countermeasure edge processors. White-space concentrates in Arctic defense circles where Norwegian maritime cluster depth has not yet penetrated, and in seabed mining data sovereignty architectures where International Seabed Authority liability frameworks remain unresolved. Lead with software-defined subscription models rather than hardware-centric procurement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed defense electronics subsidiaries holding classified program access but lacking photonic interconnect roadmaps. Five-to-ten-year viability hinges on successful firmware-to-photonics transition rather than hardware volume scale. Monitor US Navy Pacific testing range procurement acceleration as inflection indicator for edge-native architecture demand.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Interconnect Development | Fiber-optic data links with silicon photonics modulators enable 100x bandwidth expansion for AUV swarms. |
| REACH Compliance Requalification | Halogen-free flame retardant potting compounds preserve 6,000-meter pressure integrity for EU defense procurement. |
| Firmware Subscription Unbundling | Algorithm update models shift recurring revenue from system integrators to specialized software houses. |
| Arctic Defense Circle Expansion | Norwegian maritime cluster expertise extends into Baltic and polar procurement specifications. |
| Seabed Mining Data Sovereignty | Unclear International Seabed Authority liability creates first-mover advantage in international waters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across defense procurement officers at US Navy Pacific ranges and Norwegian maritime clusters, energy exploration firm subsea engineers, hydrographic firmware developers, and pressure-vessel fabrication specialists. Secondary validation drew from US Navy Unmanned Maritime Autonomy Architecture documentation, EU Marine Strategy Framework Directive filings, REACH substance restriction updates, and International Seabed Authority jurisdiction proceedings. Bottom-up volume modeling triangulated against top-down defense budget allocation analysis.
Across the analysis window, projections integrated deployment mode segmentation across fixed stations and autonomous underwater vehicles, technology tiers spanning edge computing through traditional signal processing, and application splits between security surveillance and seismic analysis. CAGRs derived from weighted average of historical procurement trajectories and policy-mandated adoption schedules. Model inputs incorporated hyperbaric chamber testing capacity constraints, titanium alloy supply elasticity, and photonic interconnect adoption curves.
Decision-makers should treat outputs as directional under sustained US Navy procurement acceleration and stable International Seabed Authority negotiation timelines; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Oil and Gas Market
Artificial Intelligence (AI)
AI Orchestration Market
Artificial Intelligence (AI)
AI Dubbing Software Market
Artificial Intelligence (AI)
Global Artificial Intelligence Chip Market
Artificial Intelligence (AI)
AI Task Manager App Market
Artificial Intelligence (AI)
Artificial Intelligence in Robots Market
Artificial Intelligence (AI)
Autonomic Platform Market
Artificial Intelligence (AI)
AI in Fashion Market
Artificial Intelligence (AI)
AI Recruitment Market
Artificial Intelligence (AI)
Automated Data Annotation Tool Market
Artificial Intelligence (AI)
Global Deep Learning Neural Networks (Dnns) Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Robotics Market
Artificial Intelligence (AI)
Machine Learning in Pharmaceutical Industry Market
Artificial Intelligence (AI)
Context Aware Computing Market
Artificial Intelligence (AI)
Global AI in Social Media Market
Artificial Intelligence (AI)
Global Artificial Intelligence SAAS Market