
 No-Code AI Platform Market | 2026-2036
No-Code AI Platform Market Size, Share, and Industry Trends Forecast 2026-2036
No-Code AI Platform Market Foresight
The no-code AI platform landscape is consolidating around a sharp split between premium enterprise suites with governance layers and commodity self-service tools priced for individual developers. Mendix anchors the high end through deep SAP integration and manufacturing sector dominance. Zapier competes at the volume tier by extending connectivity across thousands of SaaS endpoints without coding requirements. Microsoft Power Apps leverages Azure infrastructure to sustain hybrid deployment flexibility that appeals to regulated industries.
A no-code AI platform provides visual development environments where users configure machine learning models, automate workflows, and build applications through drag-and-drop interfaces rather than programming languages, typically incorporating pre-trained APIs, data pipeline builders, and model governance dashboards. The platform serves commercial purposes by collapsing development cycles from months to days while embedding compliance checkpoints for non-technical operators. Public cloud deployment leads volume adoption due to elastic scaling and minimal infrastructure overhead, though private cloud configurations capture margin pools in financial services and healthcare where data residency rules apply. Business automation applications dominate current revenue, while customer engagement segments show faster trajectory as marketing teams deploy sentiment analysis and personalized recommendation engines without engineering dependencies.
The EU AI Act imposes risk-tiered conformity obligations on automated systems deployed in European markets, compelling platform vendors to embed audit trails and human oversight mechanisms. In the United States, the FDA scrutinizes AI-enabled diagnostic tools while the SEC examines algorithmic trading applications built on no-code infrastructure, creating divergent compliance architectures across jurisdictions. Stakeholders must monitor how rapidly evolving liability frameworks assign responsibility between platform providers and end users when automated decisions produce harmful outcomes.
Market Dynamics
The no-code AI platform market is bifurcating around governance depth, with EU AI Act compliance requirements forcing vendors to embed audit infrastructure that mid-market buyers now demand as table stakes rather than premium add-ons.
Growth Catalysts
- Healthcare diagnostic automation:Providers in the United States are deploying visual workflow builders to compress radiology report generation cycles without expanding engineering headcount.
- EU AI Act conformity infrastructure:Risk-tiered obligations for automated decision-making systems are creating procurement mandates for platforms with pre-built human oversight mechanisms and documentation pipelines.
- Mid-market enterprise demand concentration:United States-based firms with 500-5,000 employees are prioritizing rapid deployment models that eliminate dependency on specialized machine learning engineering teams.
Market Restraints
- Compute cost volatility:GPU cluster pricing fluctuations directly compress margins for vendors offering elastic model training as a bundled service.
- Data residency fragmentation:Divergent national requirements for financial services and healthcare data localization force redundant infrastructure deployment across sovereign cloud zones.
- Model interpretability ceilings:Black-box neural architectures in pre-trained APIs create liability exposure under emerging algorithmic accountability frameworks.
Strategic Opportunities
- Private cloud healthcare configurations:Germany and France present whitespace for HIPAA-equivalent deployments serving hospital networks with strict data sovereignty requirements.
- Customer engagement sentiment engines:Marketing teams in retail and hospitality verticals are adopting drag-and-drop recommendation builders that bypass traditional IT queue bottlenecks.
- Hybrid deployment flexibility:Azure infrastructure integration appeals to regulated industries seeking workload portability between on-premises and public cloud environments.
Industry Challenges
- MLOps skill scarcity:Platform vendors struggle to hire personnel capable of bridging visual interface design with underlying model governance architecture.
- Legacy system integration friction:Mainframe data pipelines in banking and insurance resist standard API connectivity, extending implementation timelines.
- Cross-jurisdictional compliance timing:Simultaneous FDA diagnostic tool scrutiny and SEC algorithmic trading examination create conflicting development priorities for multi-use platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | No-Code AI Platform Market |
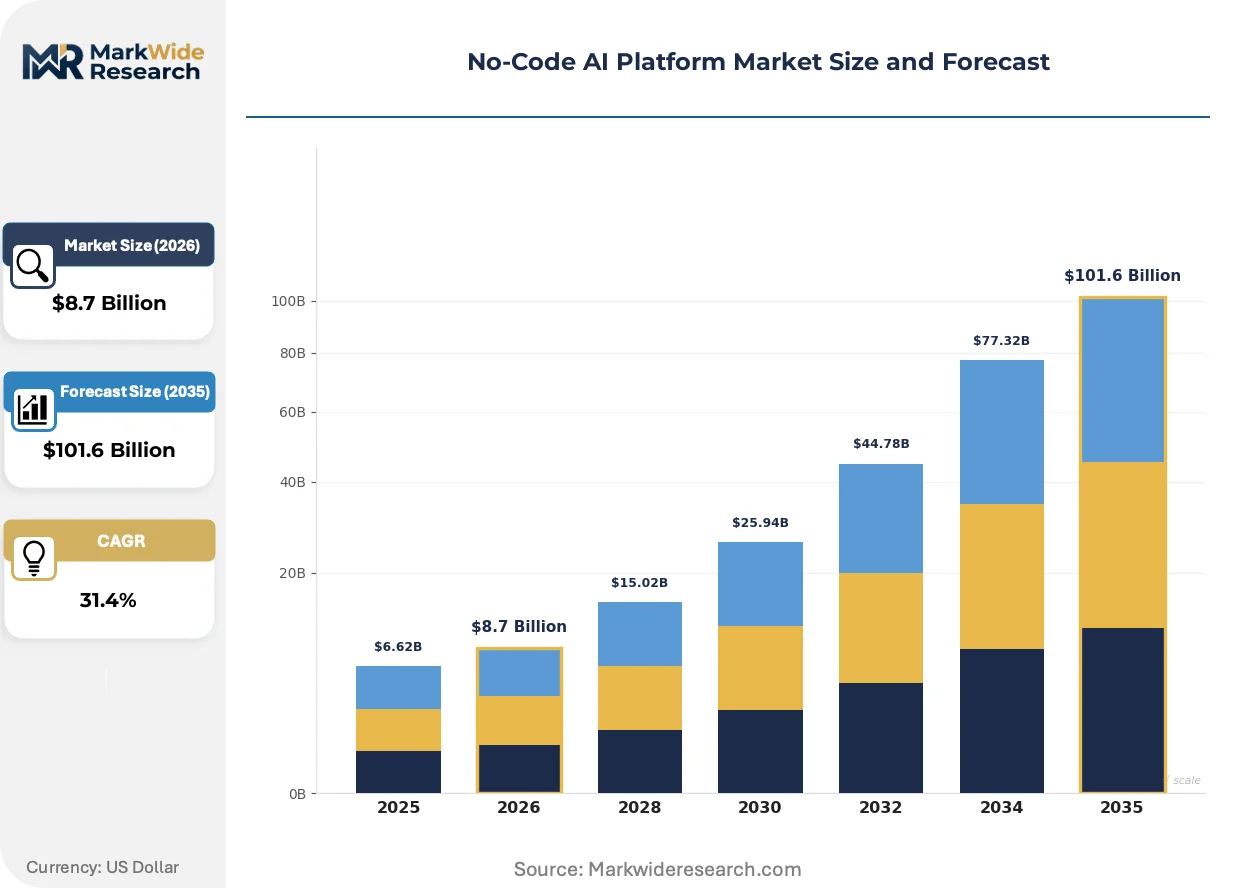
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $101.6 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Business Automation, Workflow Management, Data Analytics, Customer Engagement Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: SMEs, Large Enterprises, Independent Developers, Corporates Service Type: Technical Support, Training Services, Integration Services, Consulting |
| Companies Covered | Mendix, Replit, Microsoft Power Apps, Blaze.tech, Airtable, Zapier, OutSystems, Appian, Bubble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
No-Code AI Platform Market Shifts & Advancements
Pre-trained large language models are commoditizing natural language interfaces, forcing platform differentiation toward vertical-specific compliance templates rather than raw model performance benchmarks.
Generative AI capabilities are converging with visual workflow orchestration, enabling non-technical users to construct multi-step automation chains that previously required Python scripting. Manufacturing quality control teams in Germany and the United States are adopting these interfaces fastest, compressing defect detection deployment from quarters to weeks. The structural consequence is displacement of traditional RPA vendors who lack native machine learning model hosting.
The EU AI Act's risk classification system is mandating conformity assessment procedures for high-risk automated decision systems, compelling platform vendors to embed technical documentation generators and human-in-the-loop checkpoints. Financial services deployments across France, Germany, and the Netherlands face the steepest compliance ramps. Vendors are responding by pre-certifying sector-specific template libraries that accelerate audit readiness.
Enterprise procurement of no-code AI capabilities is consolidating around outcome-based engagement models where platform fees tie to measurable workflow efficiency gains rather than seat licenses. Mid-market professional services firms in the United States are driving this shift, pressuring vendors to embed usage analytics that validate return claims. The channel disruption is most visible in healthcare and legal verticals where traditional IT consulting margins are compressing.
No-Code AI Platform Market Segmentation
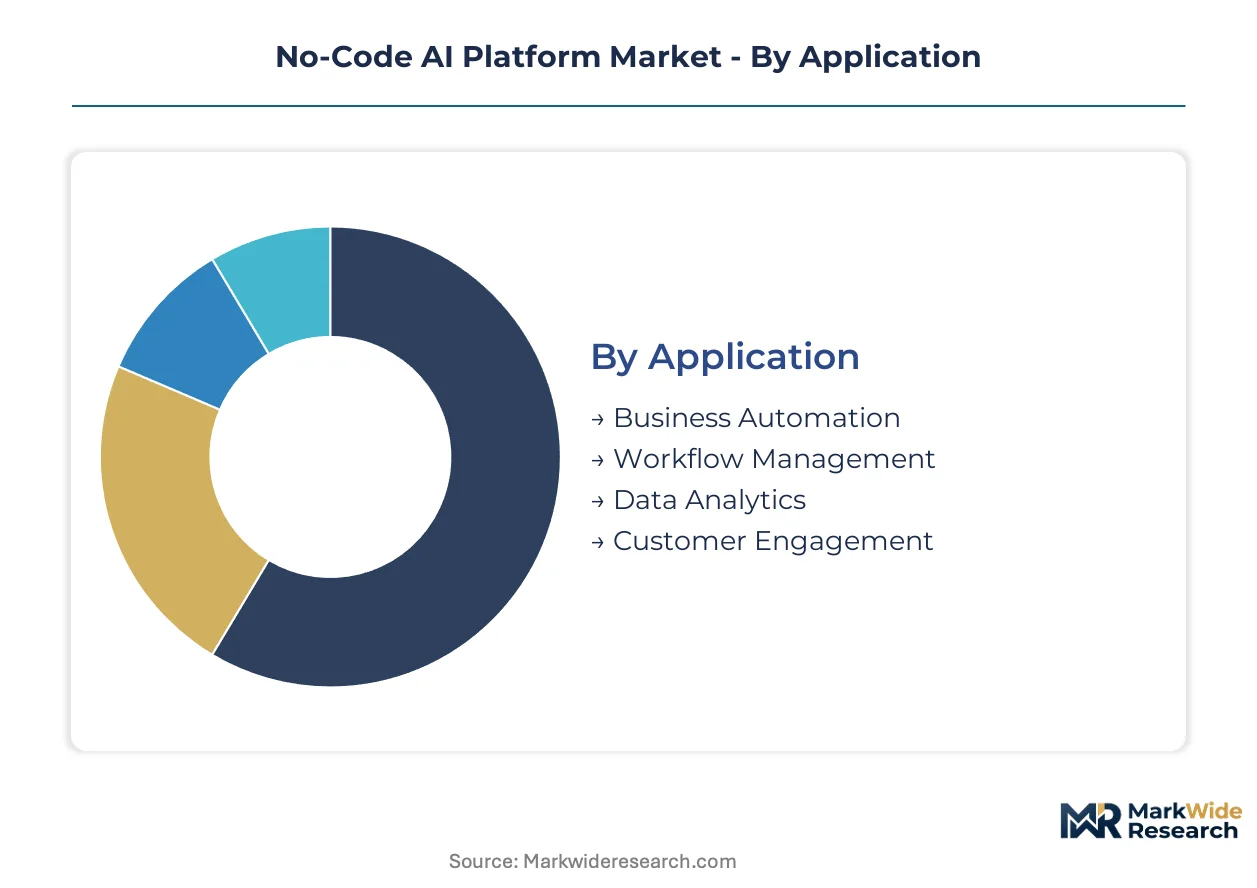
No-code AI platforms fragment across four critical dimensions that determine procurement patterns and margin architecture. Application focus dictates compliance requirements, while deployment models anchor data sovereignty commitments. End user scale shapes pricing mechanics, and service depth separates transactional vendors from strategic partners.
Application:
Supply concentration clusters around workflow automation tools that compress implementation cycles for mid-market buyers.
- Business Automation:Visual workflow builders orchestrate document processing, approval chains, and resource allocation without Python dependencies. United States healthcare providers deploy these for radiology report generation, driven by FDA scrutiny of diagnostic AI tools.
- Workflow Management:Drag-and-drop interfaces connect disparate SaaS endpoints into unified process pipelines. German manufacturing quality control teams adopt fastest, compressing defect detection deployment from quarters to weeks under EU AI Act conformity pressure.
- Data Analytics:Pre-trained model APIs enable sentiment classification and forecasting without engineering headcount.
- Customer Engagement:Recommendation engines and chatbot builders serve retail marketing teams bypassing IT queues.
Today's leader: Business Automation. Tomorrow's challenger: Customer Engagement.
Deployment Model:
Cost tier separation is pronounced between elastic public offerings and sovereign private configurations.
- Public Cloud:Elastic GPU scaling minimizes infrastructure overhead for model training workloads. United States mid-market enterprises with 500-5,000 employees prioritize this tier for rapid deployment without capital expenditure.
- Private Cloud:Isolated tenant environments satisfy HIPAA-equivalent requirements in French and German hospital networks. Data residency fragmentation forces redundant infrastructure deployment across sovereign zones.
- Hybrid Cloud:Azure-integrated workloads appeal to regulated industries seeking portability between on-premises and public environments.
- On-Premises:Air-gapped installations serve defense and intelligence sector buyers with classified data constraints.
Volume dominance: Public Cloud. Margin concentration: Private Cloud.
End User:
Customer type stratification reveals divergent purchasing authority and technical sophistication levels.
- SMEs:Seat-based licensing with pre-built templates dominates procurement. Outcome-based engagement models are gaining traction among United States professional services firms demanding workflow efficiency guarantees.
- Large Enterprises:Governance-layer requirements and audit trail mandates drive premium suite adoption. EU AI Act risk-tiered conformity obligations are now table stakes rather than add-ons.
- Independent Developers:Individual subscription tiers emphasize API accessibility and community documentation.
- Corporates:Divisional purchasing with centralized IT oversight creates complex approval workflows.
Fastest expansion: SMEs. Deepest contract value: Large Enterprises.
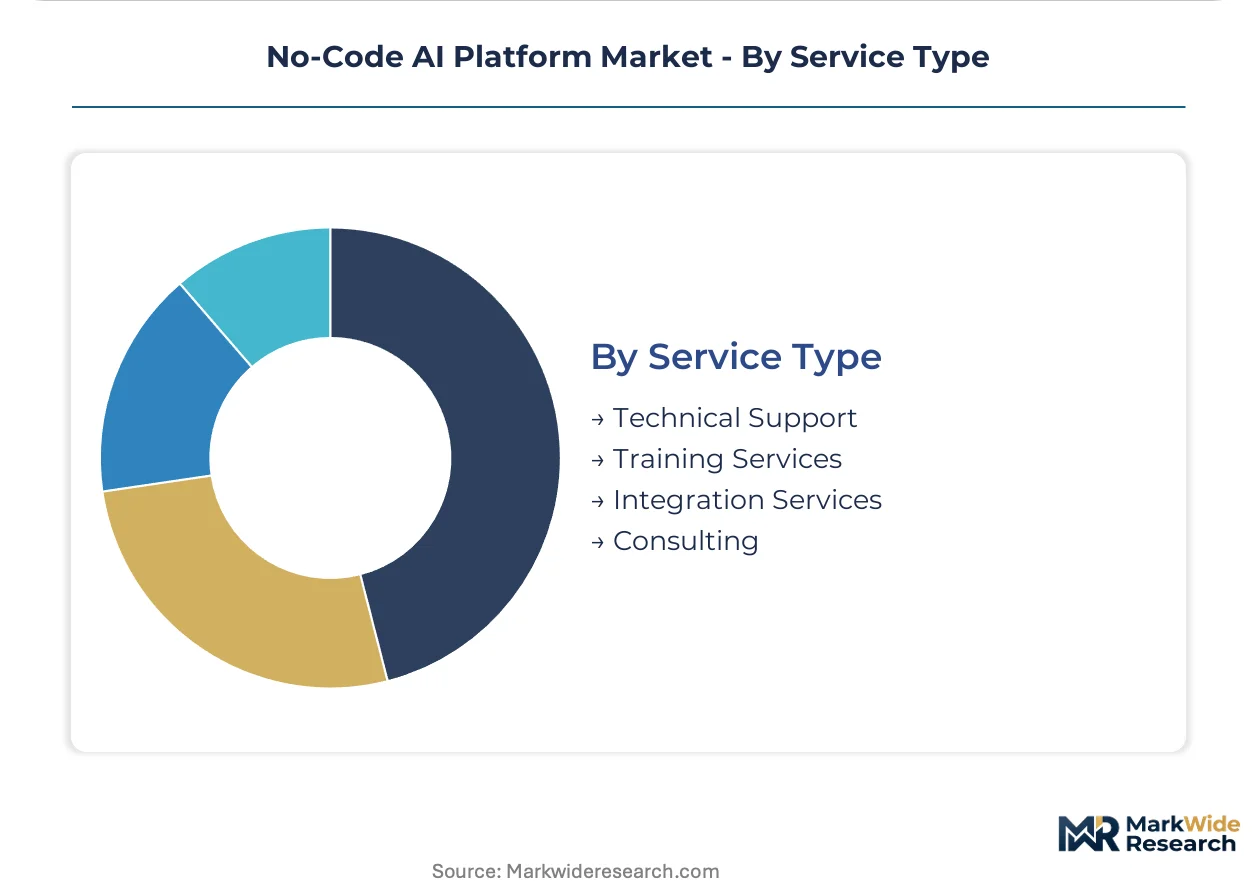
Service Type:
Margin pools concentrate in integration services where legacy system friction extends engagement duration.
- Technical Support:Tiered response SLAs separate premium from standard offerings. Banking mainframe connectivity issues drive escalation volume.
- Training Services:Certification programs for non-technical operators address MLOps skill scarcity in platform vendor hiring.
- Integration Services:Custom API development for legacy data pipelines in insurance and banking commands highest hourly rates.
- Consulting:Strategic advisory on compliance architecture spans FDA diagnostic tool pathways and SEC algorithmic trading examination.
Revenue anchor: Integration Services. Growth vector: Consulting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machine learning engineering talent concentrates in the United States, Germany, and India, anchoring platform development and enterprise adoption clusters across distinct regulatory environments.
United States
Mid-market enterprises with 500-5,000 employees drive demand for rapid deployment models that bypass specialized engineering teams. The FDA scrutinizes AI-enabled diagnostic tools while the SEC examines algorithmic trading applications, creating divergent compliance architectures. Healthcare providers in Boston and San Francisco deploy visual workflow builders for radiology report generation cycles.
Germany
Manufacturing quality control teams adopt drag-and-drop defect detection interfaces fastest under EU AI Act conformity pressure. The EU AI Act imposes risk-tiered conformity obligations compelling audit trail and human oversight mechanisms. Industrial clusters in Bavaria and Baden-Württemberg compress deployment timelines from quarters to weeks.
France
Financial services deployments face steep compliance ramps for high-risk automated decision systems. ANSM and CNIL oversight intersects with EU AI Act technical documentation requirements. Paris-based banking networks demand pre-certified sector-specific template libraries that accelerate audit readiness.
United Kingdom
Professional services firms press vendors toward outcome-based engagement models tying platform fees to measurable workflow efficiency gains. Post-Brexit regulatory divergence from EU AI Act frameworks creates procurement uncertainty. London's legal and consulting verticals compress traditional IT consulting margins through self-service adoption.
India
Technology services hubs supply MLOps talent to platform vendors struggling with skill scarcity in visual interface design. BIS standards and RBI guidelines shape data localization requirements for financial services deployments. Bangalore and Hyderabad development centers bridge governance architecture with consumer-grade usability.
No-Code AI Platform Market Competitive Landscape
Capital-heavy infrastructure providers compete with asset-light platform designers across a bifurcated market structure. The landscape consolidates around premium enterprise suites with governance layers and commodity self-service tools priced for individual developers. Three archetypes dominate: SAP-integrated manufacturing specialists, SaaS connectivity aggregators, and Azure-leveraged hybrid deployment providers. Competitive moves concentrate on embedding compliance infrastructure and extending vertical-specific template libraries.
Within the enterprise governance tier, Mendix and OutSystems exemplify deep ERP integration strategies, while Zapier occupies the volume-tier position for SaaS endpoint connectivity. Microsoft Power Apps anchors the hybrid deployment vector through cloud infrastructure relationships. These three represent distinct strategic postures rather than interchangeable substitutes, with procurement decisions hinging on existing technology stack commitments and regulatory exposure profiles.
| Leading Market Players |
|---|
| Mendix |
| Replit |
| Microsoft Power Apps |
| Blaze.tech |
| Airtable |
| Zapier |
| OutSystems |
| Appian |
| Bubble |
| Others |
Supply & Pricing Matrix
GPU cluster pricing indices cascade directly through no-code AI platform margins, compressing bundled model-training services while pushing buyers toward unbundled API-only tiers that strip out elastic compute overhead.
Pricing Analysis
The bundled-vs-unbundled service split separates enterprise buyers seeking governance-heavy suites from individual developers consuming commodity APIs. Three-tier pricing structure across premium, standard, and economy levels anchors on compliance certification depth, with EU AI Act conformity documentation commanding substantial premiums. Cost compression in the mid-market tier is intensifying because hyperscaler infrastructure partnerships reduce switching costs. SME procurement teams show highest price sensitivity, while large enterprise legal and risk officers prioritize audit-ready configurations regardless of seat cost.
Supply Chain Analysis
Freight cost volatility for specialized AI accelerator hardware from Taiwan and South Korea feeds into delivery timelines for on-premises deployments. Cloud infrastructure provisioning centers on United States, Germany, and India, with model training workloads drawing from NVIDIA GPU supply chains and sovereign cloud zone buildouts. Single-source vulnerability around advanced semiconductor fabrication creates procurement risk for vendors promising elastic scaling. Distribution runs through direct enterprise sales teams for governance-tier suites and self-service marketplaces for developer-tier subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
No-code AI platform procurement has shifted toward late-cycle quality specifications, with EU AI Act conformity infrastructure now table stakes rather than premium add-ons for European deployments.
For Market Incumbents: Lock in manufacturing sector dominance through deeper SAP integration and pre-certified industrial templates that neutralize emerging vertical-specialist challengers. Prioritize backward integration into sovereign cloud infrastructure across Germany and France to defend margin position against hyperscaler commoditization.
For New Entrants and Emerging Players: Self-service developer marketplaces offer the most penetrable white-space for asset-light entrants, with sentiment analysis APIs for retail marketing teams presenting faster revenue ramps than workflow automation. Pursue outcome-based pricing pilots with United States professional services firms to bypass entrenched IT consulting relationships.
For Investors and Strategic Acquirers: Asymmetric upside sits with private-cloud healthcare configuration specialists possessing HIPAA-equivalent deployments in French and German hospital networks. The inflection signal to watch is FDA diagnostic tool approval velocity for platforms with pre-built radiology workflow templates.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Pre-certification accelerates audit readiness for financial services deployments across France, Germany, and the Netherlands. |
| Healthcare Workflow Template Library | FDA-aligned radiology automation compresses hospital procurement cycles in Boston and San Francisco clusters. |
| Hybrid Cloud Infrastructure Partnership | Azure integration captures regulated industry demand for workload portability between on-premises and public environments. |
| Manufacturing Quality Control Integration | Drag-and-drop defect detection interfaces displace traditional RPA vendors in Bavaria and Baden-Württemberg industrial zones. |
| Outcome-Based Engagement Model | Workflow efficiency guarantees align vendor fees with measurable gains in United States mid-market professional services. |
Research Methodology
Coverage spans North America, Western Europe, and South Asia, with primary inputs from each region combined with secondary validation. Interviews with platform engineering leads, healthcare IT procurement officers, manufacturing operations directors, and regulatory compliance specialists informed demand-side assumptions. Secondary sources include SEC filings from listed platform vendors, EU AI Act implementation guidance documents, FDA diagnostic AI guidance publications, and hyperscaler infrastructure capex disclosures. Bottom-up sizing of deployment volumes triangulates against top-down market value estimates.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical application, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to disclosed vendor revenues and inferred customer acquisition trajectories. Forecast inputs incorporate GPU pricing volatility assumptions and EU AI Act enforcement timeline scenarios.
Regulatory enforcement delays, hyperscaler pricing wars, and enterprise budget contraction are the dominant revision risks for projections across the analysis window. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
US Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Automotive Predictive Diagnostic System Market
Artificial Intelligence (AI)
Global Aiops Platform Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Radiology Market
Artificial Intelligence (AI)
Cognitive Services Platform Market
Artificial Intelligence (AI)
AI in Robotics Market
Artificial Intelligence (AI)
Global AI Governance Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Robotics Market
Artificial Intelligence (AI)
AI Orchestration Market
Artificial Intelligence (AI)
Permission-Aware AI Repository Gateway Market
Artificial Intelligence (AI)
Artificial Intelligence in Transportation Market
Artificial Intelligence (AI)
AI Demand Forecasting Software Market
Artificial Intelligence (AI)
Saudi Arabia Big Data and Artificial Intelligence Market
Artificial Intelligence (AI)
Automated Data Annotation Tool Market
Artificial Intelligence (AI)
Deep Learning Market