
 Machine Learning in Pharmaceutical Industry Market | 2026-2036
Machine Learning in Pharmaceutical Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Learning in Pharmaceutical Industry Market Foresight
Platform licensing revenue is tilting away from perpetual software contracts toward usage-based arrangements tied to molecule progression milestones. Insilico Medicine leverages its generative chemistry stack to anchor long-term partnerships with major pharmaceutical companies. Recursion Pharmaceuticals sustains one of the largest proprietary biological datasets, which dominates its competitive position in phenomic screening. Exscientia differentiates through autonomous drug design capabilities that control end-to-end candidate optimization timelines.
Machine learning in pharmaceutical industry denotes the application of statistical algorithms and neural architectures to molecular data, clinical records, and biological imagery in order to predict drug behavior, identify targets, and optimize trial design; these systems typically process high-dimensional datasets exceeding ten thousand features per compound and require GPU-accelerated training infrastructure to converge within practical development windows. Predictive analytics holds the most mature margin pool among product types, as pharmaceutical companies have deployed regression and ensemble methods for adverse-event forecasting for over a decade. Natural language processing is expanding fastest across application areas, with clinical-trial matching and regulatory document mining driving new contract growth. Deep learning architectures command premium pricing within the technology dimension, though support vector machines retain substantial installed base in smaller biotech firms with limited computational budgets.
FDA guidance on AI and machine learning in drug development, alongside EMA reflection papers on big data in clinical trials, establishes the dual compliance perimeter that vendors must satisfy for transatlantic market access. ISO standards for medical device software and IEC risk management frameworks further constrain system validation protocols for patient-facing applications. Stakeholders must monitor how regulatory convergence between FDA and EMA on algorithmic transparency requirements reshapes competitive barriers for emerging entrants.
Market Dynamics
Generative chemistry platforms are compressing molecular design cycles from years to months, forcing pharmaceutical companies to restructure R&D partnerships around milestone-based licensing rather than fixed-fee software subscriptions.
Growth Catalysts
- EMA reflection papers on big data:The European Medicines Agency's guidance on real-world evidence integration creates compliance clarity that accelerates vendor procurement across EU member states.
- Phenomic screening demand:Biotech clusters in Boston and San Francisco are expanding contracts for high-content cellular imaging platforms that automate target validation workflows.
- GPU infrastructure commoditization:Cloud-based tensor processing unit availability is lowering the capital barrier for mid-size pharmaceutical firms to deploy deep learning architectures.
Market Restraints
- Algorithmic validation costs:ISO 14971 risk management frameworks for patient-facing applications impose documentation burdens that extend deployment timelines by 18-24 months.
- Training data scarcity:Proprietary biological datasets remain concentrated among a handful of contract research organizations, creating input bottlenecks for new market entrants.
- Regulatory divergence:Misalignment between FDA guidance on AI-enabled drug development tools and EMA algorithmic transparency requirements forces dual-track compliance investments.
Strategic Opportunities
- Clinical-trial matching automation:Natural language processing applications for patient recruitment remain underdeployed outside the United States, particularly in Germany and Japan where site activation lags.
- Adverse-event forecasting:Predictive analytics for pharmacovigilance represents a greenfield application in emerging biotech firms lacking legacy signal detection infrastructure.
- EU AI Act compliance services:The European Union's risk-based classification system for medical device software creates a service layer opportunity for validation consultancies.
Industry Challenges
- Computational biology talent scarcity:The intersection of cheminformatics expertise and neural architecture engineering remains critically understaffed across pharmaceutical R&D functions.
- Legacy system integration:Electronic laboratory notebook platforms and decades-old compound registration databases resist API connectivity with modern ML pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Learning in Pharmaceutical Industry Market |
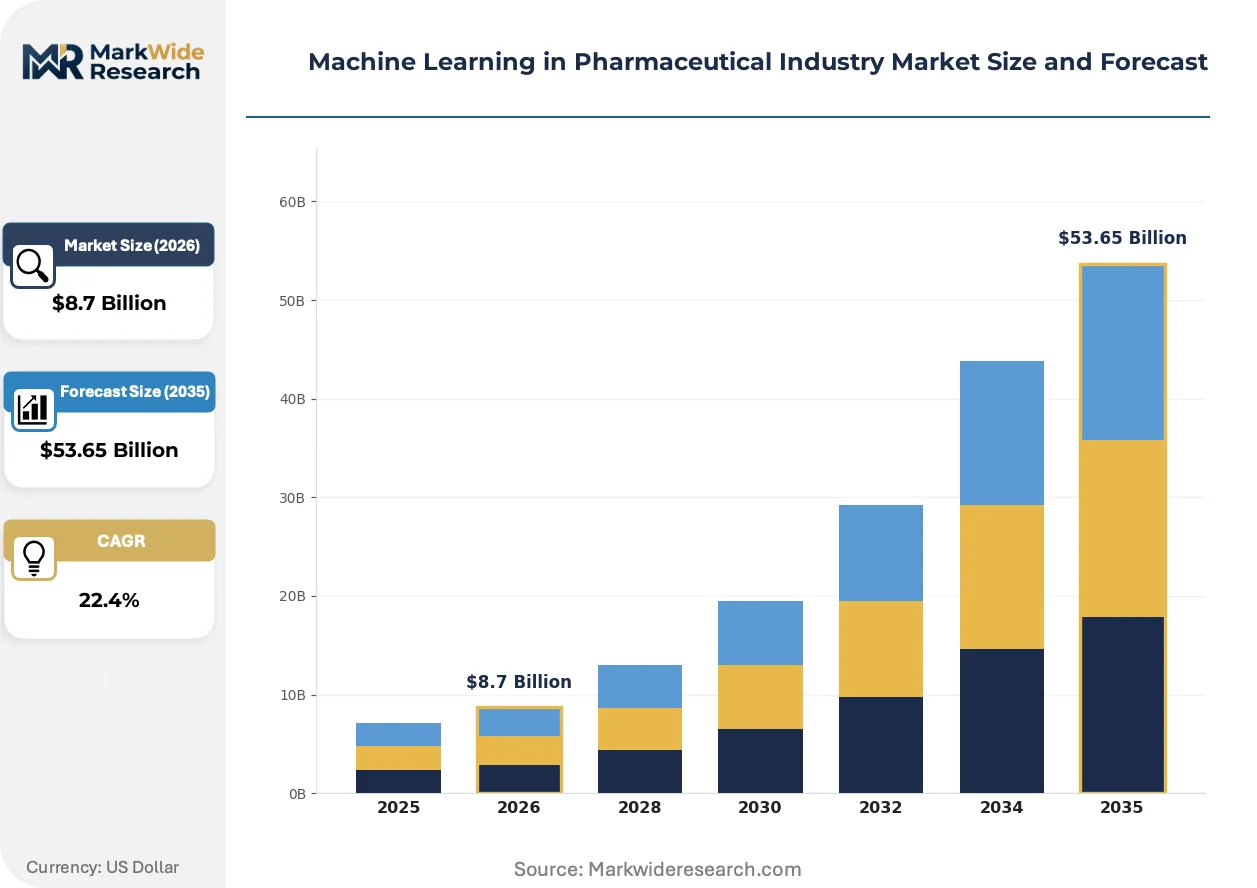
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Predictive Analytics, Natural Language Processing, Computer Vision, Reinforcement Learning Application: Drug Discovery, Clinical Trials, Patient Monitoring, Personalized Medicine Technology: Deep Learning, Neural Networks, Decision Trees, Support Vector Machines End User: Pharmaceutical Companies, Research Institutions, Healthcare Providers, Biotech Firms |
| Companies Covered | Insilico Medicine, Recursion Pharmaceuticals, Deep Intelligent Pharma, Generate Biomedicines, Exscientia, Tempus, Nabla Bio, BenevolentAI, Owkin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Learning in Pharmaceutical Industry Market Shifts & Advancements
Foundation models trained on molecular representations are redefining how pharmaceutical companies allocate R&D capital, shifting investment from high-throughput screening infrastructure toward generative model fine-tuning and proprietary dataset construction.
Diffusion models for de novo molecular generation are rendering obsolete traditional structure-based virtual screening workflows that dominated the 2010s. Large pharmaceutical companies are adopting these architectures within 12-18 month procurement cycles. The structural consequence is collapsing early-stage chemistry timelines and compressing competitive windows for target validation.
REACH registration requirements for computational toxicology predictions are forcing vendors to document training data provenance and model uncertainty quantification methods. This industrial consequence elevates compliance costs for European market access. Contract research organizations serving EMA submissions are responding by building in-house explainability engineering teams.
Biopharma procurement departments are unbundling software licenses from professional services, demanding modular API access priced per compound processed rather than annual seat subscriptions. This pattern disrupts traditional enterprise SaaS vendors and elevates usage-based infrastructure providers. The shift is most visible among mid-cap biotech firms in the United States with venture-backed burn rate constraints.
Machine Learning in Pharmaceutical Industry Market Segmentation
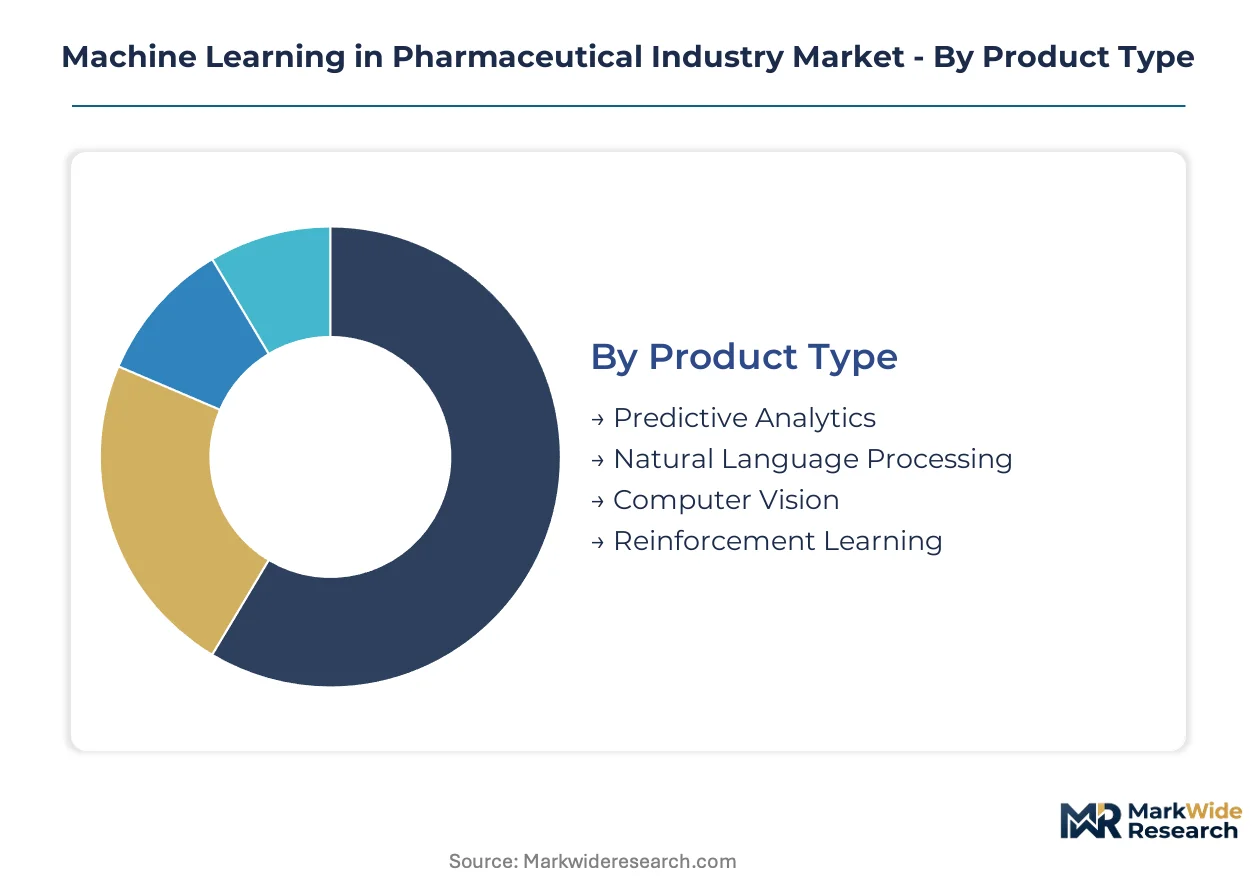
Machine learning deployments in pharmaceutical R&D fragment across distinct technical architectures and operational use cases. Procurement patterns diverge sharply between early-stage discovery teams seeking generative chemistry tools and late-stage development groups prioritizing regulatory-grade predictive models.
Product Type:
Use-case spectrum spans retrospective signal detection through prospective molecular generation, with each product category commanding different pricing power and integration complexity.
- Predictive Analytics:Regression and ensemble methods forecast adverse events, patient stratification, and trial dropout probabilities from structured clinical databases. Pharmaceutical companies in the United States anchor demand for pharmacovigilance applications, though ISO 14971 validation requirements extend deployment timelines substantially.
- Natural Language Processing:Transformer architectures extract entities from regulatory filings, mine literature for target hypotheses, and match patients to trial protocols. Contracts are concentrating in Boston and San Francisco biotech clusters where site activation velocity determines competitive positioning.
- Computer Vision:Convolutional networks classify cellular microscopy images and histopathology slides for target validation workflows.
- Reinforcement Learning:Trial-and-error optimization protocols design adaptive dosing regimens and personalized treatment policies.
The dominant share belongs to Predictive Analytics, while Natural Language Processing is closing the gap fastest.
Application:
Commercial maturity cascades from target identification through commercial launch, with each phase presenting distinct data infrastructure requirements and regulatory exposure.
- Drug Discovery:Generative models propose novel molecular scaffolds, predict binding affinity, and optimize ADMET properties before synthesis. Demand clusters among venture-backed biotech firms in San Francisco seeking to compress hit-to-lead timelines against burn rate constraints.
- Clinical Trials:Bayesian adaptive designs, synthetic control arm construction, and patient recruitment automation reshape trial economics. FDA guidance on AI-enabled drug development tools shapes vendor selection criteria for United States-based sponsors.
- Patient Monitoring:Real-world data pipelines track treatment adherence and detect safety signals post-authorization.
- Personalized Medicine:Biomarker-driven dosing algorithms segment populations by predicted response.
Drug Discovery commands the largest contract value, yet Clinical Trials exhibits the steepest expansion trajectory as regulatory acceptance of algorithmic endpoints broadens.
Technology:
Computational intensity and interpretability requirements segment technology choices across organizational resource constraints and risk tolerance profiles.
- Deep Learning:Multi-layer neural architectures process high-dimensional molecular representations and imaging data with minimal feature engineering. GPU infrastructure commoditization via cloud TPU availability lowers capital barriers for mid-size pharmaceutical firms deploying these systems.
- Neural Networks:Feedforward and recurrent architectures underpin generative chemistry platforms and sequence-based target prediction.
- Decision Trees:Interpretable ensemble methods dominate regulatory submissions requiring explicit decision logic documentation.
- Support Vector Machines:Kernel-based classifiers retain substantial installed base in smaller biotech firms with limited computational budgets and legacy codebases.
Deep Learning captures premium pricing, though Support Vector Machines persist in cost-constrained segments.
End User:
Buyer sophistication and procurement authority vary dramatically across organizational scale and R&D mission focus.
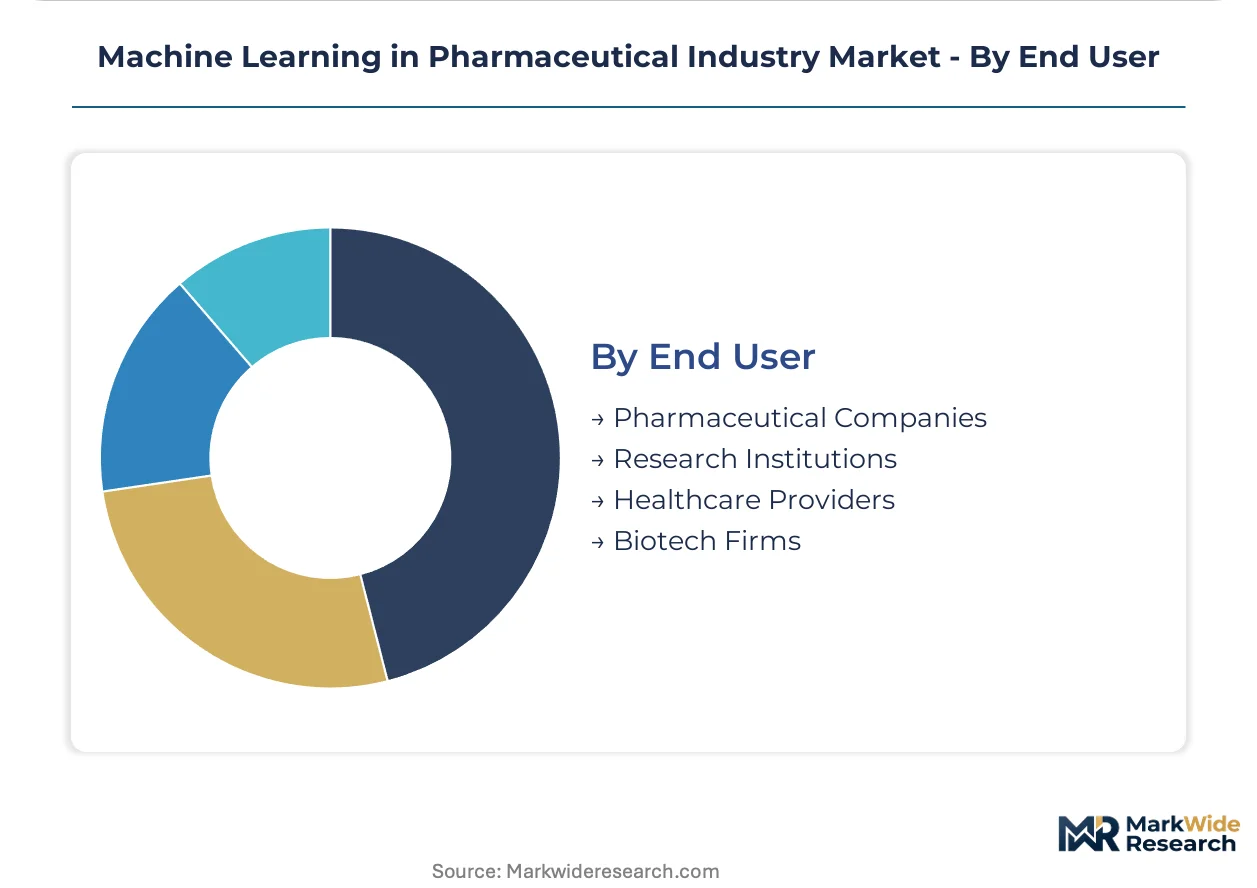
- Pharmaceutical Companies:Large-cap sponsors demand end-to-end platforms integrating discovery through regulatory submission, with procurement teams unbundling software licenses from professional services. Milestone-based pricing tied to molecule progression displaces perpetual contracts.
- Biotech Firms:Venture-backed specialists prioritize API-accessible tools priced per compound processed rather than annual seat subscriptions.
- Research Institutions:Academic centers license platforms for target validation studies with limited commercial downstream rights.
- Healthcare Providers:Hospital systems deploy clinical decision support for treatment selection and adverse event prevention.
Pharmaceutical Companies retain the dominant procurement volume, while Biotech Firms are gaining share fastest as venture funding concentrates in ML-native discovery platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States and Switzerland demonstrate the lowest price elasticity, absorbing premium pricing for regulatory-grade platforms, while mid-cap biotech firms in India and Southeast Asia drive hard bargains on API-accessible tools.
United States
FDA guidance on AI-enabled drug development tools anchors procurement decisions for large pharmaceutical sponsors, while venture-backed biotech clusters in Boston and San Francisco concentrate contract awards for generative chemistry platforms. The agency's evolving compliance benchmarks reshape vendor selection criteria across R&D functions.
Germany
EMA reflection papers on big data in clinical trials accelerate vendor procurement across EU member states, with REACH registration requirements for computational toxicology predictions elevating compliance documentation burdens. The country's pharmaceutical research infrastructure in Baden-Württemberg and North Rhine-Westphalia anchors substantial phenomic screening demand.
United Kingdom
BenevolentAI exemplifies the London-based specialist tier that attracts milestone-based partnership structures from global pharmaceutical sponsors. MHRA alignment with FDA algorithmic transparency guidance reduces dual-track compliance investments for transatlantic submissions originating from Cambridge and Oxford clusters.
China
NMPA regulatory pathways for AI-enabled drug development tools mature alongside domestic GPU infrastructure expansion, lowering capital barriers for deep learning deployment. Shanghai and Beijing biotech parks concentrate government-backed funding for generative chemistry startups seeking to compress hit-to-lead timelines.
Switzerland
Swissmedic's risk-based classification system for medical device software creates premium pricing tolerance for validated predictive analytics platforms. Basel and Zurich anchor Roche and Novartis procurement authority that extends contract values for end-to-end ML-enabled discovery partnerships.
Machine Learning in Pharmaceutical Industry Market Competitive Landscape
Capability concentration sits with specialized generative chemistry platforms; scale advantage sits with large proprietary biological dataset holders. The market structure fragments across three tiers: pure-play AI-native drug discovery firms, vertically integrated biotech platforms, and contract research organizations building algorithmic service layers. Strategic archetypes include generative model specialists, phenomic data aggregators, and regulatory compliance enablers. Dominant competitive moves encompass milestone-based partnership restructuring and in-house dataset construction to reduce external data licensing dependencies.
Among AI-native drug discovery specialists, Insilico Medicine, Recursion Pharmaceuticals, and Exscientia occupy positions that exemplify divergent competitive vectors. Insilico Medicine represents the generative chemistry archetype with its Chemistry42 platform anchoring long-term pharmaceutical partnerships. Recursion Pharmaceuticals exemplifies the phenomic data scale play, sustaining proprietary biological datasets that dominate target validation workflows. Exscientia sits within the autonomous design tier, differentiating through end-to-end candidate optimization control rather than point-solution licensing.
| Leading Market Players |
|---|
| Insilico Medicine |
| Recursion Pharmaceuticals |
| Deep Intelligent Pharma |
| Generate Biomedicines |
| Exscientia |
| Tempus |
| Nabla Bio |
| BenevolentAI |
| Owkin |
| Others |
Supply & Pricing Matrix
Single-source dependency on NVIDIA GPU clusters for deep learning training infrastructure determines both tiered pricing spreads across cloud versus on-premise deployments and supply chain concentration among hyperscale providers. Pharmaceutical buyers face extended procurement timelines when specialized tensor processing units face allocation constraints, forcing milestone-based contract restructuring that shifts pricing risk toward vendors.
Pricing Analysis
Usage-based service contracts tied to molecule progression milestones now drive lifetime value, displacing perpetual software licenses across pharmaceutical procurement departments. Three-tier pricing structure across premium regulatory-grade platforms, standard API-accessible tools, and economy open-source alternatives reflects validation depth and FDA submission support levels. Cost compression in the standard tier intensifies because venture-backed biotech firms demand per-compound transactional pricing. Mid-size pharmaceutical companies exhibit the highest price sensitivity, while large-cap sponsors in Switzerland absorb premium pricing for end-to-end validated platforms.
Supply Chain Analysis
Cloud service providers Amazon Web Services, Google Cloud Platform, and Microsoft Azure hold dominant capacity for GPU-accelerated training infrastructure serving pharmaceutical ML deployments. Hardware supply concentrates in Taiwan for semiconductor fabrication, the United States for specialized AI chip design, and China for rare earth processing essential to magnetic components in data center cooling systems. The supply chain draws from proprietary biological datasets concentrated among contract research organizations, creating input bottlenecks for new entrants. Tariff exposure on Chinese-manufactured hardware components presents structural risk. Distribution runs through direct enterprise sales teams for large pharmaceutical sponsors and self-serve API portals for venture-backed biotech firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where validation consulting and regulatory compliance layers expand faster than core platform licensing. Recurring revenue from ISO 14971 documentation support and EMA submission preparation now exceeds initial software contract values for established vendors.
For Market Incumbents: Insulate proprietary dataset advantages by accelerating in-house phenomic screening infrastructure construction rather than licensing external biological inputs. Lock in large pharmaceutical sponsors through exclusive milestone-based partnerships that embed compliance services. Vertical integration into GPU cluster ownership reduces hyperscaler dependency and secures training capacity allocation during supply crunches. Certification investment in EU AI Act conformity assessment bodies creates switching costs for European market access.
For New Entrants and Emerging Players: Pursue clinical-trial matching automation in Germany and Japan where natural language processing applications remain underdeployed relative to United States penetration. Target mid-cap biotech firms in Boston and San Francisco with API-first pricing that aligns burn rate constraints to usage-based expenditure. Go-to-market execution should anchor on regulatory document mining partnerships with contract research organizations seeking to differentiate through algorithmic efficiency rather than headcount scale.
For Investors and Strategic Acquirers: FDA guidance finalization on AI-enabled drug development tools reshapes the acquisition landscape by elevating validated platform premiums above experimental technology bets. Five-to-ten year viability favors generative chemistry specialists with demonstrated pharmaceutical partnerships over point-solution vendors lacking regulatory submission track records. Acquisition target archetype: phenomic data aggregators with proprietary high-content imaging datasets. Monitor EMA algorithmic transparency requirement convergence with FDA standards as the inflection signal for transatlantic platform scalability premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Dataset Construction | In-house biological data generation reduces licensing costs and accelerates target validation timelines for pharmaceutical partners. |
| Regulatory Compliance Service Layer | ISO 14971 documentation support creates recurring revenue streams exceeding initial platform license values. |
| GPU Infrastructure Vertical Integration | Captive tensor processing unit capacity insulates training pipelines against hyperscaler allocation constraints. |
| Milestone-Based Partnership Restructuring | Risk-sharing contracts align vendor incentives with molecule progression outcomes and extend customer lifetime value. |
| EU AI Act Conformity Investment | Early certification positioning captures premium pricing for European market access ahead of competitor compliance. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, computational biology directors, and pharmaceutical procurement managers provided ongoing calibration against market developments across the analysis window. Primary interviews with platform engineering leads at generative chemistry vendors and phenomic screening specialists were cross-validated against FDA filing databases, EMA submission records, ClinicalTrials.gov protocol registries, and venture financing disclosure documents. Bottom-up contract value aggregation and top-down R&D expenditure allocation models were reconciled to produce segment-level estimates.
Scenario-bracketing framed analytical projections across the modeling period, with high-case assumptions incorporating accelerated FDA guidance adoption and low-case assumptions reflecting extended algorithmic validation timelines. Segmentation dimensions modeled include product type, application phase, technology architecture, end-user scale, and regional regulatory cluster complexity. CAGRs were derived from fitted growth curves anchored to disclosed partnership values and R&D pipeline progression rates. Forecast inputs incorporated GPU infrastructure commoditization trajectories and EMA reflection paper implementation timelines.
Sensitivities concentrate around regulatory divergence between FDA and EMA algorithmic transparency requirements, proprietary dataset concentration among incumbent contract research organizations, and venture funding availability for mid-cap biotech firms. Forecasts reflect assumptions regarding compliance cost trajectories and cloud infrastructure pricing trends that could shift substantially. Quarterly review of FDA guidance update schedules, EMA reflection paper finalization status, and hyperscaler GPU allocation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Manufacturing Market
Artificial Intelligence (AI)
Automated Data Annotation Tool Market
Artificial Intelligence (AI)
Embedded AI Market
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
Artificial Intelligence in Logistics Market
Artificial Intelligence (AI)
AI in Construction Market
Artificial Intelligence (AI)
Global Artificial Intelligence SAAS Market
Artificial Intelligence (AI)
Global Cognitive Computing Technology Market
Artificial Intelligence (AI)
Artificial Intelligence Platform Market
Artificial Intelligence (AI)
Generative AI Market
Artificial Intelligence (AI)
Cloud Natural Language Processing (NLP) Market
Artificial Intelligence (AI)
Neural Network Market
Artificial Intelligence (AI)
Cognitive Services Platform Market
Artificial Intelligence (AI)
Global Federated Learning Solutions Market
Artificial Intelligence (AI)
AI Watermarking Market