
 AI Task Manager App Market | 2026-2036
AI Task Manager App Market Size, Share, and Industry Trends Forecast 2026-2036
AI Task Manager App Market Insights
ISO/IEC 42001 artificial intelligence management system certification is bifurcating the competitive landscape into audit-ready enterprise vendors and consumer-grade alternatives. Asana leverages its workflow automation depth to sustain large-corporation contracts. Todoist anchors the personal productivity segment with cross-platform synchronization. Monday.com competes through visual project scheduling interfaces that reduce onboarding friction.
An AI task manager app deploys machine learning models to prioritize assignments, predict completion times, and automate resource allocation through natural language processing and reinforcement learning algorithms. Cloud-based deployment dominates solution delivery, while workflow automation commands premium pricing due to integration complexity. Team collaboration tools lead solution-type revenue, though resource allocation modules attract the fastest expansion among mid-sized companies seeking operational efficiency gains.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that reshape product architecture decisions for vendors serving European enterprises. The US Federal Trade Commission scrutinizes subscription billing practices and dark-pattern interfaces in productivity software. Stakeholders must monitor evolving compliance obligations across jurisdictions while evaluating whether edge-computing deployment options justify infrastructure investments against latency and privacy tradeoffs.
Market Dynamics
ISO/IEC 42001 certification requirements are bifurcating the competitive landscape, forcing vendors to choose between enterprise-grade audit readiness and consumer-market simplicity. This structural pressure is reshaping R&D allocation and partnership strategies across the sector.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises now require algorithmic transparency documentation, creating pull for certified vendors. Procurement teams in Frankfurt and Paris prioritize audit-ready platforms.
- Natural language processing integration:Voice-first task creation reduces friction for mobile-first workforces. Technology sector buyers in California and Washington deploy these tools at scale.
- Financial services operational efficiency drives:Enterprise software procurement teams in New York and London expand intelligent scheduling adoption to compress project cycle times.
Market Restraints
- Cloud infrastructure cost volatility:GPU-intensive model training and inference create unpredictable operating expense structures for vendors.
- GDPR data residency requirements:European data localization mandates force redundant infrastructure deployment, compressing margins for smaller vendors.
- Spreadsheet and manual calendar persistence:Free substitutes limit willingness-to-pay among individual consumers and micro-businesses.
Strategic Opportunities
- Edge-computing deployment architectures:On-device inference addresses latency and privacy tradeoffs for defense and healthcare sectors.
- Mid-sized company resource allocation modules:Operational efficiency seekers in manufacturing and logistics represent underserved demand.
- US Federal Trade Commission scrutiny of dark patterns:Compliance-first design creates differentiation against consumer-grade competitors using manipulative interfaces.
Industry Challenges
- Reinforcement learning engineering scarcity:Talent capable of tuning completion-time prediction models commands premium compensation, constraining vendor expansion.
- Legacy enterprise system integration complexity:SAP and Oracle ERP connectors require sustained engineering investment without immediate revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Task Manager App Market |
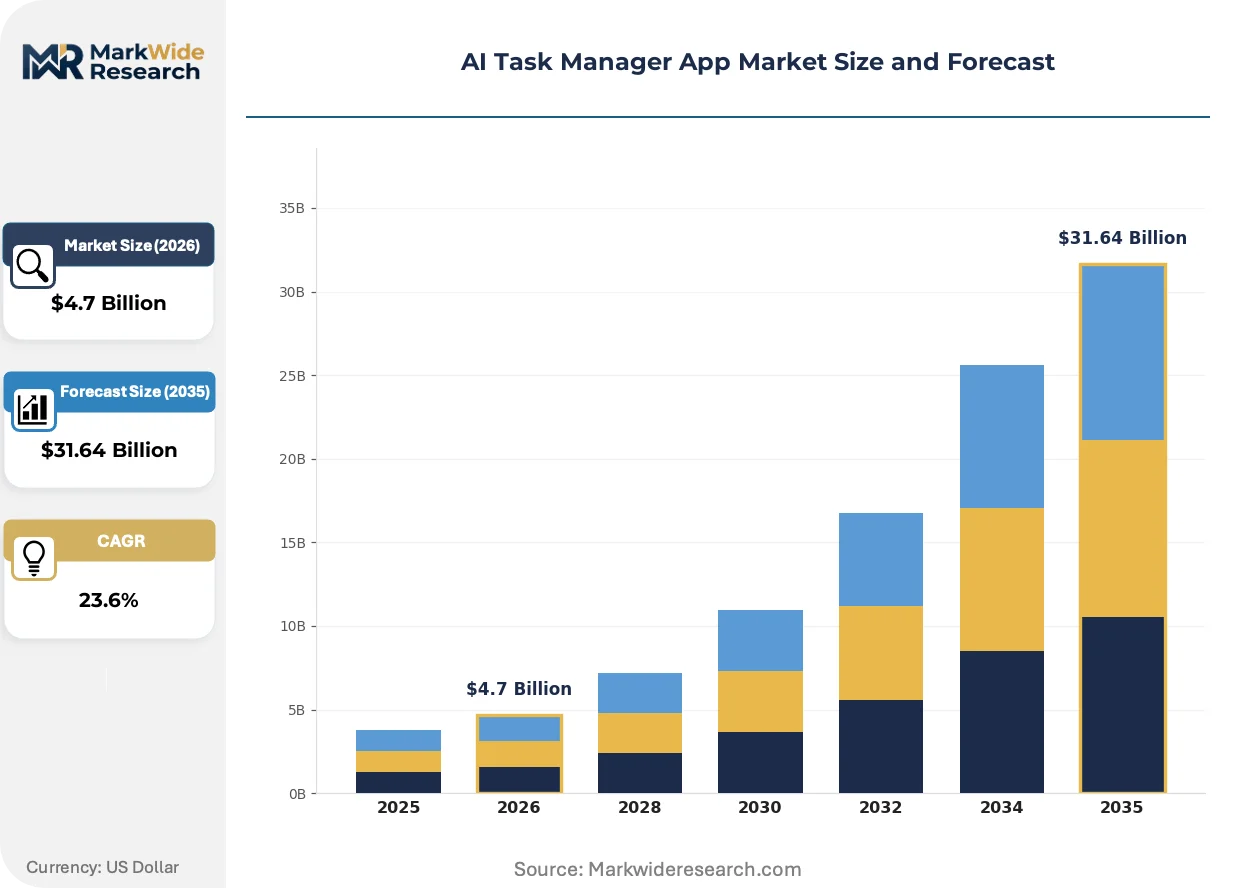
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $31.64 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Type: Personal Productivity, Team Collaboration, Project Scheduling, Workflow Automation, Resource Allocation Use Case: Freelancers, Small Enterprises, Mid-Sized Companies, Large Corporations, Startups Customer Industry: Information Technology, Financial Services, Education Services, Consulting Firms, Creative Agencies |
| Companies Covered | Todoist, Asana, Monday.com, Trello, ClickUp, Notion, Microsoft To Do, Google Tasks, Motion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Task Manager App Market Trends and Innovations
Foundation model integration is compressing development timelines while raising the bar for differentiation. Vendors must now demonstrate proprietary data advantages or specialized domain expertise to justify premium positioning.
Large language model orchestration is bifurcating product architectures between generalist assistants and specialized workflow engines. Enterprise buyers in regulated industries favor narrow, auditable systems over open-ended copilots. This technical divergence is compressing the middle market, forcing vendors to commit to one path.
The EU AI Act's algorithmic transparency requirements are mandating explainability features in scheduling and prioritization logic. Vendors serving European enterprises must document decision pathways, increasing engineering overhead. Financial services and healthcare procurement teams in Germany and France now require this documentation as standard.
Subscription fatigue is shortening evaluation cycles and compressing conversion funnels. Buyers increasingly demand proof-of-value periods before annual commitments, displacing traditional freemium models. Technology sector adopters in Seattle and Austin show the shortest tolerance for opaque pricing structures.
AI Task Manager App Market Segmentation
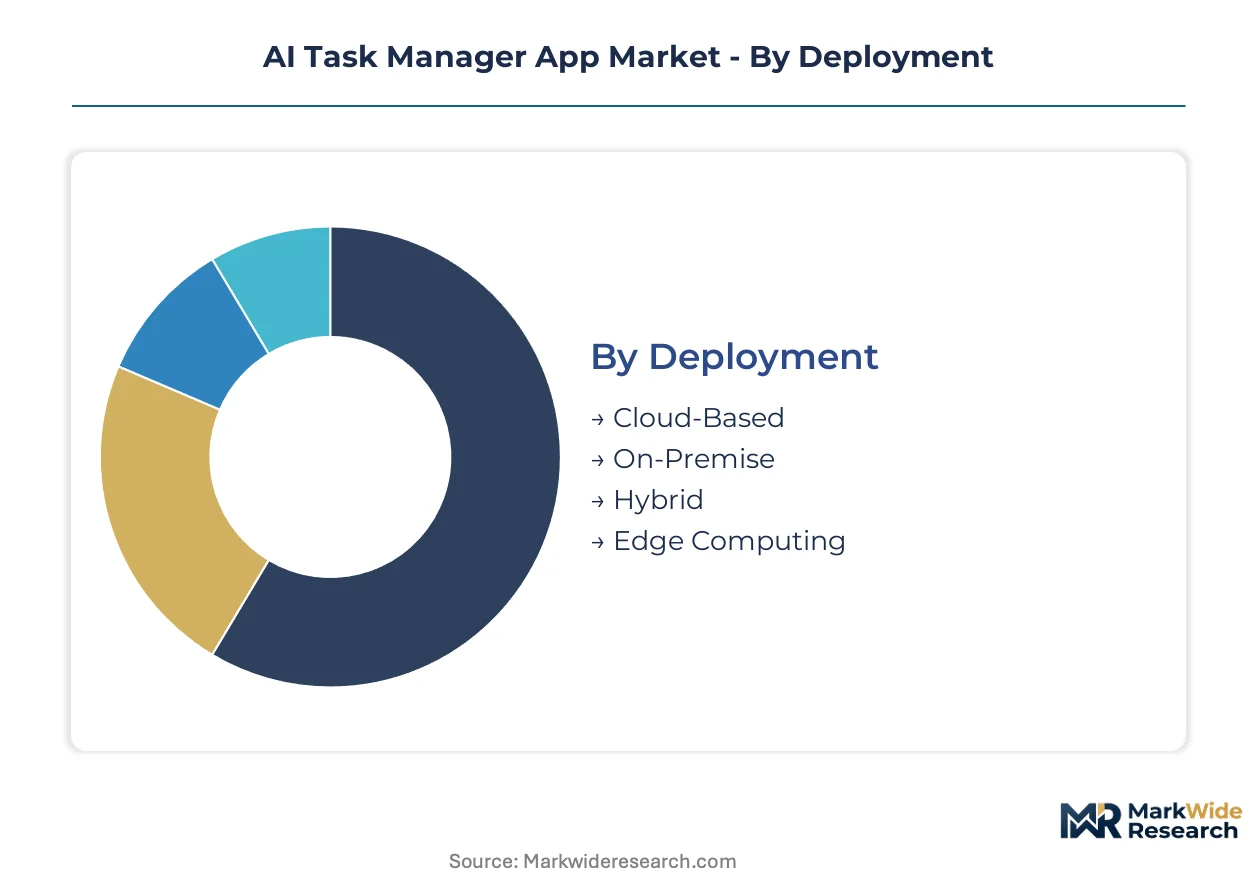
Segmentation in AI task manager apps reveals divergent infrastructure requirements across buyer sophistication levels. Cloud-native architectures dominate consumer and startup adoption, while regulated enterprises in Frankfurt and New York demand hybrid and edge deployments for data sovereignty compliance.
Deployment:
Geographic deployment patterns split sharply between export-led cloud solutions and domestically hosted alternatives serving data-residency mandates.
- Cloud-Based:Multi-tenant SaaS architectures deliver instant scalability without capital expenditure. Demand concentrates among technology sector buyers in California and Washington who prioritize rapid feature iteration over infrastructure control.
- Edge Computing:On-device inference executes prioritization algorithms locally, eliminating network latency. Defense contractors in Virginia and healthcare systems in Massachusetts drive adoption where GDPR and HIPAA data minimization requirements prohibit cloud transmission.
- On-Premise:Self-hosted installations serve German automotive manufacturers and French banking consortiums facing EU AI Act algorithmic audit requirements.
- Hybrid:Split architectures synchronize sensitive workloads locally while pushing non-critical processing to public cloud, gaining traction among London-based financial services procurement teams.
Cloud-Based commands the established base. The steepest expansion runs through Edge Computing.
Solution Type:
Cost tier differentiation separates commodity personal tools from premium enterprise workflow engines with integration depth.
- Workflow Automation:Reinforcement learning engines orchestrate cross-system task sequences through API connectors. Mid-sized companies in manufacturing and logistics across Ohio and Michigan purchase these modules to compress operational cycle times without expanding headcount.
- Resource Allocation:Predictive models distribute human and computational capacity across competing priorities. Technology sector buyers in Austin and Seattle deploy these systems to optimize sprint planning and reduce developer idle time.
- Team Collaboration:Shared workspaces with AI-generated status summaries and conflict detection. Consulting firms in London and New York represent core demand for real-time coordination across distributed professionals.
- Project Scheduling:Critical-path optimization with uncertainty quantification for deadline risk. Construction and engineering procurement teams in Texas and Florida adopt these for capital project delivery.
- Personal Productivity:Lightweight prioritization and habit tracking for individual knowledge workers. Freelancers in Portugal and Spain drive volume through mobile-first, low-subscription offerings.
Team Collaboration captures the revenue base. Workflow Automation climbs the fastest as integration complexity justifies premium pricing.
Use Case:
Customer maturity determines feature requirements, with large corporations demanding audit trails that freelancers disregard.
- Large Corporations:Enterprise-grade deployments require ISO/IEC 42001 certification, SSO integration, and custom model training on proprietary data. Financial services procurement teams in Frankfurt and Paris mandate algorithmic transparency documentation as standard.
- Mid-Sized Companies:Operational efficiency seekers need rapid deployment without dedicated ML engineering staff. Manufacturing and logistics buyers in the US Midwest and German Ruhr region expand fastest as they modernize legacy scheduling.
- Startups:Venture-backed teams prioritize speed of implementation and per-seat pricing flexibility. Technology sector adopters in Tel Aviv and Bangalore favor API-first architectures that embed into existing development workflows.
- Small Enterprises:Owner-operated businesses require minimal configuration and immediate utility. Creative agencies in Lisbon and Dublin represent concentrated demand for visual project interfaces.
- Freelancers:Solo practitioners drive volume at the lowest price points, accepting consumer-grade privacy terms. Copywriters and designers in Mexico City and São Paulo sustain the personal productivity segment.
Large Corporations anchor vendor profitability. Mid-Sized Companies gain share fastest as operational efficiency pressures intensify.
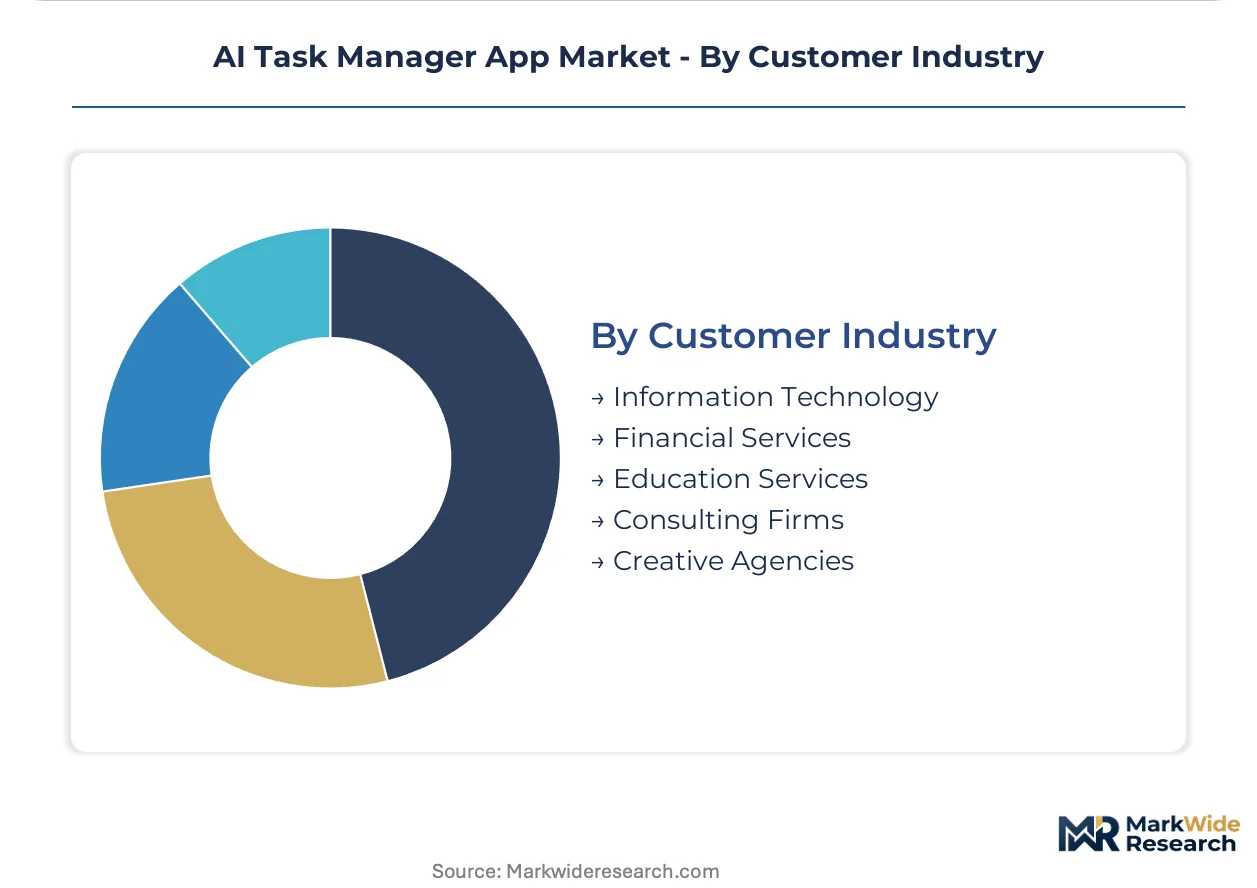
Customer Industry:
Application-specific compliance requirements fragment procurement criteria across verticals.
- Financial Services:Algorithmic trading floors and compliance departments in New York and London require deterministic scheduling with full audit logs. EU AI Act documentation demands reshape vendor qualification protocols for European deployments.
- Information Technology:Software engineering teams in Seattle, Austin, and Bangalore consume AI task managers at highest per-seat density, driving feature roadmaps for developer-specific integrations.
- Consulting Firms:Professional services partnerships in London and New York prioritize client-confidentiality controls and billable-hour tracking accuracy.
- Creative Agencies:Brand and design studios in Los Angeles and Amsterdam favor visual interfaces with asset management integration for campaign workflows.
- Education Services:Universities and edtech platforms in Boston and Oxford adopt collaboration tools for research team coordination and grant milestone tracking.
Information Technology commands the installed base. Financial Services expands most quickly as operational efficiency mandates intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government AI procurement mandates and data sovereignty regulations are redirecting enterprise software budgets toward certified vendors with regional infrastructure presence.
United States
Technology sector buyers in California and Washington deploy AI task managers at scale for developer workflow optimization. FTC scrutiny of subscription billing practices and dark-pattern interfaces forces compliance-first design revisions. Seattle-based engineering teams drive demand for voice-first task creation and API-first architectures.
Germany
Automotive manufacturers and banking consortiums require on-premise installations meeting EU AI Act algorithmic audit requirements. ISO/IEC 42001 certification is reshaping vendor qualification protocols for Frankfurt procurement teams. The Ruhr region's manufacturing base expands intelligent scheduling adoption to compress operational cycle times.
United Kingdom
London-based financial services procurement teams adopt hybrid deployment architectures synchronizing sensitive workloads locally. Consulting firms prioritize client-confidentiality controls and billable-hour tracking accuracy. GDPR data residency requirements force redundant infrastructure deployment decisions.
France
Healthcare systems and financial services procurement teams in Paris mandate explainability features in scheduling logic. ANSM and CNIL oversight extends to productivity software handling employee data. Creative agencies in Amsterdam and Paris favor visual project interfaces with asset management integration.
India
Startup ecosystems in Bangalore and Tel Aviv favor per-seat pricing flexibility and rapid implementation without dedicated ML engineering staff. Technology sector adopters embed API-first architectures into existing development workflows. BIS standards for software quality create compliance benchmarks for domestic vendors.
AI Task Manager App Market Competitive Landscape
Player mix skews toward workflow automation specialists and cross-platform synchronization providers with established enterprise footprints. Market structure shows moderate consolidation around vendors with ISO/IEC 42001 certification capabilities, while consumer-grade alternatives compete on price. Three strategic archetypes dominate: audit-ready enterprise platforms, visual project scheduling interfaces, and lightweight personal productivity tools. Competitive moves concentrate on strategic partnerships for ERP connector development and geographic expansion through regional data center deployment.
Within the enterprise workflow tier, Asana leverages automation depth to sustain large-corporation contracts, while Monday.com competes through visual scheduling interfaces that reduce onboarding friction. Todoist anchors the personal productivity segment with cross-platform synchronization. These three exemplify the certification-driven bifurcation pressuring mid-market vendors to commit to either audit-ready complexity or consumer-grade simplicity.
| Leading Market Players |
|---|
| Todoist |
| Asana |
| Monday.com |
| Trello |
| ClickUp |
| Notion |
| Microsoft To Do |
| Google Tasks |
| Motion |
| Others |
Pricing and Supply Chain Analysis
Annual subscription contracts with quarterly true-up provisions lock in both cloud infrastructure access and predictable per-seat pricing for enterprise procurement teams. This structure binds vendors to multi-year capacity reservations with hyperscalers while giving buyers cost visibility across budget cycles.
Pricing Analysis
Certification level creates the primary spread between enterprise-grade and consumer-tier offerings. Three-tier pricing structure across premium, standard, and economy levels anchors the SaaS model, with ISO/IEC 42001 compliance commanding substantial premiums over uncertified alternatives. Cost compression in the personal productivity tier intensifies as freemium alternatives proliferate. Individual freelancers and micro-businesses exhibit the highest price sensitivity, while financial services procurement teams in Frankfurt and New York accept premium positioning for audit-ready platforms.
Supply Chain Analysis
Container availability fluctuations on the Asia-North America trade lane periodically strain hardware delivery timelines for edge-computing deployments. Cloud infrastructure supply concentrates in the United States, Ireland, and Singapore, with GPU clusters and specialized inference chips forming critical input dependencies. Single-source vulnerability around NVIDIA tensor processing units creates concentration risk for vendors training proprietary models. Distribution runs through direct enterprise sales teams for large contracts, supplemented by self-service digital channels for mid-market and individual adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise software procurement cycles are recovering from budget compression phases, with operational efficiency mandates in financial services and manufacturing driving renewed investment in intelligent scheduling tools.
For Market Incumbents: Compound ISO/IEC 42001 certification advantages by embedding explainability features directly into scheduling logic before EU AI Act enforcement hardens. Deepen vertical integration into proprietary reinforcement learning model training to reduce dependency on scarce ML engineering talent. Defend against emerging API-first challengers by accelerating SAP and Oracle ERP connector development.
For New Entrants and Emerging Players: Lead with edge-computing deployment architectures targeting defense contractors in Virginia and healthcare systems in Massachusetts where data minimization requirements exclude cloud-native incumbents. Capture mid-sized manufacturing and logistics companies across the US Midwest and German Ruhr region with rapid-deployment resource allocation modules requiring zero dedicated ML staff. Pursue channel partnerships with regional systems integrators over direct sales investment.
For Investors and Strategic Acquirers: Specialist workflow automation vendors with proven ERP integration libraries and existing ISO/IEC 42001 certification represent the most defensible acquisition profile. Long-term viability hinges on proprietary data network effects rather than generic large language model orchestration. Monitor EU AI Act enforcement actions against non-compliant vendors as an inflection signal for enterprise consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 42001 Certification Investment | Algorithmic transparency documentation satisfies Frankfurt procurement team mandates under EU AI Act requirements. |
| Edge-Computing Deployment Architecture | On-device inference addresses HIPAA and GDPR data minimization constraints for Massachusetts healthcare systems. |
| ERP Connector Development Partnership | SAP and Oracle integration depth sustains large-corporation contract renewals against API-first challengers. |
| Mid-Market Resource Allocation Module Launch | Operational efficiency tools for Ohio and Michigan manufacturers capture fastest-expanding segment demand. |
| Regional Data Center Expansion | Domestic hosting infrastructure satisfies French ANSM and CNIL oversight for Paris healthcare procurement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CTOs at technology sector buyers, IT procurement officers at financial services firms, platform engineers at mid-sized manufacturers, and integration specialists at consulting firms. Secondary validation drew from SEC filings, hyperscaler capex disclosures, App Annie mobile analytics, and EU regulatory documentation. Bottom-up deployment estimates triangulated against top-down software spending projections across the analysis window.
Across the modeling period, forecasts segmented by deployment architecture, organization size, vertical industry, and integration complexity. CAGRs derived from historical adoption curves weighted by regulatory catalyst timing and infrastructure availability constraints. Reinforcement learning engineering supply scarcity and cloud GPU pricing volatility fed into scenario-bound projections.
The analysis sits within stated boundaries; outcomes outside sustained EU AI Act enforcement intensity or abrupt hyperscaler pricing recalibration would require recalibration. Forecasts reflect documented assumptions around procurement cycle normalization and certification adoption timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence Oven Market
Artificial Intelligence (AI)
AI Voice Cloning Market
Artificial Intelligence (AI)
Federated Learning Market
Artificial Intelligence (AI)
AI in Medical Writing Market
Artificial Intelligence (AI)
Emotion Detection and Recognition (EDR) Market
Artificial Intelligence (AI)
Aiops Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Construction Market
Artificial Intelligence (AI)
Artificial Intelligence Chatbots Market
Artificial Intelligence (AI)
Global Artificial Intelligence-Emotion Recognition Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Robotics Market
Artificial Intelligence (AI)
AI in Fashion Market
Artificial Intelligence (AI)
Global Legaltech Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Global Artificial Intelligence in E-Commerce Market
Artificial Intelligence (AI)
Cognitive Services Platform Market
Artificial Intelligence (AI)
Explainable AI Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Drug Discovery Market